
 Belgium Cybersecurity Market | 2026-2036
Belgium Cybersecurity Market Size, Share, and Industry Trends Forecast 2026-2036
Belgium Cybersecurity Market Outlook
The gap between premium integrated platforms and commodity point solutions is broadening across Belgian enterprise procurement. Palo Alto Networks leverages its consolidated SASE architecture to capture high-complexity deployments in federal and banking environments. Sweepatic anchors its position through specialized external attack surface management tailored to mid-market European clients. Fortinet competes aggressively on price-performance for firewall and SD-WAN bundles, dominating the infrastructure replacement cycle.
Cybersecurity encompasses technologies, processes, and controls designed to protect systems, networks, and data from digital attacks, with core functional parameters including mean time to detect (MTTD) thresholds below 200 milliseconds for automated threat response and encryption key rotation cycles measured in hours rather than days. Its primary commercial purpose is risk transfer—converting probabilistic breach losses into predictable operational expenditures. Managed Security Services lead the service type dimension as Belgian enterprises outsource 24/7 security operations center functions rather than building captive capabilities. Cloud-Based deployment is accelerating fastest among financial institutions navigating NIS2 compliance deadlines. The technology segment shows Encryption Solutions capturing expanding margin pools as post-quantum cryptographic standards drive hardware refresh cycles.
The Belgian market operates under the EU NIS2 Directive, which mandates incident reporting timelines of 24 hours and expands sectoral coverage to critical digital infrastructure providers. The national cybersecurity center coordinates with the Belgian Data Protection Authority to align breach notification obligations under GDPR with technical incident response workflows. Stakeholders must monitor how transposition of the EU Cyber Resilience Act into Belgian law reshapes product security requirements for software vendors serving the local market.
Market Dynamics
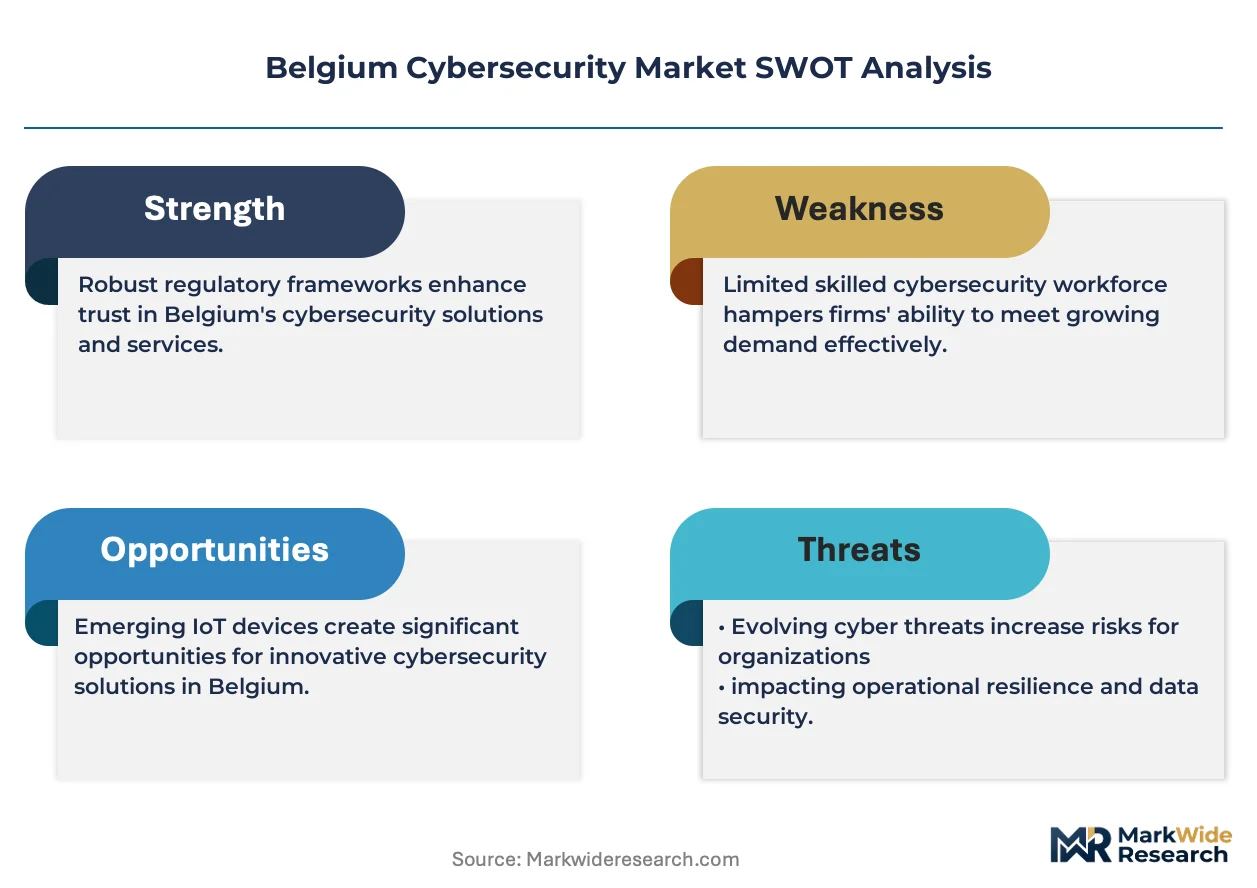
The Belgian cybersecurity landscape is undergoing structural compression as the EU NIS2 Directive forces a wholesale reconfiguration of compliance architectures across financial services and critical infrastructure operators.
Growth Catalysts
- NIS2 Directive transposition:The expanded incident reporting mandates and sectoral coverage are compelling Belgian enterprises to accelerate security operations center investments and external audit frequencies.
- Post-quantum cryptography migration:Hardware refresh cycles for encryption infrastructure are shortening as federal agencies and banks prepare for quantum-resistant standards.
- Financial sector concentration:Brussels and Antwerp host dense clusters of banking headquarters and payment processors with concentrated procurement authority driving platform consolidation.
Market Restraints
- Specialized talent scarcity:The domestic supply of certified security architects and incident response specialists lags deployment timelines, inflating personnel costs.
- Vendor concentration risk:Belgian mid-market enterprises remain dependent on a narrow base of managed security service providers headquartered in neighboring jurisdictions.
- Legacy infrastructure debt:Manufacturing and logistics operators retain operational technology systems with limited API accessibility, constraining unified threat visibility.
Strategic Opportunities
- Wallonia industrial corridor:Underpenetrated manufacturing and chemical processing facilities in southern Belgium present greenfield deployment potential for operational technology security.
- EU Cyber Resilience Act alignment:Software vendors serving the Belgian market must embed security-by-design processes, creating advisory and certification service demand.
- SASE-SIEM convergence:The integration of secure access service edge architectures with security information and event management platforms is opening multi-year transformation contracts.
Industry Challenges
- Certification timeline compression:ISO 27001 and SOC 2 audit backlogs are extending implementation schedules for NIS2-aligned security management systems.
- Multi-cloud orchestration complexity:Belgian enterprises operating across AWS, Azure, and sovereign cloud instances face fragmented policy enforcement and identity governance gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Belgium Cybersecurity Market |
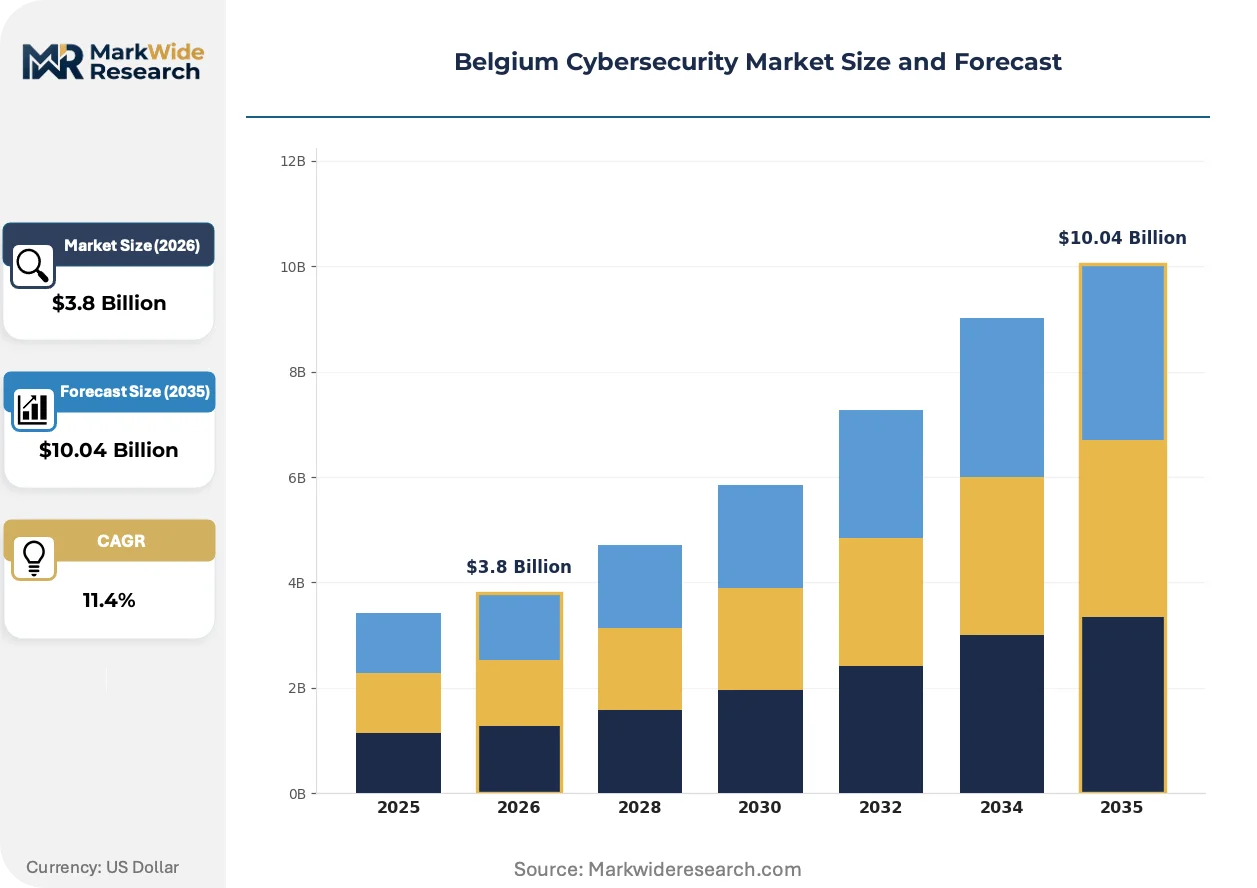
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Managed Security Services, Consulting Services, Integration Services, Incident Response Services End User: Government, Financial Institutions, Healthcare, Retail Deployment: On-Premises, Cloud-Based, Hybrid, Virtual Appliances Technology: Firewalls, Intrusion Detection Systems, Antivirus Software, Encryption Solutions |
| Companies Covered | Palo Alto Networks, Sweepatic, IBM Corporation, Fortinet, CrowdStrike, Cisco Systems, Check Point Software, Orange Cyberdefense, Thales Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Belgium Cybersecurity Market Strategic Shifts
Belgian enterprise security architecture is pivoting from perimeter defense to continuous validation models, with automated exposure management and identity-centric controls displacing static firewall configurations.
Extended detection and response platforms are rewriting how Belgian financial institutions operationalize threat intelligence. These systems correlate endpoint, network, and cloud telemetry into automated remediation workflows. Major banking groups in Brussels are deploying these capabilities within six-month procurement cycles. The technology is compressing mean-time-to-response metrics from hours to minutes for credential-based attacks.
The EU Cyber Resilience Act is mandating software bill of materials disclosure and vulnerability patching obligations for products placed on the European market. Belgian software vendors and systems integrators must restructure development pipelines to embed automated security testing. Hardware manufacturers serving federal and defense contracts are experiencing the steepest compliance cost adjustments.
Subscription-based security outcome contracts are displacing perpetual license purchases among Belgian mid-market enterprises. Chief information security officers now prioritize vendors offering guaranteed detection efficacy metrics over capital expenditure ownership. This preference shift is most pronounced in Flemish manufacturing clusters where operational technology security budgets remain constrained.
Belgium Cybersecurity Market Segmentation
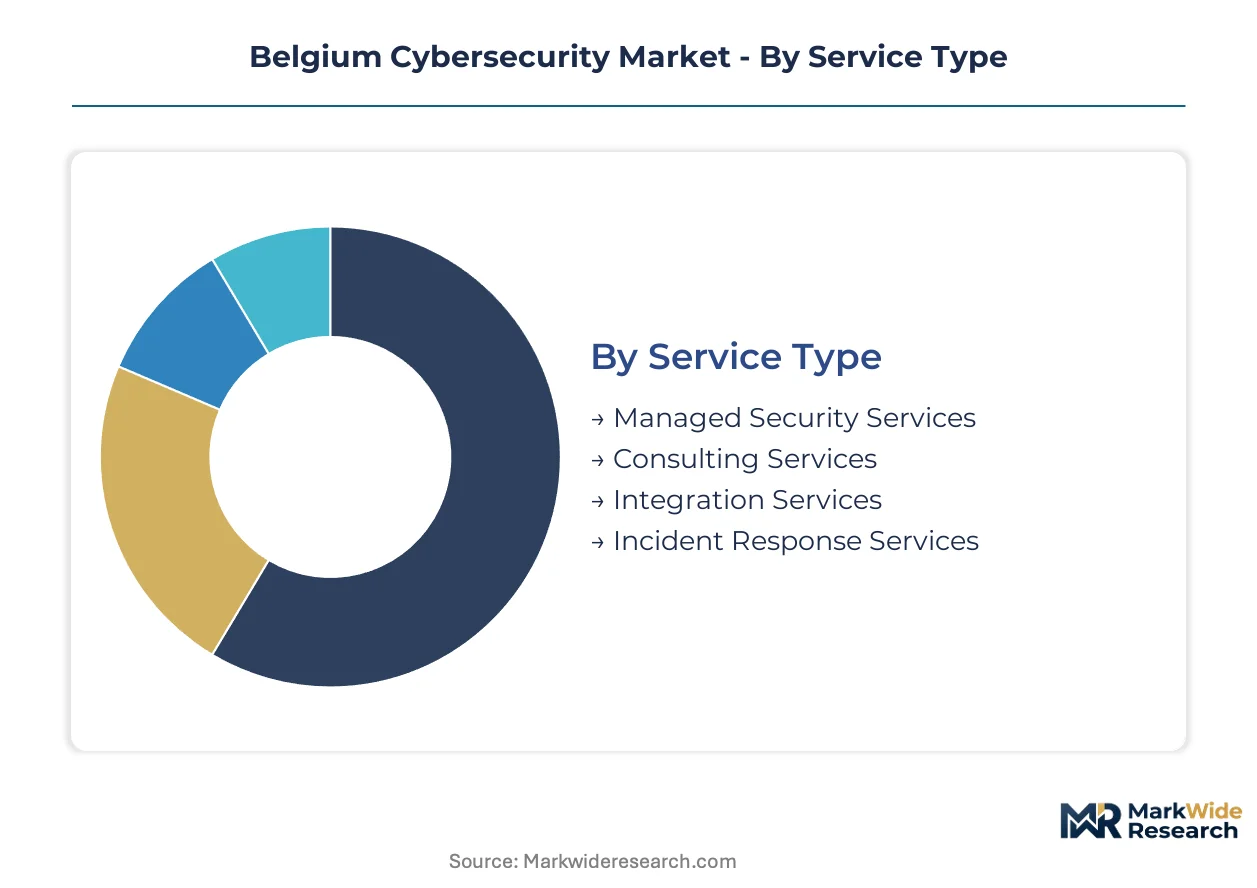
Belgian enterprise procurement patterns diverge sharply across service delivery models and infrastructure architectures. The NIS2 Directive's technical mandates reshape how organizations prioritize deployment options and technology investments.
Service Type:
Technology sophistication determines how Belgian enterprises consume cybersecurity capabilities, with operational complexity driving outsourcing decisions.
- Managed Security Services:24/7 security operations center functions delivered under subscription contracts absorb the majority of enterprise spending in Brussels and Antwerp. Banking headquarters outsource threat monitoring to avoid captive capability buildouts. Belgian mid-market manufacturers favor these arrangements to circumvent domestic talent scarcity.
- Consulting Services:Advisory engagements focus on NIS2 readiness assessments and ISO 27001 certification preparation. Audit backlogs across Belgian certification bodies extend implementation timelines, inflating project values.
- Integration Services:Multi-cloud orchestration and legacy OT system connectivity dominate project scopes in Wallonia industrial corridors.
- Incident Response Services:Retainer-based emergency response capabilities see concentrated demand from payment processors and critical infrastructure operators facing 24-hour reporting deadlines.
Managed Security Services leads on scale; Incident Response Services leads on momentum.
End User:
Regulatory exposure and asset criticality segment demand concentration across Belgian economic sectors.
- Government:Federal agencies and regional administrations drive post-quantum cryptography migration through hardware refresh mandates. Defense contracts impose software bill of materials disclosure requirements on vendors.
- Financial Institutions:Brussels hosts dense clusters of banking headquarters and payment processors with concentrated procurement authority. These entities deploy extended detection and response platforms within compressed six-month procurement cycles.
- Healthcare:Hospital networks align technical incident response with Belgian Data Protection Authority breach notification obligations under GDPR.
- Retail:E-commerce platforms and payment processors prioritize cloud-based deployment for seasonal elasticity.
Financial Institutions dominates revenue concentration; Healthcare shows steepest compliance-driven expansion.
Deployment:
Infrastructure location decisions reflect data sovereignty requirements and legacy system constraints.
- Cloud-Based:Accelerating fastest among financial institutions navigating NIS2 compliance deadlines. Belgian enterprises operating across AWS, Azure, and sovereign cloud instances face fragmented policy enforcement challenges.
- On-Premises:Federal and defense contracts retain air-gapped architectures for classified workloads. Manufacturing and logistics operators maintain operational technology systems with limited API accessibility.
- Hybrid:SASE-SIEM convergence architectures support multi-year transformation contracts across banking groups.
- Virtual Appliances:Software-defined security functions enable rapid scaling for mid-market enterprises without hardware procurement cycles.
Cloud-Based deployment is gaining share fastest; On-Premises retains highest contract values.
Technology:
Functional specifications determine margin capture and replacement cycle timing.
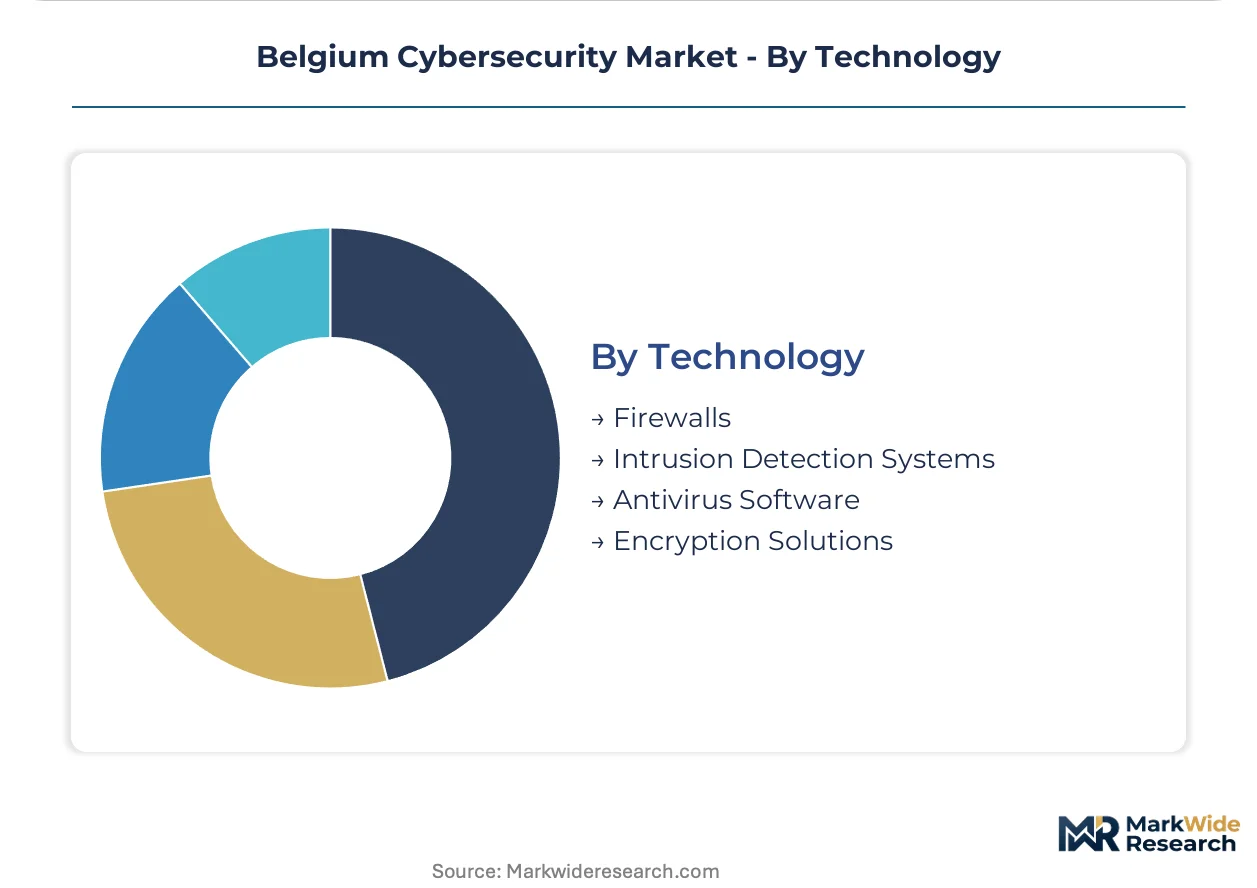
- Encryption Solutions:Hardware security modules and key management systems face accelerated refresh cycles as post-quantum cryptographic standards approach. Federal agencies and banks prepare infrastructure for quantum-resistant algorithms.
- Firewalls:Next-generation platforms with integrated SD-WAN capabilities dominate infrastructure replacement cycles. Price-performance competition concentrates procurement decisions.
- Intrusion Detection Systems:Network behavioral analytics integrate with extended detection and response platforms for automated remediation workflows.
- Antivirus Software:Endpoint protection platforms incorporate extended detection capabilities, blurring categorical boundaries.
Encryption Solutions commands expanding margin pools; Firewalls maintains highest shipment volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgian cybersecurity talent concentrates in Brussels and Antwerp, where federal agencies and banking headquarters anchor specialized workforce pools. Flanders hosts the densest cluster of security operations professionals, while Wallonia develops operational technology security expertise around Liège and Charleroi industrial corridors.
Brussels-Capital Region
EU institutions and NATO headquarters drive demand for classified-grade encryption and secure communications infrastructure. The NIS2 Directive transposition imposes 24-hour incident reporting mandates on critical digital infrastructure providers headquartered here. Banking groups along Avenue Louise deploy extended detection and response platforms within compressed procurement cycles.
Flanders
Antwerp's port authority and logistics operators accelerate investment in maritime cybersecurity and supply chain risk monitoring. The region aligns technical incident response workflows with Belgian Data Protection Authority obligations under GDPR. Ghent and Leuven host university-linked security research clusters feeding talent into financial sector SOCs.
Wallonia
Manufacturing and chemical processing facilities in Liège and Charleroi present greenfield deployment potential for operational technology security solutions. Legacy industrial control systems with limited API accessibility constrain unified threat visibility across the industrial corridor. Federal innovation incentives support OT security modernization in underpenetrated heavy industry segments.
Belgium Cybersecurity Market Competitive Environment
Capital-heavy infrastructure vendors compete with asset-light platform specialists for procurement authority across Belgian enterprise accounts. The market structure shows tiered consolidation: three to five integrated platform vendors capture high-complexity federal and banking deployments, while specialized boutiques serve mid-market manufacturing and healthcare segments. Strategic archetypes include consolidated SASE architects, external attack surface management specialists, and price-performance firewall bundlers. Dominant competitive moves center on multi-year transformation contracts and post-quantum cryptography certification racing.
Within the integrated platform tier, Palo Alto Networks and Fortinet occupy positions as consolidated architecture anchors for federal and financial sector deployments. Sweepatic exemplifies the specialized external attack surface management archetype tailored to mid-market European requirements. Orange Cyberdefense represents the managed security services model absorbing bulk enterprise spending in Brussels and Antwerp.
| Leading Market Players |
|---|
| Palo Alto Networks |
| Sweepatic |
| IBM Corporation |
| Fortinet |
| CrowdStrike |
| Cisco Systems |
| Check Point Software |
| Orange Cyberdefense |
| Thales Group |
| Others |
Value Chain & Pricing Dynamics
Captive security operations center capabilities anchor both supply positioning and pricing power for Belgian managed security services providers. Federal banking contracts in Brussels and Antwerp reward vendors maintaining in-house threat intelligence teams rather than subcontracted analyst pools, compressing margins for asset-light competitors while sustaining premium pricing for integrated platform vendors.
Pricing Analysis
Bundled managed security service contracts dominate enterprise procurement in Brussels, while unbundled point solutions persist among Wallonia mid-market manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates Palo Alto Networks' consolidated SASE deployments from Fortinet's firewall-SD-WAN bundles and commodity antivirus subscriptions. Pricing pressure stems from NIS2 compliance deadlines compressing procurement cycles and inflating certified architect premiums. Mid-market manufacturers show highest price sensitivity, deferring encryption upgrades until hardware refresh mandates force expenditure.
Supply Chain Analysis
Single-source vulnerability sits with Netherlands-based SOC analyst talent pools serving Belgian enterprise accounts. Hardware security module manufacturing draws from Taiwan, Germany, and the United States. Quantum-resistant chip fabrication rests on specialized foundry capacity concentrated in Taiwan and South Korea. Supply chain risk centers on export control restrictions affecting post-quantum cryptographic component shipments. Distribution runs through Brussels-based systems integrators with federal security clearance rather than direct vendor-to-enterprise relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Belgium cybersecurity functions as a stable compounder, with NIS2 regulatory mandates converting one-time compliance spend into recurring managed service subscriptions across financial and critical infrastructure sectors.
For Market Incumbents: Deepen vertical integration into threat intelligence data feeds to defend against CrowdStrike and SentinelOne platform consolidation. Acquire boutique OT security specialists in Liège and Charleroi before federal innovation incentives attract foreign entrants. ISO 27001 certification investment represents the critical lever for retaining federal contract eligibility under tightening procurement standards. For New Entrants and Emerging Players: Wallonia chemical processing facilities present an underserved buyer archetype with limited incumbent presence and NIS2 sectoral coverage expanding to critical manufacturing. Target operational technology security assessments as the entry wedge, converting initial advisory engagements into multi-year managed detection contracts. Partner with Leuven and Ghent university research clusters for talent pipeline access and federal credibility signaling. For Investors and Strategic Acquirers: Roll-up economics work for regional managed security service providers because NIS2 incident reporting mandates fragment compliance expertise across sector-specific workflows. Five-to-ten-year viability hinges on post-quantum cryptography certification racing and SASE-SIEM convergence execution. Watch federal procurement threshold adjustments as the inflection signal for platform consolidation acceleration versus specialist fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Cryptography Certification | Federal agencies and Brussels banking groups mandate quantum-resistant encryption hardware ahead of NIST standard finalization. |
| SASE-SIEM Platform Integration | Secure access service edge convergence with security information and event management compresses procurement cycles for financial institutions. |
| Operational Technology Security Acquisition | Manufacturing and chemical processing facilities in Wallonia require specialized industrial control system expertise lacking in generalist vendors. |
| Managed Security Service Expansion | Subscription-based 24/7 SOC functions displace perpetual licenses as Belgian enterprises outsource captive capabilities. |
| EU Cyber Resilience Act Compliance Advisory | Software vendors serving Belgian market must restructure development pipelines for security-by-design certification. |
Study Parameters
Bottom-up financial institution and manufacturing operator modeling reconciled against top-down managed security service provider capacity tracking forms the analytical core. Primary interviews with CISOs at Brussels banking headquarters, federal cybersecurity procurement officers, Wallonia plant engineers, and Antwerp port authority IT directors combined with secondary validation against Belgian Data Protection Authority breach notification statistics, NIS2 transposition legislative texts, and federal innovation incentive program disclosures. Top-down customs data on hardware security module imports and hyperscaler Belgian cloud region capex announcements triangulated against bottom-up enterprise IT budget surveys.
Historical trendline analysis of encryption infrastructure replacement cycles and SOC outsourcing penetration rates informed projection modeling across the analysis window. Segmentation dimensions include service delivery model, deployment architecture, end-use sector regulatory exposure, and technology functional specification. CAGRs derived from curve-fitting observed procurement velocity against compliance deadline proximity. Post-quantum cryptography migration timelines and SASE adoption rates among Flemish financial clusters served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; financial institution and federal government spending carries tighter precision than mid-market manufacturing and logistics operator estimates. Forecasts reflect assumptions regarding NIS2 enforcement intensity, EU Cyber Resilience Act transposition timing, and quantum computing threat advancement. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Cloud Siem Market
Cybersecurity
Italy Cybersecurity Market
Cybersecurity
Digital Security Market
Cybersecurity
Global File Integrity Monitoring Market
Cybersecurity
Spear Phishing Solution Market
Cybersecurity
Cloud Security in Banking Market
Cybersecurity
Cloud Authentication Market
Cybersecurity
Information Security Products and Services Market
Cybersecurity
United Kingdom Ransomware Protection Market
Cybersecurity
Europe Mobile Security Market
Cybersecurity
Africa Cybersecurity Market
Cybersecurity
Global Database Encryption Market
Cybersecurity
Industrial Cybersecurity Market
Cybersecurity
Germany Endpoint Detection and Response Market
Cybersecurity
Next-Generation Firewall Market
Cybersecurity
Global Deep Packet Inspection (DPI) Market