
 EV Charge Controller Market | 2026-2036
EV Charge Controller Market Size, Share, and Industry Trends Forecast 2026-2036
EV Charge Controller Market Insights
Project finance and leasing structures for charging infrastructure is tilting competitive dynamics toward capital-rich equipment suppliers. Siemens leverages its energy automation portfolio to anchor large-scale highway corridor deployments across Germany and the United States. Tesla sustains vertical control over controller firmware and network software, creating tight integration between vehicle and charging assets. Delta Electronics specializes in power conversion efficiency, competing on thermal performance in high-density DC fast charging stations.
An EV charge controller is an embedded power electronics system that manages electrical flow between grid infrastructure and electric vehicle battery packs, typically handling voltage ranges from 120V AC to 1000V DC with active thermal monitoring and communication protocol translation. Its primary purpose is to ensure safe, efficient energy transfer while enabling data exchange for billing, grid balancing, and remote diagnostics. DC Fast Chargers command the highest margin pools due to silicon carbide semiconductor costs and cooling system complexity, while Smart Chargers are reshaping network economics through dynamic load management and demand-response integration. Wireless Chargers occupy a nascent premium tier constrained by alignment precision standards and infrastructure retrofit costs.
The EU Green Deal and F-Gas Regulation are pressing manufacturers toward refrigerant-free liquid cooling in high-power controllers, while NHTSA guidelines in the United States are hardening cybersecurity requirements for connected charging systems. China's GB standards and MIIT efficiency mandates are accelerating domestic semiconductor substitution in controller designs. Stakeholders must monitor how Open Charge Point Protocol certification evolves as a gatekeeping mechanism for network interoperability and market access across jurisdictions.
Market Dynamics
Silicon carbide semiconductor adoption is compressing thermal management footprints while amplifying power density requirements, forcing controller architectures toward liquid-cooled designs that alter manufacturing economics and supplier qualification timelines.
Growth Catalysts
- NHTSA Cybersecurity Mandates:Connected charging system requirements are accelerating firmware investment cycles and creating upgrade pull-through for legacy hardware installations across the United States.
- Fleet Electrification:Commercial vehicle operators are consolidating procurement around high-reliability DC fast charging controllers with predictive maintenance capabilities.
- EU Green Deal:Refrigerant-free cooling mandates are disqualifying air-cooled designs from highway corridor tenders and favoring liquid-cooled controller suppliers with thermal engineering depth.
Market Restraints
- Silicon Carbide Supply Concentration:Wafer production concentrates among Japanese and German substrate suppliers, exposing controller manufacturers to allocation risk during automotive demand surges.
- F-Gas Regulatory Friction:European cooling system retrofits face extended certification timelines as manufacturers redesign heat exchangers to eliminate fluorinated refrigerants.
- Wireless Charging Substitution Ceiling:Alignment precision requirements and pavement retrofit costs constrain inductive systems to premium fleet depots, limiting addressable market expansion.
Strategic Opportunities
- India PLI Scheme:Domestic manufacturing incentives for power electronics are opening controller assembly opportunities for suppliers establishing local semiconductor packaging operations.
- V2G Convergence:Bidirectional power flow integration between vehicle battery management systems and grid controllers is creating new hardware specification layers for utility-facing installations.
- Subscription Service Channels:Hardware-as-a-service financing models are displacing capital purchase patterns among municipal charging network operators in Germany and France.
Industry Challenges
- OCPP Certification Bottlenecks:Open Charge Point Protocol version compliance testing backlog is extending product launch timelines by four to six months for multi-jurisdiction deployments.
- Embedded Firmware Talent Scarcity:Shortage of power electronics software engineers with functional safety expertise is constraining R&D velocity for mid-tier controller suppliers.
- Legacy Grid Integration Complexity:Rural distribution infrastructure limitations require site-specific power conditioning designs that fragment product standardization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Charge Controller Market |
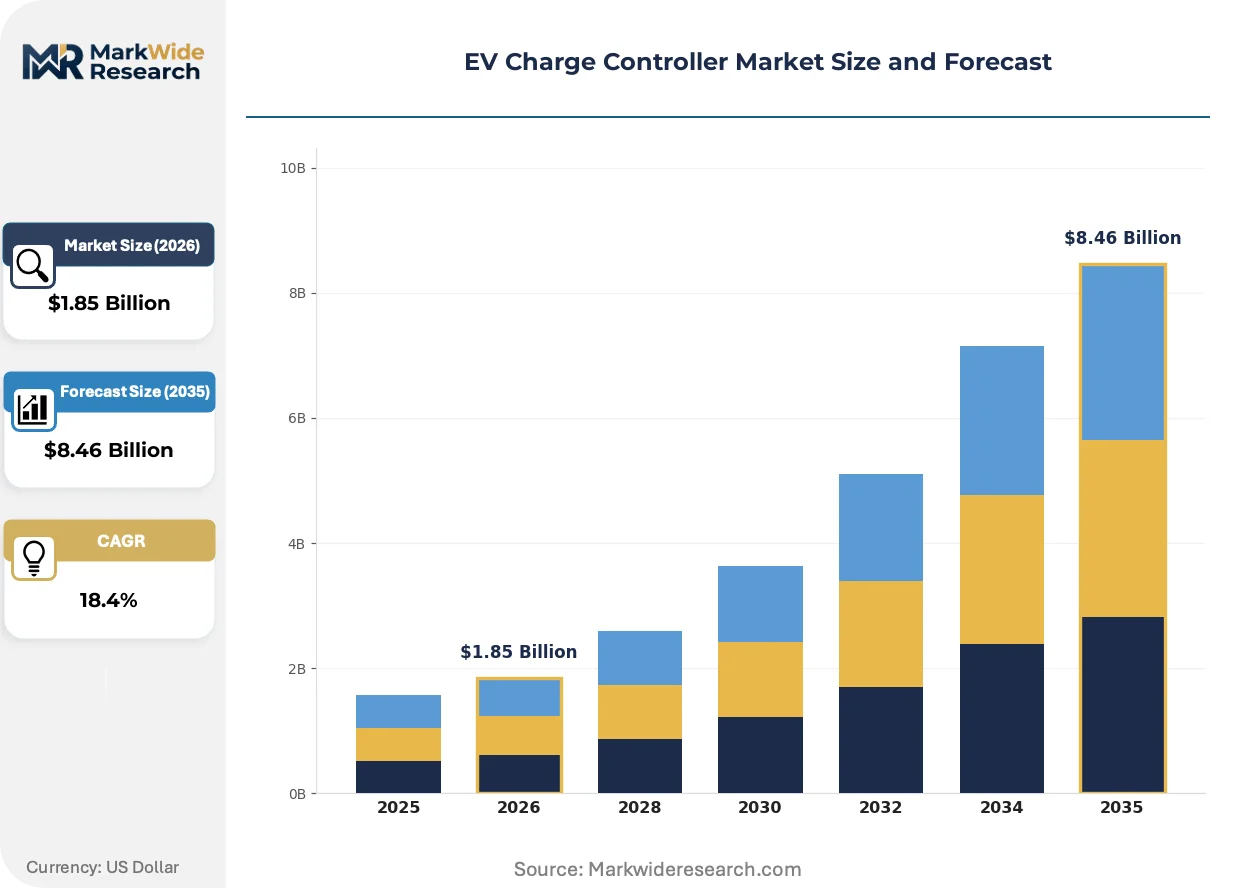
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $8.46 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Level 1 Chargers, Level 2 Chargers, DC Fast Chargers, Wireless Chargers Technology: Smart Chargers, Open Charge Point Protocol, Plug & Charge, Vehicle-to-Grid Installation Type: Wall-Mounted, Floor-Standing, Portable, Integrated Solutions End User: Residential, Commercial, Fleet Operators, Charging Networks |
| Companies Covered | LG Innotek, Robert Bosch, Schneider Electric, ABB, Siemens, Tesla, BYD, Delta Electronics, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Charge Controller Market Trends and Innovations
Controller functionality is migrating from dedicated hardware to software-defined architectures, compressing product lifecycles and redefining supplier value capture around firmware rather than power electronics alone.
Digital twin platforms are virtualizing thermal performance prediction and fault detection in high-power charging controllers. Tier-1 suppliers are deploying these tools for remote diagnostics of highway corridor installations. This virtualization is compressing field service requirements and shifting margin pools toward software maintenance contracts.
China's MIIT efficiency mandates are accelerating domestic semiconductor substitution in controller designs, with GB standards tightening standby power consumption thresholds. Local suppliers are qualifying silicon carbide modules from Chinese foundries for 350kW+ systems. This regulatory pressure is fragmenting global supply chains into region-specific certification tracks.
Utility procurement patterns are consolidating around long-term service agreements that bundle controller hardware with grid integration support. European distribution system operators are favoring suppliers with certified demand-response capabilities. Germany's transmission system operators are embedding these requirements into highway fast-charging concession tenders.
EV Charge Controller Market Segmentation
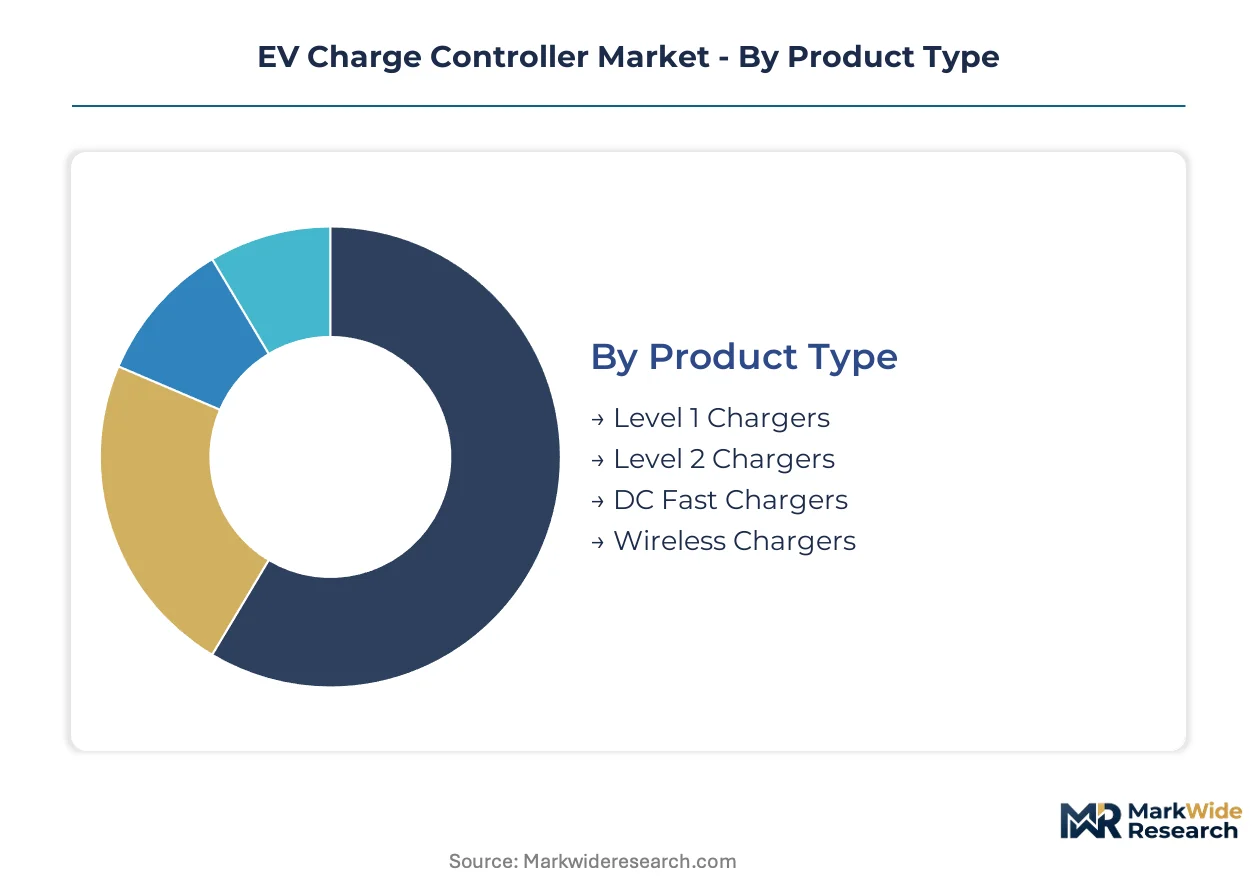
Controller architectures fragment across power levels, communication protocols, and deployment contexts. Each segment carries distinct margin profiles, certification requirements, and supplier qualification barriers that reshape competitive positioning.
Product Type:
Mature AC charging hardware competes on manufacturing scale, while emerging high-power DC systems command premium positioning through thermal engineering differentiation.
- DC Fast Chargers:High-voltage power conversion systems handle 150kW to 350kW output with silicon carbide semiconductors and liquid cooling loops. Highway corridor operators in Germany and California consolidate procurement around predictive maintenance-enabled units to minimize downtime penalties.
- Level 2 Chargers:Mid-power AC controllers (7kW to 22kW) dominate workplace and residential deployment with simpler thermal management. Property developers across France and the Netherlands specify these for multi-unit dwelling retrofits where grid connection limits prohibit DC infrastructure.
- Level 1 Chargers:Basic 120V residential units serve plug-in hybrid owners with minimal installation cost.
- Wireless Chargers:Inductive power transfer systems remain confined to premium fleet depots due to pavement retrofit requirements and alignment precision constraints.
Level 2 Chargers retain volume leadership; DC Fast Chargers hold the steepest expansion curve.
Technology:
Communication protocol choices determine network interoperability access and recurring software revenue potential.
- Smart Chargers:Grid-integrated controllers enable dynamic load management, demand-response signaling, and real-time pricing interfaces. German distribution system operators mandate these capabilities for highway fast-charging concessions, embedding hardware specifications into tender documents.
- Open Charge Point Protocol:Standardized communication framework ensures cross-network vehicle authentication and billing settlement. Certification backlog at testing laboratories extends product launch timelines for suppliers targeting multi-jurisdiction deployments.
- Plug & Charge:ISO 15118-based automatic authentication eliminates manual payment steps.
- Vehicle-to-Grid:Bidirectional power flow controllers interface battery management systems with utility-facing grid services.
Smart Chargers capture the largest installed base; Vehicle-to-Grid systems are climbing the fastest.
Installation Type:
Physical mounting configurations reflect site constraints, maintenance access requirements, and aesthetic considerations across deployment environments.
- Floor-Standing:Pedestal-mounted controllers accommodate dual-cable configurations and high-power cooling systems. Operators along U.S. interstate corridors favor these for driver accessibility and service vehicle clearance.
- Wall-Mounted:Compact enclosures attach to existing structures with minimal civil works. Retail parking operators in Japan and South Korea specify these for space-constrained urban locations.
- Portable:Mobile units address temporary or emergency charging needs.
- Integrated Solutions:Pre-engineered systems combine controller, cable management, and payment terminal in factory-tested enclosures.
Floor-Standing units dominate highway deployment; Wall-Mounted systems are expanding most quickly in urban retrofit applications.
End User:
Customer type shapes procurement scale, reliability requirements, and financing structure preferences.
- Charging Networks:Multi-site operators prioritize OCPP compliance, remote diagnostics, and hardware-as-a-service financing. French and German municipal networks are shifting from capital purchase to subscription models with bundled maintenance.
- Fleet Operators:Commercial vehicle electrification programs demand high-reliability DC fast charging with 99% uptime guarantees. Logistics operators across the Netherlands and California consolidate procurement around predictive maintenance capabilities.
- Commercial:Workplace and retail property owners balance installation cost against employee or customer amenity value.
- Residential:Single-family homeowners drive lowest-cost AC charger demand with minimal smart features.
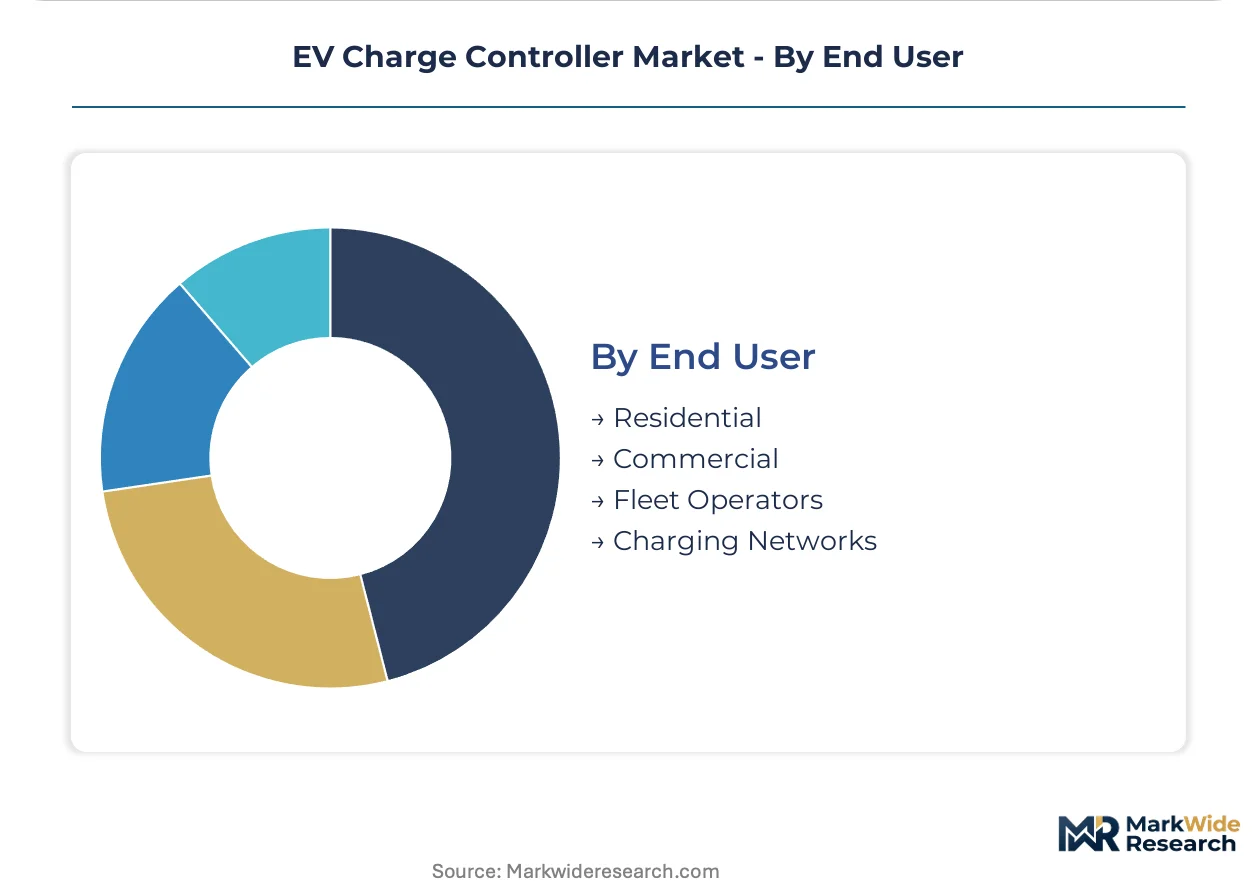
Charging Networks represent the largest addressable revenue pool; Fleet Operators are gaining share fastest as electrification timelines accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's highway corridor tenders while Chinese suppliers compress margins through domestic scale deployment. This asymmetry fragments procurement patterns across major markets.
United States
Fleet electrification programs and interstate highway expansion drive controller demand across California and Texas logistics corridors. NHTSA cybersecurity mandates for connected charging systems accelerate firmware upgrade cycles and hardware replacement timelines. Detroit-area automotive suppliers are integrating controller production with existing power electronics manufacturing.
Germany
Autobahn fast-charging concessions and distribution system operator procurement anchor European demand for high-reliability DC systems. EU Green Deal refrigerant-free cooling mandates disqualify air-cooled designs from highway tenders. Bavarian industrial clusters around Munich and Nuremberg concentrate liquid-cooled controller engineering and thermal system fabrication.
China
MIIT efficiency mandates and GB standards tightening standby power thresholds accelerate domestic semiconductor substitution in controller designs. BYD and state-grid affiliated operators deploy controllers at massive scale across metropolitan charging networks. Yangtze River Delta manufacturing bases around Shanghai and Suzhou dominate silicon carbide module packaging for 350kW+ systems.
India
PLI scheme incentives for power electronics attract controller assembly investment as fleet operators pilot electrification in Maharashtra and Gujarat logistics hubs. Central Electricity Authority grid integration guidelines shape procurement specifications for utility-facing installations. Tamil Nadu's automotive component belt is emerging as a packaging location for domestic semiconductor controller production.
Japan
Retail parking operators in Tokyo and Osaka specify compact wall-mounted controllers for space-constrained urban locations. METI standards for vehicle-to-grid interoperability create certification requirements for bidirectional power flow systems. Nagoya-area industrial suppliers leverage existing power electronics expertise for high-density thermal management components.
EV Charge Controller Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in power conversion and thermal management. The market structures around three tiers: diversified industrial conglomerates with energy automation portfolios, automotive-aligned suppliers with vehicle-side integration capabilities, and focused power electronics specialists competing on semiconductor efficiency. Consolidation pressure intensifies as highway corridor tenders bundle hardware with long-term service agreements. Vertical integration into silicon carbide sourcing and captive firmware development represent the dominant competitive vectors.
Among diversified industrial suppliers, Siemens and ABB exemplify platform-scale positioning across European and North American infrastructure deployment. Schneider Electric and Eaton occupy positions within the electrical equipment specialist tier, leveraging existing distribution relationships for charging controller market access. Robert Bosch represents the automotive-aligned archetype with vehicle-side integration heritage. Delta Electronics sits within the power electronics specialist tier, while Tesla anchors the vertically integrated model with captive network and vehicle ecosystem control.
| Leading Market Players |
|---|
| LG Innotek |
| Robert Bosch |
| Schneider Electric |
| ABB |
| Siemens |
| Tesla |
| BYD |
| Delta Electronics |
| Eaton |
| Others |
Pricing and Supply Chain Analysis
The Yangtze River Delta freight corridor's logistics cost inflation is compressing margins for silicon carbide module suppliers while amplifying price differentiation between liquid-cooled DC fast charging systems and air-cooled alternatives. This cost pressure feeds back into procurement decisions as highway corridor operators in Germany and California consolidate around predictive maintenance-enabled units that command configured-to-order premiums.
Pricing Analysis
Configured-to-order pricing for liquid-cooled DC fast charging controllers runs 40-60% above standard air-cooled units, with three-tier pricing structure across premium, standard, and economy levels anchored by certification grade and thermal engineering depth. Price differentiation hinges on OCPP certification tier and silicon carbide semiconductor sourcing, with German distribution system operators embedding hardware specifications into tender documents that favor premium tiers. Cost compression in standard AC controllers is intensifying because Chinese domestic suppliers leverage MIIT efficiency mandates to qualify local silicon carbide modules at scale. Fleet operators demonstrate lowest price sensitivity due to 99% uptime guarantee requirements, while residential buyers drive aggressive standard-tier negotiation.
Supply Chain Analysis
Contract manufacturing for controller assembly concentrates among Yangtze River Delta EMS providers and Bavarian industrial clusters around Munich, with foundry capacity for silicon carbide wafers anchoring in Japan and Germany. Geographic supply concentration spans China for module packaging, Japan for substrate production, and Germany for thermal system fabrication. Raw material dependencies draw from silicon carbide wafers, liquid cooling loop components, and high-voltage capacitors. Single-source vulnerability in Japanese wafer suppliers exposes controller manufacturers to allocation risk during automotive demand surges. Distribution runs through charging network operators, fleet procurement consortia, and utility-facing installation contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where firmware maintenance contracts and predictive diagnostics subscriptions expand faster than hardware unit sales, particularly among German and French municipal networks shifting from capital purchase to subscription models.
For Market Incumbents: Build switching-cost moats through OCPP certification depth and embedded firmware talent retention. Siemens and ABB should deepen backward integration into silicon carbide sourcing to defend against Chinese domestic substitution accelerated by MIIT efficiency mandates. Consolidation pressure intensifies as highway corridor tenders bundle hardware with long-term service agreements, favoring suppliers with certified demand-response capabilities. For New Entrants and Emerging Players: Pursue white-space targets in India's PLI scheme power electronics assembly and V2G bidirectional controller specifications for utility-facing installations. The most penetrable segment sits with municipal charging network operators in Germany and France adopting hardware-as-a-service financing models. A software-defined architecture go-to-market angle bypasses capital-intensive power electronics manufacturing while capturing recurring firmware revenue. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates spinning off non-core charging controller divisions amid consolidation pressure. Long-term viability over the next decade hinges on captive silicon carbide supply and firmware development capabilities rather than commodity power electronics assembly. Monitor Open Charge Point Protocol version compliance testing backlog as an inflection indicator for product launch timeline risk.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Backward Integration | Captive wafer supply from Japanese and German substrate producers insulates allocation risk during automotive demand surges. |
| OCPP Certification Investment | Version compliance testing depth accelerates multi-jurisdiction product launches and locks in network interoperability access. |
| Liquid-Cooled Thermal Engineering | EU Green Deal refrigerant-free mandates disqualify air-cooled designs from German highway corridor tenders. |
| Predictive Maintenance Platform | Digital twin virtualization compresses field service requirements and shifts margin pools toward software contracts. |
| Hardware-as-a-Service Financing | Subscription models displace capital purchase patterns among French and German municipal charging network operators. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with charging network procurement directors, fleet electrification program managers, power electronics R&D leads, and utility grid integration specialists. Secondary validation drew from NHTSA cybersecurity filings, EU Green Deal implementation documents, MIIT efficiency mandate disclosures, and silicon carbide supply chain trade data. Bottom-up unit economics modeling triangulated against top-down infrastructure investment forecasts across the analysis window.
Calibration against historical deployment trajectories in Germany's autobahn concession awards and China's state-grid metropolitan network rollouts anchored the analytical framework. Segmentation dimensions modeled include power level tier, communication protocol architecture, installation configuration, and end-user procurement structure. CAGRs were derived from installed base expansion rates and replacement cycle compression driven by NHTSA cybersecurity mandates and EU refrigerant-free cooling requirements.
Sensitivities concentrate around silicon carbide wafer allocation shocks, OCPP certification testing backlog extensions, and F-Gas regulatory friction delaying European cooling system retrofits. Forecasts reflect assumptions on fleet electrification timelines, utility demand-response procurement consolidation, and domestic semiconductor substitution rates in Chinese controller designs. Quarterly review of highway corridor tender awards, PLI scheme power electronics incentive uptake, and V2G interoperability certification progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle Charging Adapter Market
Electric Vehicle Charging
Electric Vehicle 800-Volt Charging Pile Market
Electric Vehicle Charging
Second Life Electric Vehicle Battery Market
Electric Vehicle Charging
South America Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Global EV Charging Piles Market
Electric Vehicle Charging
EV Charging Point Market
Electric Vehicle Charging
China Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Pantograph Charger Market
Electric Vehicle Charging
Battery Liquid Cooling Plates for Electric Vehicle Market
Electric Vehicle Charging
Electric Vehicle Charging Facilities Market
Electric Vehicle Charging
Bidirectional Charging Units Market
Electric Vehicle Charging
Global Automotive Charging System Market
Electric Vehicle Charging
Global Electric Vehicle (EV) Charging Service Market
Electric Vehicle Charging
Global Electric Vehicle Charging As a Service Market
Electric Vehicle Charging
Electric Vehicle Battery Charger Market
Electric Vehicle Charging
Electric Vehicle Public Charging Pile Market