
 Global Electronic Shift Operations Management Solutions (Esoms) Market | 2026-2036
Global Electronic Shift Operations Management Solutions (Esoms) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electronic Shift Operations Management Solutions (Esoms) Market Foresight
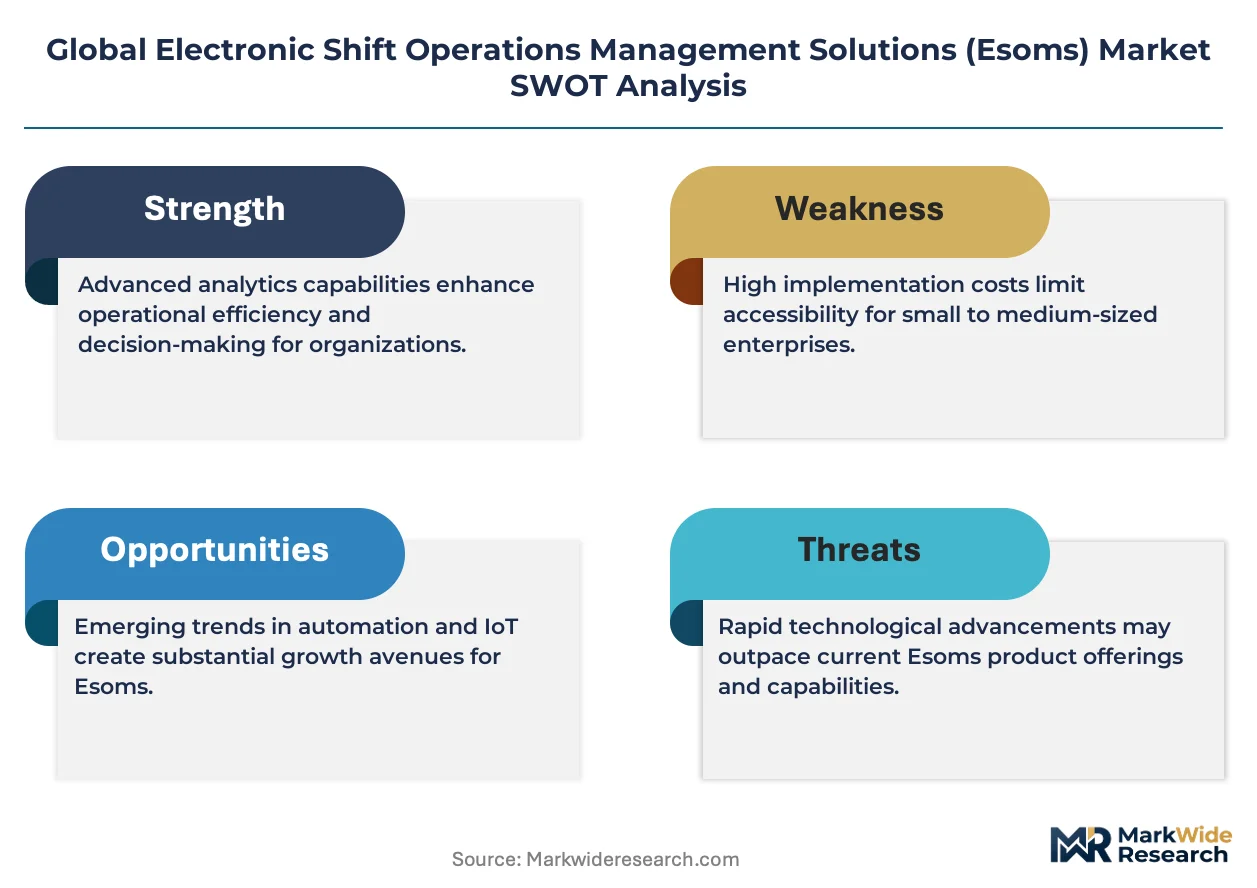
Subscription-based maintenance tiers is realigning how vendors monetize electronic shift operations management solutions, shifting revenue from perpetual licenses to recurring service contracts. Schneider Electric SE leverages its energy management heritage to anchor industrial workforce scheduling platforms across European manufacturing clusters. Siemens AG sustains competitive differentiation through deep integration with its automation hardware ecosystem. Honeywell International Inc dominates North American deployments by coupling shift management with its established process control infrastructure.
Electronic shift operations management solutions comprise software platforms that orchestrate workforce allocation, real-time performance tracking, and compliance logging across multi-shift industrial environments, typically operating through centralized dashboards with edge connectivity to shop-floor devices. Cloud-based deployment leads solution adoption as manufacturers prioritize remote accessibility and reduced IT overhead, while on-premise installations retain traction among defense contractors and critical infrastructure operators subject to stringent data sovereignty requirements. Performance tracking and compliance management functions capture disproportionate margin pools as regulatory audit trails become non-negotiable in hazardous industries.
OSHA mandates in the United States, REACH-aligned worker safety protocols across EU member states, and Japan's METI industrial productivity guidelines collectively elevate demand for auditable shift management documentation. FDA 21 CFR Part 11 requirements for pharmaceutical manufacturing further tighten the specification envelope for electronic record-keeping within these platforms. Stakeholders must weigh interoperability investments against the risk of vendor lock-in as consolidation among automation software providers accelerates.
Market Dynamics
Cloud-native architectures and API interoperability standards are compressing procurement cycles while fragmenting vendor lock-in risks across industrial buyers.
Growth Catalysts
- OSHA Recordkeeping Modernization:Updated workplace safety documentation mandates in the United States are forcing energy-intensive manufacturers to deploy auditable shift logging systems.
- Pharmaceutical serialization:FDA 21 CFR Part 11 compliance requirements for electronic batch records are accelerating platform adoption across drug manufacturing facilities.
- Edge-to-cloud connectivity:Real-time workforce performance telemetry from shop-floor sensors is enabling predictive labor allocation in German automotive clusters.
Market Restraints
- Data sovereignty compliance:Defense contractors and nuclear operators in France and Japan face prolonged procurement cycles due to air-gapped deployment requirements.
- Legacy system entrenchment:Proprietary protocols from 1990s-era manufacturing execution systems create integration friction with modern REST APIs.
- Specialized labor scarcity:Shortages of industrial IoT security architects constrain rollout velocity for multi-site deployments.
Strategic Opportunities
- India's PLI manufacturing incentives:Production-linked incentive schemes for electronics and pharmaceuticals are creating greenfield demand for workforce orchestration platforms.
- EU CSRD reporting alignment:Corporate Sustainability Reporting Directive mandates for social metrics disclosure are opening compliance-driven upsell paths.
- Digital twin convergence:Integration of shift scheduling data with process simulation models is enabling scenario-based labor planning in semiconductor fabs.
Industry Challenges
- Interoperability certification delays:Fragmented testing protocols between ISA-95 and OPC UA standards prolong multi-vendor integration timelines.
- Cyber-physical security hardening:Ransomware targeting operational technology networks demands continuous security patching without disrupting 24/7 production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electronic Shift Operations Management Solutions (Esoms) Market |
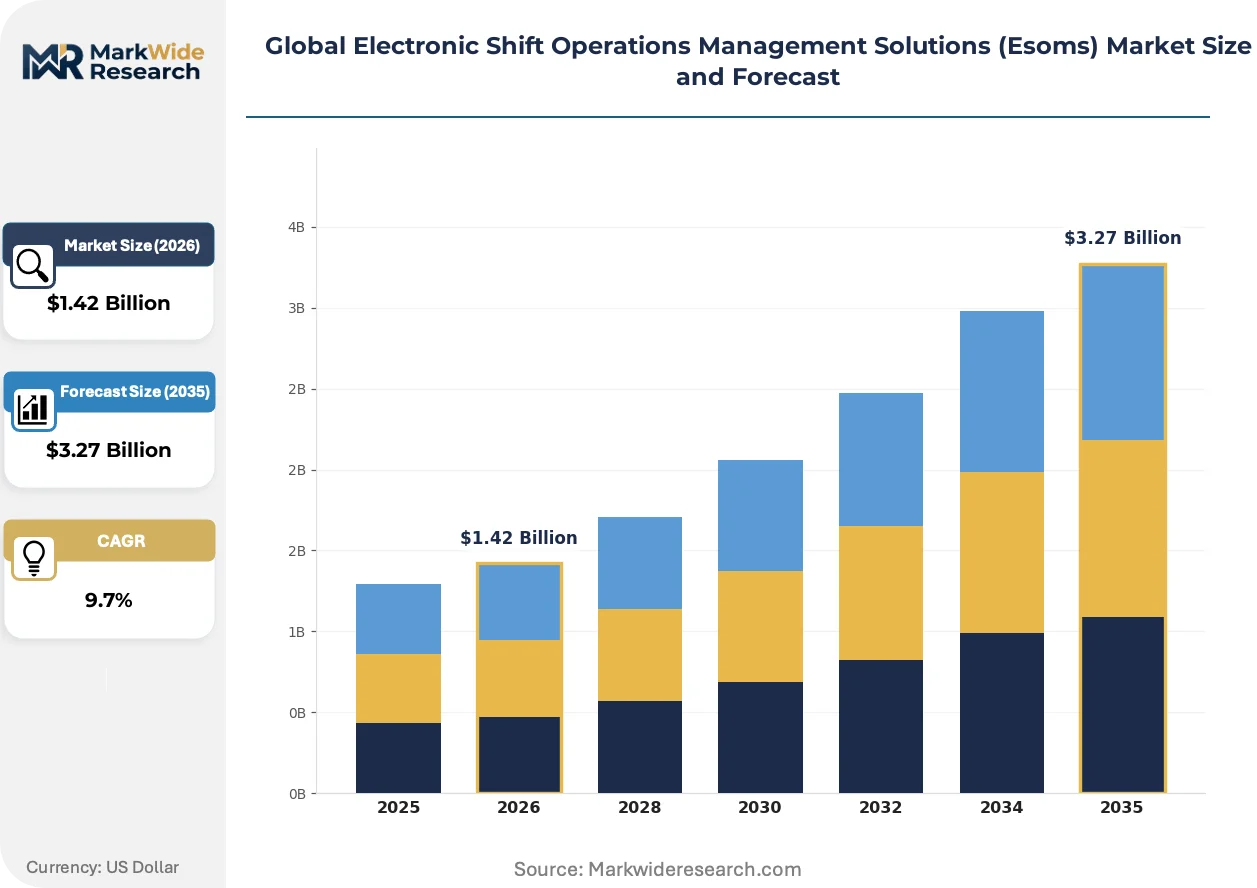
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.27 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Edge, Virtualized Solution Type: Workforce Scheduling, Performance Tracking, Compliance Management, Analytics & Reporting, Incident Management Use Case: Manufacturing Facilities, Logistics Coordination, Retail Management, Hospitality Staffing, Public Safety Coordination Customer Type: Large Enterprises, SMEs, Government Agencies, Non-Profit Organizations, Educational Institutions |
| Companies Covered | Schneider Electric SE, Siemens AG, ABB Ltd, Emerson Electric Co, Yokogawa Electric Corporation, Hexagon AB, Honeywell International Inc, Hitachi Energy Ltd, GE Digital, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electronic Shift Operations Management Solutions (Esoms) Market Shifts & Advancements
Workforce orchestration platforms are absorbing adjacent functionality from time-tracking, safety compliance, and energy management systems, collapsing previously separate software categories.
Unified namespace architectures are unifying historian data, shift schedules, and operator skill matrices into single queryable data models. Chemical manufacturers in the US Gulf Coast are piloting these integrations to correlate fatigue patterns with process deviation events. This unification is compressing the addressable market for standalone point solutions.
Japan's METI has issued updated guidelines for human-machine collaboration in smart factories, requiring documented competency verification for operators supervising autonomous equipment. Pharmaceutical and automotive plants must now maintain granular training records tied to shift assignments. Japanese industrial consortia are responding by embedding micro-credential tracking directly into scheduling workflows.
Consolidated vendor relationships are displacing best-of-breed procurement as manufacturers prioritize single-source accountability for uptime guarantees. German automotive OEMs now bundle shift management with predictive maintenance contracts under unified service-level agreements. This concentration is most visible in Bavaria's supplier parks, where tier-one contractors demand integrated workforce and asset performance dashboards.
Global Electronic Shift Operations Management Solutions (Esoms) Market Segmentation
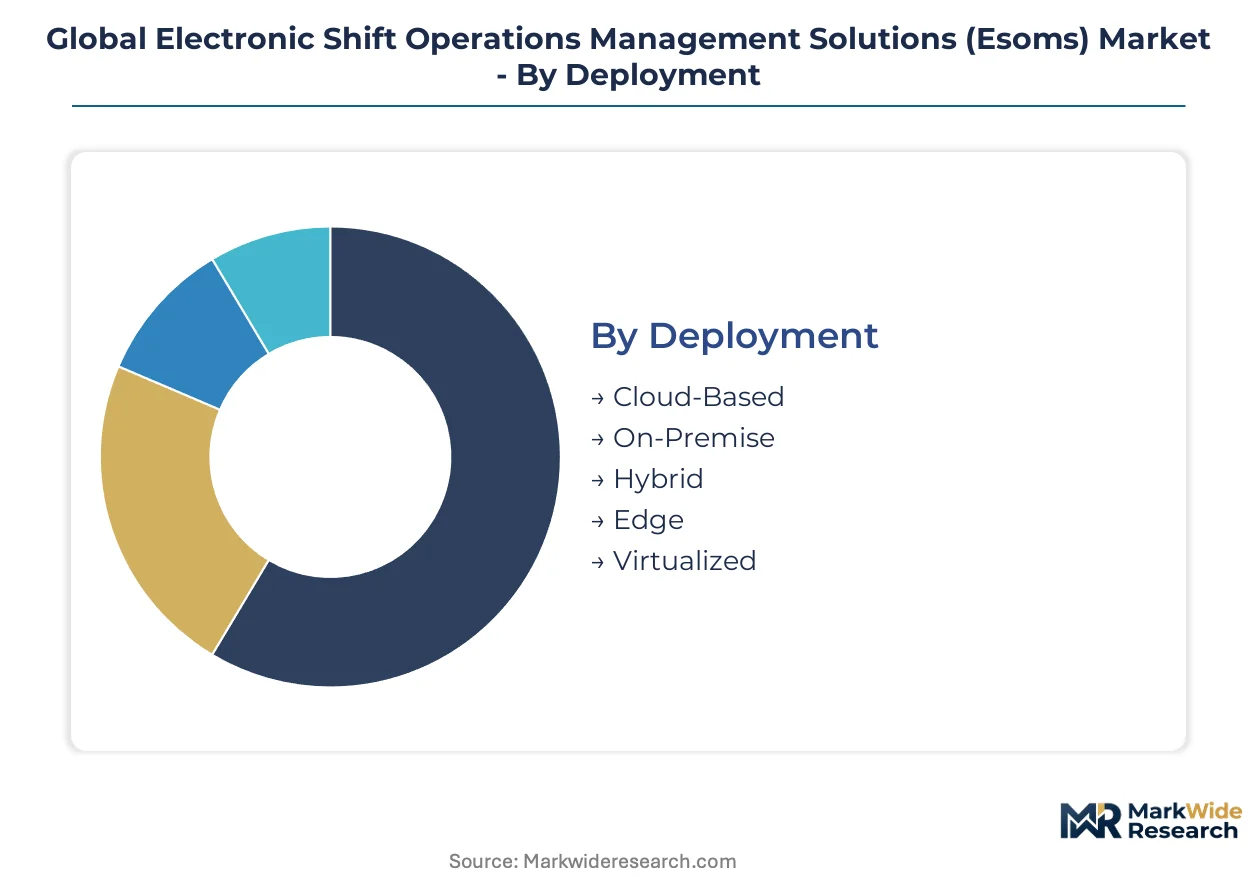
Deployment architecture choices directly determine integration complexity and recurring revenue profiles for Esoms vendors. Solution type segmentation reveals where compliance premiums concentrate versus commoditized scheduling functionality. Customer scale and use case verticality further fragment procurement patterns across industrial buyers.
Deployment:
Volume deployment favors standardized cloud configurations, while premium capture concentrates in air-gapped and edge-hardened installations.
- Cloud-Based:Multi-tenant SaaS architectures with REST API accessibility dominate manufacturing procurement in Germany and the United States. German automotive clusters prioritize remote workforce dashboards to coordinate supplier park shift rotations across Bavaria and Baden-Württemberg.
- On-Premise:Dedicated server installations with offline redundancy serve defense contractors and nuclear operators in France and Japan facing data sovereignty mandates. French defense procurement cycles extend due to ANSM certification requirements for critical infrastructure software.
- Hybrid:Split architectures synchronizing cloud analytics with local transaction processing address pharmaceutical manufacturers balancing FDA 21 CFR Part 11 audit trails with corporate IT standardization.
- Edge:Shop-floor gateway deployments with localized decision logic support real-time fatigue monitoring in Japanese automotive plants under METI human-machine collaboration guidelines.
- Virtualized:Containerized microservices running on hyperconverged infrastructure enable rapid scaling for seasonal demand spikes in US Gulf Coast chemical processing.
Mature deployment sits with On-Premise configurations in regulated defense and nuclear sectors. Newer deployment is concentrated in Edge architectures for real-time shop-floor integration.
Solution Type:
Functionality depth separates compliance-driven premium tiers from workforce optimization commoditization.
- Workforce Scheduling:Core shift allocation engines with constraint-based optimization handle multi-skill rostering across 24-hour production cycles. US-based energy-intensive manufacturers deploy these platforms to satisfy OSHA Recordkeeping Modernization documentation requirements.
- Compliance Management:Audit trail generation with electronic signature capture and immutable logging commands pricing premiums in pharmaceutical and hazardous materials processing. FDA 21 CFR Part 11 validation drives specification rigor for drug manufacturing facilities.
- Performance Tracking:Real-time productivity telemetry correlating operator output with equipment status supports predictive labor allocation in German automotive clusters.
- Analytics & Reporting:Unified namespace architectures integrating historian data with shift schedules enable scenario-based labor planning in semiconductor fabrication.
- Incident Management:Safety event logging with automated escalation protocols serves chemical manufacturers subject to EPA Risk Management Plan reporting obligations.
Revenue concentration sits with Compliance Management. Fastest functional expansion is occurring in Analytics & Reporting as digital twin convergence accelerates.
Use Case:
Industrial verticality determines integration complexity and regulatory overlay intensity.
- Manufacturing Facilities:Multi-shift orchestration across discrete and process industries with MES integration and quality gate alignment. Japanese automotive and pharmaceutical plants embed METI-mandated competency verification into scheduling workflows.
- Logistics Coordination:Dynamic driver and warehouse labor allocation responding to demand volatility in freight and last-mile distribution networks.
- Retail Management:Part-time workforce optimization across store networks with seasonal demand forecasting and labor law compliance.
- Hospitality Staffing:Event-driven scheduling for hotels and venues with skill-based room assignment and service level matching.
- Public Safety Coordination:Emergency responder rostering with certification tracking and mutual aid resource mobilization protocols.
Specification complexity peaks in Manufacturing Facilities. Greenfield demand is climbing fastest in Logistics Coordination driven by e-commerce fulfillment expansion.
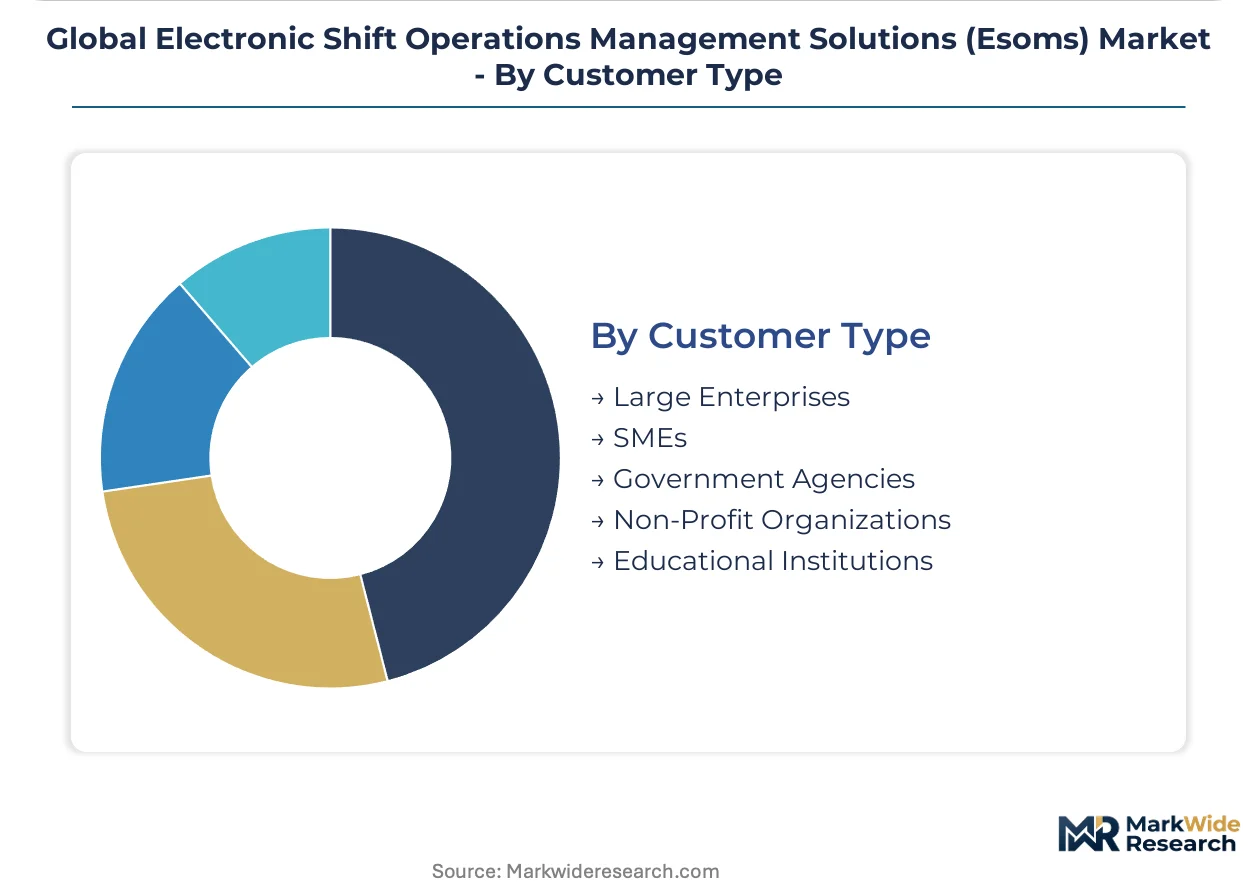
Customer Type:
Scale determines procurement centralization and vendor consolidation tolerance.
- Large Enterprises:Multi-site standardization with unified service-level agreements and consolidated vendor accountability. German automotive OEMs bundle shift management with predictive maintenance contracts across tier-one supplier parks.
- SMEs:Departmental adoption with limited IT resources favoring cloud-native solutions with minimal configuration overhead.
- Government Agencies:Public sector procurement with transparency mandates and extended vendor qualification timelines.
- Non-Profit Organizations:Volunteer coordination with flexible scheduling and mission-aligned workforce engagement tools.
- Educational Institutions:Academic calendar alignment with facilities management and student employment coordination.
Contract value concentration sits with Large Enterprises. Fastest adoption velocity is appearing among SMEs as subscription pricing lowers entry barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's automotive supplier parks anchor European demand for workforce orchestration platforms, with Siemens AG and Schneider Electric SE deploying integrated shift management across tier-one manufacturing clusters in Ingolstadt and Munich.
United States
OSHA Recordkeeping Modernization mandates drive platform adoption across Gulf Coast chemical processors and Pennsylvania steel mills. FDA 21 CFR Part 11 requirements tighten specifications for pharmaceutical manufacturers in New Jersey and North Carolina. Houston's petrochemical corridor pilots unified fatigue monitoring systems tied to EPA Risk Management Plan reporting.
Germany
Automotive OEMs bundle shift management with predictive maintenance contracts under unified service-level agreements across Baden-Württemberg supplier networks. REACH-aligned worker safety protocols elevate audit trail requirements for hazardous materials handling. Stuttgart's manufacturing consortia demand API interoperability between workforce platforms and MES systems.
Japan
METI human-machine collaboration guidelines mandate documented competency verification for operators supervising autonomous equipment in Toyota City and Nagoya automotive plants. Pharmaceutical facilities in Osaka embed micro-credential tracking into scheduling workflows. Edge-to-cloud connectivity enables real-time labor allocation across Kyushu semiconductor fabrication sites.
India
Production-linked incentive schemes for electronics and pharmaceuticals create greenfield demand for workforce orchestration platforms in Karnataka and Tamil Nadu. BIS certification requirements shape procurement criteria for industrial software. Pune's automotive clusters and Hyderabad's pharmaceutical parks represent concentrated deployment zones for cloud-native scheduling solutions.
France
ANSM certification requirements prolong procurement cycles for defense contractors and nuclear operators requiring air-gapped deployments. CSRD reporting alignment opens compliance-driven upsell paths for social metrics disclosure in manufacturing. Île-de-France's aerospace suppliers and Normandy's chemical processors represent high-specification demand pockets.
Global Electronic Shift Operations Management Solutions (Esoms) Market Competitive Landscape
Capital-heavy automation conglomerates compete with asset-light software specialists across deployment architectures, with consolidated vendor relationships displacing best-of-breed procurement. Three archetypes dominate: integrated industrial technology providers leveraging hardware ecosystems, pure-play workforce software vendors emphasizing cloud-native architectures, and energy management specialists extending into labor optimization. M&A activity concentrates among automation software providers, while strategic partnerships between shift management platforms and MES vendors accelerate.
Within the integrated industrial tier, Schneider Electric SE and Siemens AG exemplify capital-intensive positioning anchored in European manufacturing heritage, while Honeywell International Inc occupies a parallel position in North American process control markets. These entities represent archetypal strategies of extending automation hardware dominance into adjacent workforce software categories through bundled service-level agreements and unified namespace architectures.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Siemens AG |
| ABB Ltd |
| Emerson Electric Co |
| Yokogawa Electric Corporation |
| Hexagon AB |
| Honeywell International Inc |
| Hitachi Energy Ltd |
| GE Digital |
| Others |
Supply & Pricing Matrix
OSHA Recordkeeping Modernization mandates are forcing US energy-intensive manufacturers toward auditable shift logging systems, compelling vendors to absorb compliance certification costs into subscription tiers while air-gapped deployments for French defense contractors sustain premium pricing power.
Pricing Analysis
Margin tightening in cloud-native tiers reflects aggressive SaaS bundling by automation conglomerates seeking recurring revenue lock-in. Three-tier pricing structure across premium compliance, standard workforce, and economy scheduling levels dominates procurement, with FDA 21 CFR Part 11 certification and API interoperability depth as primary differentiation drivers. Cost-down pressure on mid-market subscriptions accelerates because SME buyers prioritize rapid deployment over customization. Government agencies exhibit lowest price sensitivity due to extended vendor qualification timelines.
Supply Chain Analysis
Single-source vulnerability sits with German automation hardware ecosystems where Siemens AG and Schneider Electric SE control edge-to-cloud integration pathways. Component sourcing draws from Taiwan for semiconductor gateways, Ireland for cloud infrastructure, and India for software development centers. Tariff exposure on edge computing hardware threatens margin stability for US Gulf Coast chemical processors. Distribution runs through direct enterprise sales teams with embedded solution architects rather than channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into industrial IoT security capabilities is reshaping competitive positioning as ransomware targeting operational technology networks forces vendors to control endpoint protection rather than outsource it.
For Market Incumbents: Acquire specialized industrial cybersecurity firms to harden edge deployments against ransomware targeting 24/7 production schedules. Consolidate predictive maintenance contracts with shift management under unified service-level agreements to displace best-of-breed procurement. Lock in tier-one automotive supplier parks through bundled workforce and asset performance dashboards before cloud-native challengers achieve API parity.
For New Entrants and Emerging Players: MES vendors represent the most accessible channel partnership pathway for workforce orchestration platforms lacking automation hardware heritage. Target India's PLI manufacturing incentives in Karnataka electronics and Tamil Nadu pharmaceutical clusters where greenfield deployments lack legacy system entrenchment. Lead with rapid cloud-native deployment against prolonged on-premise procurement cycles in French defense and Japanese nuclear sectors.
For Investors and Strategic Acquirers: Re-rating potential sits with asset-light software specialists possessing OPC UA interoperability credentials given accelerating consolidation among automation software providers. Five-to-ten year viability hinges on sustained API standardization rather than proprietary protocol dominance. Monitor ISA-95 and OPC UA certification velocity as the inflection signal for multi-vendor integration timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifying shift schedules with digital twin process models enables scenario-based labor planning in semiconductor fabrication. |
| Acquisition of Specialist Firm | Industrial IoT security capabilities address ransomware targeting operational technology networks without disrupting production. |
| Strategic Partnership | MES vendor alliances accelerate multi-vendor integration timelines constrained by fragmented ISA-95 testing protocols. |
| Geographic Expansion | India's PLI manufacturing incentives create greenfield demand for workforce orchestration in electronics and pharmaceuticals. |
| Product Launch | Micro-credential tracking modules satisfy Japan's METI human-machine collaboration guidelines for autonomous equipment supervision. |
Research Methodology
Independent corroboration across plant engineering directors, IT procurement officers at multi-site manufacturers, MES integration specialists, and industrial cybersecurity consultants underwrites the qualitative findings. Primary fieldwork combined with secondary validation from SEC 10-K filings, customs and trade data on industrial software imports, and regulatory filings with OSHA and Japan's METI establishes demand-side triangulation. Bottom-up deployment volume estimates and top-down vendor revenue analysis converge on segment-level conclusions.
Rate-of-change decomposition across deployment architecture, solution type functionality depth, and customer scale segments structures the analytical framework over the projection horizon. CAGRs derive from modeled adoption curves weighted by regulatory mandate timing and greenfield manufacturing investment cycles. Edge-to-cloud connectivity penetration and API interoperability certification velocity serve as industry-specific forecast inputs alongside workforce automation spending patterns.
Caveats apply where delays in ISA-95 and OPC UA unified testing protocols or escalated cyber-physical security requirements could materially shift the outlook. Forecasts reflect documented assumptions on regulatory enforcement intensity and manufacturing capital expenditure trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Deviation Management and CAPA Platforms for Cold Chain Logistics Market
Digital Solutions
Enterprise Mobility in Manufacturing Market
Digital Solutions
Enterprise Asset Management (EAM) Market
Digital Solutions
Electronic Data Interchange (EDI) Market
Digital Solutions
Utility Cases Market
Digital Solutions
Stylus Pen for Education Market
Digital Solutions
Supply Side Platform (SSP) Market
Digital Solutions
Smart Signage Market
Digital Solutions
Data As a Service (Daas) Market
Digital Solutions
Foot Traffic and Customer Location Intelligence Solution Market
Digital Solutions
Global Mesh App and Service Architecture Market
Digital Solutions
Decision Management Applications Market
Digital Solutions
Global Photo Management Software Market
Digital Solutions
Australia ICT Market
Digital Solutions
India Digital Twin Market
Digital Solutions
Mobile Campaign Management Market