
 US Multi-Tenant (Colocation) Data Center Market | 2026-2036
US Multi-Tenant (Colocation) Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
US Multi-Tenant (Colocation) Data Center Market Analytics
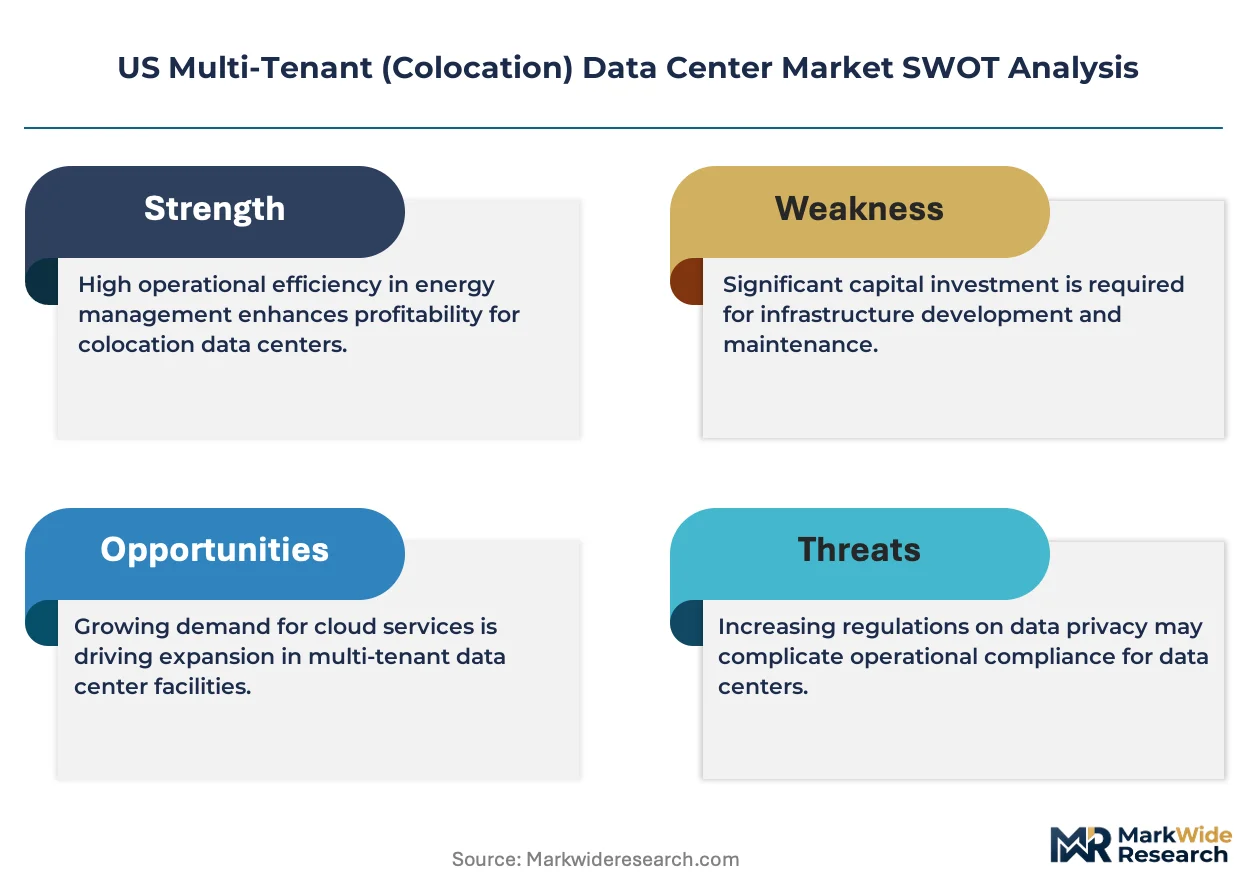
Hyperscale-ready power density specifications above 150 kW per rack is rotating the US colocation market toward premium-tier facility investments. Equinix leverages its interconnection platform density to sustain metro-market premiums across primary coastal markets. CyrusOne anchors its position through wholesale campus scale in secondary geographies. Digital Realty competes via global account coordination for multinational enterprise deployments.
A multi-tenant colocation data center delivers third-party leased space, power, cooling, and physical security for multiple customers' IT equipment, typically maintaining redundant electrical systems with N+1 or 2N configurations and precision cooling within four degrees Fahrenheit of setpoint. Wholesale colocation captures the dominant share of new megawatt commitments as hyperscalers seek dedicated data hall footprints without capital ownership. Edge computing deployments within retail colocation footprints represent the fastest-expanding technology segment, driven by latency-sensitive applications in manufacturing and autonomous systems.
NIST cybersecurity frameworks and SOC 2 Type II attestations shape baseline market access requirements for federal and financial services tenants. EPA emissions reporting obligations and state-level renewable portfolio standards in California, Virginia, and Texas directly influence site selection and power purchase agreement structures. Stakeholders must monitor interconnection queue delays and utility transformer lead times as binding constraints on delivery schedules.
Market Dynamics
The Inflation Reduction Act's clean energy incentives are forcing facility operators to restructure power purchase agreements around renewable sourcing, compressing development timelines as interconnection queues lengthen across Virginia, Texas, and California.
Growth Catalysts
- Hyperscale Cloud Expansion:Amazon Web Services, Microsoft Azure, and Google Cloud are absorbing dedicated data hall footprints in wholesale configurations, pulling rack density specifications above 150 kW.
- IRA Tax Credits:Investment and production tax credits for solar, wind, and battery storage are reshaping site selection economics toward renewable-heavy grids.
- Edge Computing Latency Requirements:Autonomous vehicle testing and smart manufacturing are deploying micro-data centers within 10 milliseconds of population centers, expanding retail colocation demand.
Market Restraints
- Utility Transformer Scarcity:Lead times for medium-voltage transformers from domestic and Asian suppliers have extended to 18-24 months, binding delivery schedules.
- Interconnection Queue Delays:PJM and ERCOT interconnection studies are stretching to 36-48 months for new multi-megawatt loads, freezing greenfield development.
- Skilled Electrical Labor Shortage:Journeyman electricians with medium-voltage and generator paralleling experience command 40% wage premiums in Northern Virginia and Dallas-Fort Worth.
Strategic Opportunities
- Secondary Metro Expansion:Columbus, Ohio and Phoenix, Arizona offer lower land costs and favorable tax abatements while maintaining sub-2ms latency to major population centers.
- Liquid Cooling Retrofit:Direct-to-chip and immersion cooling systems enable 250-500 kW rack densities in existing facilities, extending asset life without full rebuilds.
- Carbon Accounting Services:EPA emissions reporting obligations and customer ESG mandates are creating attach-rate opportunities for real-time power consumption transparency tools.
Industry Challenges
- NIST 800-53 Compliance Complexity:Federal tenants require continuous monitoring and boundary protection implementations that extend commissioning by 4-6 months.
- Legacy Raised-Floor Incompatibility:20-year-old facilities cannot support liquid cooling manifold weights or cable tray loads for 400G fiber densities without structural reinforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Multi-Tenant (Colocation) Data Center Market |
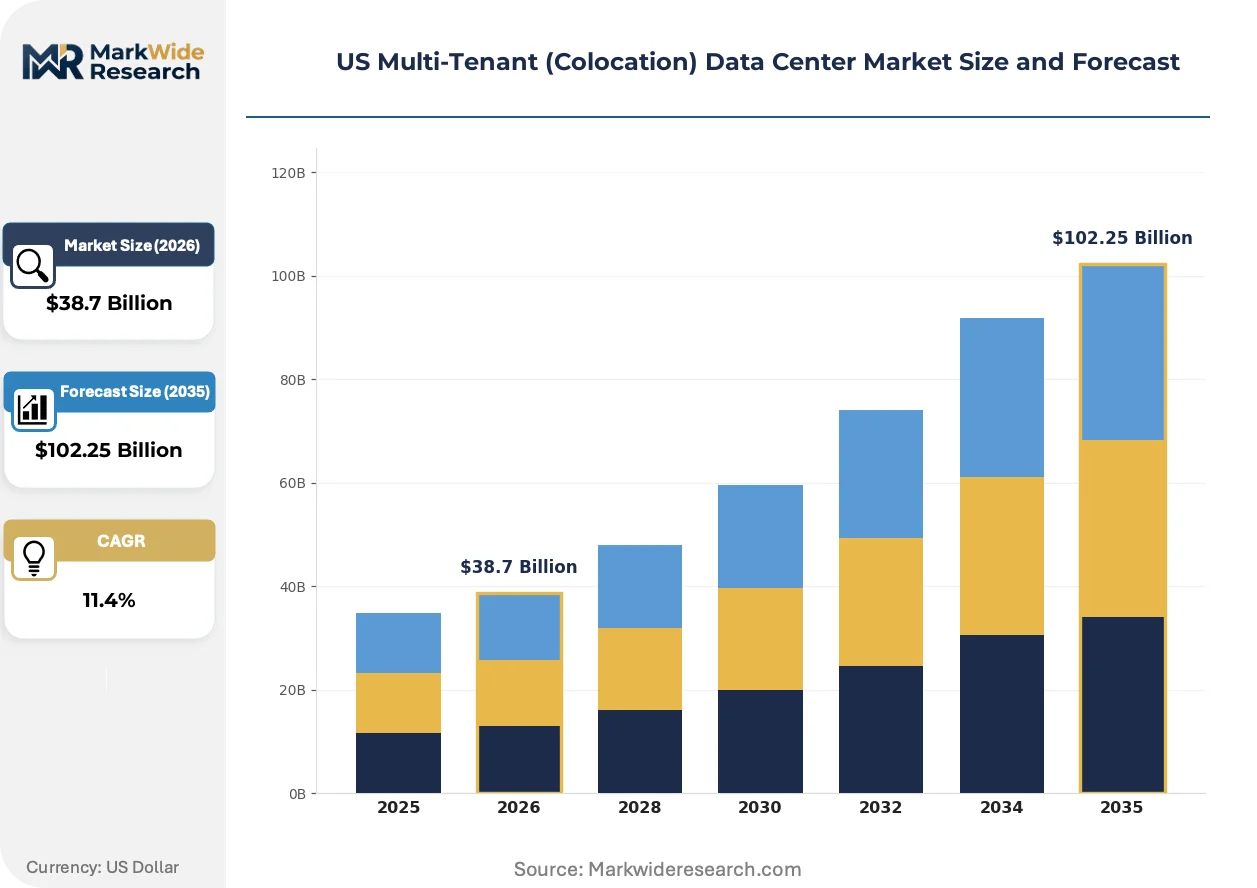
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Retail Colocation, Wholesale Colocation, Hybrid Colocation, Managed Services Size: Small, Medium, Large, Extra-Large Technology: Cloud Infrastructure, Edge Computing, Virtualization, Security Solutions End User: BFSI, IT & Telecom, Government, Retail |
| Companies Covered | Equinix, Digital Realty, CyrusOne, QTS Realty Trust, CoreSite, Switch, Iron Mountain Data Centers, Flexential, STACK Infrastructure, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Multi-Tenant (Colocation) Data Center Market Evolving Landscape
Power delivery architectures and customer contracting models are diverging simultaneously, splitting the market into hyperscale wholesale campuses and latency-optimized edge footprints.
Liquid cooling infrastructure is bifurcating facility investment strategies. Direct-to-chip cold plates and single-phase immersion tanks enable 300+ kW rack densities required by GPU clusters. Hyperscalers are specifying these systems in new builds, while retail operators face retrofit cost barriers. The technology is compressing the viable lifespan of air-cooled legacy assets in primary markets.
EPA greenhouse gas reporting mandates under the Inflation Reduction Act are forcing Scope 2 emissions disclosure. Facility operators must now procure hourly-matched renewable energy certificates or face customer defection to cleaner competitors. Financial services and federal tenants in Northern Virginia are requiring 24/7 carbon-free energy matching in new contracts.
Power purchase agreement structures are displacing traditional utility tariff reliance. Large tenants are negotiating sleeved renewables contracts directly with developers, bypassing incumbent utilities. This behavior is most visible among cloud providers in Texas ERCOT territory, where nodal pricing volatility creates arbitrage opportunities for behind-the-meter solar and storage.
US Multi-Tenant (Colocation) Data Center Market Segmentation
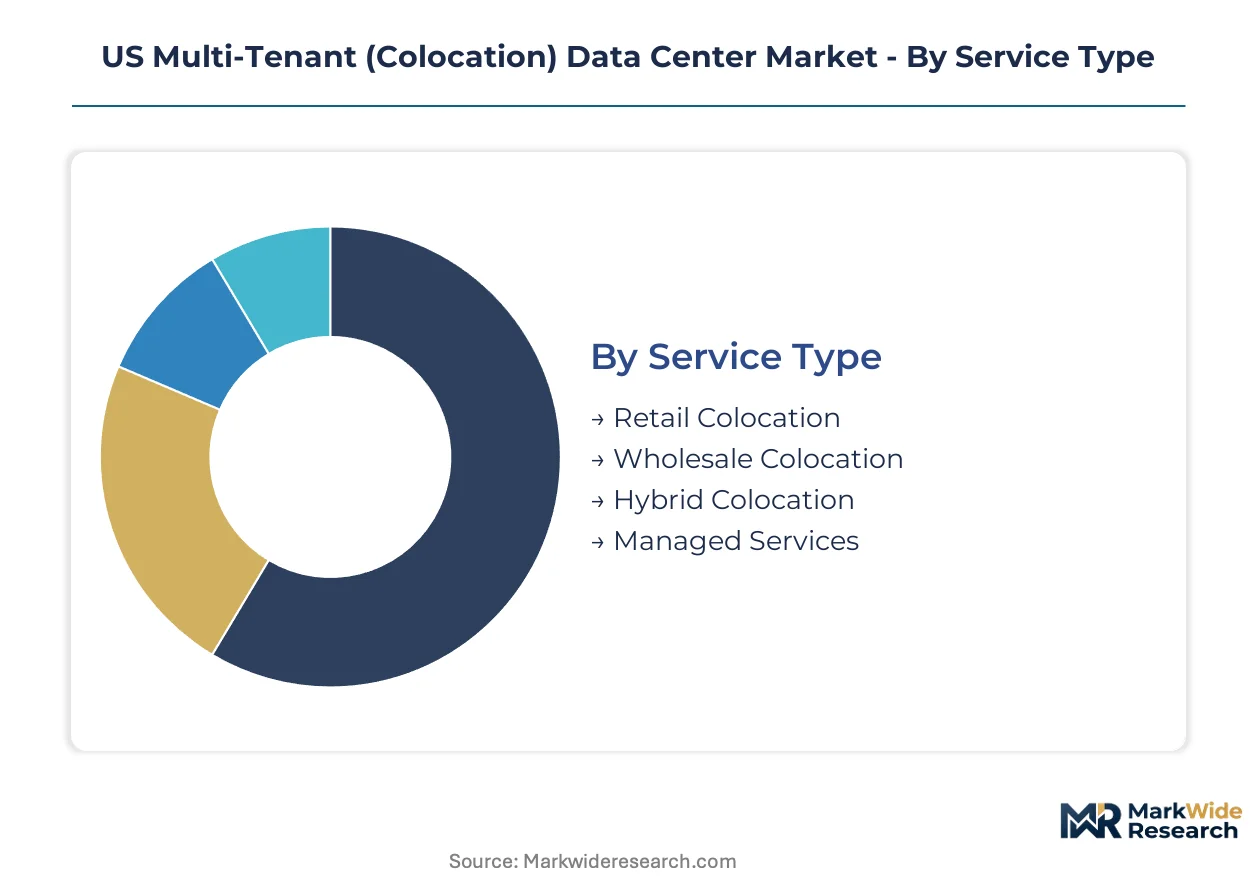
Segmentation in the US colocation market reflects divergent procurement patterns between hyperscale cloud tenants and latency-sensitive edge deployers. Regulatory compliance requirements from NIST, EPA, and state renewable portfolio standards further stratify facility specifications across service tiers.
Service Type:
EPA emissions reporting obligations and NIST 800-53 compliance frameworks create divergent contracting structures across service tiers, with federal and financial services tenants demanding differentiated security attestations.
- Retail Colocation:Individual cabinet or cage deployments with shared power and cooling infrastructure, typically under 500 kW per tenant. Demand concentrates in Northern Virginia and Dallas-Fort Worth from enterprises requiring SOC 2 Type II attestation without capital expenditure.
- Wholesale Colocation:Dedicated data hall footprints with customized power densities above 150 kW per rack and direct utility interconnection. Hyperscalers in Data Center Alley absorb the dominant share of new megawatt commitments as AWS, Microsoft Azure, and Google Cloud expand dedicated capacity.
- Hybrid Colocation:Blended on-premises and cloud-connected infrastructure with cross-connect orchestration to public cloud nodes.
- Managed Services:Fully outsourced IT operations including remote hands, hardware procurement, and network management layered atop physical colocation.
Wholesale colocation handles the majority of throughput; edge-optimized retail footprints are gaining share fastest among autonomous vehicle and smart manufacturing deployers.
Size:
Facility scale directly determines interconnection queue positioning and transformer procurement priority from utilities, with extra-large campuses commanding preferential engineering study timelines.
- Small:Facilities under 1 MW of critical IT load, typically retrofit commercial buildings with limited expansion corridor.
- Medium:1-5 MW deployments serving regional enterprise clusters with N+1 redundancy and diverse fiber entry points.
- Large:5-20 MW purpose-built facilities with 2N electrical architecture and on-site substations. Columbus, Ohio and Phoenix, Arizona attract this tier through tax abatements and sub-2ms latency to major population centers.
- Extra-Large:Campus-scale developments exceeding 20 MW with phased buildout and dedicated renewable energy procurement. PJM and ERCOT interconnection studies stretching to 36-48 months bind delivery schedules for this tier.
Extra-large facilities anchor capital deployment; small-scale edge nodes are climbing the fastest on share as latency requirements harden below 10 milliseconds.
Technology:
Infrastructure technology selection determines compliance posture against EPA greenhouse gas mandates and NIST cybersecurity frameworks, with liquid cooling and zero-trust architectures becoming baseline for federal tenants.
- Cloud Infrastructure:API-driven compute and storage orchestration with software-defined networking. Texas ERCOT territory sees dominant adoption as cloud providers negotiate sleeved renewables contracts bypassing incumbent utilities.
- Edge Computing:Micro-data centers deployed within 10 milliseconds of population centers for autonomous systems and industrial IoT. Manufacturing hubs in Dallas-Fort Worth drive fastest expansion as latency-sensitive applications proliferate.
- Virtualization:Hypervisor-based workload abstraction enabling multi-tenant resource pooling and rapid provisioning.
- Security Solutions:Zero-trust network segmentation, DDoS mitigation, and hardware security modules for cryptographic key management.
Cloud infrastructure commands the dominant installed base; edge computing infrastructure shows the steepest expansion trajectory through the forecast window.
End User:
Sector-specific regulatory obligations from SEC climate disclosure rules, HIPAA safeguards, and FedRAMP authorization requirements create non-negotiable compliance thresholds that filter facility eligibility.
- BFSI:Banking, financial services, and insurance tenants requiring PCI-DSS compliance, geographic redundancy for business continuity, and 24/7 carbon-free energy matching in Northern Virginia contracts.
- IT & Telecom:Cloud providers, content delivery networks, and telecommunications carriers with the highest power density specifications. Skilled electrical labor shortages in Data Center Alley and Dallas-Fort Worth command 40% wage premiums for this tenant category.
- Government:Federal, state, and local agencies mandating NIST 800-53 continuous monitoring and boundary protection implementations that extend commissioning by 4-6 months.
- Retail:E-commerce platforms and brick-and-mortar chains with seasonal demand volatility and distributed point-of-sale connectivity requirements.
IT and Telecom tenants absorb the majority of new capacity; government sector demand is expanding most quickly as FedRAMP-authorized facilities proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Northern Virginia absorb capacity premiums without price elasticity, while Texas and Ohio markets compete aggressively on power rates and tax abatements.
Northern Virginia
Loudoun County's Data Center Alley processes over one-third of US internet traffic through hyperscale footprints. Virginia's renewable portfolio standard mandates carbon-free procurement timelines that compress interconnection queue negotiations. Ashburn and Sterling campuses command 20-40% lease rate premiums over secondary metros due to fiber density and latency arbitrage.
Dallas-Fort Worth
Texas ERCOT nodal pricing volatility attracts cloud providers seeking behind-the-meter solar arbitrage. The state's property tax abatement programs for data center equipment reduce total cost of ownership by 15-25% over Virginia equivalents. Irving and Plano clusters concentrate wholesale commitments from financial services tenants requiring geographic redundancy.
Phoenix
Arizona's sales tax exemption on server equipment and sub-2ms latency to Los Angeles drive retail colocation expansion. The state's water stress regulations under the Groundwater Management Act impose cooling technology constraints on new builds. Chandler and Mesa submarkets attract edge computing deployers serving autonomous vehicle testing corridors.
Columbus
Ohio's data center sales tax abatement and 40% lower land costs than Northern Virginia position the market for secondary metro absorption. The state's renewable energy credit trading system enables hourly-matched clean power procurement. New Albany and Dublin campuses target enterprise tenants fleeing primary market congestion.
Atlanta
Georgia's film and gaming tax credits spill into data center construction labor pools, tightening skilled electrical availability. The state's nuclear-heavy grid provides baseload carbon-free energy without renewable intermittency. Lithia Springs and Alpharetta submarkets serve latency-sensitive fintech tenants requiring sub-10ms reach to Southeast population centers.
US Multi-Tenant (Colocation) Data Center Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Interconnection density and wholesale scale represent the two dominant capability vectors. Premium-tier operators compete on metro-market fiber access and cross-connect velocity. Scale-driven players anchor positions through campus-level power procurement and phased buildout flexibility. Consolidation pressure concentrates among mid-tier regional operators lacking either interconnection depth or utility-scale land positions.
Within the premium interconnection tier, Equinix occupies a position exemplifying metro-market platform density. CyrusOne represents wholesale campus scale in secondary geographies. Digital Realty anchors global account coordination for multinational enterprise deployments.
| Leading Market Players |
|---|
| Equinix |
| Digital Realty |
| CyrusOne |
| QTS Realty Trust |
| CoreSite |
| Switch |
| Iron Mountain Data Centers |
| Flexential |
| STACK Infrastructure |
| Others |
Value Network & Pricing Analysis
EPA greenhouse gas reporting mandates under the Inflation Reduction Act gate both facility qualification and lease rate differentiation simultaneously, forcing operators to embed hourly-matched renewable energy costs into pricing structures while supply chain constraints on medium-voltage transformers compress margin flexibility across all tiers.
Pricing Analysis
After-sales revenue from managed services and cross-connect orchestration drives lifetime value capture beyond base lease rates. The dominant pricing structure operates on contract-based long-term offtake with volume-scaled rates and renewable energy matching premiums. Price differentiation rests on fiber density proximity and NIST 800-53 certification tier, with hyperscale wholesale tenants showing minimal price sensitivity compared to retail colocation deployers facing cost compression from edge computing latency requirements.
Supply Chain Analysis
Medium-voltage transformer procurement from domestic and Asian suppliers constitutes the critical chokepoint binding delivery schedules across Northern Virginia and Dallas-Fort Worth. The supply chain draws from China, South Korea, and Germany for electrical switchgear, cooling compressors, and precision HVAC components. Single-source vulnerability on transformer manufacturing feeds into 18-24 month lead time exposure. Distribution runs through direct utility interconnection agreements and EPC contractor-led turnkey deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US colocation market faces high-growth disruption as liquid cooling retrofits and IRA-driven renewable procurement reshape capital deployment economics.
For Market Incumbents: Compound interconnection platform density in Northern Virginia and Dallas-Fort Worth to defend against wholesale campus operators capturing hyperscale volume. Prioritize vertical integration into behind-the-meter solar and battery storage development to offset ERCOT nodal pricing volatility. Lock skilled electrical labor through apprenticeship pipelines before wage premiums erode project returns. For New Entrants and Emerging Players: Anchor in Columbus and Phoenix submarkets where tax abatements and sub-2ms latency create white-space absorption potential. Target enterprise tenants fleeing Data Center Alley congestion with liquid-cooled retrofit offerings for legacy raised-floor facilities. Pursue carbon accounting services attach-rates as differentiated go-to-market positioning against established operators. For Investors and Strategic Acquirers: The Inflation Reduction Act's clean energy incentives reshape the acquisition landscape toward renewable-heavy grid positions and sleeved PPA negotiation capabilities. Long-term viability centers on campus-scale land positions with phased buildout flexibility rather than metro-market fiber density plays. Monitor interconnection queue resolution timelines at PJM and ERCOT as the critical inflection signal for development velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Retrofit Deployment | Direct-to-chip systems enable 300+ kW rack densities in legacy facilities without structural rebuilds. |
| Behind-the-Meter Solar Development | IRA tax credits and ERCOT nodal pricing arbitrage reshape site selection economics for hyperscale tenants. |
| Interconnection Queue Priority Positioning | Extra-large campus scale commands preferential engineering study timelines at PJM and ERCOT. |
| Carbon Accounting Services Integration | EPA emissions reporting mandates create attach-rate opportunities for real-time consumption transparency tools. |
| Secondary Metro Expansion | Columbus and Phoenix tax abatements attract enterprise tenants fleeing primary market congestion. |
Research Methodology
Initial hypotheses were tested against primary input from data center development executives, utility interconnection planners, hyperscale cloud procurement officers, and electrical contracting specialists and refined through secondary validation against FERC interconnection filings, EIA power plant databases, SEC 10-K facility disclosures, and state renewable portfolio standard documentation. Bottom-up capacity buildout tracking and top-down utility load forecast triangulation anchored market sizing.
Variance decomposition across service type, facility scale, technology infrastructure, and end-user vertical dimensions structured the analytical framework throughout the projection horizon. CAGRs were derived from capacity absorption rates, interconnection queue velocity, and power density specification trajectories. Hyperscaler capex disclosures and utility transformer procurement lead times served as industry-specific forecast calibration inputs.
Material uncertainties — interconnection study delays, transformer supply constraints, and skilled labor availability — sit outside the modeled envelope. Forecasts reflect assumptions on IRA tax credit continuity and state renewable mandate trajectories. Practitioners should keep alternative scenarios live as PJM queue reform and ERCOT market redesign evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Switzerland Data Center Server Market
Data Center Infrastructure
Data Processing and Hosting Services Market
Data Center Infrastructure
Europe Data Center Physical Security Market
Data Center Infrastructure
Taiwan Data Center Power Market
Data Center Infrastructure
Indonesia Enterprise Network Infrastructure Market
Data Center Infrastructure
Russia Data Center Market
Data Center Infrastructure
France Data Center Server Market
Data Center Infrastructure
Singapore Data Center Physical Security Market
Data Center Infrastructure
France Data Center Market
Data Center Infrastructure
Data Center Outsourcing and Infrastructure Utility Services Market
Data Center Infrastructure
Malaysia Data Center Storage Market
Data Center Infrastructure
Dedicated Server Hosting Market
Data Center Infrastructure
Norway Data Center Rack Market
Data Center Infrastructure
Denmark Data Center Rack Market
Data Center Infrastructure
Europe Data Center Server Market
Data Center Infrastructure
Israel Data Center Rack Market