
 Saudi Arabia Data Center Rack Market | 2026-2036
Saudi Arabia Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Data Center Rack Market Insights
Saudi Vision 2030 sustainability targets and NEOM's renewable-powered data center commitments is consolidating demand for energy-efficient rack infrastructure across the Kingdom. Schneider Electric leverages integrated power and cooling architectures to capture premium deployments in Riyadh's expanding cloud corridors. Vertiv anchors its position through thermal management expertise that aligns with rising liquid-cooled rack requirements. Rittal competes via modular enclosure systems designed for rapid deployment in hyperscale facilities.
Data center racks are standardized metal frameworks engineered to house servers, networking equipment, and power distribution units, typically measured in rack units with 19-inch mounting widths and load capacities exceeding 1,500 kg for dense computing environments. Rack enclosure configurations dominate procurement as operators prioritize physical security and controlled airflow management in Saudi Arabia's high-temperature climate. Colocation deployment models are expanding fastest as international cloud providers seek local presence without capital-intensive buildouts. Open frame rack demand concentrates in enterprise labs and testing facilities where accessibility outweighs environmental sealing requirements.
SFDA and the Communications, Space and Technology Commission shape equipment certification and telecommunications infrastructure standards, while SASO enforces product conformity for imported rack assemblies entering the Kingdom. CITC spectrum and data localization policies directly determine where rack infrastructure must be physically installed, creating location-specific procurement clusters. Stakeholders should monitor evolving Saudi data sovereignty requirements and NEOM's zero-carbon facility specifications as these will dictate next-generation rack thermal and power density standards.
Market Dynamics
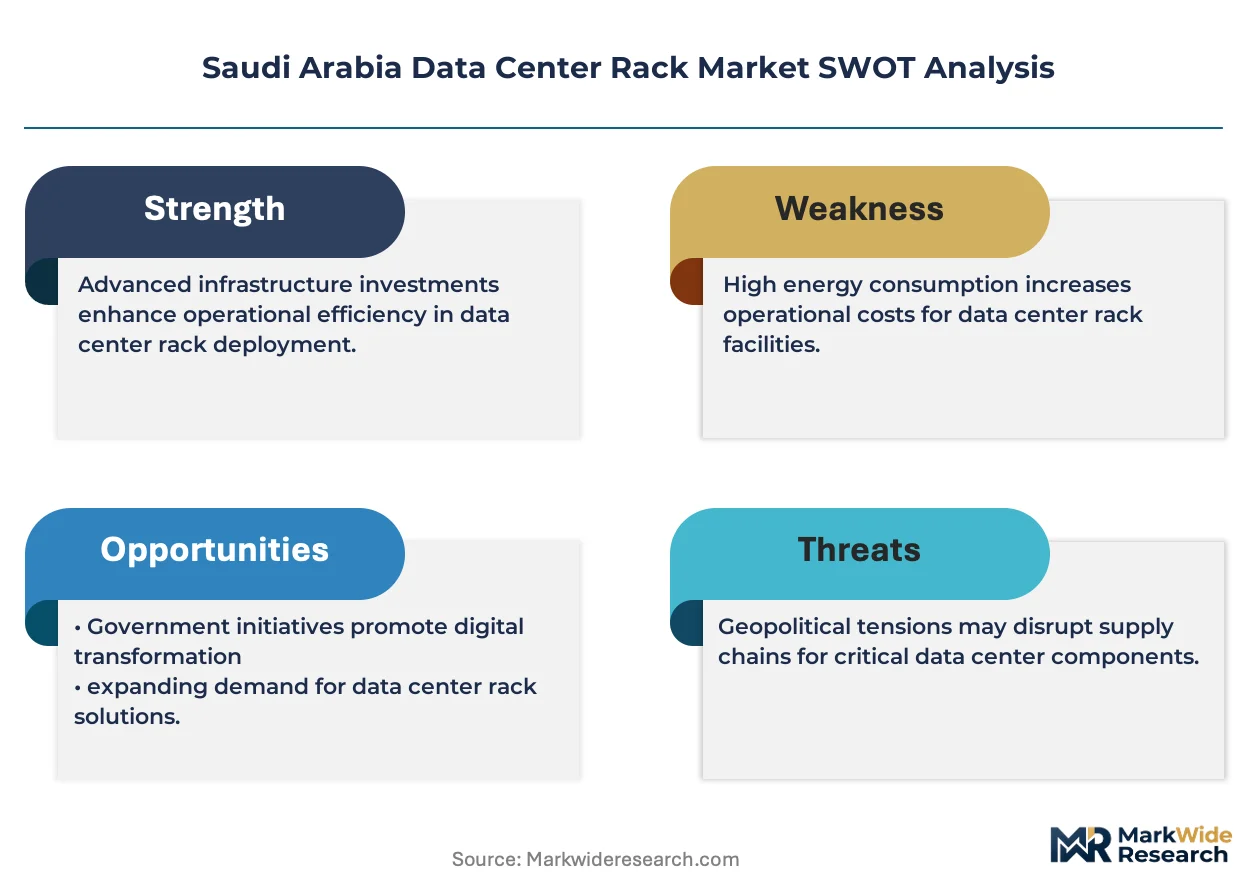
Hyperscale cloud operators are consolidating procurement power across Riyadh and Jeddah corridors, compressing margins for rack manufacturers while demanding higher thermal density specifications that legacy infrastructure cannot support.
Growth Catalysts
- Saudi Vision 2030 digital infrastructure mandates:Government cloud-first policies require sovereign data center capacity, directly stimulating rack procurement across NEOM and existing Riyadh zones.
- Edge computing deployments:Latency-sensitive applications in financial services and healthcare are driving distributed rack installations beyond traditional hyperscale clusters.
- Liquid cooling adoption:Power densities exceeding 30kW per rack necessitate thermal management upgrades that standard air-cooled enclosures cannot deliver.
Market Restraints
- Steel and aluminum input volatility:Rack enclosure manufacturing faces margin pressure from commodity price swings in structural metals.
- Supply concentration in East Asian fabrication:Overreliance on imported sheet metal components creates lead time vulnerability for Saudi integrators.
- SASO certification complexity:Product conformity assessment timelines for imported rack assemblies extend deployment schedules by 8-12 weeks.
Strategic Opportunities
- NEOM zero-carbon facility specifications:Renewable-powered data center commitments create premium demand for energy-efficient rack infrastructure with integrated power monitoring.
- Modular prefabricated data centers:Factory-integrated rack and power modules reduce on-site construction time for rapid hyperscale expansion.
- Data localization enforcement:CITC policies requiring domestic data storage are compelling international cloud providers to establish local presence through colocation partnerships.
Industry Challenges
- Thermal engineering talent scarcity:Liquid cooling system design and computational fluid dynamics expertise remains concentrated among a limited pool of specialists in the Kingdom.
- Legacy facility retrofit complexity:Existing data centers built for 10-15kW densities require structural reinforcement and power distribution upgrades to accommodate next-generation servers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Data Center Rack Market |
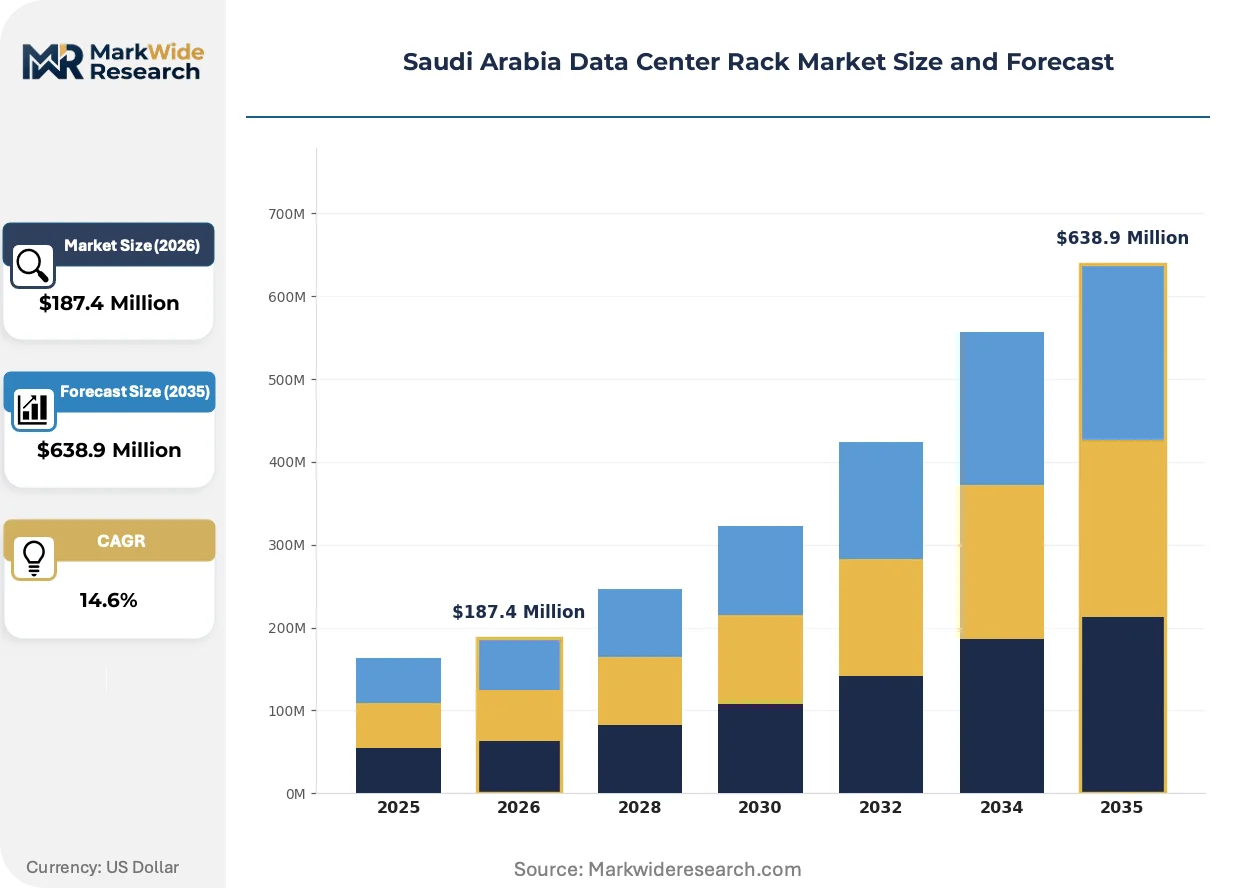
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Rack, Open Frame Rack, Rack Enclosure, Wall-Mount Rack End User: Telecommunications, BFSI, IT & Telecom, Government Deployment: On-premise, Colocation, Hybrid, Managed Services Rack Size: 42U, 45U, 48U, 24U |
| Companies Covered | Schneider Electric, Vertiv, Rittal, Eaton, Hewlett Packard Enterprise, Dell Technologies, Legrand, Panduit, Norden Communication, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Data Center Rack Market Trends and Innovations
Rack infrastructure is evolving from passive mounting hardware to intelligent thermal and power management platforms. This transformation reflects pressure from rising compute densities and sustainability mandates.
Liquid-cooled rack architectures are expanding into mainstream hyperscale deployments. These systems circulate dielectric fluid directly to processor heat sinks, enabling 50-100kW densities impossible with air cooling. Colocation operators in Riyadh's King Abdullah Financial District are retrofitting facilities with rear-door heat exchangers and immersion tanks to capture enterprise workloads migrating from legacy air-cooled environments.
SFDA equipment certification requirements and CITC telecommunications infrastructure standards are tightening electromagnetic compatibility and fire safety specifications for rack assemblies entering the Kingdom. Manufacturers must now submit thermal test data and seismic load calculations alongside traditional electrical safety documentation. This regulatory layering favors suppliers with established conformity assessment capabilities over new market entrants.
Buyers are consolidating vendor relationships around integrated infrastructure platforms that combine racks with power distribution and cooling. Single-source procurement reduces interface complexity but shifts negotiation leverage toward suppliers with full-stack capabilities. Government and banking verticals in Jeddah and Riyadh are driving this consolidation through framework agreements that specify turnkey thermal containment systems rather than discrete rack purchases.
Saudi Arabia Data Center Rack Market Segmentation
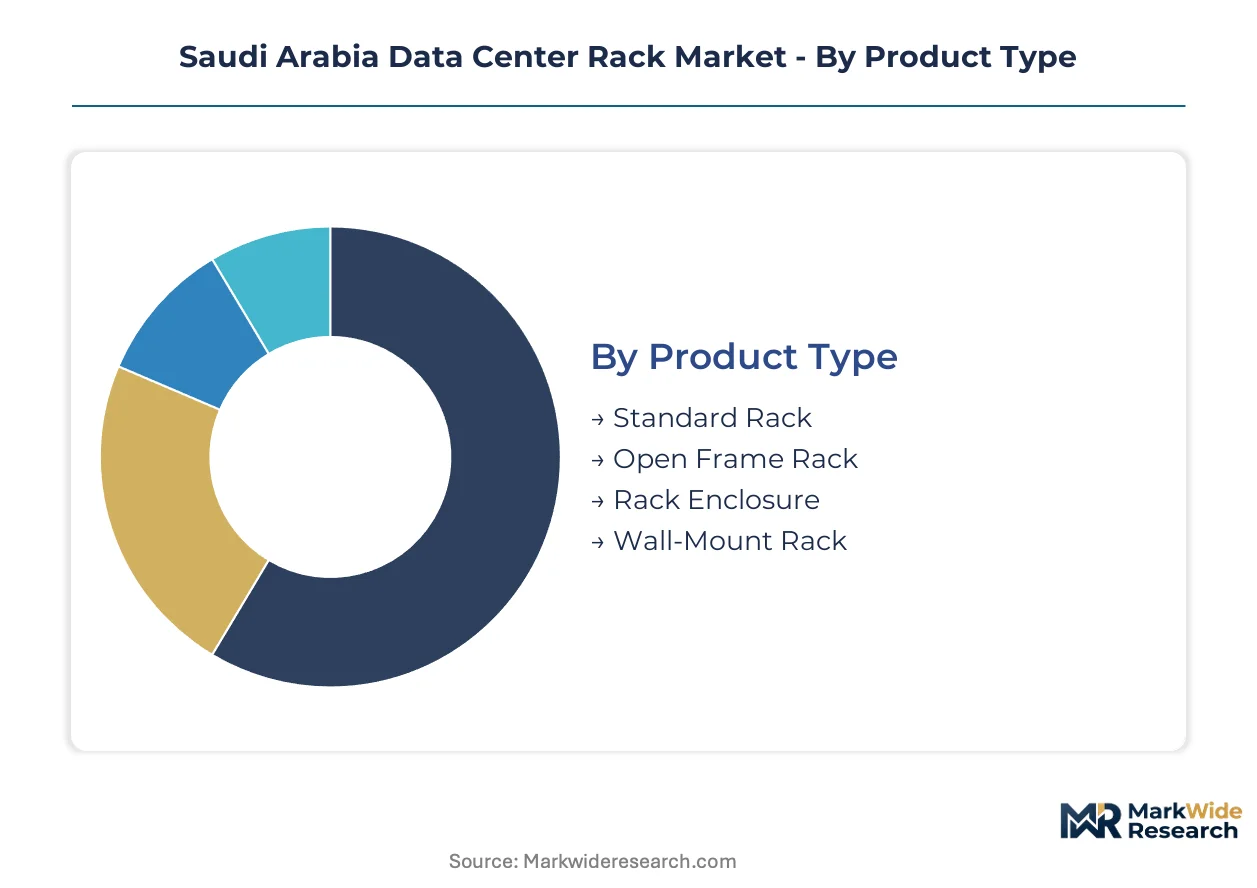
Data center rack procurement patterns in Saudi Arabia diver sharply across deployment environments and end-user compliance requirements. Product specifications must satisfy SASO conformity assessments, SFDA equipment certifications, and CITC telecommunications standards simultaneously.
Product Type:
Rack enclosure configurations face the heaviest SASO thermal test documentation burdens, while open frame variants navigate lighter electromagnetic compatibility requirements. SFDA certification complexity scales with physical security and fire suppression integration levels.
- Rack Enclosure:Sealed metal housings with integrated cable management and airflow containment systems. Demand concentrates in Riyadh's King Abdullah Financial District colocation facilities where CITC data localization policies mandate sovereign infrastructure. SASO requires seismic load calculations and thermal performance data for every enclosure imported into the Kingdom.
- Open Frame Rack:Four-post skeletal structures without side panels or doors, optimized for accessibility and ventilation. Enterprise testing labs across Jeddah's technology zones favor these for rapid equipment swap cycles where environmental sealing is secondary. SFDA equipment certification requirements apply only to power distribution components, not the frame itself.
- Standard Rack:19-inch EIA-310 compliant frames with fixed or adjustable mounting rails. Government data centers in NEOM specify these for baseline compute infrastructure under Saudi Vision 2030 procurement frameworks.
- Wall-Mount Rack:Compact enclosures secured vertically to structural surfaces for space-constrained deployments. Edge computing nodes in Dammam's industrial corridor deploy these for latency-sensitive manufacturing automation.
Leading the category by volume: Rack Enclosure. Growing fastest: Open Frame Rack.
End User:
Telecommunications carriers and government entities operate under distinct CITC spectrum licensing conditions that dictate rack physical placement and power density specifications. BFSI procurement clusters around SASO-certified thermal containment for disaster recovery mandates.
- Telecommunications:Mobile network operators and fixed-line providers deploying 5G core infrastructure. STC and Mobily are expanding Riyadh and Jeddah facilities under CITC domestic data storage requirements. These deployments drive 48U high-density configurations with integrated liquid cooling readiness.
- Government:Ministries and sovereign entities executing Saudi Vision 2030 cloud-first policies. NEOM's zero-carbon data center specifications require rack infrastructure with embedded power monitoring and renewable energy compatibility. SASO conformity timelines extend government procurement cycles significantly.
- BFSI:Banking, financial services, and insurance institutions with stringent disaster recovery obligations. SAMA regulatory expectations for operational resilience are pushing Riyadh-based banks toward colocation rack leases with guaranteed uptime tiers.
- IT & Telecom:Systems integrators and managed service providers serving enterprise clients. These intermediaries aggregate demand across verticals, standardizing on 42U rack configurations that balance density with legacy equipment accommodation.
Highest certification burden: Government. Expanding most quickly: Telecommunications.
Deployment:
Capital intensity separates deployment models, with colocation and managed services shifting SASO compliance responsibility to facility operators rather than end-users. On-premise installations require direct product conformity assessment for every rack assembly.
- Colocation:Rack space leased within multi-tenant facilities operated by specialized providers. International cloud providers are establishing presence in Riyadh and Jeddah through these arrangements to satisfy CITC data localization without facility construction. Demand centers on 45U-48U cabinets with pre-installed power distribution.
- On-premise:Enterprise-owned and operated data center infrastructure. Saudi Aramco and SABIC maintain extensive on-premise facilities with custom rack specifications for industrial control system integration. SASO certification must be obtained for each imported assembly.
- Hybrid:Architectures combining owned infrastructure with colocation burst capacity. Financial institutions in Jeddah deploy hybrid models to manage SAMA-mandated data sovereignty while accessing cloud scalability.
- Managed Services:Fully outsourced data center operations including rack infrastructure provision. Government entities under Saudi Vision 2030 digital transformation programs are outsourcing to specialized operators to accelerate deployment timelines.
Largest revenue pool: Colocation. Steepest expansion trajectory: Managed Services.
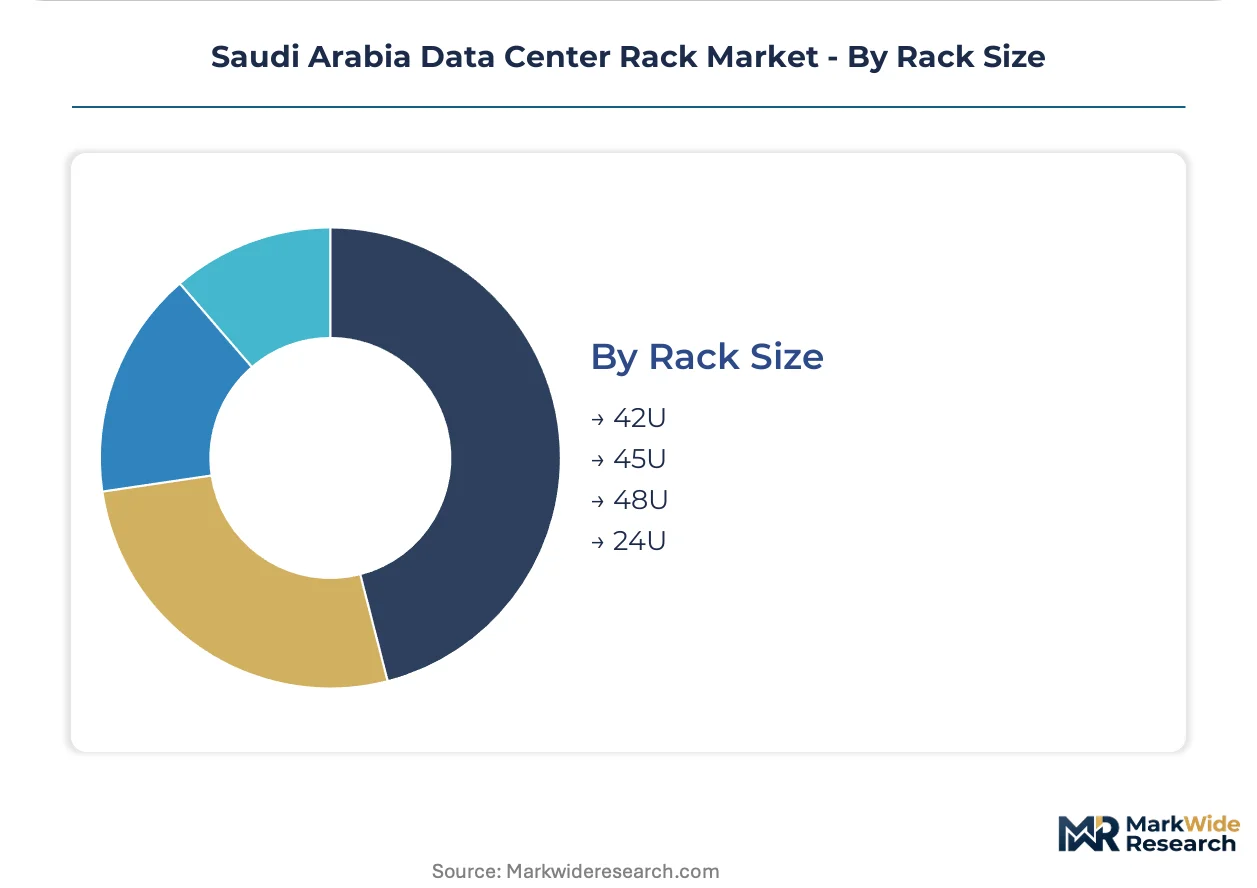
Rack Size:
Height specifications correlate directly with power density planning and cooling architecture decisions. Larger form factors face stricter SASO thermal documentation requirements due to higher heat load concentrations.
- 42U:Standard height accommodating most enterprise server configurations. This remains the procurement default across Riyadh enterprise data centers where legacy equipment mixes with newer dense compute. SASO certification protocols are well-established for this form factor.
- 48U:Extended height for maximum vertical density in hyperscale environments. NEOM's renewable-powered facilities specify these for AI training clusters where space optimization offsets premium thermal engineering costs. CITC telecommunications infrastructure standards mandate specific seismic bracing for 48U installations.
- 45U:Intermediate height gaining traction in colocation facilities seeking density differentiation. Jeddah's expanding cloud corridors specify these for enterprise-grade deployments balancing capacity with accessibility.
- 24U:Compact height for edge and remote office deployments. Industrial IoT gateways in Dammam and Jubail industrial cities utilize these for localized data processing.
Dominating procurement volume: 42U. Gaining share fastest: 48U.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic consumption of data center racks in Saudi Arabia outpaces local manufacturing capacity by a significant margin. Riyadh and Jeddah absorb the majority of imported rack assemblies. NEOM's emerging infrastructure is reshaping procurement patterns in the northwest.
Riyadh
Financial services consolidation and government cloud migration are driving rack demand in the capital. CITC data localization mandates require sovereign infrastructure deployment. King Abdullah Financial District colocation facilities are expanding 48U high-density configurations for banking disaster recovery.
Eastern Province
Industrial automation and energy sector digitization are creating edge computing rack requirements. SASO certification protocols extend procurement timelines for imported assemblies. Dammam and Jubail industrial cities are deploying 24U wall-mount racks for localized IoT data processing.
Western Region
International cloud provider entry and maritime logistics digitization are stimulating Jeddah corridor expansion. SAMA operational resilience expectations are pushing banks toward colocation rack leases. Jeddah's technology zones favor open frame racks for enterprise testing environments.
NEOM Northwest
Zero-carbon data center commitments are consolidating demand for energy-efficient rack infrastructure with embedded power monitoring. Saudi Vision 2030 digital transformation programs are outsourcing to specialized operators. The region's renewable-powered facilities specify liquid-cooled rack architectures for AI training clusters.
Saudi Arabia Data Center Rack Market Competitive Landscape
The competitive structure tilts toward integrated infrastructure platforms rather than discrete component suppliers. Hyperscale operators are consolidating vendor relationships around single-source thermal and power management systems. Three archetypes dominate: full-stack platform providers, thermal management specialists, and modular enclosure fabricators. Capacity expansion and strategic partnerships represent the dominant competitive moves as operators seek to capture NEOM and Riyadh cloud corridor contracts.
Among European-based platform providers, Schneider Electric exemplifies the integrated power and cooling architecture archetype. Vertiv occupies a position within the thermal management specialist tier, while Rittal represents the modular enclosure systems approach designed for rapid hyperscale deployment. These three anchors illustrate the competitive positioning required to serve Saudi Arabia's escalating density requirements and regulatory compliance landscape.
| Leading Market Players |
|---|
| Schneider Electric |
| Vertiv |
| Rittal |
| Eaton |
| Hewlett Packard Enterprise |
| Dell Technologies |
| Legrand |
| Panduit |
| Norden Communication |
| Others |
Pricing and Supply Chain Analysis
Hyperscale cloud operators in Riyadh and Jeddah are consolidating procurement volumes around integrated rack-cooling-power bundles, compressing supplier margins and shifting pricing power toward buyers with framework agreement leverage. This buyer concentration feeds directly into contract-based long-term offtake structures that prioritize thermal density specifications over unit cost minimization.
Pricing Analysis
Margin tightening in standard rack tiers reflects steel and aluminum input volatility from East Asian fabrication centers. Three-tier pricing structure across premium liquid-cooled, standard air-cooled, and economy open-frame levels stratifies by certification grade and integrated power monitoring capabilities. Cost-down pressure on economy enclosures accelerates because SASO certification timelines extend deployment schedules and inflate landed costs. Government and BFSI verticals demonstrate lowest price sensitivity due to sovereign infrastructure mandates, while enterprise testing labs in Jeddah's technology zones drive hardest bargain on open-frame procurement.
Supply Chain Analysis
Sheet metal fabrication for rack enclosures rests on concentrated capacity in China, South Korea, and Taiwan, with dielectric fluid supply for liquid cooling systems anchored in German and Japanese specialty chemical producers. Cold-rolled steel, aluminum extrusions, and precision-machined mounting rails constitute the core input dependencies. Single-source vulnerability in East Asian metal stamping creates lead time exposure for Saudi integrators facing CITC-mandated deployment deadlines. Distribution runs through authorized systems integrators and direct hyperscale procurement channels, with colocation operators increasingly sourcing factory-integrated modules to compress on-site construction windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Local manufacturing capacity for rack assemblies remains negligible against Saudi Arabia's procurement scale, with import dependency propping pricing premiums for rapid-delivery configurations. This supply bottleneck sustains margin capture for integrated platform providers with established conformity assessment capabilities.
For Market Incumbents: Extend thermal engineering service offerings to capture retrofit demand from legacy facilities built for 10-15kW densities. Deepen backward integration into power distribution unit manufacturing to defend margin position against hyperscale procurement consolidation. Invest in SASO pre-certification inventory buffers to compress deployment timelines against emerging competitors lacking conformity assessment infrastructure. For New Entrants and Emerging Players: Begin with edge computing rack deployments in Dammam and Jubail industrial corridors, where 24U wall-mount specifications face lighter certification burdens than hyperscale configurations. Target manufacturing automation verticals with IP65-rated enclosures for harsh environment IoT gateways. Pursue partnership routes with Saudi systems integrators already holding CITC telecommunications infrastructure approvals rather than direct hyperscale competition. For Investors and Strategic Acquirers: The window for entry favors thermal management specialists with liquid cooling IP and established Middle East project references. Acquisition targets should demonstrate computational fluid dynamics expertise and NEOM zero-carbon facility engagement. Monitor CITC data localization enforcement intensity as the signal indicating hyperscale buildout acceleration versus colocation preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Technology Licensing | Enables 50-100kW rack densities for NEOM AI training clusters under renewable power constraints. |
| SASO Certification Pre-Investment | Compresses 8-12 week conformity timelines that currently disadvantage new market entrants. |
| Modular Prefabricated Integration | Reduces on-site construction time for Riyadh hyperscale corridors facing CITC deployment deadlines. |
| Edge Computing Partnership | Captures latency-sensitive manufacturing automation demand in Eastern Province industrial cities. |
| Thermal Engineering Talent Acquisition | Addresses scarcity of liquid cooling system design expertise concentrated among limited Kingdom specialists. |
Research Methodology
Trade statistics from Saudi Customs, CITC telecommunications infrastructure filings, and SASO product conformity databases formed the secondary backbone for demand quantification. Primary interviews with data center facility operators, rack systems integrators, thermal engineering consultants, and hyperscale procurement executives combined with secondary validation to establish installation timelines and specification trends. Bottom-up rack shipment aggregation by deployment type and end-use vertical triangulated against top-down infrastructure investment flow analysis.
Historical hyperscale capex deployment patterns and colocation lease commencement data established baseline trendlines across the projection horizon. Segmentation modeling incorporated product type, rack size, deployment model, and end-use vertical dimensions with regional regulatory cluster differentiation. CAGRs derived from regression-adjusted deployment schedules reflecting Saudi Vision 2030 milestone alignment and CITC data localization enforcement intensity. Industry-specific inputs included NEOM zero-carbon facility specifications and liquid cooling adoption curves from King Abdullah Financial District retrofit activity.
Underlying measurement precision varies by segment; colocation and hyperscale deployments carry tighter precision than distributed edge installations due to visible procurement documentation. Forecasts reflect assumptions around CITC policy continuity and SASO certification timeline stability. Regulatory enforcement intensity shifts, commodity price volatility in structural metals, and thermal engineering talent availability constitute the trigger set warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Philippines Data Center Power Market
Data Center Infrastructure
Denmark Data Center Physical Security Market
Data Center Infrastructure
Global Software Defined Infrastructure (SDI) Market
Data Center Infrastructure
Israel Data Center Market
Data Center Infrastructure
Stockholm Data Center Market
Data Center Infrastructure
Data Center Asset Management Market
Data Center Infrastructure
Russia Data Center Rack Market
Data Center Infrastructure
Fault Tolerant Servers Market
Data Center Infrastructure
Mexico Data Center Rack Market
Data Center Infrastructure
Global Data Center Rack and Enclosure Market
Data Center Infrastructure
APAC Data Center Server Market
Data Center Infrastructure
Netherlands Data Center Market
Data Center Infrastructure
Hong Kong Data Center Server Market
Data Center Infrastructure
Switzerland Data Center Server Market
Data Center Infrastructure
Denmark Data Center Rack Market
Data Center Infrastructure
Taiwan Data Center Power Market