
 Data Center CPU Market | 2026-2036
Data Center CPU Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center CPU Market Analysis
High-core-count server-grade silicon is reorganizing procurement priorities across hyperscale facilities. Intel Corporation sustains manufacturing scale through captive foundry investments in Arizona and Oregon. Advanced Micro Devices differentiates via Epyc socket density advantages in virtualization workloads. Arm Holdings Plc positions its Neoverse roadmap as the efficiency alternative for cloud-native container orchestration.
A data center CPU is a multi-core x86 or Arm-based processor engineered for simultaneous multithreading, error-correcting memory support, and thermal design power envelopes exceeding 150 watts, fabricated on sub-5 nanometer process nodes for sustained throughput in always-on server environments. Xeon and Epyc product lines anchor the bulk of enterprise and cloud server sockets, while Arm-based designs capture share in power-constrained edge and hyperscale deployments. Cloud Providers and Enterprises represent the dominant end-user categories, with virtualization and large-scale analytics absorbing the majority of socket shipments.
The EPA Energy Star server specification and EU Ecodesign requirements constrain idle power draw and thermal profiles for processors sold into European facilities. The SEC climate disclosure rules and California Title 24 building standards extend compliance obligations to embodied carbon in server hardware procurement decisions. Stakeholders must weigh ISA ecosystem maturity against emerging power-efficiency mandates when selecting long-term platform commitments.
Market Dynamics
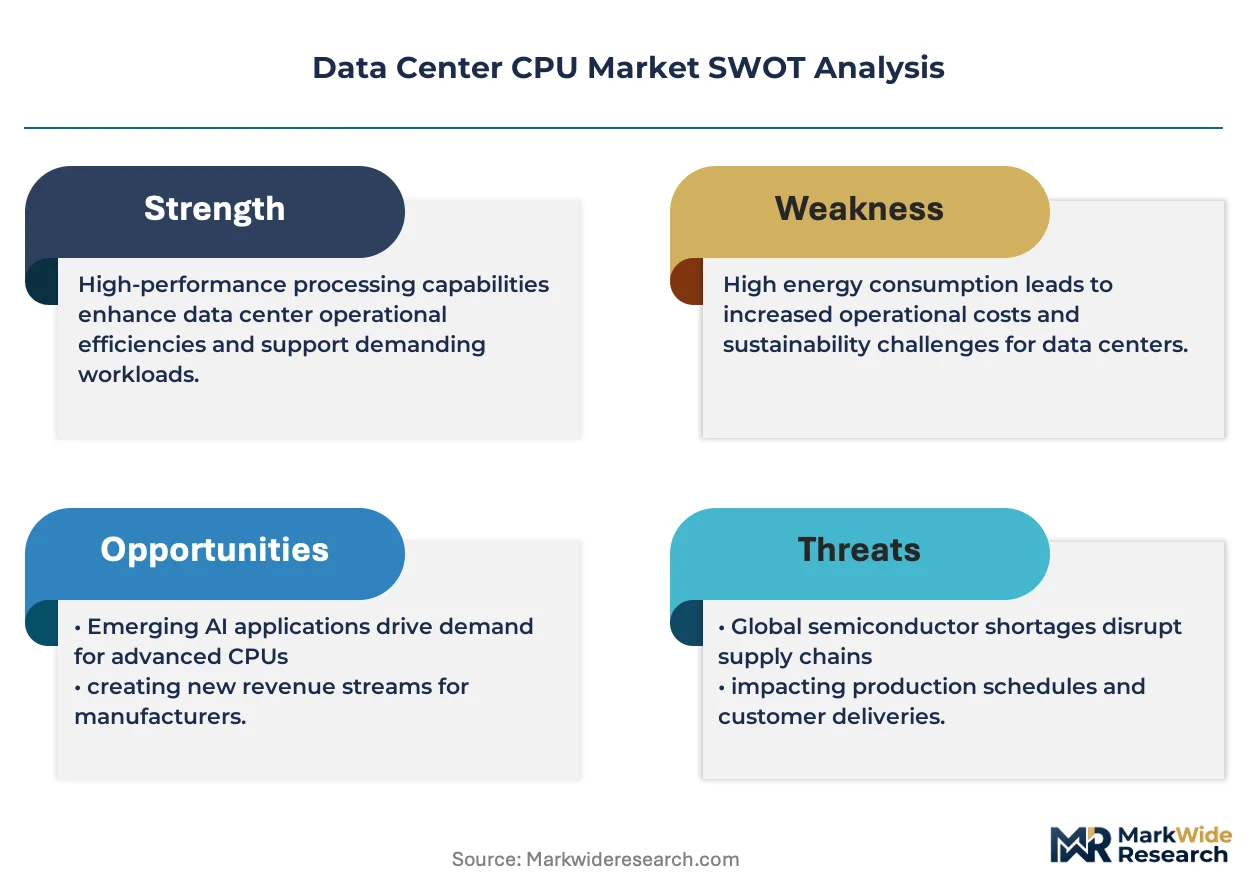
Hyperscale cloud operators are consolidating server procurement around high-core-density silicon architectures, compressing socket volumes while amplifying per-unit performance requirements and thermal design power thresholds.
Growth Catalysts
- AI Training Clusters:Generative model deployment is pulling thousand-plus GPU-accelerated server configurations into production, each requiring companion host CPUs with expanded PCIe lane counts and memory bandwidth.
- EU Ecodesign Mandates:Idle power caps under the EU F-Gas Regulation and Ecodesign requirements are accelerating replacement cycles in Frankfurt, Amsterdam, and Dublin facilities.
- Container Orchestration Density:Kubernetes-native workloads favor Arm-based Neoverse sockets for per-watt throughput advantages in hyperscale rack deployments.
Market Restraints
- Advanced Substrate Bottlenecks:CoWoS and EMIB packaging capacity constraints at Taiwan-based foundries limit high-end server CPU output regardless of wafer availability.
- US Export Controls:Commerce Department licensing restrictions on sub-7 nanometer fabrication equipment are fragmenting supply assurance for China-bound server shipments.
- DDR5 Memory Cost Volatility:PMIC component shortages and yield challenges at Korean memory houses are inflating platform-level bill-of-materials for new socket generations.
Strategic Opportunities
- India Data Center Buildout:Noida, Mumbai, and Chennai cloud regions under the PLI scheme offer greenfield deployment paths for efficiency-optimized processor architectures.
- Liquid Cooling Convergence:Direct-to-chip cold plate integration with high-TDP silicon is opening retrofit and new-build service revenue streams for thermal infrastructure vendors.
- SEC Climate Disclosure Alignment:Embodied carbon reporting requirements are creating procurement preference for foundries with verified renewable energy supply chains.
Industry Challenges
- Chiplet Integration Complexity:Multi-die packaging architectures are extending validation timelines and stressing thermal-mechanical co-design capabilities at OEMs.
- Firmware Supply Chain Attestation:C-SCRM mandates from NIST and equivalent EU frameworks require traceable signing authority across BIOS, BMC, and microcode update streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center CPU Market |
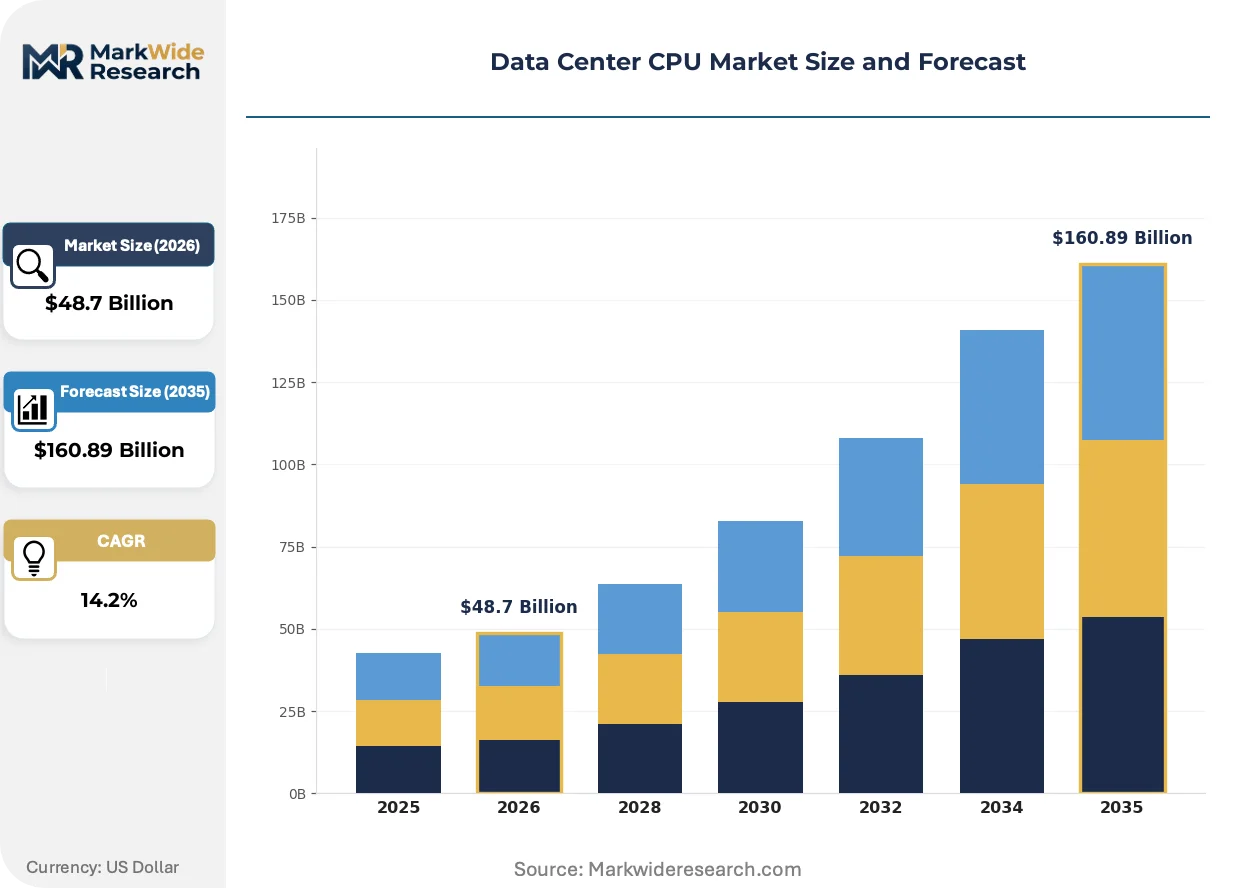
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $160.89 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Xeon, Epyc, Arm-based, Power9 Technology: Multi-core, Hyper-threading, 64-bit Architecture, Integrated Graphics End User: Cloud Providers, Enterprises, Telecom, Research Institutions Application: Virtualization, High-Performance Computing, Large Scale Analytics, Data Storage |
| Companies Covered | Amazon Web Services, Broadcom Inc, Intel Corporation, Qualcomm Incorporated, Arm Holdings Plc, Advanced Micro Devices, Google LLC, IBM Corporation, NVIDIA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center CPU Market Emerging Trajectories
Processor architecture roadmaps are diverging between throughput-maximized x86 designs and efficiency-optimized Arm alternatives, with packaging technology and memory subsystem choices becoming primary competitive differentiators.
Chiplet-based CPU construction is bifurcating the market into monolithic-die legacy platforms and disaggregated designs mixing compute, I/O, and cache tiles from heterogeneous process nodes. Hyperscale operators in Oregon and Virginia are qualifying these configurations for 2025-2026 rack refreshes. The structural consequence is compressing time-to-market for socket derivatives while concentrating advanced packaging capability among three foundry ecosystems.
The EU AI Act risk-classification framework is mandating conformity assessment procedures for high-performance computing infrastructure deployed in European Economic Area facilities. Server OEMs must now document training data provenance and model card transparency for AI-optimized CPU-GPU configurations. German and French data center operators are front-loading procurement specifications with these attestation requirements ahead of full enforcement.
Enterprise buyers are consolidating server purchases around vertically integrated cloud-adjacent configurations rather than discrete component sourcing. Systems integrators and direct OEM channels are displacing traditional distributor relationships for socket volumes above five hundred units annually. This concentration is most visible across Virginia's Northern Virginia data center corridor and Singapore's Tuas industrial zone.
Data Center CPU Market Segmentation
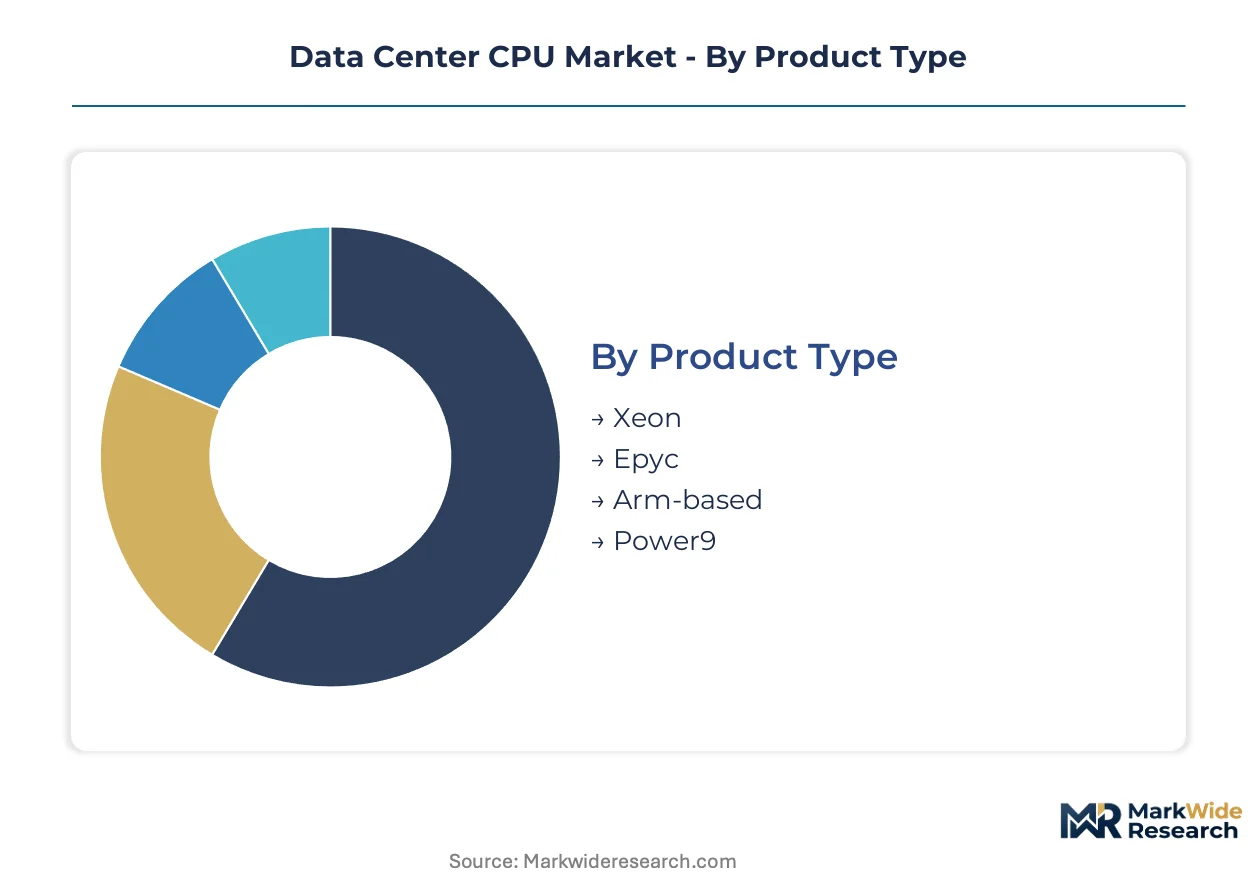
Data center CPU procurement decisions fragment across four intersecting dimensions: instruction set architecture, silicon packaging technology, buyer organizational type, and workload computational profile. Each segmentation axis carries distinct regulatory, thermal, and ecosystem constraints that reshape supplier qualification timelines.
Product Type:
EU Ecodesign idle-power caps and EPA Energy Star server specifications create divergent certification burdens across x86 and alternative ISA portfolios.
- Xeon:Intel's x86 server processor line delivers mature virtualization ecosystems with established error-correcting memory support and broad OEM qualification. Virginia and Oregon hyperscale clusters consume the majority of socket volumes for legacy enterprise workload migration.
- Epyc:AMD's multi-chiplet x86 architecture emphasizes socket density and PCIe lane expansion for GPU-accelerated AI host configurations. Frankfurt and Amsterdam facilities are standardizing on these packages for Ecodesign-compliant rack refreshes.
- Arm-based:Neoverse-derived silicon targets per-watt efficiency in container-native deployments.
- Power9:IBM's RISC architecture retains footprint in specialized HPC and financial services mainframe environments.
Xeon handles the majority of throughput; Arm-based is the fastest mover on share.
Technology:
Process node maturation and packaging yield economics concentrate competitive advantage among foundries with verified sub-5 nanometer capacity.
- Multi-core:Die-level core count scaling defines thermal design power envelopes and direct-to-chip liquid cooling requirements. High-core-count chiplets from Taiwan-based foundries dominate Oregon and Singapore qualification pipelines.
- Hyper-threading:Simultaneous multithreading doubles logical processor exposure to virtualization hypervisors. Cloud Providers in Northern Virginia mandate this capability for Kubernetes node density optimization.
- 64-bit Architecture:Memory address space expansion enables terabyte-scale DRAM configurations for in-memory analytics.
- Integrated Graphics:On-die GPU blocks accelerate lightweight inference and display output without discrete accelerator cards.
Multi-core absorbs the bulk of silicon area investment; Hyper-threading is climbing the fastest as a mandatory procurement checkbox.
End User:
Buyer scale and compliance sophistication stratify pricing power, with hyperscale direct procurement displacing channel intermediaries above five-hundred-unit annual thresholds.
- Cloud Providers:Hyperscale operators in Virginia, Oregon, and Singapore consolidate socket procurement around vertically integrated server configurations. SEC climate disclosure rules and EU CSRD obligations drive renewable energy supply chain verification requirements.
- Enterprises:Corporate data centers in Germany and France face EU AI Act conformity assessments for high-performance computing infrastructure. These buyers favor x86 ecosystem maturity over architectural experimentation.
- Telecom:Edge computing deployments in India and Japan prioritize power-constrained Arm-based sockets for 5G core virtualization.
- Research Institutions:National laboratories in the United States and European member states access controlled-technology CPUs through export-licensed channels.
Cloud Providers command the dominant procurement volume; Telecom is expanding most quickly as edge infrastructure buildouts accelerate.
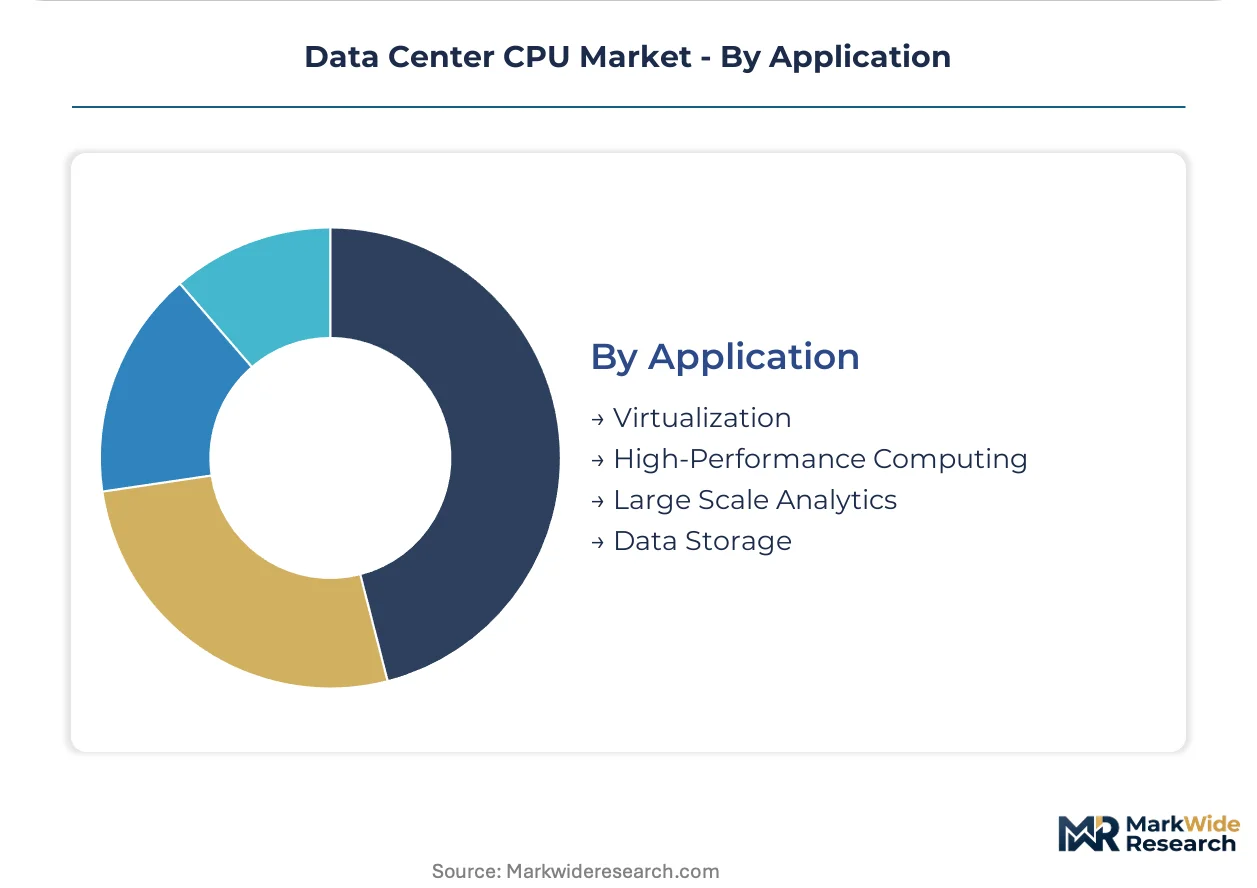
Application:
Workload computational intensity and memory bandwidth requirements determine socket selection, with AI training clusters pulling specialized host CPU configurations into production.
- Virtualization:Hypervisor-consolidated workloads demand high core counts and robust I/O virtualization extensions. This segment concentrates in Northern Virginia and Frankfurt enterprise colocation facilities.
- High-Performance Computing:MPI-parallelized scientific computing favors high-memory-bandwidth architectures with HBM integration. US national laboratories and European supercomputing centers anchor demand.
- Large Scale Analytics:Spark and Hadoop-derived workloads scale horizontally across commodity x86 clusters.
- Data Storage:Software-defined storage controllers prioritize PCIe lane density for NVMe fabric attachment.
Virtualization maintains the largest installed base; High-Performance Computing is gaining share fastest as AI training clusters proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export controls on sub-7 nanometer fabrication equipment have shifted trade flows for server-grade processors. The United States maintains net import reliance on advanced packaging capacity concentrated in East Asian foundries. Germany and France are accelerating domestic certification regimes to reduce technology dependency.
United States
Virginia's Northern Virginia data center corridor and Oregon's Hillsboro cluster absorb the majority of hyperscale socket procurement. SEC climate disclosure rules mandate embodied carbon reporting for server hardware acquisitions. Cloud providers in these regions are consolidating procurement around vertically integrated configurations exceeding five hundred units annually.
Germany
Frankfurt and Berlin facilities face accelerated replacement cycles under EU Ecodesign idle-power caps and F-Gas Regulation mandates. The KBA and federal environment ministry are tightening processor thermal certification requirements. Bavarian data center operators are front-loading procurement specifications with EU AI Act conformity assessments ahead of full enforcement.
China
Domestic cloud operators are scaling deployments despite Commerce Department licensing restrictions on advanced lithography equipment. MIIT and SAMR are promoting indigenous server CPU architectures through dual carbon goals and localization targets. Yangtze River Delta facilities in Shanghai and Suzhou are qualifying captive foundry production for non-export workloads.
India
Noida, Mumbai, and Chennai cloud regions are expanding under the PLI scheme for electronics manufacturing. CEA and TRAI guidelines are shaping power infrastructure standards for hyperscale facilities. Telangana and Karnataka state governments are offering greenfield deployment incentives for efficiency-optimized processor architectures.
Singapore
Tuas industrial zone is consolidating Southeast Asian cloud demand with strict energy efficiency procurement standards. The country's national environment agency is enforcing thermal design power thresholds for new data center approvals. Operators are qualifying Arm-based sockets for container-native deployments to meet per-watt throughput requirements.
Data Center CPU Market Vendor Landscape
Listed leaders compete with private specialists across captive foundry investments and architectural licensing models. The vendor base concentrates around three foundry ecosystems with verified sub-5 nanometer capacity. Strategic archetypes include captive foundry operators, fabless chiplet designers, and cloud-native silicon architects. Competitive moves center on multi-die packaging partnerships and renewable energy supply chain verification for SEC and CSRD compliance.
Within the captive foundry tier, Intel Corporation and Advanced Micro Devices anchor x86 ecosystem maturity through Arizona and Oregon manufacturing investments. Arm Holdings Plc occupies a licensing-centric position enabling Neoverse-derived efficiency optimization for hyperscale rack deployments. These three entities exemplify the divergence between throughput-maximized and power-optimized architectural roadmaps reshaping procurement qualification timelines.
| Leading Market Players |
|---|
| Amazon Web Services |
| Broadcom Inc |
| Intel Corporation |
| Qualcomm Incorporated |
| Arm Holdings Plc |
| Advanced Micro Devices |
| Google LLC |
| IBM Corporation |
| NVIDIA Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts with Taiwan-based foundries lock in wafer supply and price visibility for hyperscale cloud operators, insulating procurement teams from spot-market volatility in advanced packaging substrates while committing to fixed thermal design power specifications under EU Ecodesign mandates.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Premium tiers command certification premiums for SEC climate disclosure alignment and renewable energy supply chain verification, while economy sockets face cost compression from DDR5 memory PMIC shortages and yield challenges at Korean memory houses. Cloud providers with annual volumes exceeding five hundred units exercise strongest pricing leverage through direct OEM channels, whereas research institutions show highest price sensitivity due to grant-funded procurement cycles.
Supply Chain Analysis
Port congestion on transpacific trade lanes from Kaohsiung and Busan to Long Beach elevates inbound logistics costs for substrate shipments, compressing margin buffers for server OEMs. Foundry output concentrates in Taiwan, South Korea, and the United States, with CoWoS and EMIB packaging capacity serving as the binding constraint regardless of wafer availability. The supply chain draws from silicon wafers, advanced organic substrates, and DDR5 memory modules, with single-source vulnerability in Taiwan-based advanced packaging creating structural risk. Distribution runs through vertically integrated hyperscale direct procurement and systems integrator channels, displacing traditional distributors above volume thresholds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Data Center CPU Market is entering a cyclical recovery phase driven by hyperscale AI training cluster buildouts, with thousand-plus GPU-accelerated server configurations pulling companion host CPU demand through expanded PCIe lane requirements.
For Market Incumbents: Fortify captive foundry investments in Arizona and Oregon against Arm-based Neoverse encroachment in container-native workloads. Prioritize thermal-mechanical co-design capabilities to compress chiplet validation timelines, and secure renewable energy supply chain verification ahead of full EU CSRD enforcement to defend procurement preference among SEC-regulated cloud operators.
For New Entrants and Emerging Players: EU AI Act conformity assessment fast-tracks offer entry velocity for specialized HPC configurations in Frankfurt and Bavarian facilities. Target edge computing deployments in India's PLI scheme regions where power-constrained Arm-based sockets penetrate 5G core virtualization, and pursue channel partnerships with systems integrators displacing legacy distributor relationships.
For Investors and Strategic Acquirers: Fabless chiplet designers with verified sub-5 nanometer foundry partnerships represent the priority acquisition archetype for medium-term platform consolidation. Long-term viability hinges on backward integration into advanced packaging capability or exclusive capacity reservation structures. Monitor Commerce Department licensing restriction enforcement as the critical inflection signal for supply assurance fragmentation in China-bound shipments.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Reservation | Long-term offtake agreements with Taiwan-based foundries secure wafer supply ahead of CoWoS packaging constraints. |
| Liquid Cooling Integration | Direct-to-chip cold plate partnerships with thermal infrastructure vendors open retrofit revenue streams for high-TDP silicon. |
| EU AI Act Conformity Certification | Documented training data provenance and model card transparency accelerate qualification in Frankfurt and Berlin facilities. |
| Renewable Energy Supply Chain Verification | Verified clean energy sourcing addresses SEC climate disclosure rules and EU CSRD embodied carbon reporting requirements. |
| Chiplet Architecture Licensing | Multi-die packaging IP partnerships concentrate competitive advantage among three foundry ecosystems with sub-5 nanometer capacity. |
Methodological Framework
Operator-level perspectives from cloud procurement executives, server OEM platform engineers, foundry account managers, and thermal infrastructure vendors anchored the qualitative base. Primary interviews triangulated with secondary validation from SEC 10-K filings, hyperscaler capex disclosures, EU regulatory filings, and customs trade data. Bottom-up socket shipment modeling and top-down market sizing converged across the analysis window.
Sensitivity analysis tested forecast robustness across the projection horizon. The analytical framework segmented by instruction set architecture, silicon packaging technology, buyer organizational type, and workload computational profile. CAGRs derived from unit shipment trajectories and average selling price evolution, incorporating foundry capacity expansion schedules and regulatory compliance timeline assumptions specific to EU Ecodesign and SEC disclosure mandates.
Underlying assumptions cover sustained hyperscale AI cluster deployment, stable foundry yield progression, and intact transpacific logistics corridors, with deviation risk concentrated in Commerce Department export control expansion and advanced packaging capacity constraints. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Italy Smart Home Market
Others
Enterprise Video Content Management Market
Others
Canada Laser Hair Removal Market
Others
Nanomedicine for Drug Delivery Market
Others
Industrial Personal Computer Market
Others
Induced Pluripotent Stem Cells (Ipscs) Market
Others
Content Experience Platforms Market
Others
Basketball Apparel Market
Others
Biopharma Plastics Market
Others
North America Commercial Vehicles Lubricants Market
Others
Middle East and Africa Cocoa Products Market
Others
Global Smart Kitchen Market
Others
Cathode Battery Material Market
Others
Middle East Paper Making Machine Market
Others
Storage Dewar and Dry Shipper Market
Others
Versatile Video Coding Market