
 Multi Cloud Storage Market | 2026-2036
Multi Cloud Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Multi Cloud Storage Market Outlook
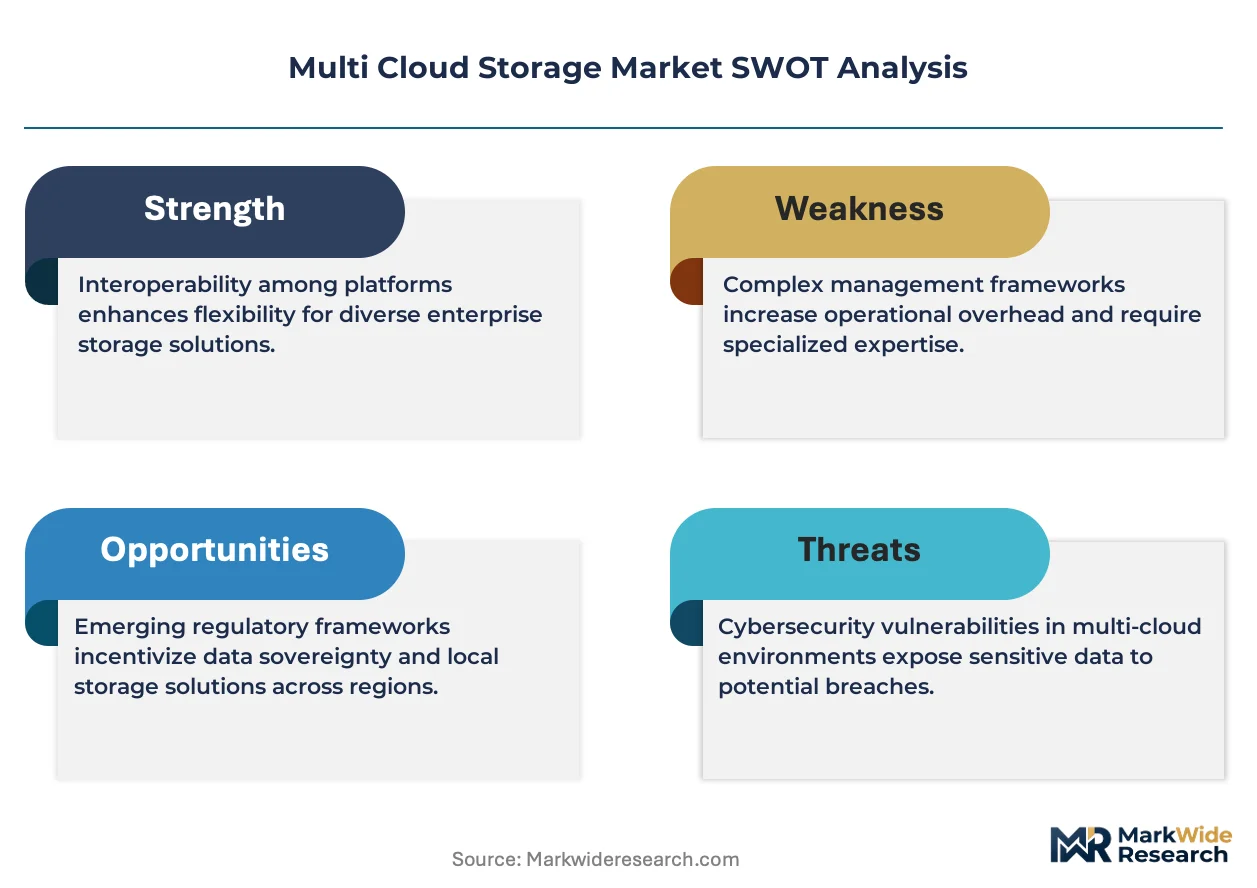
Container-native object storage is rewriting enterprise data architectures by decoupling workloads from single-vendor lock-in. Amazon Web Services leverages its early infrastructure investments to sustain hyperscale dominance across North American workloads. Microsoft Azure anchors hybrid cloud deployments through deep Active Directory integration and on-premises bridging. Google Cloud differentiates with AI-optimized storage tiers that attract analytics-intensive customers.
Multi cloud storage refers to distributed data architectures spanning two or more independent cloud service providers, typically orchestrated through Kubernetes-native control planes and S3-compatible APIs with sub-100ms latency SLAs. These systems enable workload portability, vendor negotiation leverage, and compliance-driven data sovereignty across jurisdictional boundaries. Hybrid cloud deployment captures the largest revenue pool as enterprises retain sensitive workloads on-premises while bursting to public infrastructure. Disaster recovery solutions within the solution type category represent the fastest-expanding margin segment as ransomware frequency elevates recovery-time-objective requirements. Managed services under the service model dimension lead contract value per customer by absorbing operational complexity that internal IT teams lack bandwidth to address.
ISO 27001 certification and SOC 2 Type II attestation frame baseline trust requirements for multi-cloud providers seeking enterprise procurement approval. The EU AI Act and GDPR impose data residency constraints that directly shape provider selection and architecture design in European deployments. Stakeholders must monitor evolving cross-border data transfer mechanisms and sovereign cloud mandates as these regulatory instruments increasingly determine viable market access strategies.
Market Dynamics
Container-native object storage architectures are decoupling enterprise workloads from single-vendor infrastructure lock-in, forcing providers to compete on API compatibility and latency SLAs rather than proprietary ecosystem capture.
Growth Catalysts
- EU AI Act data residency mandates:European financial services firms must maintain audit trails within jurisdictional boundaries, accelerating sovereign cloud procurement across Germany, France, and the Netherlands.
- Ransomware recovery-time compression:Enterprise disaster recovery teams now demand sub-15-minute recovery point objectives, expanding managed backup service contracts.
- Kubernetes orchestration standardization:S3-compatible APIs enable workload portability across hyperscale providers, reducing switching costs for data-intensive analytics pipelines.
Market Restraints
- Cross-border data transfer uncertainty:Schrems II rulings invalidate Privacy Shield mechanisms, complicating EU-US data flows for multinational enterprises.
- Specialized talent scarcity:Cloud architecture engineers with multi-vendor certification command premium compensation, constraining mid-market adoption velocity.
- Egress fee accumulation:Data retrieval charges across three or more providers create unpredictable cost structures that finance teams struggle to forecast.
Strategic Opportunities
- India's data localization requirements:RBI directives mandate domestic storage for payment systems, creating demand for indigenous multi-cloud infrastructure.
- Edge-to-core synchronization:5G manufacturing deployments in Germany require real-time data consistency between factory floors and centralized archives.
- Carbon-aware storage tiering:EU Green Deal reporting obligations reward providers offering renewable-energy-matched capacity scheduling.
Industry Challenges
- Legacy mainframe integration:Financial institutions struggle to reconcile decades-old COBOL-based record systems with cloud-native object APIs.
- ISO 27001 audit fatigue:Multi-cloud architectures require separate certification cycles for each provider, extending compliance timelines by 6-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi Cloud Storage Market |
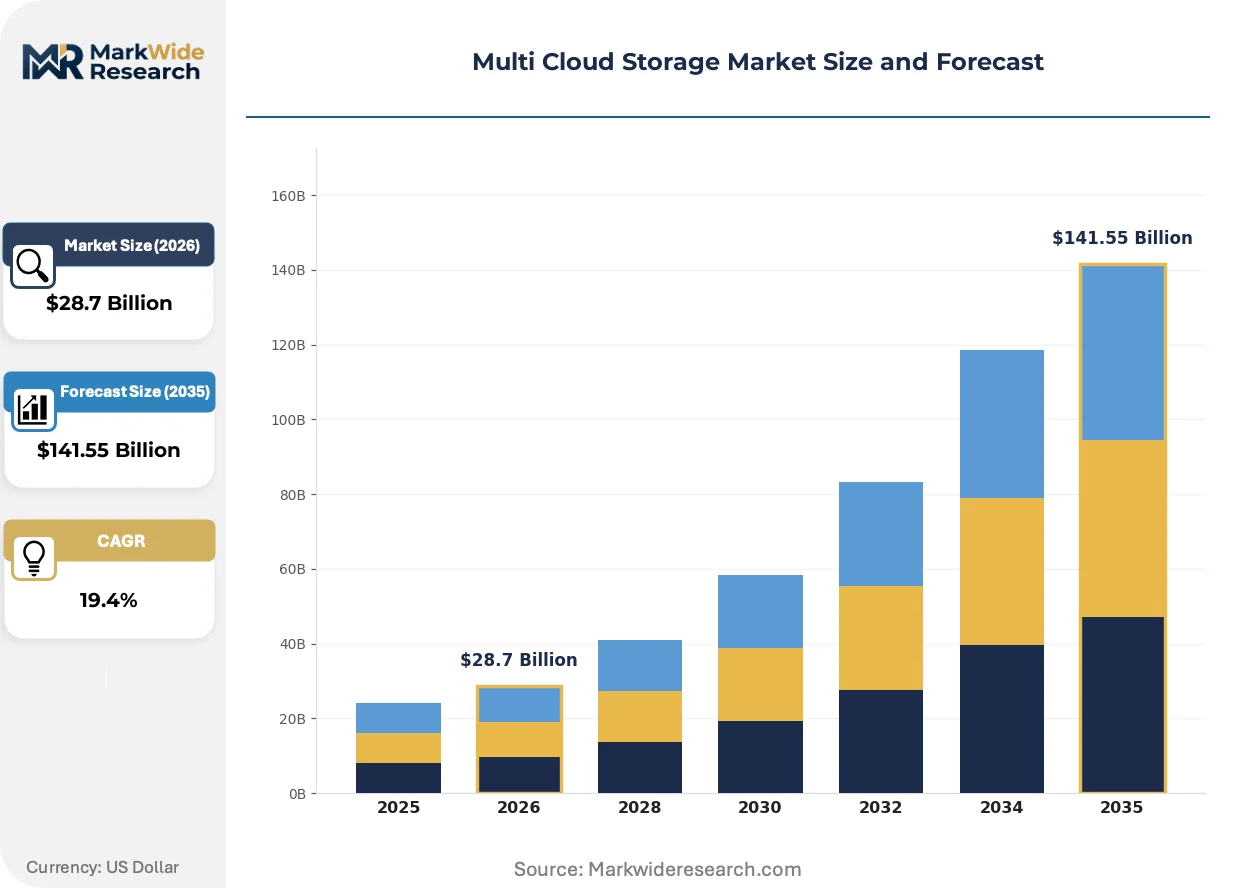
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $141.55 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Solution Type: Backup Solutions, Disaster Recovery, Archiving Solutions, Data Migration End User: SMBs, Enterprises, Government Agencies, Educational Institutions Service Model: IaaS, PaaS, SaaS, Managed Services |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud, IBM, VMware, Hewlett Packard Enterprise, Dell Technologies, Nasuni, Qumulo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi Cloud Storage Market Strategic Shifts
Immutable storage architectures and AI-optimized data tiering are redefining how enterprises balance cost, performance, and compliance across distributed infrastructure footprints.
Erasure coding with local reconstruction codes is migrating from hyperscale-only deployments to mid-market object storage platforms. Healthcare and media archives in the United States now adopt these algorithms to reduce replication overhead by 40-50% while maintaining eleven-nines durability guarantees. This compression of redundancy costs enables smaller enterprises to match the data protection standards previously exclusive to cloud-native giants.
The EU AI Act's training data documentation requirements are forcing storage providers to implement automated lineage tracking and provenance hashing. German automotive manufacturers must now demonstrate that AI model inputs reside within European Economic Area boundaries throughout the development lifecycle. This regulatory pressure is accelerating investment in geo-fenced storage pools with cryptographic attestation capabilities.
Consumption-based procurement through marketplace aggregators is displacing direct enterprise contracts with individual hyperscalers. Mid-sized technology firms in the United Kingdom now procure multi-cloud capacity through FinOps platforms that normalize pricing and automate workload placement optimization. This intermediation compresses provider margins while transferring operational complexity to specialized third-party orchestrators.
Multi Cloud Storage Market Segmentation
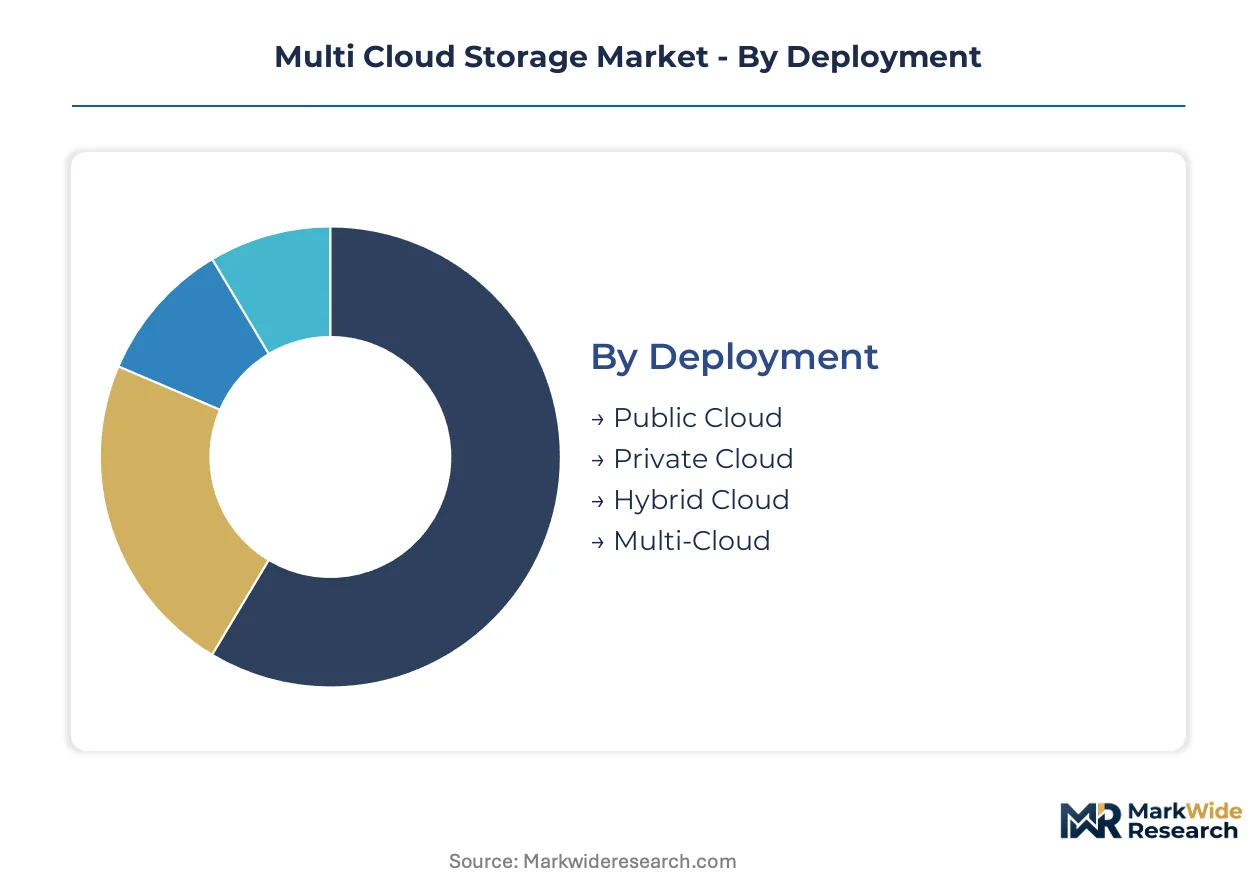
Multi-cloud storage architectures fragment across deployment topologies, solution purposes, and operational models. Understanding these segment boundaries clarifies where vendor competition intensifies and where procurement decision-making concentrates across enterprise IT hierarchies.
Deployment:
Post-deployment service intensity varies dramatically across infrastructure models, with hybrid and multi-cloud configurations demanding sustained architectural support.
- Hybrid Cloud:Combines on-premises infrastructure with public cloud bursting, requiring continuous workload orchestration and latency optimization. German automotive manufacturers anchor sensitive design data locally while bursting simulation workloads to public infrastructure. This deployment captures the largest revenue pool as enterprises retain sovereignty over critical datasets.
- Multi-Cloud:Distributes workloads across two or more independent hyperscale providers, eliminating single-vendor dependency. Financial services firms in the Netherlands adopt this model to satisfy Dutch Central Bank resilience mandates while negotiating favorable contract terms. Momentum sits with this segment as container-native orchestration matures.
- Public Cloud:Delivers storage capacity through shared infrastructure with metered consumption billing. Startups and digital-native enterprises favor this model for zero capital expenditure entry.
- Private Cloud:Deploys dedicated infrastructure within enterprise-controlled facilities or single-tenant hosted environments. Defense contractors and intelligence agencies mandate this topology for classified information handling.
Hybrid Cloud holds the largest share; momentum sits with Multi-Cloud.
Solution Type:
Commercial gravity shifts toward solutions that compress recovery timelines and automate compliance documentation.
- Disaster Recovery:Replicates production environments across geographically separated zones to enable rapid failover. Ransomware frequency has compressed recovery-time-objective requirements to sub-15-minute thresholds, expanding managed service contracts. Healthcare systems in France prioritize this capability to maintain patient care continuity during cyber incidents.
- Backup Solutions:Creates point-in-time copies of production data with configurable retention policies. Immutable backup architectures attract financial institutions seeking SEC-compliant record preservation.
- Archiving Solutions:Migrates infrequently accessed data to cost-optimized cold storage tiers with extended retrieval latency. Media companies leverage these systems for decades-long content preservation.
- Data Migration:Orchestrates bulk transfer of datasets between cloud providers or from legacy on-premises systems. EMEA enterprises deploying this solution face EU AI Act provenance documentation requirements.
Backup Solutions holds the largest installed base; Disaster Recovery is climbing the fastest.
End User:
Procurement sophistication and contract scale diverge sharply across organizational categories.
- Enterprises:Maintain dedicated cloud architecture teams with multi-vendor certification requirements. These organizations negotiate enterprise licensing agreements spanning three-year horizons with committed spend thresholds.
- Government Agencies:Mandate FedRAMP, ISO 27001, or sovereign cloud certifications depending on jurisdiction. India's Ministry of Electronics and Information Technology directs domestic data localization for citizen records.
- SMBs:Procure through managed service providers and marketplace aggregators rather than direct hyperscale contracts. UK mid-market technology firms normalize pricing across providers through FinOps platforms.
- Educational Institutions:Leverage discounted academic pricing and research grant funding for storage infrastructure. University research consortia share multi-tenant deployments to achieve scale economics.
Enterprises holds the largest share; Government Agencies are gaining share fastest.
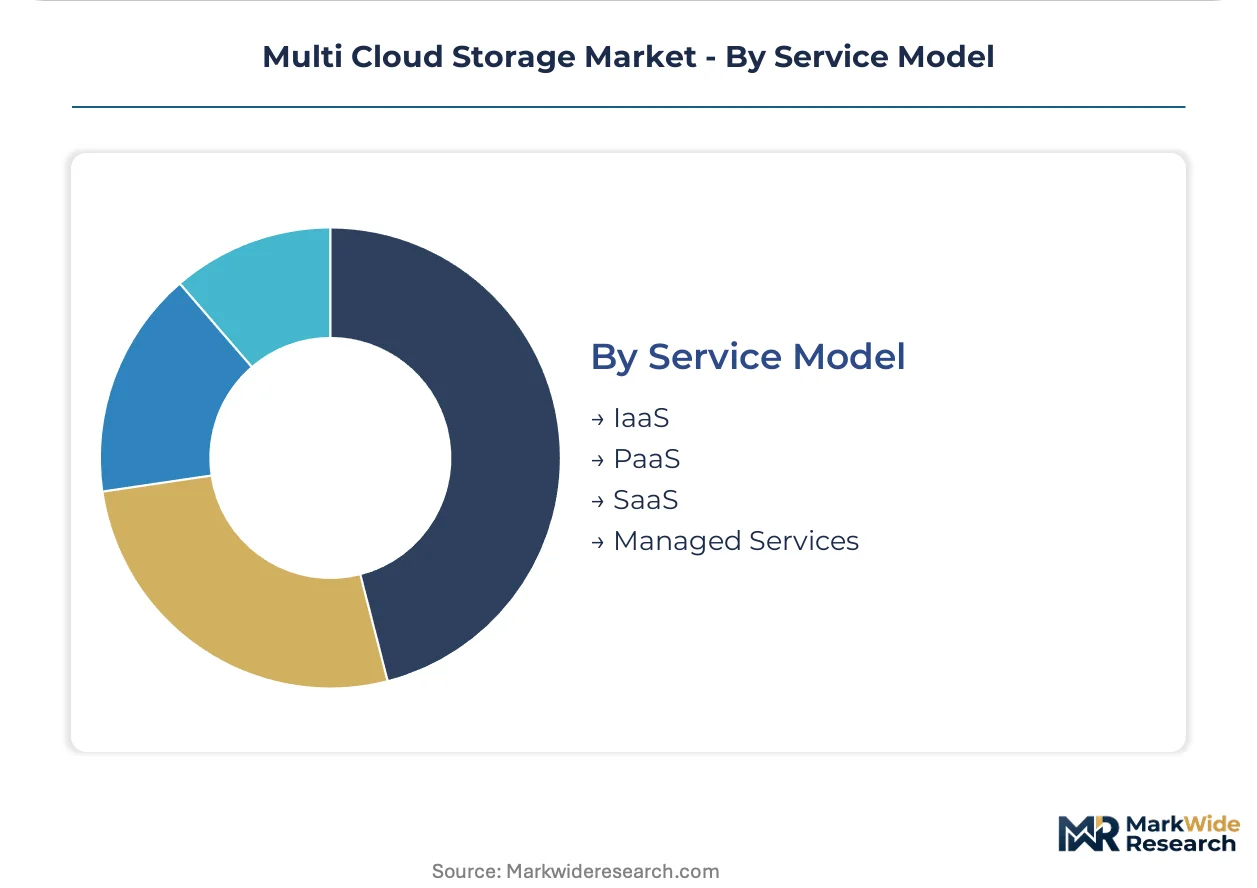
Service Model:
Margin structure and operational responsibility allocation define competitive positioning across delivery mechanisms.
- Managed Services:Absorbs full operational responsibility including monitoring, patching, capacity planning, and cost optimization. Internal IT teams at mid-market manufacturing firms lack bandwidth for multi-vendor orchestration, driving contract value concentration here.
- IaaS:Provides raw compute and storage resources with customer-managed operating systems and applications. Infrastructure teams retain maximum configuration flexibility at the cost of operational burden.
- PaaS:Delivers application development frameworks with integrated database and middleware services. Software vendors accelerate release cycles by outsourcing underlying infrastructure management.
- SaaS:Offers complete application functionality with embedded storage services invisible to end users. Collaboration platforms and analytics tools embed this model by default.
Managed Services holds the largest share; PaaS is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive manufacturers export connected vehicle data processing services to North American fleet operators, establishing cross-Atlantic data corridors that require jurisdictional compliance architectures.
Germany
Automotive AI training pipelines and industrial IoT analytics drive sovereign cloud procurement. The EU AI Act mandates training data residency documentation, compelling BMW and Siemens to deploy geo-fenced storage pools. Bavarian manufacturing clusters around Munich and Ingolstadt anchor multi-cloud orchestration for autonomous vehicle development.
United States
Healthcare ransomware recovery and SEC-compliant financial record retention compress recovery-time objectives to sub-15-minute thresholds. HIPAA and state-level privacy laws fragment compliance requirements across California, Texas, and New York. Healthcare systems in Greater Boston prioritize immutable backup architectures for patient care continuity.
India
Payment system data localization and digital public infrastructure expansion accelerate indigenous cloud capacity buildout. RBI directives mandate domestic storage for UPI transaction logs and lending records. Mumbai and Bangalore financial technology clusters drive demand for multi-cloud disaster recovery among neobanks and insurance platforms.
United Kingdom
Post-Brexit data adequacy negotiations and FinOps platform intermediation reshape enterprise procurement patterns. UK GDPR retention requirements intersect with FCA operational resilience mandates for financial services. London-based hedge funds and insurance syndicates normalize pricing across hyperscalers through third-party orchestrators.
France
Healthcare continuity planning and nuclear energy sector operational technology security elevate managed backup service contracts. ANSM and CNIL guidance imposes strict health data processing boundaries. Paris-Saclay research clusters and Lyon pharmaceutical manufacturing deploy multi-cloud archiving for decades-long clinical trial preservation.
Multi Cloud Storage Market Competitive Environment
Channel-controlling players compete with product-specialist players across three distinct tiers. Hyperscale infrastructure operators anchor the premium tier through early capital deployment and API ecosystem capture. Mid-market orchestration specialists occupy the middle band by absorbing operational complexity that enterprise IT teams cannot address. Niche compliance-focused providers serve regulated verticals with sovereign cloud certifications. Competitive moves concentrate on strategic partnerships for Kubernetes-native integration and geographic expansion into data localization-mandated jurisdictions.
Among hyperscale infrastructure operators, Amazon Web Services, Microsoft Azure, and Google Cloud exemplify the channel-control archetype through S3-compatible API standardization and sub-100ms latency SLA commitments. These entities anchor procurement decisions for data-intensive analytics pipelines while competing on AI-optimized storage tiering and Active Directory integration depth.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud |
| IBM |
| VMware |
| Hewlett Packard Enterprise |
| Dell Technologies |
| Nasuni |
| Qumulo |
| Others |
Value Chain & Pricing Dynamics
Egress fee accumulation across three or more providers determines both tier spreads between managed service bundles and self-orchestrated infrastructure while reshaping supply chain partnerships toward FinOps intermediaries that absorb cost unpredictability.
Pricing Analysis
Prior-generation S3-compatible object storage commands economy-tier rates while current-generation Kubernetes-native architectures with sub-100ms latency SLAs capture standard-tier positioning, and next-generation AI-optimized tiering with automated provenance tracking anchors premium pricing. Subscription-based managed services dominate enterprise procurement, with ISO 27001 certification and SOC 2 Type II attestation driving differentiation between tiers. Cost compression in self-managed IaaS stems from hyperscaler price competition for analytics workloads. Mid-market manufacturing firms exhibit highest price sensitivity due to unpredictable egress accumulation, while financial services firms prioritize compliance-grade SLAs over unit economics.
Supply Chain Analysis
Supply-chain finance facilities extended by hyperscalers to certified integration partners are compressing payment cycles for Kubernetes orchestration specialists and FinOps platform providers. Hardware concentration rests on Taiwan for advanced NAND fabrication, South Korea for memory components, and the United States for specialized AI accelerators. Flash storage wafer supply, optical networking gear, and precision cooling systems constitute critical input dependencies. Single-source vulnerability in EU sovereign cloud infrastructure creates chokepoint exposure for German automotive manufacturers. Distribution runs through hyperscaler marketplaces, systems integrators, and managed service providers in tiered downstream structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-vendor cloud architecture certification scarcity constrains enterprise scaling velocity, with fewer than one in five IT organizations maintaining staff capable of cross-provider Kubernetes orchestration and jurisdictional compliance engineering.
For Market Incumbents: Pre-empt margin erosion from FinOps intermediaries by embedding cost optimization automation directly into managed service contracts and accelerating sovereign cloud certification in Germany and India before indigenous providers mature. Deepen API ecosystem capture through S3-compatible lineage tracking that satisfies EU AI Act documentation mandates. For New Entrants and Emerging Players: Build out carbon-aware storage tiering capabilities aligned with EU Green Deal reporting obligations, targeting mid-market UK technology firms currently underserved by hyperscaler direct sales. Sovereign cloud alternatives in France and the Netherlands represent the most penetrable geography given Dutch Central Bank resilience mandates and ANSM health data boundaries. For Investors and Strategic Acquirers: EU AI Act enforcement reshapes the acquisition landscape toward providers with cryptographic attestation and geo-fenced storage pool capabilities. Long-term viability favors orchestration specialists with demonstrated Kubernetes-native integration across three or more hyperscalers. Watch for RBI data localization deadline compliance as the signal indicating indigenous Indian provider consolidation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Kubernetes-Native Platform Integration | Enables workload portability across AWS, Azure, and Google Cloud without vendor lock-in. |
| Sovereign Cloud Geographic Expansion | Satisfies EU AI Act and RBI mandates in Germany and India respectively. |
| Strategic Partnership with FinOps Orchestrators | Absorbs mid-market procurement complexity that internal IT teams cannot address. |
| Acquisition of Compliance Specialist Firm | Accelerates ISO 27001 and SOC 2 Type II certification timelines for multi-cloud architectures. |
| AI-Optimized Storage Tiering Product Launch | Captures analytics-intensive customers with automated cost-performance balancing. |
Study Parameters
A standing panel of cloud architecture directors, FinOps platform engineers, enterprise procurement officers, and sovereign cloud compliance specialists provided ongoing calibration across primary interview cycles, validated against hyperscaler capex disclosures, SEC 10-K infrastructure segments, EU regulatory filings, and RBI directive documentation. Bottom-up deployment sizing and top-down market aggregation triangulated segment boundaries.
Scenario-bracketing framed low, base, and high cases across the projection horizon, modeling deployment topology, solution type, service model, organization size, and regional regulatory cluster as core segmentation dimensions. CAGRs derived from installed base evolution and replacement cycle analysis incorporated Kubernetes adoption curves and data localization mandate timelines as industry-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity buildout by indigenous Indian providers or accelerated EU AI Act enforcement would shift outcomes. Macroeconomic contraction in enterprise IT spending, Schrems II ruling expansion, or breakthrough in quantum-resistant encryption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Global Storage As a Service Market
Storage Solutions
Poland Data Center Storage Market
Storage Solutions
Italy Data Center Storage Market
Storage Solutions
Singapore Data Center Storage Market
Storage Solutions
Brazil Data Center Storage Market
Storage Solutions
United Arab Emirates Data Center Storage Market
Storage Solutions
5D Data Storage Market
Storage Solutions
Saudi Arabia Data Center Storage Market
Storage Solutions
South Africa Data Center Storage Market
Storage Solutions
Global Cloud Object Storage Market
Storage Solutions
Public Cloud Storage Services Market
Storage Solutions
Automated Storage and Retrieval System (AS & RS) Market
Storage Solutions
Hybrid Cloud Storage Market
Storage Solutions
Global Personal Cloud Storage Market
Storage Solutions
Copy Data Management Software Market
Storage Solutions
Data Backup and Recovery Market