
 US Mexico Cross Border FTL Freight Transport Market | 2026-2036
US Mexico Cross Border FTL Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
US Mexico Cross Border FTL Freight Transport Market Insights
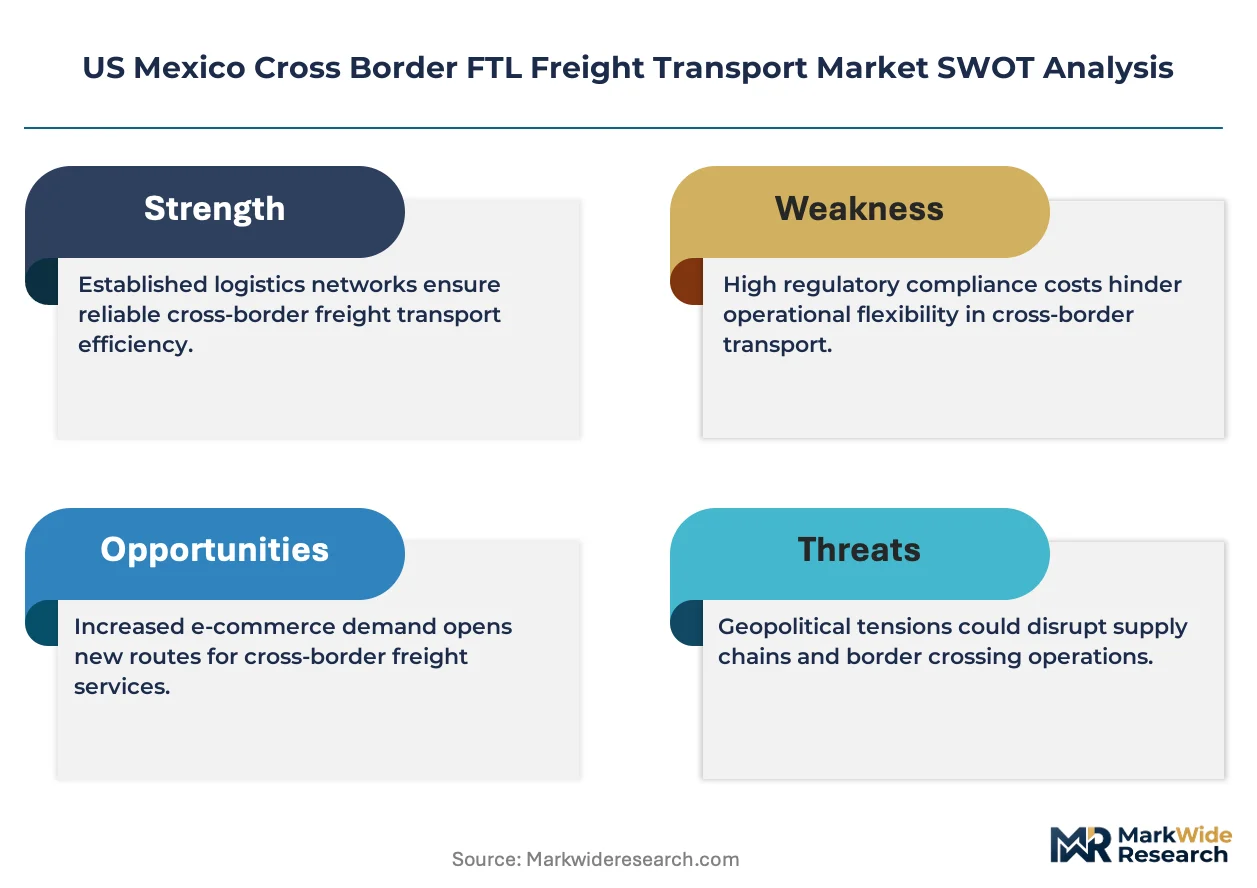
Expedited customs-clearance certification is rotating toward the center of carrier strategy. C.H. Robinson leverages its brokerage network to secure faster border processing for automotive and aerospace shippers. Schneider National anchors its cross-border franchise through dedicated fleet assets positioned at Laredo and El Paso. Mexicom Logistics specializes in southbound consolidation services that reduce empty-mile ratios for Mexican manufacturing clients.
US Mexico cross-border FTL freight transport involves tractor-trailer movement of dedicated full truckload shipments across the international boundary, typically requiring bonded carrier authority, customs documentation harmonization between US CBP and Mexican SAT systems, and dwell-time minimization at ports of entry. Its primary commercial purpose is to synchronize just-in-time supply chains for maquiladora operations and US distribution centers. Refrigerated freight commands premium rate structures due to cold-chain integrity requirements across climatic zones. Intermodal rail-road combinations gain share on lanes exceeding 800 miles as fuel cost differentials widen. Dry cargo retains volume leadership but faces margin compression from excess dry van capacity in border zones.
US CBP enforces CTPAT security standards that filter carrier eligibility for expedited lane access, while Mexican SAT mandates electronic invoice validation through CFDI protocols for all cross-border commercial movements. FMCSA hours-of-service regulations constrain driver availability on US segments, pushing fleet operators toward team-driver configurations on high-velocity lanes. Stakeholders must monitor USMCA rules-of-origin enforcement shifts and emerging Mexican highway toll structures that alter route economics between Nuevo Laredo and Altamira port corridors.
Market Dynamics
USMCA rules-of-origin enforcement is compressing carrier qualification timelines while Mexican SAT electronic invoicing mandates force real-time documentation upgrades across bonded fleets.
Growth Catalysts
- Nearshoring acceleration:Automotive and electronics manufacturers are relocating assembly operations from Asia to Monterrey and Guanajuato, generating dedicated FTL demand for just-in-time component flows.
- CTPAT certification expansion:US CBP expedited lane access programs reward compliant carriers with reduced dwell times at Laredo and Otay Mesa crossings, creating service differentiation premiums.
- Refrigerated cold-chain investment:Temperature-controlled trailer fleets serving pharmaceutical and fresh produce sectors command rate premiums as US FDA import integrity requirements tighten.
Market Restraints
- Driver availability constraints:FMCSA hours-of-service regulations limit US segment driving windows, forcing expensive team-driver configurations on high-velocity I-35 lanes.
- Fuel cost volatility:Diesel price fluctuations between Texas and Nuevo Leon erode contracted margin structures for independent owner-operators lacking fuel surcharge mechanisms.
- Border infrastructure saturation:Peak-hour queuing at Laredo World Trade Bridge creates unpredictable dwell costs that distort route economics versus alternative rail intermodal.
Strategic Opportunities
- CFDI integration services:Technology platforms that automate Mexican SAT electronic invoice validation capture value from carriers struggling with bilingual documentation compliance.
- El Paso corridor development:Underutilized Santa Teresa crossing capacity offers dwell-time arbitrage for shippers willing to route away from congested Laredo entry points.
- Electric truck pilot zones:California CARB zero-emission mandates and Mexican federal clean transport incentives create early-mover advantages for battery-electric tractor deployment.
Industry Challenges
- Dual customs brokerage complexity:Harmonizing US CBP ACE filings with Mexican SAT VUCEM portals requires specialized bilingual compliance staff that command wage premiums.
- Empty-mile repositioning:Southbound freight imbalances force costly deadhead runs from US distribution centers to Mexican manufacturing clusters, compressing asset utilization metrics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Mexico Cross Border FTL Freight Transport Market |
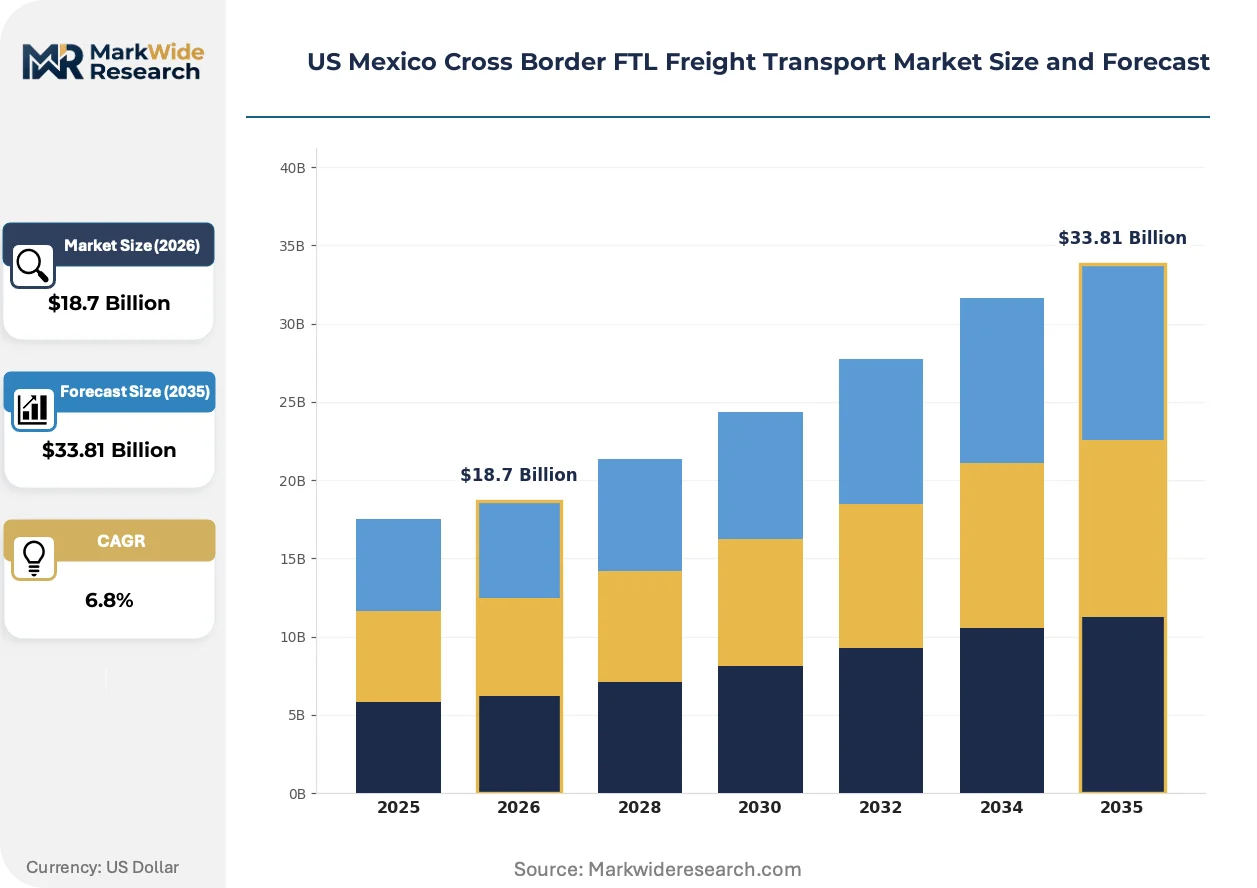
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dedicated Freight, Partial Load, Full Truck Load, Time-Sensitive Delivery Transport Mode: Road, Rail, Intermodal, Container Shipping Load Type: Dry Cargo, Refrigerated Freight, Hazardous Material, Oversized Cargo Client Type: Manufacturers, Retailers, Wholesalers, Importers |
| Companies Covered | C.H. Robinson, XPO Logistics, Schneider National, Kuehne + Nagel, R+L Global Logistics, Mexicom Logistics, APEX Transit, DCL Logistics, Prologis, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Mexico Cross Border FTL Freight Transport Market Trends and Innovations
Telematics and predictive analytics are compressing transit time variability while regulatory digitization forces documentation infrastructure upgrades across carrier networks.
Blockchain-enabled cargo documentation is miniaturizing customs clearance latency by creating immutable chain-of-custody records shared between US CBP, Mexican SAT, and shipper ERP systems. Automotive OEMs with just-in-time Monterrey assembly plants are piloting these platforms to eliminate paper-based delays. The technology is miniaturizing border dwell from hours to minutes for certified participants.
US CBP is expanding biometric driver verification protocols at commercial ports of entry, requiring fingerprint and facial recognition enrollment for all cross-border operators. This security layer adds processing steps but reduces secondary inspection rates for compliant fleets. Refrigerated carriers serving pharmaceutical lanes face the steepest compliance timelines due to cargo sensitivity.
Shippers are consolidating vendor relationships around carriers offering integrated US-Mexico insurance and customs brokerage, displacing fragmented spot-market sourcing. Large retail distribution centers in Texas and California now mandate single-carrier accountability for end-to-end transit. This concentration is most visible in aerospace and medical device verticals where cargo liability thresholds exceed standard coverage limits.
US Mexico Cross Border FTL Freight Transport Market Segmentation
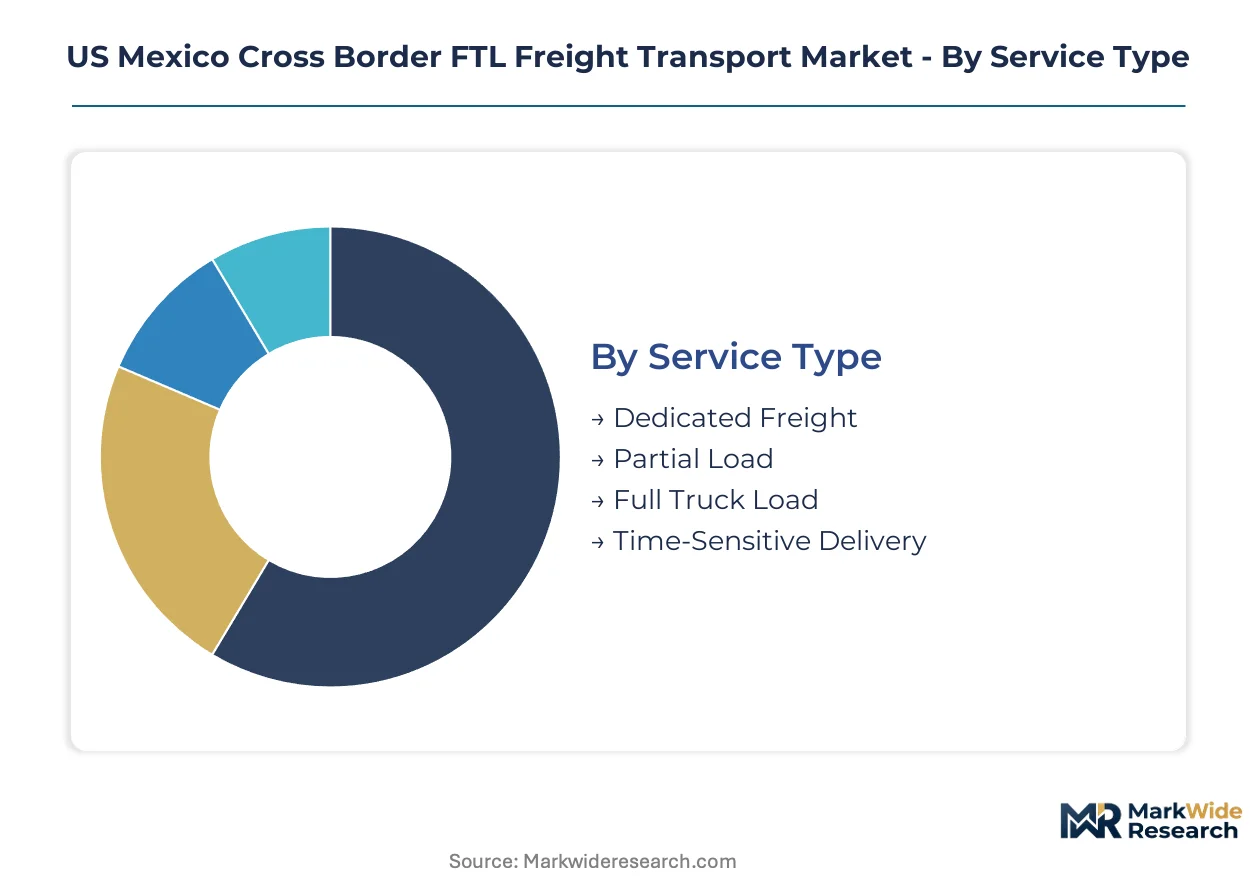
Cross-border freight segmentation reveals divergent operational economics between bonded dedicated lanes and spot-market capacity. Service configurations, transport infrastructure, cargo characteristics, and shipper sophistication each create distinct margin profiles and qualification barriers across the US-Mexico corridor.
Service Type:
Dedicated contract services concentrate along I-35 maquiladora corridors, while time-critical offerings capture aerospace and medical device verticals with penalty-clause exposure.
- Dedicated Freight:Long-term contracted capacity with assigned tractor-trailer assets and guaranteed transit windows. Demand clusters at Monterrey automotive assembly plants requiring synchronized component delivery schedules.
- Partial Load:Consolidated shipments sharing trailer space across multiple shippers. Southbound manufacturing inputs from Texas distribution centers drive volume, though margin compression from empty-mile repositioning limits carrier participation.
- Full Truck Load:Exclusive trailer utilization for single-shipper cargo. USMCA rules-of-origin documentation requirements and CTPAT certification standards filter carrier eligibility for expedited lane access.
- Time-Sensitive Delivery:Expedited transit with team-driver configurations and guaranteed delivery windows. Aerospace OEMs in Queretaro and pharmaceutical distributors pay substantial premiums for customs-precleared dedicated capacity.
Dedicated Freight commands the established base. The steepest expansion runs through Time-Sensitive Delivery.
Transport Mode:
Road freight dominates corridor economics under 800 miles, while intermodal combinations capture cost-sensitive lanes where fuel differentials outweigh speed requirements.
- Road:Tractor-trailer movement across commercial ports of entry with bonded carrier authority. Laredo World Trade Bridge processes the highest truck volume, though Santa Teresa offers dwell-time arbitrage for compliant fleets.
- Rail:Class I railroads operating dedicated automotive and intermodal trains through border gateways. BNSF and Union Pacific maintain terminal infrastructure at Eagle Pass and Nogales corridors.
- Intermodal:Rail-road combinations optimizing cost-velocity tradeoffs on lanes exceeding 800 miles. Dry van containers transitioning to drayage at border ramps serve retail distribution centers in California and Texas.
- Container Shipping:Maritime feeder services connecting Altamira and Veracruz to US Gulf ports. Bulk agricultural exports and chemical feedstocks bypass overland congestion through ocean alternatives.
Road transport anchors volume leadership. Intermodal configurations are climbing the fastest as fuel cost differentials widen.
Load Type:
Temperature-controlled cargo commands rate premiums, while hazardous materials face dual regulatory compliance across FMCSA and Mexican SCT jurisdictions.
- Dry Cargo:Standard van shipments of manufactured goods, consumer products, and industrial components. Excess capacity in border zones compresses spot rates for non-refrigerated movements.
- Refrigerated Freight:Temperature-controlled trailers maintaining cold-chain integrity across climatic zones. FDA import integrity requirements and Mexican NOM standards tighten equipment specifications for pharmaceutical and fresh produce lanes.
- Hazardous Material:Chemical, fuel, and industrial gas shipments requiring specialized placarding and driver certification. Dual permitting across US DOT hazmat regulations and Mexican SCT dangerous goods protocols extends transit documentation timelines.
- Oversized Cargo:Heavy machinery, industrial equipment, and wind turbine components exceeding standard dimensional limits. Permit coordination between Texas DOT and Mexican federal highway authorities determines viable routing through Columbia Solidarity and Bridge of the Americas crossings.
Dry Cargo retains volume dominance. Refrigerated Freight is gaining share fastest from cold-chain integrity investments.
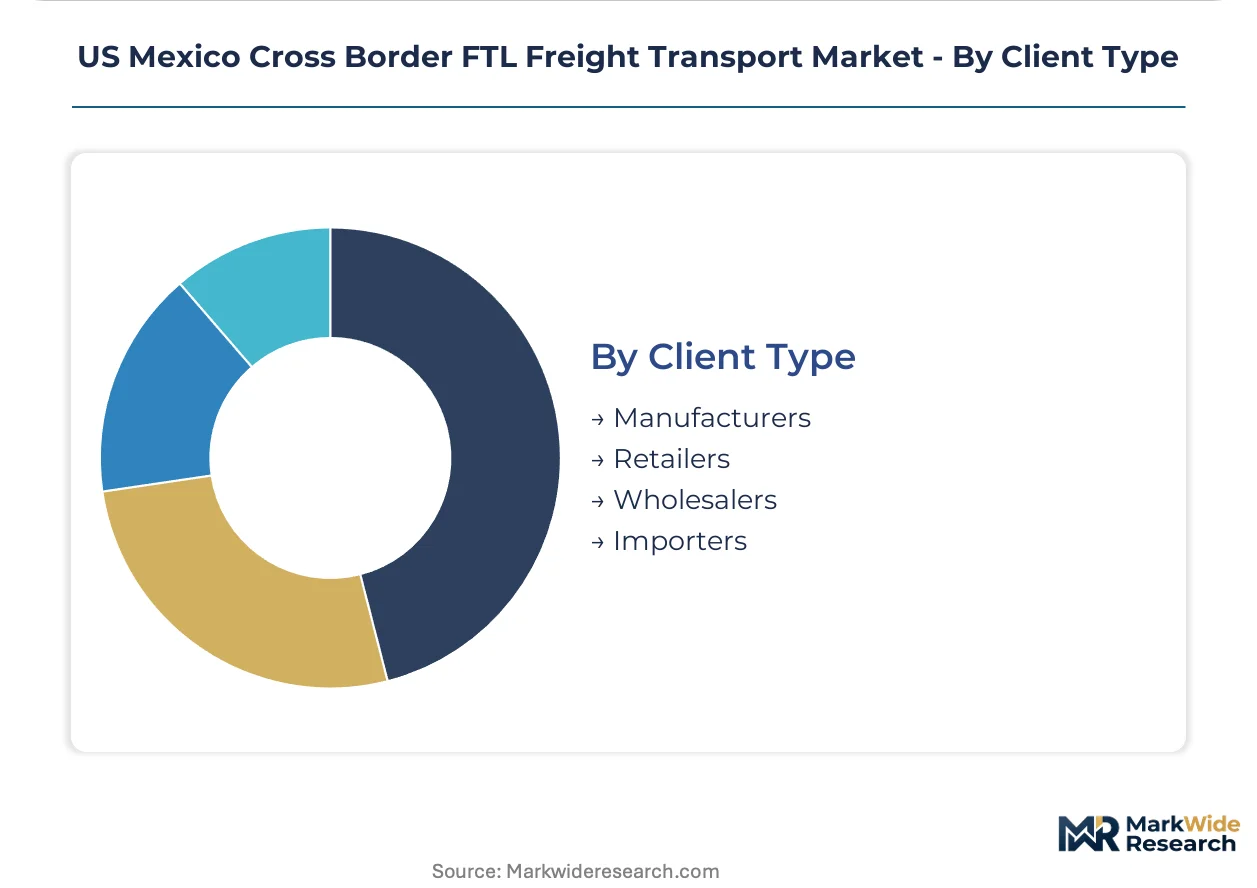
Client Type:
Shipper sophistication determines customs brokerage integration depth, with manufacturers demanding end-to-end accountability versus fragmented spot-market sourcing.
- Manufacturers:Automotive, electronics, and aerospace producers with just-in-time supply chain requirements. CTPAT-certified carriers capture dedicated contract volumes through integrated US-Mexico insurance and customs brokerage offerings.
- Retailers:Big-box distribution centers and e-commerce fulfillment operations consolidating vendor relationships. Single-carrier accountability mandates displace fragmented procurement in Texas and California gateway markets.
- Wholesalers:Intermediate distributors aggregating shipments across multiple product categories. CFDI electronic invoice validation requirements strain smaller operators lacking bilingual compliance infrastructure.
- Importers:Third-party logistics providers and customs brokers managing cross-border commercial flows. USMCA rules-of-origin enforcement shifts and SAT electronic documentation mandates force real-time technology upgrades.
Manufacturers command the established base. Retailers are expanding most quickly through vendor consolidation mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border freight flows concentrate along the I-35 corridor where Mexican export manufacturing meets US import demand. Trade imbalances between northbound manufactured goods and southbound raw materials create empty-mile inefficiencies that reshape carrier routing strategies.
Texas
Laredo World Trade Bridge processes the highest commercial truck volume between the two nations. FMCSA hours-of-service regulations constrain driver availability on northbound segments, pushing fleets toward team-driver configurations. Dallas-Fort Worth distribution centers anchor dedicated contract lanes serving Monterrey automotive plants.
California
Otay Mesa crossing serves aerospace and medical device shippers requiring CTPAT-certified expedited clearance. CARB zero-emission mandates accelerate electric truck pilot programs at border drayage operations. San Diego warehousing clusters support just-in-time delivery windows for Tijuana maquiladora operations.
Nuevo León
Monterrey automotive assembly plants generate dedicated FTL demand for synchronized component flows from US suppliers. Mexican SAT electronic invoicing mandates through CFDI protocols force real-time documentation upgrades across bonded fleets. Apodaca industrial parks concentrate Tier 1 supplier distribution centers.
Guanajuato
Silao and Irapuato manufacturing clusters attract electronics and appliance producers relocating from Asian supply chains. Mexican federal highway toll structures between Querétaro and Nuevo Laredo alter route economics for time-sensitive cargo. León logistics parks offer consolidation services reducing empty-mile ratios.
Chihuahua
Ciudad Juárez maquiladora corridor maintains dedicated freight relationships with El Paso and Santa Teresa crossings. Underutilized Santa Teresa port capacity offers dwell-time arbitrage versus congested Laredo entry points. Juárez assembly operations for automotive wiring harnesses demand temperature-controlled transport integrity.
US Mexico Cross Border FTL Freight Transport Market Competitive Landscape
Concentration sits with integrated logistics providers possessing dual customs brokerage capabilities. The vendor base stratifies between asset-heavy fleet operators and technology-enabled freight brokers, with qualification barriers rising around USMCA compliance infrastructure. Two archetypes dominate: CTPAT-certified carriers commanding expedited lane premiums, and digital freight platforms automating cross-border documentation. Competitive moves center on customs brokerage acquisitions and dedicated fleet positioning at saturated border crossings.
Among North American integrated providers, C.H. Robinson, Schneider National, and Mexicom Logistics occupy distinct strategic positions. C.H. Robinson represents the brokerage-heavy archetype leveraging network scale for faster border processing. Schneider National exemplifies asset-based market presence through dedicated fleet positioning at Laredo and El Paso. Mexicom Logistics anchors the specialized southbound consolidation segment serving Mexican manufacturing clients with reduced empty-mile solutions.
| Leading Market Players |
|---|
| C.H. Robinson |
| XPO Logistics |
| Schneider National |
| Kuehne + Nagel |
| R+L Global Logistics |
| Mexicom Logistics |
| APEX Transit |
| DCL Logistics |
| Prologis |
| Others |
Pricing and Supply Chain Analysis
Fleet asset density at Laredo and El Paso border crossings creates scale economies that compress per-mile operating costs while simultaneously elevating price floors for non-certified carriers lacking CTPAT expedited lane access. This concentration of bonded capacity allows CTPAT-certified operators to capture service premiums while independent owner-operators face margin erosion from fuel surcharge gaps and dwell-time unpredictability.
Pricing Analysis
Industrial OEM buyers anchor contract pricing through long-term dedicated freight agreements with penalty clauses for missed just-in-time delivery windows. Three-tier pricing structure across CTPAT-certified premium, standard bonded, and spot-market economy levels reflects customs clearance speed and cargo liability coverage. Cost compression in the spot tier is intensifying because excess dry van capacity in border zones erodes rate negotiation leverage for non-specialized carriers. Wholesalers and intermediate distributors exhibit highest price sensitivity due to thin margins and fragmented procurement, while aerospace and pharmaceutical OEMs accept substantial premiums for guaranteed transit integrity.
Supply Chain Analysis
Inventory positioning and lead-time variability concentrate supply chain risk at the border interface where US CBP ACE filings must harmonize with Mexican SAT VUCEM portals in real time. Manufacturing inputs draw from US Midwest automotive component clusters, Texas petrochemical feedstocks, and Mexican raw material processing centers. Single-source vulnerability sits with specialized refrigerated trailer fleets serving pharmaceutical lanes where FDA import integrity requirements limit qualified carrier pools. Distribution runs through bonded warehouse networks at Laredo, El Paso, and Otay Mesa before final-mile drayage to maquiladora assembly plants and US distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where CTPAT certification creates regulatory entrenchment that locks out unqualified competitors and embeds switching costs through integrated customs brokerage relationships.
For Market Incumbents: Consolidate customs brokerage capabilities through targeted capability acquisitions that deepen bilingual compliance infrastructure and SAT electronic invoicing automation. Expand dedicated fleet positioning at underutilized Santa Teresa and Otay Mesa corridors to capture dwell-time arbitrage against congested Laredo entry points. The priority defensive move centers on vertical integration into cold-chain trailer assets before pharmaceutical lane qualification windows close. For New Entrants and Emerging Players: Lead with CFDI integration software platforms that automate Mexican SAT electronic invoice validation for mid-tier carriers struggling with bilingual documentation compliance. The most penetrable white space sits with southbound consolidation services serving Guanajuato and Queretaro manufacturing clusters where empty-mile repositioning costs currently compress carrier participation. Target team-driver logistics configurations on high-velocity I-35 lanes where FMCSA hours-of-service constraints limit incumbent capacity flexibility. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among CTPAT-certified carriers with embedded customs brokerage relationships that generate multi-year contract renewals through switching cost entrenchment. Long-term viability across the projection horizon rests on regulatory compliance infrastructure rather than pure asset scale. Acquisition targets should display integrated US-Mexico insurance offerings and pharmaceutical cold-chain certification. The signal to watch as inflection indicator is Mexican federal highway toll structure revisions between Nuevo Laredo and Altamira corridors that would reroute time-sensitive cargo flows.| Strategic Initiative | Industry Significance |
|---|---|
| CTPAT Certification Investment | Expedited lane access at Laredo World Trade Bridge reduces dwell costs for automotive shippers. |
| CFDI Platform Integration | Automated SAT electronic invoice validation captures value from compliance-strapped mid-tier carriers. |
| Santa Teresa Corridor Development | Underutilized crossing capacity offers dwell-time arbitrage versus congested Laredo entry points. |
| Refrigerated Fleet Expansion | Temperature-controlled assets command rate premiums as FDA import integrity requirements tighten. |
| Team-Driver Configuration Deployment | FMCSA hours-of-service constraints on US segments force high-velocity lane service differentiation. |
Research Methodology
Desk research of carrier operating authority filings, US CBP trade statistics, and Mexican SAT commercial movement records preceded structured interviews with cross-border fleet operations directors, customs brokerage compliance officers, automotive procurement managers, and maquiladora supply chain directors. Primary fieldwork with bonded carriers at Laredo and El Paso border crossings validated capacity utilization patterns and dwell-time economics. Secondary triangulation drew from FMCSA enforcement data, USMCA rules-of-origin documentation requirements, and refrigerated transport equipment specifications. Bottom-up segment sizing across service types, transport modes, and cargo categories converged with top-down market value reconstruction.
Variance decomposition across the projection horizon isolates volume growth from rate inflation and mix shift effects. The analytical framework models dedicated contract, spot market, and time-sensitive delivery configurations against road, rail, and intermodal transport modes. Dry cargo, refrigerated freight, hazardous material, and oversized load categories incorporate cargo-specific equipment requirements and regulatory compliance costs. CAGRs derive from trend extrapolation of nearshoring-driven manufacturing relocation, CTPAT certification expansion rates, and cold-chain infrastructure investment cycles. Fuel cost volatility, driver availability constraints, and border infrastructure saturation serve as scenario-adjustment inputs.
The analysis sits within stated boundaries; outcomes outside sustained USMCA trade policy stability and Mexican highway toll structure continuity would require recalibration. Forecasts reflect documented assumptions regarding automotive and electronics nearshoring momentum, CTPAT program expansion trajectories, and refrigerated fleet capacity addition rates. Revision becomes warranted when border infrastructure investment delays or regulatory harmonization setbacks cross thresholds that materially alter dwell-time economics or carrier qualification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Apparel Logistics Market
Logistics and Shipping
Last Mile Delivery Transportation Market
Logistics and Shipping
North America Refrigerated Container Shipping Market
Logistics and Shipping
Internet of Things (IoT) in Logistics Market
Logistics and Shipping
Europe Refrigerated Container Shipping Market
Logistics and Shipping
Digital Freight Management Market
Logistics and Shipping
Central and Eastern Europe Cold Chain Logistics Market
Logistics and Shipping
Central and Eastern Europe Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Germany Last Mile Delivery Market
Logistics and Shipping
US Fourth-Party Logistics (4PL) Market
Logistics and Shipping
Iraq Logistics Market
Logistics and Shipping
China International Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Cross-Border Logistics Services Market
Logistics and Shipping
France Cold Chain Logistics Market
Logistics and Shipping
Thailand Freight and Logistics Market
Logistics and Shipping
Kazakhstan Freight and Logistics Market