
 California Freight and Logistics Market | 2026-2036
California Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
California Freight and Logistics Market Insights
Last-mile delivery network densification is reshaping margin distribution across California's logistics value chain. UPS leverages its established hub infrastructure in Ontario and Redding to sustain next-day coverage across the state's northern and southern corridors. Flexport competes on digital freight forwarding platforms that aggregate ocean and air cargo bookings for shippers moving goods through the San Pedro Bay ports.
California freight and logistics encompasses the physical movement, storage, and information coordination of goods across road, rail, air, and maritime infrastructure, typically measured by ton-miles, container twenty-foot equivalent units, and dwell time at intermodal facilities. The sector's primary purpose is to synchronize supply with demand across distance and time while minimizing inventory carrying costs and transportation expenditure. Truck transportation occupies the dominant share of intrastate freight tonnage, though rail intermodal is gaining share on long-haul corridors between the Central Valley and Southern California distribution clusters. Warehousing revenue pools concentrate in the Inland Empire, where e-commerce providers drive demand for facilities exceeding 500,000 square feet with automated sortation systems.
The California Air Resources Board enforces fleet electrification mandates through the Advanced Clean Trucks regulation, while the Federal Motor Carrier Safety Administration governs driver hours-of-service rules that constrain capacity expansion. The California Environmental Protection Agency coordinates with local air districts to impose warehouse indirect source rules that affect site selection and facility design in the South Coast and San Joaquin Valley air basins. Stakeholders must monitor how zero-emission vehicle infrastructure deployment timelines align with port drayage electrification requirements.
Market Dynamics
The Advanced Clean Trucks regulation is compressing fleet turnover timelines while warehouse operators race to secure electrified sites ahead of indirect source rule enforcement in the South Coast Air Basin.
Growth Catalysts
- Port Electrification Mandates:The California Air Resources Board's drayage truck requirements are pulling forward zero-emission vehicle deployment at Los Angeles-Long Beach terminals. Terminal operators must phase out diesel rigs by 2035.
- E-commerce Fulfillment Density:Retailers are expanding automated sortation facilities across Riverside and San Bernardino counties to position inventory within two-day ground coverage of coastal population centers.
- Rail Intermodal Investment:BNSF and Union Pacific are adding terminal capacity at Stockton and Barstow to capture Central Valley agricultural exports and reduce highway truck volumes on Interstate 5 corridors.
Market Restraints
- Electric Infrastructure Gaps:Grid interconnection queues at Southern California Edison and Pacific Gas and Electric extend 18-24 months for megawatt-scale charging depots, delaying fleet electrification.
- Land Scarcity in Core Basins:Industrial zoned parcels exceeding 20 acres within 50 miles of the San Pedro Bay ports trade at premiums exceeding Central Valley equivalents by factors of four to six.
- Driver Pool Constraints:Federal Motor Carrier Safety Administration hours-of-service rules cap available driving hours while California's independent contractor classification law narrows owner-operator participation in drayage.
Strategic Opportunities
- Central Valley Cold Chain Expansion:Temperature-controlled warehousing in Fresno and Kern counties remains underdeveloped relative to produce export volumes through Oakland and Los Angeles-Long Beach.
- Battery-Electric Refrigerated Units:Convergence of solid-state battery chemistry and trailer telematics is enabling zero-emission cold chain transport on inland corridors previously served by diesel auxiliary power units.
- Last-Mile Micro-Fulfillment:Urban infill sites in Oakland, San Jose, and San Diego offer regulatory tailwinds through California Environmental Protection Agency warehouse indirect source rule exemptions for sub-100,000 square foot facilities.
Industry Challenges
- Charging Hardware Standardization:Fleet managers face integration complexity across competing connector protocols and payment systems when deploying mixed-vendor electric truck portfolios.
- Air Quality Compliance Timelines:South Coast Air Quality Management District warehouse indirect source rules require emissions reductions from on-site truck trips, forcing retrofits at legacy distribution centers built before 2010.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | California Freight and Logistics Market |
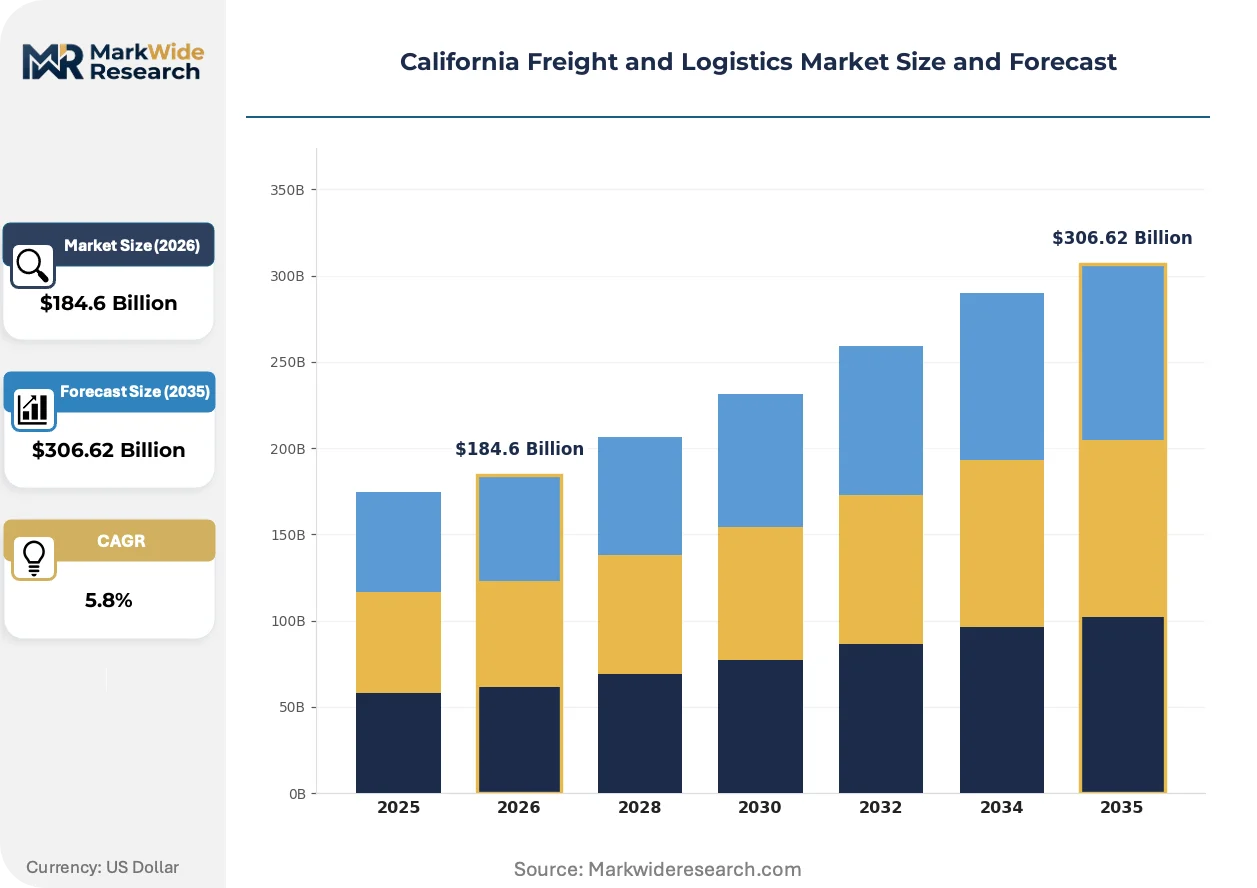
| Market Size in 2026 | $184.6 Billion |
| Market Size in 2035 | $306.62 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Last-Mile Delivery, Freight Forwarding End User: Retailers, Manufacturers, Distributors, E-Commerce Providers Transportation Mode: Truck, Rail, Air, Ocean Technology: IoT Solutions, Freight Management Systems, Autonomous Vehicles, Blockchain |
| Companies Covered | Agramont Worldwide Logistics Inc, Flexport, SHIPHYPE Fulfillment, UPS, AP Express Logistics, InterFulfillment Inc., Dedola Global Logistics, GoBolt, Falcon International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
California Freight and Logistics Market Trends and Innovations
Automation and electrification are converging to redefine asset productivity benchmarks across California's freight corridors, with regulatory deadlines acting as the primary synchronization mechanism for capital deployment.
Autonomous yard tractors are rendering obsolete manual spotting operations at intermodal terminals. Union Pacific and BNSF are piloting driverless shuttle systems at Barstow and Commerce facilities to compress container dwell times. The technology is rendering obsolete the traditional drayage broker model that mediated short-haul moves between rail ramps and warehouses.
California Environmental Protection Agency coordination with the California Air Resources Board is tightening warehouse indirect source rules in the South Coast and San Joaquin Valley air basins. Industrial developers must now demonstrate zero-emission truck visit fractions to secure air permits. Cold storage operators in Ontario and Redlands are responding by pre-wiring facilities for megawatt-scale charging before tenant occupancy.
Shippers are consolidating procurement through digital freight platforms that aggregate ocean, rail, and truck capacity on single interfaces. Traditional asset-based carriers with captive drayage fleets are losing share to technology-enabled brokers that optimize mode selection in real time. This pattern concentrates most visibly among apparel and electronics importers routing through Los Angeles-Long Beach who prioritize visibility over carrier loyalty.
California Freight and Logistics Market Segmentation
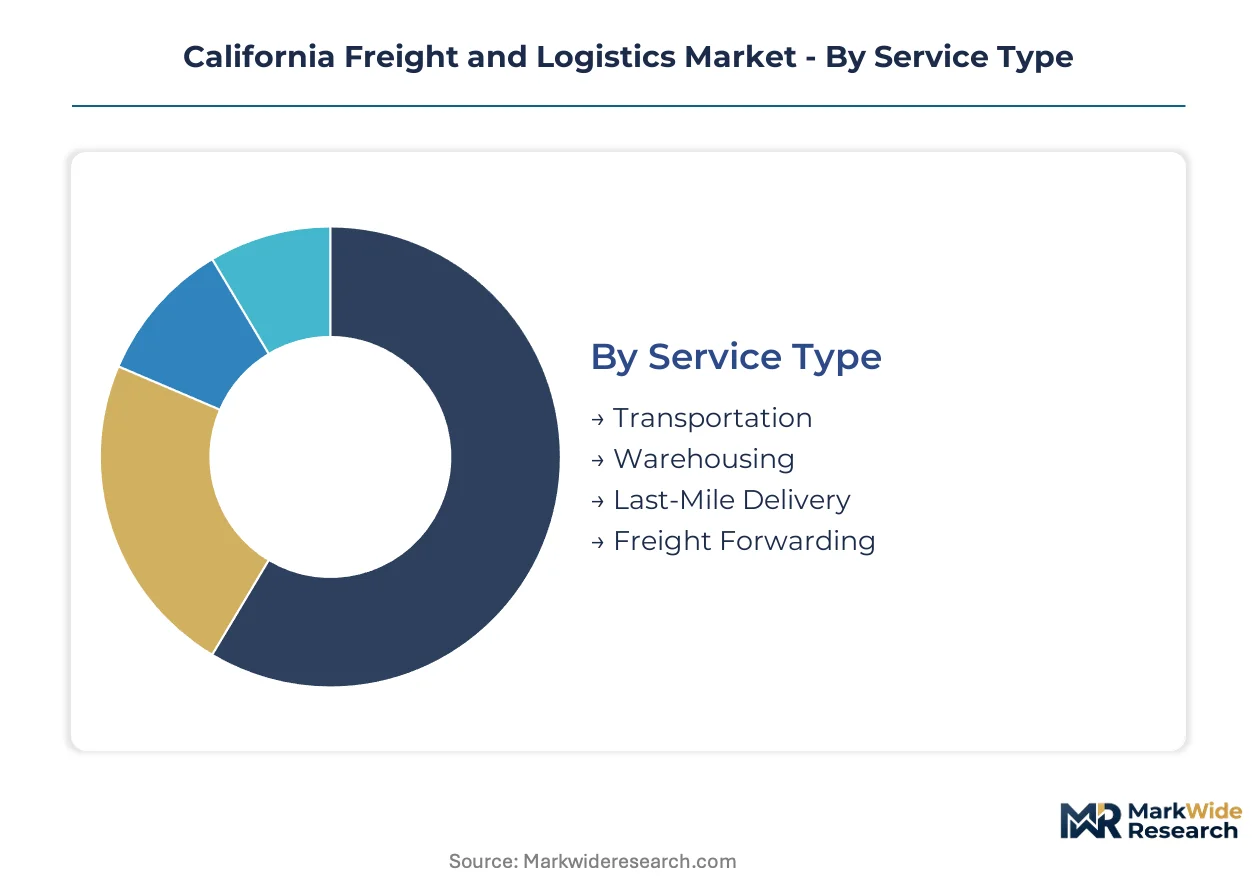
Segmentation reveals how California's freight and logistics value chain fragments across service delivery models, customer procurement patterns, and technology adoption curves. Understanding these divisions clarifies where electrification mandates and e-commerce density concentrate investment returns.
Service Type:
Cost tier differentiation separates asset-heavy infrastructure plays from technology-mediated coordination services.
- Transportation:Truck and rail carriers move goods across California's interstate corridors, with fleet operators in the Los Angeles-Long Beach port complex facing accelerated zero-emission vehicle deadlines under the California Air Resources Board's Advanced Clean Trucks regulation. Drayage operators must phase out diesel rigs while securing megawatt-scale charging infrastructure through Southern California Edison's congested interconnection queues.
- Warehousing:Facilities exceeding 500,000 square feet with automated sortation systems dominate the Inland Empire, where e-commerce providers position inventory within two-day ground coverage of coastal population centers. The South Coast Air Quality Management District's indirect source rules now require emissions reductions from on-site truck trips, forcing retrofits at legacy distribution centers.
- Last-Mile Delivery:Parcel networks deploy electric vans and cargo bikes for urban density, with micro-fulfillment centers in Oakland and San Jose qualifying for warehouse indirect source rule exemptions.
- Freight Forwarding:Digital platforms aggregate ocean and air cargo bookings, displacing traditional broker relationships among apparel and electronics importers.
Transportation holds installed capacity. Last-Mile Delivery is rotating up the share rankings.
End User:
Customer type determines facility specifications, with e-commerce procurement patterns driving the fastest warehouse square footage expansion.
- Retailers:Big-box chains operate dedicated distribution networks with private fleet drayage, insulating them from spot market volatility at Los Angeles-Long Beach terminals.
- Manufacturers:Just-in-time assembly plants in the Central Valley require temperature-controlled warehousing for agricultural inputs, with cold chain gaps persisting in Fresno and Kern counties relative to export volumes through Oakland.
- Distributors:Third-party logistics providers consolidate multi-tenant facilities, absorbing compliance burdens from the California Environmental Protection Agency's warehouse indirect source rules across the South Coast Air Basin.
- E-Commerce Providers:Automated sortation facilities in Riverside and San Bernardino counties represent the steepest expansion trajectory, with same-day delivery promises forcing inventory positioning closer to end consumers than traditional retail distribution models permitted.
Retailers hold installed capacity. E-Commerce Providers is climbing the fastest.
Transportation Mode:
Volume concentration across modes reflects infrastructure legacy and regulatory pressure differentially applied to each network.
- Truck:Dominates intrastate freight tonnage with drayage, long-haul, and last-mile segments each facing distinct electrification timelines. The Federal Motor Carrier Safety Administration's hours-of-service rules constrain capacity expansion while California's independent contractor classification law narrows owner-operator participation.
- Rail:BNSF and Union Pacific are adding terminal capacity at Stockton and Barstow to capture Central Valley agricultural exports and reduce Interstate 5 truck volumes, with intermodal gaining share on long-haul corridors.
- Air:Los Angeles International and Ontario International handle time-critical cargo, with belly freight dependent on passenger airline recovery patterns.
- Ocean:The San Pedro Bay port complex processes the majority of containerized imports entering California, with terminal operators implementing shore power and zero-emission yard tractors to meet California Air Resources Board mandates.
Truck holds installed capacity. Rail is rotating up the share rankings.
Technology:
Maturity curves separate proven deployment from pilot-stage innovation, with regulatory deadlines acting as the primary synchronization mechanism for capital deployment.
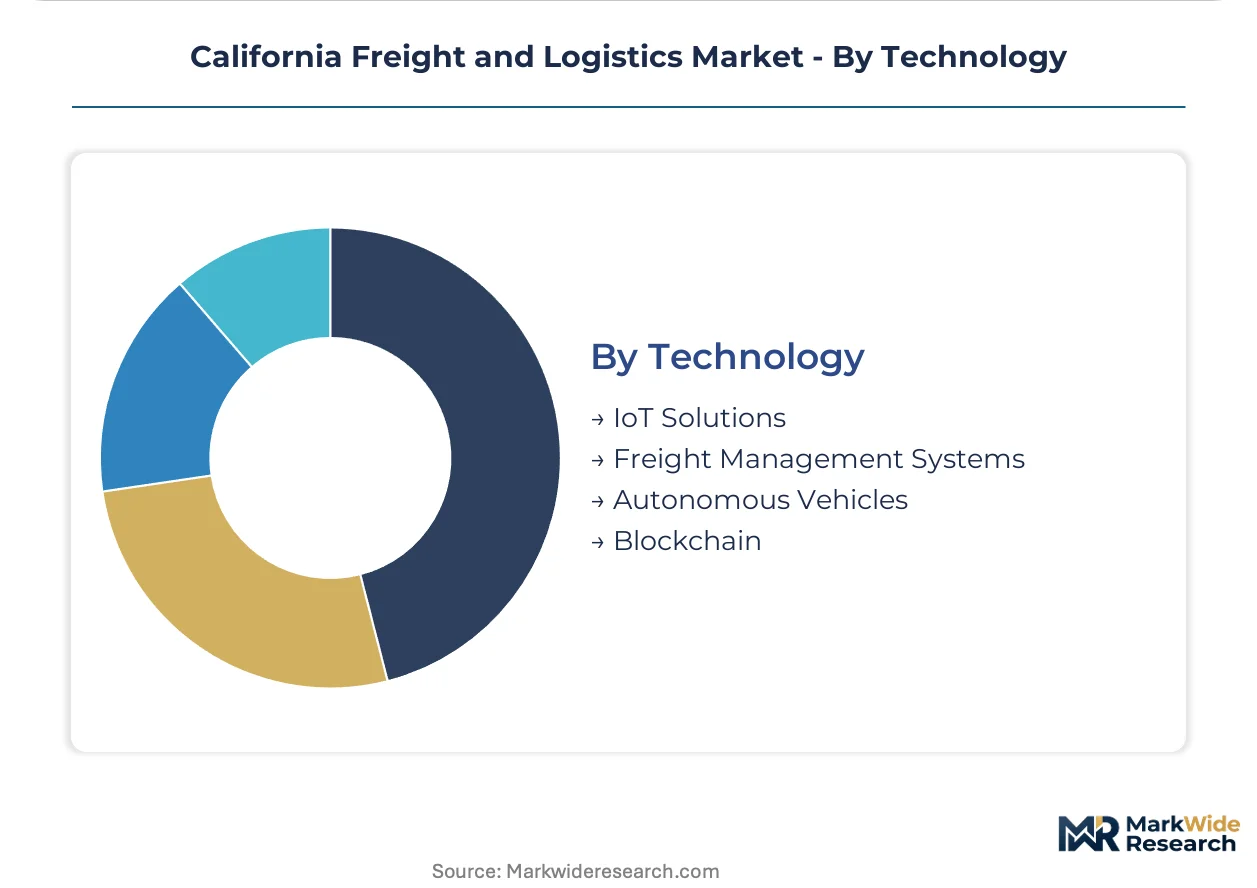
- IoT Solutions:Trailer telematics and warehouse sensors enable real-time inventory visibility, with cold chain operators in Ontario and Redlands pre-wiring facilities for temperature monitoring integration.
- Freight Management Systems:Digital platforms consolidate procurement across ocean, rail, and truck capacity, with technology-enabled brokers optimizing mode selection in real time and displacing traditional asset-based carriers.
- Autonomous Vehicles:Driverless yard tractors at Barstow and Commerce intermodal terminals compress container dwell times, rendering obsolete the traditional drayage broker model for short-haul moves.
- Blockchain:Documentation standardization pilots remain confined to ocean carrier alliances, with limited penetration into California's domestic freight networks.
Freight Management Systems holds installed capacity. Autonomous Vehicles is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across California's freight corridors. Shippers moving agricultural exports through the Central Valley exhibit high price sensitivity to rail versus truck mode selection. E-commerce fulfillment networks in the Inland Empire show low elasticity, absorbing premium land costs to maintain delivery velocity.
Los Angeles-Long Beach Metro
The San Pedro Bay port complex processes the majority of containerized imports entering California. The California Air Resources Board enforces drayage truck electrification deadlines through the Advanced Clean Trucks regulation. Terminal operators at Los Angeles and Long Beach implement shore power and zero-emission yard tractors to meet 2035 diesel phase-out mandates.
Inland Empire
Riverside and San Bernardino counties concentrate e-commerce fulfillment demand from retailers positioning inventory within two-day ground coverage of coastal population centers. The South Coast Air Quality Management District applies warehouse indirect source rules requiring emissions reductions from on-site truck trips. Developers in Ontario and Redlands pre-wire facilities for megawatt-scale charging before tenant occupancy.
Central Valley
Agricultural exporters in Fresno and Kern counties generate temperature-controlled warehousing demand that remains underdeveloped relative to produce volumes through Oakland and Los Angeles-Long Beach. The California Environmental Protection Agency coordinates with local air districts on indirect source rule enforcement timelines. Cold storage gaps persist despite solid-state battery advances enabling zero-emission refrigerated transport.
San Francisco Bay Area
Technology sector supply chains drive high-value air freight through San Francisco International and Oakland International airports. The Bay Area Air Quality Management District imposes facility emissions standards affecting warehouse site selection. Micro-fulfillment centers in Oakland and San Jose qualify for warehouse indirect source rule exemptions under sub-100,000 square foot thresholds.
San Diego Border Corridor
Cross-border manufacturing supply chains generate drayage demand between Tijuana assembly plants and Southern California distribution nodes. The California Air Resources Board's fleet electrification mandates apply equally to border-crossing operators. Industrial developers target Otay Mesa for electrified sites serving just-in-time automotive and electronics supply chains.
California Freight and Logistics Market Competitive Landscape
Asset-heavy carriers and technology-enabled brokers split the market along service model lines. The vendor base concentrates around established hub infrastructure operators and digital freight platforms. Two strategic archetypes dominate: integrated parcel networks with captive ground fleets, and software-mediated forwarders optimizing multi-modal capacity aggregation. Competitive moves center on electrified facility pre-commitments and real-time visibility platform deployment.
Among integrated logistics providers, UPS anchors the hub-and-spoke infrastructure tier with established operations in Ontario and Redding. Flexport occupies the digital freight forwarding position, exemplifying technology-enabled ocean and air cargo aggregation for shippers routing through San Pedro Bay ports. Within the specialized forwarding segment, Dedola Global Logistics and Falcon International represent regional expertise archetypes serving California-specific compliance and customs requirements.
| Leading Market Players |
|---|
| Agramont Worldwide Logistics Inc |
| Flexport |
| SHIPHYPE Fulfillment |
| UPS |
| AP Express Logistics |
| InterFulfillment Inc. |
| Dedola Global Logistics |
| GoBolt |
| Falcon International |
| Others |
Pricing and Supply Chain Analysis
The Los Angeles-Long Beach port corridor concentrates drayage capacity within a fifty-mile radius where land scarcity and electrification mandates compound cost layering. Supply concentration at these terminals enables carriers to extract premium rates for zero-emission compliant moves while downstream e-commerce fulfillment networks absorb higher per-unit logistics costs to maintain delivery velocity commitments.
Pricing Analysis
After-sales service contracts for fleet maintenance and charging infrastructure management drive lifetime value capture for truck operators navigating California Air Resources Board compliance deadlines. The dominant pricing structure stratifies across contract-based long-term offtake agreements for large shippers and spot-market transactional rates for smaller freight forwarders. Price differentiation rests on zero-emission certification tier and volume scale, with Class 8 electric truck fleets commanding premiums over diesel equivalents. Cost compression in the drayage segment is intensifying because grid interconnection delays at Southern California Edison extend fleet deployment timelines. Small apparel importers exhibit highest price sensitivity, while big-box retailers with dedicated distribution networks show least sensitivity due to captive fleet insulation.
Supply Chain Analysis
Tariff exposure between China and the United States dominates import cargo flow volatility through the San Pedro Bay complex. Geographic supply concentration draws from China, Vietnam, and Mexico for containerized manufactured goods entering California ports. Raw material dependencies center on lithium-ion battery cells, semiconductor components, and steel chassis for trailer manufacturing. Single-source vulnerability persists in megawatt-scale charging hardware where limited qualified vendors service fleet electrification timelines. Distribution runs through intermodal rail ramps at Barstow and Stockton before final-mile deployment via contracted motor carriers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
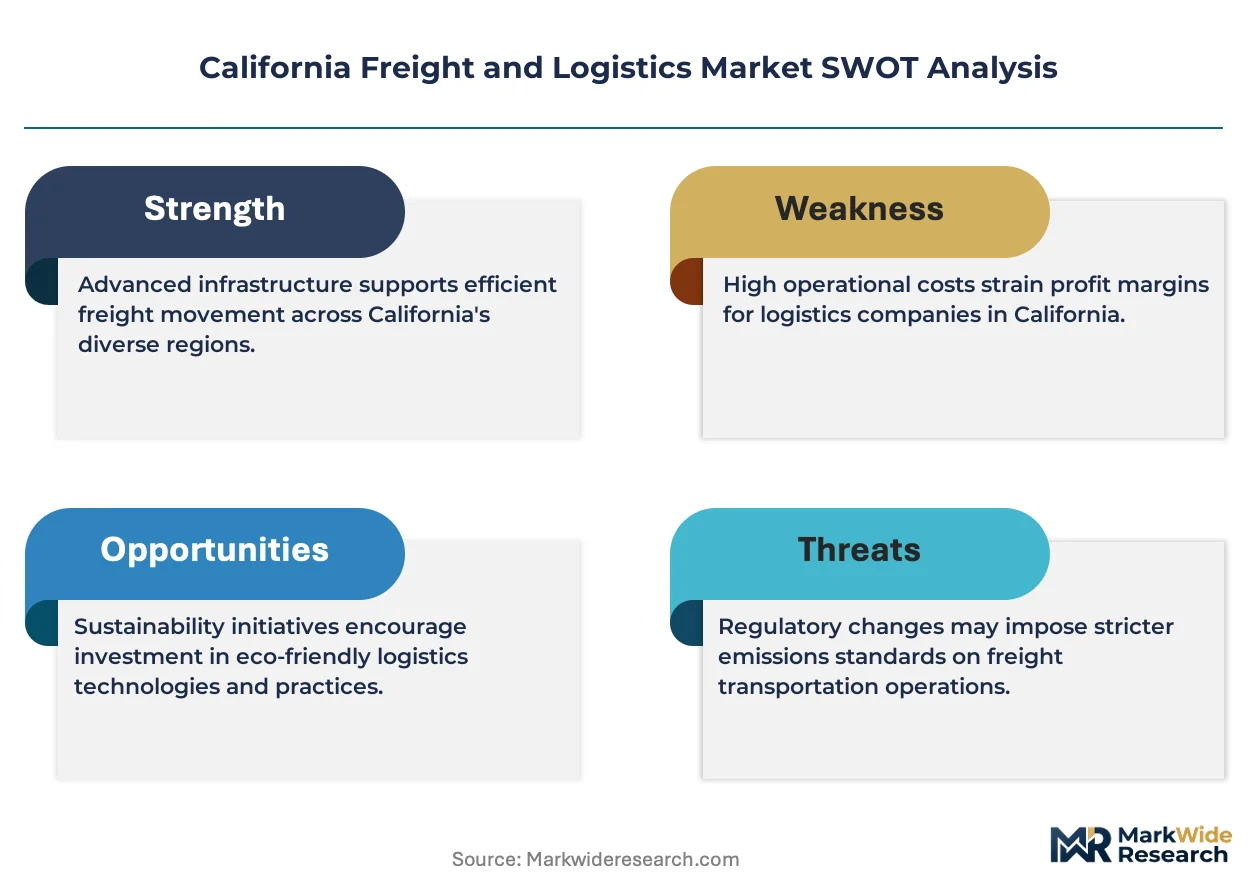
California freight and logistics rewards operators who secure electrified real estate and charging infrastructure ahead of regulatory enforcement, yet qualified site development expertise remains scarce relative to capital deployment timelines. The capability gap sits with developers capable of navigating South Coast Air Quality Management District permitting while pre-wiring facilities for tenant-specific power requirements.
For Market Incumbents: Build electrified facility moats by pre-committing to megawatt-scale charging infrastructure at Inland Empire distribution centers before indirect source rule enforcement tightens. Secure long-term power purchase agreements with Southern California Edison to bypass interconnection queue delays that threaten fleet turnover timelines. Absorb compliance burdens from California Environmental Protection Agency warehouse rules across multi-tenant facilities to lock in e-commerce provider tenancy. Channel control through captive drayage fleets insulates against technology-enabled broker displacement.
For New Entrants and Emerging Players: Central Valley cold chain warehousing represents the most penetrable geography, with temperature-controlled capacity in Fresno and Kern counties lagging produce export volumes through Oakland and Los Angeles-Long Beach. Target agricultural distributor relationships by offering solid-state battery refrigerated units that enable zero-emission transport on corridors previously served by diesel auxiliary power units. Go-to-market angle centers on California Environmental Protection Agency air quality compliance as a bundled service rather than capital expense.
For Investors and Strategic Acquirers: Mid-scale intermodal terminal operators with Barstow or Stockton rail access present acquisition targets given BNSF and Union Pacific capacity expansion commitments. Long-term viability across the analysis window depends on electrification infrastructure deployment pace matching California Air Resources Board mandate timelines. Signal to monitor: Southern California Edison interconnection queue clearance rates for megawatt-scale charging depots, which indicate fleet turnover feasibility and drayage operator solvency.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrified Facility Pre-Wiring | Pre-wiring Ontario and Redlands warehouses for megawatt-scale charging secures South Coast Air Quality Management District permits ahead of tenant occupancy. |
| Intermodal Terminal Capacity Expansion | Adding Stockton and Barstow rail capacity captures Central Valley agricultural exports while reducing Interstate 5 truck volumes. |
| Digital Freight Platform Integration | Aggregating ocean, rail, and truck bookings on single interfaces displaces traditional broker relationships among San Pedro Bay apparel importers. |
| Autonomous Yard Tractor Deployment | Driverless shuttle systems at Commerce and Barstow terminals compress container dwell times and obsolete traditional drayage broker models. |
| Cold Chain Zero-Emission Transition | Solid-state battery chemistry convergence with trailer telematics enables zero-emission refrigerated transport on inland agricultural corridors. |
Research Methodology
Initial hypotheses were tested against primary input from fleet operations managers, warehouse development executives, intermodal terminal planners, and California Air Resources Board compliance officers and refined through secondary validation across customs records, Southern California Edison interconnection queue data, South Coast Air Quality Management District permit filings, and SEC disclosures from publicly traded logistics REITs. Bottom-up triangulation aggregated facility square footage, truck fleet composition, and port throughput volumes against top-down macroeconomic freight demand indicators.
Demand-supply balance framing anchored the analytical framework across the analysis window, modeling service type segmentation alongside transportation mode, end-user category, and technology adoption curve dimensions. CAGRs were derived from volume trajectory convergence across these segments, incorporating California Environmental Protection Agency regulatory phase-in schedules and e-commerce fulfillment density projections as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by technology-enabled freight brokers or accelerated utility infrastructure deployment would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Qatar Freight and Logistics Market
Logistics and Shipping
Sea Freight Forwarding Market
Logistics and Shipping
Malaysia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
France Last Mile Delivery Market
Logistics and Shipping
China Shipping Agency Services Market
Logistics and Shipping
Manufacturing Logistics Market
Logistics and Shipping
Germany Same Day Delivery Market
Logistics and Shipping
Poland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Asia-Pacific Cold Chain Logistics Market
Logistics and Shipping
Global Air Cargo and Freight Logistics Market
Logistics and Shipping
Sustainable Logistics Market
Logistics and Shipping
ASEAN Cross Border Road Freight Transport Market
Logistics and Shipping
United States Chemical Logistics Market
Logistics and Shipping
Asia-Pacific less-Than Container Load (LCL) Market
Logistics and Shipping
Internet of Things (IoT) in Logistics Market
Logistics and Shipping
Singapore 3PL Market