
 Japan Freight and Logistics Market | 2026-2036
Japan Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Freight and Logistics Market Foresight
The capability gap between asset-heavy integrators and digital-first freight brokers is rotating competitive capital allocation across Japan's logistics sector. Nippon Express Holdings leverages its domestic terminal network to sustain overnight delivery coverage nationwide. Yamato Transport Co., Ltd. anchors consumer parcel flows through dense last-mile infrastructure in metropolitan corridors. Kintetsu World Express, Inc. competes on international air freight specialization, particularly for semiconductor and electronics shippers.
Japan freight and logistics encompasses the physical movement, storage, and customs facilitation of goods across domestic and international supply chains, typically operating through temperature-controlled facilities, cross-docking terminals, and multi-modal transfer hubs designed for just-in-time manufacturing synchronization. The service type dimension shows transportation and warehousing commanding established revenue pools, while freight forwarding gains margin from customs complexity and trade lane volatility. End user segmentation reveals e-commerce and pharmaceuticals as the fastest-expanding demand verticals, driven by cold-chain requirements and same-day delivery expectations. Technology adoption concentrates on IoT and automation, where real-time inventory tracking and robotic picking systems reduce labor dependency in aging workforce markets.
METI's carbon neutrality roadmap and the Ministry of Land, Infrastructure, Transport and Tourism's truck driver hour limits are reshaping fleet composition and modal shift incentives toward rail and coastal shipping alternatives. JIS standards for pallet dimensions and container interoperability reduce friction in multi-handler networks, while the EPA enforces emission benchmarks that filter older diesel assets from metropolitan zones. Stakeholders must weigh automation deployment pace against workforce transition timelines as regulatory pressure and demographic contraction converge on operational design choices.
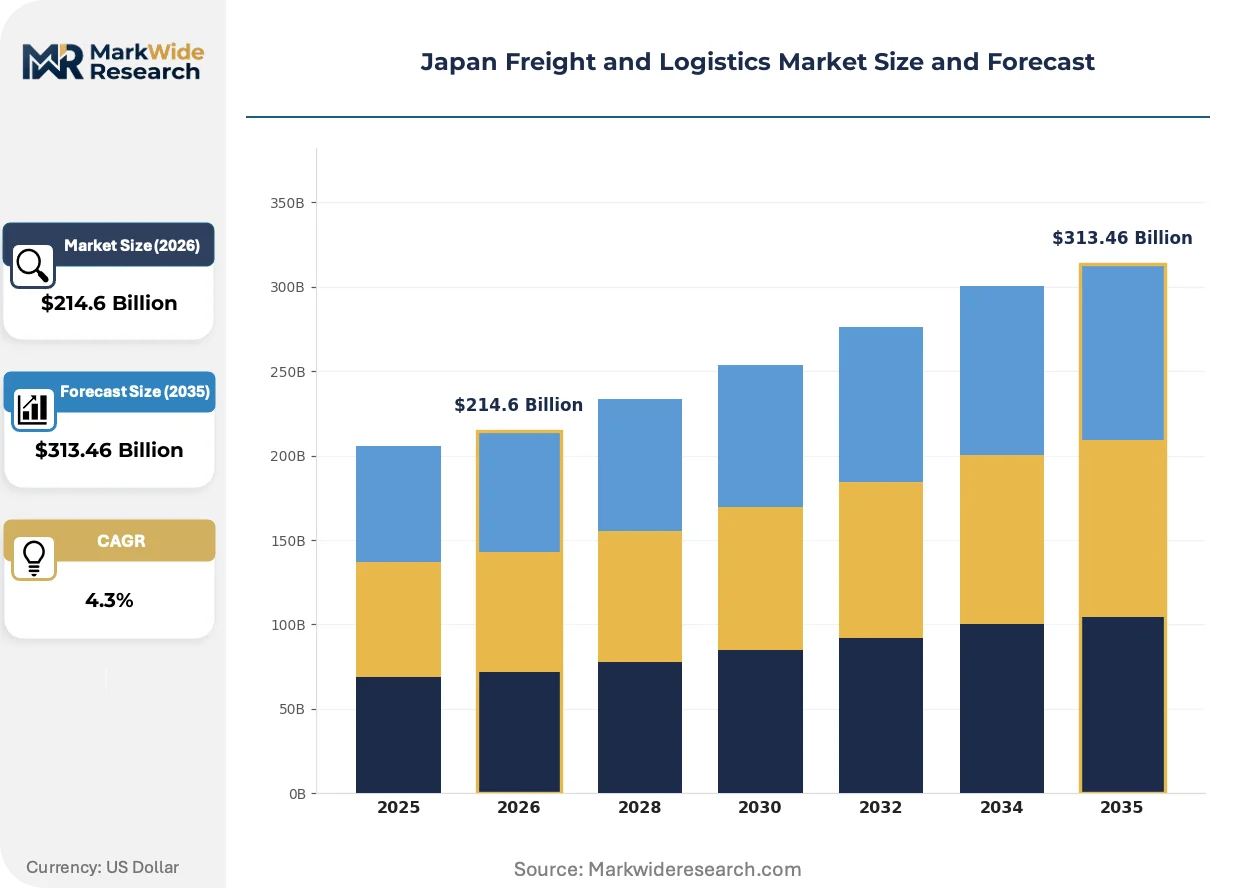
Market Dynamics
Japan's logistics sector faces a workforce contraction that is compressing operational timelines and accelerating capital deployment into automation systems. METI's carbon neutrality mandates and the Ministry of Land, Infrastructure, Transport and Tourism's driver hour restrictions are forcing modal reconfigurations across freight networks.
Growth Catalysts
- E-commerce fulfillment density:Same-day delivery expectations from platforms like Rakuten and Amazon Japan are expanding warehouse footprints in the Kanto corridor. Cold-chain infrastructure investments follow pharmaceutical distribution requirements.
- METI efficiency mandates:Regulatory pressure to reduce logistics costs as percentage of GDP is accelerating warehouse management system adoption and robotic picking deployment.
- Semiconductor supply chain regionalization:Electronics manufacturers are reshoring inventory buffers, increasing demand for bonded warehousing and just-in-time air freight coordination.
Market Restraints
- Diesel fleet obsolescence costs:EPA-aligned emission benchmarks in metropolitan zones are forcing premature asset retirement without sufficient electric truck charging infrastructure.
- Terminal network concentration:Domestic freight flows concentrate through Osaka and Nagoya hubs, creating single-point vulnerability during disruption events.
- Labor pool demographic cliff:Truck driver age profiles show 40% above 50 years, with insufficient youth entry to replace retiring operators under existing hour limits.
Strategic Opportunities
- Hokkaido agricultural export corridor:Underdeveloped cold-chain connectivity to Asian markets offers first-mover advantage for temperature-controlled coastal shipping integration.
- Pharmaceutical serialization compliance:PMDA track-and-trace mandates are creating service revenue pools for logistics providers with validated IT infrastructure.
- Autonomous yard vehicle convergence:Integration of LiDAR navigation with existing warehouse management systems enables labor-free container repositioning at intermodal terminals.
Industry Challenges
- Multi-generational system integration:Legacy mainframe-based inventory platforms at established 3PLs resist API connectivity with modern IoT sensor networks.
- Certification timeline compression:PMDA good distribution practice validation for pharmaceutical logistics requires 18-24 month facility qualification cycles that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Freight and Logistics Market |
| Market Size in 2026 | $214.6 Billion |
| Market Size in 2035 | $313.46 Billion |
| CAGR (2026 – 2036) | 4.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Customs Brokerage End User: Retailers, Manufacturers, E-commerce, Pharmaceuticals Technology: Automation, RFID, IoT, Blockchain Delivery Mode: Air Freight, Ocean Freight, Road Transport, Rail Transport |
| Companies Covered | Japan Post Holdings Co., Ltd., DB Schenker, Nippon Express Holdings, MOL Logistics Global, Suzuyo, SG Holdings Co., Ltd., Kuehne+Nagel, Kintetsu World Express, Inc., Yamato Transport Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Freight and Logistics Market Shifts & Advancements
Automation investment patterns in Japan's logistics sector are diverging based on facility age and customer sophistication tiers. Technology deployment is fragmenting across robotic process intensity levels rather than following uniform adoption curves.
Autonomous mobile robots in warehouse operations are bifurcating fulfillment economics between greenfield automated facilities and retrofit-constrained brownfield sites. E-commerce platforms with dedicated fulfillment centers are deploying robotic picking at scale, while third-party logistics providers serving fragmented manufacturing bases face capital allocation constraints. This technology divide is compressing margin structures for mid-tier operators unable to match throughput efficiency.
METI's carbon neutrality roadmap is mandating fleet electrification timelines that outpace charging infrastructure deployment. Logistics operators must absorb asset stranding risk from diesel truck premature retirement while securing grid connection capacity for electric alternatives. The Kanto region faces the most acute infrastructure gap, with metropolitan delivery routes most affected by zero-emission zone designations.
Shippers are consolidating vendor relationships around integrated service capabilities that bundle transportation, warehousing, and customs brokerage. Pharmaceutical manufacturers are replacing fragmented supplier networks with single-source logistics partners possessing PMDA-validated cold-chain credentials. This concentration pattern is most visible in the Osaka-Kobe pharmaceutical cluster, where compliance complexity favors scale operators.
Japan Freight and Logistics Market Segmentation
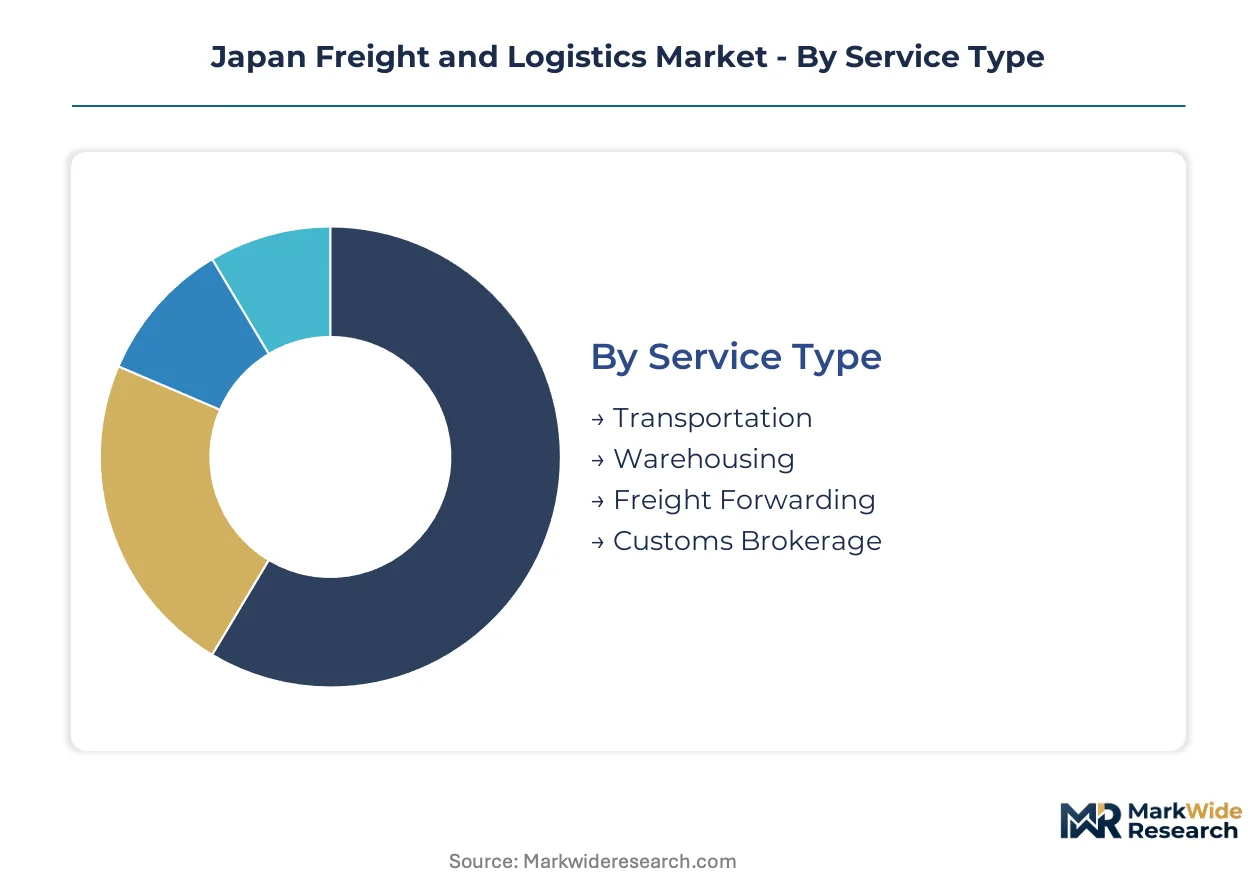
Segmentation in Japan's logistics sector reveals how regulatory pressure and automation maturity are concentrating investment across service tiers. Understanding these divisions exposes where METI mandates and workforce constraints are reshaping competitive economics.
Service Type:
METI's logistics efficiency mandates apply differential compliance burdens across service categories, with warehousing and transportation facing the most stringent automation requirements.
- Transportation:Asset-heavy fleet operations move goods across modal networks, with diesel-to-electric transition timelines compressing under EPA-aligned emission benchmarks in metropolitan Tokyo and Osaka zones. Road transport dominates domestic volume, though driver hour restrictions from the Ministry of Land, Infrastructure, Transport and Tourism are forcing modal shifts toward rail and coastal alternatives.
- Warehousing:Temperature-controlled facilities and cross-docking terminals form the physical backbone of just-in-time manufacturing synchronization. Kanto region demand concentration around Tokyo and Yokohama is expanding warehouse footprints to meet same-day delivery expectations from e-commerce platforms.
- Freight Forwarding:Customs facilitation and trade lane coordination services gain margin from documentation complexity and tariff volatility. Bonded warehousing demand follows semiconductor supply chain regionalization trends.
- Customs Brokerage:Documentation processing and regulatory compliance services reduce clearance friction at Narita, Kansai, and Nagoya ports.
Established volume favors Transportation; emerging adoption favors Warehousing.
End User:
Cost tier differentiation separates high-compliance verticals from price-sensitive commodity flows.
- E-commerce:Same-day delivery expectations from Rakuten and Amazon Japan are expanding fulfillment center footprints in the Kanto corridor. Cold-chain infrastructure investments follow pharmaceutical distribution requirements.
- Pharmaceuticals:PMDA track-and-trace mandates and good distribution practice validation create 18-24 month facility qualification cycles. The Osaka-Kobe pharmaceutical cluster concentrates demand for validated cold-chain credentials.
- Retailers:Dense last-mile infrastructure in metropolitan corridors anchors consumer parcel flows through established terminal networks.
- Manufacturers:Just-in-time synchronization requirements from electronics and automotive producers drive demand for bonded warehousing and air freight coordination.
Pharmaceuticals command premium pricing through compliance complexity; E-commerce drives volume expansion fastest.
Technology:
Application maturity separates greenfield automated facilities from retrofit-constrained brownfield sites.
- Automation:Robotic picking systems and autonomous mobile robots reduce labor dependency in aging workforce markets. E-commerce platforms with dedicated fulfillment centers deploy at scale, while mid-tier 3PLs face capital allocation constraints.
- IoT:Real-time inventory tracking and sensor networks enable predictive maintenance across fleet and warehouse assets. Integration with legacy mainframe platforms at established operators creates API connectivity friction.
- RFID:Pallet-level tracking improves throughput accuracy in multi-handler networks where JIS standards reduce interoperability friction.
- Blockchain:Documentation verification and supply chain transparency applications remain in pilot phases for pharmaceutical serialization compliance.
IoT anchors near-term deployment; Automation represents the steepest expansion trajectory as labor pool contraction accelerates.
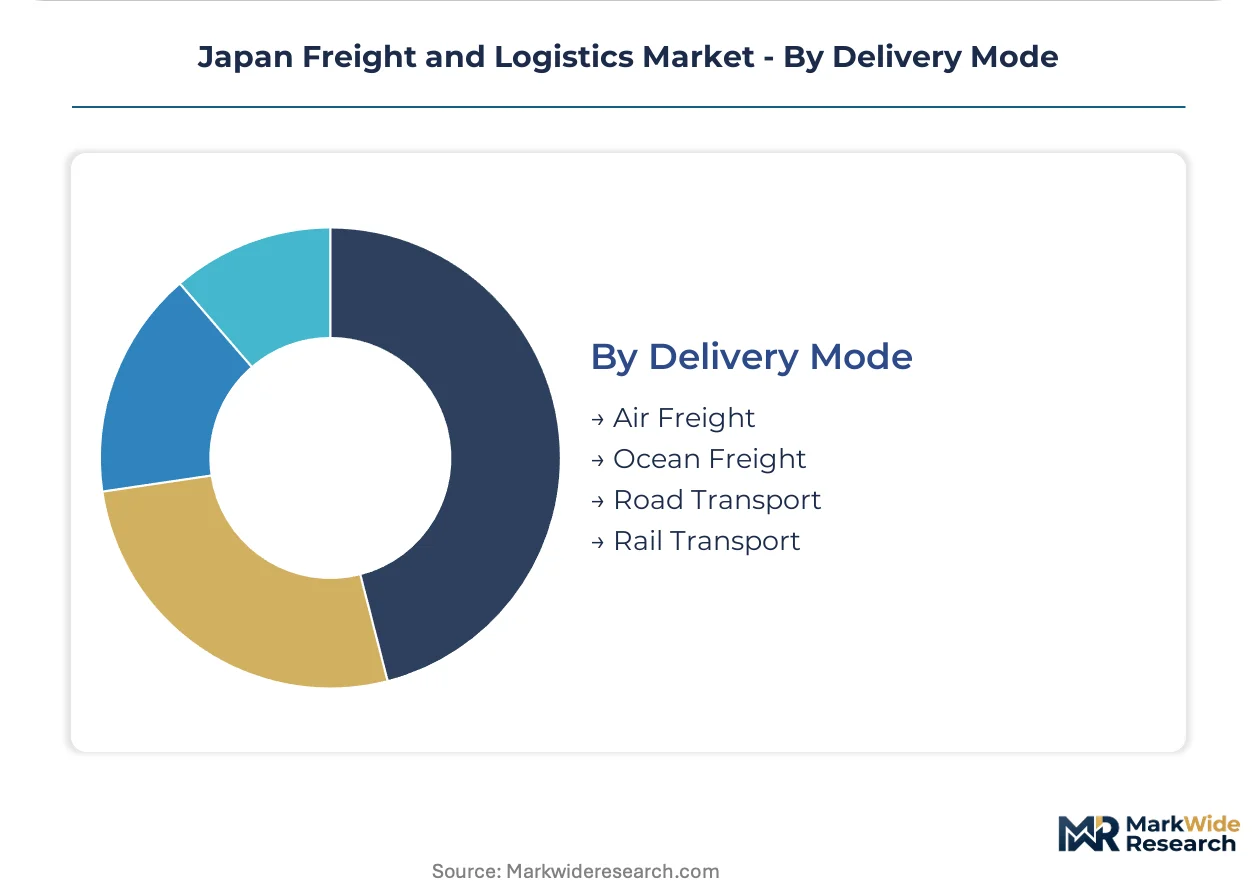
Delivery Mode:
Geography concentration determines modal economics, with Kanto region infrastructure gaps most acute for zero-emission transitions.
- Road Transport:Metropolitan delivery routes face the most severe charging infrastructure gaps for electric truck deployment under METI's carbon neutrality roadmap.
- Air Freight:Semiconductor and electronics shippers demand just-in-time coordination through Narita and Kansai gateways. Kintetsu World Express specializes in this vertical.
- Ocean Freight:Coastal shipping alternatives gain modal share as driver hour restrictions compress road transport timelines.
- Rail Transport:Intermodal terminals in Osaka and Nagoya create single-point vulnerability during disruption events.
Road Transport maintains volume dominance; Rail Transport gains share through modal shift incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Japan's logistics corridors. E-commerce shippers in the Kanto region absorb premium pricing for same-day delivery, while agricultural exporters in peripheral regions face acute cost sensitivity on cold-chain services.
Kanto/Tokyo
Same-day delivery expectations from Rakuten and Amazon Japan are expanding fulfillment center footprints across Greater Tokyo. METI's carbon neutrality roadmap is forcing diesel-to-electric fleet transitions ahead of charging infrastructure readiness. The Tokyo-Yokohama corridor concentrates warehouse automation investment as labor shortages bite deepest.
Kansai/Osaka
The Osaka-Kobe pharmaceutical cluster generates validated cold-chain demand for PMDA-compliant distribution. The Ministry of Land, Infrastructure, Transport and Tourism's driver hour restrictions are pushing modal shifts toward coastal shipping alternatives. Bonded warehousing capacity is expanding to serve semiconductor reshoring inventory buffers.
Chubu/Nagoya
Automotive just-in-time synchronization requirements from Toyota and suppliers anchor intermodal terminal throughput. JIS standards for pallet interoperability reduce friction in multi-handler manufacturing networks. Nagoya's port infrastructure is upgrading to handle elevated electronics air freight coordination.
Hokkaido
Agricultural export corridors to Asian markets remain underdeveloped on temperature-controlled coastal shipping connectivity. METI efficiency mandates are accelerating warehouse management system adoption in regional distribution centers. Sapporo-based cold-chain operators face infrastructure gaps for pharmaceutical-grade serialization compliance.
Kyushu
Semiconductor manufacturing reshoring is elevating demand for bonded warehousing and just-in-time air freight through Fukuoka gateways. The aging truck driver demographic shows 45% above 50 years in regional fleets. Container terminal automation is lagging Kanto investment cycles by 3-5 years.
Japan Freight and Logistics Market Competitive Landscape
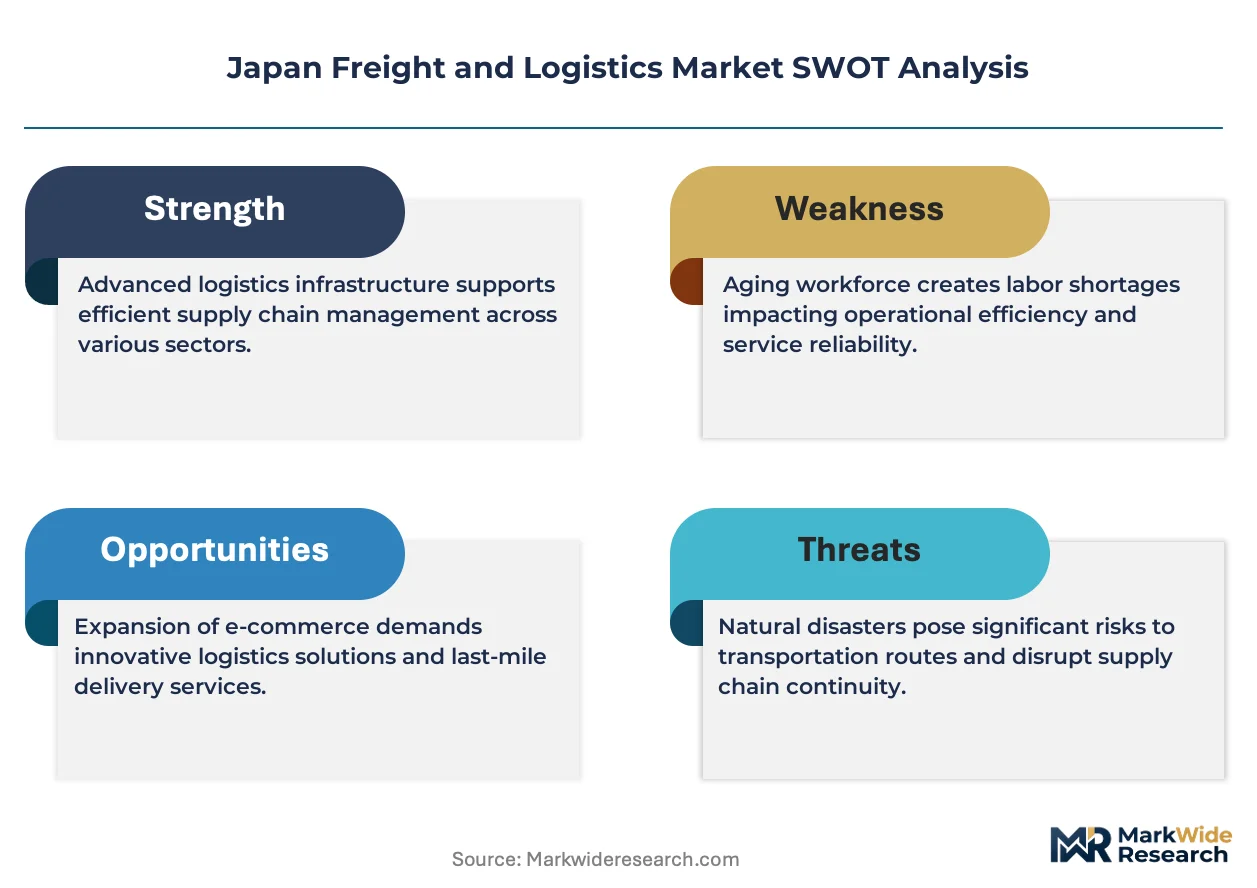
Technology leadership and cost leadership are held by different player archetypes across Japan's logistics sector. Asset-heavy integrators with dense terminal networks command premium positioning on overnight coverage, while digital-first freight brokers capture margin from customs complexity and trade lane volatility. Three archetypes dominate: domestic network operators with legacy infrastructure, international specialists with air freight credentials, and platform-integrated e-commerce fulfillment providers. Competitive moves concentrate on warehouse automation deployment and strategic partnerships for last-mile density.
Among domestic network operators, Nippon Express Holdings and Yamato Transport Co., Ltd. exemplify the asset-heavy archetype with established terminal infrastructure. Kintetsu World Express, Inc. occupies a specialist position on international air freight coordination for semiconductor and electronics verticals. These three represent distinct competitive vectors: overnight domestic coverage, consumer parcel density, and cross-border manufacturing synchronization.
| Leading Market Players |
|---|
| Japan Post Holdings Co., Ltd. |
| DB Schenker |
| Nippon Express Holdings |
| MOL Logistics Global |
| Suzuyo |
| SG Holdings Co., Ltd. |
| Kuehne+Nagel |
| Kintetsu World Express, Inc. |
| Yamato Transport Co., Ltd. |
| Others |
Supply & Pricing Matrix
Three-day inventory turns at Kanto e-commerce fulfillment centers concentrate pricing power with asset-heavy operators possessing dense terminal networks, while METI efficiency mandates compress margins for mid-tier third-party logistics providers lacking automation scale.
Pricing Analysis
After-sales service contracts and extended maintenance agreements drive lifetime value capture for warehouse automation providers serving pharmaceutical and e-commerce verticals. Contract-based long-term offtake structures dominate, with price differentiation hinging on PMDA validation tier and geographic delivery density. Cost compression in standard freight forwarding is intensifying because digital-first brokers capture customs coordination margin without asset ownership. Small and mid-sized manufacturers show highest price sensitivity, while pharmaceutical shippers absorb premium pricing for validated cold-chain credentials.
Supply Chain Analysis
Inventory positioning at Osaka-Nagoya intermodal terminals reveals concentration vulnerability, with semiconductor and electronics inputs drawing from Taiwan, South Korea, and domestic Kyushu fabrication clusters. Diesel engine components, lithium-ion battery cells, and warehouse robotics hardware anchor procurement exposure. Single-source vulnerability runs through concentrated terminal throughput during disruption events. Distribution feeds from bonded warehousing nodes at Narita, Kansai, and Nagoya ports into metropolitan last-mile corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity is opening across Japan's logistics sector as e-commerce fulfillment requirements splinter demand across specialized temperature-controlled, same-day, and pharmaceutical-grade service tiers.
For Market Incumbents: Compound terminal network density through selective automation deployment at Kanto and Kansai hubs to defend against digital freight broker margin capture. Prioritize PMDA certification investment to lock pharmaceutical vertical relationships before facility qualification timelines extend. Vertical integration into warehouse robotics maintenance services creates captive revenue streams as labor pool contraction accelerates.
For New Entrants and Emerging Players: Anchor in Hokkaido agricultural export corridors where temperature-controlled coastal shipping connectivity remains underdeveloped against Asian market demand. Target pharmaceutical serialization compliance services as the most penetrable segment, leveraging 18-24 month qualification cycle delays at established operators. Lead with validated IT infrastructure partnerships as the go-to-market angle to bypass capital-intensive facility buildouts.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across warehouse automation sub-segments as robotic picking deployment becomes table stakes for Kanto corridor competitiveness. Long-term viability favors asset-light platform models with API-native architecture over legacy mainframe-dependent operators. Acquisition target archetype: mid-tier 3PLs with dense regional terminal networks but underinvested automation. Signal to watch: METI carbon neutrality enforcement pace against electric truck charging infrastructure deployment gaps.
| Strategic Initiative | Industry Significance |
|---|---|
| Warehouse Automation Scale-Up | Robotic picking deployment at Kanto fulfillment centers addresses METI efficiency mandates and labor shortage convergence. |
| PMDA Validation Investment | Facility qualification cycles create 18-24 month competitive moats in Osaka-Kobe pharmaceutical cluster. |
| Coastal Shipping Modal Shift | Driver hour restrictions from the Ministry of Land, Infrastructure, Transport and Tourism force rail and maritime alternatives. |
| Electric Fleet Transition | Zero-emission zone designations in metropolitan Tokyo and Osaka compress diesel asset retirement timelines. |
| Pharmaceutical Serialization Partnership | Track-and-trace mandates generate service revenue for logistics providers with validated IT infrastructure. |
Research Methodology
Operator-level perspectives from logistics network planners, warehouse operations directors, pharmaceutical supply chain managers, e-commerce fulfillment executives, and METI policy liaisons anchored the qualitative base. Primary interview insights combined with secondary validation from Ministry of Land, Infrastructure, Transport and Tourism regulatory filings, Japan Customs trade statistics, JIS standards documentation, and listed logistics operator securities disclosures. Bottom-up facility and fleet capacity assessments triangulated against top-down GDP logistics cost ratio benchmarks.
Sensitivity analysis framing tested volume and value outputs against modal shift elasticity, automation adoption curves, and regulatory enforcement pace variations across the projection horizon. Segmentation dimensions modeled encompass service type, end-user vertical, technology tier, and regional demand cluster. CAGRs derived from historical logistics cost-to-GDP trajectory analysis, e-commerce penetration trend extrapolation, and semiconductor supply chain regionalization patterns. Forecast inputs incorporated workforce demographic cliff projections and charging infrastructure deployment schedules.
Decision-makers should treat outputs as directional under base assumptions of METI mandate continuity and moderate e-commerce growth; material deviation in regulatory enforcement pace or modal shift subsidies would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
UAE Contract Logistics Market
Logistics and Shipping
Military Logistics Market
Logistics and Shipping
Digital Freight Management Market
Logistics and Shipping
Global Connected Logistics Market
Logistics and Shipping
Remanufacturing and Core Returns Logistics Management Market
Logistics and Shipping
Third-Party Logistics (3PL) Market
Logistics and Shipping
India E-Commerce Logistics Market
Logistics and Shipping
Digital Freight Brokerage Market
Logistics and Shipping
APAC Contract Logistics Market
Logistics and Shipping
Shipping Container Modification Market
Logistics and Shipping
Automotive Logistics Market
Logistics and Shipping
Logistics Automation Market
Logistics and Shipping
France Last Mile Delivery Market
Logistics and Shipping
Thailand Courier Express Parcel (CEP) Market
Logistics and Shipping
Logistics Outsourcing Market
Logistics and Shipping
Nigeria Air Freight Market