
 Microphytes Market | 2026-2036
Microphytes Market Size, Share, and Industry Trends Forecast 2026-2036
Microphytes Market Intelligence
Open-pond and closed photobioreactor cultivation technology is fragmenting the production landscape as capital requirements and yield profiles diverge sharply between methods. Algatech Ltd. leverages its Israeli desert facility advantages for astaxanthin purity leadership. DIC Corporation anchors the spirulina segment through backward integration into Hawaiian production sites. Cyanotech Corporation differentiates via its controlled-environment Kona facility and GRAS self-affirmation strategy.
Microphytes are microscopic photosynthetic organisms, typically unicellular algae, cultivated in saline or freshwater systems with cell diameters below 0.2 mm and lipid contents ranging from 20% to 50% dry weight depending on strain and stress conditions. Their primary commercial purpose centers on high-value metabolite extraction for nutrition, feed, and bioactive applications. Dry powder formulations dominate pharmaceutical and nutraceutical procurement channels due to stability and dosing precision. Liquid extracts lead cosmetics applications where formulation flexibility commands premium positioning. Biofertilizer applications in agriculture companies represent the fastest-expanding end-user channel as nitrogen-fixing cyanobacteria replace synthetic inputs.
EMA novel food approval pathways and EFSA health claim substantiation requirements shape European market access timelines for microalgae-derived ingredients. EPA effluent guidelines and USDA organic certification standards govern US production site compliance and product positioning. FDA GRAS notification procedures create a de facto gatekeeping mechanism for new strain introductions. Stakeholders must monitor evolving carbon accounting methodologies for biomass credits as regulatory frameworks mature.
Market Dynamics
Fishmeal substitution mandates are compressing aquafeed formulation timelines while EU sustainability regulations force capital reallocation toward closed photobioreactor systems. This dual pressure is fragmenting production economics between commodity and premium biomass tiers.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of synthetic refrigerants accelerates investment in naturally derived astaxanthin for salmon pigmentation, redirecting aquafeed procurement toward microalgae sources.
- China's domestic cultivation clusters:Spirulina and chlorella production concentration in Yunnan and Inner Mongolia generates export-ready supply chains serving nutraceutical buyers across Southeast Asia.
- Nitrogen-fixing cyanobacteria:Biofertilizer applications displace synthetic urea in Indian and Brazilian row-crop agriculture, creating pull-through demand for bulk biomass contracts.
Market Restraints
- Energy input volatility:Closed photobioreactor operations consume 3-7 kWh per kilogram dry biomass, exposing producers to European and North American electricity price swings.
- Strain IP concentration:Proprietary high-lipid and high-astaxanthin strains remain concentrated among Israeli, Japanese, and US research consortia, limiting technology transfer to new entrants.
- EMA novel food timelines:EFSA health claim substantiation requires 18-36 months for microalgae-derived ingredients, delaying European market entry for new strain developers.
Strategic Opportunities
- Carbon credit methodologies:Evolving ISO 14064 and EU Carbon Border Adjustment Mechanism frameworks create monetization pathways for biomass producers with verified sequestration claims.
- Precision fermentation convergence:Hybrid production combining phototrophic cultivation with heterotrophic fermentation enables 24-hour production cycles for high-value metabolites.
- Direct-to-formulator channels:Cosmetics manufacturers in South Korea and France increasingly procure liquid extracts bypassing traditional ingredient distributors.
Industry Challenges
- Phycologist talent scarcity:Strain optimization and contamination control require specialized expertise concentrated in university research programs at Wageningen, Tel Aviv, and Queensland.
- GRAS self-affirmation complexity:FDA notification procedures for new microalgae strains demand toxicology packages costing $400,000-$800,000, constraining small-scale innovators.
- Contamination protocol standardization:Lack of harmonized HACCP guidelines across US, EU, and Chinese inspection regimes complicates multi-site production strategies.
Report Scope
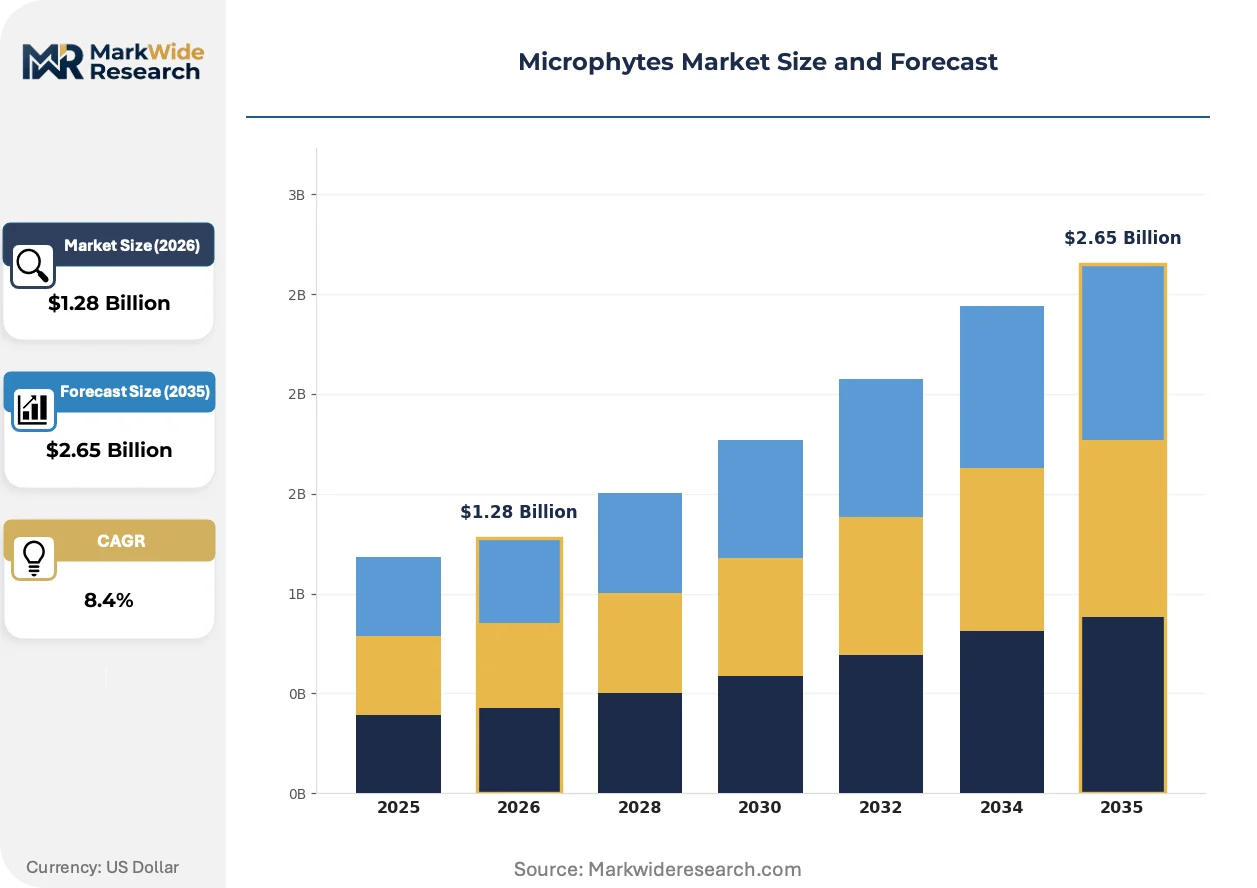
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microphytes Market |
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Green Algae, Red Algae, Blue-Green Algae, Diatoms, Brown Algae Application: Biofertilizers, Aquaculture Feed, Wastewater Treatment, Biofuels, Cosmetics End User: Pharmaceutical Firms, Agriculture Companies, Aquaculture Farms, Energy Producers, Personal Care Brands Form: Dry Powder, Liquid Extract, Granules, Paste, Capsules |
| Companies Covered | Algatech Ltd., Fuqing King Dnarmsa Spirulina, DIC Corporation, Dongying Haifu Biological, Shengbada Biology, Cyanotech Corporation, Cargill Incorporated, TAAU Australia, Algaetech Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microphytes Market Strategic Shifts & Innovations
Digital twin technology and spectral monitoring systems are compressing cultivation cycle optimization from months to weeks. These advances are converging with regulatory data requirements to reshape competitive capability thresholds.
Hyperspectral imaging combined with machine learning is virtualizing real-time biomass composition analysis in both open-pond and closed photobioreactor operations. Mid-scale producers in Spain and Australia are deploying these systems to reduce laboratory testing overhead by sixty percent. The technology is virtualizing quality assurance workflows, enabling batch-release decisions without offline sampling delays.
REACH registration requirements for microalgae-derived novel substances are tightening substance characterization obligations for European market access. Industrial consequences include mandatory full toxicological dossiers for extracts exceeding one tonne annual volume. Cosmetic formulators and nutraceutical blenders are responding by consolidating supplier relationships toward established REACH-registered producers.
Certification-driven procurement is displacing price-first supplier selection in premium nutraceutical channels. Buyers now prioritize USDA Organic, EU Organic, and ASC-MSC chain-of-custody credentials over per-kilogram cost metrics. This shift is most visible in German and US dietary supplement distribution, where retailer shelf-access depends on multi-certification compliance.
Microphytes Market Segmentation
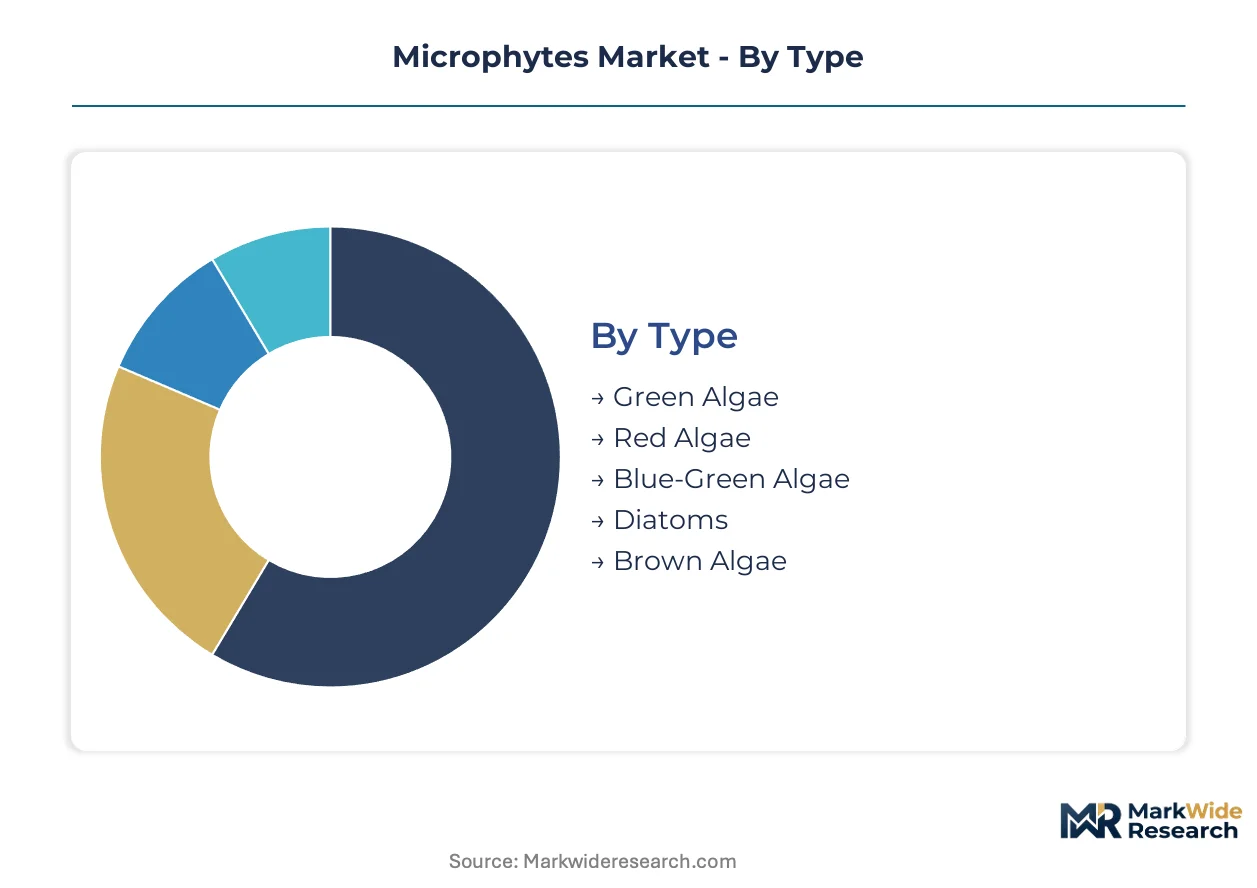
Microphytes classification determines cultivation system selection, regulatory pathway complexity, and margin structure across the value chain. Strain-specific lipid profiles and metabolite concentrations create divergent production economics that reshape supplier positioning. Procurement patterns fragment sharply between bulk biomass contracts and precision-extract formulations.
Type:
Cycle times vary from 48-hour harvest windows for fast-growing cyanobacteria to 14-day maturation for astaxanthin-accumulating red algae strains.
- Green Algae:Chlorella and Scenedesmus strains dominate nutraceutical spirulina substitution with protein contents exceeding 60% dry weight. Chinese cultivation clusters in Yunnan supply both domestic TCM compounders and European organic certifiers facing EFSA novel food delays.
- Red Algae:Haematococcus pluvialis accumulates astaxanthin esters up to 5% dry weight under nitrogen stress, commanding premium positioning in salmon pigmentation markets. Israeli desert photobioreactor operators leverage solar intensity advantages for purity leadership against synthetic astaxanthin competitors.
- Blue-Green Algae:Nitrogen-fixing cyanobacteria strains enable biofertilizer applications displacing synthetic urea in Indian soybean and Brazilian sugarcane belts.
- Diatoms:Silica-frustule structures deliver unique lipid profiles for omega-3 concentrates targeting pharmaceutical omega-3 API specifications.
- Brown Algae:Fucoxanthin-rich strains concentrate in East Asian coastal cultivation serving South Korean and Japanese cosmetics formulators.
Green algae anchors the volume base while red algae gains share at the steepest rate.
Application:
Cost tiers separate commodity biomass contracts from precision-extract formulations with tenfold price differentials.
- Biofertilizers:Bulk cyanobacterial inoculants replace synthetic nitrogen in Indian Punjab wheat systems and Brazilian Cerrado soybean operations. State subsidy programs in Maharashtra and Minas Gerais accelerate procurement velocity beyond private channel growth.
- Aquaculture Feed:Fishmeal substitution mandates compress formulation timelines as EU F-Gas Regulation redirects salmon pigmentation procurement from synthetic astaxanthin. Norwegian and Scottish farm operators now specify algae-derived carotenoids for ASC-MSC chain-of-custody compliance.
- Wastewater Treatment:Nutrient-stripping deployments concentrate in Israeli and Spanish municipalities with high effluent phosphorus loads.
- Biofuels:Lipid-to-FAME conversion economics remain marginal outside Brazilian integrated sugarcane-algae pilot facilities.
- Cosmetics:Liquid extract procurement bypasses traditional distributors as South Korean and French formulators source directly for premium serum positioning.
Aquaculture feed commands the largest contract values while biofertilizers expand most quickly across emerging agricultural markets.
End User:
Customer sophistication determines specification stringency from bulk biomass assays to pharmaceutical-grade COA requirements.
- Pharmaceutical Firms:Omega-3 API producers demand DHA concentrations above 35% with full REACH registration dossiers for European market access. CDSCO and FDA dual-filing requirements extend development timelines for Indian and US generic developers.
- Agriculture Companies:Row-crop input suppliers in Brazil and India negotiate multi-year bulk contracts for nitrogen-fixing inoculants with price escalation clauses tied to synthetic urea benchmarks.
- Aquaculture Farms:Norwegian and Vietnamese integrated operators specify astaxanthin inclusion rates for flesh color scoring at harvest.
- Energy Producers:Brazilian sugarcane ethanol processors pilot lipid extraction for renewable diesel blending mandates.
- Personal Care Brands:South Korean chaebol cosmetics divisions and French independent formulators procure liquid extracts with customized phycocyanin concentrations.
Agriculture companies anchor procurement volumes while pharmaceutical firms drive specification escalation.
Form:
Stability requirements and dosing precision create divergent packaging and logistics cost structures.
- Dry Powder:Spray-dried biomass with moisture below 7% dominates nutraceutical encapsulation and feed premix applications. German and US dietary supplement distributors require USDA Organic and EU Organic dual certification for shelf access.
- Liquid Extract:Glycerin-stabilized phycocyanin and astaxanthin suspensions enable cosmetics formulation flexibility with 18-month stability windows. Direct procurement from Israeli and Spanish producers displaces traditional ingredient distribution in premium channels.
- Granules:Slow-release formulations target agricultural broadcast applications with extended soil residence times.
- Paste:High-moisture concentrates serve regional aquafeed mills with short supply chains in Vietnam and Indonesia.
- Capsules:Finished dosage forms concentrate in Chinese TCM and Indian Ayurveda distribution networks.
Dry powder commands the installed base while liquid extracts climb the fastest in premium cosmetics procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese cultivation clusters in Yunnan and Inner Mongolia supply spirulina and chlorella to nutraceutical buyers across Southeast Asia and Europe. Israeli desert photobioreactor operators export astaxanthin to Norwegian salmon farms. Brazilian biofertilizer producers ship nitrogen-fixing cyanobacteria to Argentine soybean growers.
China
Domestic spirulina and chlorella cultivation concentrates in Yunnan province and Inner Mongolia, serving both regional TCM compounders and export markets. The Ministry of Ecology and Environment enforces dual carbon goals that redirect investment toward closed photobioreactor systems with lower energy intensity. Qingdao and Dalian harbor zones host extraction facilities processing biomass for European nutraceutical distributors awaiting EFSA novel food approvals.
Israel
Desert photobioreactor operators leverage solar intensity advantages for astaxanthin purity leadership in salmon pigmentation markets. The national water authority regulates effluent discharge from cultivation facilities with stringent phosphorus recovery mandates. Arava Valley production sites supply carotenoid extracts directly to Norwegian and Scottish aquaculture operators seeking ASC-MSC chain-of-custody compliance.
Norway
Integrated salmon farm operators specify algae-derived astaxanthin inclusion rates for flesh color scoring at harvest. The Norwegian Food Safety Authority enforces residue monitoring protocols that favor naturally derived pigments over synthetic alternatives. Bergen and Trondheim procurement offices contract Israeli and Spanish producers for multi-year pigment supply agreements.
Brazil
State subsidy programs in Minas Gerais and São Paulo accelerate nitrogen-fixing cyanobacterial inoculant procurement for Cerrado soybean operations. ANVISA regulates microbial fertilizer registration with efficacy trial requirements that favor established domestic blenders. Piracicaba and Ribeirão Preto distribution hubs consolidate bulk biomass contracts from regional cultivation cooperatives.
India
Maharashtra and Punjab state governments subsidize biofertilizer adoption to displace synthetic urea in wheat and rice systems. CDSCO filing requirements extend development timelines for microalgae-derived nutraceutical exports to European and US markets. Chennai and Hyderabad processing clusters extract phycocyanin for domestic Ayurveda distribution and cosmetics formulators.
Microphytes Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented production tiers. Consolidation concentrates among Israeli and Japanese photobioreactor operators with proprietary strain libraries, while Chinese open-pond cultivators compete on biomass volume. Three archetypes dominate: desert-advantaged astaxanthin specialists, backward-integrated spirulina producers with captive Hawaiian sites, and bulk cyanobacterial suppliers serving agricultural subsidy channels. Capacity expansion and REACH registration dossier completion constitute the dominant competitive moves.
Within the premium-extract tier, Algatech Ltd. and Cyanotech Corporation exemplify controlled-environment production archetypes. DIC Corporation anchors the volume-integrated segment through in-house Hawaiian cultivation. Fuqing King Dnarmsa Spirulina and Dongying Haifu Biological represent Chinese open-pond biomass specialists serving cost-sensitive nutraceutical channels. Cargill Incorporated occupies a position bridging agricultural procurement networks with emerging microalgae feed ingredient sourcing.
| Leading Market Players |
|---|
| Algatech Ltd. |
| Fuqing King Dnarmsa Spirulina |
| DIC Corporation |
| Dongying Haifu Biological |
| Shengbada Biology |
| Cyanotech Corporation |
| Cargill Incorporated |
| TAAU Australia |
| Algaetech Group |
| Others |
Cost & Logistics Intelligence
Overcapacity in Chinese open-pond spirulina operations is compressing spot biomass prices while Israeli photobioreactor operators maintain premium positioning through astaxanthin purity leadership. This utilization divergence is forcing mid-tier producers toward contract-manufacturing arrangements or certification investments to escape commodity pricing traps.
Pricing Analysis
Photobioreactor-to-open-pond technology pricing gaps separate premium astaxanthin extracts from bulk chlorella powder by order-of-magnitude differentials. Pricing stratifies across REACH-registered premium tiers, organic-certified standard tiers, and uncertified economy biomass for feed applications. Cost compression in Chinese open-pond supply is intensifying because Inner Mongolia cultivation clusters are expanding faster than nutraceutical absorption. Agriculture companies in Brazil and India exhibit highest price sensitivity, while pharmaceutical omega-3 API producers accept premium positioning for DHA concentration guarantees.
Supply Chain Analysis
Contract-manufacturing concentration in Israeli Arava Valley and Spanish Almería desert facilities holds premium astaxanthin extraction capacity. Geographic supply concentrates in China, Israel, and Brazil, with Chinese Yunnan clusters feeding nutraceutical encapsulators and Israeli sites serving Norwegian salmon farms. Raw material dependencies center on carbon dioxide feedstock purity, phosphorus recovery from municipal effluent, and proprietary strain licensing. Single-source vulnerability runs through Israeli desert photobioreactor operators dependent on national water authority discharge permits. Distribution runs through direct-to-formulator channels displacing traditional ingredient distributors in South Korean and French cosmetics procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microphytes procurement is evolving toward service-attach models where strain optimization consulting and carbon credit verification generate recurring revenue streams expanding faster than commodity biomass sales. Technical advisory contracts for photobioreactor deployment and EFSA novel food navigation now command multi-year retainer structures.
For Market Incumbents: Build regulatory dossier moats by completing REACH registrations for novel extracts ahead of EFSA timeline acceleration. Incumbents should secure backward integration into Hawaiian or Israeli cultivation sites to control astaxanthin supply against Chinese volume competition. Cyanotech Corporation and DIC Corporation demonstrate how GRAS self-affirmation investments create FDA pathway barriers for emerging strain developers. For New Entrants and Emerging Players: Establish a beachhead in Indian and Brazilian biofertilizer subsidy channels where state procurement programs in Maharashtra and Minas Gerais specify nitrogen-fixing cyanobacterial inoculants. New entrants should target precision fermentation hybrid production for 24-hour metabolite cycles, bypassing capital-intensive photobioreactor construction. Direct-to-formulator liquid extract sales in South Korea offer the most penetrable premium channel. For Investors and Strategic Acquirers: Capital is best deployed toward controlled-environment photobioreactor operators with proprietary strain libraries and existing REACH registrations, as these assets compound regulatory barriers over the analysis window. Acquisition targets should demonstrate verified sequestration claims eligible for EU Carbon Border Adjustment Mechanism monetization. The signal to watch is EMA novel food approval acceleration for microalgae-derived ingredients, which would unlock European pharmaceutical channel expansion.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Registration Completion | EMA novel food pathways require full toxicological dossiers for European market access above one tonne annual volume. |
| Desert Photobioreactor Expansion | Israeli Arava Valley solar intensity advantages sustain astaxanthin purity leadership against synthetic competitors. |
| Precision Fermentation Convergence | Hybrid phototrophic-heterotrophic systems enable 24-hour production cycles for high-value metabolite extraction. |
| Direct-to-Formulator Channel Development | South Korean and French cosmetics manufacturers increasingly procure liquid extracts bypassing traditional distributors. |
| Carbon Credit Methodology Verification | ISO 14064-compliant sequestration claims create monetization pathways under EU Carbon Border Adjustment Mechanism frameworks. |
Research Approach
Desk research of EFSA novel food approval databases, EPA effluent guideline filings, and USDA organic certification registries preceded structured interviews with photobioreactor operations directors, aquafeed procurement managers at Norwegian salmon farms, Indian state agriculture department officials, and cosmetics formulators in South Korea. Secondary validation drew from customs trade data for spirulina and chlorella shipments, SEC 10-K disclosures for listed microalgae producers, and ANVISA microbial fertilizer registration records. Bottom-up cultivation capacity estimates were triangulated against top-down nutraceutical and feed demand projections.
Assumptions across the projection horizon held EU F-Gas Regulation phasedown schedules fixed while varying Chinese dual carbon goal enforcement intensity and Brazilian biofertilizer subsidy allocation. Segmentation dimensions modeled include algae type, application channel, end-user sophistication tier, and form factor. CAGRs were derived from production capacity buildout trajectories and procurement contract velocity analysis. Forecast inputs incorporated electricity price volatility scenarios for European closed photobioreactor operations and strain IP licensing fee structures.
Stress conditions across energy input costs, EFSA approval timeline extensions, and Chinese export quota fluctuations were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these bounded assumptions and acknowledge that regulatory acceleration in novel food pathways or carbon credit methodology finalization could materially revise trajectory. Quarterly review of EMA novel food approval velocity, Israeli water authority discharge permit modifications, and Indian state subsidy program renewals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
US Biofungicide Market
Bio-Agriculture
Global Citrus Bioflavonoids Market
Bio-Agriculture
Poultry Manure Biofertilizers Market
Bio-Agriculture
South America Biopesticides Market
Bio-Agriculture
India Biopesticides Market
Bio-Agriculture
North America Feed Probiotics Market
Bio-Agriculture
South America Biological Organic Fertilizers Market
Bio-Agriculture
Asia-Pacific Biopesticides Market
Bio-Agriculture
South America Biofertilizers Market
Bio-Agriculture
Biostimulants Market
Bio-Agriculture
Global Feed Phytogenics Market
Bio-Agriculture
Asia-Pacific Agricultural Biologicals Market
Bio-Agriculture
Azotobacter Based Biofertilizer Market
Bio-Agriculture
Biochar Machine Market
Bio-Agriculture
Global Bio-Organic Acid Market
Bio-Agriculture
Biological Seed Treatment Market