
 Europe Feed Probiotics Market | 2026-2036
Europe Feed Probiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Feed Probiotics Market Foresight
Poultry operations across Europe is recalibrating feed formulations toward probiotic inclusion as antibiotic growth promoter bans harden. DSM-Firmenich leverages its nutritional science platform to sustain leadership in microbial strain development. Lallemand anchors its position through yeast-based probiotic specialization for monogastric species. Chr. Hansen competes with deep culture collections targeting ruminant digestive efficiency.
Feed probiotics comprise live microbial cultures administered through animal feed to colonize the gastrointestinal tract and confer metabolic benefits. These preparations typically deliver colony-forming units measured in billions per gram, with viability thresholds dictating storage conditions and shelf stability. Lactobacillus and Bifidobacterium strains command premium positioning in poultry and swine applications where gut health directly correlates with feed conversion ratios. Powder formulations retain cost advantages across bulk compound feed channels, while liquid delivery systems gain traction in aquaculture operations requiring precise dosing integration.
The European Food Safety Authority (EFSA) evaluates novel probiotic strains through Qualified Presumption of Safety pathways, while REACH governs fermentation byproducts and residual metabolites in manufacturing. EMA guidelines on veterinary medicinal products create compliance thresholds that filter smaller strain developers from commercial supply chains. Feed compounders must monitor EFSA strain authorization timelines and national implementation variations across member states.
Market Dynamics
The EU Green Deal is compressing livestock emissions ceilings while EFSA tightens strain authorization timelines, forcing feed compounders to accelerate probiotic substitution for antibiotic growth promoters across monogastric and ruminant operations.
Growth Catalysts
- Regulatory Phase-Out Mandates:The EU's ban on antibiotic growth promoters in animal feed creates immediate substitution demand for microbial alternatives in poultry and swine diets. EFSA's Qualified Presumption of Safety pathway streamlines novel strain market entry.
- Poultry Sector Expansion:Broiler integrators in Germany and the Netherlands are expanding probiotic inclusion rates to optimize feed conversion ratios and reduce enteric disease incidence in high-density operations.
- Fermentation Scale-Up:Advances in submerged fermentation technology for Lactobacillus and Bifidobacterium strains are reducing unit production costs and improving viability stability through shelf life.
Market Restraints
- Input Cost Volatility:Specialized growth media and cryoprotectant costs fluctuate with agricultural commodity markets, squeezing margins for strain manufacturers without backward integration into fermentation inputs.
- Supply Concentration Risk:Master seed banks and primary culture collections concentrate in Denmark and France, creating single-source vulnerability for commercial strain licensing across Southern and Eastern Europe.
- Regulatory Friction:REACH compliance for fermentation metabolites and residual byproducts adds 18-24 month pre-market timelines that filter smaller developers from commercial supply chains.
Strategic Opportunities
- Eastern European Penetration:Poland and Romania's expanding compound feed capacity remains underpenetrated for premium probiotic inclusion, offering first-mover positioning before EU Green Deal enforcement tightens.
- Aquaculture Application Expansion:Liquid delivery systems for salmon and trout operations in Norway and Scotland enable precise dosing integration that dry formulations cannot match in recirculating systems.
- F-Gas Regulation Tailwind:The EU F-Gas Regulation's cooling requirements are accelerating cold-chain infrastructure investment that simultaneously supports probiotic viability preservation through distribution.
Industry Challenges
- Strain Characterization Expertise Gap:Commercial feed compounders lack in-house microbiology capacity to evaluate CFU claims and viability thresholds, creating dependency on third-party verification.
- Multi-Strain Compatibility Complexity:Formulating stable multi-species preparations requires solving antagonistic interactions between Lactobacillus, Bifidobacterium, and Bacillus strains during storage and gastric transit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Feed Probiotics Market |
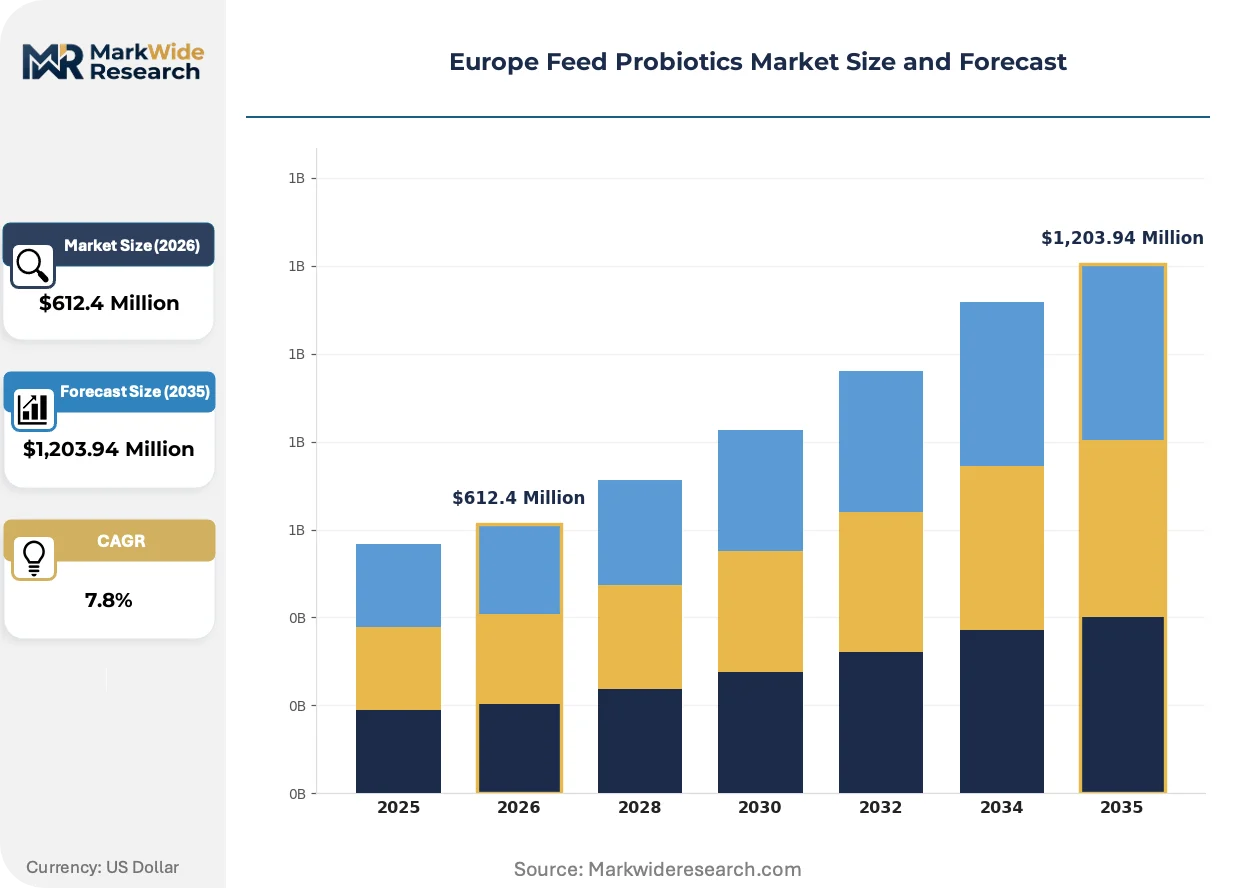
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,203.94 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yeast, Lactobacillus, Bifidobacterium, Streptococcus Livestock Type: Poultry, Swine, Ruminants, Aquaculture Formulation: Pellets, Powder, Liquid, Granules Distribution Channel: Online, Retail, Direct Sales, Wholesalers |
| Companies Covered | Evonik Industries, DSM-Firmenich, Cargill, Lallemand, Novonesis, Adisseo, Chr. Hansen, Lesaffre & Cie, DuPont de Nemours, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Feed Probiotics Market Shifts & Advancements
Next-generation sequencing and metabolomics are rewriting how strain developers screen for colonization efficiency and metabolic output, compressing development cycles while EFSA demands deeper safety dossiers.
Encapsulation technologies using alginate and lipid matrices are rewriting viability protection standards for feed probiotics, enabling pelleting temperature tolerance above 85°C that previously destroyed unprotected cultures. DSM-Firmenich and Lallemand are integrating these systems into broiler and layer formulations across Benelux operations. The structural consequence is extending probiotic applicability into steam-pelleted feeds that dominate European compound feed manufacturing, collapsing the historical powder-versus-liquid formulation divide.
The EU Green Deal's Farm to Fork Strategy is rewriting nitrogen and phosphorus emission accounting for livestock operations, embedding feed additives into compliance strategies. Member states are implementing national reduction targets that elevate probiotics from performance enhancers to emission management tools. Ruminant operations in France and Ireland face the steepest methane reduction mandates, driving demand for yeast-based direct-fed microbials that modulate rumen fermentation patterns.
Compound feed procurement is consolidating around integrated poultry and pork operations with in-house nutrition teams capable of running probiotic challenge trials. This buyer capability concentration is displacing traditional distributor-led technical sales in Germany and the Netherlands, where De Heus and ForFarmers now specify strain-level performance data in supplier qualification. The shift is most visible in Dutch broiler operations where feed conversion ratio guarantees have become standard contract terms.
Europe Feed Probiotics Market Segmentation
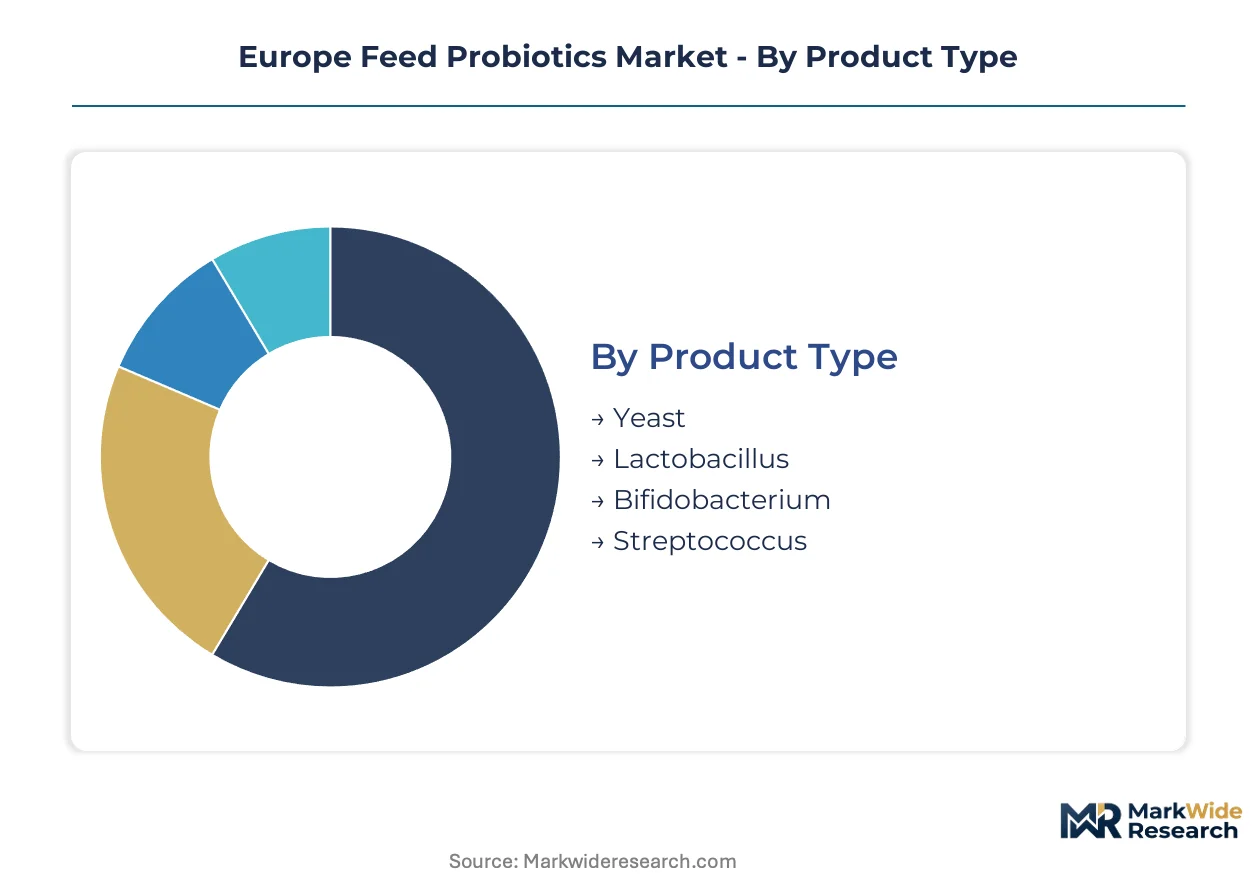
Feed probiotic segmentation in Europe reflects divergent supply capabilities across strain types and delivery formats. Compound feed manufacturers select segments based on EFSA authorization status, pelleting temperature tolerance, and integration complexity with existing feed mill infrastructure.
Product Type:
Strain manufacturing concentrates in Denmark and France where master culture collections and submerged fermentation expertise cluster, creating tiered supply reliability across microbial categories.
- Lactobacillus:These Gram-positive bacteria dominate poultry and swine formulations through lactic acid production that suppresses pathogenic colonization. German broiler integrators specify Lactobacillus-based preparations in feed conversion ratio guarantee contracts, though cryoprotectant costs pressure margin structures for non-integrated suppliers.
- Yeast:Saccharomyces cerevisiae and related strains command ruminant applications where rumen fermentation modulation delivers methane reduction compliance under EU Green Deal nitrogen accounting. French and Irish dairy operations drive procurement volume as national emission ceilings tighten.
- Bifidobacterium:Anaerobic cultivation requirements limit viable suppliers to firms with specialized bioreactor capabilities.
- Streptococcus:Enterococcus faecium strains hold narrower EFSA approvals targeting specific enteric disease suppression in weaning piglets.
Today's leader: Yeast. Tomorrow's challenger: Lactobacillus.
Livestock Type:
End-use demand splits across species based on regulatory pressure intensity and production system scale, with poultry and ruminants absorbing distinct probiotic functionalities.
- Poultry:Broiler and layer operations in the Netherlands and Germany deploy probiotics as antibiotic growth promoter substitutes in high-density housing systems. Feed conversion ratio optimization contracts now embed strain-specific performance clauses that filter generic suppliers from qualified vendor lists.
- Ruminants:Cattle and sheep producers in France and Ireland face the steepest methane reduction mandates under national Farm to Fork implementations. Yeast-based direct-fed microbials that alter rumen volatile fatty acid ratios are climbing the fastest as compliance tools rather than optional performance enhancers.
- Swine:Post-weaning diarrhea management drives inclusion in Danish and Spanish farrow-to-finish operations.
- Aquaculture:Salmon and trout farmers in Norway and Scotland require liquid delivery systems compatible with recirculating aquaculture system dosing infrastructure.
Poultry commands current procurement volume. Ruminants present the steepest expansion trajectory through emission compliance linkages.
Formulation:
Manufacturing process compatibility and viability preservation requirements create sharp trade-offs between feed mill integration ease and culture survival rates through pelleting and distribution.
- Powder:Spray-dried preparations retain cost advantages across bulk compound feed channels in Germany and Poland, though unprotected cultures face viability thresholds above 65°C pelleting temperatures that limit application in steam-conditioned feeds.
- Pellets:Alginate and lipid matrix encapsulation enables pelleting temperature tolerance exceeding 85°C, extending probiotic applicability into steam-pelleted feeds that dominate Benelux compound feed manufacturing.
- Liquid:Precision dosing integration in Norwegian salmon recirculating systems commands premium positioning.
- Granules:Intermediate particle sizing targets specialty feed blenders serving smaller Polish and Romanian operations.
Powder formulations defend installed base. Encapsulated pellets are gaining share fastest through temperature tolerance breakthroughs.
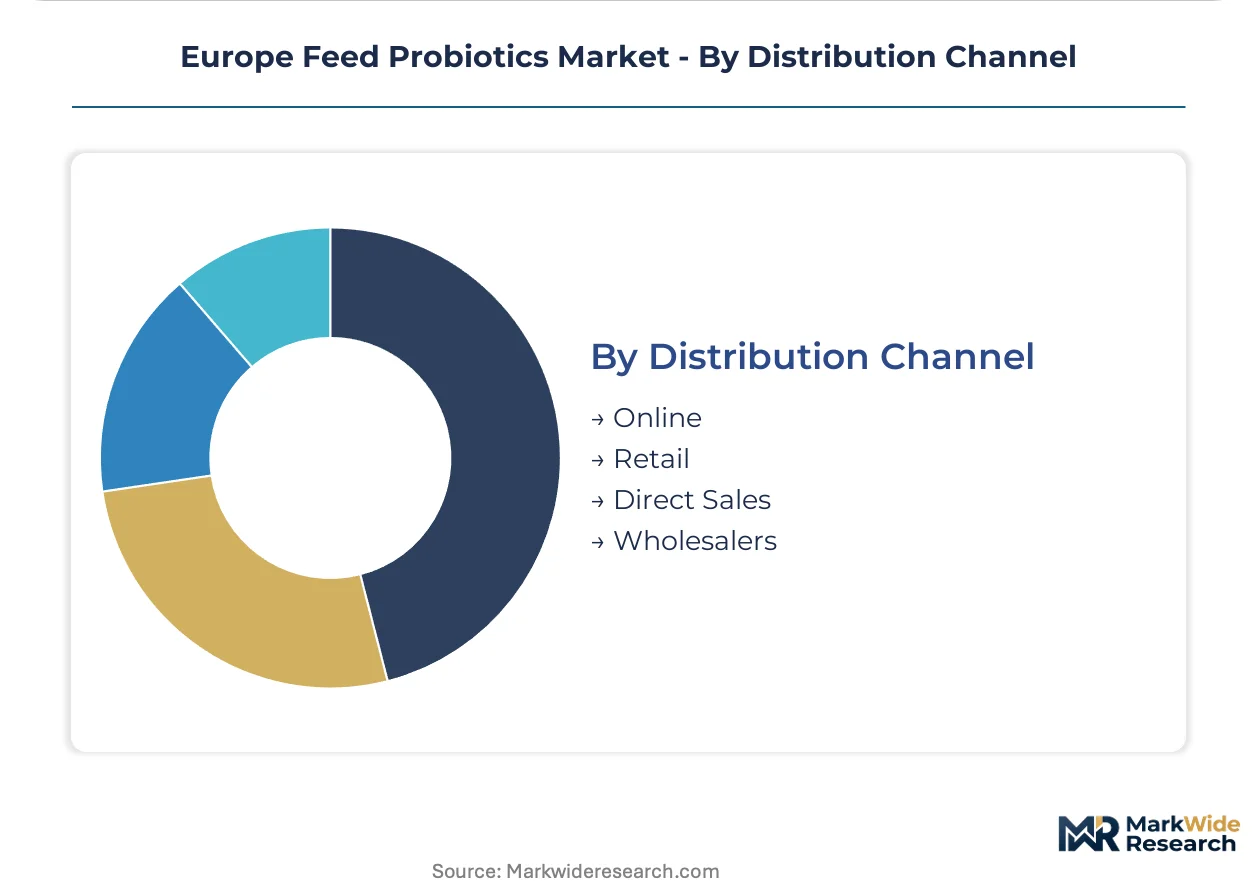
Distribution Channel:
Buyer capability concentration among integrated poultry and pork operations is restructuring channel economics, displacing traditional distributor technical sales with direct specification relationships.
- Direct Sales:De Heus and ForFarmers in the Netherlands negotiate strain-level performance data and feed conversion ratio guarantees directly with DSM-Firmenich and Lallemand, bypassing distributor margins and embedding technical service into procurement contracts.
- Wholesalers:Regional feed ingredient distributors in Poland and Romania retain relevance where smaller compound feed operations lack in-house microbiology capacity to evaluate CFU claims and viability thresholds independently.
- Retail:Farm supply cooperatives serve fragmented beef and sheep producers in Ireland and Scotland.
- Online:Digital procurement platforms capture spot purchases from specialty livestock operators seeking trial quantities.
Direct sales anchor premium segment value capture. Wholesalers retain defensive positioning in Eastern European expansion markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Netherlands' feed manufacturing corridor around Veghel and Boxmeer anchors European probiotic demand through De Heus and ForFarmers compound feed operations. National emission ceilings under the EU Green Deal Farm to Fork Strategy compress procurement timelines for microbial feed additives.
Germany
Broiler integrators in Lower Saxony and North Rhine-Westphalia specify Lactobacillus-based preparations in feed conversion ratio guarantee contracts. The F-Gas Regulation accelerates cold-chain infrastructure investment that preserves probiotic viability through distribution. DSM-Firmenich maintains strain development operations near Kaiseraugst, Switzerland, serving German compound feed manufacturers.
France
Dairy and beef operations in Brittany and Normandy face steep methane reduction mandates under national Farm to Fork implementations. EFSA's Qualified Presumption of Safety pathway streamlines novel strain authorization for ruminant applications. Lallemand anchors yeast-based probiotic production through Lesaffre & Cie fermentation facilities serving French livestock cooperatives.
Netherlands
Poultry operations in Gelderland and Overijssel deploy probiotics as antibiotic growth promoter substitutes in high-density housing systems. REACH compliance requirements for fermentation metabolites filter smaller strain developers from commercial supply chains. ForFarmers and De Heus negotiate strain-level performance data directly with suppliers, bypassing traditional distributor channels.
Poland
Expanding compound feed capacity in Greater Poland and Silesia remains underpenetrated for premium probiotic inclusion. National implementation variations of EFSA strain authorizations create compliance timing gaps across member states. Regional feed ingredient distributors retain relevance where smaller operations lack in-house microbiology capacity to evaluate CFU claims independently.
Norway
Salmon and trout farmers in Vestland and Trøndelag require liquid delivery systems compatible with recirculating aquaculture system dosing infrastructure. The EU Green Deal's nitrogen accounting extends to imported feed additives through EEA alignment. Norwegian aquafeed producers specify precision dosing integration that dry formulations cannot match in closed-water systems.
Europe Feed Probiotics Market Competitive Landscape
Strategic partnerships dominate the current landscape as fermentation specialists align with compound feed distributors to secure strain authorization pathways. The vendor base concentrates around three tiers: integrated nutrition platforms with culture collection ownership, specialized yeast and bacteria manufacturers with submerged fermentation expertise, and regional distributors lacking backward integration into primary strain development. Two archetypes define positioning: science-led strain developers competing on EFSA authorization speed and scale-driven fermentation houses competing on unit cost. M&A activity and technology licensing agreements represent the dominant competitive moves as mid-cap players seek access to master seed banks.
Within the integrated nutrition tier, DSM-Firmenich and Novonesis occupy positions anchored by deep culture collections and regulatory affairs capabilities spanning EFSA and national implementation frameworks. Lallemand exemplifies the specialized fermentation archetype through yeast-based probiotic concentration for monogastric and ruminant applications. Among distributor-dependent regional suppliers, Adisseo represents the scale-driven model competing on feed additive portfolio breadth rather than strain-level proprietary development. Chr. Hansen sits within the science-led tier, leveraging anaerobic cultivation expertise for Bifidobacterium and Lactobacillus applications where bioreactor capabilities limit viable competition.
| Leading Market Players |
|---|
| Evonik Industries |
| DSM-Firmenich |
| Cargill |
| Lallemand |
| Novonesis |
| Adisseo |
| Chr. Hansen |
| Lesaffre & Cie |
| DuPont de Nemours |
| Others |
Supply & Pricing Matrix
Specialized growth media and cryoprotectant costs trace a volatile path from agricultural commodity markets through tiered pricing structures, compressing margins for non-integrated strain manufacturers while rewarding Danish and French fermentation houses with captive supply chains.
Pricing Analysis
Distributor margins in Poland and Romania absorb 15-25 point spreads between master seed bank licensors and compound feed compounders, though direct sales channels in the Netherlands bypass these layers entirely. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-authorized strains with full QPS dossiers from provisional approvals and generic formulations. Pricing pressure stems from REACH compliance timelines that filter smaller developers, intensifying competition among surviving suppliers. Integrated poultry operations with in-house nutrition teams exhibit lowest price sensitivity, while Eastern European distributors serving fragmented feed mills face relentless cost compression.
Supply Chain Analysis
Reverse-logistics flows for temperature-compromised probiotic shipments concentrate remediation costs on cold-chain operators in Germany and the Netherlands, where F-Gas Regulation cooling infrastructure investments simultaneously protect viability. Master seed banks in Denmark and France anchor primary culture collections, with submerged fermentation capacity drawing from specialized growth media suppliers in Belgium and the Netherlands. Single-source vulnerability concentrates in Paris and Copenhagen culture repositories, exposing Southern and Eastern European compounders to licensing disruption. Distribution runs through integrated nutrition platforms for premium tiers, while regional wholesalers retain defensive positioning in Polish and Romanian expansion markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where EFSA authorization speed and strain-specific performance data now separate qualified suppliers from commodity competitors, as Dutch broiler integrators embed feed conversion ratio guarantees into standard procurement terms.
For Market Incumbents: Deploy master seed bank control as the priority defensive lever. DSM-Firmenich and Novonesis should accelerate EFSA QPS pathway submissions ahead of national Farm to Fork implementations, locking out mid-tier competitors lacking regulatory affairs depth. Backward integration into cryoprotectant supply buffers margin compression from agricultural commodity volatility, while direct technical service contracts with ForFarmers and De Heus displace distributor-dependent challengers from qualified vendor lists. For New Entrants and Emerging Players: Premium-economy tier gaps in Polish and Romanian compound feed markets offer viable white-space entry before EU Green Deal enforcement tightens. Target aquaculture liquid delivery systems in Norway where precision dosing requirements filter established powder-formulation incumbents. Partner with regional wholesalers possessing microbiology evaluation capacity to overcome buyer skepticism toward unproven CFU claims. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance costs and EFSA authorization timelines exceed standalone R&D budgets for sub-scale strain developers. Mid-cap fermentation specialists with anaerobic bioreactor capabilities but limited culture collection depth represent prime acquisition targets. Monitor EFSA strain authorization announcement velocity as the inflection signal distinguishing science-led platforms from scale-driven commodity suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA QPS Pathway Acceleration | Speeds market entry for novel Lactobacillus and Bifidobacterium strains ahead of competitor dossiers. |
| Encapsulation Technology Licensing | Extends probiotic applicability into steam-pelleted feeds dominating Benelux compound manufacturing. |
| Cold-Chain Infrastructure Partnership | Aligns with F-Gas Regulation cooling investments to preserve viability through distribution. |
| Direct Technical Service Contracts | Bypasses distributor margins while embedding strain-level performance guarantees with Dutch integrators. |
| Backward Integration into Fermentation Inputs | Captures cryoprotectant supply to buffer margin pressure from agricultural commodity volatility. |
Research Methodology
Bottom-up livestock operation modeling reconciled against top-down fermentation capacity tracking forms the analytical core of this study. Primary interviews with strain development scientists, regulatory affairs directors at EFSA-authorized suppliers, compound feed procurement managers at De Heus and ForFarmers, and veterinary microbiologists at Dutch broiler integrators combined with secondary validation from EFSA QPS registry filings, REACH compliance databases, EU Green Deal national implementation documents, and Lesaffre fermentation capacity disclosures. Top-down and bottom-up estimates triangulated through cross-referencing EFSA authorization timelines against disclosed production capacity expansions.
Input-output matrices mapped strain-level supply capabilities against species-specific demand segments across the projection horizon. Segmentation dimensions modeled include microbial category, livestock species, formulation type, and distribution channel complexity. CAGRs derived from exponential smoothing of disclosed capacity additions against Farm to Fork emission ceiling trajectories. Industry-specific forecast inputs incorporated EFSA strain authorization velocity and national implementation lag variations across member states.
Caveats apply where EFSA regulatory delays or REACH compliance timeline extensions could materially shift the outlook for novel strain commercialization. Forecasts reflect assumptions regarding continued antibiotic growth promoter prohibition enforcement and EU Green Deal methane reduction mandate adherence. Practitioners should monitor EFSA QPS pathway announcement frequency and Polish compound feed capacity utilization rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Brazil Biofertilizers Market
Bio-Agriculture
India Biopesticides Market
Bio-Agriculture
Global Bio-Organic Acid Market
Bio-Agriculture
Latin America Biopesticide Market
Bio-Agriculture
Global Biofungicides Market
Bio-Agriculture
Hydroponics Market
Bio-Agriculture
India Biocontrol Agents Market
Bio-Agriculture
Azotobacter Based Biofertilizer Market
Bio-Agriculture
GCC Biofertilizer Market
Bio-Agriculture
West Africa Biostimulants Market
Bio-Agriculture
China Feed Probiotics Market
Bio-Agriculture
Global Citrus Bioflavonoids Market
Bio-Agriculture
Global Feed Phytogenics Market
Bio-Agriculture
France Biopesticides Market
Bio-Agriculture
Bio Rational Fungicides Market
Bio-Agriculture
Fish Vaccines Market