
 Polyurethane (PU) Coatings Market | 2026-2036
Polyurethane (PU) Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Polyurethane (PU) Coatings Market Analytics
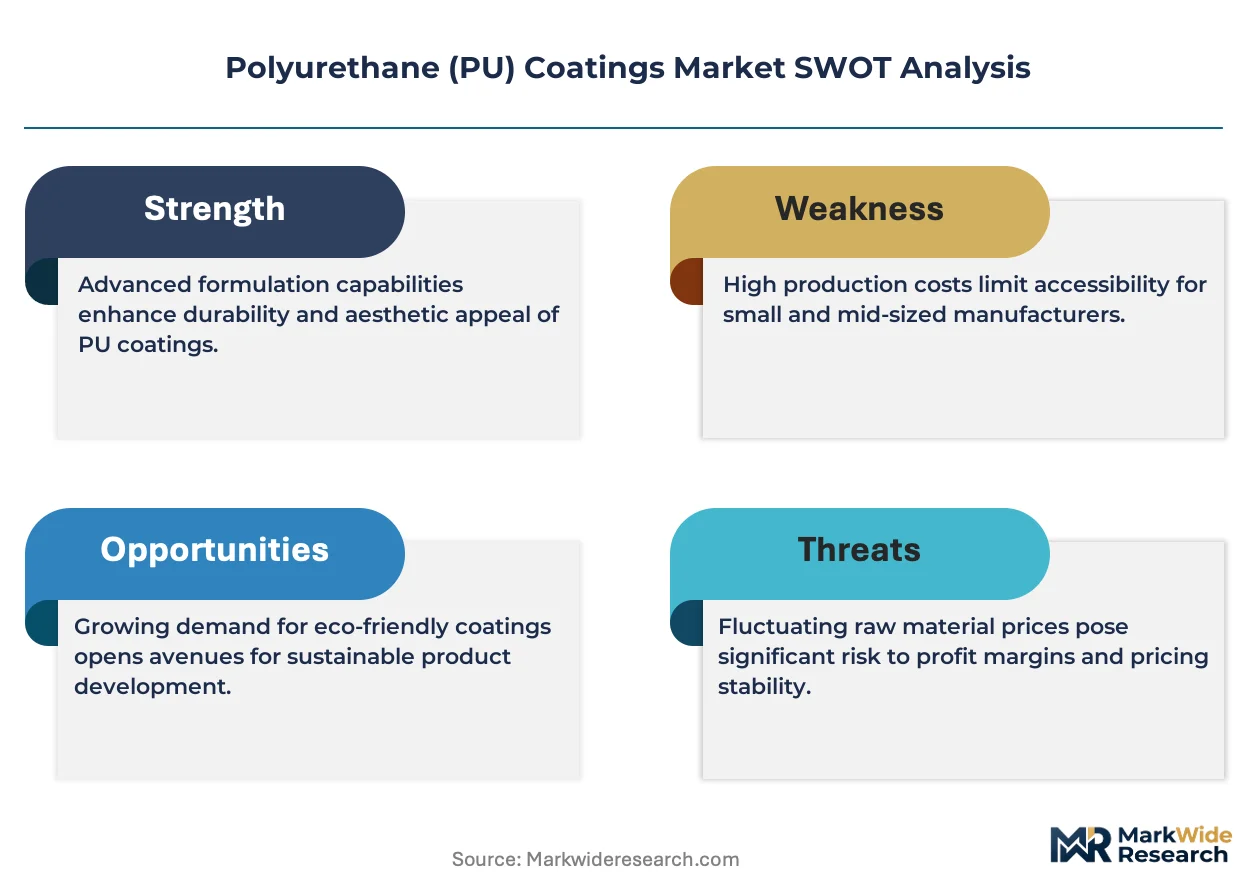
Multi-source resin procurement is recalibrating how formulators manage isocyanate and polyol supply security. Akzo Nobel N.V. leverages integrated marine coatings laboratories in the Netherlands to control specification-grade waterborne development. PPG Industries, Inc. anchors North American automotive refinish channels through certified distributor networks. BASF SE sustains backward integration into aliphatic isocyanates, insulating margin pools from raw material cyclicality.
Polyurethane coatings are thermosetting polymer films formed by the reaction of polyols with polyisocyanates, typically cured at ambient or elevated temperatures to achieve hardness ratings of 2H to 6H pencil scale. They serve primarily as protective and decorative barriers against abrasion, chemical attack, and UV degradation in industrial and transportation environments. Waterborne formulations now lead product type evolution as VOC thresholds tighten across jurisdictions, while solventborne systems retain share in heavy-equipment and marine applications where film build and corrosion resistance dominate specification sheets. Flooring application growth tracks commercial construction velocity in high-traffic environments requiring rapid-return-to-service cure profiles.
EPA VOC limits under 40 CFR Part 59, REACH Annex XVII restrictions on isocyanate monomer content, and China's GB standards on hazardous substance limits in coatings collectively redirect formulation investment toward low-emission technologies. The EU Green Deal's industrial emissions framework accelerates capital allocation to waterborne and high-solids production lines. Stakeholders must monitor regulatory divergence between jurisdictions where harmonized standards lower compliance costs versus fragmented rules that fragment product portfolios and testing budgets.
Market Dynamics
Waterborne PU formulation chemistry is restructuring competitive advantage as VOC compliance deadlines compress R&D cycles and force capital redeployment from solventborne assets. Formulators with captive polyol synthesis and isocyanate stabilization expertise capture specification control in automotive OEM and marine protective segments.
Growth Catalysts
- EPA 40 CFR Part 59 Subpart D:The automotive refinish sector accelerates waterborne PU conversion to meet federal VOC limits, triggering coating line retrofits across US collision repair networks.
- Shipbuilding clusters in South Korea and China:Newbuild vessel orders for LNG carriers and container ships drive specification-grade marine PU demand for ballast tank and deck coating systems.
- Aliphatic isocyanate hardener technology:UV-stable crosslinking chemistry expands PU use in exterior architectural coatings where gloss retention and color stability command premium positioning.
Market Restraints
- MDI and TDI feedstock volatility:Benzene and toluene derivative pricing swings compress formulation margin pools, particularly for small-batch custom coaters lacking long-term supply contracts.
- Isocyanate monomer supply concentration:Asian producers control bulk polymeric MDI output, exposing European and North American formulators to freight cost spikes and allocation risk during plant turnarounds.
- Cure temperature limitations:Ambient-cure waterborne systems require extended drying windows versus solventborne equivalents, restricting deployment in high-throughput OEM lines with takt-time constraints.
Strategic Opportunities
- India industrial corridor expansion:The PLI scheme for domestic manufacturing and infrastructure buildout creates first-mover positioning for protective PU systems in automotive and electronics assembly plants.
- EU Green Deal industrial emissions framework:Capital subsidies for low-emission coating production incentivize greenfield waterborne capacity with integrated solvent recovery.
- UV-LED hybrid curing convergence:Combination of waterborne PU basecoats with energy-curable topcoats enables single-pass processing in furniture and flooring applications.
Industry Challenges
- Formulation chemist shortage:Expertise in isocyanate handling, hydrolysis stabilization, and VOC-compliant rheology control resides with aging technical workforces in Germany and Japan.
- REACH Annex XVII certification timelines:Extended safety dossier preparation for novel polyol structures delays product launches by 18-24 months versus historical development cycles.
- Legacy solventborne line stranded assets:Coaters with recent investments in high-bake enamel systems face write-down pressure as customer specifications pivot to waterborne.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyurethane (PU) Coatings Market |
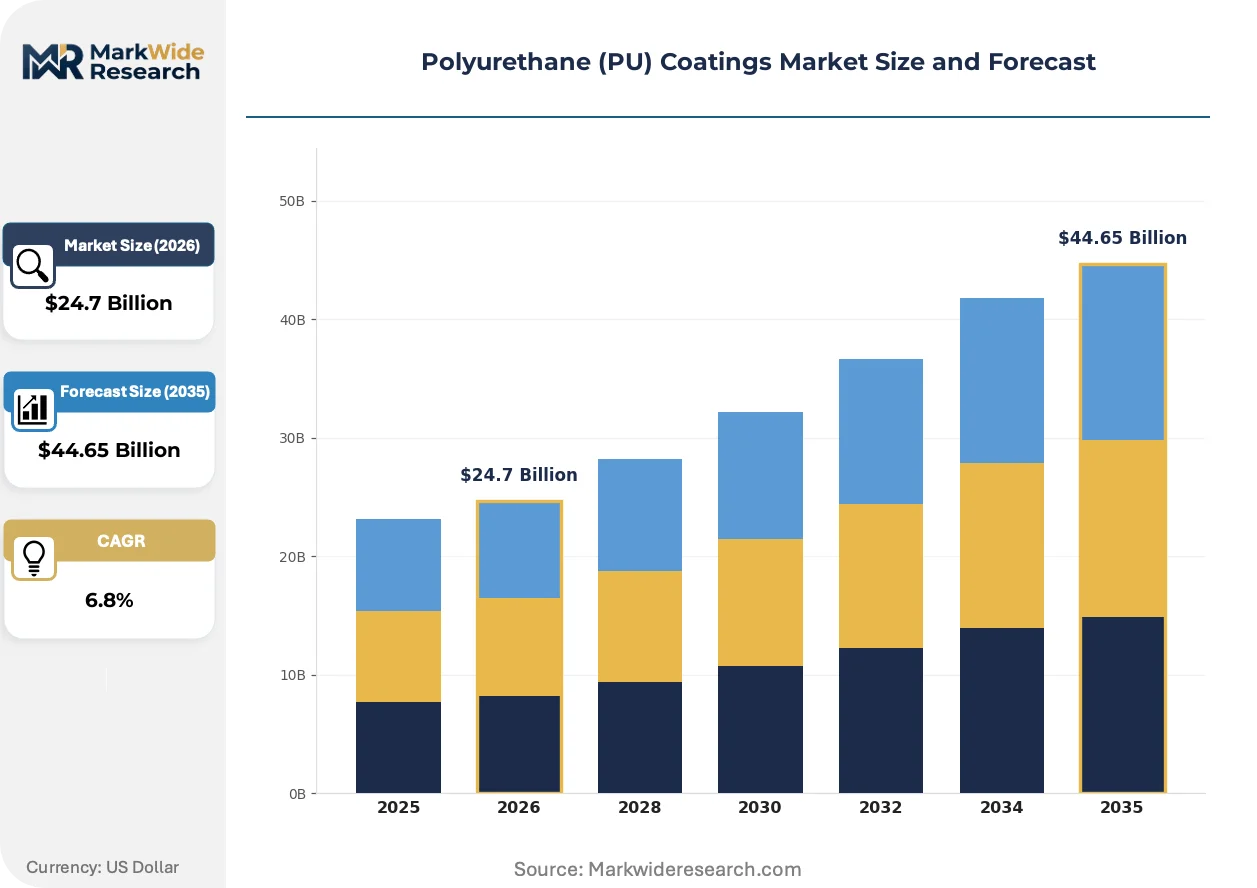
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $44.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Waterborne, Solventborne, High Solids, 2K Application: Automotive, Construction, Packaging, Flooring End User: Manufacturers, Contractors, Distributors, Retailers Technology: Spray Coating, Roll Coating, Brush Coating, Electrostatic |
| Companies Covered | Akzo Nobel N.V., The Sherwin-Williams Company, PPG Industries, Inc., Axalta Coating Systems, BASF SE, Jotun, RPM International Inc., Asian Paints Ltd., Kansai Paint Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyurethane (PU) Coatings Market Evolving Landscape
Formulation architecture is fragmenting into application-specific modules as end-users demand performance customization without inventory complexity. This shift rewards chemists who can recombine building blocks across automotive, marine, and industrial protective segments.
Polyaspartic aliphatic polyol technology is modularizing protective coating system design by enabling variable pot-life extension and accelerated cure profiles from a common resin platform. Heavy-equipment manufacturers in the US Midwest adopt these systems for field touch-up applications where return-to-service speed determines contract awards. The technology compresses SKU proliferation while allowing performance tiering through hardener selection rather than base resin variation.
REACH restrictions on isocyanate monomer content in consumer and professional-use products are forcing reformulation of two-component PU systems toward blocked or prepolymer architectures. Industrial maintenance contractors face retraining costs and application protocol revisions as legacy spray equipment becomes incompatible with higher-viscosity alternatives. Marine and protective segments in Northwestern Europe absorb the steepest compliance costs due to workforce exposure limits and environmental release permitting.
Specification-driven procurement now dominates large-account buying as facility owners consolidate coating decisions at corporate engineering level rather than site maintenance discretion. Distributor technical service capabilities determine vendor selection in North American automotive refinish channels where color-matching accuracy and inventory availability outweigh price competition. The shift concentrates volume with formulators maintaining direct specification relationships and certified applicator networks.
Polyurethane (PU) Coatings Market Segmentation
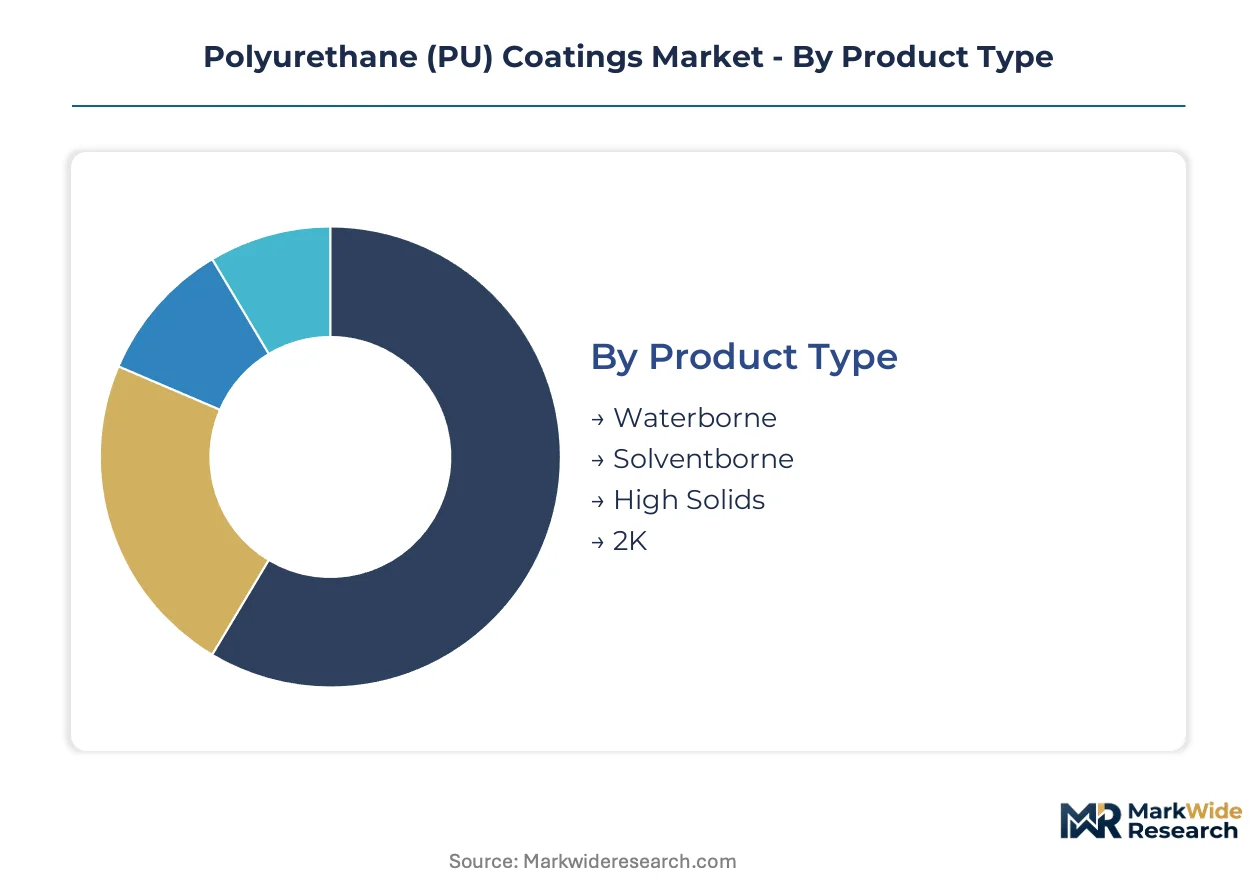
Polyurethane coatings segmentation reveals how formulation chemistry, application method, and procurement channel intersect with regulatory compliance burdens. Understanding these divisions exposes where specification control concentrates and margin pools shift across the value chain.
Product Type:
Certification requirements diverge sharply across product categories, with waterborne systems facing EPA 40 CFR Part 59 testing protocols while solventborne formulations navigate REACH Annex XVII isocyanate monomer restrictions.
- Waterborne:Polyol-isocyanate dispersions in aqueous carrier systems achieve VOC levels below regulatory thresholds without sacrificing film hardness. Demand concentrates in US automotive refinish networks where EPA Subpart D compliance deadlines force coating line conversions. The technology commands specification control in Germany and China OEM operations where MEE rules parallel European emission frameworks.
- Solventborne:Traditional organic solvent carriers deliver superior film build and corrosion resistance in single-coat applications. Shipbuilding clusters in South Korea and China specify these systems for ballast tank protection where waterborne alternatives fail immersion testing protocols. Regulatory pressure is concentrating volume in heavy-equipment and marine segments exempt from the strictest VOC limits.
- High Solids:Reduced solvent content formulations bridge compliance and performance requirements for industrial maintenance contractors.
- 2K:Two-component systems with separated resin and hardener components enable customized cure profiles for specialty OEM applications.
Waterborne sits at the top of the volume ranking, with high solids climbing the fastest as formulators seek intermediate compliance pathways.
Application:
End-use sectors separate by durability specification intensity, with automotive and marine applications demanding certified applicator networks while construction tolerates broader distribution channels.
- Automotive:OEM refinishing lines and collision repair networks require color-matching precision and rapid cure compatibility with takt-time constraints. German and Chinese manufacturing corridors drive specification-grade demand as domestic production expands. The segment rewards formulators with integrated laboratory capabilities and certified distributor technical service.
- Construction:Architectural metal and concrete protection applications span commercial infrastructure and residential building envelopes. Demand concentrates in India's industrial corridor expansion where PLI-scheme manufacturing buildout creates first-mover positioning for protective systems. Weathering resistance specifications vary by sub-regional climate exposure.
- Packaging:Food-contact and industrial container coatings require migration testing and FDA or EFSA compliance for direct substrate contact.
- Flooring:Commercial high-traffic environments specify rapid-return-to-service cure profiles in healthcare, retail, and logistics facilities.
Automotive generates the largest revenue concentration, with construction expanding most quickly on infrastructure investment cycles.
End User:
Procurement authority shifts upstream as facility owners consolidate coating decisions, fragmenting volume across direct specification relationships and distributor inventory commitments.
- Manufacturers:Industrial OEMs and fabricators specify coatings at the engineering design stage, locking in volume through qualified product lists. Automotive and heavy-equipment producers in the US Midwest and Germany maintain captive formulation partnerships. The segment demands batch consistency documentation and supply security guarantees.
- Contractors:Application specialists in marine maintenance and industrial protective segments control specification influence through field performance validation. European contractors face retraining costs as REACH restrictions force spray equipment modifications for higher-viscosity blocked isocyanate systems.
- Distributors:Channel intermediaries concentrate inventory risk and technical service delivery in fragmented regional markets.
- Retailers:Consumer and professional DIY segments absorb compliance cost pass-through with limited specification leverage.
Manufacturers command the steepest pricing premiums, with contractors gaining specification influence fastest in protective maintenance segments.
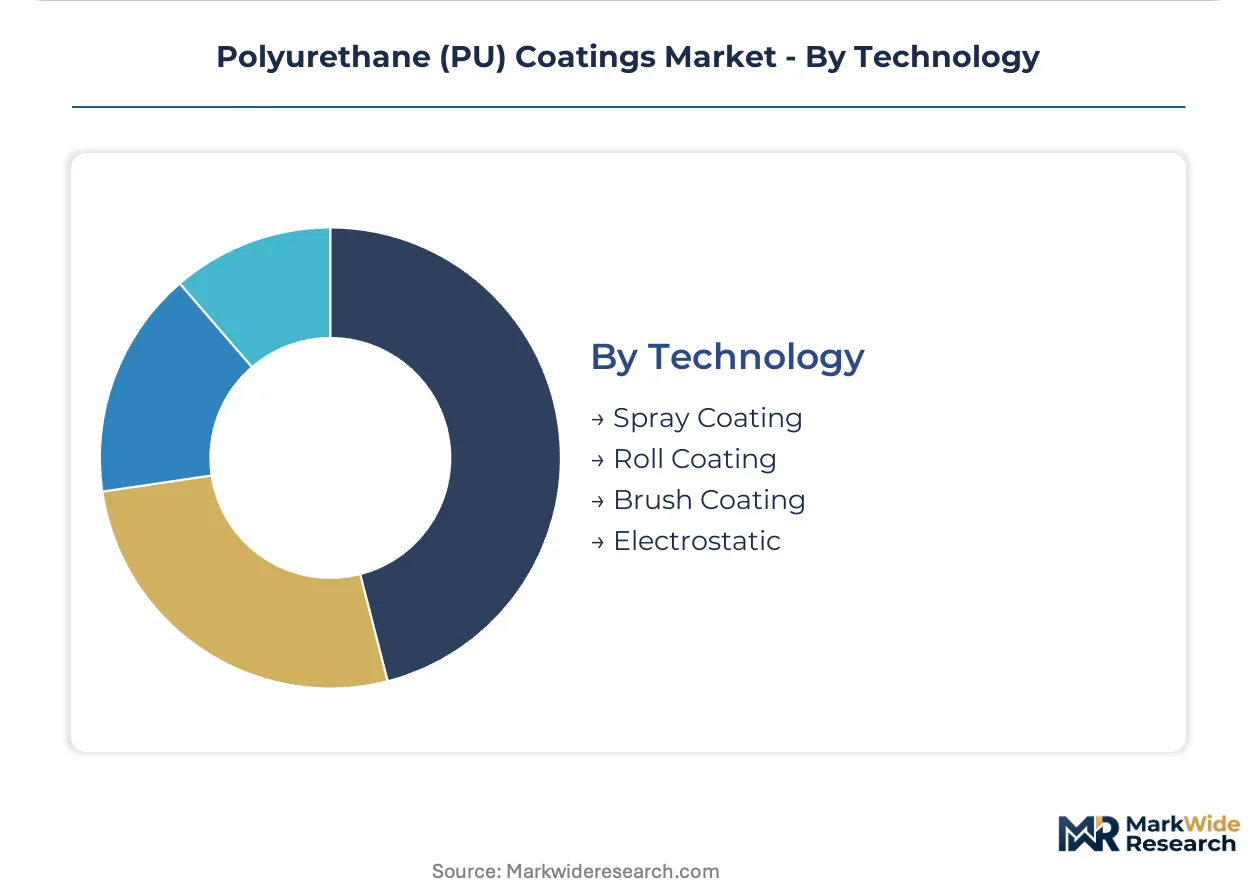
Technology:
Application method selection tracks substrate geometry, production volume, and labor cost structures across manufacturing environments.
- Spray Coating:Airless and conventional spray systems dominate automotive refinish and industrial maintenance where complex geometries prevent roller or brush access. US collision repair networks and European marine yards standardize on HVLP equipment for transfer efficiency compliance. The technology faces workforce exposure scrutiny under REACH Annex XVII isocyanate handling protocols.
- Roll Coating:Continuous web applications in flooring and packaging substrates achieve uniform film thickness at production line speeds. Manufacturing corridors in East Asia deploy these systems for electronics assembly plant flooring where rapid cure enables minimal downtime installation.
- Brush Coating:Field touch-up and small-batch maintenance applications retain manual application flexibility.
- Electrostatic:Charged particle deposition maximizes transfer efficiency on conductive metal substrates in OEM operations.
Spray coating holds the widest installed base, with electrostatic gaining adoption fastest on efficiency and waste reduction metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian manufacturing corridors concentrate the heaviest specification-grade demand, with automotive OEM refinishing lines and shipbuilding clusters driving waterborne PU conversion timelines. Regulatory divergence between EPA, REACH, and MEE frameworks fragments product portfolios and testing budgets across export-dependent formulators.
China
MEE rules on hazardous substance limits in coatings are tightening solventborne PU boundaries in automotive refinishing corridors. The Yangtze River Delta and Pearl River Delta manufacturing belts absorb the steepest compliance costs as GB standards align with European emission frameworks. Shanghai and Guangzhou host the densest concentrations of certified waterborne production lines serving domestic OEM expansion.
Germany
EU Green Deal industrial emissions subsidies accelerate capital redeployment from solventborne assets to waterborne and high-solids capacity. Bavaria and Baden-Württemberg anchor automotive OEM specification control through captive formulation partnerships with integrated laboratory networks. The KBA maintains certification protocols that German coaters leverage as competitive moats in export markets.
United States
EPA 40 CFR Part 59 Subpart D compliance deadlines force coating line retrofits across collision repair networks concentrated in the Midwest and Southeast. Michigan and Ohio industrial corridors demand batch consistency documentation from formulators serving heavy-equipment manufacturers. OSHA workplace exposure protocols compound REACH-equivalent compliance burdens for isocyanate handling.
South Korea
Newbuild LNG carrier and container ship orders at Ulsan and Geoje shipyards drive specification-grade marine PU demand for ballast tank systems. The Busan-Ulsan manufacturing cluster maintains the tightest procurement integration between domestic steel producers and protective coating formulators. MFDS chemical substance registration timelines delay novel polyol introductions versus European equivalents.
India
PLI scheme manufacturing incentives and infrastructure buildout create first-mover positioning for protective PU systems in automotive and electronics assembly plants. Maharashtra and Gujarat industrial corridors concentrate demand from domestic OEM capacity expansion and commercial construction velocity. BIS certification requirements for imported coating raw materials extend supply security planning horizons for formulators.
Polyurethane (PU) Coatings Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue waterborne technology licensing and regional distributor partnerships as entry vectors. The vendor base stratifies across integrated resin manufacturers, formulation specialists with captive applicator networks, and regional distributors consolidating technical service capabilities. Three archetypes dominate: backward-integrated chemical conglomerates controlling isocyanate supply; specification-grade formulators with OEM laboratory partnerships; and channel-focused distributors capturing collision repair volume through inventory availability. Competitive moves concentrate on M&A for regional laboratory assets and greenfield waterborne capacity with integrated solvent recovery.
Within the integrated chemical tier, Akzo Nobel N.V. and BASF SE exemplify archetypes combining captive resin synthesis with specification control in marine and automotive segments. PPG Industries, Inc. occupies a position representing channel-anchored distribution strength in North American automotive refinish networks. These three entities demonstrate how geographic origin and corporate structure map to competitive positioning: Dutch and German conglomerates with SE/AG suffixes leverage backward integration, while US-based Inc. structures emphasize distributor certification density.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| The Sherwin-Williams Company |
| PPG Industries, Inc. |
| Axalta Coating Systems |
| BASF SE |
| Jotun |
| RPM International Inc. |
| Asian Paints Ltd. |
| Kansai Paint Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap German formulators anchor supply discipline through generational capital structures that resist short-term margin compression. Their ownership models sustain pricing power against volatile MDI and TDI feedstock cycles while channeling reinvestment into captive polyol synthesis capabilities. This financing pattern insulates specification-grade waterborne production from quarterly earnings pressure that erodes R&D continuity at publicly traded rivals.
Pricing Analysis
Input-cost pass-through from benzene and toluene derivatives operates on quarterly lag contracts for small-batch custom coaters lacking long-term supply security. Pricing stratifies across specification-grade, certified-standard, and commodity-economy tiers based on VOC compliance certification and applicator network density. Pricing pressure stems from Asian polymeric MDI producers absorbing freight spikes during plant turnarounds. Small collision repair networks in the US Midwest exhibit highest price sensitivity, while German OEM captive partnerships show least elasticity due to qualified product list lock-in.
Supply Chain Analysis
Certification gating through EPA 40 CFR Part 59 and REACH Annex XVII restricts raw material sourcing to pre-qualified isocyanate and polyol suppliers with documented safety dossiers. Supply concentrates in China, Germany, and South Korea, where integrated chemical conglomerates control aliphatic isocyanate hardener technology. The chain draws from benzene derivatives, specialty polyols, and UV stabilizer additives. Single-source vulnerability around Asian polymeric MDI output exposes European formulators to allocation risk. Distribution runs through certified technical service distributors in North American automotive refinish channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as automotive OEM refinishing specifications pivot toward waterborne PU systems with certified gloss retention and color stability. Demand is concentrating in premium specification tiers that reward formulators with integrated laboratory capabilities and backward integration into isocyanate supply.
For Market Incumbents: Cement specification control in German and Chinese automotive corridors through captive laboratory partnerships with OEM engineering teams. Prioritize greenfield waterborne capacity with integrated solvent recovery to capture EU Green Deal industrial emissions subsidies. Defend against emerging Asian producers by locking in long-term polyol supply contracts before feedstock volatility intensifies. For New Entrants and Emerging Players: EPA 40 CFR Part 59 Subpart D in the United States opens a window for waterborne technology licensing partnerships with Midwest collision repair networks seeking compliance pathway guidance. Target India's PLI-scheme manufacturing corridors where domestic OEM capacity expansion lacks qualified local formulators. Pursue distributor technical service certification as the primary go-to-market angle rather than price competition. For Investors and Strategic Acquirers: Valuations sit cheapest among regional solventborne specialists with recent high-bake enamel investments now facing stranded asset risk. The five-to-ten year viability window favors acquisition of waterborne-capable mid-caps with certified applicator networks in automotive or marine segments. Watch EPA enforcement intensity and MEE rule implementation timelines as the signal for inflection in North American and Chinese conversion rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aliphatic Isocyanates | BASF SE's captive supply insulates margin pools from benzene derivative cyclicality. |
| Greenfield Waterborne Capacity with Solvent Recovery | EU Green Deal subsidies accelerate capital redeployment from legacy solventborne assets. |
| Certified Distributor Network Expansion | PPG Industries anchors North American automotive refinish through technical service density. |
| Marine Coatings Laboratory Partnerships | Akzo Nobel N.V. controls specification-grade development through integrated Netherlands facilities. |
| Regional Formulation Licensing Agreements | Technology transfer enables first-mover positioning in India's PLI-scheme industrial corridors. |
Research Methodology
Coverage spans East Asian manufacturing corridors, European automotive belts, and North American industrial regions, with primary inputs from each. The approach combines interviews with plant managers at coating production facilities, procurement leads at automotive OEMs, distribution channel partners, and technical R&D directors with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA regulatory filings. Bottom-up volume modeling triangulates against top-down macroeconomic drivers.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon. The analytical framework models segmentation dimensions including product type chemistry, end-use industry application, technology deployment method, and regional regulatory cluster. CAGRs derive from regression against historical adoption curves and input-output analysis of downstream manufacturing velocity. Industry-specific forecast inputs incorporate shipbuilding order backlogs at South Korean yards and automotive production schedules in German OEM corridors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained MDI feedstock price spikes or accelerated REACH Annex XVII restriction timelines. Deviation in EPA enforcement intensity or MEE rule implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Polyaspartic Coatings Market
Coatings
Thermal Insulation Coating Market
Coatings
Process Pipe Coating Market
Coatings
Global Diamond Coatings Market
Coatings
Corrosion Protection Coating Market
Coatings
US Industrial Coatings Market
Coatings
South Africa Protective Coatings Market
Coatings
Energy Efficient Powder Coatings Market
Coatings
Global Solar Panel Coatings Market
Coatings
Global Water-Based Coatings Market
Coatings
Cladding Coatings Market
Coatings
Global Radiation Cured Coatings Market
Coatings
Brazil Automotive OEM Coatings Market
Coatings
Stain Resistance Coatings Market
Coatings
Leisure Boat Marine Coatings Market
Coatings
Anti-Friction Coatings Market