
 Cutting Fluid Market | 2026-2036
Cutting Fluid Market Size, Share, and Industry Trends Forecast 2026-2036
Cutting Fluid Market Analysis
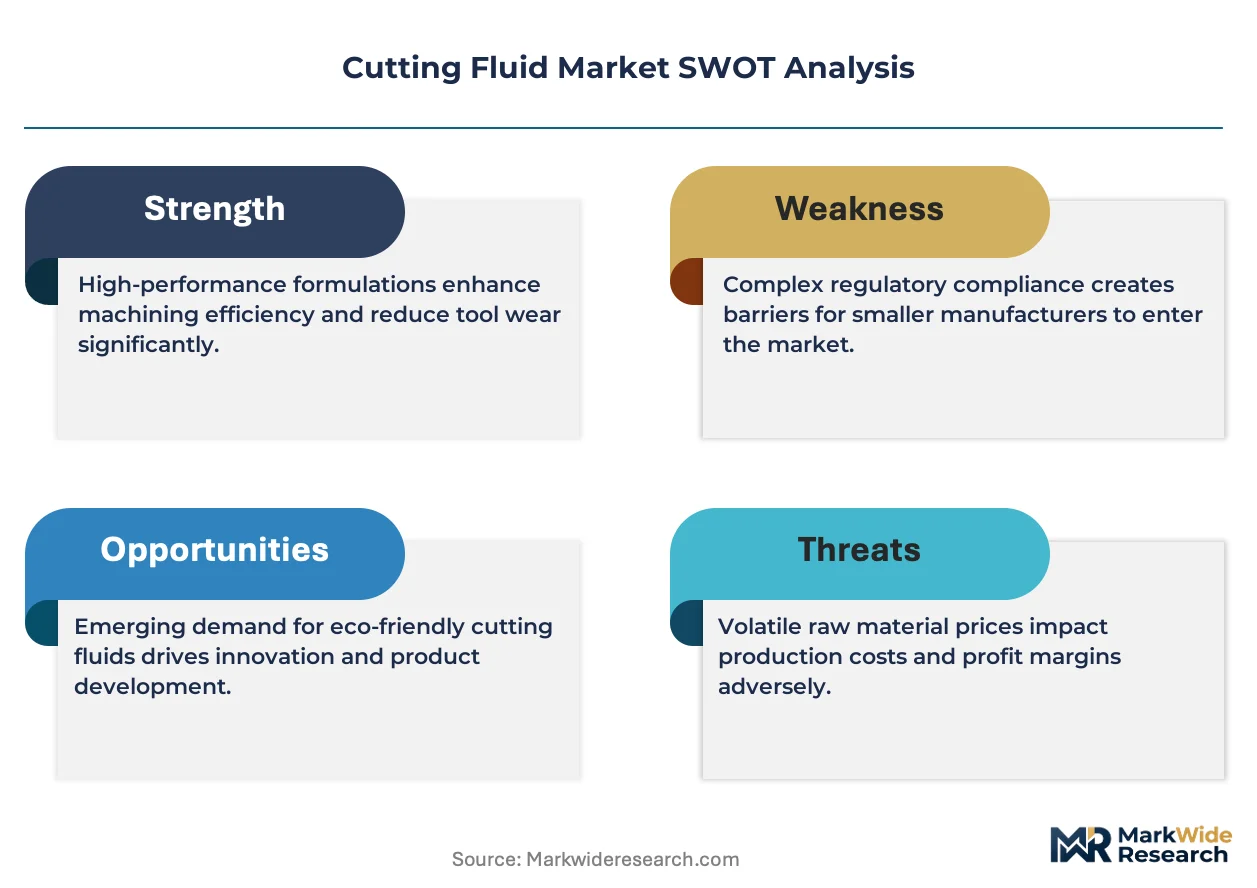
The premium-commodity split in cutting fluids is shifting toward performance-certified synthetics on one side and price-driven mineral emulsions on the other. Fuchs Petrolub SE leverages its European R&D base to dominate specialty formulations for tight-tolerance machining. Idemitsu Kosan anchors the Asia-Pacific supply map through integrated base oil production and localized blending networks. Blaser Swisslube differentiates via Swiss-quality precision fluids targeting medical and aerospace tier-one suppliers.
Cutting fluid denotes a engineered lubricant—typically comprising mineral or synthetic base oils, emulsifiers, extreme-pressure additives, and biocides—delivered as neat oil or diluted emulsion to reduce friction, dissipate heat, and evacuate chips during metal removal operations. Water-soluble formulations lead volume in high-speed machining centers where heat flux demands effective cooling, while synthetic grades capture expanding margin pools as aerospace and medical end users specify cleaner chemistries with extended sump life. The metal cutting application segment sustains the largest revenue footprint across automotive powertrain and transmission component manufacturing.
EPA discharge regulations in the United States, REACH chemical restrictions in Europe, and China's MEE wastewater standards collectively tighten permissible limits on boron, formaldehyde-releasing biocides, and chlorinated paraffins in metalworking effluent. These frameworks force reformulation investments and raise compliance costs for commodity producers while creating market access barriers for uncertified imports. Stakeholders must monitor evolving biocide approval timelines and regional carbon-intensity disclosures that will reshape supplier qualification criteria.
Market Dynamics
REACH compliance deadlines and EPA discharge enforcement are forcing simultaneous reformulation of base chemistries and biocide packages, compressing product development cycles while elevating R&D spend as a percentage of revenue for mid-tier suppliers.
Growth Catalysts
- Synthetic formulation demand:Aerospace tier-one suppliers in Germany and Japan specify extended-sump synthetic grades to reduce changeout frequency and machining downtime.
- China's eastern manufacturing corridor:Automotive and precision metalworking clusters in Jiangsu and Zhejiang provinces concentrate volume demand for water-soluble emulsions.
- MEE wastewater standards:China's Ministry of Ecology and Environment mandates lower boron and chlorinated paraffin limits, accelerating replacement of legacy mineral oil systems.
Market Restraints
- Base oil supply concentration:Integrated petrochemical majors in South Korea and Singapore control Group III and synthetic ester feedstock, exposing formulators to margin squeeze.
- Biocide approval timelines:ECHA's prolonged substance evaluation under REACH delays commercialization of new microbial control chemistries by 18-36 months.
- Water-based concentrate limitations:Extreme-pressure machining of titanium and nickel superalloys exceeds the lubricity ceiling of current bio-based emulsions.
Strategic Opportunities
- Medical device machining:Swiss and German orthopedic implant manufacturers specify residue-free synthetic fluids compatible with gamma sterilization protocols.
- Carbon-intensity disclosure mandates:EU CSRD requires Scope 3 reporting from metalworking customers, creating preference for bio-based formulations with certified lifecycle data.
- Direct-to-plant blending systems:On-site micro-dosing equipment reduces concentrate transport costs and inventory carrying charges for high-volume automotive powertrain plants.
Industry Challenges
- Tribochemistry expertise gap:Formulators struggle to recruit specialists capable of balancing extreme-pressure additive response with microbial stability in hard water.
- Legacy sump infrastructure:Centralized coolant systems in aging automotive stamping plants resist retrofit for synthetic fluids due to incompatible elastomer seals and filtration ratings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cutting Fluid Market |
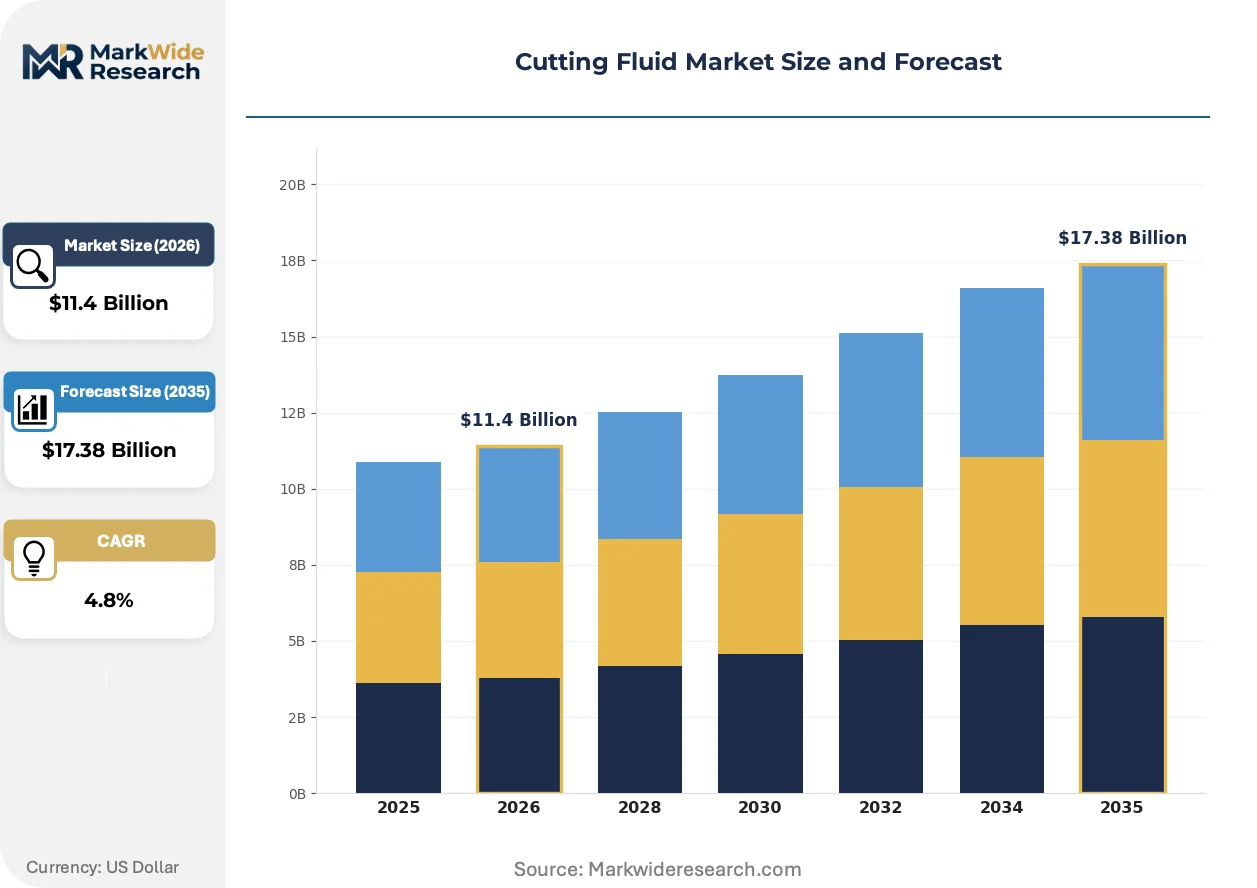
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $17.38 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Soluble, Oil-Based, Semi-Synthetic, Synthetic Application: Metal Cutting, Machining, Grinding, Milling End User: Automotive, Aerospace, Metalworking, Manufacturing Formulation: Additives, Chemicals, Concentrates, Emulsions |
| Companies Covered | Fuchs Petrolub SE, Idemitsu Kosan, Quaker Chemical Corporation, China Petrochemical Corporation, BP plc, Exxon Mobil Corporation, TotalEnergies SE, Blaser Swisslube, Chevron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cutting Fluid Market Emerging Trajectories
Formulation science is converging with digital monitoring and circular service models, shifting competitive advantage from chemical composition alone to integrated fluid management ecosystems.
Micro-emulsion technology is integrating nanoscale droplet stabilization to deliver cutting performance approaching neat oils while maintaining the heat removal capacity of water-based systems. Japanese automotive transmission manufacturers are piloting these grades in high-speed hobbing operations. The technology is integrating predictive maintenance platforms by enabling real-time refractometry and pH telemetry that signal additive depletion before tool wear accelerates.
REACH Annex XIV authorization requirements for boric acid derivatives are eliminating a cost-effective pH buffer and corrosion inhibitor from European formulations. Compounders must substitute amine-neutralized carboxylic acid packages at 15-40% raw material cost premiums. German machine tool builders and their tier suppliers face the steepest compliance burden, accelerating qualification of boron-free alternatives ahead of 2025 sunset dates.
Consolidated procurement by multi-site automotive groups is displacing fragmented distributor relationships with corporate-level fluid management contracts. Blending network operators and chemical management service providers capture multi-year agreements bundling concentrate supply, sump monitoring, and waste hauling. This concentration is most visible in North American powertrain manufacturing, where Detroit-based OEMs have reduced approved supplier lists from twelve to four cutting fluid vendors since 2020.
Cutting Fluid Market Segmentation
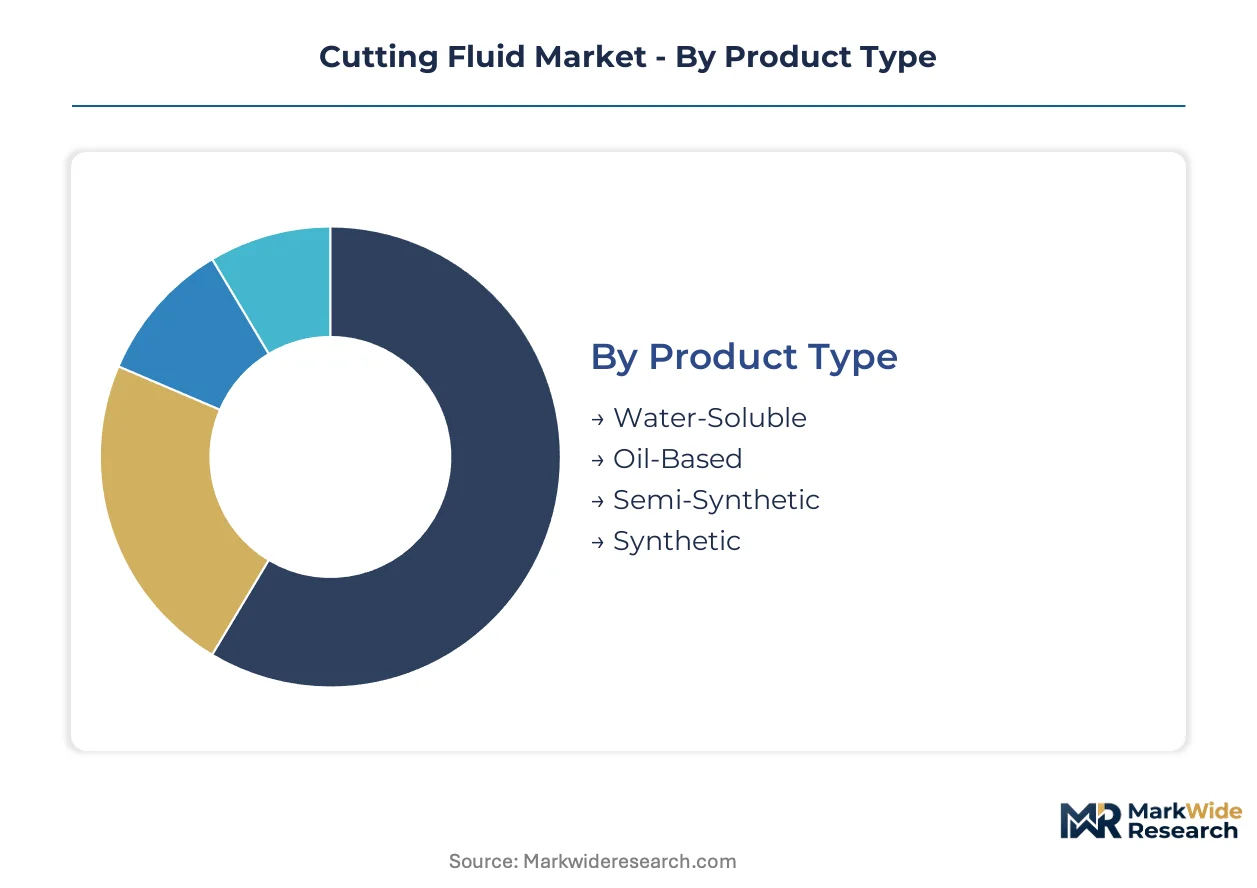
Cutting fluid segmentation reveals divergent performance requirements across metal removal operations. Formulation chemistry and application severity dictate whether standalone neat oils or integrated water-based systems capture procurement budgets.
Product Type:
Standalone neat oils dominate heavy-duty machining where lubricity cannot be compromised, while integrated water-based systems penetrate high-speed production environments demanding thermal management.
- Synthetic:Engineered from polyalphaolefins and synthetic esters without petroleum base stocks. Aerospace tier-one suppliers in Germany and Japan specify these grades for extended sump life and reduced changeout frequency in tight-tolerance operations. REACH Annex XIV restrictions on boric acid derivatives are accelerating reformulation toward amine-neutralized alternatives at raw material cost premiums.
- Water-Soluble:Mineral or synthetic base oils emulsified with surfactants for dilution in water, typically at 3-10% concentration. China's eastern manufacturing corridor in Jiangsu and Zhejiang provinces concentrates volume demand as automotive powertrain plants prioritize heat removal capacity over extreme-pressure lubricity. MEE wastewater standards mandate lower boron limits, forcing displacement of legacy formulations.
- Semi-Synthetic:Hybrid formulations blending mineral oil with synthetic components to balance cost and performance.
- Oil-Based:Neat petroleum-derived fluids requiring no dilution, retaining dominance in broaching and gear cutting.
Volume placements concentrate in Water-Soluble; the faster expansion belongs to Synthetic.
Application:
Application severity separates commodity emulsions from precision-formulated synthetics, with thermal load and surface finish requirements determining specification tiers.
- Metal Cutting:Primary metal removal operations including turning, drilling, and broaching where chip evacuation and tool life extension drive fluid selection. Automotive powertrain manufacturing in Germany and the United States sustains the largest revenue footprint, though EPA discharge enforcement is elevating compliance costs for centralized coolant systems.
- Grinding:Precision finishing operations generating fine particulate requiring superior filtration compatibility. Swiss and German orthopedic implant manufacturers specify residue-free synthetic fluids compatible with gamma sterilization protocols, creating premium margin pools.
- Machining:General-purpose material removal encompassing milling, drilling, and boring across varied substrates.
- Milling:Intermittent cutting operations with cyclical thermal loading and chip formation challenges.
Metal Cutting commands the deepest volume base; Grinding is climbing the fastest on medical and aerospace specification intensity.
End User:
End-user sophistication stratifies procurement between price-driven commodity buyers and performance-certified precision manufacturers.
- Automotive:High-volume powertrain and transmission component manufacturing with consolidated multi-site procurement. Detroit-based OEMs have reduced approved supplier lists from twelve to four vendors since 2020, bundling concentrate supply with sump monitoring and waste hauling services.
- Aerospace:Tier-one suppliers specifying extended-sump synthetic grades to reduce machining downtime. German and Japanese manufacturers lead qualification of boron-free alternatives ahead of regulatory sunset dates.
- Metalworking:Job shops and contract manufacturers serving fragmented industrial demand.
- Manufacturing:General industrial machinery and equipment production with varied specification requirements.
Automotive anchors the volume foundation; Aerospace is gaining share fastest on synthetic formulation premiums.
Formulation:
Formulation architecture determines whether fluids function as standalone concentrates or integrated additive packages requiring field blending.
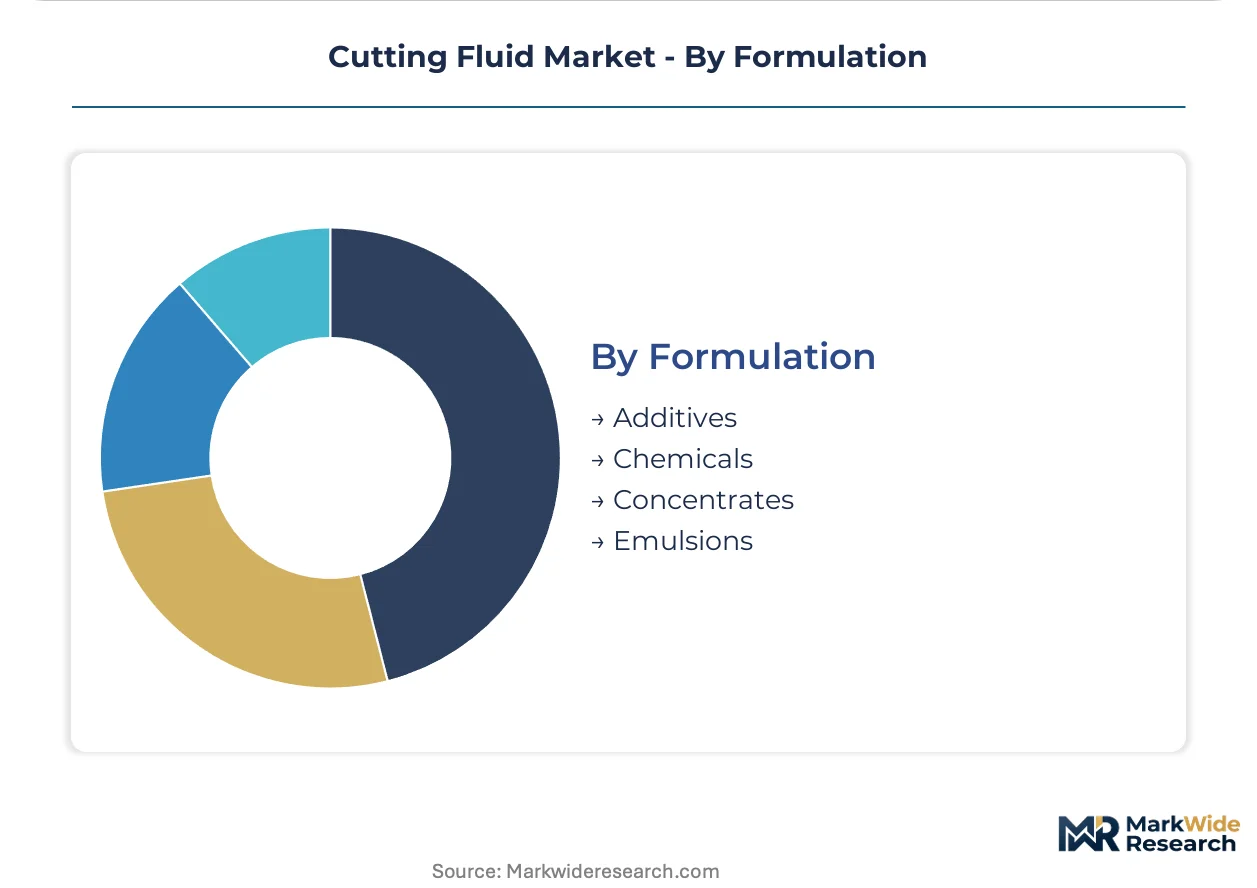
- Emulsions:Pre-stabilized oil-water dispersions delivering consistent droplet size distribution. Japanese automotive transmission manufacturers pilot micro-emulsion technology with nanoscale stabilization for high-speed hobbing operations.
- Additives:Functional chemistries including extreme-pressure agents, corrosion inhibitors, and biocides dosed into base fluids. ECHA's prolonged substance evaluation under REACH delays commercialization of new microbial control chemistries.
- Concentrates:Undiluted base formulations requiring on-site blending with water.
- Chemicals:Raw material inputs including base oils, surfactants, and performance polymers.
Emulsions capture the broadest deployment base; Additives face the steepest reformulation pressure from biocide approval delays.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Zhejiang provinces anchor the dominant demand corridor for water-soluble cutting fluids, where automotive powertrain clusters and precision metalworking shops concentrate procurement volumes. The regulatory landscape fragments across national jurisdictions, with each major manufacturing economy imposing distinct chemical restrictions on metalworking effluent. Industrial clusters in Germany, Japan, and the United States drive specification intensity for synthetic grades.
China
Automotive transmission plants and CNC machining centers in Suzhou and Ningbo absorb the largest water-soluble emulsion volumes across the eastern manufacturing corridor. MEE wastewater standards mandate progressive reductions in boron and chlorinated paraffin discharge limits, forcing displacement of legacy mineral oil systems. Jiangsu province hosts the densest concentration of metalworking fluid blenders serving export-oriented component manufacturers.
Germany
Aerospace tier-one suppliers in Bavaria and Baden-Württemberg specify extended-sump synthetic grades to minimize machining downtime in tight-tolerance operations. REACH Annex XIV authorization requirements eliminate boric acid derivatives from formulations by 2025, compelling substitution with amine-neutralized carboxylic acid packages. Stuttgart and Munich anchor the precision machining ecosystem where medical device and aerospace specifications converge.
United States
Detroit-based automotive OEMs have consolidated approved supplier lists from twelve to four cutting fluid vendors since 2020, bundling concentrate supply with fluid management services. EPA discharge enforcement tightens permissible limits on formaldehyde-releasing biocides in metalworking effluent across Great Lakes manufacturing zones. Ohio and Michigan host the most extensive centralized coolant infrastructure requiring reformulation investment.
Japan
Automotive transmission manufacturers in Aichi Prefecture pilot micro-emulsion technology with nanoscale droplet stabilization for high-speed hobbing operations. METI industrial standards encourage extended fluid life cycles to reduce waste generation in precision manufacturing. Nagoya and Toyota City concentrate demand for synthetic formulations serving hybrid powertrain component machining.
South Korea
Integrated petrochemical majors in Ulsan and Yeosu control Group III base oil and synthetic ester feedstock supply, positioning domestic formulators amid margin compression pressures. MFDS chemical safety notifications govern biocide incorporation in metalworking fluids distributed to automotive and electronics manufacturing. Gyeonggi Province semiconductor equipment fabricators generate specialized demand for residue-free synthetic chemistries.
Cutting Fluid Market Vendor Landscape
Capital-heavy integrated refiners compete with asset-light specialty formulators across divergent margin structures. The market exhibits tiered consolidation: petrochemical majors leverage captive base oil supply, regional blenders defend local service relationships, and precision specialists capture premium niches through formulation certification. Three archetypes dominate: upstream-integrated oil majors, European and Japanese specialty compounders, and Asia-Pacific distributor-blenders with localized technical service. Competitive dynamics center on backward integration into synthetic ester production and chemical management service bundling.
Among European specialty compounders, Fuchs Petrolub SE and Blaser Swisslube exemplify the precision-formulation archetype targeting aerospace and medical device specifications. Idemitsu Kosan represents the Asia-Pacific integrated model, combining base oil production with localized blending networks. These three occupy positions defined by geographic R&D anchoring and end-market certification depth rather than scale alone.
| Leading Market Players |
|---|
| Fuchs Petrolub SE |
| Idemitsu Kosan |
| Quaker Chemical Corporation |
| China Petrochemical Corporation |
| BP plc |
| Exxon Mobil Corporation |
| TotalEnergies SE |
| Blaser Swisslube |
| Chevron Corporation |
| Others |
Supply Flow & Price Mechanics
Backward integration into synthetic ester production anchors both supply security and pricing power for European specialty compounders facing REACH-mandated reformulation costs. Captive control over Group III base oil and additive chemistry insulates integrated majors from margin compression while forcing independent blenders toward service-based differentiation.
Pricing Analysis
Value-based pricing tied to machining throughput and tool life extension dominates specification-grade synthetics for aerospace tier-one suppliers. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified boron-free formulations from legacy mineral emulsions and commodity water-soluble concentrates. Cost compression in mid-tier synthetic segments is intensifying because South Korean and Singaporean petrochemical majors control feedstock supply. Automotive powertrain plants exhibit highest price sensitivity through consolidated procurement, while medical device manufacturers accept premium positioning for gamma-sterilization-compatible grades.
Supply Chain Analysis
Group III base oil and synthetic ester supply rests on integrated petrochemical complexes in South Korea, Singapore, and Japan. Formulators draw from polyalphaolefin feedstock, extreme-pressure additive packages, and amine-neutralized corrosion inhibitors to meet evolving biocide restrictions. Single-source vulnerability concentrates in boron-free pH buffer alternatives where ECHA approval timelines lag formulation demand. Distribution runs through regional blending networks serving automotive clusters with direct-to-plant micro-dosing systems displacing traditional distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cutting fluid sector sits in a formulation-transition phase as micro-emulsion technology with nanoscale droplet stabilization displaces legacy mineral oil systems in high-speed machining applications.
For Market Incumbents: Extend synthetic formulation certification depth to defend aerospace and medical device premium positions against integrated oil majors expanding downstream. Accelerate boron-free alternative qualification ahead of REACH Annex XIV sunset dates. Deepen chemical management service bundling to lock in multi-year automotive powertrain contracts. For New Entrants and Emerging Players: Direct-to-plant blending system partnerships offer the lowest-friction entry path into high-volume automotive manufacturing. Target China's Jiangsu and Zhejiang provinces where MEE wastewater standards displace legacy mineral systems. Pursue residue-free synthetic formulations for Swiss and German orthopedic implant manufacturers as the most penetrable premium niche. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated petrochemical majors seeking formulation expertise and regional blending infrastructure. Five-to-ten year viability favors compounders with demonstrated REACH compliance and carbon-intensity disclosure capabilities. Watch ECHA biocide approval timelines as the critical inflection signal for microbial control chemistry commercialization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Ester Production | Captive supply of Group III feedstock insulates margin position against South Korean and Singaporean petrochemical pricing power. |
| REACH-Compliant Boron-Free Formulation Launch | Amine-neutralized carboxylic acid packages secure German aerospace tier-one qualification ahead of regulatory sunset. |
| Chemical Management Service Contract | Bundled concentrate supply with sump monitoring captures multi-year Detroit OEM procurement consolidation. |
| Micro-Emulsion Technology Pilot Program | Nanoscale droplet stabilization penetrates Japanese automotive transmission high-speed hobbing operations. |
| Direct-to-Plant Blending System Deployment | On-site micro-dosing reduces transport costs and inventory carrying charges for high-volume powertrain plants. |
Methodological Framework
Independent corroboration across plant managers at automotive powertrain facilities, procurement leads at aerospace tier-one suppliers, and technical R&D directors at European specialty compounders underwrites the qualitative findings. Secondary validation draws from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA substance evaluation databases. Bottom-up demand modeling across end-use segments triangulates with top-down supply capacity assessments.
Rate-of-change decomposition separates volume growth from value expansion across synthetic grade tier, end-use industry, and regional production hub dimensions throughout the forecast period. CAGRs derive from segment-level demand elasticity analysis calibrated to REACH compliance investment cycles and MEE wastewater standard implementation phases. Forecast inputs incorporate biocide approval timeline probability distributions and automotive OEM supplier consolidation trajectories.
The model holds under stable regulatory enforcement timelines; deviation in ECHA substance evaluation acceleration or EPA discharge rule stringency would shift synthetic adoption curves. Forecasts reflect documented assumptions regarding feedstock supply concentration and tier-one qualification protocols. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Spain Lubricants Market
Lubricants
Thailand Automotive Engine Oils Market
Lubricants
Global Hydraulic Fluid Market
Lubricants
Global Friction Modifiers Market
Lubricants
Nigeria Lubricants Market
Lubricants
Lube Skid Market
Lubricants
China Refrigeration Lubricants Market
Lubricants
Middle East Commercial Vehicles Lubricants Market
Lubricants
Contact Lubricants Market
Lubricants
Marine Lubricants Market
Lubricants
Germany Lubricants Market
Lubricants
Hydraulic Oil Additives Market
Lubricants
Norway Automotive Lubricants Market
Lubricants
Italy Lubricants Market
Lubricants
Yarn Lubricant Market
Lubricants
Mexico Commercial Vehicles Lubricants Market