
 Nigeria Lubricants Market | 2026-2036
Nigeria Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Lubricants Market Outlook
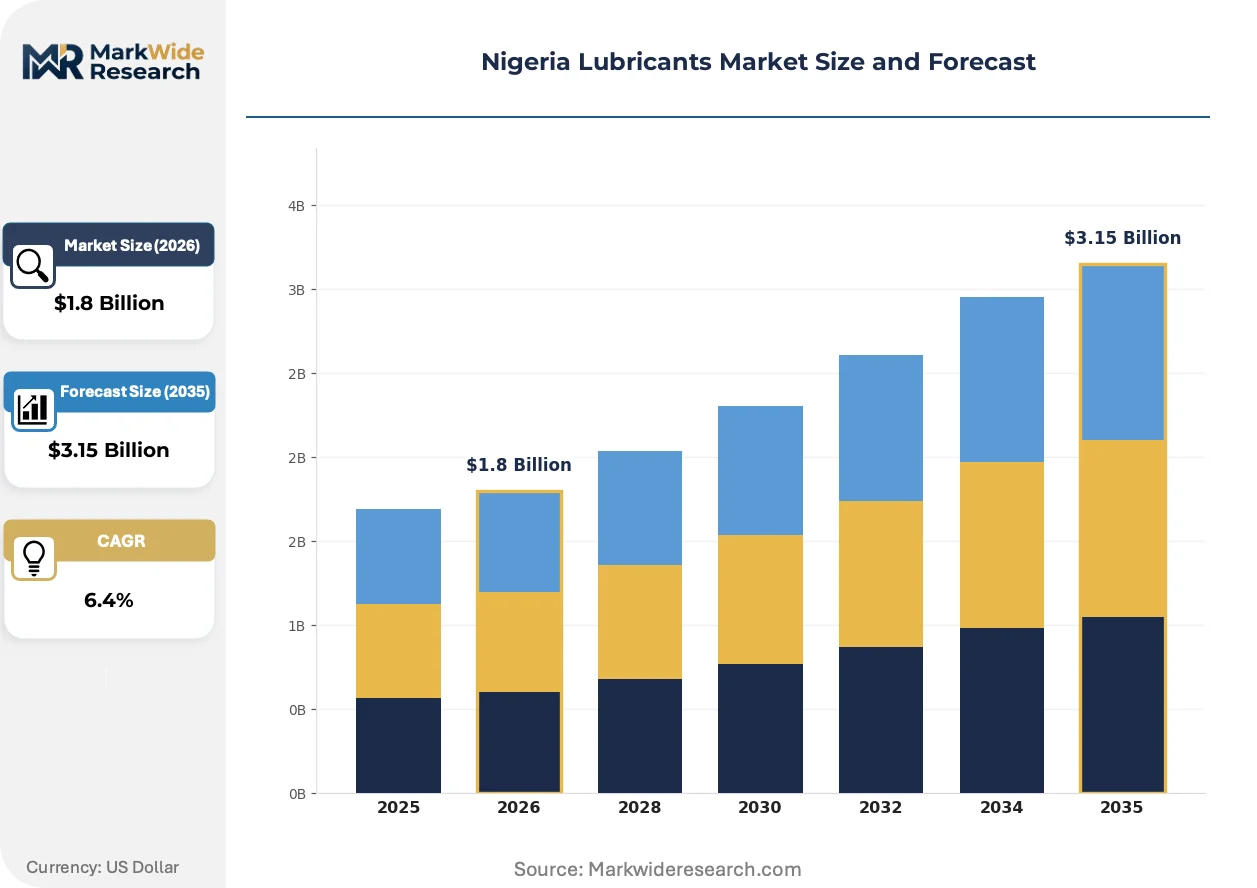
Nigeria's transition toward cleaner fuel standards under the African Petroleum Producers Organization sustainability compact is expanding the addressable market for high-performance lubricant formulations. TotalEnergies leverages its integrated refining and blending infrastructure across West Africa to secure feedstock reliability for Nigerian operations. Shell plc, through Ardova PLC, anchors retail distribution through an extensive service station network that reaches secondary cities. Exxon Mobil Corporation, operating via 11 PLC, competes on technical service partnerships with fleet operators and industrial accounts.
Lubricants are formulated mixtures of base oils and additive packages engineered to reduce friction, dissipate heat, and prevent corrosion in mechanical systems operating under load; viscosity grades typically range from ISO VG 32 to VG 680 for industrial applications, with total base number (TBN) serving as a critical parameter for engine oil service life in high-sulfur fuel environments. Engine Oil commands the largest product category share due to Nigeria's substantial vehicle parc and commercial transport intensity, while Industrial Machinery applications in cement, steel, and food processing plants represent the fastest-growing demand segment as manufacturing capacity expands. The Aftermarket Providers channel dominates volume flows through independent workshops and parts distributors, though OEMs are tightening specification control through branded service programs.
The Department of Petroleum Resources and the Standards Organisation of Nigeria jointly govern lubricant quality through mandatory product registration and periodic laboratory testing, with SON's Nigerian Industrial Standards mandating minimum performance benchmarks for engine oils sold in the country. The National Agency for Food and Drug Administration and Control extends oversight to food-grade lubricants used in processing equipment, creating a dual compliance burden for suppliers serving Nigeria's agro-industrial sector. Stakeholders must monitor regulatory alignment between domestic standards and evolving API and ACEA specifications, as specification gaps between imported products and local blending outputs create both compliance risk and competitive opportunity for technically capable blenders.
Market Dynamics
The Department of Petroleum Resources' stricter base oil import standards is compressing formulation flexibility for Nigerian blenders while simultaneously elevating technical barriers to market entry.
Growth Catalysts
- Fleet Operator Specification Upgrades:Logistics corridors serving cement and steel manufacturing are mandating higher TBN engine oils to combat accelerated engine wear in tropical heat and dust conditions.
- AFRI-4 Fuel Standards Alignment:The African Petroleum Producers Organization sustainability compact is expanding demand for low-SAPS lubricant formulations compatible with cleaner diesel specifications.
- Niger Delta Industrial Cluster Density:Concentrated energy infrastructure and manufacturing capacity around Port Harcourt and Warri creates predictable offtake volumes for industrial lubricant suppliers.
Market Restraints
- API Group II/III Base Oil Import Dependency:Nigerian blenders lack domestic hydrocracking capacity, exposing margins to dollar-denominated feedstock volatility and shipping cost swings.
- SON Certification Bottlenecks:Mandatory product registration and laboratory testing timelines create working capital strain for smaller blenders seeking market access.
- Extended Oil Drain Interval Technologies:Synthetic formulations and condition monitoring systems threaten volume-based revenue models for traditional mineral oil suppliers.
Strategic Opportunities
- Food-Grade Lubricant Specialization:NAFDAC's dual compliance burden for agro-industrial processing equipment creates premium pricing potential for technically capable suppliers.
- Branded Service Program Expansion:OEMs tightening specification control opens channel partnership opportunities for blenders with laboratory and technical service capabilities.
- Lagos State Aftermarket Consolidation:Independent workshop networks remain fragmented, presenting acquisition targets for distributors seeking route density.
Industry Challenges
- Formulation Chemist Talent Scarcity:Blending operations struggle to recruit personnel capable of navigating API, ACEA, and SON specification alignment simultaneously.
- Laboratory Testing Infrastructure Gaps:In-house analytical capabilities for TBN, viscosity index, and oxidation stability require capital deployment that mid-tier blenders cannot absorb.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Lubricants Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Gear Oil, Hydraulic Fluid, Grease Application: Automotive, Industrial Machinery, Marine, Aerospace End User: OEMs, Aftermarket Providers, Factories, Logistics Distribution Channel: Retail, Online, Wholesale, Direct Sales |
| Companies Covered | TotalEnergies, Shell plc (Ardova PLC), Exxon Mobil Corporation (11 PLC), MRS Oil Nigeria PLC, Conoil PLC, Oando PLC, BP Plc (Castrol), Ammasco International Limited, Eterna Plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Lubricants Market Strategic Shifts
Digital oil condition monitoring and synthetic formulation advances are compressing traditional service intervals while regulatory alignment pressures are fragmenting supplier tiers based on technical capability.
Sensor-enabled lubricant analysis is automating predictive maintenance decisions for fleet operators across Nigerian logistics corridors. Transport companies operating between Lagos and Kano are deploying real-time viscosity and particle count monitoring to extend drain intervals beyond manufacturer recommendations. This capability is automating procurement timing and reducing safety stock requirements for large-scale commercial vehicle operators.
The Standards Organisation of Nigeria's Nigerian Industrial Standards revisions are tightening minimum performance benchmarks for engine oils sold domestically. Blenders must now demonstrate compliance with API SN Plus or ACEA C sequences to maintain product registration, forcing technical upgrades or market exit. Lagos-based independent lubricant marketers are responding by outsourcing formulation development to regional technical centers in South Africa and the UAE.
Condition-based maintenance contracts are displacing traditional volume-based supply agreements among Nigerian cement and steel manufacturers. Industrial accounts now demand lubricant performance guarantees tied to equipment uptime metrics rather than per-liter pricing. This shift is most visible in the Niger Delta manufacturing cluster, where Dangote Cement and other integrated producers are unbundling lubricant supply from broader maintenance service agreements.
Nigeria Lubricants Market Segmentation
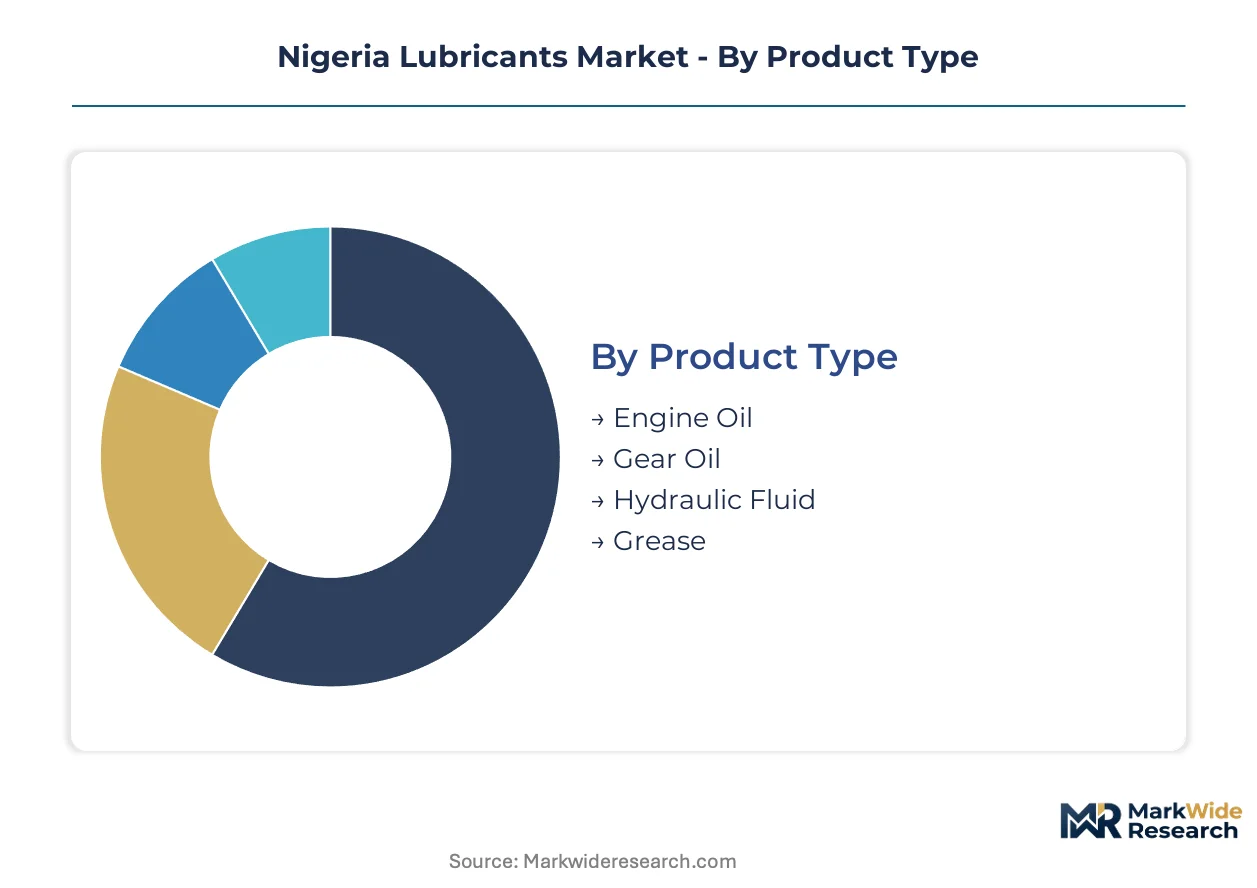
Nigeria's lubricant segmentation reflects divergent technical requirements across tropical operating conditions, import-dependent supply chains, and fragmented distribution infrastructure. Specification alignment with SON standards and API sequences creates tiered competitive access across product categories.
Product Type:
Buyers differentiate by base oil group compatibility with high-sulfur fuel environments and tropical heat degradation profiles.
- Engine Oil:Formulated with elevated total base number to neutralize acid byproducts from high-sulfur diesel prevalent across Nigerian filling stations. Fleet operators plying Lagos-Kano logistics corridors mandate API CK-4 or ACEA E9 specifications to combat accelerated cylinder wear from dust infiltration and thermal load.
- Hydraulic Fluid:Anti-wear additive packages with zinc dialkyldithiophosphate chemistry protect pump components in cement plant and steel mill hydraulic systems. Dangote Cement's Obajana complex and other Niger Delta manufacturing clusters drive concentrated offtake for ISO VG 46 and VG 68 viscosity grades.
- Gear Oil:Extreme pressure formulations with sulfur-phosphorus chemistry protect differentials and transmissions in commercial vehicle applications.
- Grease:Lithium complex and calcium sulfonate thickeners serve bearings in food processing equipment under NAFDAC compliance requirements.
Volume sits with Engine Oil; growth tilts toward Hydraulic Fluid.
Application:
End-use concentration varies by asset ownership structure and maintenance outsourcing patterns across Nigerian industrial zones.
- Automotive:Passenger vehicle service intervals remain compressed by mineral oil dominance, while commercial transport fleets adopt synthetic blends for extended drain intervals. Lagos State's dense vehicle parc and informal mechanic networks sustain high-volume, low-margin trade.
- Industrial Machinery:Cement, steel, and food processing plants in Port Harcourt and Warri industrial clusters demand condition-based maintenance contracts with uptime guarantees. Equipment manufacturers specify lubricant performance metrics rather than per-liter pricing, compressing traditional distributor margins.
- Marine:Two-stroke crosshead engine oils and trunk piston formulations serve vessels operating Nigerian coastal and inland waterways.
- Aerospace:Synthetic turbine oils and hydraulic fluids for fixed-wing and rotary aircraft operating from Lagos and Abuja hubs.
Automotive commands current volume; Industrial Machinery offers the steepest expansion trajectory.
End User:
Procurement sophistication separates specification-controlled accounts from price-sensitive spot buyers.
- Aftermarket Providers:Independent workshops and parts distributors across Lagos, Kano, and Onitsha trade in unbranded or third-party lubricants with variable SON compliance. Working capital constraints and certification bottlenecks limit technical service capabilities among smaller operators.
- OEMs:Vehicle and equipment manufacturers tighten specification control through branded service programs, requiring blenders to demonstrate laboratory testing infrastructure and formulation development partnerships. TotalEnergies and Shell plc anchor these channels through integrated technical service networks.
- Factories:Integrated manufacturing operations with captive maintenance teams negotiate direct supply agreements bypassing distributor markups.
- Logistics:Fleet operators with centralized procurement and sensor-enabled condition monitoring compress safety stock requirements.
Aftermarket Providers dominate transaction volume; OEMs concentrate value capture.
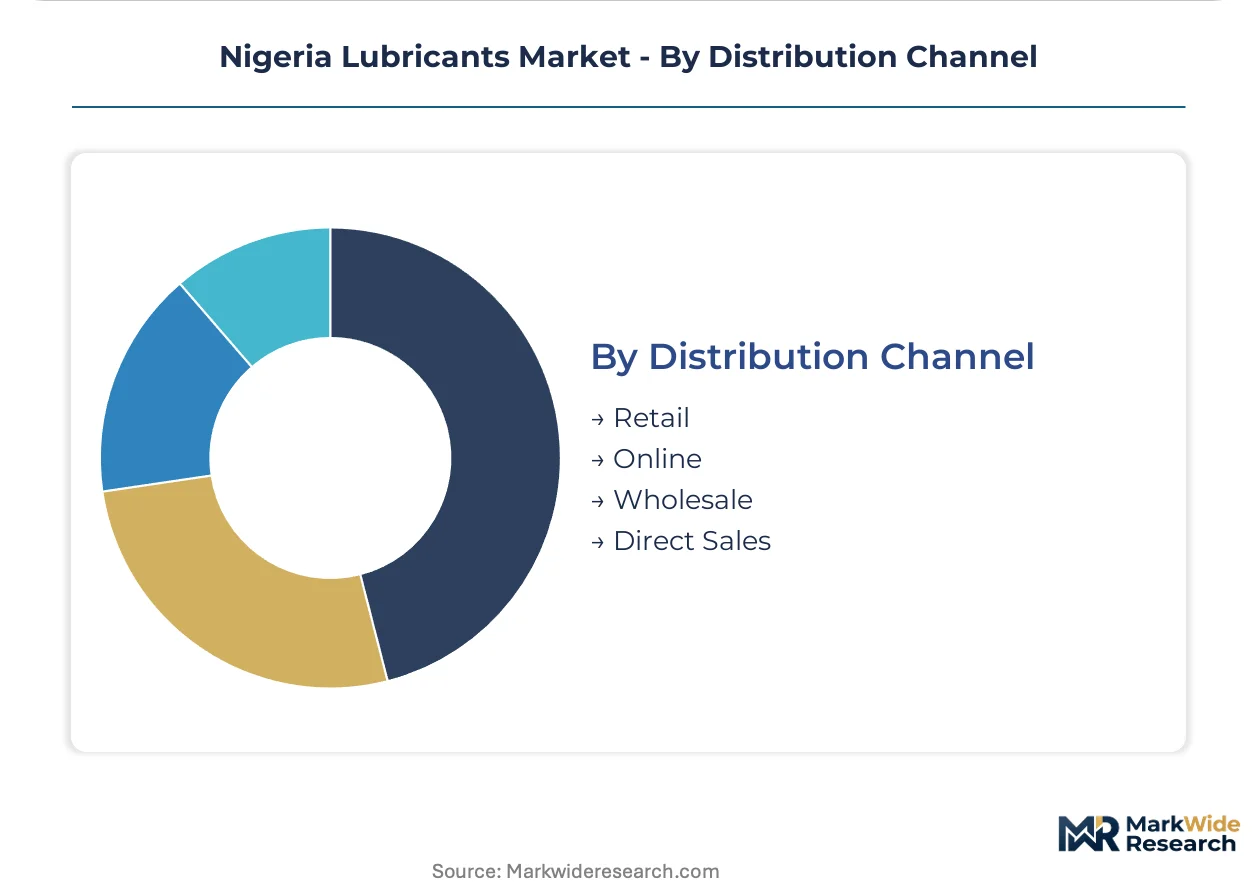
Distribution Channel:
Channel selection reflects buyer scale, technical support requirements, and working capital availability.
- Wholesale:Bulk deliveries to blender-owned depots and independent distributors serve high-volume industrial accounts and retail network replenishment. Port Harcourt and Lagos storage terminals anchor geographic coverage for Niger Delta and southwestern demand clusters.
- Direct Sales:Technical service engineers from Ardova PLC and 11 PLC secure long-term contracts with cement manufacturers and fleet operators. Condition monitoring integration and performance guarantees differentiate these relationships from transactional supply.
- Retail:Service station forecourts and independent auto parts shops reach fragmented passenger vehicle owners.
- Online:E-commerce platforms and B2B procurement portals serve small fleet operators and workshops with credit-constrained spot purchasing.
Wholesale moves the highest liters; Direct Sales captures premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lagos State and the Niger Delta industrial cluster concentrate Nigeria's lubricant demand through manufacturing density, port logistics, and energy infrastructure. Fleet operators along the Lagos-Kano corridor drive specification upgrades for tropical operating conditions. The Department of Petroleum Resources and Standards Organisation of Nigeria enforce quality benchmarks that shape regional supply patterns.
Lagos State
Lagos commands the largest vehicle parc and aftermarket workshop density in Nigeria. The Standards Organisation of Nigeria operates product testing facilities in Lagos that enforce mandatory lubricant registration. Apapa port and Ijora industrial zones create concentrated offtake for hydraulic fluids and engine oils serving cement plants and logistics fleets.
Niger Delta
Port Harcourt and Warri anchor energy infrastructure and manufacturing capacity that drives industrial lubricant consumption. The Department of Petroleum Resources maintains regional offices in Port Harcourt that monitor base oil import quality. Dangote Cement's Obajana complex and other integrated producers negotiate condition-based maintenance contracts with uptime guarantees.
Kano and Northern Corridors
Commercial transport fleets plying Lagos-Kano logistics routes mandate elevated total base number engine oils for dust-intensive operating conditions. The National Agency for Food and Drug Administration and Control extends oversight to food-grade lubricants used in Kano's agro-processing facilities. Distributor networks in Kano and Onitsha trade unbranded lubricants with variable compliance levels.
South-East Industrial Zone
Enugu and Aba manufacturing clusters generate demand for industrial machinery lubricants in food processing and light manufacturing. The Standards Organisation of Nigerian Industrial Standards revisions pressure blenders toward API SN Plus compliance. Independent workshop networks remain fragmented, presenting consolidation opportunities for distributors seeking route density.
Federal Capital Territory
Abuja's aviation hub generates specialized demand for synthetic turbine oils and hydraulic fluids. The Department of Petroleum Resources coordinates national policy alignment with African Petroleum Producers Organization sustainability standards. Fleet operators with centralized procurement compress safety stock requirements through sensor-enabled condition monitoring.
Nigeria Lubricants Market Competitive Environment
Premium-margin players sit above commodity-margin players across technical service capabilities and laboratory infrastructure. The Nigerian lubricants market structures around integrated international majors, domestic blenders with distribution scale, and independent marketers competing on price. Three archetypes dominate: global energy majors with captive refining and technical networks; Nigerian petroleum marketing companies with retail station density; and independent blenders serving price-sensitive aftermarket channels. Competitive moves concentrate on branded service program expansion and direct supply agreements with industrial accounts.
Within the integrated major tier, TotalEnergies leverages West African refining infrastructure to secure feedstock reliability for Nigerian blending operations. Shell plc, operating through Ardova PLC, anchors retail distribution through extensive service station networks reaching secondary cities. Exxon Mobil Corporation, via 11 PLC, competes through technical service partnerships with fleet operators and industrial accounts requiring condition monitoring integration.
| Leading Market Players |
|---|
| TotalEnergies |
| Shell plc (Ardova PLC) |
| Exxon Mobil Corporation (11 PLC) |
| MRS Oil Nigeria PLC |
| Conoil PLC |
| Oando PLC |
| BP Plc (Castrol) |
| Ammasco International Limited |
| Eterna Plc |
| Others |
Value Chain & Pricing Dynamics
API Group II/III base oil spot indices in Rotterdam and Singapore set the floor for Nigerian blender input costs, cascading through dollar-denominated import contracts into three distinct pricing tiers segmented by SON certification status and technical service bundling.
Pricing Analysis
Condition-based maintenance contracts with uptime guarantees anchor value-based pricing for industrial accounts in the Niger Delta cement and steel clusters. Three-tier pricing structure across premium, standard, and economy levels separates OEM-branded synthetic formulations from SON-certified mineral blends and unregistered spot-market products. Pricing pressure stems from synthetic formulations extending drain intervals and compressing per-liter volumes. Aftermarket providers and independent workshops exhibit highest price sensitivity, while fleet operators with sensor-enabled monitoring prioritize performance guarantees over unit economics.
Supply Chain Analysis
Formulation chemist scarcity in Nigerian blending operations constrains technical capacity expansion despite feedstock availability through Apapa and Port Harcourt port infrastructure. Base oil supply concentrates in Belgium, the UAE, and South Korea as primary export hubs for API Group II/III hydrocracked stocks. Nigerian blenders draw from dollar-denominated spot and term contracts, exposing margins to currency volatility and shipping cost swings. Single-source vulnerability intensifies around European base oil supply during refinery maintenance cycles. Distribution runs through blender-owned depots in Lagos and Port Harcourt, with wholesale bulk deliveries serving industrial accounts and retail network replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Nigerian lubricants market functions as a cost-of-compliance story where SON certification timelines and laboratory testing requirements erect barrier-to-entry moats favoring technically capable blenders with capital reserves.
For Market Incumbents: Lock in formulation development partnerships with regional technical centers in South Africa and the UAE to circumvent domestic chemist scarcity. Secure captive laboratory testing infrastructure to compress SON registration timelines and defend against smaller blenders seeking market access through outsourced compliance. Channel control through branded service programs with OEMs provides defensive positioning against direct sales erosion from condition-based maintenance contracts. For New Entrants and Emerging Players: Independent workshop networks in Kano and Onitsha present the most penetrable channel entry points given fragmentation and working capital constraints limiting incumbent coverage. Food-grade lubricant specialization under NAFDAC dual compliance requirements offers white-space positioning in agro-industrial processing equipment serving Kano's grain milling and oilseed crushing facilities. Technical service partnerships with smaller cement and steel manufacturers outside Dangote's integrated operations provide a go-to-market angle distinct from volume-based commodity supply. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier blenders with existing SON registration portfolios and Port Harcourt or Lagos storage terminal access during periods of base oil price volatility. Long-term viability across a 5-10 year window hinges on backward integration into regional base oil supply relationships or formulation technology licensing. Monitor API Group II/III import duty adjustments and SON standard revision timing as inflection indicators for margin compression or competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Supply | Secures feedstock reliability against dollar volatility and Rotterdam price swings. |
| Laboratory Testing Infrastructure Buildout | Compresses SON certification timelines and enables premium OEM service programs. |
| Food-Grade Lubricant Specialization | Captures NAFDAC-compliant premium pricing in Kano agro-processing clusters. |
| Condition Monitoring Integration | Enables uptime-guarantee contracts displacing volume-based supply agreements. |
| Independent Workshop Network Acquisition | Builds route density in fragmented Lagos and Onitsha aftermarket channels. |
Study Parameters
Document review covered customs and trade data from Nigerian Ports Authority, Department of Petroleum Resources regulatory filings, and SON product registration databases, complemented by interviews with lubricant blending plant managers, procurement leads at Dangote Cement and other Niger Delta manufacturers, fleet operations directors along Lagos-Kano corridors, and aftermarket distribution channel partners. Secondary validation drew from API licensing records, ACEA oil sequences documentation, and base oil trade flow analysis from Rotterdam and Singapore hubs. Bottom-up volume estimates from individual blender capacity and top-down demand segmentation triangulated market sizing.
Segment-level outputs across product type, application, end user, and distribution channel dimensions were modeled over the projection horizon. CAGRs were derived from elasticity-adjusted demand drivers including fleet expansion rates, industrial capacity additions, and specification upgrade penetration. Industry-specific forecast inputs incorporated AFRI-4 fuel standards implementation timelines and SON Nigerian Industrial Standards revision schedules.
Caveats apply where base oil price volatility, naira exchange rate movements, or SON certification processing delays could materially shift the outlook. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Russia Automotive Lubricants Market
Lubricants
America Lubricants Market
Lubricants
Global Engineered Fluids Market
Lubricants
Global Lubricant Antioxidants Market
Lubricants
Colombia Lubricants Market
Lubricants
Global Refrigeration Lubricants Market
Lubricants
Indonesia Lubricants Market
Lubricants
Bulgaria Lubricants Market
Lubricants
Germany Automotive Engine Oils Market
Lubricants
Forestry Lubricants Market
Lubricants
Saudi Arabia Lubricants Market
Lubricants
Angola Lubricants Market
Lubricants
Spain Commercial Vehicles Lubricants Market
Lubricants
Jordan Lubricants Market
Lubricants
Africa Commercial Vehicles Lubricants Market
Lubricants
United Kingdom Commercial Vehicles Lubricants Market