
 Commercial Deep Fryer Parts and Accessories Market | 2026-2036
Commercial Deep Fryer Parts and Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Deep Fryer Parts and Accessories Market Outlook
Full-service restaurant capital expenditure on deep fryer maintenance is collapsing as quick-service chains accelerate equipment refresh cycles. Frymaster dominates the OEM replacement channel through captive distribution networks. Henny Penny Corporation anchors the high-volume frying segment with specialized gas thermostat assemblies. Electrolux Professional competes in European aftermarket supply through regional service partnerships.
Commercial deep fryer parts and accessories encompass replaceable mechanical and electrical subsystems—heating elements rated between 3 kW and 24 kW, bimetallic thermostats, sediment-filtration cartridges, and pressure-rated safety valves—sustaining continuous oil temperature control in high-throughput food preparation environments. Stainless steel heating elements lead component-type revenue due to thermal fatigue resistance and NSF compliance requirements, while filtration systems represent the fastest-expanding segment as operators face stricter oil quality mandates. Baskets and covers in the accessory-type category occupy mature margin pools with limited differentiation, whereas oil disposal units are gaining share from sustainability-driven kitchen redesigns.
The U.S. FDA Food Code and NSF International standards govern material safety and cleanability specifications, compelling manufacturers to certify all food-contact surfaces under unified protocols. The EPA's used oil management regulations under 40 CFR Part 279 shape demand for integrated disposal and recycling accessories in commercial installations. Stakeholders must monitor evolving state-level energy efficiency mandates and grease interceptor codes that could disqualify legacy fryer configurations from retrofit eligibility.
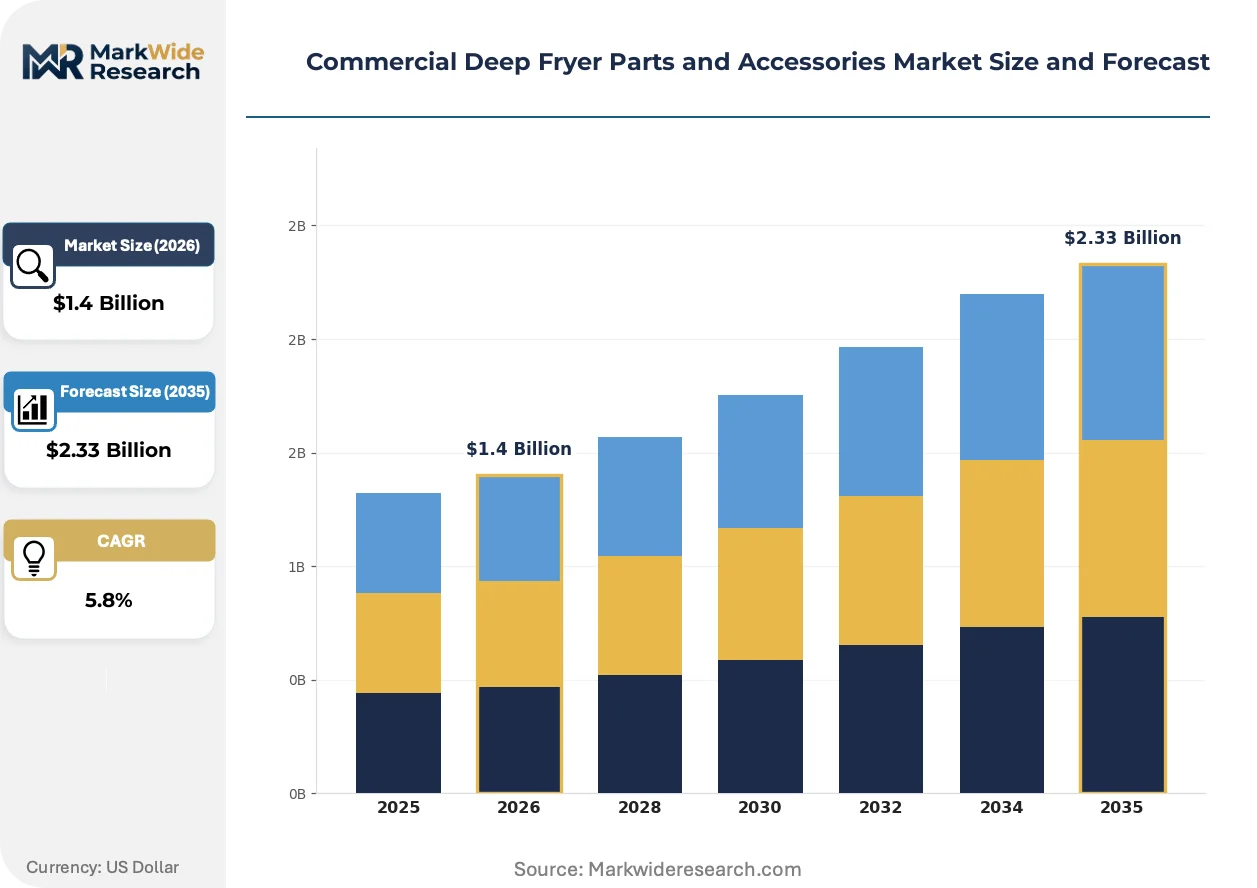
Market Dynamics
Quick-service restaurant fleet refresh cycles are compressing replacement part demand into concentrated procurement windows, while FDA oil quality mandates force simultaneous upgrades across filtration and monitoring subsystems. This dual pressure restructures how operators sequence capital deployment across heating elements, thermostats, and disposal accessories.
Growth Catalysts
- Regulatory Compliance Pressure:The U.S. FDA Food Code updates on oil quality management compel operators to install higher-grade filtration cartridges and temperature monitoring assemblies. Chain restaurants face inspection-driven replacement timelines.
- Equipment Refresh Concentration:Quick-service chains across the southern United States are accelerating fryer fleet replacements, creating synchronized demand spikes for heating elements, gas thermostat assemblies, and sediment-filtration systems.
- Stainless Steel Thermal Performance:NSF-compliant stainless steel heating elements rated between 3 kW and 24 kW dominate component selection due to thermal fatigue resistance and cleanability certification requirements.
Market Restraints
- Supply Concentration Risk:OEM replacement channels remain captive to dominant fryer manufacturers, limiting aftermarket supplier access to technical specifications and installation protocols.
- Input Cost Volatility:Nickel and chromium price swings directly impact stainless steel heating element production economics, compressing margins for component fabricators.
- Technical Obsolescence Threshold:Legacy fryer configurations face disqualification from retrofit eligibility under evolving state-level energy efficiency mandates and grease interceptor codes.
Strategic Opportunities
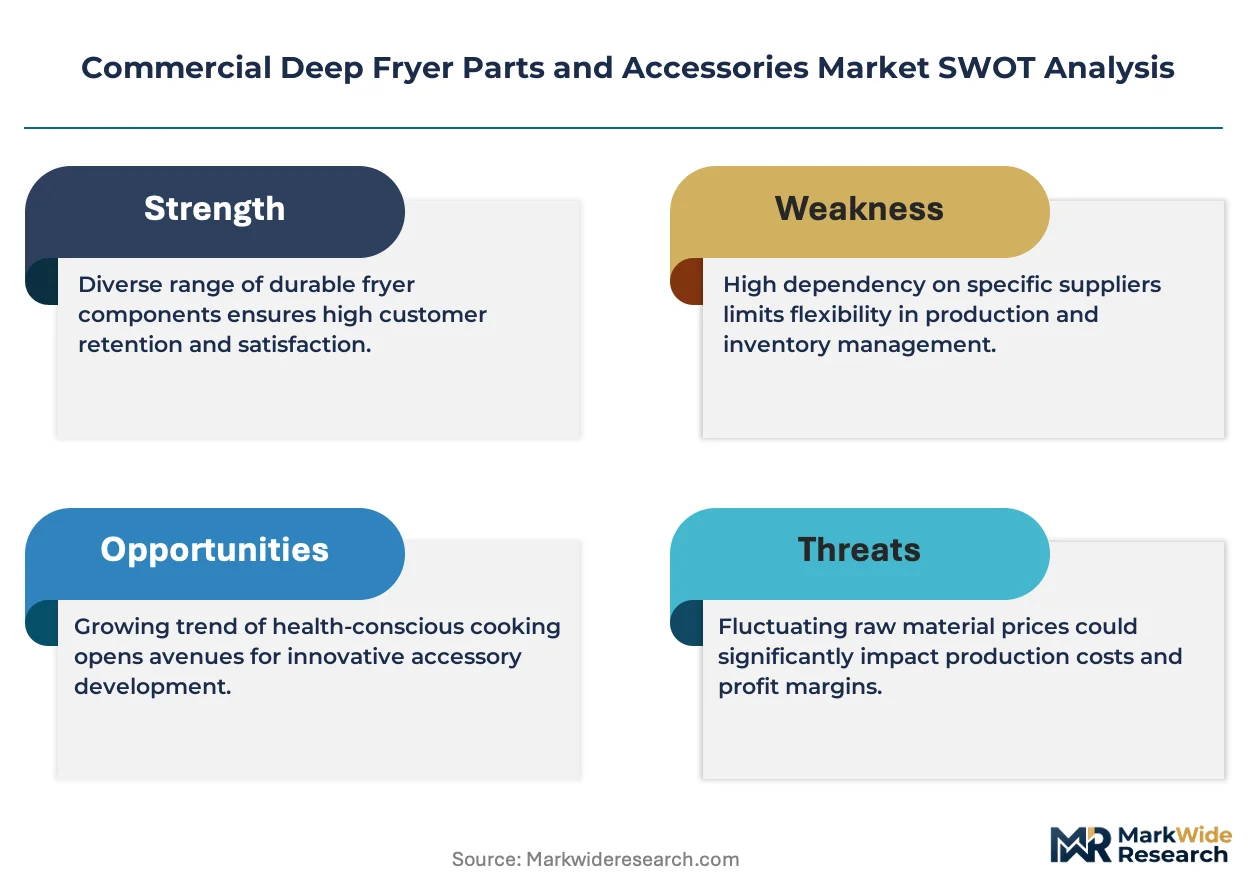
- Underpenetrated Food Truck Segment:Permitting rates for mobile food operations in Texas, Florida, and Georgia outpace fixed-location growth, creating demand for compact filtration accessories and portable oil disposal units.
- Sustainability-Driven Redesign:Integrated oil recycling accessories gain share as kitchen redesigns prioritize closed-loop waste management aligned with EPA 40 CFR Part 279 compliance.
- IoT-Enabled Monitoring Convergence:Connected temperature sensors and predictive maintenance software create attach-rate opportunities for smart thermostat assemblies in high-volume frying environments.
Industry Challenges
- Certification Timeline Compression:NSF International material safety and cleanability specifications require extended validation cycles for new food-contact surface designs, delaying product launches.
- Integration Complexity:Aftermarket filtration systems must interface with proprietary fryer architectures without voiding manufacturer warranties, constraining design flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Deep Fryer Parts and Accessories Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Heating Elements, Thermostats, Filtration Systems, Safety Valves Material: Stainless Steel, Aluminum, Copper, Non-Stick Coating Accessory Type: Baskets, Covers, Oil Disposal Units, Racks Usage Context: Restaurants, Cafes, Catering Services, Food Trucks |
| Companies Covered | ITW Food Equipment Group, Frymaster, Henny Penny Corporation, The Middleby Corporation, Welbilt Inc., Electrolux Professional, Taurus Group, Avantco Equipment, National Presto Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Deep Fryer Parts and Accessories Market Strategic Shifts
Active transformation in commercial frying equipment centers on modular subsystem design, predictive maintenance integration, and regulatory-driven material upgrades. These forces reconfigure how operators evaluate lifecycle costs against upfront capital deployment.
Modular heating element architectures are decomposing traditional integrated fryer designs into swappable subcomponents. High-volume operators in quick-service chains now specify field-replaceable element cartridges rather than full-unit replacement. This shift compresses downtime costs while expanding the addressable aftermarket for component suppliers.
The U.S. EPA's used oil management regulations under 40 CFR Part 279 mandate documented disposal chains for commercial kitchens. Operators must install integrated recycling accessories or contract certified haulers, reshaping capital allocation toward disposal infrastructure. Full-service restaurants face the steepest compliance burden due to lower throughput and thinner margins.
Food truck operators and ghost kitchen facilities now prioritize rapid-install accessory bundles over individual component sourcing. Distributors respond with pre-configured filtration and disposal kits targeting mobile and compact installations. This pattern concentrates in the southern United States where permitting velocity and real estate constraints favor flexible kitchen configurations.
Commercial Deep Fryer Parts and Accessories Market Segmentation
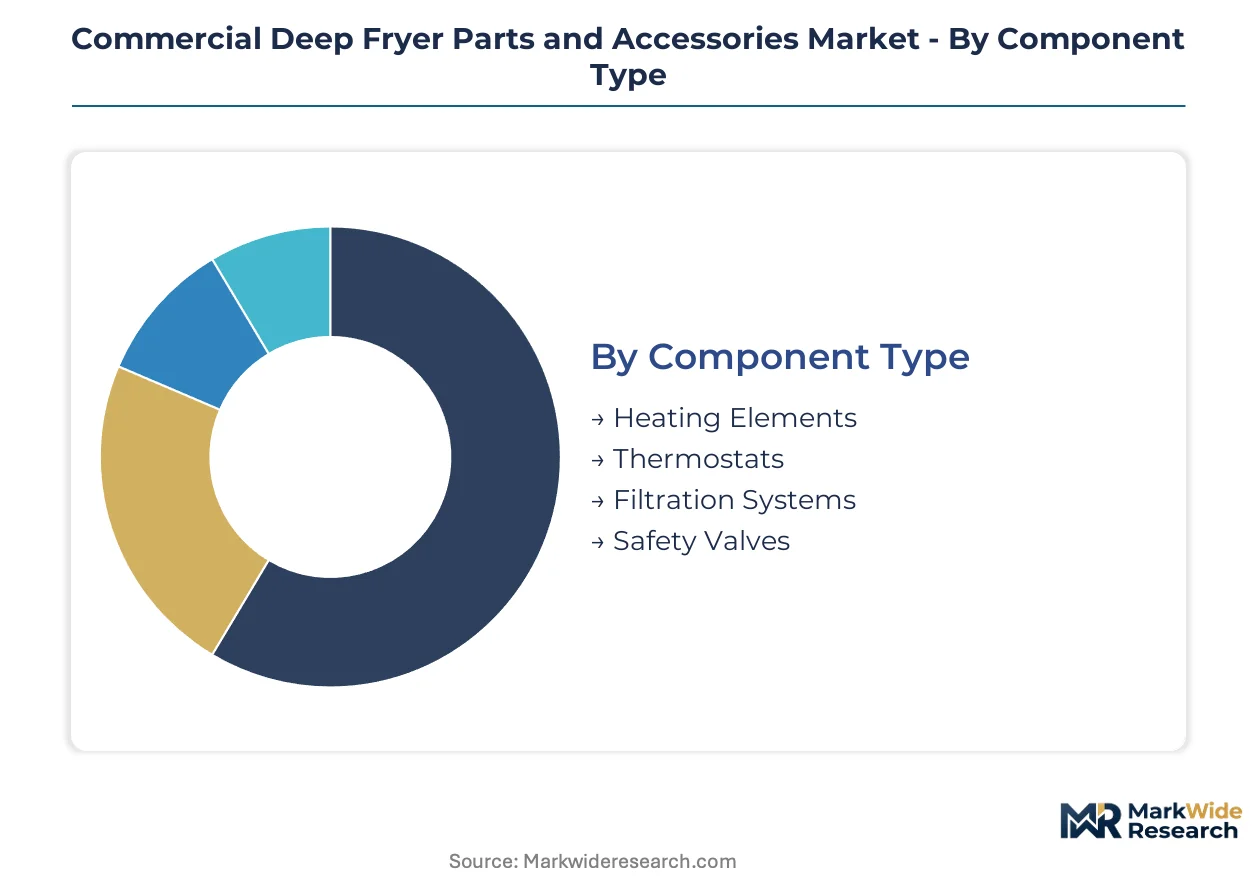
Component selection in commercial deep fryer parts and accessories follows strict material certification and thermal performance requirements. Segmentation reveals how regulatory pressure on oil quality and energy efficiency reshapes procurement patterns across equipment subsystems.
Component Type:
FDA Food Code oil quality mandates and NSF material safety standards differentiate component demand by forcing simultaneous upgrades across interconnected subsystems.
- Heating Elements:Rated between 3 kW and 24 kW, these stainless steel subsystems deliver thermal fatigue resistance required for continuous oil temperature control. Quick-service chains in Texas and Florida specify field-replaceable cartridges to compress downtime during fleet refresh cycles.
- Filtration Systems:Sediment-filtration cartridges and integrated recycling accessories now face mandatory installation timelines under inspection-driven compliance schedules. Southern U.S. chain restaurants drive concentrated procurement windows as operators synchronize upgrades with equipment replacement.
- Thermostats:Bimetallic and gas thermostat assemblies regulate temperature precision across high-volume frying environments.
- Safety Valves:Pressure-rated valves prevent thermal runaway in commercial installations subject to OSHA and local fire code inspections.
Heating elements handle the majority of throughput; filtration systems are climbing the fastest on share.
Material:
Cost tiers separate NSF-certified food-contact surfaces from standard industrial grades, with thermal performance specifications driving premium positioning.
- Stainless Steel:NSF-compliant grades dominate component-type revenue due to cleanability certification and corrosion resistance under continuous thermal cycling. EPA 40 CFR Part 279 disposal regulations reinforce demand for durable materials that extend replacement intervals.
- Aluminum:Lower thermal mass suits compact food truck installations where weight constraints and permitting velocity prioritize portability over longevity.
- Copper:Superior thermal conductivity positions this material in precision thermostat assemblies for high-end frying equipment.
- Non-Stick Coating:Food-contact surface treatments face extended NSF validation cycles that delay product launches for new formulations.
Stainless steel commands the volume base; aluminum is expanding most quickly in mobile applications.
Accessory Type:
Application context determines whether operators prioritize durability, rapid installation, or closed-loop waste management in accessory procurement.
- Baskets:Wire mesh configurations in standard and jumbo sizes occupy mature margin pools with limited differentiation across quick-service and full-service segments.
- Oil Disposal Units:Integrated recycling accessories gain share from sustainability-driven kitchen redesigns aligned with EPA 40 CFR Part 279 compliance requirements. Ghost kitchen facilities in Georgia and Texas specify compact units for flexible configurations.
- Covers:Insulated and standard covers reduce thermal loss during idle periods in high-throughput environments.
- Racks:Drainage and storage racks support batch frying workflows in catering and institutional settings.
Baskets maintain the installed base; oil disposal units show the steepest expansion trajectory.
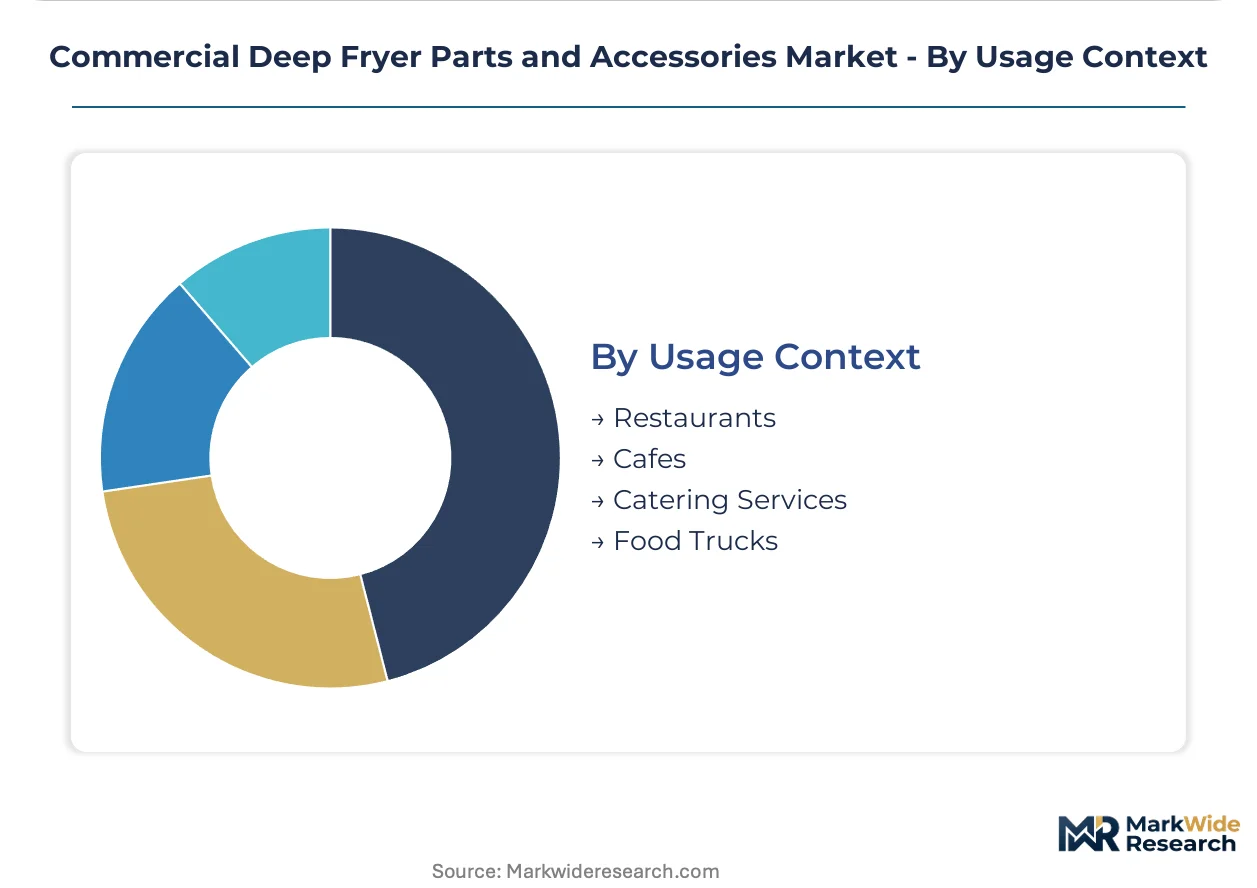
Usage Context:
Customer type segments by capital deployment rhythm, with fleet-scale operators compressing replacement demand into synchronized procurement windows.
- Restaurants:Quick-service chains accelerate fryer fleet replacements across the southern United States, creating demand spikes for heating elements, thermostats, and filtration systems. Full-service operators face collapsing maintenance budgets that shift volume toward essential safety components.
- Food Trucks:Permitting rates in Texas, Florida, and Georgia outpace fixed-location growth, driving demand for compact filtration accessories and portable oil disposal units. Mobile operators prioritize rapid-install bundles over individual component sourcing.
- Cafes:Limited frying volumes constrain accessory replacement frequency to inspection-driven timelines.
- Catering Services:Event-based throughput patterns favor durable basket and rack configurations over continuous-duty subsystems.
Restaurants absorb the dominant share of component volume; food trucks are gaining share fastest on permitting velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Houston's container throughput underwrites Texas's position as the dominant logistics hub for commercial kitchen equipment distribution across the southern United States.
United States
Quick-service restaurant chains in Texas, Florida, and Georgia are accelerating fryer fleet replacements, creating synchronized procurement windows for heating elements and filtration systems. The FDA's Food Code updates on oil quality management compel operators to install higher-grade filtration cartridges under inspection-driven timelines. Atlanta's concentration of chain restaurant headquarters drives centralized purchasing decisions for standardized component specifications.
Germany
German commercial kitchen operators prioritize NSF-compliant stainless steel components for thermal fatigue resistance in high-throughput environments. The EU's F-Gas Regulation and national energy efficiency mandates pressure retrofit eligibility for legacy fryer configurations. Bavaria's industrial fabrication clusters supply precision thermostat assemblies to central European aftermarket channels.
China
Domestic quick-service expansion and export manufacturing capacity concentrate demand for cost-optimized heating elements and accessory bundles. The country's national food safety regulator enforces material certification requirements for food-contact surfaces in commercial installations. The Yangtze River Delta manufacturing corridor produces standardized component volumes for regional distribution networks.
Japan
Japanese operators emphasize precision temperature control systems for high-end frying equipment in compact urban kitchen configurations. METI energy efficiency standards and JIS material specifications govern component selection for commercial installations. The Kansai region's precision manufacturing base supplies specialized thermostat assemblies to domestic and export markets.
Commercial Deep Fryer Parts and Accessories Market Competitive Environment
Concentration sits with integrated equipment manufacturers that control captive distribution networks for OEM replacement channels. The vendor base fragments across regional aftermarket suppliers and specialized component fabricators competing on material certification and thermal performance specifications. Three archetypes dominate: integrated fryer manufacturers with captive parts divisions, independent component specialists focused on NSF-certified stainless steel subsystems, and regional distributors bundling rapid-install accessory kits. Competitive moves center on strategic partnerships with chain restaurant procurement divisions and portfolio diversification into IoT-enabled monitoring subsystems.
Among North American integrated manufacturers, Frymaster and Henny Penny Corporation exemplify the captive-channel archetype, while Electrolux Professional represents European aftermarket supply through regional service partnerships. These companies anchor their respective geographic markets by controlling technical specifications and installation protocols that constrain independent supplier access.
| Leading Market Players |
|---|
| ITW Food Equipment Group |
| Frymaster |
| Henny Penny Corporation |
| The Middleby Corporation |
| Welbilt Inc. |
| Electrolux Professional |
| Taurus Group |
| Avantco Equipment |
| National Presto Industries |
| Others |
Value Chain & Pricing Dynamics
NSF International material safety and cleanability specifications gate both supplier qualification and price differentiation simultaneously, forcing component fabricators into extended validation cycles that compress margin flexibility while allowing certified manufacturers to command structural premiums over uncertified competitors.
Pricing Analysis
Volume-discount tiering structures dominate procurement between quick-service chains and OEM replacement channels, with fleet-scale operators extracting 15-25 point spreads over independent restaurant buyers. Price differentiation hinges on NSF certification grade and thermal performance specifications, with stainless steel heating elements rated above 12 kW commanding measurable premiums. Cost compression in standard-grade components is intensifying because nickel and chromium price volatility feeds directly into input economics. Quick-service chains exhibit lowest price sensitivity due to synchronized fleet refresh budgets, while food truck operators and independent full-service restaurants face acute margin constraints.
Supply Chain Analysis
Strait of Malacca transit underwrites raw material flows for Asian component fabrication, with supply concentration in China, South Korea, and Germany shaping global availability of precision thermostat assemblies and NSF-certified stainless steel substrates. Raw material dependencies center on nickel ore from Indonesia, chromium from South Africa, and specialized bimetallic strips from Japanese precision metalworkers. Single-source vulnerability concentrates in gas thermostat assemblies where Henny Penny Corporation maintains technical specification control. Distribution runs through captive OEM networks for chain restaurant procurement, while independent aftermarket suppliers rely on regional distributor bundling for food truck and ghost kitchen segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial deep fryer parts and accessories markets are entering a cyclical recovery phase as quick-service restaurant capital expenditure rebounds from pandemic-depressed maintenance budgets and FDA inspection timelines normalize replacement demand.
For Market Incumbents: Consolidate captive distribution networks against emerging IoT-enabled monitoring specialists by deepening backward integration into stainless steel heating element fabrication and securing exclusive service partnerships with top-10 quick-service chain procurement divisions. Lock in multi-year filtration cartridge supply agreements before state-level energy efficiency mandates disqualify legacy fryer configurations from retrofit eligibility.
For New Entrants and Emerging Players: NSF certification fast-tracks for compact oil disposal units open immediate access to food truck permitting surges in Texas, Florida, and Georgia where mobile operators prioritize rapid-install bundles over component-level sourcing. Target ghost kitchen facilities in Atlanta and Houston with pre-configured filtration and disposal kits. Lead with sustainability positioning aligned with EPA 40 CFR Part 279 compliance to differentiate against established OEM channels.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across IoT-enabled thermostat assemblies as sensor commoditization reduces hardware content requirements. Five-to-ten year viability favors acquiring regional aftermarket distributors with established chain restaurant relationships rather than component fabricators exposed to raw material volatility. Monitor FDA Food Code revision cycles as the critical inflection signal for filtration system demand spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Fabrication | Captive control over heating element production insulates margin pressure from nickel price swings. |
| IoT-Enabled Monitoring Platform Development | Smart thermostat assemblies attach predictive maintenance software to high-volume frying environments. |
| Food Truck Rapid-Install Bundle Launch | Pre-configured filtration and disposal kits address permitting velocity in Texas and Florida. |
| NSF Certification Fast-Track Investment | Accelerated validation cycles compress time-to-revenue for new food-contact surface designs. |
| Chain Restaurant Procurement Partnership | Exclusive service agreements with quick-service operators lock in synchronized fleet refresh demand. |
Study Parameters
Operator-level perspectives from quick-service chain procurement directors, food truck fleet managers, commercial kitchen maintenance contractors, and NSF certification auditors anchored the qualitative base. Primary interviews with these stakeholders combined with secondary validation against FDA Food Code regulatory filings, EPA 40 CFR Part 279 compliance databases, SEC 10-K disclosures from listed equipment manufacturers, and customs trade data for nickel and chromium imports. Bottom-up triangulation across component-level demand estimates and top-down reconciliation against aggregate capital expenditure flows ensured cross-verification.
Sensitivity analysis framing guided the analytical approach across the projection horizon, with segmentation dimensions spanning component type, material grade, accessory category, and usage context including fleet-scale versus independent operator procurement patterns. CAGRs derived from equipment replacement cycle modeling and regulatory compliance timeline analysis, incorporating oil quality mandate enforcement intensity and state-level energy efficiency adoption curves as industry-specific forecast inputs.
Underlying assumptions cover normalized quick-service restaurant capital expenditure recovery and stable nickel-chromium price corridors, with deviation risk concentrated in accelerated FDA inspection timelines or state-level grease interceptor code revisions. Practitioners should keep alternative scenarios live as regulatory enforcement intensity and raw material supply disruptions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Retail Bubble Tea Kits Market
Food Service
Food and Grocery Retail Market
Food Service
One-Off Chopsticks Market
Food Service
Global Waffle Maker Market
Food Service
Personal Chef Services Market
Food Service
United States Online Food Delivery Market
Food Service
Singapore Food Service Market
Food Service
Food Delivery Services Market
Food Service
Europe Inflight Catering Market
Food Service
US Restaurant Point of Sale Solution Market
Food Service
Europe Biodegradable Food Service Disposables Market
Food Service
Cutting Boards Market
Food Service
China Retail Bubble Tea Kits Market
Food Service
Healthy Takeout Market
Food Service
India Retail Bubble Tea Kits Market
Food Service
Street Vendors Market