
 Software License Management (SLM) Market | 2026-2036
Software License Management (SLM) Market Size, Share, and Industry Trends Forecast 2026-2036
Software License Management (SLM) Market Analytics
The EU AI Act is repositioning enterprise software governance by mandating traceable licensing for high-risk algorithmic systems. Zylo leverages subscription intelligence to anchor recurring revenue visibility for SaaS-heavy organizations. Snow License Manager specializes in compliance automation across Microsoft, Oracle, and SAP estates. ServiceNow Software Asset Management extends its platform dominance by embedding SLM into broader IT workflows.
Software License Management encompasses the systematic tracking, optimization, and compliance verification of software entitlements across on-premise, cloud, and hybrid infrastructures, typically interfacing with discovery tools that inventory installed applications against purchased licenses. Its primary commercial purpose is eliminating audit exposure, reclaiming unused subscriptions, and rationalizing vendor spend across decentralized procurement. Cloud-based deployment now captures the fastest expansion as enterprises retire perpetual licenses for elastic consumption models, while AI-driven technology segments attract disproportionate R&D investment from vendors seeking predictive renewal and anomaly detection capabilities. License Tracking offerings remain the foundational revenue pool, though Compliance Management modules command premium pricing due to regulatory penalty exposure.
The US Sarbanes-Oxley framework and SEC disclosure rules shape demand by requiring documented software asset controls for financial reporting integrity, while HIPAA obligates healthcare entities to maintain audit trails for all applications processing protected health information. The EU GDPR and emerging CSRD standards further tighten data residency and vendor accountability requirements that SLM platforms must map and enforce. Procurement leaders should evaluate whether their current tooling can automate license position reconciliation across containerized and serverless architectures before their next enterprise agreement renewal cycle.
Market Dynamics
Enterprise migration from perpetual licenses to consumption-based SaaS models is fragmenting procurement authority across departmental buyers, forcing centralized governance platforms to absorb distributed spending visibility.
Growth Catalysts
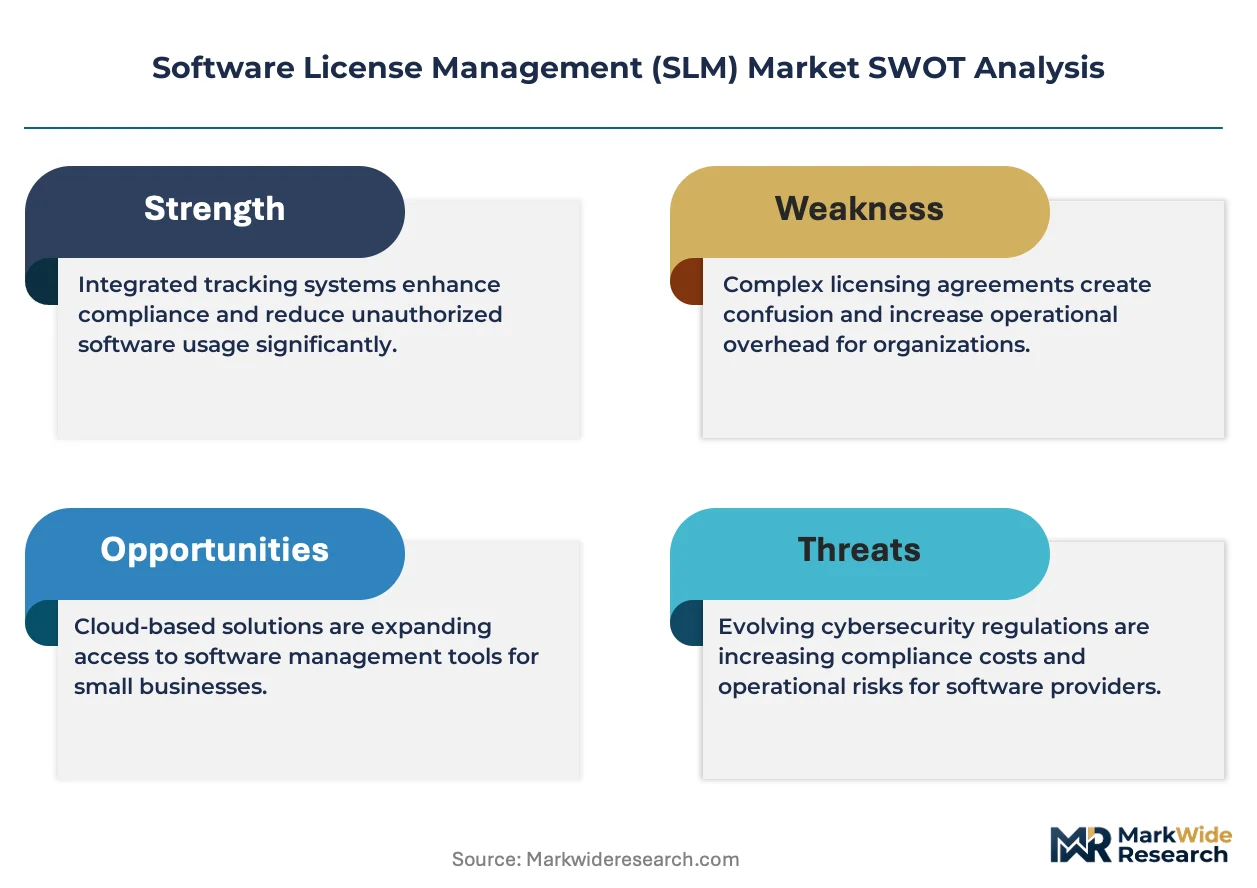
- EU AI Act compliance mandates:High-risk algorithmic systems require documented software provenance and usage rights, expanding SLM deployment across European financial services and healthcare operators.
- Container orchestration complexity:Kubernetes and serverless architectures obscure traditional license boundaries, driving demand for automated entitlement reconciliation across ephemeral compute environments.
- India's digital infrastructure scale-up:IT services exporters and domestic fintech platforms are adopting SLM to manage multi-cloud vendor portfolios and BIS cybersecurity certification requirements.
Market Restraints
- Implementation cost concentration:Enterprise-grade SLM deployments require substantial professional services investment, with total cost of ownership spanning 18-36 month payback periods.
- Vendor lock-in risk:Deep integration with Microsoft, Oracle, and SAP estates creates switching friction and limits buyer negotiating leverage during renewal cycles.
- Data residency fragmentation:Divergent national cloud sovereignty laws complicate unified license management across distributed operations.
Strategic Opportunities
- AI-driven predictive renewal:Machine learning models analyzing consumption patterns enable proactive entitlement optimization before contract expiration.
- Embedded finance expansion:Banking-as-a-Service platforms require granular license tracking for regulatory capital allocation, creating specialized SLM modules.
- Japan's operational technology convergence:METI smart manufacturing initiatives are extending SLM from IT into industrial control systems and IoT device fleets.
Industry Challenges
- Hybrid architecture skill scarcity:Shortage of professionals capable of reconciling on-premise, cloud, and edge license positions slows enterprise implementation timelines.
- API versioning complexity:Rapid SaaS platform updates create entitlement mapping drift between contractual terms and actual feature access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Software License Management (SLM) Market |
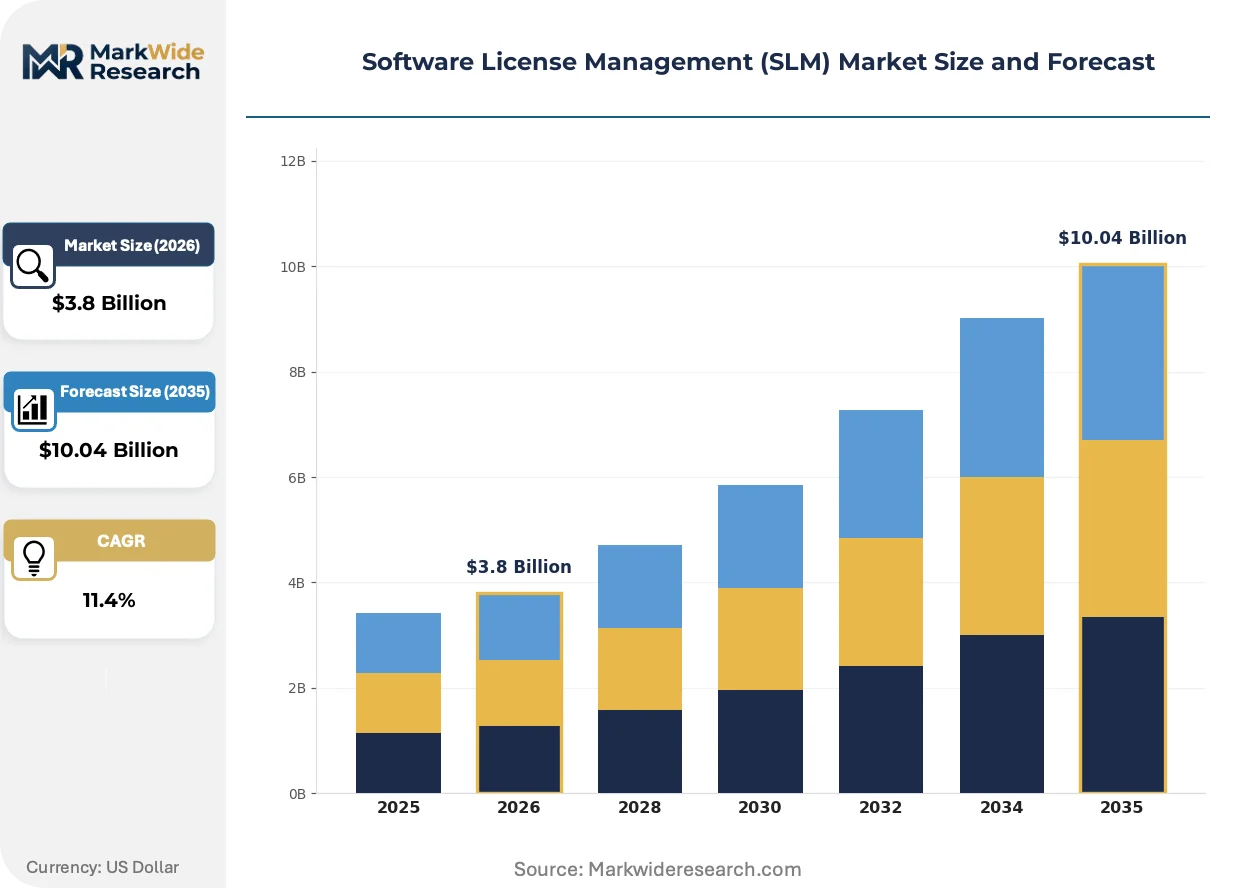
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: SMEs, Large Enterprises, Government, Educational Institutions Offering: License Tracking, Compliance Management, Analytics, Support Services Technology: AI-Driven, Machine Learning, Blockchain, Traditional Software |
| Companies Covered | ManageEngine Asset Explorer, Zylo, Stitchflow, Snow License Manager, ServiceNow Software Asset Management, Zluri, Torii, InvGate Asset Management, Flexera One IT Asset Management, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Software License Management (SLM) Market Evolving Landscape
Artificial intelligence is embedding predictive capabilities into license optimization workflows, compressing the cycle from usage discovery to contract renegotiation.
Agentic AI is automating entitlement reconciliation across containerized and serverless environments. Financial services firms with distributed multi-cloud estates are deploying these systems at scale. The technology is automating previously manual license position calculations that consumed quarterly audit cycles.
The EU CSRD mandates granular software asset disclosure for sustainability reporting, extending SLM scope beyond compliance into ESG data collection. Industrial manufacturers with complex supply chains face the steepest documentation requirements. German automotive suppliers are consolidating vendor management platforms to satisfy auditor scrutiny.
Subscription intelligence platforms now anchor recurring revenue visibility for SaaS-heavy organizations, displacing spreadsheet-based renewal tracking. Technology and healthcare conglomerates with global operations are consolidating procurement authority. United States Fortune 500 firms exhibit the fastest adoption velocity for these unified governance tools.
Software License Management (SLM) Market Segmentation
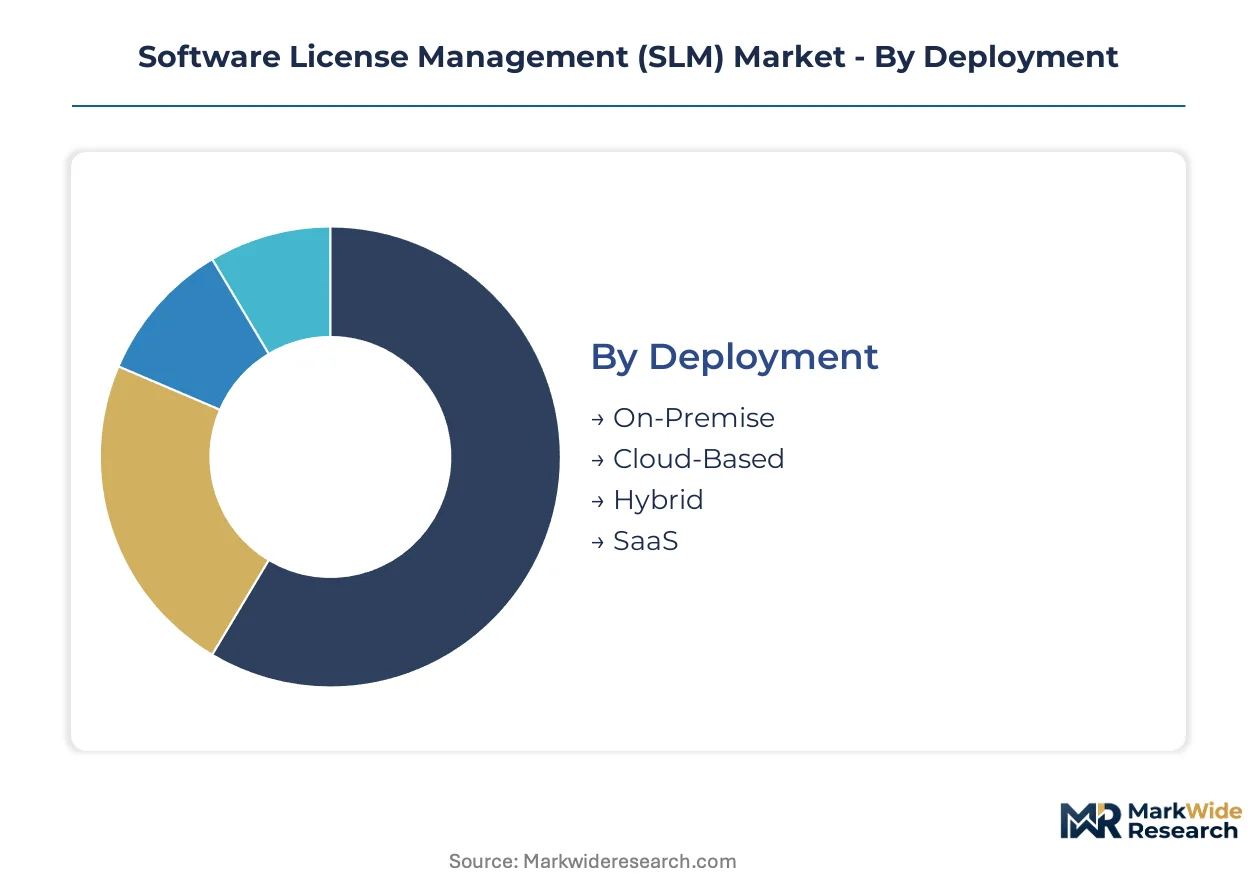
Software License Management vendors architect product portfolios around distinct technical specifications, operational scale requirements, and intelligence capabilities. Segmentation clarity enables procurement leaders to match deployment architecture with compliance complexity and consumption visibility needs.
Deployment:
Technical architecture determines integration depth, data sovereignty compliance, and total cost trajectory across enterprise estates.
- On-Premise:Installed within corporate data centers with direct control over license inventory databases and audit trail retention. Financial services firms in the United States with stringent HIPAA and SEC data localization requirements maintain these deployments for core ERP systems.
- Cloud-Based:Delivered via multi-tenant SaaS infrastructure with elastic scaling for consumption tracking across distributed workforces. Healthcare conglomerates with remote clinical staff favor this model for rapid deployment without infrastructure capital.
- Hybrid:Combines on-premise license servers with cloud analytics layers, enabling phased migration of perpetual estates while preserving legacy compliance documentation. German automotive suppliers use this architecture to satisfy EU CSRD disclosure mandates without disrupting SAP backbone systems.
- SaaS:Native subscription delivery with API-first integration into procurement and finance systems, automating renewal workflows for elastic consumption models. Technology sector buyers with high vendor turnover rates prioritize this deployment for real-time spend visibility.
Cloud-Based leads on scale; SaaS leads on momentum.
End User:
Organizational scale and regulatory exposure shape feature requirements, implementation timelines, and pricing tolerance.
- SMEs:Typically deploy lightweight license tracking with standardized connectors to Microsoft and Google workspaces. Budget constraints drive preference for SaaS delivery with minimal professional services.
- Large Enterprises:Require multi-domain governance spanning on-premise Oracle databases, AWS container estates, and SaaS application portfolios. Compliance Management modules command premium pricing due to audit penalty exposure across Fortune 500 technology and healthcare conglomerates.
- Government:Mandates FedRAMP or equivalent certification with air-gapped deployment options for classified environments. Procurement cycles extend 18-24 months with emphasis on vendor longevity.
- Educational Institutions:Manage complex volume licensing agreements with Microsoft, Adobe, and specialized research software vendors. Site-wide entitlements and seasonal enrollment fluctuations create unique reconciliation challenges.
Large Enterprises dominate current revenue; SMEs represent the steepest expansion trajectory.
Offering:
Functional modules align with distinct risk categories: operational efficiency, regulatory exposure, and strategic decision support.
- License Tracking:Foundational inventory reconciliation comparing discovered installations against purchased entitlements. Remains the largest revenue pool though facing commoditization pressure from native vendor tools.
- Compliance Management:Automated audit preparation, true-up calculations, and penalty risk quantification for Microsoft, Oracle, and SAP estates. Commands premium pricing due to direct liability reduction.
- Analytics:Consumption pattern analysis, renewal forecasting, and vendor spend benchmarking. AI-driven predictive capabilities are displacing spreadsheet-based renewal tracking.
- Support Services:Professional implementation, license position reconciliation, and contract negotiation advisory. Required for complex hybrid architectures with 18-36 month payback periods.
License Tracking anchors volume; Compliance Management captures margin.
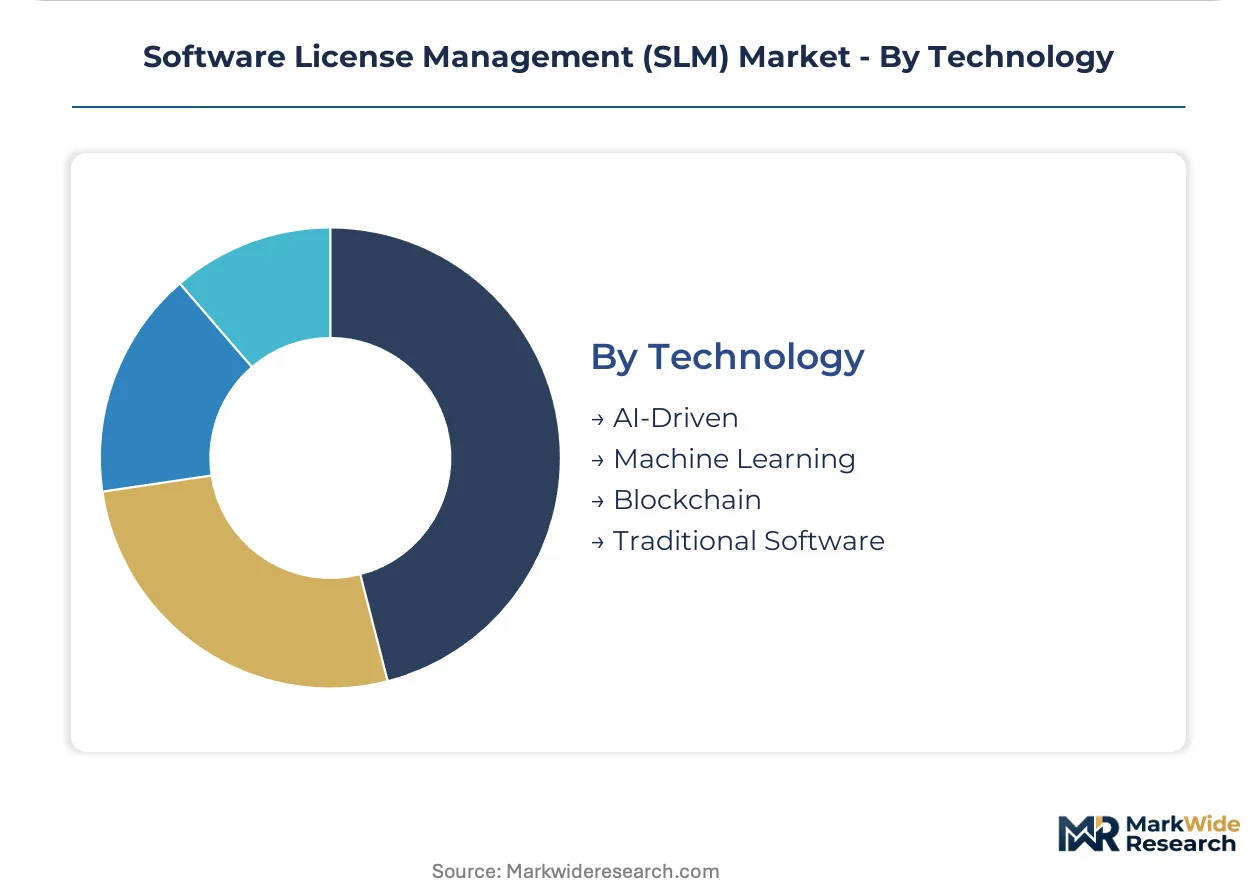
Technology:
Intelligence layer differentiation determines automation depth and predictive accuracy across ephemeral compute environments.
- AI-Driven:Agentic systems automating entitlement reconciliation across Kubernetes and serverless architectures without manual intervention. Financial services firms with distributed multi-cloud estates deploy these at scale.
- Machine Learning:Pattern recognition models analyzing historical consumption to forecast renewal requirements and identify optimization opportunities before contract expiration.
- Blockchain:Immutable license provenance records for high-risk algorithmic systems under EU AI Act documentation mandates. European operators in healthcare and financial services pilot these for audit defensibility.
- Traditional Software:Rule-based engines with manual configuration for license metric definitions and reconciliation logic. Retained by conservative buyers with stable, non-containerized estates.
Traditional Software retains installed base; AI-Driven gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The software license management industry traces its commercial origins to United States enterprise software auditing practices of the 1990s, with early compliance tools emerging from Silicon Valley vendor management consulting engagements before migrating to cloud-native architectures.
United States
Fortune 500 technology and healthcare conglomerates with distributed global operations anchor North American demand for unified governance platforms. The SEC disclosure rules and Sarbanes-Oxley framework mandate documented software asset controls for financial reporting integrity. Greater Boston's biotech cluster deploys SLM systems to maintain HIPAA audit trails for applications processing protected health information.
Germany
Automotive suppliers and industrial manufacturers drive European adoption amid stringent documentation requirements. The EU CSRD mandates granular software asset disclosure for sustainability reporting, extending SLM scope into ESG data collection. Bavaria's automotive supply chain is consolidating vendor management platforms to satisfy auditor scrutiny under these disclosure mandates.
United Kingdom
Financial services firms with multi-cloud estates require automated entitlement reconciliation across ephemeral compute environments. The UK Information Commissioner's Office enforces GDPR-aligned data residency requirements that SLM platforms must map and enforce. London's fintech corridor deploys subscription intelligence tools to anchor recurring revenue visibility for SaaS-heavy operations.
India
IT services exporters and domestic fintech platforms are scaling adoption to manage multi-cloud vendor portfolios. BIS cybersecurity certification requirements and RBI operational guidelines compel documented software provenance for financial infrastructure. Bengaluru's technology services cluster integrates license tracking across containerized architectures serving global enterprise clients.
Japan
Smart manufacturing initiatives are extending SLM from IT systems into industrial control environments. METI operational technology convergence programs mandate license tracking for IoT device fleets and automated production lines. The Nagoya industrial corridor deploys hybrid architectures to reconcile on-premise legacy systems with cloud analytics layers.
Software License Management (SLM) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across compliance automation depth and AI-driven predictive capabilities. The vendor base organizes into three tiers: platform-native suites from IT service management incumbents, specialized license optimization pure-plays, and emerging subscription intelligence challengers. Consolidation pressure favors vendors with embedded finance workflows and container-native entitlement reconciliation. Competitive moves concentrate on strategic partnerships with hyperscale cloud providers and portfolio diversification into adjacent IT asset management domains.
Within the subscription intelligence tier, Zylo and Torii exemplify vendors anchoring recurring revenue visibility for SaaS-heavy organizations. Zylo leverages consumption analytics to compress renewal cycles, while Torii occupies a position among Israeli-founded specialists automating distributed procurement authority. Snow License Manager represents the compliance automation archetype, with ServiceNow Software Asset Management sitting within the platform extension tier that embeds SLM into broader IT workflows. These three anchors illustrate how competitive positioning stratifies across technical specialization rather than geographic scale.
| Leading Market Players |
|---|
| ManageEngine Asset Explorer |
| Zylo |
| Stitchflow |
| Snow License Manager |
| ServiceNow Software Asset Management |
| Zluri |
| Torii |
| InvGate Asset Management |
| Flexera One IT Asset Management |
| Others |
Value Network & Pricing Analysis
Enterprise software licensing cost indices cascade through vendor ecosystems into three distinct pricing tiers: premium compliance automation suites, mid-market subscription intelligence platforms, and economy-tier license tracking tools. This cost structure shapes procurement decisions across Fortune 500 technology conglomerates and healthcare operators managing distributed global estates.
Pricing Analysis
Subscription-based SaaS pricing with tiered feature entitlements anchors vendor revenue models across the SLM landscape. Price differentiation rests on compliance depth and AI-driven predictive capabilities rather than raw license volume. Cost compression in the mid-tier is intensifying because native vendor tools are commodifying basic inventory tracking. SMEs exhibit the highest price sensitivity, while large enterprises with Oracle and SAP audit exposure tolerate premium pricing for liability reduction.
Supply Chain Analysis
Single-source vulnerability sits with hyperscale cloud infrastructure providers concentrated in the United States, Ireland, and Singapore. Software delivery draws from container orchestration platforms, API gateway services, and identity management systems. Regulatory fragmentation across EU AI Act documentation mandates and US HIPAA data residency requirements creates compliance chokepoints. Distribution runs through direct enterprise sales teams with embedded professional services for complex hybrid deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SLM market reads as a late-cycle quality story. Procurement leaders are consolidating vendor relationships toward unified governance platforms with embedded compliance automation.
For Market Incumbents: Hedge against platform-native competition from IT service management suites by deepening API-first integration capabilities. Acquire specialized container-native entitlement reconciliation providers before hyperscalers bundle comparable functionality. Vertical integration into adjacent IT asset management domains preserves margin structure. For New Entrants and Emerging Players: EU AI Act compliance mandates in Germany and France open a window for blockchain-based license provenance tools targeting high-risk algorithmic system documentation. White-space concentration sits with Indian IT services exporters managing multi-cloud portfolios for global clients. A channel partnership strategy with hyperscaler marketplaces accelerates customer acquisition without direct enterprise sales investment. For Investors and Strategic Acquirers: Asymmetric upside sits with AI-driven predictive renewal platforms serving financial services firms with distributed multi-cloud estates. Long-term viability favors vendors with embedded finance workflows and container-native architectures. Monitor EU CSRD disclosure enforcement intensity as an inflection indicator for ESG data collection module demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding SLM into broader IT workflows captures ServiceNow's dominance pattern across Fortune 500 accounts. |
| Acquisition of Specialist Firm | Container-native entitlement reconciliation capabilities address Kubernetes license boundary opacity for financial services operators. |
| Strategic Partnership | Hyperscaler marketplace listings accelerate SME penetration without proportional sales force expansion. |
| Geographic Expansion | India's BIS cybersecurity certification requirements create localized product adaptation opportunities for IT services exporters. |
| Product Launch | AI-driven predictive renewal modules displace spreadsheet-based tracking in technology sector buyers with high vendor turnover. |
Research Methodology
Multiple input streams — primary interviews with CTOs and IT procurement officers, secondary validation against hyperscaler capex disclosures and SEC filings, and technical documentation review — were reconciled to construct market estimates. Conversations with platform engineers, channel partners, and integration specialists informed deployment model segmentation. Bottom-up vendor revenue analysis and top-down enterprise spend allocation triangulated volume and value outputs.
Data-stream reconciliation across deployment architecture, organization size, vertical industry, and regional adoption pattern enabled granular forecasting. CAGRs were derived from trend extrapolation moderated by implementation timeline constraints and professional services capacity limitations. Container orchestration penetration rates and EU regulatory enforcement calendars served as industry-specific calibration inputs across the modeling period.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated cloud sovereignty legislation or hyperscaler bundling of native license management tools. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Back Testing Software Market
Software & Services
Talent Acquisition Software Market
Software & Services
Global Programming Software Market
Software & Services
Global Open Source Services Market
Software & Services
Global Intellectual Property Management Software Market
Software & Services
Classified Platform Market
Software & Services
Medical E-Commerce Software Market
Software & Services
Dealer Management System Market
Software & Services
Global Product Management and Road Mapping Tool Market
Software & Services
Automation Test Software Market
Software & Services
Compositing Software Market
Software & Services
Global Database Software Market
Software & Services
Global Java Web Frameworks Software Market
Software & Services
HSM-As-A-Service Market
Software & Services
Lighting Control Software Market
Software & Services
Global Campaign Management Software Market