
 Bridge Analysis Software Market | 2026-2036
Bridge Analysis Software Market Size, Share, and Industry Trends Forecast 2026-2036
Bridge Analysis Software Market Outlook
Modular bundling of finite element analysis with cloud-based deployment is recalibrating how construction firms evaluate procurement options. Bentley Systems leverages deep specialization in civil engineering workflows to anchor its position among infrastructure owners. Autodesk competes through extensive R&D intensity in computational design platforms. Trimble differentiates by integrating geospatial hardware with structural software ecosystems.
Bridge analysis software encompasses computational tools that apply numerical methods—finite element meshing, load distribution algorithms, and material nonlinear modeling—to predict structural behavior under traffic, seismic, and environmental loading. These platforms primarily serve engineers in verifying code compliance and optimizing maintenance schedules for steel and concrete spans. Finite element analysis commands the largest margin pool due to its complexity and certification requirements, while cloud-based deployment represents the fastest-expanding configuration as agencies modernize IT infrastructure. Load testing applications remain mature in North America and Western Europe, where established bridge inventories sustain steady renewal demand.
The Federal Highway Administration enforces National Bridge Inspection Standards that mandate documented structural evaluations, directly stimulating software procurement across U.S. state departments of transportation. Eurocodes and the EU Green Deal impose lifecycle carbon accounting requirements that expand the functional scope of analysis platforms in Europe. Stakeholders must monitor evolving building information modeling mandates and determine whether to build captive cloud infrastructure or rely on vendor-hosted environments.
Market Dynamics
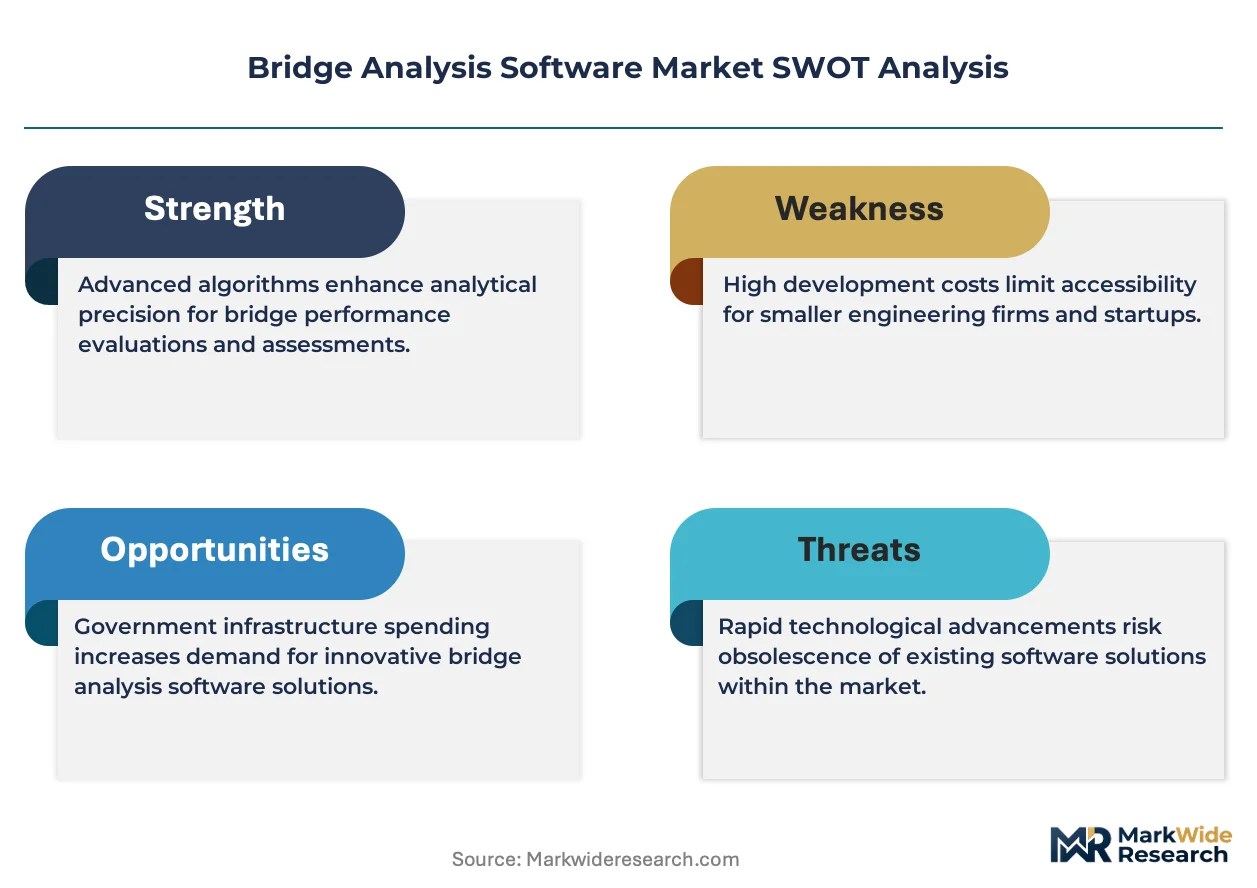
Cloud migration mandates from transportation agencies are compressing deployment timelines for bridge analysis platforms, forcing vendors to rearchitect licensing models around subscription-based finite element solvers.
Growth Catalysts
- Federal Highway Administration mandates:National Bridge Inspection Standards require documented structural evaluations, compelling state departments of transportation to procure certified analysis software.
- EU Green Deal lifecycle requirements:Eurocodes now embed carbon accounting for aging infrastructure, expanding software functionality to cover embodied emissions calculations.
- Digital twin adoption:German federal highway authorities prioritize physics-based bridge models for predictive maintenance scheduling, creating concentrated demand for real-time sensor integration capabilities.
Market Restraints
- Specialized engineering talent scarcity:Finite element meshing expertise concentrates among licensed structural engineers, limiting implementation velocity for mid-size civil firms.
- Certification timeline friction:Eurocode compliance validation for nonlinear material models extends product release cycles by 18-24 months.
- Legacy data silos:Proprietary file formats from 1990s-era CAD systems obstruct seamless model handoff between inspection contractors and design consultants.
Strategic Opportunities
- Geospatial-structural convergence:Integration of LiDAR point clouds with finite element pre-processors enables as-built model generation without manual surveying.
- Subscription model penetration:Perpetual license holders in North America represent a conversion opportunity as IT modernization budgets favor operational expenditure structures.
- Resilience engineering modules:Climate adaptation requirements from the EU Green Deal create white space for flood-load and thermal-expansion analysis tools.
Industry Challenges
- Interoperability complexity:Building information modeling mandates require bidirectional data exchange with asset management systems, demanding costly API development.
- Computational infrastructure capex:High-fidelity seismic simulations require GPU clusters that strain municipal engineering department budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bridge Analysis Software Market |
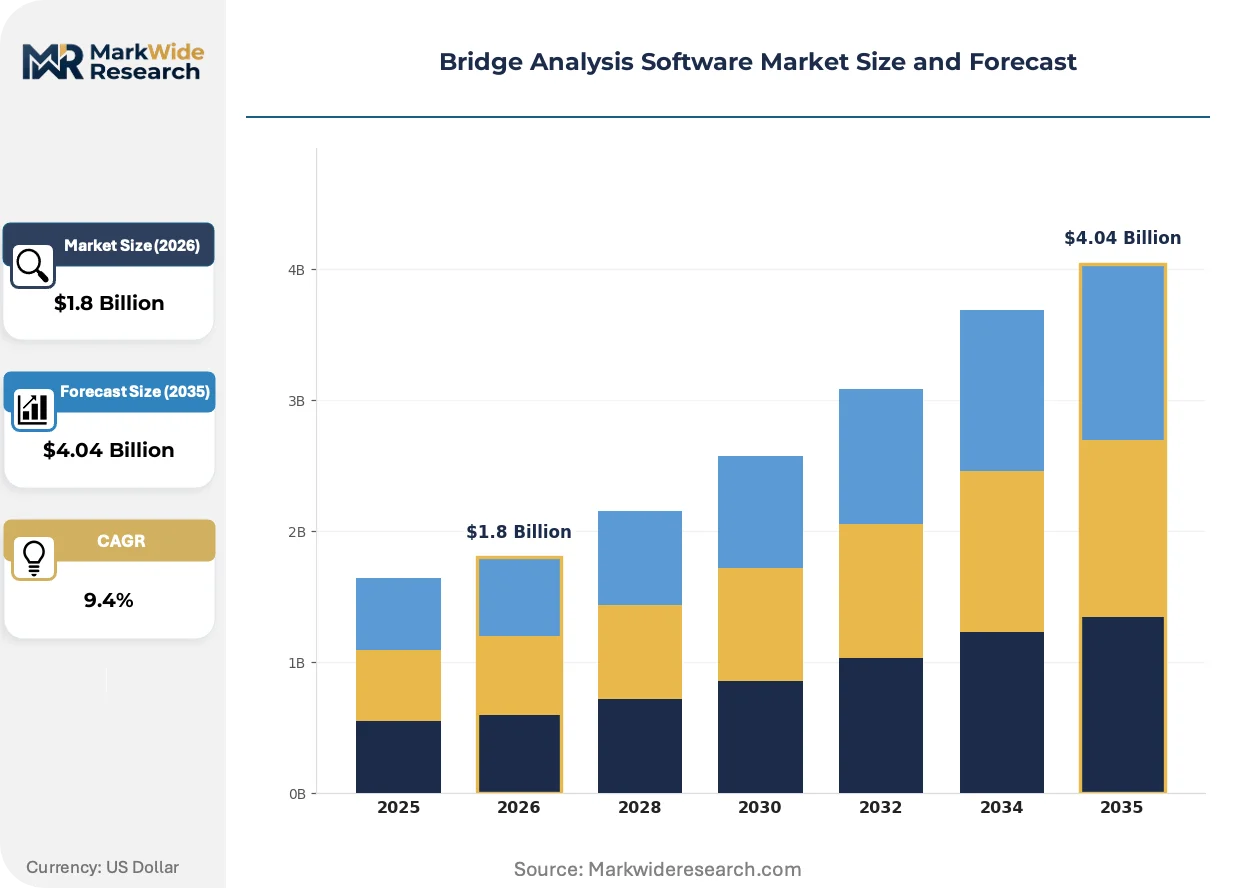
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
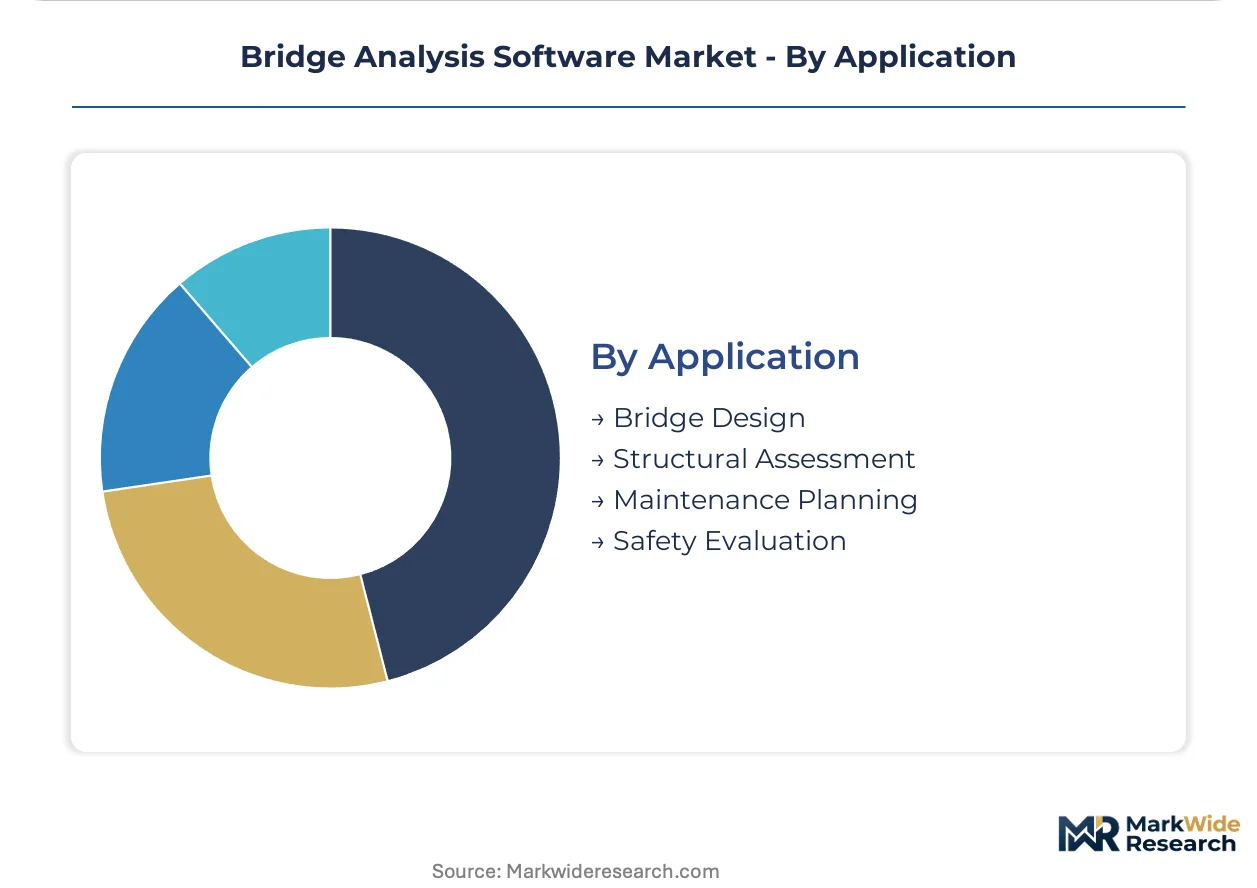
| Segmentation | Product Type: Beam Analysis, Truss Analysis, Load Testing, Finite Element Analysis End User: Civil Engineers, Construction Firms, Government Agencies, Consulting Firms Deployment: On-Premises, Cloud-Based, Hybrid, SaaS Application: Bridge Design, Structural Assessment, Maintenance Planning, Safety Evaluation |
| Companies Covered | Bentley Systems, Autodesk, Trimble, AECOM, WSP Global, SAP SE, Oracle Corporation, IBM Corporation, AgileAssets, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bridge Analysis Software Market Strategic Shifts
Computational methods are migrating toward real-time structural monitoring, blurring the boundary between design-phase analysis and operational asset management. This convergence demands new architectural approaches from software architects.
Physics-informed machine learning is rewriting how engineers approach surrogate modeling for complex load cases. State transportation agencies in California and Texas are piloting neural-network-based response predictions for seismic vulnerability screening. The technology is compressing analysis turnaround from hours to minutes for preliminary design iterations.
REACH and the EU AI Act are imposing algorithmic transparency requirements on automated structural assessment tools. Vendors must now document training data provenance and decision boundaries for machine learning modules used in safety-critical calculations. European infrastructure owners are responding by demanding explainable AI features in procurement specifications.
Engineering consultancies are unbundling software licenses from professional services, selling analysis capacity rather than seat subscriptions. Municipal bridge owners in the Pacific Northwest increasingly procure cloud-hosted solver hours through usage-based contracts. This model shifts vendor revenue recognition and accelerates price competition among platform providers.
Bridge Analysis Software Market Segmentation
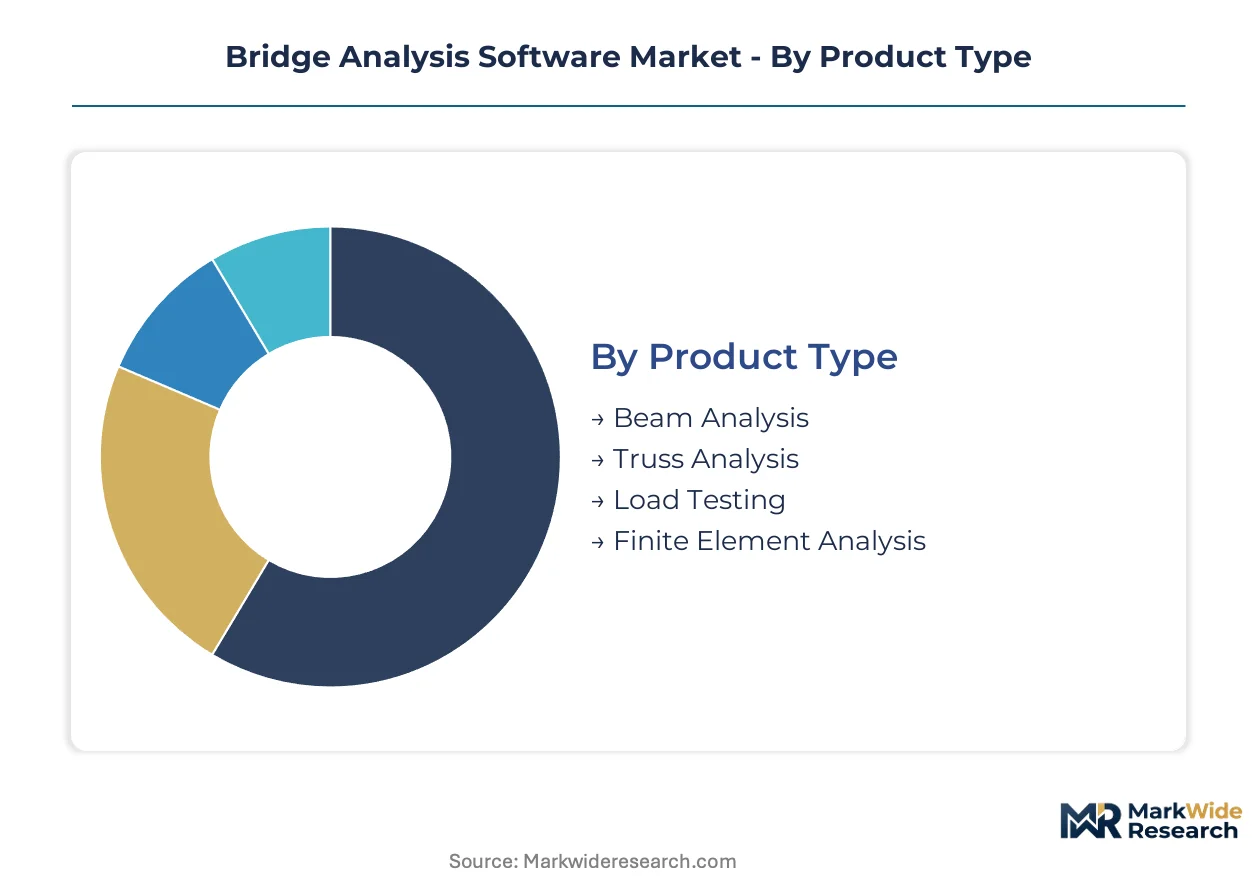
Bridge analysis software procurement patterns diverge sharply across engineering disciplines and infrastructure ownership models. Deployment configurations and analytical methodologies segment buyer priorities in ways that reshape vendor go-to-market strategies.
Product Type:
Engineering firms select analytical tools based on project complexity thresholds and certification requirements for specific bridge typologies.
- Beam Analysis:Linear elastic solvers handle simply-supported and continuous girder configurations for routine highway overpass evaluations. State departments of transportation in the United States specify these tools for standardized inventory ratings where code-checking automation outweighs modeling sophistication.
- Finite Element Analysis:Nonlinear meshing engines resolve stress concentrations at cable anchorages, orthotropic deck details, and seismic isolation bearings. German federal highway authorities mandate FEA certification for major river crossing assessments, concentrating demand among specialized structural consultancies.
- Truss Analysis:Pin-jointed frame solvers serve heritage railway bridge evaluations and pedestrian cable-stayed structures. Historic preservation agencies in France and Italy drive niche procurement for wrought-iron arch assessments.
- Load Testing:Diagnostic platforms correlate strain gauge measurements with analytical predictions for post-event damage quantification. Emergency response protocols in California and Japan sustain steady deployment following seismic events.
Finite element analysis leads volumes today; beam analysis is gaining share fastest through cloud-enabled subscription models.
End User:
Budget authority and risk tolerance separate infrastructure owners from contracted engineering services.
- Government Agencies:Federal and state transportation departments procure certified platforms through multi-year enterprise agreements. The Federal Highway Administration's National Bridge Inspection Standards mandate documented analytical workflows, locking in procurement cycles.
- Civil Engineers:Licensed practitioners operating within design-build consortia require seat-based licenses with interoperability across CAD and BIM environments. Eurocode compliance validation concentrates purchasing decisions among senior technical reviewers.
- Construction Firms:EPC contractors prioritize temporary works analysis and erection sequencing simulations. Major infrastructure projects in the United Kingdom and Australia drive concentrated demand for staged construction modeling.
- Consulting Firms:Specialized structural practices sell analysis capacity through professional services engagements. Independent verification mandates for public-private partnership bridges in Canada sustain premium solver procurement.
Government agencies dominate current procurement value; consulting firms are expanding their software footprints most aggressively.
Deployment:
IT modernization timelines and data sovereignty requirements dictate architectural preferences across infrastructure owner categories.
- Cloud-Based:Browser-accessible solvers eliminate on-site server maintenance for municipal engineering departments. State transportation agencies in Texas and Florida are migrating inspection databases to vendor-hosted environments.
- SaaS:Usage-metered access aligns operational expenditure structures with fluctuating project pipelines. Regional bridge owners in the Pacific Northwest increasingly procure solver hours rather than perpetual licenses.
- On-Premises:Air-gapped installations satisfy classified infrastructure and nuclear facility adjacent bridge assessments. Military engineering commands in the United States retain captive computational clusters.
- Hybrid:Split architectures reserve sensitive model data locally while outsourcing compute-intensive seismic simulations. German state road authorities pilot this configuration for digital twin implementations.
On-premises retains share in defense-adjacent segments; cloud-based configurations show the steepest expansion trajectory.
Application:
Lifecycle stage determines functional requirements from geometric optimization through deterioration forecasting.
- Structural Assessment:Rating engines evaluate load-carrying capacity against permit vehicle configurations. Overweight truck routing programs in the United States sustain continuous demand for rapid capacity calculations.
- Maintenance Planning:Deterioration models integrate inspection data to forecast deck rehabilitation and superstructure replacement timing. German federal priorities for predictive maintenance concentrate digital twin investment here.
- Bridge Design:Preliminary and final design modules optimize member sizing against code-specified limit states. Design-build procurement growth in Australia and the United Kingdom accelerates integrated analysis-platform adoption.
- Safety Evaluation:Post-event forensic tools reconstruct failure mechanisms and vulnerability screening protocols. Seismic retrofit prioritization programs in California and Japan drive specialized procurement.
Structural assessment commands the largest installed base; maintenance planning is climbing the fastest as aging infrastructure inventories expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bridge analysis software originated within North American transportation agencies during the 1970s highway expansion era, with early finite element solvers developed at university engineering laboratories in the United States before commercialization spread to European infrastructure authorities.
United States
The Federal Highway Administration enforces National Bridge Inspection Standards that mandate documented structural evaluations, compelling state departments of transportation to procure certified analysis platforms. Texas and Florida agencies are migrating inspection databases to vendor-hosted cloud environments. California's seismic retrofit prioritization programs sustain specialized procurement for post-event forensic tools.
Germany
Federal highway authorities prioritize physics-based bridge models for predictive maintenance scheduling, creating concentrated demand for real-time sensor integration capabilities. Eurocode compliance validation extends product release cycles for nonlinear material models. The Rhine-Ruhr metropolitan corridor anchors digital twin pilot programs for aging steel truss inventories.
United Kingdom
Design-build procurement growth accelerates integrated analysis-platform adoption among EPC contractors. Building information modeling mandates require bidirectional data exchange with asset management systems. The Greater London Authority drives cloud-based structural assessment procurement for Thames crossing maintenance programs.
Japan
Emergency response protocols following seismic events sustain steady deployment of diagnostic load testing platforms. METI guidelines encourage computational infrastructure investment for high-fidelity seismic simulations. The Kansai region's Osaka-Kobe corridor concentrates specialized structural consultancy demand for orthotropic deck assessments.
Australia
State road authorities in New South Wales and Victoria procure cloud-hosted solver hours through usage-based contracts rather than perpetual licenses. Climate adaptation requirements create procurement specifications for flood-load analysis modules. Sydney's infrastructure advisory cluster leads digital twin implementation for harbor bridge asset management.
Bridge Analysis Software Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification depth and civil engineering workflow specialization. The vendor base organizes into three tiers: infrastructure-software specialists with deep domain expertise, diversified design-software conglomerates with broad platform reach, and IT services firms wrapping analysis tools within enterprise asset management contracts. Dominant competitive moves include cloud-architecture reconfiguration for subscription licensing and geospatial-structural convergence through LiDAR integration partnerships.
Within the infrastructure-software specialist tier, Bentley Systems exemplifies deep civil engineering workflow anchoring, while Autodesk occupies a position bridging computational design platforms with structural analysis modules. Trimble represents the geospatial-structural convergence archetype through hardware-software ecosystem integration.
| Leading Market Players |
|---|
| Bentley Systems |
| Autodesk |
| Trimble |
| AECOM |
| WSP Global |
| SAP SE |
| Oracle Corporation |
| IBM Corporation |
| AgileAssets |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal lifecycle carbon accounting requirements gate both qualified supply and premium-tier pricing access for bridge analysis software vendors. Certification timelines for Eurocode-compliant nonlinear material models stretch product release cycles, concentrating premium pricing power among established specialists while mid-tier providers face margin compression from accelerated cloud migration mandates.
Pricing Analysis
Subscription-based SaaS licensing anchored in finite element solver access now dominates procurement across transportation agencies. Three-tier pricing structure across premium, standard, and economy levels separates certified FEA platforms with full Eurocode validation from cloud-enabled beam analysis tools and entry-level load testing modules. Price differentiation rests on certification depth and sensor integration capability for digital twin implementations. Cost compression in the standard tier is intensifying because state transportation departments are consolidating vendor relationships under enterprise agreements. Municipal engineering departments exhibit the highest price sensitivity, while German federal highway authorities demonstrate lowest sensitivity due to mandated predictive maintenance budgets.
Supply Chain Analysis
Direct-to-agency channels handle government procurement demand, with vendor-hosted cloud environments displacing on-premises installations. Software development concentrates in the United States, Germany, and the United Kingdom, drawing from specialized civil engineering talent pools and university research laboratories. Raw material dependencies include GPU compute clusters for seismic simulations, LiDAR hardware for geospatial integration, and proprietary meshing algorithms protected by trade secret. Single-source vulnerability in certified finite element solver engines poses structural risk, as Eurocode validation creates sticky relationships with incumbent providers. Distribution runs through systems integrators and direct sales teams targeting infrastructure owners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bridge analysis software market functions as a regulatory compounder, with Federal Highway Administration National Bridge Inspection Standards mandating documented analytical workflows that lock in recurring procurement cycles across state transportation departments.
For Market Incumbents: Hedge against cloud-native entrants by accelerating API development for BIM-asset management interoperability, a capability gap that threatens platform stickiness. Acquire specialized sensor integration firms to anchor digital twin offerings before German federal authorities consolidate vendor relationships. Prioritize backward integration into LiDAR preprocessing to defend margin position in the geospatial-structural convergence segment.
For New Entrants and Emerging Players: Physics-informed machine learning modules offer a technology-first wedge into seismic vulnerability screening, where California and Texas transportation agencies pilot neural-network-based response predictions. Target maintenance planning applications for aging steel truss inventories in the Rhine-Ruhr corridor, where incumbent platforms lack real-time deterioration forecasting. Pursue usage-based solver hour contracts with Pacific Northwest municipal bridge owners to bypass perpetual license barriers.
For Investors and Strategic Acquirers: Roll-up economics work for specialized structural consultancies with captive software development because Eurocode certification timelines create defensive moats against pure-play technology entrants. Focus acquisition screening on firms with hybrid deployment architectures serving German state road authorities. Watch for inflection when EU AI Act algorithmic transparency requirements trigger procurement specification rewrites favoring explainable AI features.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Architecture Reconfiguration | Subscription licensing aligns Texas and Florida agency budgets with operational expenditure structures. |
| Geospatial-Structural Convergence | LiDAR integration partnerships enable as-built model generation without manual surveying overhead. |
| Digital Twin Platform Development | Real-time sensor integration captures German federal highway authority predictive maintenance procurement. |
| Certification Investment Acceleration | Eurocode compliance validation extends product release cycles, concentrating premium pricing power. |
| API Ecosystem Expansion | Bidirectional data exchange with asset management systems addresses UK Building Information Modeling mandates. |
Study Parameters
Coverage spans the United States, Germany, the United Kingdom, Japan, and Australia, with primary inputs from each market informing demand-side calibration. The research combines structured interviews with state transportation department procurement officers, structural engineering firm technical directors, and civil infrastructure asset managers with secondary validation against Federal Highway Administration bridge inventory databases, Eurocode implementation guidance documents, and vendor SEC disclosures. Bottom-up segment sizing triangulates against top-down infrastructure spending forecasts across the analysis window.
Rate-of-change decomposition separates volume effects from pricing dynamics throughout the forecast period. The analytical framework models deployment configuration, end-user category, product type complexity, and application lifecycle stage alongside regional regulatory adoption patterns. CAGRs derive from segment-level growth rate blending anchored in infrastructure modernization budget trajectories and cloud migration timelines. Forecast inputs include transportation agency IT expenditure surveys and digital twin pilot program expansion rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Eurocode revision schedules and EU AI Act implementation timing. Outputs reflect documented assumptions regarding certification timeline friction and legacy data interoperability progress. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Data Visualization Software Market
Software & Services
Towing Software Market
Software & Services
Emotion Recognition and Sentiment Analysis Software Market
Software & Services
Media Planning Software Market
Software & Services
Mobile Speech Recognition Software Market
Software & Services
Global Vendor Management Software Market
Software & Services
Data Conversion Services Market
Software & Services
Inventory Management Software Market
Software & Services
Global Time Series Analysis Software Market
Software & Services
Global Job Evaluation Software Market
Software & Services
North America Restaurant Management Software Market
Software & Services
Global Maintenance Management Software Market
Software & Services
France HR Payroll Software Market
Software & Services
Attendance Tracking Software Market
Software & Services
Global Continuous Integration Tools Market
Software & Services
Global Online Expense Management Software Market