
 United States Human Resource (HR) Technology Market | 2026-2036
United States Human Resource (HR) Technology Market Size, Share, and Industry Trends Forecast 2026-2036
United States Human Resource (HR) Technology Market Intelligence
Mid-market employers is collapsing the legacy dominance of large enterprises as the primary growth vector for HR technology procurement. Paychex anchors its position through deep vertical integration across payroll and benefits administration for businesses under 500 employees. Gusto competes aggressively on user experience design, sustaining subscription renewals through intuitive self-service interfaces that reduce support overhead.
Human Resource Technology comprises software platforms, cloud infrastructure, and embedded analytics tools that automate workforce administration including recruitment, compensation, compliance reporting, and talent development. Core systems integrate with ERP and financial software through standardized APIs, enabling real-time data synchronization across organizational functions. Cloud-Based delivery models lead adoption curves as SMEs abandon legacy on-premise installations, while Talent Management modules capture disproportionate R&D investment due to retention-focused buyer priorities. Applicant Tracking Systems represent a mature segment where feature differentiation narrows and price competition intensifies.
The Department of Labor enforces Fair Labor Standards Act record-keeping requirements that mandate precise time-tracking and overtime calculation capabilities in certified platforms. OSHA workplace safety reporting obligations and emerging state-level pay transparency laws in California and New York compel vendors to embed configurable compliance engines. Stakeholders must evaluate whether their current architecture can absorb accelerating regulatory fragmentation without custom development cycles.
Market Dynamics
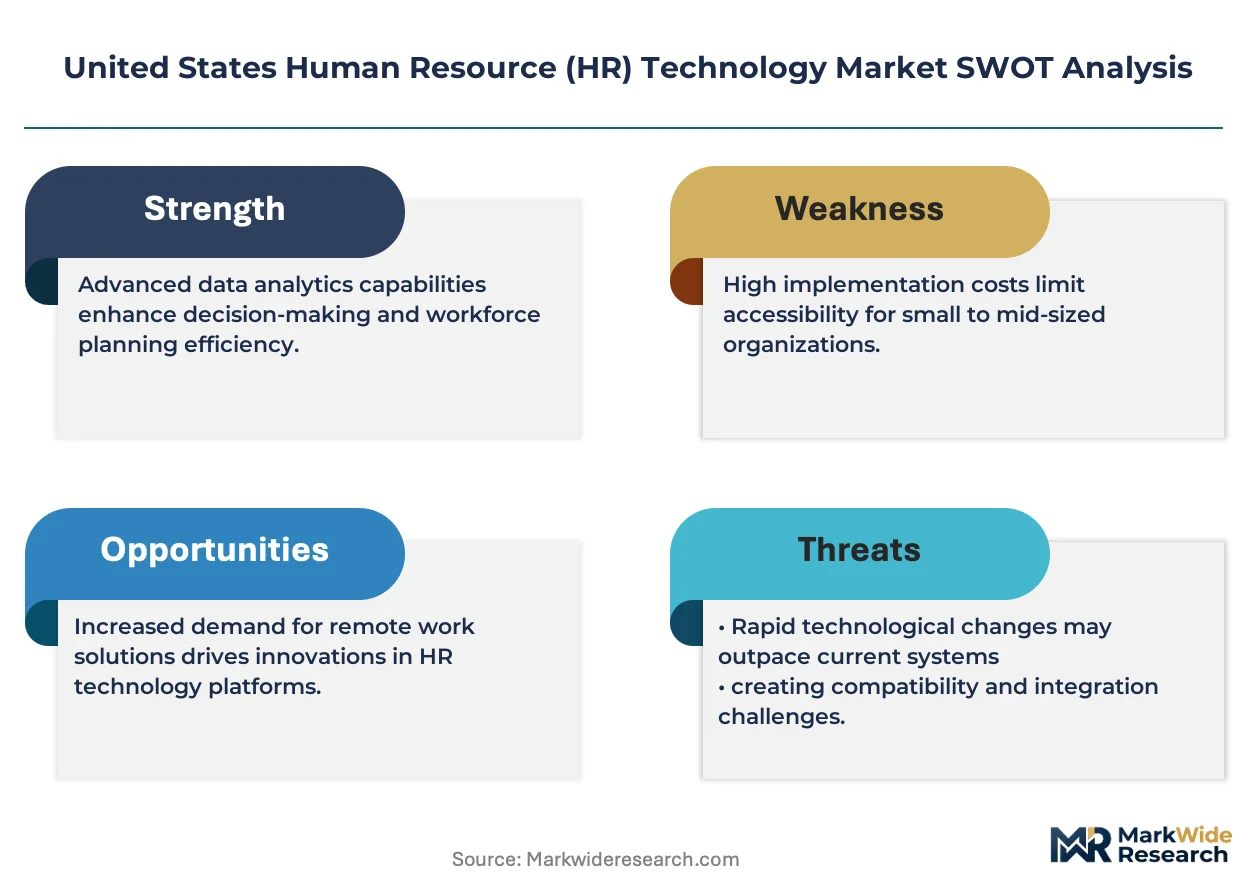
Mid-sized healthcare employers are collapsing the legacy dominance of large enterprises as the primary growth vector for HR technology procurement, while SEC climate disclosure rules for human capital metrics are reshaping vendor requirements across all buyer tiers.
Growth Catalysts
- Texas Energy Sector Payroll Complexity:Metropolitan corridors in Texas drive platform upgrades as energy and tech employers demand integrated talent systems capable of managing multi-state compensation and equity vesting schedules.
- OSHA Workplace Safety Reporting:Federal mandates for precise incident tracking and documentation compel employers to adopt certified platforms with embedded compliance engines and automated regulatory submission workflows.
- Cloud Migration Acceleration:SMEs are abandoning legacy on-premise installations in favor of cloud-based delivery models that reduce IT overhead and enable real-time data synchronization across distributed workforces.
Market Restraints
- API Standardization Gaps:Inconsistent data exchange protocols between HR platforms and ERP systems force costly custom integration development, particularly for mid-market buyers with limited technical resources.
- State-Level Regulatory Fragmentation:Emerging pay transparency laws in California and New York create compliance engine complexity that strains vendor R&D budgets and extends certification timelines.
- Legacy System Entrenchment:Large enterprises with decades-old on-premise installations face high switching costs and data migration risks that delay replacement cycles despite superior cloud alternatives.
Strategic Opportunities
- Applicant Tracking System Consolidation:Feature differentiation has narrowed in this mature segment, creating white space for vendors offering specialized vertical functionality or AI-powered candidate matching.
- Embedded Analytics Convergence:Integration of predictive workforce analytics with core HR platforms enables retention-focused buyers to identify flight-risk employees before departure.
- Benefits Administration Expansion:Deep vertical integration across payroll and benefits administration for businesses under 500 employees captures recurring revenue through regulatory complexity that self-service tools cannot address.
Industry Challenges
- Compliance Engineering Talent Scarcity:Vendors struggle to hire software engineers with expertise in Fair Labor Standards Act record-keeping requirements and multi-jurisdictional tax code interpretation.
- Real-Time Synchronization Complexity:Core systems must maintain sub-second data consistency across ERP, financial software, and third-party benefits providers, demanding expensive distributed systems architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Human Resource (HR) Technology Market |
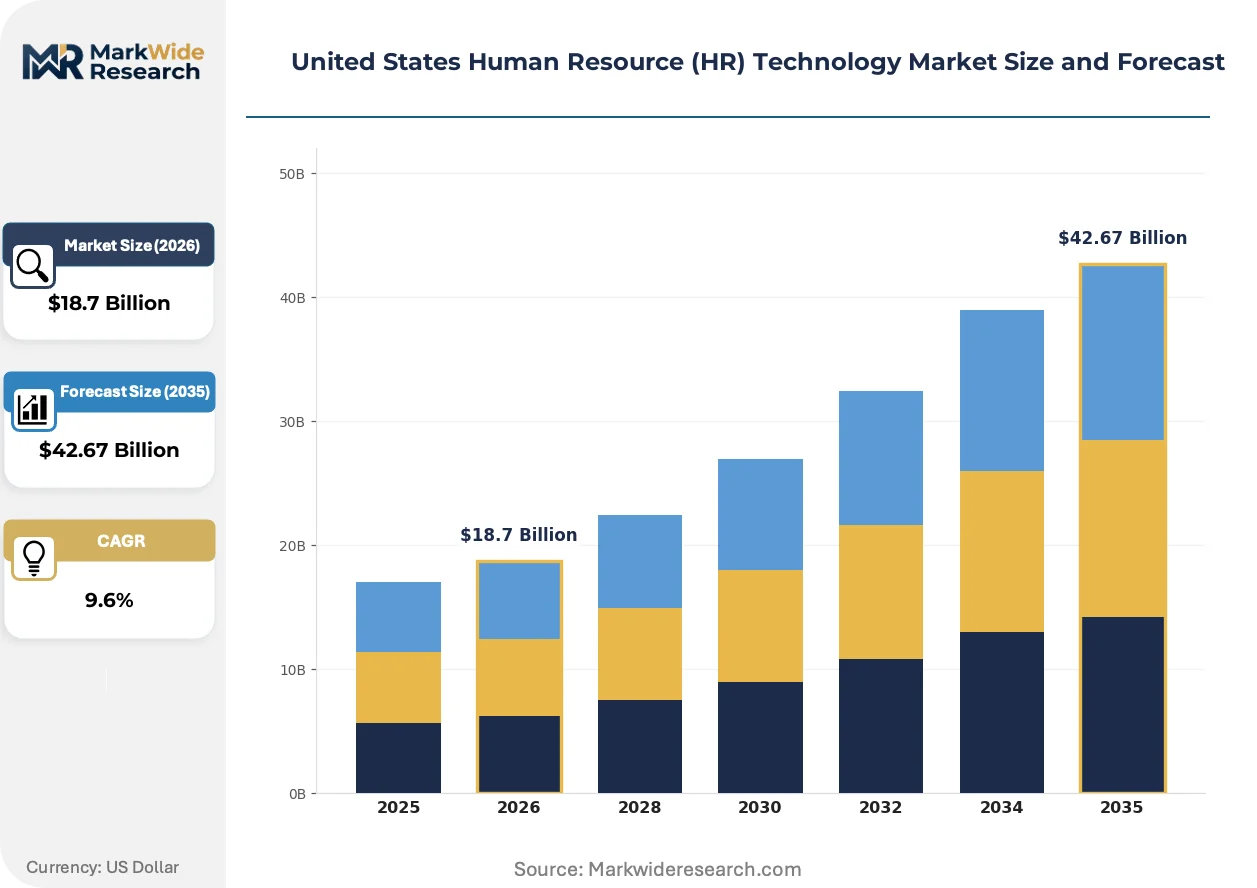
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $42.67 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Applicant Tracking Systems, Performance Management, Payroll Processing, Talent Management Delivery Model: Software as a Service, On-Premise, Cloud-Based, Hybrid End User: SMEs, Enterprises, Staffing Agencies, Educational Institutions Feature: Analytics, Automation, Employee Self-Service, Mobile Accessibility |
| Companies Covered | Paychex, HireVue, ADP, Bambee, Workable, Rippling, Insperity, Justworks, Gusto, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Human Resource (HR) Technology Market Strategic Shifts & Innovations
Generative AI capabilities are fragmenting traditional HR workflows across recruitment, compensation analysis, and policy drafting, while regulatory pressure on human capital disclosures accelerates investment in embedded analytics infrastructure.
AI-powered candidate screening and interview scheduling is fragmenting the traditional applicant tracking market. Mid-sized healthcare employers are adopting these tools fastest, drawn by promises of reduced time-to-hire. The technology is fragmenting established vendor hierarchies by enabling point solutions to capture discrete workflow steps without requiring full platform replacement.
The SEC's climate disclosure rules for human capital metrics are mandating granular workforce data collection and standardized reporting formats. Industrial consequence includes mandatory board-level visibility into retention rates, diversity metrics, and training investments. Public companies in the energy and tech sectors are most affected, responding by demanding pre-certified compliance modules from platform vendors rather than building custom reporting infrastructure.
Subscription pricing for talent management modules is displacing perpetual licensing as the dominant procurement model. Mid-market buyers are shifting from capital expenditure approval cycles to operational budget line items that reduce upfront commitment. This pattern is most visible in Texas metropolitan corridors where energy sector employers prioritize cash flow flexibility over long-term asset ownership.
United States Human Resource (HR) Technology Market Segmentation
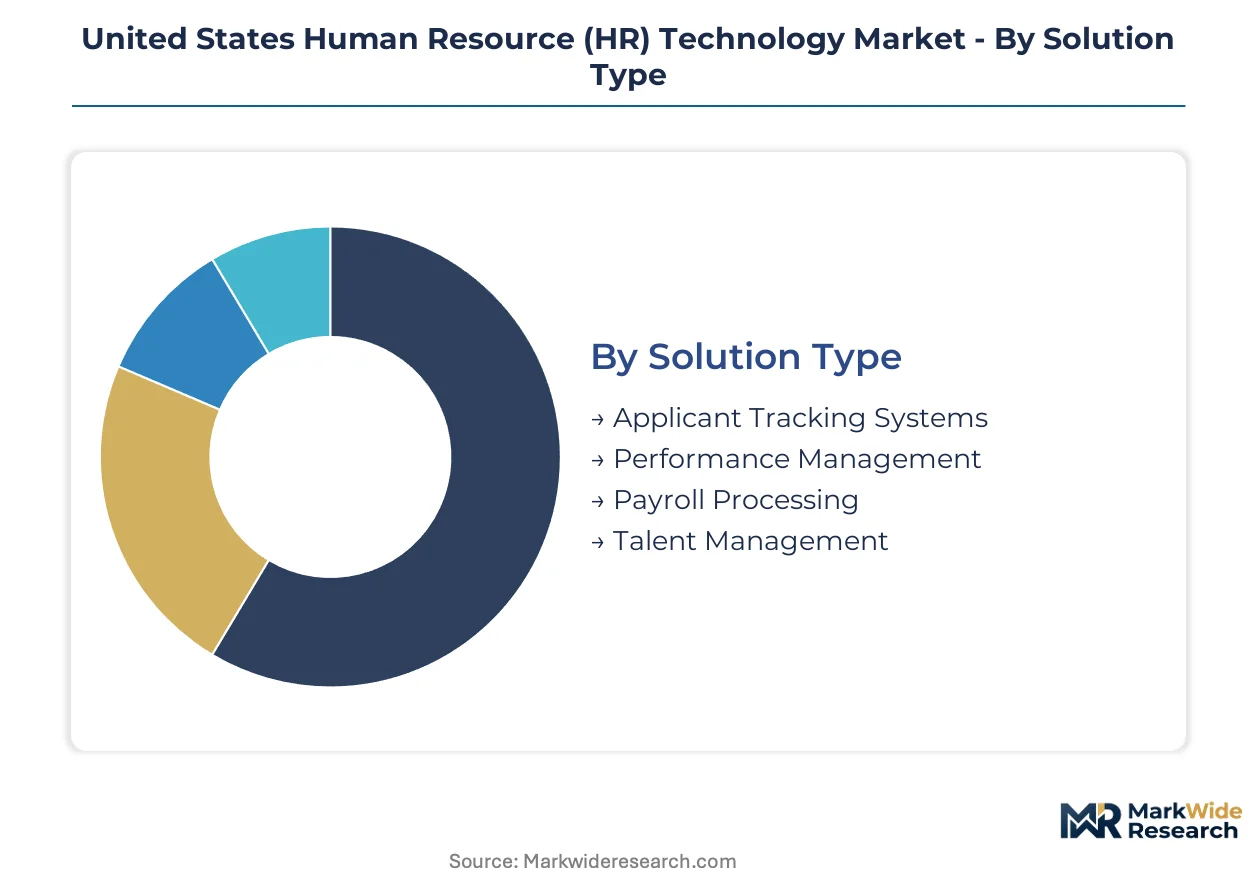
HR technology procurement patterns diverge sharply across organizational scale and technical infrastructure maturity. Buyers select platforms based on regulatory exposure intensity, workforce dispersion, and existing ERP integration depth rather than feature checklists alone.
Solution Type:
OSHA record-keeping mandates and SEC climate disclosure requirements for human capital metrics drive divergent certification burdens across functional modules.
- Payroll Processing:Core systems automate multi-state tax withholding, overtime calculation per Fair Labor Standards Act requirements, and equity compensation vesting schedules. Texas metropolitan energy employers demand integrated platforms capable of handling complex cross-border compensation and mineral rights royalty distributions.
- Talent Management:Retention-focused modules capture disproportionate R&D investment as mid-sized healthcare employers prioritize flight-risk identification and succession planning. Embedded predictive analytics correlate training investments with turnover probability, satisfying emerging board-level visibility requirements.
- Applicant Tracking Systems:Mature segment where AI-powered candidate screening fragments established vendor hierarchies.
- Performance Management:Continuous feedback tools replace annual review cycles for distributed workforces.
Established volume favors Payroll Processing; emerging adoption favors Talent Management.
Delivery Model:
IT overhead reduction pressures and real-time synchronization requirements reshape infrastructure decisions across buyer tiers.
- Cloud-Based:SMEs abandon legacy on-premise installations for subscription models that eliminate hardware maintenance and enable automatic regulatory update deployment. Mid-market buyers in California and New York prioritize cloud delivery to absorb state-level pay transparency law changes without custom development cycles.
- Software as a Service:Operational budget line items displace capital expenditure approval cycles, accelerating procurement velocity for businesses under 500 employees. Subscription pricing aligns vendor incentives with customer retention rather than upfront license extraction.
- On-Premise:Large enterprises with decades-old installations face high switching costs despite superior cloud alternatives.
- Hybrid:Transitional architecture bridging legacy ERP connections with cloud analytics layers.
Deployment gravity centers on Cloud-Based for new procurement; Hybrid sustains entrenched enterprise accounts.
End User:
Workforce scale and regulatory scrutiny intensity determine platform complexity requirements and integration architecture.
- SMEs:Businesses under 500 employees drive fastest expansion as integrated talent platforms collapse the legacy dominance of large enterprises in procurement growth. Paychex and Gusto compete for this segment through payroll-benefits vertical integration and intuitive self-service interfaces that reduce support overhead.
- Enterprises:Public companies in energy and tech sectors demand pre-certified compliance modules for SEC human capital disclosure rules rather than building custom reporting infrastructure. Board-level visibility mandates into retention rates and diversity metrics require granular workforce data collection capabilities.
- Staffing Agencies:High-velocity placement workflows demand rapid candidate matching and credential verification.
- Educational Institutions:Seasonal employment patterns and grant-funded position management create specialized scheduling requirements.
Revenue concentration tilts toward Enterprises; subscription growth velocity favors SMEs.
Feature:
User experience expectations and distributed workforce management reshape capability prioritization across platform roadmaps.
- Automation:Federal mandates for precise OSHA incident tracking and automated regulatory submission workflows compel embedded compliance engines. Workflow automation reduces administrative burden for mid-sized healthcare employers managing complex credentialing and shift scheduling.
- Analytics:Predictive workforce analytics integration enables retention-focused buyers to identify flight-risk employees before departure. SEC disclosure rules mandate standardized reporting formats that strain vendor data architecture investments.
- Employee Self-Service:Intuitive interfaces reduce HR support ticket volume and accelerate information access.
- Mobile Accessibility:Distributed workforces demand full functionality across device types without security compromise.
Capability investment clusters on Automation for compliance; Analytics commands premium pricing for predictive applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic software vendors in the United States export HR technology platforms to Canadian energy firms and Mexican manufacturing subsidiaries seeking compliance-ready workforce management systems. Cross-border data flows concentrate in metropolitan corridors where payroll complexity demands integrated multi-jurisdictional solutions.
Texas Metropolitan Corridors
Energy sector employers in Houston and Dallas-Fort Worth drive demand for platforms managing equity vesting schedules and mineral rights royalty distributions. OSHA workplace safety reporting mandates compel adoption of certified systems with automated incident documentation. Austin's tech sector concentrates procurement of cloud-based talent management modules for distributed engineering teams.
California
State-level pay transparency laws in San Francisco and Los Angeles force vendors to embed configurable compliance engines for salary range disclosures. Silicon Valley technology employers prioritize predictive analytics integration for flight-risk identification. San Diego's biotech cluster demands specialized credentialing workflows for research personnel.
New York Metro
Financial services employers in Manhattan require SEC-compliant human capital disclosure modules for board-level retention metrics. State pay transparency regulations extend vendor certification timelines for multi-state employers. Brooklyn's emerging tech sector accelerates subscription pricing adoption over perpetual licensing.
Illinois and Midwest Manufacturing Belt
Chicago-headquartered industrial employers seek hybrid architectures bridging legacy ERP connections with cloud analytics layers. Department of Labor Fair Labor Standards Act enforcement drives precise time-tracking platform upgrades. Detroit's automotive sector demands integrated systems managing union scheduling and overtime calculation.
Florida and Southeast Growth Corridors
Healthcare systems in Miami and Tampa accelerate adoption of integrated talent platforms for mid-sized hospital networks. Seasonal tourism employment patterns create specialized scheduling requirements for hospitality-focused vendors. Orlando's simulation and training industry drives demand for competency-tracking modules.
United States Human Resource (HR) Technology Market Key Industry Players
Listed leaders compete with private specialists across payroll processing depth and user experience design. The vendor base organizes around three strategic archetypes: legacy payroll processors with deep vertical integration, cloud-native challengers prioritizing intuitive interfaces, and point-solution specialists fragmenting discrete workflow steps. Dominant competitive moves include M&A activity consolidating applicant tracking capabilities and strategic partnerships embedding predictive analytics into core platforms.
Within the legacy processor tier, Paychex and ADP occupy positions defined by decades of payroll-benefits vertical integration for businesses under 500 employees. Gusto exemplifies the cloud-native archetype competing aggressively on self-service interface design that reduces support overhead. Rippling represents emerging platform consolidation spanning IT device management alongside traditional HR workflows.
| Leading Market Players |
|---|
| Paychex |
| HireVue |
| ADP |
| Bambee |
| Workable |
| Rippling |
| Insperity |
| Justworks |
| Gusto |
| Others |
Cost & Logistics Intelligence
Thirty-to-forty-five-day implementation lead-times for cloud-based HR platforms concentrate pricing power with vendors possessing pre-certified compliance engines, while subscription renewal cycles compress margin buffers for point-solution providers lacking embedded analytics infrastructure.
Pricing Analysis
Cloud-native platform pricing diverges sharply from legacy on-premise licensing through subscription-SaaS-tiered models that displace perpetual ownership. Price differentiation rests on certification depth for OSHA record-keeping and SEC disclosure compliance, plus vertical integration breadth across payroll-benefits workflows. Cost compression in the mid-market tier intensifies as Gusto and Rippling compete on self-service interface quality. SMEs under 500 employees exhibit highest price sensitivity, while energy sector enterprises in Texas absorb premium pricing for multi-state equity vesting capabilities.
Supply Chain Analysis
Inbound cloud infrastructure costs through AWS and Azure data center availability shape vendor margin structures more than traditional hardware logistics. Software development labor concentrates in the United States, India, and Eastern Europe, with compliance engineering talent scarcity in North America forcing offshore expansion. Raw material dependencies center on GPU compute capacity, API middleware licenses, and cybersecurity certification services. Single-source vulnerability in generative AI model providers creates concentration risk. Distribution runs through direct sales teams for enterprises and self-service digital channels for SME procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among mid-sized healthcare employers, whose collective procurement volume now exceeds large enterprise growth rates and forces vendors toward configurable compliance engines over custom development.
For Market Incumbents: Fortify embedded analytics infrastructure to capture SEC climate disclosure compliance demand before point-solution specialists fragment the market. Deepen backward integration into benefits administration workflows to lock in recurring revenue. Prioritize certification investment for California and New York pay transparency engines as regulatory fragmentation accelerates.
For New Entrants and Emerging Players: AI-powered candidate screening for mid-sized healthcare employers represents the most penetrable service-layer gap, as incumbent platforms under-invest in specialized credentialing workflows. Target Texas metropolitan energy corridors where mineral rights royalty distribution complexity exceeds current self-service tool capabilities. Pursue channel partnerships with existing payroll processors rather than direct enterprise sales.
For Investors and Strategic Acquirers: Long-term, this sits as a compliance-anchored SaaS play because regulatory fragmentation creates durable switching costs that transcend feature parity cycles. Acquisition targets should demonstrate pre-certified OSHA and SEC modules with healthcare or energy vertical depth. Watch for inflection when state-level pay transparency laws exceed five jurisdictions, forcing consolidation among under-capitalized point-solution vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates payroll, benefits, and talent management into unified workflows reducing IT overhead for mid-market buyers. |
| Compliance Engine Certification | Pre-certification for OSHA record-keeping and SEC human capital disclosures accelerates procurement cycles with risk-averse public companies. |
| Acquisition of Specialist Firm | Captures AI-powered candidate screening capabilities that fragment traditional applicant tracking market hierarchies. |
| Strategic Partnership | Embeds predictive analytics from third-party providers into core platforms serving retention-focused healthcare employers. |
| Geographic Expansion | Targets Texas metropolitan corridors where energy sector payroll complexity demands multi-state equity vesting capabilities. |
Research Approach
Initial hypotheses were tested against primary input from HR technology procurement officers, compliance engineering leads at platform vendors, benefits administration specialists, and mid-market healthcare CFOs and refined through secondary validation against SEC disclosure filings, OSHA certification databases, state labor department regulatory updates, and cloud infrastructure spending disclosures from hyperscaler quarterly reports. Bottom-up sizing of vendor subscription revenue combined with top-down triangulation against employer establishment counts produced volume estimates.
Variance decomposition across the projection horizon allocated growth between organic SME adoption, regulatory-driven replacement cycles, and platform consolidation effects. Segmentation dimensions modeled include delivery model, organization size, vertical industry, compliance intensity tier, and regional regulatory cluster. CAGRs were derived from fitted adoption curves calibrated to historical cloud migration patterns. Forecast inputs incorporated Fair Labor Standards Act enforcement intensity indices and state-level pay transparency legislative tracking.
Material uncertainties — regulatory repeal or delay, AI capability commoditization, and macroeconomic contraction affecting SME software budgets — sit outside the modeled envelope. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Construction Simulation Software Market
Software & Services
User Experience (UX) Research Software Market
Software & Services
Mobile Application Testing Services (MATS) Market
Software & Services
Business Spend Management (BSM) Software Market
Software & Services
Global Rapid Application Development Market
Software & Services
Video Editing Software Market
Software & Services
Consignment Software Market
Software & Services
Customs Declaration Software Market
Software & Services
Global Automotive Software Market
Software & Services
Global Testing Software Market
Software & Services
Lending Software Market
Software & Services
Canada HR Payroll Software Market
Software & Services
Sales Enablement Software Market
Software & Services
Sales Compensation Software Market
Software & Services
Plant Design Software Market
Software & Services
Global Construction Punch List Software Market