
 Global Application Performance Monitoring (APM) Market | 2026-2036
Global Application Performance Monitoring (APM) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Application Performance Monitoring (APM) Market Foresight
The EU Green Deal is pivoting enterprise software procurement toward energy-efficient infrastructure monitoring. Datadog leverages cloud-native architecture to sustain its position in container and serverless observability. Dynatrace anchors its competitive stance through AI-driven root-cause automation across hybrid estates. Cisco Systems controls network-centric APM distribution through embedded hardware-software integration.
Application Performance Monitoring encompasses software tools and platforms that capture, measure, and analyze transaction response times, error rates, and infrastructure health across distributed computing environments. These systems employ distributed tracing, code-level profiling, and synthetic transaction simulation to maintain service-level objectives for business-critical applications. Cloud-Based deployment is accelerating fastest as enterprises retire data center footprints, while On-Premises solutions retain strength in regulated industries with data sovereignty requirements. Real User Monitoring captures the largest solution-type revenue pool by correlating frontend experience metrics with backend latency, though Container Monitoring is expanding rapidly alongside Kubernetes orchestration adoption.
The U.S. Securities and Exchange Commission mandates incident disclosure timelines that pressure financial institutions toward sub-minute anomaly detection, while HIPAA compliance obligations constrain how Healthcare Providers deploy cloud-hosted monitoring for patient-facing applications. The EU AI Act introduces algorithmic transparency requirements that extend APM scope into model inference latency and bias-audit logging. Stakeholders must weigh sovereign cloud mandates against the operational efficiency of centralized SaaS observability platforms.
Market Dynamics
The EU AI Act is forcing APM vendors to embed algorithmic audit trails and inference latency monitoring into observability stacks, compressing product roadmaps and elevating compliance engineering to core R&D priority.
Growth Catalysts
- Kubernetes orchestration density:Container-native workloads in financial services and e-commerce generate exponential telemetry volumes that mandate automated APM ingestion pipelines.
- SEC incident disclosure mandates:Sub-minute anomaly detection requirements for publicly traded institutions accelerate real-time streaming analytics deployment.
- EU Green Deal procurement criteria:Energy-efficient infrastructure monitoring specifications redirect enterprise software budgets toward carbon-aware observability platforms.
Market Restraints
- Cloud egress cost volatility:Telemetry data transfer fees from hyperscale providers constrain multi-region APM deployment economics for mid-market enterprises.
- Data sovereignty fragmentation:Divergent national data localization laws in Germany, France, and India fragment SaaS observability architectures into costly sovereign cloud instances.
- Legacy agent technical debt:Monolithic application instrumentation libraries resist modernization, delaying unified observability consolidation.
Strategic Opportunities
- Edge computing telemetry gaps:Distributed manufacturing and autonomous vehicle deployments in Japan and South Korea lack mature APM coverage for ultra-low-latency workloads.
- AI model observability convergence:MLOps pipeline integration with APM tooling creates new revenue pools for inference monitoring and drift detection.
- Outcome-based pricing models:Consumption metering tied to mean-time-to-resolution metrics displaces seat-based licensing in enterprise procurement negotiations.
Industry Challenges
- Distributed systems expertise scarcity:Site reliability engineering talent shortages in Brazil and Southeast Asia delay enterprise APM implementation timelines.
- Multi-cloud integration complexity:Heterogeneous Kubernetes distributions across AWS, Azure, and GCP estates fragment observability data models and correlation logic.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Application Performance Monitoring (APM) Market |
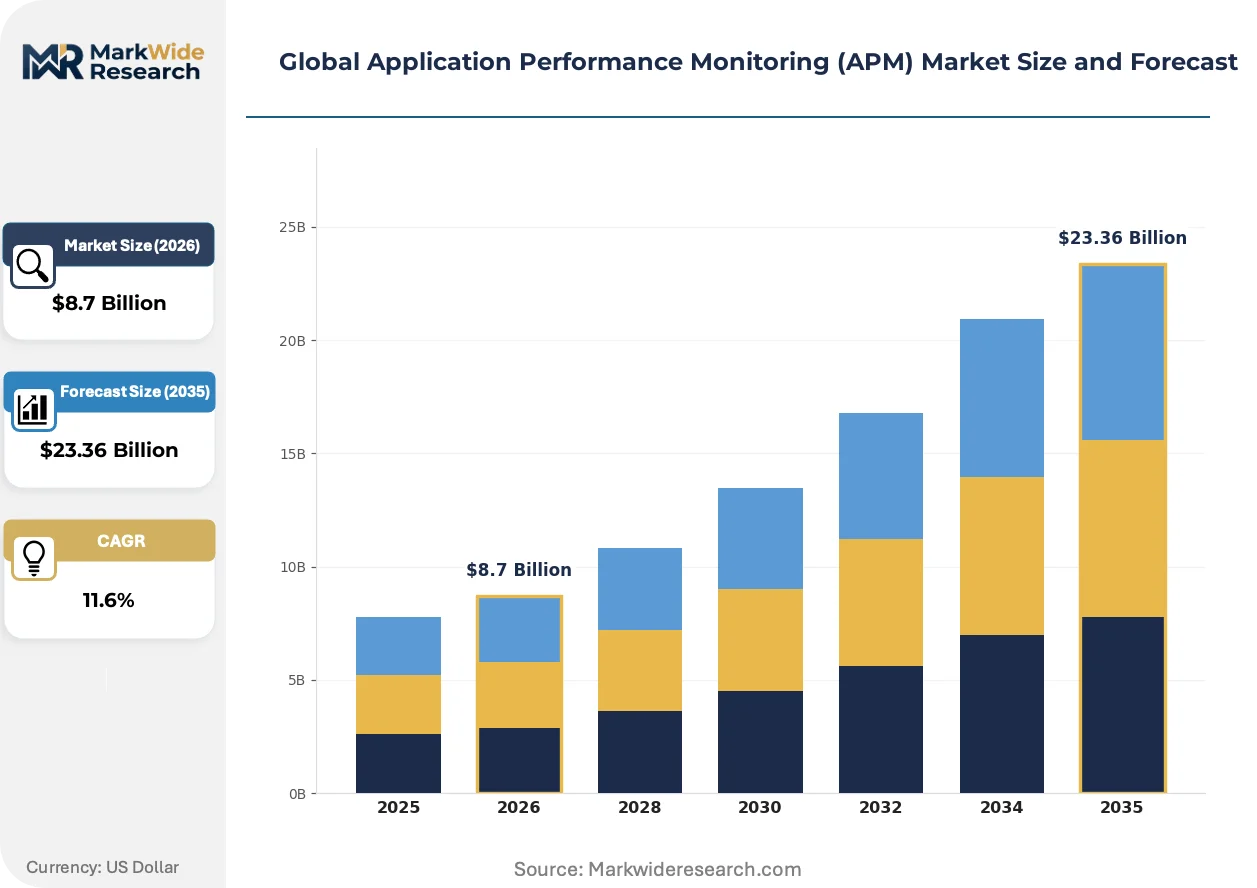
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $23.36 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS, Managed Services Solution Type: Real User Monitoring, Synthetic Monitoring, Infrastructure Monitoring, Container Monitoring, Log Analytics Application Industry: Information Technology, Telecommunications, Banking, Healthcare Providers, Government Agencies End User: Software Developers, IT Operations, DevOps Teams, Network Administrators, Security Teams |
| Companies Covered | SolarWinds Worldwide, Splunk, Datadog, Cisco Systems, LogicMonitor, Dynatrace, AppDynamics, Zoho Corporation, New Relic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Application Performance Monitoring (APM) Market Shifts & Advancements
OpenTelemetry standardization is collapsing proprietary agent lock-in, while AI-driven root-cause automation compresses incident response workflows. Observability data gravity is shifting toward embedded analytics within developer toolchains.
eBPF kernel instrumentation is electrifying cloud-native observability by capturing system-level telemetry without application code modification. Platform engineering teams at SaaS providers and fintechs are deploying eBPF-based agents at scale. This technology is electrifying competitive positioning by decoupling APM value from language-specific library dependencies.
The EU AI Act's algorithmic transparency mandates are extending APM scope into machine learning inference pipelines and bias-audit logging. Financial services deployers in Germany and the Netherlands must now correlate model latency with fairness metrics. Healthcare AI applications face the steepest compliance engineering burden under these requirements.
Developer-centric procurement patterns are displacing centralized IT operations as the primary APM buying center. Platform engineering budgets now control observability tool selection at technology-intensive enterprises. This shift is most pronounced in the United States, where cloud-native application density supports self-service instrumentation adoption.
Global Application Performance Monitoring (APM) Market Segmentation
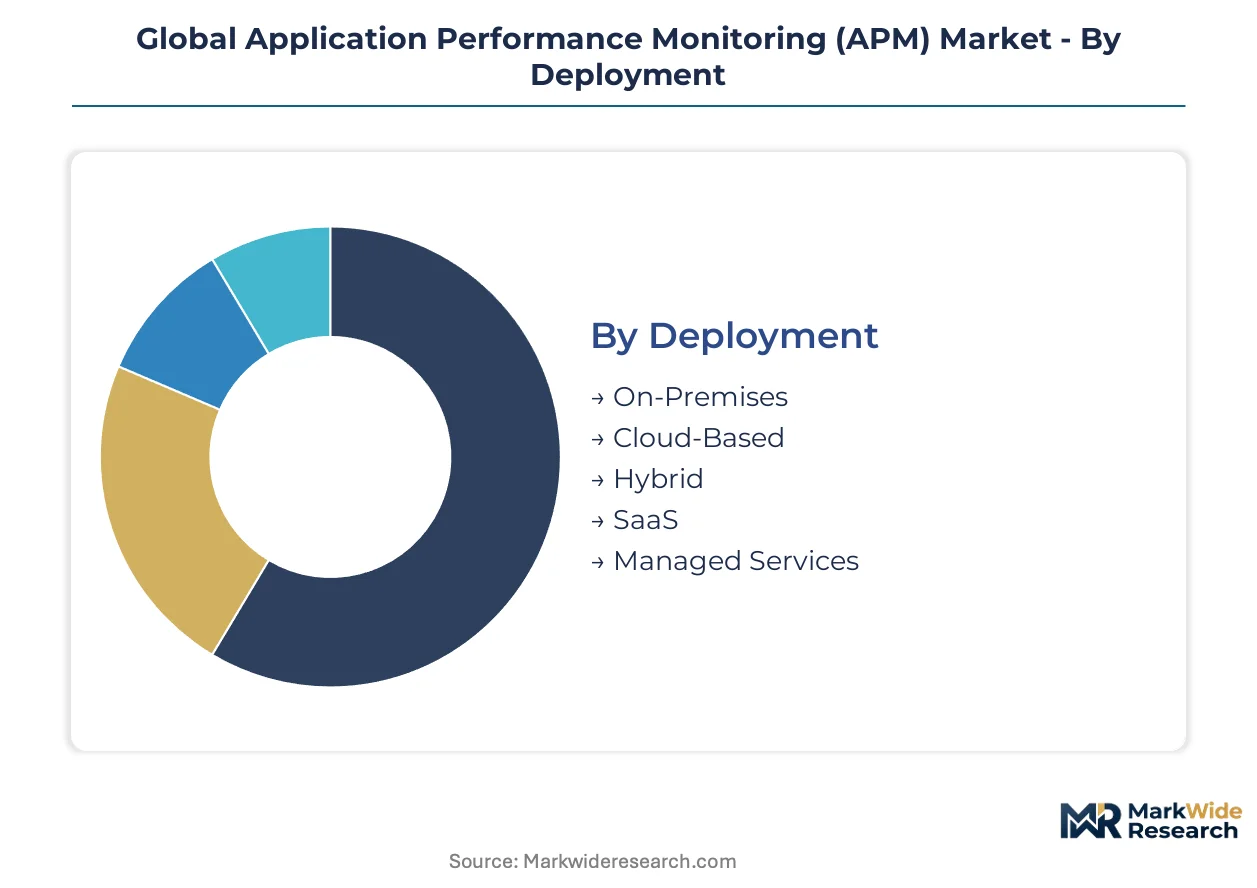
APM procurement decisions split sharply across deployment sovereignty requirements, solution telemetry depth, and end-user technical sophistication. Financial institutions in Frankfurt and Singapore impose divergent compliance burdens on identical product categories.
Deployment:
HIPAA and EU AI Act certification burdens fall heaviest on On-Premises and Hybrid configurations, while Cloud-Based deployments navigate SEC disclosure timelines through sub-minute streaming architectures.
- On-Premises:Hardware-resident installations capture full telemetry within sovereign data centers. Banking deployers in Germany and India favor this model for patient and transaction data under BIS and national banking regulator mandates.
- Cloud-Based:Hyperscale-hosted observability scales ingestion pipelines for Kubernetes-orchestrated workloads. E-commerce platforms in the United States and Japan drive demand despite egress cost volatility from AWS, Azure, and GCP transfer fees.
- Hybrid:Split architectures balance regulated data on-premises with burst analytics in cloud. Healthcare providers partition PHI-bound monitoring from synthetic transaction testing.
- SaaS:Multi-tenant platforms accelerate procurement cycles for mid-market enterprises. Developer-centric buying centers in fintech clusters favor self-service instrumentation.
- Managed Services:Outsourced operations offload Site Reliability Engineering scarcity in Brazil and Southeast Asia to specialized providers.
Cloud-Based sits at the top of the volume ranking, with Container Monitoring climbing the fastest alongside Kubernetes density expansion.
Solution Type:
Cost tier differentiation separates premium real-time streaming analytics from standardized log aggregation, with container-native tooling commanding R&D premium pricing.
- Real User Monitoring:Frontend experience correlation with backend latency generates the largest revenue pool. Retail and media streaming deployers in the United States and South Korea prioritize session replay for conversion optimization.
- Container Monitoring:Kubernetes pod-level telemetry captures resource contention and restart storms. Platform engineering teams at SaaS providers adopt eBPF-based agents to eliminate language-specific instrumentation.
- Synthetic Monitoring:Scripted transaction simulation validates uptime from external vantage points. Telecommunications operators deploy probes across cellular edge networks.
- Infrastructure Monitoring:Server, storage, and network health baselines support capacity planning. Legacy data center estates in regulated industries retain this as primary coverage.
- Log Analytics:Centralized query engines aggregate distributed system events. Security teams correlate APM traces with SIEM alerts for incident response.
Real User Monitoring captures dominant procurement budget share, though Container Monitoring gains share fastest through cloud-native migration waves.
Application Industry:
End-use application determines telemetry granularity requirements, with financial services mandating transaction-level tracing and healthcare enforcing patient data isolation.
- Banking:Sub-minute anomaly detection satisfies SEC disclosure mandates for publicly traded institutions. Frankfurt and New York deployers integrate model inference monitoring for EU AI Act algorithmic transparency.
- Healthcare Providers:HIPAA constraints restrict cloud-hosted monitoring for patient-facing applications. German and Dutch hospital networks face additional bias-audit logging under AI Act healthcare provisions.
- Information Technology:SaaS providers instrument microservice meshes for service-level objective maintenance. Silicon Valley and Bangalore clusters drive OpenTelemetry standardization adoption.
- Telecommunications:5G network slicing and edge compute deployments generate ultra-low-latency telemetry gaps. Japanese and South Korean operators lack mature APM coverage for manufacturing and autonomous vehicle workloads.
- Government Agencies:Sovereign cloud mandates fragment observability architectures into costly national instances. Indian and French procurement criteria emphasize energy-efficient infrastructure under EU Green Deal and domestic carbon targets.
Banking leads sector expenditure, with Healthcare Providers expanding most quickly under compliance-engineering investment cycles.
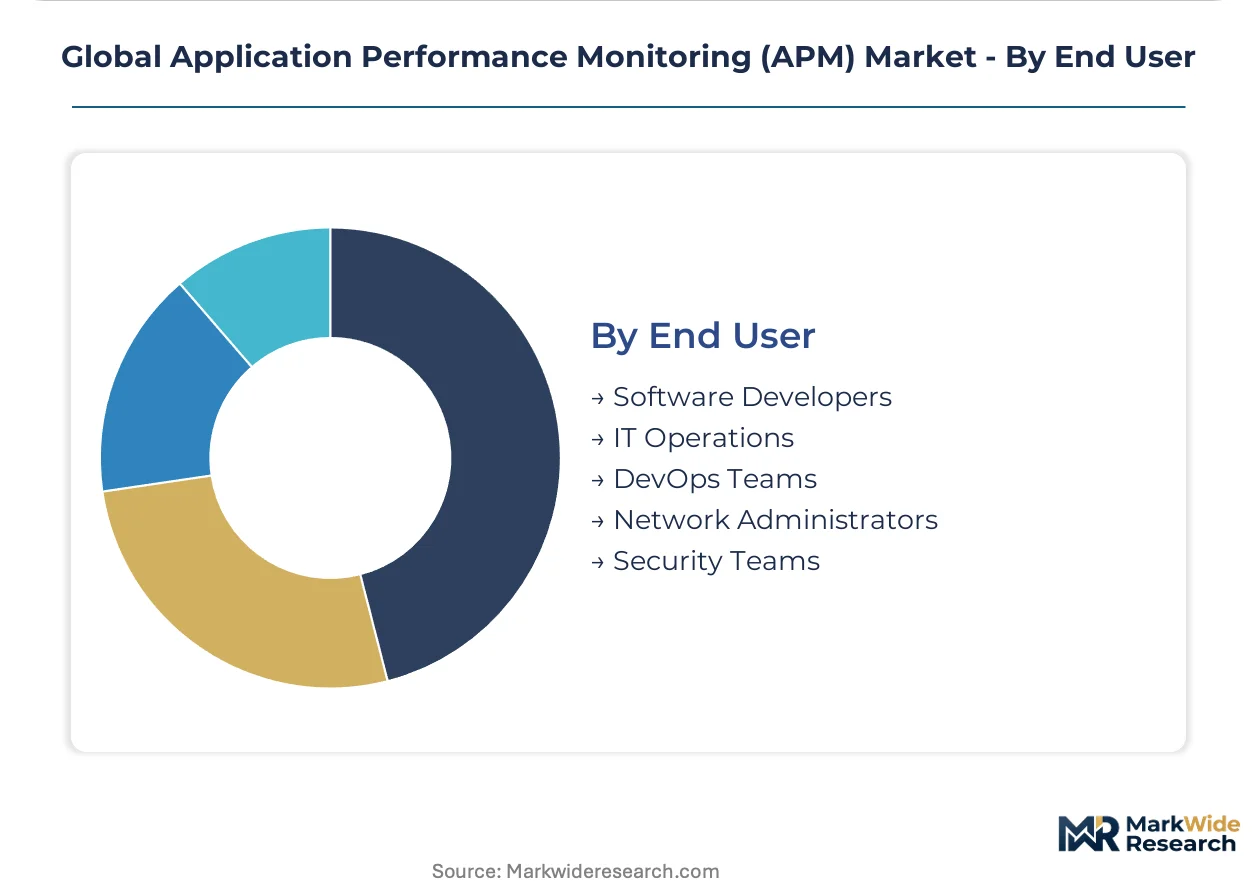
End User:
Customer type segmentation tracks organizational buying center migration from centralized IT operations to platform engineering and developer self-service.
- DevOps Teams:CI/CD pipeline integration demands shift-left observability with code-level profiling. Platform engineering budgets now control tool selection at technology-intensive enterprises.
- Software Developers:Embedded analytics within IDEs and version control systems accelerate instrumentation adoption. United States cloud-native density supports this procurement pattern most fully.
- IT Operations:Traditional NOC-centric monitoring consolidates alerting and escalation workflows. Regulated industries retain this structure for change control compliance.
- Security Teams:Threat hunting correlation with application behavior traces expands APM scope into XDR convergence. Financial services deployers prioritize this integration.
- Network Administrators:Cisco-embedded hardware-software integration controls distribution for packet-level visibility. Hybrid estate coverage requires this specialized expertise.
DevOps Teams command the largest addressable spend, with Software Developers representing the steepest expansion trajectory through developer-centric procurement displacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Site reliability engineering talent concentrates in the United States, Germany, and India, anchoring APM deployment velocity. Cloud-native application density in these markets generates telemetry volumes that mandate automated ingestion pipelines. Regulatory divergence across jurisdictions fragments observability architectures into sovereign cloud instances.
United States
SEC disclosure mandates for publicly traded institutions require sub-minute anomaly detection, accelerating real-time streaming analytics deployment. HIPAA compliance obligations constrain how healthcare providers deploy cloud-hosted monitoring for patient-facing applications. Silicon Valley and New York fintech clusters drive developer-centric procurement patterns through platform engineering budgets.
Germany
Frankfurt banking deployers integrate model inference monitoring for EU AI Act algorithmic transparency requirements. BIS mandates and national banking regulator directives favor on-premises hardware-resident installations for transaction data sovereignty. Munich and Berlin technology clusters balance regulated data on-premises with burst analytics in cloud through hybrid architectures.
India
Bangalore SaaS providers instrument microservice meshes for service-level objective maintenance amid Kubernetes orchestration density expansion. RBI guidelines and SEBI disclosure requirements impose sub-minute detection standards on financial institutions. Mumbai and Hyderabad fintech clusters adopt OpenTelemetry standardization to collapse proprietary agent lock-in.
Japan
Tokyo telecommunications operators deploy synthetic monitoring probes across 5G network slicing and edge compute deployments. METI industrial policy emphasizes energy-efficient infrastructure monitoring under carbon reduction targets. Osaka manufacturing clusters lack mature APM coverage for ultra-low-latency autonomous vehicle workloads.
United Kingdom
London financial services firms expand APM adoption to ensure transaction integrity across distributed computing environments. FCA operational resilience requirements pressure institutions toward automated root-cause automation. Manchester and Edinburgh technology clusters navigate GDPR certification burdens through hybrid deployment configurations.
Global Application Performance Monitoring (APM) Market Competitive Landscape
Capital-heavy infrastructure vendors compete with asset-light SaaS observability platforms for enterprise telemetry budgets. The vendor base consolidates around three tiers: hyperscale cloud-native specialists, legacy network-embedded incumbents, and open-source-centric challengers. Strategic archetypes include AI-driven root-cause automation providers, container-native eBPF instrumentation specialists, and hardware-software integrated distribution controllers. Dominant competitive moves encompass M&A for telemetry pipeline capabilities and strategic partnerships for multi-cloud correlation logic.
Among cloud-native observability platforms, Datadog and Dynatrace exemplify the AI-driven automation archetype, while Cisco Systems anchors the network-centric embedded integration tier. SolarWinds Worldwide and Splunk occupy positions spanning legacy enterprise IT operations and modern DevOps tooling transitions. New Relic and AppDynamics represent developer-centric procurement displacement, with Zoho Corporation and LogicMonitor sitting within the mid-market SaaS acceleration segment.
| Leading Market Players |
|---|
| SolarWinds Worldwide |
| Splunk |
| Datadog |
| Cisco Systems |
| LogicMonitor |
| Dynatrace |
| AppDynamics |
| Zoho Corporation |
| New Relic |
| Others |
Supply & Pricing Matrix
Site reliability engineering talent concentration in the United States, Germany, and India creates labor-cost differentials that widen pricing-tier spreads between premium AI-driven automation platforms and standardized log aggregation tools. Cloud egress fee volatility from AWS, Azure, and GCP compresses margins for mid-market SaaS observability providers while hyperscale-native vendors absorb telemetry transfer costs through volume scale.
Pricing Analysis
Consumption-based subscription tiers stratify across premium real-time streaming analytics, standard synthetic monitoring bundles, and economy log aggregation entry points. Price differentiation hinges on inference latency monitoring certification under EU AI Act algorithmic transparency mandates and Kubernetes pod-density telemetry granularity. Cost compression in the economy tier intensifies because OpenTelemetry standardization collapses proprietary agent lock-in and commoditizes basic instrumentation. Mid-market enterprises exhibit highest price sensitivity, while Frankfurt banking deployers accept premium positioning for sub-minute anomaly detection compliance.
Supply Chain Analysis
Returns and refurbishment flows for on-premises hardware-resident APM appliances cycle through authorized service depots in Germany, India, and Japan to extend equipment lifecycles under BIS and national banking regulator mandates. Component sourcing draws from Taiwan for semiconductor telemetry processors, South Korea for memory modules, and the United States for AI acceleration silicon. Single-source vulnerability concentrates in eBPF kernel instrumentation IP held by a narrow specialist tier. Distribution runs through hyperscale cloud marketplaces for SaaS provisioning and Cisco-embedded hardware channels for network-centric deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Application Performance Monitoring Market functions as a stable compounder anchored by regulatory compliance engineering that mandates continuous observability investment regardless of macroeconomic cycles.
For Market Incumbents: To counter OpenTelemetry-driven commoditization of basic telemetry ingestion, hyperscale cloud-native specialists should deepen backward integration into eBPF kernel instrumentation IP and establish sovereign cloud instances in Frankfurt, Mumbai, and São Paulo to satisfy data localization mandates. Certification investment for EU AI Act algorithmic transparency and HIPAA audit trail compliance defends pricing power in regulated verticals. For New Entrants and Emerging Players: Edge computing telemetry gaps for ultra-low-latency autonomous vehicle workloads in Osaka manufacturing clusters and 5G network slicing deployments in South Korea represent the most penetrable white-space. Platform engineering self-service procurement patterns in United States fintech clusters enable developer-centric go-to-market positioning through IDE-embedded analytics and GitOps-native instrumentation workflows. For Investors and Strategic Acquirers: Hyperscale cloud providers are the most active acquirer in this space, consolidating telemetry pipeline capabilities to complement infrastructure-as-a-service offerings. The long-term viability window favors asset-light SaaS platforms with proven Kubernetes-native architecture over legacy agent-dependent incumbents. Practitioners should monitor SEC disclosure mandate enforcement intensity and EU AI Act healthcare provision implementation timelines as inflection indicators for compliance-driven procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | OpenTelemetry standardization collapses proprietary agent lock-in and accelerates multi-vendor telemetry correlation. |
| Acquisition of Specialist Firm | eBPF kernel instrumentation specialists decouple APM value from language-specific library dependencies. |
| Strategic Partnership | Multi-cloud correlation logic partnerships with AWS, Azure, and GCP address fragmented Kubernetes distribution complexity. |
| Geographic Expansion | Sovereign cloud instances in Germany, India, and Brazil satisfy BIS, RBI, and national data localization mandates. |
| Product Launch | AI model observability convergence with MLOps pipelines creates new revenue pools for inference monitoring and drift detection. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with platform engineering directors, DevOps team leads, IT procurement officers at financial institutions, healthcare compliance engineers, and hyperscaler solution architects with secondary validation through SEC disclosure filings, hyperscaler capex disclosures, EU regulatory documentation, and hospital procurement databases. Bottom-up telemetry volume modeling and top-down enterprise IT spending allocation triangulated market sizing across deployment modes and solution types.
Segment-weighting approaches distributed value estimates across cloud-based, on-premises, hybrid, SaaS, and managed services deployment configurations, further disaggregated by real user monitoring, container monitoring, synthetic monitoring, infrastructure monitoring, and log analytics solution types. CAGRs were derived from regression analysis of historical adoption curves and forward projection of Kubernetes orchestration density, SEC disclosure mandate compliance deadlines, and EU AI Act implementation phases. Forecast inputs incorporated site reliability engineering talent availability indices and cloud egress fee trajectory assumptions from hyperscale provider pricing disclosures.
The model holds under sustained regulatory enforcement of algorithmic transparency and incident disclosure timelines; deviation in sovereign cloud mandate fragmentation or OpenTelemetry standardization acceleration would shift competitive positioning toward commodity telemetry layers. Practitioners should monitor EU AI Act healthcare provision enforcement intensity and hyperscale provider egress pricing volatility for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
RIP Software Market
Software & Services
Metal Fabrication Software Market
Software & Services
Theatrical Distribution Software Market
Software & Services
Procure to Pay Software Market
Software & Services
Global Electronic Data Capture Software Market
Software & Services
Global Backup Restore Software Market
Software & Services
AR Remote Collaboration Software Market
Software & Services
Mobile Application Testing Services (MATS) Market
Software & Services
Landing Page Creation Software Market
Software & Services
Global Inside Sales Software Market
Software & Services
Personal Budgeting Software Market
Software & Services
Africa Financial Services Software Market
Software & Services
Sales Compensation Software Market
Software & Services
Office Productivity Software Market
Software & Services
Digital Onboarding Platform Market
Software & Services
RIP Color Management Software Market