
 Global Business Software Market | 2026-2036
Global Business Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Business Software Market Analysis
Modular unbundling of enterprise suites into API-first microservices is rebalancing buyer choice across the Global Business Software Market. Microsoft Corporation leverages its Azure-native application stack to sustain platform stickiness among large enterprises. SAP SE anchors its competitive position through deep vertical specialization in process manufacturing and supply chain modules. Salesforce, Inc. differentiates via low-code extensibility and embedded AI workflows across sales and service clouds.
Business software encompasses integrated application suites, middleware platforms, and standalone productivity tools that automate commercial workflows, enforce data governance, and enable real-time analytics across distributed organizations. Cloud-based deployment now leads structural growth as enterprises migrate from capital-intensive on-premises infrastructure to consumption-based SaaS models; hybrid architectures retain relevance in regulated sectors requiring localized data residency. Within software type segmentation, ERP systems command the largest installed base while CRM platforms capture disproportionate expansion from e-commerce and customer data platform convergence.
The EU AI Act, GDPR, and SEC cybersecurity disclosure rules collectively elevate compliance spending and reshape vendor qualification criteria across procurement functions. ISO 27001 and SOC 2 Type II certifications have become baseline requirements for enterprise software contracts, effectively filtering mid-tier providers from contested RFP processes. Stakeholders must monitor regulatory fragmentation between jurisdictions as divergence in data sovereignty rules threatens to complicate multi-national rollout strategies.
Market Dynamics
Cloud-native ERP architectures are compressing deployment cycles from multi-year implementations to quarterly rollouts, forcing incumbent vendors to restructure professional services revenue models around subscription retention rather than upfront license fees.
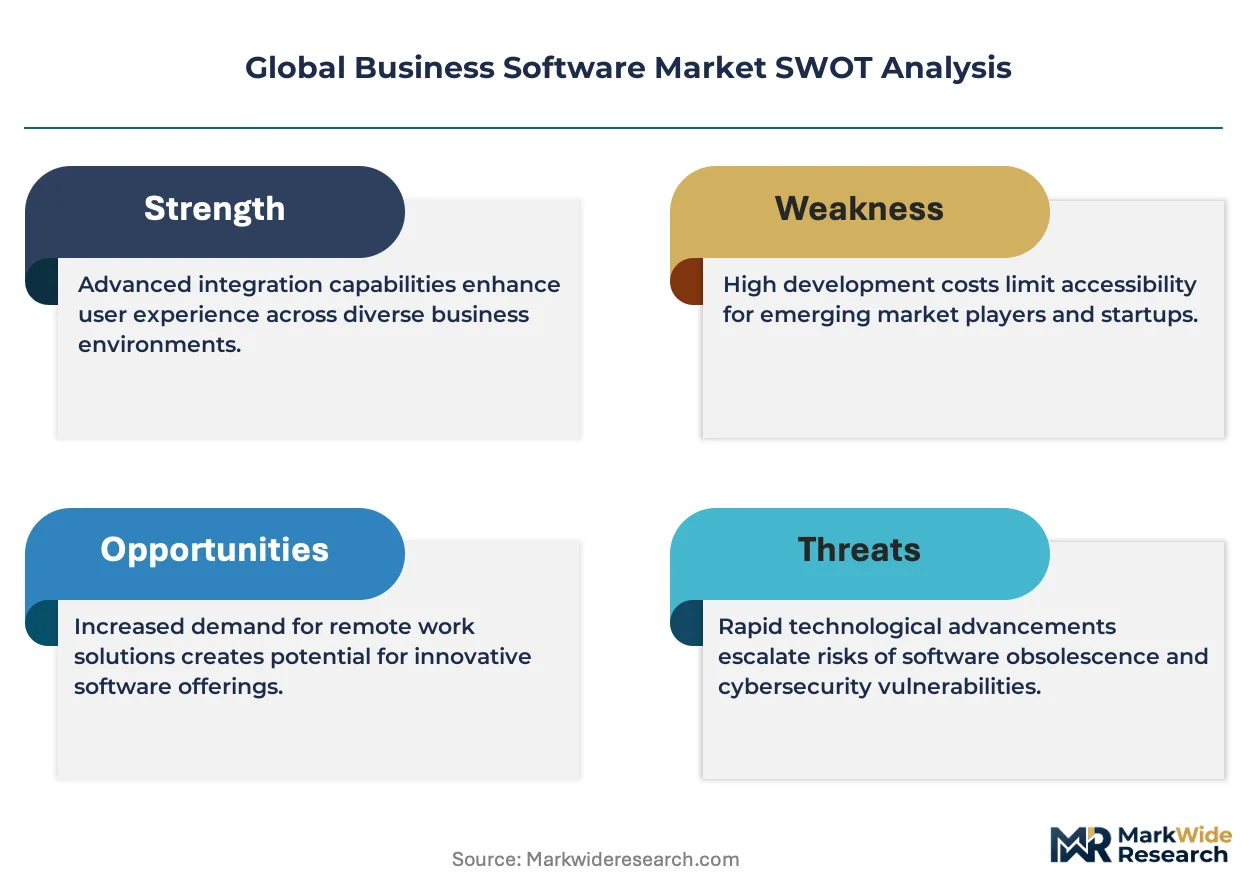
Growth Catalysts
- EU AI Act compliance mandates:Automated governance tooling embedded in enterprise suites creates mandatory upgrade cycles across financial services and healthcare verticals in Germany and France.
- Mid-market manufacturers:Discrete production facilities in India are replacing legacy MRP systems with modular SaaS platforms to support export traceability requirements.
- API-first microservices:Containerized application components enable buyers to assemble best-of-breed workflows without full-suite replacement, accelerating procurement velocity.
Market Restraints
- Data residency requirements:Russia's data localization law and China's cybersecurity regulations fragment cloud infrastructure economics, forcing redundant regional deployments.
- Specialized talent scarcity:SAP S/4HANA migration expertise concentrates among a narrow pool of systems integrators, inflating implementation costs.
- Legacy technical debt:COBOL and mainframe-dependent financial institutions face decade-long modernization timelines that delay SaaS transitions.
Strategic Opportunities
- Indonesia's digital transformation program:Government-mandated e-invoicing and tax automation create greenfield demand for localized ERP modules.
- Embedded carbon accounting:Convergence of ERP data models with emissions tracking APIs addresses CSRD disclosure requirements for EU-based multinationals.
- Vertical marketplaces:Industry-specific software exchanges in Brazil and Mexico aggregate niche compliance modules for mid-market buyers.
Industry Challenges
- Multi-cloud integration complexity:Enterprises operating across Azure, AWS, and Google Cloud environments struggle with unified identity management and cost governance.
- ISO 27001 certification timelines:Vendor security audits now extend 9-14 months, delaying contract execution and revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Business Software Market |
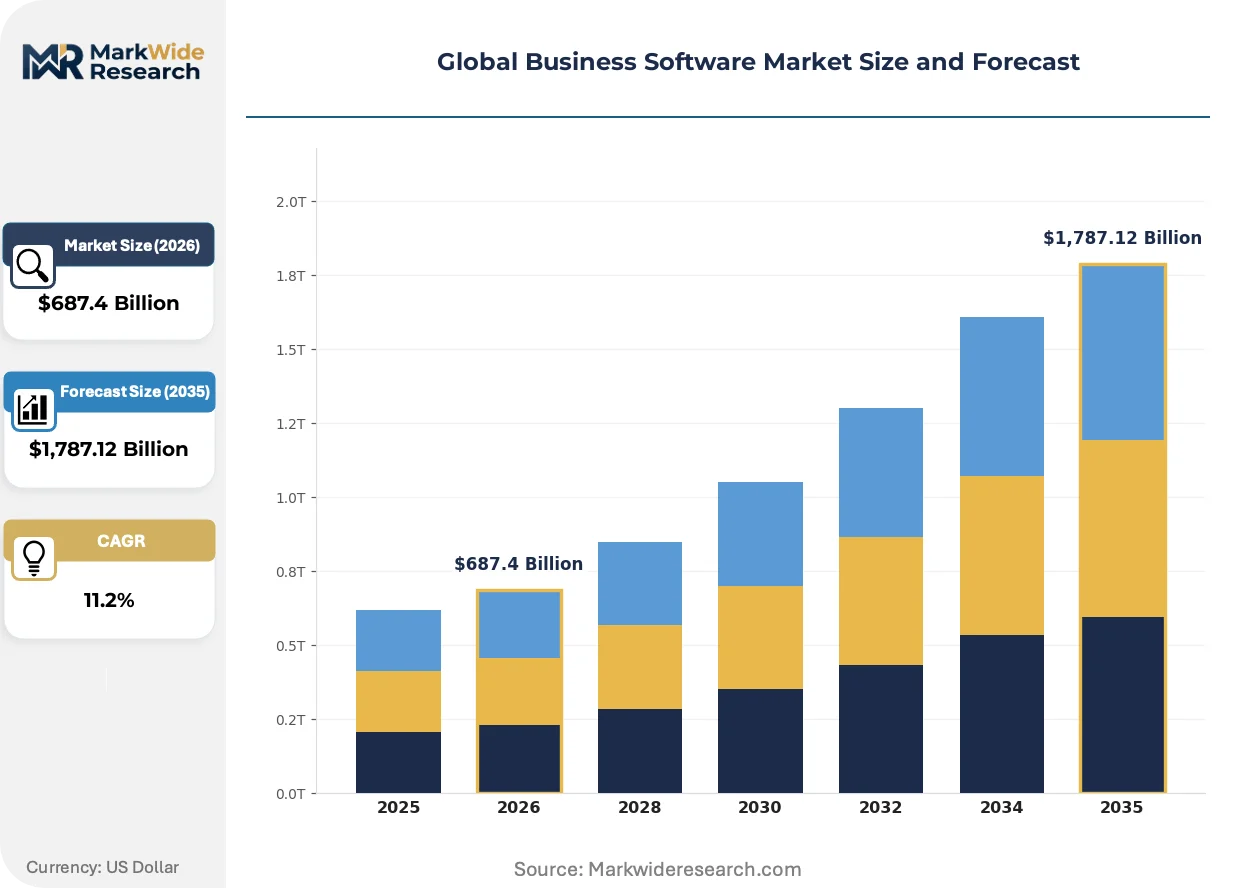
| Market Size in 2026 | $687.4 Billion |
| Market Size in 2035 | $1,787.12 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Corporate, SMEs, Government, Educational Institutions Software Type: CRM, ERP, HRM, Accounting Software Feature: Automation, Data Analytics, Collaboration, Security |
| Companies Covered | Microsoft Corporation, Oracle Corporation, SAP SE, IBM Corporation, Salesforce, Inc., ServiceNow, Inc., Workday, Inc., Intuit Inc., Infor, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Business Software Market Emerging Trajectories
Generative AI capabilities are embedding directly into core workflow applications, transforming software from passive record-keeping systems into active decision-support engines that anticipate user intent.
Agentic AI orchestration layers are rewriting how enterprise users interact with business applications. These systems autonomously execute multi-step workflows across disconnected modules. Mid-market finance teams in the United States are piloting autonomous invoice reconciliation. The technology is compressing the traditional RPA-to-AI upgrade cycle from years to months.
The EU AI Act's risk classification framework imposes documentation and human oversight requirements on high-risk automated decision systems. Enterprise procurement teams now mandate algorithmic impact assessments as standard contract terms. German automotive suppliers and French insurance underwriters face the most immediate compliance deadlines, driving demand for embedded audit trails.
Subscription fatigue among CIOs is fragmenting vendor consolidation strategies. Buyers increasingly unbundle monolithic suites to purchase point solutions through cloud marketplaces. This pattern concentrates among technology and professional services sectors in the United Kingdom and Netherlands, where procurement functions maintain dedicated software asset management teams.
Global Business Software Market Segmentation
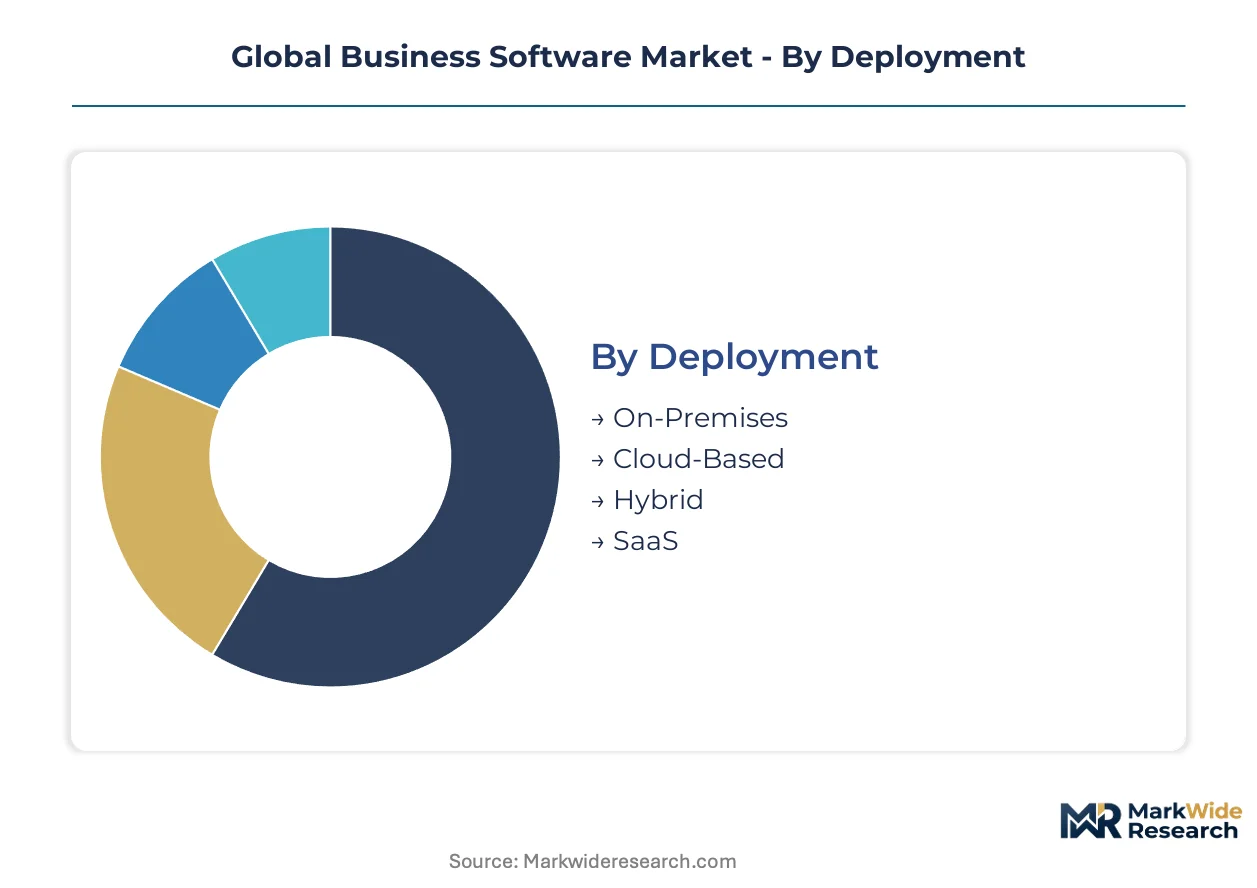
Deployment architecture and end-user scale determine pricing elasticity, implementation complexity, and regulatory exposure across the Global Business Software Market. Procurement patterns diverge sharply between capital-intensive on-premises commitments and consumption-driven SaaS subscriptions.
Deployment:
Customization intensity decreases from self-managed infrastructure to fully abstracted cloud services, reshaping vendor margin structures and buyer total cost of ownership calculations.
- On-Premises:Licensed software operating within buyer-controlled data centers demands dedicated hardware procurement and internal IT staffing. German automotive suppliers and French banking groups retain these deployments to satisfy GDPR data residency requirements and EU AI Act audit trail mandates.
- Cloud-Based:Vendor-managed infrastructure delivered over internet protocols eliminates capital expenditure while introducing recurring operational costs. Mid-market manufacturers in India favor this model to accelerate ERP replacement timelines without on-site server investments.
- Hybrid:Split architectures maintain sensitive workloads locally while bursting transactional processing to public cloud. Financial services firms in the United States deploy hybrid stacks to reconcile SEC cybersecurity disclosure obligations with legacy mainframe dependencies.
- SaaS:Fully managed multi-tenant applications with browser-based access standardize feature delivery across user bases. Educational institutions and government agencies in Indonesia adopt SaaS tax automation modules under national digital transformation directives.
Leading the category by volume: Cloud-Based. Expanding most quickly: SaaS.
End User:
Budget scale and procurement sophistication create four distinct buying personas with incompatible sales cycle lengths and contract negotiation patterns.
- Corporate:Multinational enterprises with centralized procurement functions negotiate enterprise-wide licensing agreements spanning multiple geographies. These buyers mandate ISO 27001 and SOC 2 Type II certifications as baseline qualification criteria, filtering mid-tier vendors from contested RFP processes.
- SMEs:Small and medium enterprises purchase through cloud marketplaces with limited IT staff and accelerated decision timelines. Modular API-first microservices enable these buyers to assemble best-of-breed workflows without full-suite replacement, concentrating demand among technology and professional services sectors in the United Kingdom and Netherlands.
- Government:Public sector entities operate under strict procurement regulations with extended vendor qualification periods. Brazil and Mexico host industry-specific software exchanges aggregating niche compliance modules for mid-market government buyers.
- Educational Institutions:Universities and research facilities prioritize collaboration features and volume-based pricing for distributed student populations. These end users drive disproportionate expansion in CRM platforms from e-commerce and customer data platform convergence.
Dominant by contract value: Corporate. Steepest expansion trajectory: SMEs.
Software Type:
Functional scope breadth determines integration complexity and replacement cost, locking buyers into migration cycles that span multiple fiscal years.
- CRM:Customer relationship management platforms orchestrate sales pipelines, marketing automation, and service interactions through unified data models. Salesforce and Microsoft anchor this segment through low-code extensibility and embedded AI workflows across sales and service clouds.
- ERP:Enterprise resource planning systems command the largest installed base by integrating finance, supply chain, and manufacturing operations. SAP SE sustains platform stickiness through deep vertical specialization in process manufacturing modules serving German chemical producers.
- HRM:Human resource management suites automate payroll, benefits administration, and talent acquisition workflows. These applications face compressed deployment cycles as cloud-native architectures displace multi-year implementation timelines.
- Accounting Software:Financial record-keeping and reporting tools serve as entry-point solutions for micro-enterprises scaling toward full ERP adoption. Indonesian government-mandated e-invoicing requirements are generating greenfield demand for localized accounting modules.
Widest installed base: ERP. Gaining share fastest: CRM.
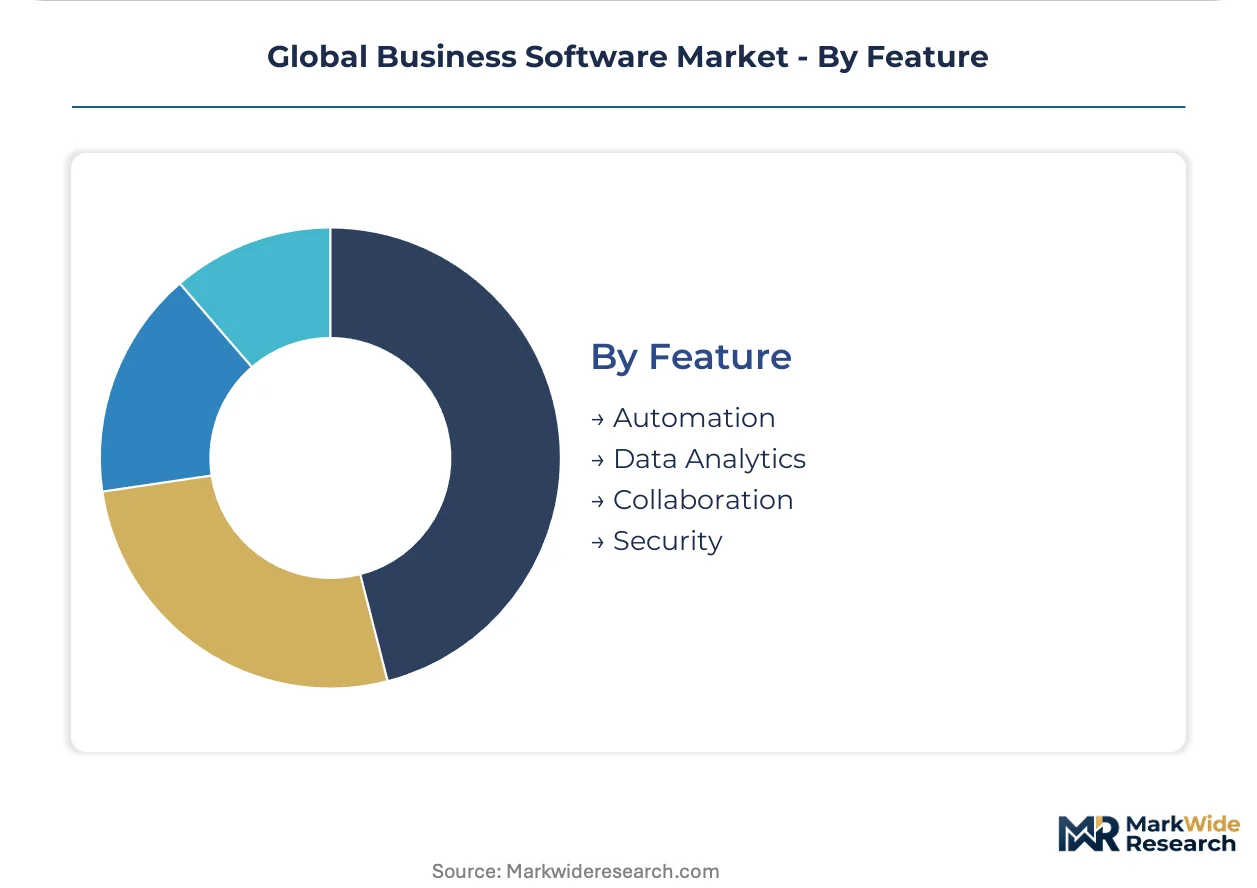
Feature:
Capability prioritization reflects organizational maturity, with advanced functions commanding premium pricing only after foundational infrastructure proves stable.
- Automation:Workflow engines and robotic process automation reduce manual intervention across repetitive tasks. Agentic AI orchestration layers are compressing traditional RPA-to-AI upgrade cycles from years to months for United States mid-market finance teams.
- Data Analytics:Business intelligence and predictive modeling tools transform operational data into strategic decision support. Embedded carbon accounting capabilities address CSRD disclosure requirements for EU-based multinationals converging ERP data models with emissions tracking APIs.
- Collaboration:Real-time document sharing, communication channels, and project management functions enable distributed workforce coordination. Post-pandemic hybrid work policies have elevated this feature to mandatory status across enterprise procurement evaluations.
- Security:Access controls, encryption protocols, and threat detection mechanisms protect sensitive commercial data. Vendor security audits now extend 9-14 months for ISO 27001 certification, delaying contract execution and revenue recognition across procurement functions.
Highest procurement priority: Security. Climbing the fastest: Automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software production concentrates in the United States while consumption spreads across manufacturing hubs in Germany, India, and Indonesia. Cloud infrastructure investments follow data residency requirements rather than pure cost optimization. Regulatory fragmentation between GDPR jurisdictions and sovereign data laws reshapes vendor deployment strategies.
United States
Mid-market finance teams pilot agentic AI orchestration for autonomous invoice reconciliation. SEC cybersecurity disclosure rules force hybrid architectures that reconcile legacy mainframe dependencies with cloud bursting capabilities. Silicon Valley clusters anchor generative AI embedding into core workflow applications.
Germany
Automotive suppliers and chemical producers drive demand for deep vertical ERP specialization. EU AI Act risk classification mandates algorithmic impact assessments as standard contract terms. Bavarian manufacturing clusters require ISO 27001 and SOC 2 Type II certifications as baseline procurement filters.
India
Discrete production facilities replace legacy MRP systems with modular SaaS platforms for export traceability. Government-mandated e-invoicing under digital transformation directives generates greenfield accounting module demand. Karnataka and Maharashtra host concentrated ERP replacement programs among mid-market manufacturers.
Indonesia
National digital transformation directives accelerate SaaS tax automation adoption among educational institutions and government agencies. Centralized procurement regulations extend vendor qualification periods for public sector contracts. Jakarta clusters concentrate localized ERP module deployment for compliance automation.
France
Insurance underwriters face immediate EU AI Act compliance deadlines for high-risk automated decision systems. CNIL oversight elevates embedded audit trail requirements in enterprise procurement. Parisian financial services clusters mandate human oversight documentation for algorithmic workflows.
Global Business Software Market Vendor Landscape
The competitive structure tilts toward platform consolidators with multi-product ecosystems. Incumbent vendors defend position through vertical specialization and compliance-embedded feature sets. Two archetypes dominate: cloud-native challengers with API-first microservices, and legacy suite providers restructuring around subscription retention. Competitive moves concentrate on strategic partnerships for multi-cloud integration and portfolio diversification into carbon accounting modules.
Within the platform consolidator tier, Microsoft Corporation and Oracle Corporation exemplify archetypes leveraging infrastructure-native application stacks for enterprise stickiness. Salesforce, Inc. occupies a position representing low-code extensibility specialists. SAP SE anchors the vertical specialization vector for process manufacturing modules. These three named entities collectively illustrate how vendor qualification criteria now filter toward compliance-embedded certification holders.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Oracle Corporation |
| SAP SE |
| IBM Corporation |
| Salesforce, Inc. |
| ServiceNow, Inc. |
| Workday, Inc. |
| Intuit Inc. |
| Infor, Inc. |
| Others |
Supply Flow & Price Mechanics
Cloud infrastructure costs cascade through SaaS subscription tiers, compressing margins for mid-tier vendors while hyperscalers capture premium pricing through Azure-native and AWS-integrated stacks. German automotive suppliers and French banking groups absorb higher per-seat costs for GDPR-compliant on-premises deployments, diverging from consumption-based models favored by Indian mid-market manufacturers.
Pricing Analysis
Margin tightening in the SME tier reflects hyperscaler marketplace commission structures and API-first microservices unbundling. Three-tier pricing structure across premium, standard, and economy levels anchors enterprise negotiations, with ISO 27001 and SOC 2 Type II certification premiums widening spreads. Cost-down pressure on mid-market ERP modules accelerates because SAP S/4HANA migration expertise concentrates among narrow systems integrator pools. Corporate buyers exhibit lowest price sensitivity due to compliance-embedded vendor lock-in, while educational institutions drive hardest bargain on volume-based SaaS contracts.
Supply Chain Analysis
Cross-border data transfer costs inflate cloud service delivery to regulated jurisdictions, forcing redundant regional infrastructure deployments. Software production concentrates in the United States, India, and Ireland, with intellectual property development anchored in Silicon Valley and Bengaluru clusters. Raw material dependencies center on semiconductor substrates for AI training infrastructure, undersea fiber capacity for latency-sensitive applications, and scarce SAP S/4HANA implementation talent. Single-source vulnerability concentrates in NVIDIA GPU supply for generative AI embedding. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams, with channel partners losing ground to self-service procurement portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into carbon accounting modules and compliance-embedded audit trails is reshaping competitive positioning, as vendors race to own the data layer connecting ERP systems to CSRD disclosure requirements.
For Market Incumbents: Lock in platform stickiness through deep vertical specialization in process manufacturing modules serving German chemical producers and automotive suppliers. Defend against API-first microservices fragmentation by embedding EU AI Act governance tooling directly into core workflows. Prioritize backward integration into emissions tracking APIs to capture CSRD-driven procurement mandates from EU-based multinationals. For New Entrants and Emerging Players: Begin with Indonesia's government-mandated e-invoicing and tax automation modules, where localized compliance requirements filter out global incumbents. Target Brazilian and Mexican vertical marketplaces aggregating niche compliance modules for mid-market government buyers. Lead with low-code extensibility and embedded AI workflows to bypass entrenched sales cycles in saturated CRM and HRM segments. For Investors and Strategic Acquirers: ISO 27001 certification timeline extensions to 9-14 months is the leading indicator that security-embedded vendors will command acquisition premiums over unqualified competitors. Mid-cap specialists with captive SAP S/4HANA migration expertise represent the most defensible acquisition profile across the analysis window. Watch for agentic AI orchestration pilots achieving production deployment in United States mid-market finance teams as the signal that autonomous workflow automation has crossed from experimental to enterprise-grade.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure-native application stacks sustain enterprise stickiness through unified identity management across multi-cloud environments. |
| Acquisition of Specialist Firm | Captive SAP S/4HANA migration expertise deflates implementation timelines and captures professional services revenue pools. |
| Strategic Partnership | Multi-cloud integration alliances address unified cost governance pain points for enterprises operating across AWS, Azure, and Google Cloud. |
| Product Launch | Embedded carbon accounting modules converge ERP data models with emissions tracking APIs for CSRD disclosure compliance. |
| Geographic Expansion | Localized ERP modules for Indonesia's digital transformation program capture greenfield demand from government and educational institutions. |
Methodological Framework
Document review covered SEC cybersecurity disclosure filings, EU AI Act implementation guidance, hyperscaler capex disclosures, and ISO certification databases, complemented by interviews with CTOs, IT procurement officers, platform engineers, and channel partners across the United States, Germany, and India. Primary fieldwork included structured conversations with SAP systems integrators, Salesforce implementation specialists, and cloud marketplace operators. Secondary validation drew from customs data on software services trade, hyperscaler regional infrastructure investment announcements, and enterprise software contract registries. Bottom-up deployment model penetration rates were triangulated against top-down market sizing from vendor revenue disclosures.
Historical CAGR trajectories were cross-referenced against panel input from vendor strategy teams and systems integrator capacity planning. The analytical framework modeled deployment architecture, organization size, vertical industry, integration complexity, and regional adoption pattern across the projection horizon. CAGRs were derived from segment-level growth rate convergence analysis. Industry-specific forecast inputs included EU AI Act compliance deadline schedules, Indonesia's national e-invoicing rollout timeline, and SAP S/4HANA end-of-maintenance commitments.
Underlying measurement precision varies by segment; cloud-based and SaaS deployment models carry tighter precision than hybrid architectures where legacy mainframe dependencies complicate migration timeline assumptions. Forecasts reflect documented assumptions around regulatory enforcement intensity and hyperscaler infrastructure expansion cadence. Stakeholders should weight assumptions against their own operating context, particularly regarding data residency requirements and available systems integration capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Feed Software Market
Software & Services
G Suite Technology Services Market
Software & Services
Collaborative Office Software Market
Software & Services
Africa HR Payroll Software Market
Software & Services
Global Data Entry Software Market
Software & Services
Global Healthcare Contract Management Software Market
Software & Services
Office Software Market
Software & Services
Global Data Extraction Software Market
Software & Services
Game Development Software Market
Software & Services
Pay-Per-Click (PPC) Software Market
Software & Services
Global DevOps Software Market
Software & Services
Global Qualitative Data Analysis Software Market
Software & Services
Specification Management Software Market
Software & Services
Global Order Management Software Market
Software & Services
Instant Messaging Software Market
Software & Services
Saas-Based SCM Market