
 Global Digital Vault Market | 2026-2036
Global Digital Vault Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Vault Market Foresight
Subscription-based project finance for cloud infrastructure is fragmenting competitive dynamics in digital vault provisioning. CyberArk Software Ltd. leverages privileged access management depth to sustain enterprise loyalty across hybrid deployments. IBM Corporation anchors its position through mainframe-integrated cryptographic vaulting for regulated workloads. Microsoft Corporation competes via Azure Confidential Computing integration with native key escrow services.
A digital vault is a hardened, cryptographically secured repository engineered to store sensitive digital assets with tamper-evident logging, multi-party access controls, and automated policy enforcement. The architecture typically employs AES-256 encryption, hardware security module key segregation, and immutable audit chains to protect credentials, certificates, and contractual records against unauthorized extraction or modification. Cloud-based deployment leads solution uptake as financial institutions migrate core custody operations away from capital-intensive on-premises HSM farms. Data encryption and access management solutions command the deepest margin pools because regulatory mandates in the BFSI and government sectors require demonstrable key segregation and role-based governance. Compliance management solutions are gaining velocity fastest where GDPR, SEC, and MAS rules impose strict data provenance and retention standards.
The U.S. SEC and FFIEC impose granular access logging and encryption standards on financial vault operators, while the EU GDPR and EU AI Act mandate data localization and automated breach disclosure that directly shape product roadmaps. ISO 27001 and SOC 2 Type II certifications function as market-access gatekeepers for vendors serving cross-border enterprises. Stakeholders must weigh sovereign cloud mandates against interoperability costs when selecting vault architectures for multi-jurisdiction operations.
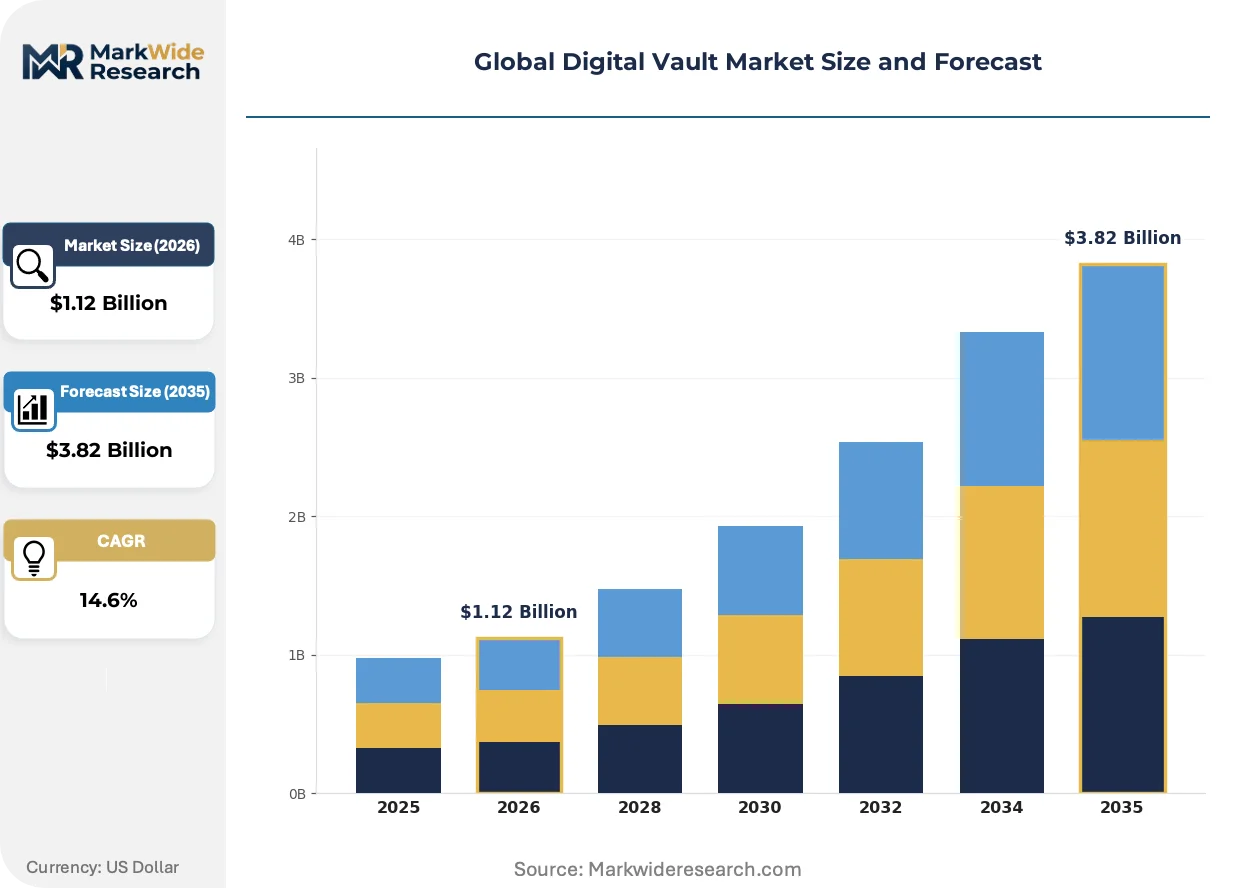
Market Dynamics
Financial institutions are abandoning capital-intensive on-premises hardware security module farms for subscription cloud vault architectures, restructuring vendor competitive dynamics around operational expenditure models rather than perpetual license economics.
Growth Catalysts
- EU AI Act data localization mandates:Automated breach disclosure and data provenance requirements in the European Union are compelling financial institutions to deploy sovereign cloud vault instances with immutable audit chains.
- Hardware security module as-a-service:Cloud-native HSM provisioning eliminates upfront capital barriers for mid-tier asset managers, accelerating vault adoption across Singapore's expanding wealth management sector.
- Post-trade settlement documentation digitization:Singapore's financial institutions are expanding digital vault deployments to automate custody of derivatives confirmation records and collateral agreements.
Market Restraints
- Specialized cryptographic engineering talent scarcity:Vault operators face acute shortages of professionals qualified in hardware security module firmware development and side-channel attack mitigation.
- Cross-border data transfer friction:Conflicting data residency requirements between EU GDPR, Singapore MAS guidelines, and US CLOUD Act create architectural complexity for multi-jurisdiction deployments.
- Quantum computing threat horizon:Long-dated certificate and key storage obligations in financial vaults confront the mathematical vulnerability of RSA and elliptic curve cryptography to fault-tolerant quantum systems.
Strategic Opportunities
- Confidential computing-encrypted memory enclaves:Convergence of Intel SGX and AMD SEV technologies with vault key management is collapsing the operational boundary between encryption-at-rest and encryption-in-use.
- India's digital rupee infrastructure:The Reserve Bank of India's central bank digital currency pilot creates demand for institutional-grade vault architectures among scheduled commercial banks.
- Automated policy enforcement APIs:Programmable vault governance enables embedded compliance for decentralized finance protocols seeking institutional custody partnerships.
Industry Challenges
- FIPS 140-3 Level 4 certification timelines:Physical tamper-resistance validation for next-generation hardware security modules extends vendor product development cycles by 18-24 months.
- Legacy mainframe cryptographic subsystem integration:Financial institutions running IBM z/OS environments require specialized middleware to bridge decades-old transaction processing with modern REST-based vault APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Vault Market |
| Market Size in 2026 | $1.12 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Virtual Solution: Data Encryption, Access Management, Compliance Management, Incident Response, Backup & Recovery Application: BFSI, Government, Energy & Utilities, Telecommunications, Media & Entertainment End User: Financial Institutions, Public Sector, Oil & Gas Firms, Telecom Operators, Content Creators |
| Companies Covered | Microsoft Corporation, Oracle Corporation, IBM Corporation, CyberArk Software Ltd., Hitachi Vantara LLC, Fiserv, Inc., Johnson Controls International Plc, Micro Focus International plc, Keeper Security, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Vault Market Shifts & Advancements
Vault architectures are converging with confidential computing primitives and programmable compliance engines, shifting competitive differentiation from static encryption strength to dynamic policy automation and workload isolation guarantees.
Confidential computing with encrypted memory enclaves is collapsing the traditional separation between key storage and computational environments. Financial institutions running derivatives pricing workloads in Frankfurt and Singapore are adopting Intel SGX and AMD SEV enclaves to process sensitive data without exposing decryption keys to host operating systems. This architectural shift is compressing demand for standalone hardware security module appliances by embedding equivalent cryptographic isolation directly within compute infrastructure.
The EU AI Act's automated logging and auditability requirements are reshaping vault product roadmaps for artificial intelligence training data custody. Providers serving model developers must now demonstrate immutable provenance chains for datasets containing personal information, with technical documentation subject to conformity assessment by notified bodies. German automotive manufacturers and French healthcare AI specialists represent the most affected buyer segments, with procurement specifications increasingly mandating EU sovereign cloud deployment.
Subscription consumption models are displacing perpetual license structures across enterprise vault procurement. Chief information security officers in US banking and German insurance are prioritizing operational expenditure alignment with cloud migration timelines, rejecting multi-year capital commitments for on-premises hardware. This behavioral shift favors vendors with native multi-tenant architectures and metered key-operation pricing, particularly visible in competitive evaluations for London-based hedge fund custody operations.
Global Digital Vault Market Segmentation
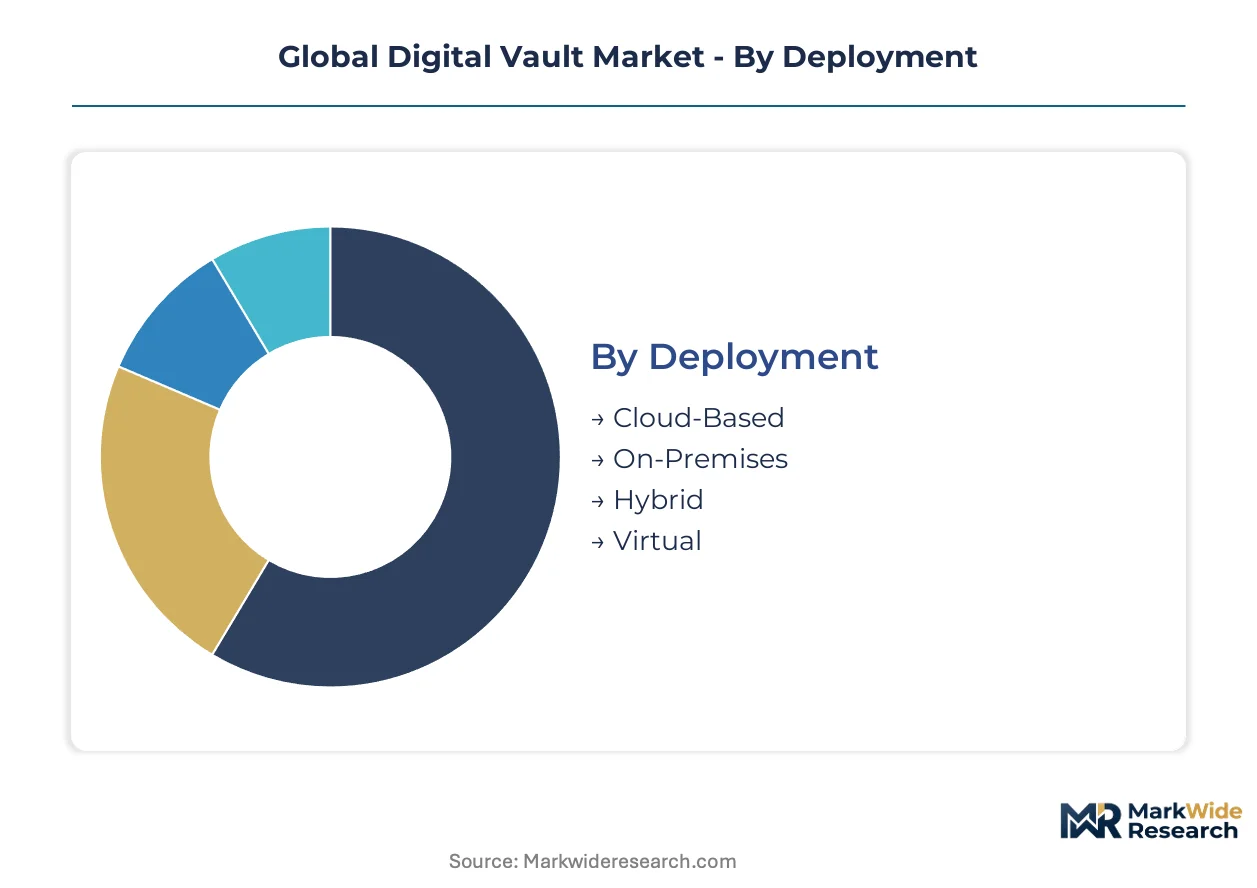
Digital vault procurement patterns diverge sharply across deployment architectures and regulatory contexts, with solution choice directly constraining operational expenditure profiles and compliance posture. Understanding segment-level technology cycles and margin structures enables vendors to align product roadmaps with buyer procurement priorities.
Deployment:
Cloud-based vault instances turn over fastest as financial institutions cycle through capacity expansions quarterly, while on-premises hardware refresh cycles extend across multiple years due to capital approval timelines.
- Cloud-Based:Multi-tenant architectures with metered consumption eliminate upfront HSM capital outlays. Singapore's wealth management sector and Frankfurt's derivatives clearing houses drive demand as MAS and BaFin auditors scrutinize data residency controls.
- On-Premises:Dedicated hardware security module farms with FIPS 140-2 Level 3 certification serve classified government workloads. US defense contractors and Swiss private banks maintain these deployments despite higher total cost of ownership.
- Hybrid:Split-custody models partition encryption keys between cloud and local HSM instances. Energy utilities in Germany and Australia adopt this architecture to satisfy critical infrastructure regulations while leveraging elastic compute.
- Virtual:Software-defined vaulting on commodity servers without dedicated cryptographic hardware. Mid-tier asset managers in India and Brazil deploy these for non-regulated document repositories.
Cloud-Based anchors the volume base while Hybrid gains share at the steepest rate as regulated industries seek operational flexibility without sacrificing audit compliance.
Solution:
Cost tier differentiation separates enterprise-grade platforms with FIPS certification from mid-market offerings, with compliance modules commanding premium pricing due to automated audit trail generation.
- Data Encryption:AES-256 and post-quantum algorithm implementations protect credentials and contractual records. BFSI procurement in the US, UK, and Japan prioritizes NIST-compliant key derivation functions.
- Access Management:Privileged credential vaulting with session recording and just-in-time elevation. This segment climbs the fastest as SEC and MAS mandate granular access logging for system administrators.
- Compliance Management:Automated policy enforcement with immutable audit chains for GDPR and EU AI Act documentation. German automotive AI developers and French healthcare data processors represent concentrated demand.
- Incident Response:Breach containment workflows with automated credential rotation and forensic preservation. Telecommunications operators in South Korea and Australia deploy these for critical infrastructure protection.
- Backup & Recovery:Cryptographically verifiable restoration of encrypted vault contents. Oil and gas firms in Norway and Saudi Arabia maintain these for operational technology continuity.
Data Encryption anchors the volume base while Access Management expands most quickly under escalating regulatory pressure on insider threat controls.
Application:
Customer maturity varies from BFSI's sophisticated procurement committees to media sector's reactive security investments following public breaches.
- BFSI:Derivatives confirmation storage, collateral agreement custody, and payment token vaulting. Singapore's post-trade settlement digitization and US Treasury market infrastructure upgrades concentrate demand.
- Government:Classified document repositories and citizen identity credential management. India's digital public infrastructure expansion and EU member state sovereign cloud mandates shape procurement specifications.
- Energy & Utilities:Operational technology credential isolation and grid control system key management. German and Australian critical infrastructure operators face tightening national security audits.
- Telecommunications:Subscriber identity protection and lawful intercept data custody. South Korean and Japanese carriers deploy these under telecommunications security frameworks.
- Media & Entertainment:Content distribution key management and royalty transaction records. This segment shows the steepest expansion trajectory as streaming platforms secure pre-release content against piracy.
BFSI anchors the volume base while Media & Entertainment gains share at the steepest rate as content piracy losses drive security investment.
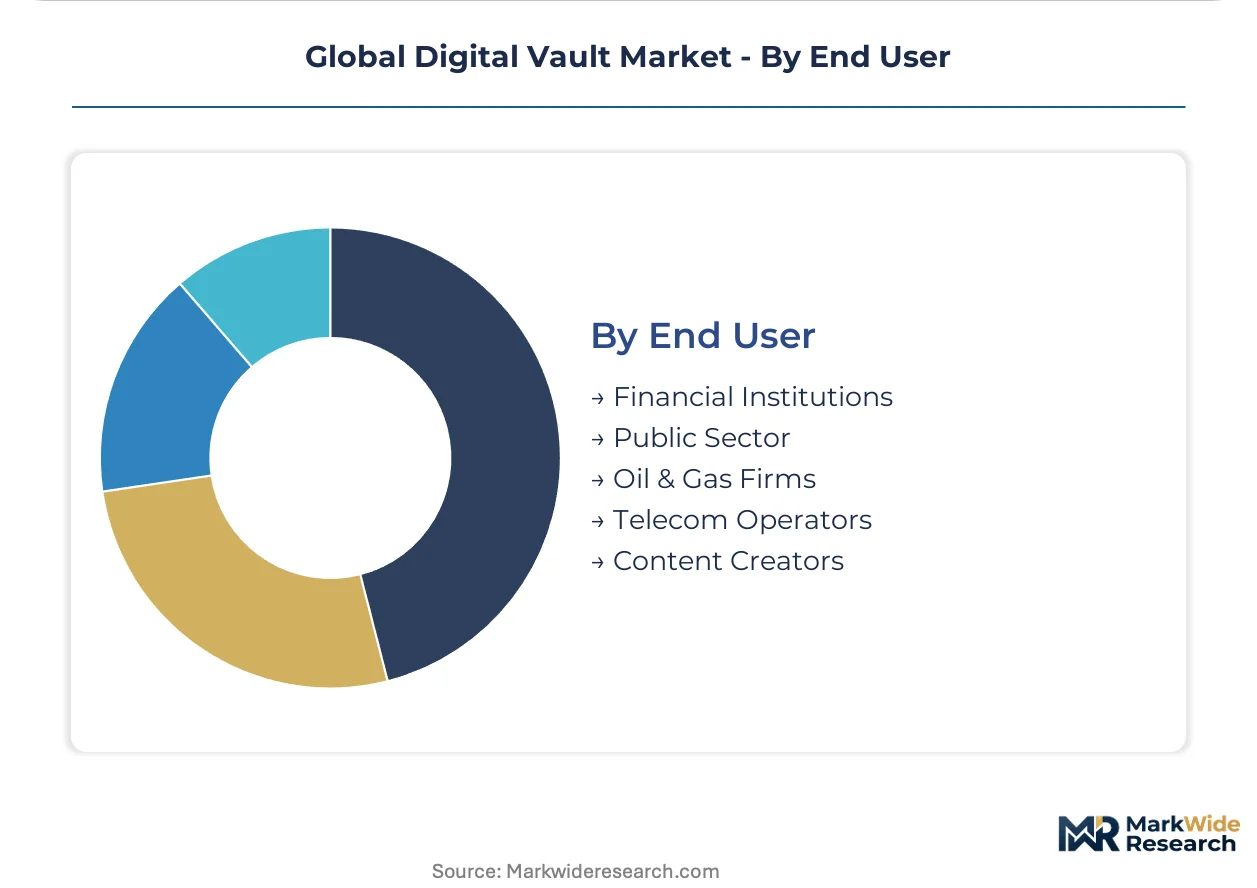
End User:
Volume concentration sits with institutional buyers running multi-year enterprise agreements, while content creator adoption spreads through self-service SaaS platforms with monthly billing.
- Financial Institutions:Investment banks, asset managers, and insurance carriers with dedicated CISO organizations. Frankfurt, London, and Singapore financial districts represent geographic clustering.
- Public Sector:National identity authorities, tax administrations, and defense procurement agencies. India's UIDAI and Germany's federal IT consolidation programs drive specification requirements.
- Oil & Gas Firms:Upstream exploration data protection and downstream trading documentation. Norwegian and Saudi national oil companies maintain the most stringent security postures.
- Telecom Operators:Mobile network authentication centers and 5G infrastructure key management. South Korean and Japanese carriers lead deployment sophistication.
- Content Creators:Production studios, music labels, and independent streaming platforms. Los Angeles and Mumbai production clusters adopt vaulting for pre-release content protection.
Financial Institutions anchors the volume base while Content Creators gains share at the steepest rate as independent production security budgets expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sovereign data residency mandates are reshaping procurement specifications across financial centers, with regulators in Singapore, Germany, and the United States imposing divergent technical requirements that fragment deployment architectures.
United States
SEC and FFIEC auditors enforce granular access logging for derivatives clearinghouses and asset managers operating from New York and Chicago. Treasury market infrastructure upgrades concentrate demand in Manhattan's financial district, where institutions deploy vault instances for payment token custody and collateral agreement automation.
Singapore
Wealth management sector expansion and post-trade settlement digitization drive cloud vault adoption across the Marina Bay financial hub. MAS guidelines on data localization compel institutions to maintain sovereign cloud instances with immutable audit chains for derivatives confirmation records.
Germany
BaFin scrutiny and EU AI Act automated breach disclosure requirements shape procurement for Frankfurt's derivatives clearing houses. Automotive manufacturers in Stuttgart and Munich deploy vault architectures for AI training data custody with conformity assessment documentation.
India
RBI's central bank digital currency pilot creates institutional demand among scheduled commercial banks in Mumbai and Delhi. The country's digital public infrastructure expansion drives specification requirements for citizen identity credential management and tax administration vaulting.
United Kingdom
FCA operational resilience mandates and post-Brexit data transfer arrangements complicate multi-jurisdiction deployments for London-based hedge funds and investment banks. The City of London concentrates demand for hybrid vault architectures splitting custody between local HSM instances and EU sovereign cloud.
Global Digital Vault Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: cloud-native platform operators, mainframe-integrated legacy specialists, and privileged access management depth players. Strategic archetypes include subscription-scale aggregators, FIPS-certified hardware purists, and confidential computing integrators. Competitive dynamics center on M&A activity targeting API governance startups and strategic partnerships bridging legacy mainframe environments with REST-based vault architectures.
Within the cloud-native tier, Microsoft Corporation and Oracle Corporation exemplify platform-scale aggregation strategies. IBM Corporation anchors the mainframe-integrated specialist segment with z/OS cryptographic subsystem expertise. CyberArk Software Ltd. occupies a distinct position in privileged access management depth, sustaining enterprise loyalty across hybrid deployment patterns.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Oracle Corporation |
| IBM Corporation |
| CyberArk Software Ltd. |
| Hitachi Vantara LLC |
| Fiserv, Inc. |
| Johnson Controls International Plc |
| Micro Focus International plc |
| Keeper Security, Inc. |
| Others |
Supply & Pricing Matrix
Hardware security module fabrication concentrates in Taiwan and South Korea, anchoring margin capture for FIPS 140-2 Level 3 certified vault appliances while subscription SaaS models downstream compress differentiation to operational reliability metrics.
Pricing Analysis
Certification grade creates the primary spread between FIPS 140-2 Level 3 appliances and software-defined virtual instances. Three-tier pricing structure across sovereign cloud deployments, hybrid split-custody architectures, and commodity virtual vaults reflects compliance burden rather than encryption strength. Cost compression in virtual tiers intensifies as Indian and Brazilian mid-tier asset managers prioritize operational expenditure alignment. Financial institutions in Frankfurt and Singapore exhibit lowest price sensitivity due to regulatory audit requirements, while independent content creators in Mumbai and Los Angeles drive volume through self-service SaaS platforms with monthly billing.
Supply Chain Analysis
US export controls on advanced cryptographic processors limit hardware security module flows to sovereign cloud operators in Germany and Singapore. Taiwan and South Korea anchor HSM chip fabrication, while China and Vietnam supply commodity server hardware for virtual deployments. Raw material dependencies span silicon wafers, tamper-resistant enclosures, and quantum-resistant algorithm libraries. Single-source vulnerability concentrates in advanced node semiconductor fabrication. Distribution runs through direct enterprise sales for certified appliances and hyperscaler marketplaces for cloud-native instances.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital vault market enters a cyclical recovery phase as financial institutions restart capital expenditure cycles deferred through rate tightening, with Singapore's post-trade settlement digitization serving as the leading indicator.
For Market Incumbents: Insulate recurring revenue streams by deepening FIPS 140-3 Level 4 certification investment ahead of competitor product cycles, while embedding confidential computing enclaves into existing customer workloads to raise switching costs against cloud-native entrants. The quantum computing threat horizon demands accelerated post-quantum cryptography R&D to defend long-dated key storage contracts. For New Entrants and Emerging Players: Mid-market wealth managers in Southeast Asia represent the most penetrable entry point, with India's scheduled commercial banks participating in the Reserve Bank of India's central bank digital currency pilot forming a secondary beachhead. Automated policy enforcement APIs for decentralized finance protocols offer a technical wedge for institutional custody partnerships without competing head-to-head on FIPS certification. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed privileged access management specialists seeking platform scale through vaulting capability adjacencies. Five-to-ten year viability hinges on quantum-resistant migration roadmaps and confidential computing integration depth. The signal to watch is FIPS 140-3 Level 4 certification completion timelines as a proxy for technical moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Cryptography Migration | Long-dated financial key storage obligations in Frankfurt and Singapore require algorithmic upgrades before fault-tolerant quantum systems mature. |
| Confidential Computing Integration | Intel SGX and AMD SEV enclave convergence collapses the boundary between encryption-at-rest and encryption-in-use for derivatives pricing workloads. |
| Sovereign Cloud Partnership | EU AI Act data localization mandates in Germany and MAS guidelines in Singapore compel region-specific instance deployment. |
| API Governance Acquisition | Programmable vault compliance engines enable embedded policy enforcement for decentralized finance institutional custody partnerships. |
| Legacy Mainframe Bridge Development | IBM z/OS cryptographic subsystem middleware connects decades-old transaction processing with modern REST-based vault architectures. |
Research Methodology
Cross-validation between primary interviews with chief information security officers, cloud infrastructure architects, and regulatory compliance leads anchors the qualitative findings, while secondary validation draws from SEC filings, MAS regulatory circulars, EU AI Act technical documentation, and hyperscaler capex disclosures. Bottom-up and top-down triangulation reconciles vendor shipment data with enterprise procurement patterns across the analysis window.
Calibration against historical adoption curves in financial services and government sectors shapes the analytical framework. Segmentation dimensions span deployment architecture, solution type, application vertical, and end-user scale across the projection horizon. CAGRs derive from fitted growth curves adjusted for regulatory mandate implementation timelines and hardware refresh cycle patterns. Quantum computing threat assessments and confidential computing penetration rates constitute industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in central bank rate trajectories and sovereign cloud infrastructure investment flows would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement intensity and certification timeline adherence. Material shifts in FIPS 140-3 validation schedules or quantum computing breakthrough timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
NFT Analytics Tools Market
Digital Assets and Cryptocurrency Finance
Digital Asset Trading Platform Market
Digital Assets and Cryptocurrency Finance
Global Non-Fungible Tokens Market
Digital Assets and Cryptocurrency Finance
Crypto Asset Management Platform Market
Digital Assets and Cryptocurrency Finance
Smart Contracts Platforms Market
Digital Assets and Cryptocurrency Finance
Decentralized Finance Market
Digital Assets and Cryptocurrency Finance
Germany Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Hardware Wallet Market
Digital Assets and Cryptocurrency Finance
South Korea Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
Global Smart Contracts Market
Digital Assets and Cryptocurrency Finance
GCC Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
Automated Trading Market
Digital Assets and Cryptocurrency Finance
United States Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
Digital Collectibles Platform Market
Digital Assets and Cryptocurrency Finance
Digital Finance Market
Digital Assets and Cryptocurrency Finance
Bitcoin and Cryptocurrency Atms Market