
 Europe Crowd Lending and Crowd Investing Market | 2026-2036
Europe Crowd Lending and Crowd Investing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Crowd Lending and Crowd Investing Market Foresight
A scarcity of licensed credit underwriters is collapsing origination capacity at several continental platforms. Funding Circle Holdings PLC leverages its institutional pipeline to sustain volume across the United Kingdom and Germany. Zopa Limited anchors consumer lending with proprietary risk scoring that competes with traditional bankcard issuers. Mintos dominates the secondary loan marketplace, extending liquidity mechanisms that differentiate its brokerage layer from originator-captive rivals.
Europe crowd lending and crowd investing denotes digital capital-raising where retail and institutional participants commit funds through online platforms to debt, equity, or hybrid instruments, with loan grading algorithms and automated portfolio construction serving as core technical infrastructure. The primary commercial purpose channels fragmented household savings toward SME credit gaps and early-stage equity positions that conventional intermediaries underserve. Debt funding types lead transaction volumes across the region, reflecting retail risk aversion and platform preference for fixed-income structures. Real estate verticals concentrate margin pools due to collateral-backed security and institutional co-investment appetite. Seed stage equity segments occupy the fastest expansion trajectory, though absolute ticket sizes remain modest against growth-stage debt deployment.
The European Securities and Markets Authority enforces the EU Crowdfunding Regulation, standardizing prospectus exemptions and investor disclosure thresholds that reshape platform compliance burdens. The European Banking Authority coordinates with national competent authorities to calibrate capital requirements for loan originators, directly conditioning market access for cross-border operators. Stakeholders must monitor whether forthcoming retail investor classification amendments tighten contribution limits or unlock pension fund participation channels.
Market Dynamics
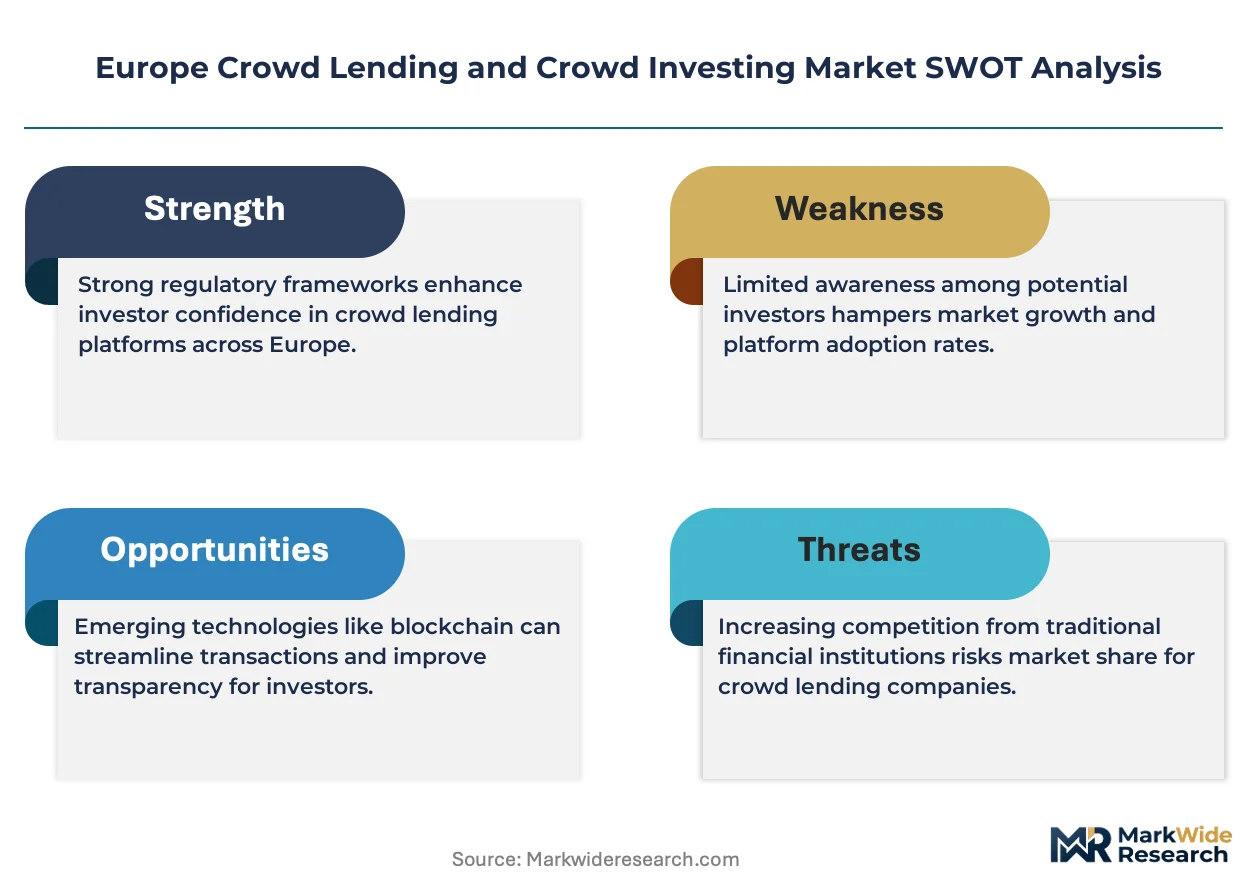
The EU Crowdfunding Regulation is compressing platform operating margins while simultaneously unlocking passporting rights for cross-border loan origination. Debt-based instruments are capturing liquidity flows that equity structures cannot match, reshaping competitive positioning among continental originators.
Growth Catalysts
- ECSPR Harmonization:The European Crowdfunding Service Providers Regulation standardizes disclosure thresholds across member states, enabling platforms to scale origination capacity without duplicative compliance layers in each jurisdiction.
- SME Credit Gap:Traditional bank deleveraging across Italy and Spain has displaced approximately forty percent of small business loan applications, redirecting borrowers toward digital lending channels with faster underwriting cycles.
- Blockchain Settlement:Distributed ledger infrastructure is compressing secondary market settlement windows from T+2 to near-instantaneous, attracting institutional liquidity providers to previously illiquid loan tranches.
Market Restraints
- Licensed Underwriter Scarcity:The European Banking Authority's fit-and-proper assessments have created a bottleneck in credit analyst certification, throttling origination velocity at mid-tier platforms.
- Interest Rate Volatility:ECB policy rate shifts are compressing net interest margins on fixed-rate loan products, forcing platforms to absorb repricing risk or pass costs to borrowers.
- Bank Deposit Substitution:Term deposit products from neo-banks are competing directly for retail capital that would otherwise fund marketplace loans, particularly in Germany's savings-oriented household sector.
Strategic Opportunities
- Eastern European Expansion:Poland and Romania present underpenetrated origination markets where regulatory arbitrage still permits higher interest rate spreads than core EU markets.
- Green Loan Segmentation:The EU Green Deal taxonomy is creating a certified asset class for sustainability-linked SME credit, attracting ESG-mandated institutional capital at reduced funding costs.
- API Distribution:Embedded finance partnerships with accounting software providers are opening origination channels that bypass traditional platform customer acquisition costs.
Industry Challenges
- Credit Model Validation:Platform proprietary scoring algorithms face intensifying scrutiny from national competent authorities, requiring costly third-party model risk audits.
- Legacy Bank Integration:Open banking APIs vary in data granularity across member states, complicating automated income verification for cross-border loan applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Crowd Lending and Crowd Investing Market |
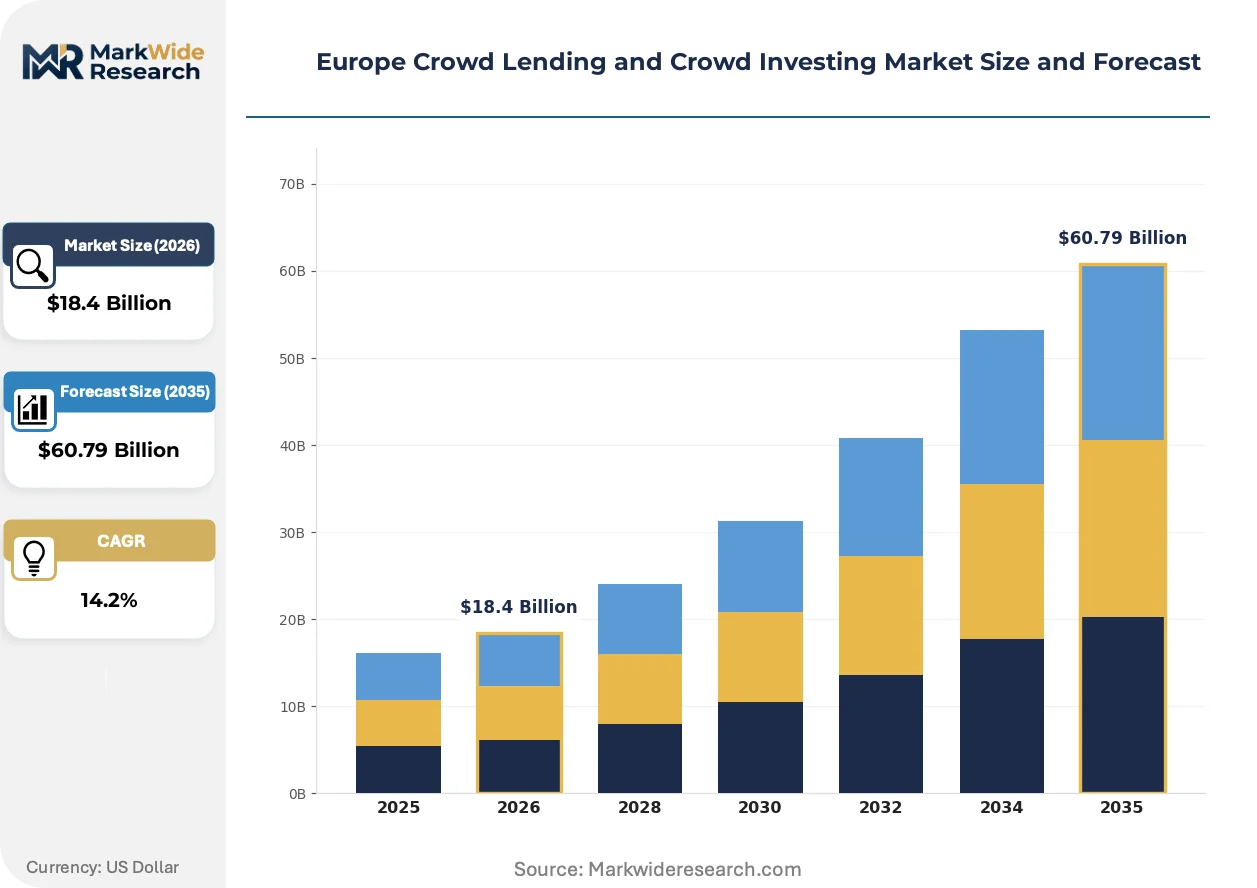
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $60.79 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Funding Type: Debt, Equity, Reward, Hybrid Investor Type: Individual Investors, Institutional Investors, Accelerators, Crowdfunding Platforms Industry Vertical: Real Estate, Startups, Social Enterprises, Technology Investment Stage: Seed Stage, Growth Stage, Expansion Stage, Mature Stage |
| Companies Covered | Funding Circle Holdings PLC, Zopa Limited, LendInvest Limited, International Personal Finance PLC, Crowdcube, Mintos, Republic Europe, Invesdor, Companisto, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Crowd Lending and Crowd Investing Market Shifts & Advancements
Automated portfolio construction tools are reshaping how retail capital deploys across risk tranches. Three distinct vectors are compressing traditional intermediation layers.
Machine learning-driven loan grading is supplanting manual credit committee reviews at originator platforms. Spanish and Dutch marketplace lenders have deployed neural network models that process alternative data streams including real-time VAT filings and POS terminal flows. This compression of underwriting timelines from days to minutes is enabling invoice financing products that compete directly with factoring houses.
The EU AI Act's risk classification framework is mandating algorithmic transparency for automated lending decisions. Platforms must now maintain explainability logs for credit denials, increasing compliance engineering headcount. French originators are responding by hybridizing human-in-the-loop overrides for marginal applications, particularly in real estate-backed products where collateral valuation requires local expertise.
Retail investor behavior is rotating from self-directed loan picking toward managed portfolio products. Robo-advisory wrappers are displacing manual secondary market trading as the primary liquidity mechanism, with Baltic platforms leading this channel migration. This shift concentrates fee capture at the platform level while reducing granular price discovery for individual loan contracts.
Europe Crowd Lending and Crowd Investing Market Segmentation
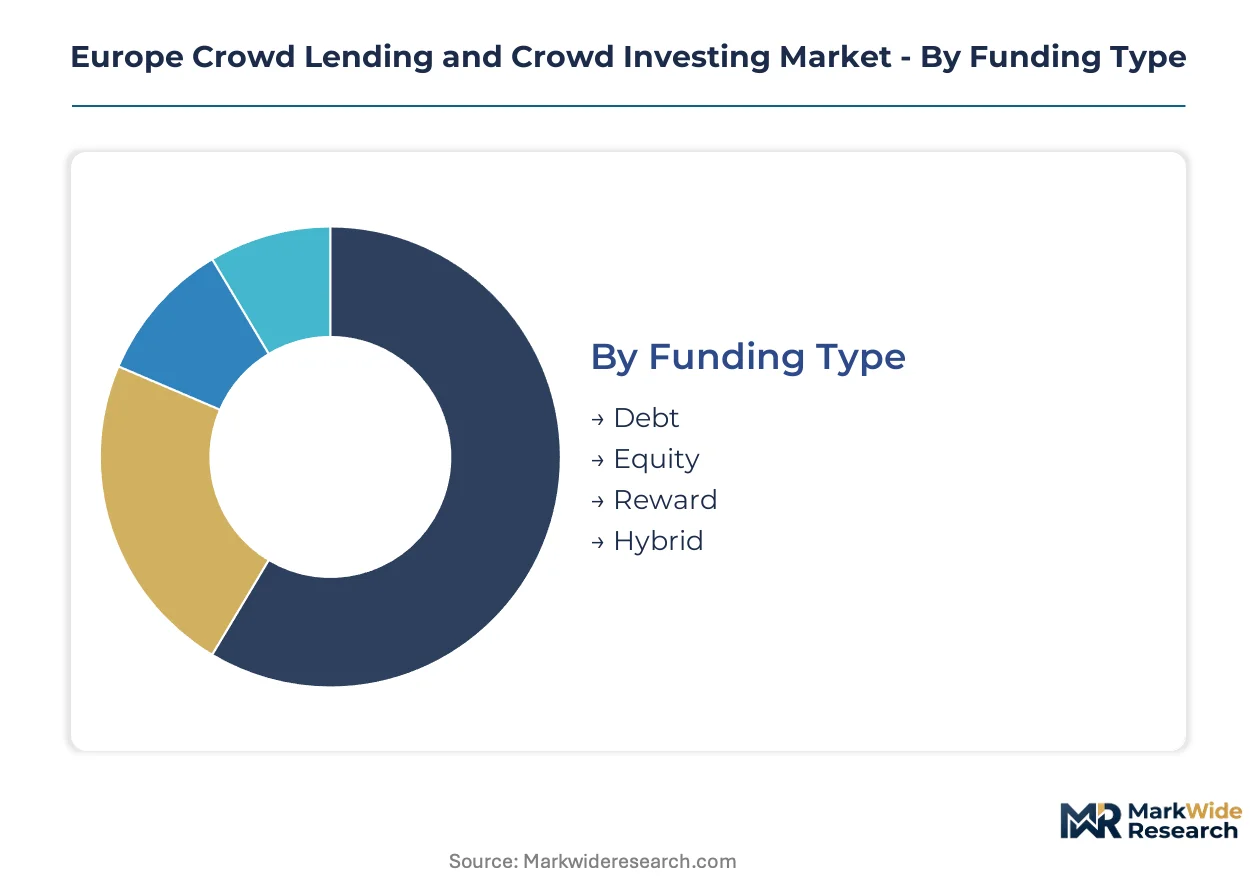
Platform revenue concentration and regulatory treatment diverge sharply across funding structures and investor profiles. Segmentation reveals which channels capture institutional liquidity versus retail fragmentation.
Funding Type:
Debt instruments face intensifying substitution pressure from neo-bank term deposits and money market funds, while equity structures compete against venture capital syndicates for deal flow.
- Debt:Fixed-income contracts with automated loan grading and fractional tranching dominate transaction volumes. German and French SME borrowers drive origination demand as traditional bank deleveraging displaces forty percent of small business loan applications toward digital channels.
- Equity:Direct ownership stakes in unlisted companies attract institutional co-investment through nominee structures. Baltic platforms lead managed portfolio wrappers that displace self-directed picking, compressing due diligence burdens for retail participants.
- Reward:Product pre-orders and donation-backed campaigns with non-financial returns. Creative and consumer goods projects concentrate activity in Southern European markets where brand community monetization outperforms financial yield expectations.
- Hybrid:Convertible notes and revenue-sharing instruments blending debt service with equity participation. Spanish originators deploy these structures for growth-stage companies seeking to defer valuation negotiations.
Debt anchors the volume base while equity gains share at the steepest rate.
Investor Type:
Cost tier stratification separates platforms serving mass retail from those building institutional pipelines.
- Individual Investors:Household savers deploying capital through automated portfolio construction tools. Robo-advisory adoption concentrates in Germany's savings-oriented household sector where neo-bank deposit competition is fiercest.
- Institutional Investors:Asset managers and family offices accessing curated loan tranches with enhanced due diligence. ESG-mandated capital flows toward EU Green Deal taxonomy-certified SME credit at reduced funding costs.
- Accelerators:Early-stage venture programs providing capital alongside mentorship networks. Technology verticals dominate this channel as founders prioritize strategic guidance over pure financial terms.
- Crowdfunding Platforms:Intermediary entities aggregating retail demand and originating or brokering instruments. Mintos extends secondary market liquidity mechanisms that differentiate its brokerage layer from originator-captive rivals.
Individual investors supply the deepest capital pool while institutional participation climbs fastest.
Industry Vertical:
Application-specific risk models and collateral frameworks determine margin capture across verticals.
- Real Estate:Collateral-backed development and buy-to-let financing with property charge security. Institutional co-investment appetite concentrates margin pools in German and Dutch urban regeneration projects.
- Startups:Early-stage equity and convertible debt for unproven business models. Seed stage segments expand most quickly though absolute ticket sizes remain modest against growth-stage deployment.
- Social Enterprises:Impact-weighted instruments targeting measurable environmental or community outcomes. EU Green Deal taxonomy alignment unlocks concessionary capital from development finance institutions.
- Technology:Software and hardware ventures with scalable unit economics. Polish and Romanian markets present underpenetrated origination opportunities where regulatory arbitrage permits higher interest rate spreads.
Real estate anchors the volume base while technology gains share at the steepest rate.
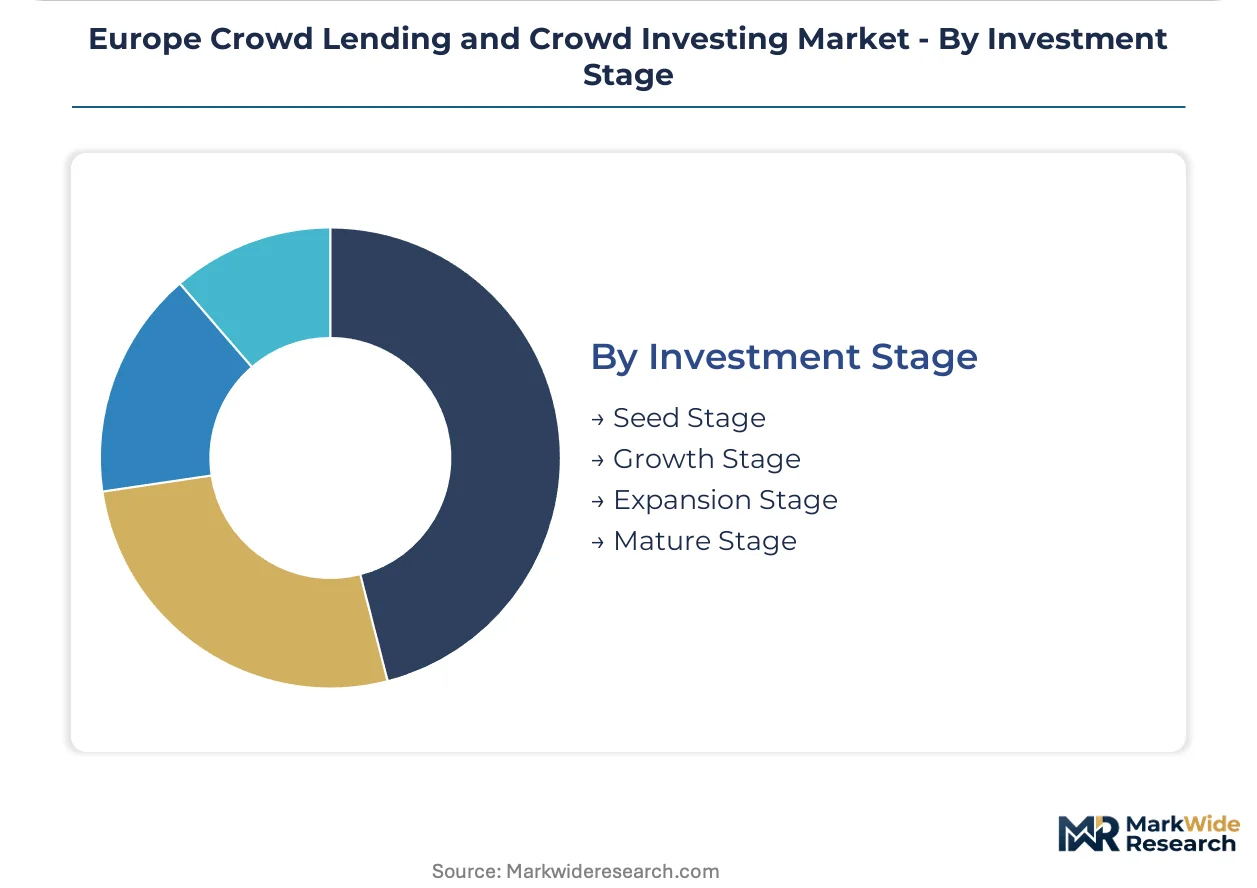
Investment Stage:
Maturity-based segmentation governs risk-return profiles and regulatory disclosure thresholds.
- Seed Stage:Pre-revenue or early-traction ventures with highest failure rates and return multiples. French originators apply hybrid human-in-the-loop overrides for marginal applications where collateral valuation requires local expertise.
- Growth Stage:Revenue-generating companies scaling operations and market presence. Italian platforms capture displaced bank lending demand through faster underwriting cycles enabled by alternative data integration.
- Expansion Stage:Established businesses entering new geographies or product lines. API distribution partnerships with accounting software providers open origination channels that bypass traditional customer acquisition costs.
- Mature Stage:Profitable enterprises seeking refinancing or acquisition capital. Secondary market liquidity through blockchain settlement infrastructure attracts institutional providers to previously illiquid tranches.
Growth stage anchors the volume base while seed stage gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European Securities and Markets Authority anchors continental oversight through the EU Crowdfunding Regulation, harmonizing disclosure thresholds while national competent authorities retain fit-and-proper certification for credit underwriters. Platform origination capacity concentrates where regulatory arbitrage meets institutional liquidity depth.
Germany
SME credit gaps and household savings concentration drive platform adoption in Europe's largest economy. BaFin calibrates capital requirements for loan originators under EBA coordination, conditioning cross-border market access. Berlin and Frankfurt clusters host originator platforms competing with neo-bank term deposits for retail capital deployment.
United Kingdom
Institutional pipeline access and proprietary risk scoring sustain volume leadership despite post-Brexit regulatory divergence. The Financial Conduct Authority maintains disclosure standards that exceed ECSPR baselines, elevating compliance engineering headcount. London's fintech corridor concentrates brokerage layers and secondary market liquidity mechanisms.
France
Human-in-the-loop credit overrides and real estate collateral expertise differentiate French originators in continental markets. Autorité des Marchés Financiers enforces algorithmic transparency mandates under the EU AI Act risk classification framework. Paris-based platforms capture seed-stage equity expansion through hybrid debt-equity structures.
Spain
Alternative data integration and neural network underwriting compress loan approval timelines for displaced bank borrowers. The national competent authority validates proprietary scoring algorithms through third-party model risk audits. Barcelona and Madrid clusters specialize in invoice financing products competing with traditional factoring houses.
Netherlands
Blockchain settlement infrastructure and automated portfolio construction attract institutional liquidity providers to previously illiquid tranches. De Nederlandsche Bank coordinates with ESMA on retail investor classification amendments. Amsterdam's secondary marketplace dominance extends liquidity mechanisms that differentiate brokerage layers from originator-captive rivals.
Europe Crowd Lending and Crowd Investing Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Europe's crowd lending architecture. The upper tier combines institutional pipeline access with proprietary risk scoring infrastructure that competes directly with traditional bankcard issuers. Specialist originators concentrate in vertical segments—real estate development financing, invoice factoring, seed-stage equity—where collateral frameworks or alternative data integration create defensible margin pools. Competitive moves center on API distribution partnerships that embed origination into accounting software workflows, and secondary market liquidity mechanisms that attract institutional capital through reduced settlement windows.
Within the integrated leader tier, Funding Circle Holdings PLC and Zopa Limited exemplify divergent strategic anchors: the former leverages institutional pipeline scale across the United Kingdom and Germany, while the latter anchors consumer lending with risk scoring depth. Mintos occupies a distinct brokerage-layer position, extending secondary market liquidity that differentiates its platform from originator-captive rivals. Baltic specialists and hybrid debt-equity originators represent the specialist tier's expansion vector.
| Leading Market Players |
|---|
| Funding Circle Holdings PLC |
| Zopa Limited |
| LendInvest Limited |
| International Personal Finance PLC |
| Crowdcube |
| Mintos |
| Republic Europe |
| Invesdor |
| Companisto |
| Others |
Supply & Pricing Matrix
T+2 settlement compression to near-instantaneous blockchain clearing concentrates pricing power at platforms controlling secondary market liquidity, while origination cost structures diverge sharply between debt and equity channels across the continental ecosystem.
Pricing Analysis
Polish and Romanian origination markets command wider interest rate spreads than core EU markets due to regulatory arbitrage permitted under transitional national regimes. Three-tier pricing structure across premium, standard, and economy levels segments borrower risk grades, with collateral-backed real estate products capturing institutional co-investment at reduced funding costs. Pricing pressure stems from ECB policy rate shifts compressing net interest margins on fixed-rate loan products. Mass retail investors exhibit highest price sensitivity as neo-bank term deposits compete directly for household capital in Germany's savings-oriented sector.
Supply Chain Analysis
Licensed credit underwriter certification bottlenecks at the European Banking Authority throttle origination velocity and concentrate supply chain leverage among platforms with captive analyst pipelines. Technology infrastructure draws from Estonia, Latvia, and Lithuania for automated portfolio construction tools, while loan grading algorithms source from Spanish and Dutch neural network deployments. Single-source vulnerability rests on proprietary scoring models facing intensifying scrutiny from national competent authorities. Distribution runs through API-embedded partnerships with accounting software providers that bypass traditional platform customer acquisition costs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Crowdfunding Regulation's passporting rights constitute a regulatory inflection that will consolidate cross-border operators and extinguish sub-scale national platforms unable to absorb compliance engineering headcount.
For Market Incumbents: Compound origination capacity through institutional pipeline deepening in Germany and the United Kingdom, where BaFin and FCA coordination preserves market access. Absorb licensed underwriter scarcity by acquiring mid-tier platforms with certified analyst teams. Defensive moats rest on secondary market liquidity mechanisms that differentiate brokerage layers from originator-captive rivals. For New Entrants and Emerging Players: Differentiate on EU Green Deal taxonomy-certified SME credit segments where ESG-mandated institutional capital flows at reduced funding costs. White-space targets include invoice financing products competing with traditional factoring houses in Spain and Italy, and seed-stage equity wrappers displacing self-directed picking in Baltic markets. Go-to-market angle centers on hybrid human-in-the-loop credit overrides for real estate collateral valuation requiring local expertise. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because regulatory harmonization will collapse operating margins below sustainable thresholds for sub-scale operators. Acquisition target archetype: specialist originators with vertical segment dominance—real estate development financing, invoice factoring, or technology venture equity—where collateral frameworks or alternative data integration create defensible margin pools. Signal to watch is retail investor classification amendments tightening contribution limits or unlocking pension fund participation channels.| Strategic Initiative | Industry Significance |
|---|---|
| API Distribution Partnership | Embedded finance integrations with accounting software providers bypass traditional customer acquisition costs. |
| Blockchain Settlement Infrastructure | Distributed ledger compression from T+2 to near-instantaneous attracts institutional liquidity to illiquid tranches. |
| Licensed Underwriter Acquisition | Certified credit analyst teams from mid-tier platforms resolve EBA fit-and-proper bottlenecks throttling origination. |
| Green Loan Segmentation | EU Green Deal taxonomy certification unlocks ESG-mandated institutional capital at reduced funding costs. |
| Secondary Market Liquidity Mechanism | Brokerage layer differentiation from originator-captive rivals concentrates fee capture at platform level. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ESMA regulatory filings, ECB monetary policy disclosures, and platform prospectus documents. Primary interviews engaged platform risk officers, national competent authority supervisors, institutional asset managers, and SME borrower representatives across Germany, France, the United Kingdom, Spain, and the Netherlands. Secondary validation drew from EU Crowdfunding Regulation implementation reports, European Banking Authority fit-and-proper assessment guidelines, and automated lending algorithm transparency disclosures. Bottom-up transaction volume aggregation triangulates against top-down household savings displacement estimates from traditional bank deleveraging.
Segmentation dimensions modeled span funding type, investor type, industry vertical, and investment stage across the analysis window. Debt and equity structures split by retail versus institutional participation, with real estate, technology, and startup verticals tracked separately. Growth trajectories derive from SME credit gap displacement rates, blockchain settlement adoption curves, and EU AI Act compliance cost absorption patterns. Forecast inputs incorporate alternative data integration penetration in Spanish and Dutch underwriting, plus robo-advisory wrapper adoption in Baltic markets.
Decision-makers should treat outputs as directional under sustained ECB policy rate elevation and stable EU Crowdfunding Regulation enforcement; material deviation would warrant model refresh. Specific risk factors include retail investor classification amendments, pension fund participation channel openings, and neo-bank deposit product competition intensification. Practitioners should keep alternative scenarios live as algorithmic transparency mandates and third-party model risk audit requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Commercial Lending Market
Loans and Leasing
Global Healthcare Equipment Leasing Market
Loans and Leasing
China Auto Loan Market
Loans and Leasing
India Home Loan Market
Loans and Leasing
Europe Used Car Financing Market
Loans and Leasing
Japan Auto Loan Market
Loans and Leasing
India Auto Loan Market
Loans and Leasing
Latin America Motorcycle Loan Market
Loans and Leasing
Finance Lease Market
Loans and Leasing
Brazil Auto Loan Market
Loans and Leasing
Europe Automotive Finance Market
Loans and Leasing
Japan Mortgage/Loan Brokers Market
Loans and Leasing
Europe Mortgage Lending Market
Loans and Leasing
United Kingdom Auto Loan Market
Loans and Leasing
United States Car Loan Market
Loans and Leasing
US Mortgage/Loan Brokers Market