
 Cosmetic Pipette Market | 2026-2036
Cosmetic Pipette Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic Pipette Market Outlook
European glassworks capacity is restructuring as artisanal producers scale precision-blowing lines for cosmetic-grade droppers. Virospack leverages its Barcelona manufacturing base to supply calibrated glass pipettes for luxury serum houses. Comar sustains North American throughput with automated plastic pipette assembly serving mass-market lip gloss brands. Quadpack competes through design-led dropper systems that anchor shelf differentiation for indie beauty labels.
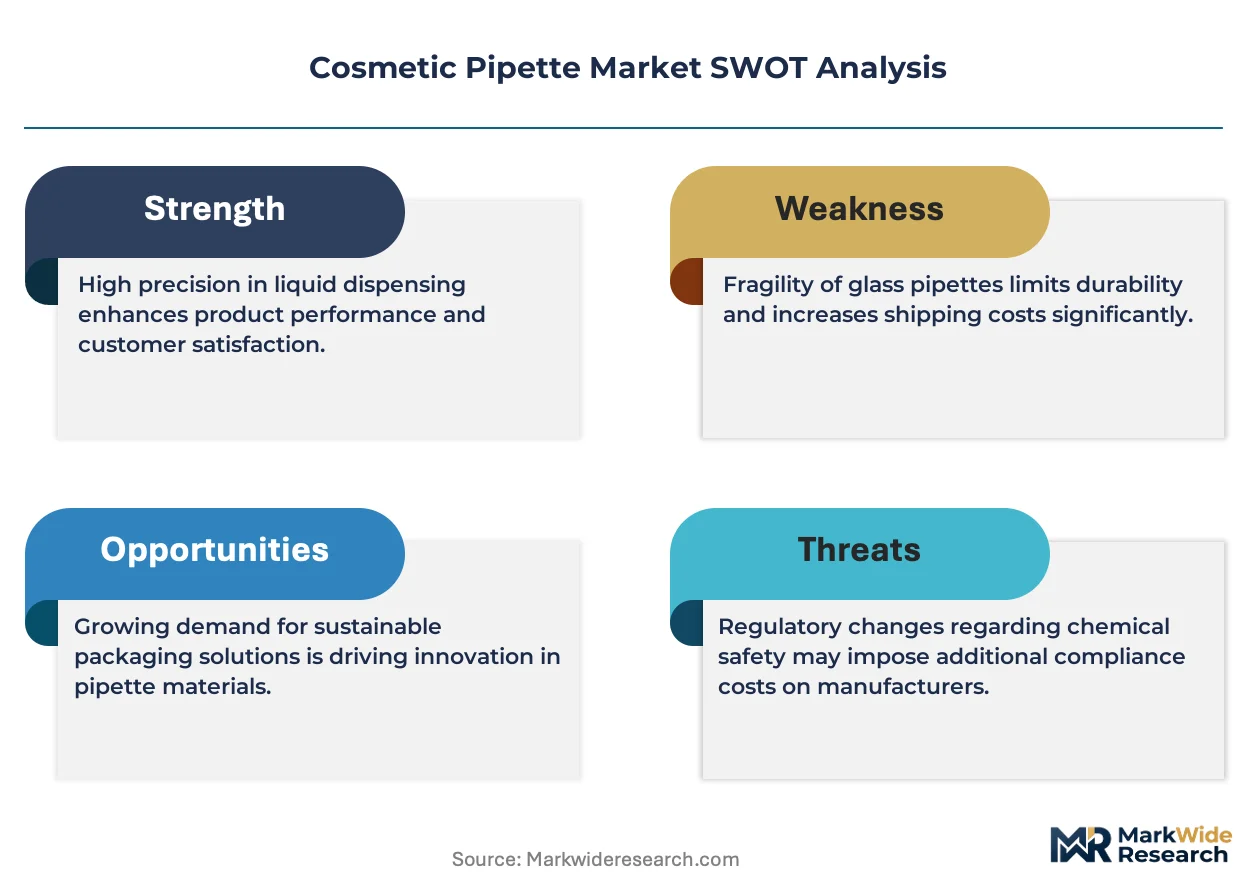
A cosmetic pipette is a slender, calibrated tube—typically borosilicate glass, soda-lime glass, or medical-grade polymers such as LDPE or PP—engineered to draw and dispense controlled volumes of liquid personal care products via capillary action or bulb suction, with tip diameters ranging from 0.5 mm to 3 mm and volumetric tolerances often within ±5%. Its primary commercial purpose is to ensure hygienic, precise dosing of high-value formulations while minimizing oxidation and contamination exposure. Glass pipettes for serum delivery command the dominant share of value given consumer perception of chemical inertness and premium aesthetics, though plastic variants represent the fastest-growing category as brands seek shatter-resistant formats for travel retail. Dropper bottles as a packaging type concentrate margin pools among cosmetic manufacturers pursuing refillable luxury positioning, while single-use vials serve spa centers with stringent cross-contamination protocols.
EU REACH restrictions on heavy metals in glass colorants and the EU Packaging and Packaging Waste Regulation shape material choices and end-of-life obligations for pipette suppliers operating in Europe. FDA cosmetic labeling requirements and USP Class VI polymer standards govern market access for plastic pipette exporters targeting dermatology clinics in the United States. Stakeholders must monitor evolving extended producer responsibility frameworks and decide between regional manufacturing footprints versus consolidated export hubs before compliance timelines tighten.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing design cycles for cosmetic pipette suppliers as refillable formats displace single-use glass across European serum brands. This structural pressure cascades through material selection, manufacturing location decisions, and end-of-life compliance obligations.
Growth Catalysts
- EU Green Deal packaging mandates:Refillable dropper formats gain preference among luxury skincare houses seeking to preempt extended producer responsibility fees. Glass pipette demand concentrates in France and Italy where artisanal blowing capacity serves premium positioning.
- Travel retail format requirements:Shatter-resistant polymer pipettes displace glass in airport duty-free channels. LDPE and medical-grade PP variants capture volume from brands requiring TSA-compliant serum packaging.
- Dermatology clinic protocols:Single-use vial systems with calibrated plastic droppers address cross-contamination standards in US and German medical aesthetics practices. USP Class VI polymer certification unlocks institutional procurement.
Market Restraints
- Borosilicate glass feedstock concentration:German and Czech glassworks control premium cosmetic-grade tubing supply. Disruptions in natural gas pricing transmit directly to pipette unit economics.
- REACH heavy metal restrictions:Cobalt and cadmium colorant bans limit aesthetic differentiation for amber and blue-tinted glass droppers. Reformulation timelines extend 18-24 months for validated alternatives.
- Pump dispenser substitution:Airless pump systems capture serum applications where oxidation sensitivity exceeds dosing precision requirements. Pipette suppliers defend position through volumetric accuracy claims.
Strategic Opportunities
- Indian domestic beauty market expansion:Local serum brands in Mumbai and Bengaluru seek calibrated glass droppers for ayurvedic oil formulations. CDSCO medical device pathway offers regulatory clarity for precision-delivery claims.
- Biodegradable polymer convergence:PHA and PLA pipette development aligns with BIS compostability standards. Material suppliers partner with blow-molding equipment makers to scale medical-grade tolerances.
- Direct-to-consumer subscription channels:Refill pipette cartridges displace full-bottle replacement in Nordic and Benelux markets. Brands optimize shipping weight and packaging waste simultaneously.
Industry Challenges
- Precision-blowing technician scarcity:Artisanal glassworks in Bohemia and Catalonia face retirement waves. Training pipelines for cosmetic-grade calibration lag automated assembly line expansion.
- Multi-jurisdiction certification timelines:Simultaneous FDA cosmetic labeling, REACH substance registration, and USP Class VI polymer testing extend product launch cycles. Smaller suppliers lack dedicated regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic Pipette Market |
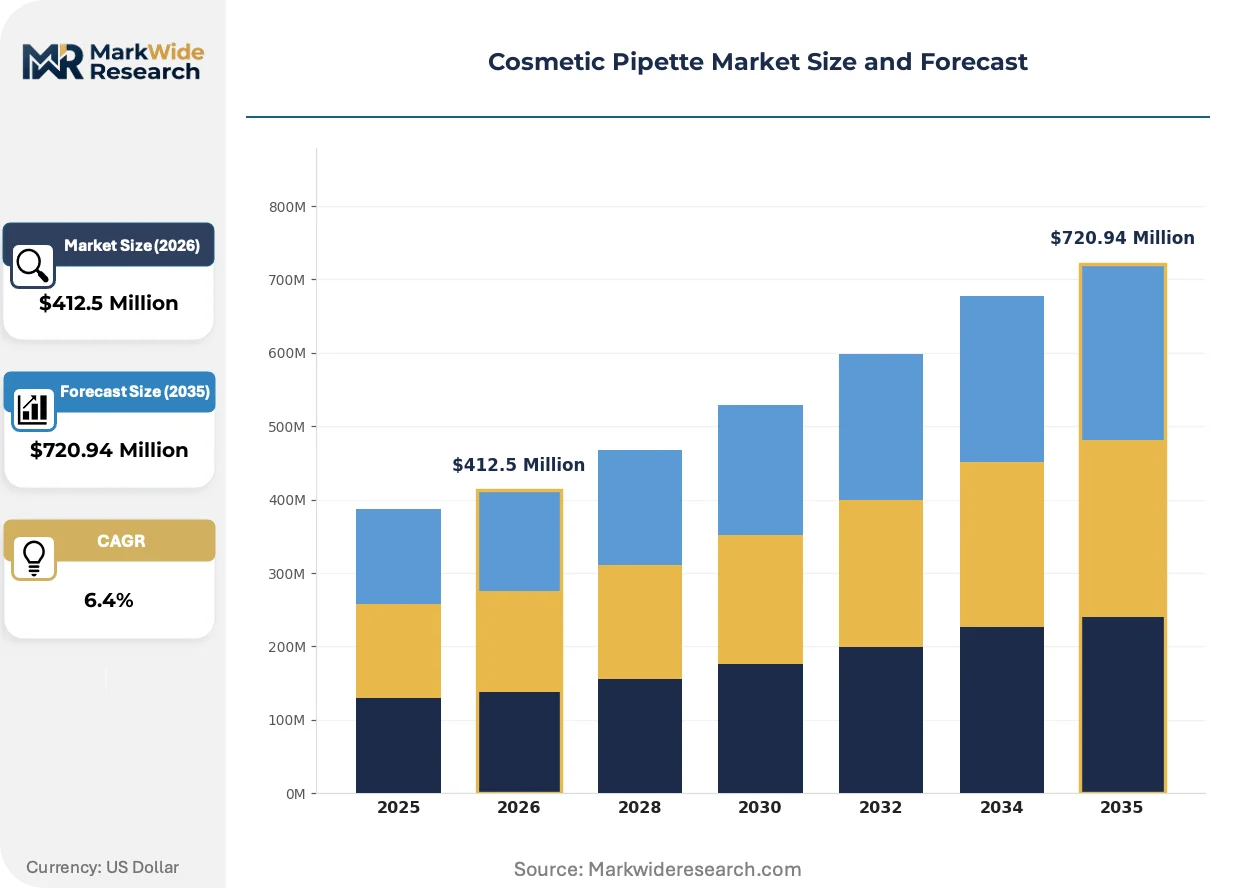
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Pipettes, Plastic Pipettes, Graduated Pipettes, Micropipettes, Automatic Pipettes Application: Serum Delivery, Lip Gloss Application, Eye Drop Dispensing, Foundation Application, Essential Oil Packaging End User: Beauty Salons, Cosmetic Manufacturers, Dermatology Clinics, Spa Centers, Cosmetic Retailers Packaging Type: Dropper Bottles, Refillable Containers, Single-use Vials, Airless Pumps, Squeeze Tubes |
| Companies Covered | Virospack, Comar, FH Packaging, RTN Applicator Company, yellopackaging, Quadpack, FusionPKG, Yonwoo, HirschmannLaborgeräte, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic Pipette Market Strategic Shifts
Active reshaping in cosmetic pipettes centers on material science convergence, regulatory anticipation, and channel-specific format fragmentation. Suppliers must now engineer for compliance timelines that precede actual mandate enforcement.
Coated borosilicate glass is unifying chemical inertness claims with breakage resistance through silicone and polymer exterior layers. Luxury serum houses in Germany and Switzerland adopt these hybrid droppers for e-commerce shipments where transit damage rates compressed customer lifetime value. The technology is unifying previously separate premium and travel-retail supply chains into single SKU platforms.
REACH Annex XVII restrictions on microplastics in rinse-off cosmetics are extending to leave-on product packaging guidance. ECHA pre-registration consultations signal future restrictions on non-recyclable polymer additives. Glass pipette suppliers in France and Italy accelerate post-consumer recycled content programs to anchor preferred vendor status ahead of delegated act finalization.
Subscription-based refill cartridge procurement is displacing traditional bottle-plus-pipette replacement cycles among direct-to-consumer skincare brands. Nordic markets lead this behavioral shift, with Swedish and Danish consumers accepting deposit-return mechanisms for glass dropper hardware. Indie beauty labels in Copenhagen and Stockholm negotiate multi-year pipette supply agreements locked to refill volume commitments rather than unit pricing.
Cosmetic Pipette Market Segmentation
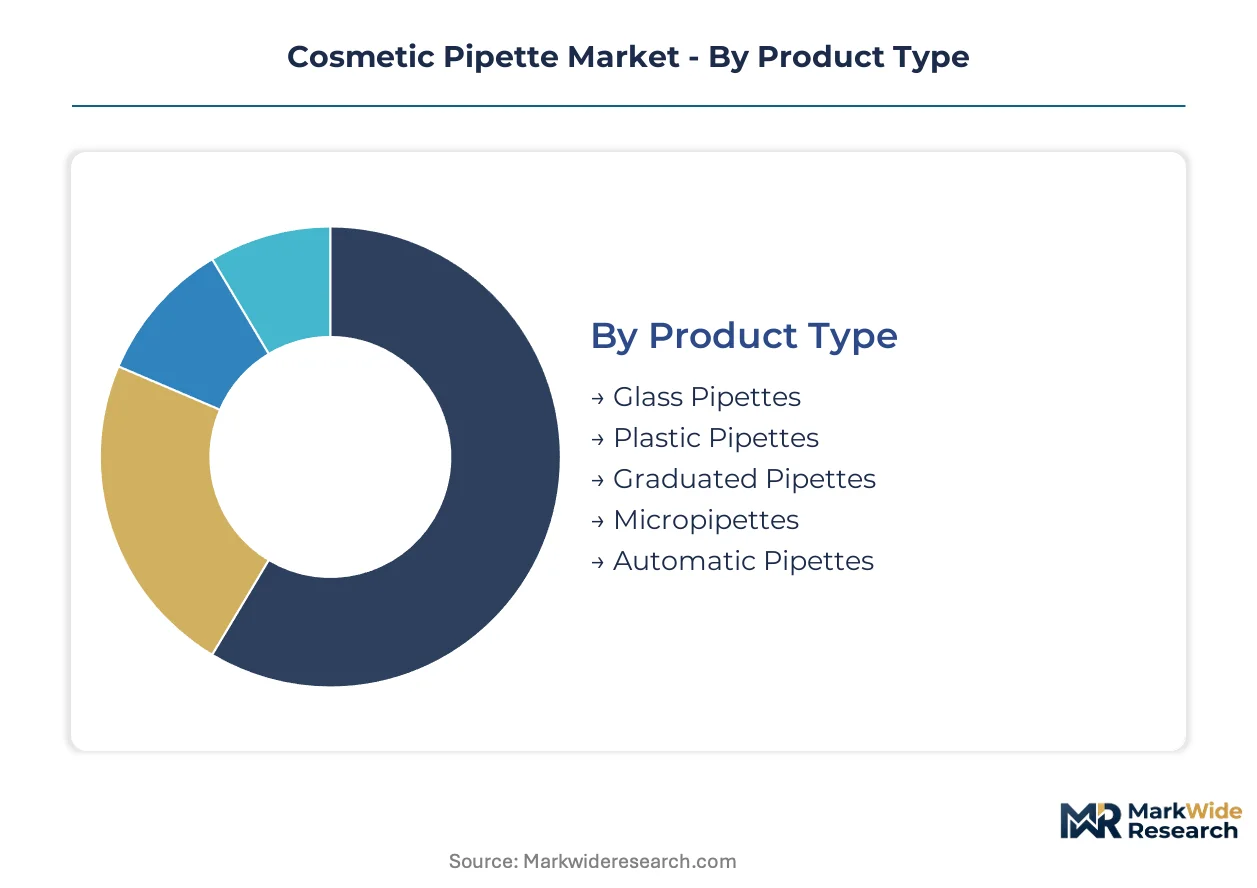
Cosmetic pipette procurement decisions diverge sharply across certification requirements, with USP Class VI polymer standards governing medical aesthetics channels while EU REACH compliance shapes glass colorant specifications for premium skincare. Manufacturers must align production lines to these divergent regulatory burdens before volume commitments materialize.
Product Type:
FDA cosmetic labeling and USP Class VI certification burdens fall heaviest on polymer variants, while EU REACH heavy metal restrictions constrain glass colorant innovation across European supply chains.
- Glass Pipettes:Borosilicate and soda-lime formulations dominate serum delivery for luxury houses in France and Italy. German glassworks supply precision-blown tubing calibrated to ±5% volumetric tolerance. REACH cobalt and cadmium bans compress 18-24 month reformulation timelines for amber and blue-tinted variants.
- Plastic Pipettes:Medical-grade LDPE and PP variants capture travel retail and dermatology clinic procurement. USP Class VI certification unlocks institutional sales in US medical aesthetics practices. Shatter resistance addresses TSA-compliant serum packaging requirements in airport duty-free channels.
- Graduated Pipettes:Calibrated volume markings serve ayurvedic oil brands in Mumbai requiring precise dosing claims.
- Micropipettes:Micro-liter precision targets peptide serum formulations from Swiss and German luxury laboratories.
- Automatic Pipettes:Spring-loaded mechanisms reduce technician variability in Korean medical spa protocols.
Leading the category by volume: Glass Pipettes. Growing fastest: Plastic Pipettes.
Application:
Cost tier stratification separates medical-grade precision requirements from mass-market convenience positioning.
- Serum Delivery:Antioxidant and peptide formulations demand chemical inertness and oxidation minimization. Glass droppers with silicone-coated exteriors unify premium positioning with e-commerce transit durability for German and Swiss subscription brands.
- Lip Gloss Application:Wand-style plastic pipettes dominate mass-market throughput. Comar's automated North American assembly lines serve volume brands with LDPE variants optimized for viscosity tolerance.
- Eye Drop Dispensing:Sterile single-use vials address ophthalmic-grade contamination protocols in German dermatology networks.
- Foundation Application:Squeeze-bulb droppers with wider bores accommodate higher-viscosity silicone formulations.
- Essential Oil Packaging:Amber glass with tamper-evident collars serves aromatherapy brands in Copenhagen and Stockholm refill programs.
Highest margin concentration: Serum Delivery. Steepest volume expansion: Lip Gloss Application.
End User:
Customer type determines batch size, certification documentation depth, and direct-versus-distributor procurement patterns.
- Cosmetic Manufacturers:Multi-year supply agreements with refill volume commitments displace unit pricing in Nordic markets. Swedish and Danish brands negotiate locked glass dropper hardware with cartridge replenishment schedules.
- Dermatology Clinics:Cross-contamination protocols in US and German medical aesthetics practices drive single-use vial procurement. USP Class VI polymer certification gates institutional purchasing.
- Beauty Salons:Mid-volume orders split between reusable glass and cost-optimized plastic depending on service tier positioning.
- Spa Centers:Hygiene-sensitive environments in Swiss alpine resorts specify individually wrapped droppers.
- Cosmetic Retailers:Private-label serum houses in Bengaluru seek CDSCO medical device pathway clarity for precision-delivery claims.
Largest procurement volume: Cosmetic Manufacturers. Fastest contract restructuring: Dermatology Clinics.
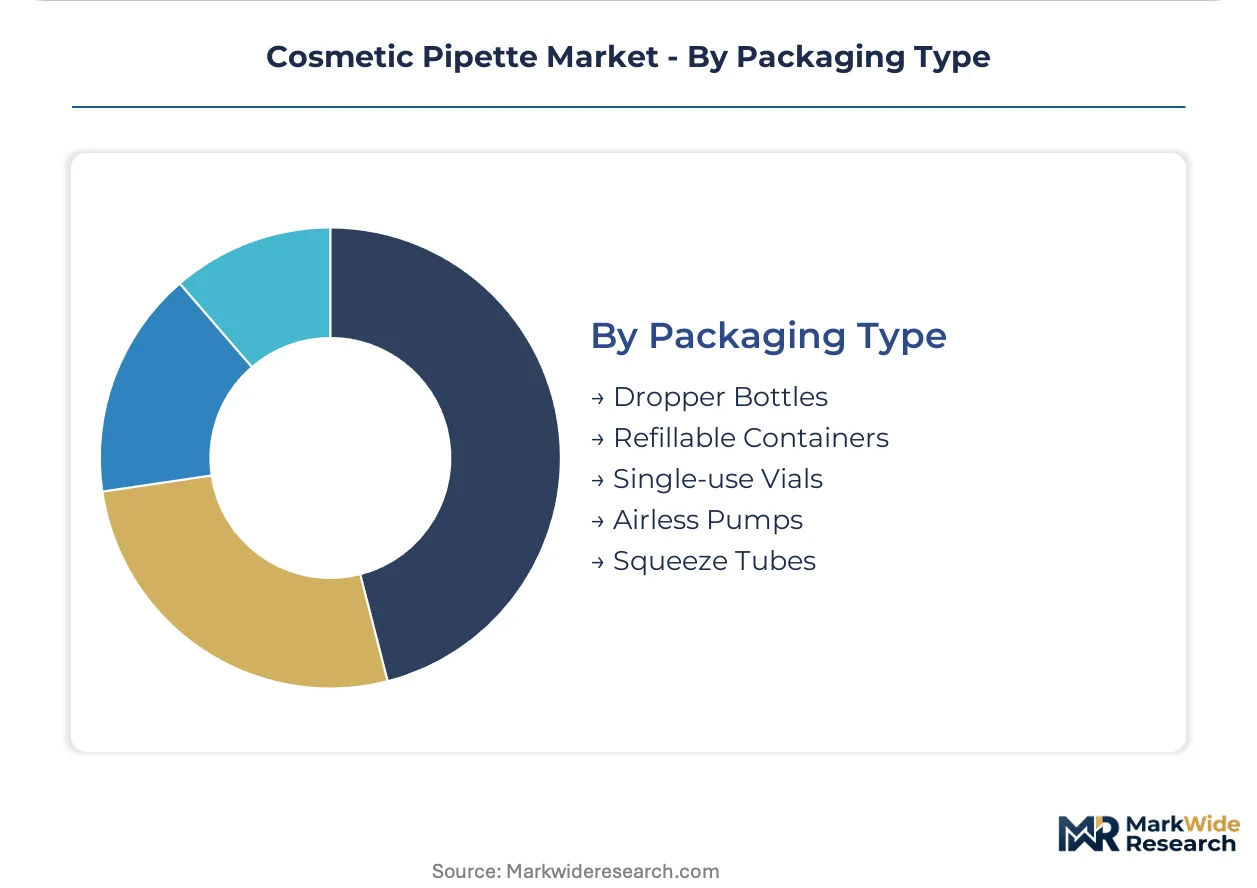
Packaging Type:
Supply concentration in artisanal glassworks versus automated polymer assembly dictates regional manufacturing footprint decisions.
- Dropper Bottles:Refillable formats concentrate margin pools among luxury houses pursuing EU Green Deal compliance. Virospack's Barcelona precision-blowing capacity serves calibrated glass demand from French serum brands.
- Single-use Vials:Sterile polymer systems address German spa center cross-contamination standards with validated supply chains from Czech blow-molding specialists.
- Refillable Containers:Deposit-return mechanisms in Swedish and Danish markets optimize shipping weight and packaging waste simultaneously.
- Airless Pumps:Oxidation-sensitive formulations substitute pump dispensers where dosing precision yields to shelf-life extension.
- Squeeze Tubes:Travel retail formats accommodate TSA volume restrictions with collapsible polymer construction.
Dominant value pool: Dropper Bottles. Gaining share fastest: Refillable Containers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Czech glassworks dominate borosilicate feedstock supply for precision-blown cosmetic droppers, anchoring European manufacturing gravity while Asian polymer specialists scale medical-grade alternatives for travel retail channels.
Germany
Luxury serum houses in Hamburg and Berlin drive calibrated glass pipette procurement for refillable formats under EU Green Deal packaging mandates. ECHA REACH restrictions on cobalt colorants force 18-24 month reformulation timelines for amber-tinted variants. Bavarian glassworks concentrate artisanal blowing capacity serving domestic premium brands.
France
Paris-based cosmetic laboratories specify borosilicate droppers for antioxidant peptide formulations requiring chemical inertness. ANSM guidance on medical device borderline classifications shapes precision-delivery claims for dermatology channels. Alsace glassworks scale silicone-coated exterior layers to unify premium aesthetics with e-commerce transit durability.
Italy
Milan and Florence anchor demand for soda-lime glass pipettes in artisanal skincare positioning. EU Packaging and Packaging Waste Regulation compliance timelines compress design cycles for refillable dropper systems. Murano glassworking traditions translate into cosmetic-grade calibration expertise for export markets.
United States
FDA cosmetic labeling requirements and USP Class VI polymer standards govern market access for plastic pipette suppliers targeting dermatology clinics in California and New York. TSA-compliant travel retail formats drive LDPE variant adoption in airport duty-free channels. Midwest automated assembly lines serve mass-market lip gloss brands with viscosity-tolerant designs.
India
Mumbai and Bengaluru serum brands seek calibrated glass droppers for ayurvedic oil formulations requiring precise dosing claims. CDSCO medical device pathway offers regulatory clarity for precision-delivery positioning. Domestic blow-molding specialists scale to capture share from European import dependency.
Cosmetic Pipette Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue biodegradable polymer convergence and subscription-format refill systems. The supplier base stratifies across artisanal glassworks with precision-blowing heritage, automated polymer assemblers serving volume brands, and design-led specialists anchoring shelf differentiation for indie labels. Three archetypes dominate: European glassworks with calibrated blowing expertise, North American automated polymer fabricators, and Asia-Pacific specialists in shatter-resistant travel formats. Competitive moves concentrate on regional manufacturing footprint expansion and multi-jurisdiction certification capacity building.
Among European precision-blowing specialists, Virospack and HirschmannLaborgeräte exemplify the artisanal glassworks archetype with established calibration protocols. Quadpack occupies a position within the design-led tier, representing specialists who anchor shelf differentiation through aesthetic innovation. Comar exemplifies the automated polymer assembler archetype, serving volume-driven procurement patterns with standardized throughput capacity.
| Leading Market Players |
|---|
| Virospack |
| Comar |
| FH Packaging |
| RTN Applicator Company |
| yellopackaging |
| Quadpack |
| FusionPKG |
| Yonwoo |
| HirschmannLaborgeräte |
| Others |
Value Chain & Pricing Dynamics
Natural gas futures at the Dutch TTF benchmark cascade directly into borosilicate glass tubing costs, compressing margin pools for precision-blown cosmetic droppers while amplifying pricing power for German and Czech glassworks with captive energy hedging.
Pricing Analysis
Warranty terms and calibration-certification bundling separate premium glass pipette suppliers from unbundled commodity polymer alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects volumetric tolerance grades and REACH-compliant colorant validation. Pricing pressure stems from pump dispenser substitution in oxidation-sensitive serum applications, with cost compression running through mid-tier borosilicate variants. Mass-market lip gloss brands exhibit highest price sensitivity, while Swiss and German luxury serum houses absorb premium positioning costs.
Supply Chain Analysis
EU Packaging and Packaging Waste Regulation local-content mandates are reshaping sourcing patterns for refillable dropper hardware. German and Czech glassworks concentrate precision-blowing capacity, while North American automated polymer assembly and Chinese LDPE blow-molding feed travel retail channels. Borosilicate tubing, medical-grade PP resin, and silicone exterior coatings constitute critical input dependencies. Single-source vulnerability concentrates in Bohemian artisanal glassworks facing technician retirement waves. Distribution runs through cosmetic manufacturer direct procurement and distributor networks serving dermatology clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Artisanal glassblowing technician scarcity props pricing for precision-calibrated droppers, constraining volume expansion for European suppliers despite refill-format demand acceleration.
For Market Incumbents: Anticipate REACH Annex XVII microplastic guidance extending to leave-on packaging by accelerating post-consumer recycled glass programs ahead of delegated act finalization. Lock multi-year refill-volume commitments with Nordic subscription brands to defend position against pump dispenser substitution. Prioritize automated calibration equipment deployment to offset precision-blowing labor constraints. For New Entrants and Emerging Players: CDSCO medical device pathway clarity in India opens a window for calibrated glass dropper penetration in Mumbai and Bengaluru ayurvedic oil markets. Target biodegradable polymer convergence under BIS compostability standards to capture sustainability-premium positioning. Pursue direct-to-consumer refill cartridge partnerships with Swedish and Danish brands seeking deposit-return mechanism suppliers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale European glassworks with validated REACH compliance and dormant precision-blowing capacity in secondary Czech or Spanish regions. Long-term viability hinges on subscription-format refill system integration and multi-jurisdiction certification infrastructure. Monitor ECHA pre-registration consultations on polymer additives as inflection signal for glass pipette demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Tubing | Captive supply of German glassworks insulates margin from TTF benchmark volatility. |
| REACH-Compliant Colorant Reformulation | Eighteen-month validation timelines lock preferred supplier status with French luxury houses. |
| Silicone-Coated Glass Scale-Up | Hybrid dropper platforms unify premium and travel-retail supply chains for Swiss e-commerce brands. |
| USP Class VI Polymer Certification | Institutional procurement gates open for US dermatology clinic single-use vial systems. |
| Refill Cartridge Subscription Partnerships | Swedish deposit-return mechanisms optimize shipping weight and packaging waste simultaneously. |
Study Parameters
Multi-period observation of borosilicate glass feedstock pricing, REACH regulatory filing timelines, and refill-format adoption rates anchored the trend analysis, supplemented by interviews with cosmetic packaging procurement directors, precision-blowing plant managers, regulatory affairs leads at glassworks, and dermatology clinic supply coordinators. Secondary validation drew from ECHA substance registration databases, EU Packaging and Packaging Waste Regulation delegated act drafts, FDA cosmetic labeling guidance documents, and customs trade flow records. Bottom-up volume builds across product type, application, end user, and packaging type segments triangulated against top-down market sizing.
Segment-weighting approaches applied differential growth assumptions across glass versus polymer material categories, serum delivery versus lip gloss application channels, and cosmetic manufacturer versus dermatology clinic end-user archetypes. CAGRs were derived from installed base replacement cycles, refill-format penetration curves, and regulatory compliance deadline clustering. Industry-specific forecast inputs included natural gas price trajectory assumptions for glassworks energy costs and TSA travel retail volume recovery patterns for shatter-resistant polymer demand.
The model assumes a particular technology adoption path for coated borosilicate glass; alternative pathways for biodegradable polymer convergence under BIS standards would alter the outlook for plastic pipette share expansion. Forecasts reflect assumptions regarding REACH implementation timelines and EU Green Deal packaging mandate enforcement. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Disposable Hospital Gowns Market
Medical Supplies
Surgical Gloves Market
Medical Supplies
Cryotubes Market
Medical Supplies
Suture Tapes Market
Medical Supplies
External Nasal Dilator and Nasal Strip Market
Medical Supplies
GCC Syringes and Needles Market
Medical Supplies
North America Insulin Syringe Market
Medical Supplies
Respiratory Masks Market
Medical Supplies
Hydrogel Dressing Market
Medical Supplies
Medical Nitrile Gloves Market
Medical Supplies
Saudi Arabia Medical Disposables Market
Medical Supplies
Global Medical Supplies Market
Medical Supplies
Mortuary Bags Market
Medical Supplies
Urine Meter Trays Market
Medical Supplies
Push-In Plug Vials Market
Medical Supplies
Arterial Blood Collection Market