
 Tularemia Market | 2026-2036
Tularemia Market Size, Share, and Industry Trends Forecast 2026-2036
Tularemia Market Outlook
Modular bundling of diagnostics with antibiotic regimens is expanding treatment protocol standardization across institutional buyers. Emergent BioSolutions leverages its biodefense manufacturing infrastructure to anchor government contract fulfillment. Pfizer Inc. competes through sustained production scale for broad-spectrum antibiotics used in post-exposure prophylaxis. Novartis AG differentiates via specialized vaccine development pipelines targeting Select Agent pathogen categories.
Tularemia is a zoonotic infection caused by Francisella tularensis, a gram-negative facultative intracellular bacterium requiring Biosafety Level 3 containment for laboratory manipulation and diagnostic confirmation through direct fluorescent antibody or PCR-based assays. Its primary purpose spans human clinical treatment, veterinary outbreak control, and biodefense preparedness against potential aerosolized weaponization. Diagnostics currently lead product type segmentation due to persistent underdiagnosis in endemic rural regions and mandatory reporting requirements. Public Health Agencies represent the fastest-growing end user channel as federal stockpiling programs expand sentinel surveillance networks. Direct Sales distribution concentrates margin pools where sole-source procurement contracts govern biodefense countermeasure acquisition.
FDA, BARDA, and CDC Select Agent regulations collectively shape market access through mandatory registration, security risk assessments, and validated assay performance standards for diagnostic platforms. The USDA Animal and Plant Health Inspection Service further constrains veterinary product commercialization through interstate movement controls on F. tularensis cultures and derived materials. Stakeholders must monitor evolving Select Agent rulemaking and biodefense budget appropriations to align R&D portfolios with federally funded procurement cycles.
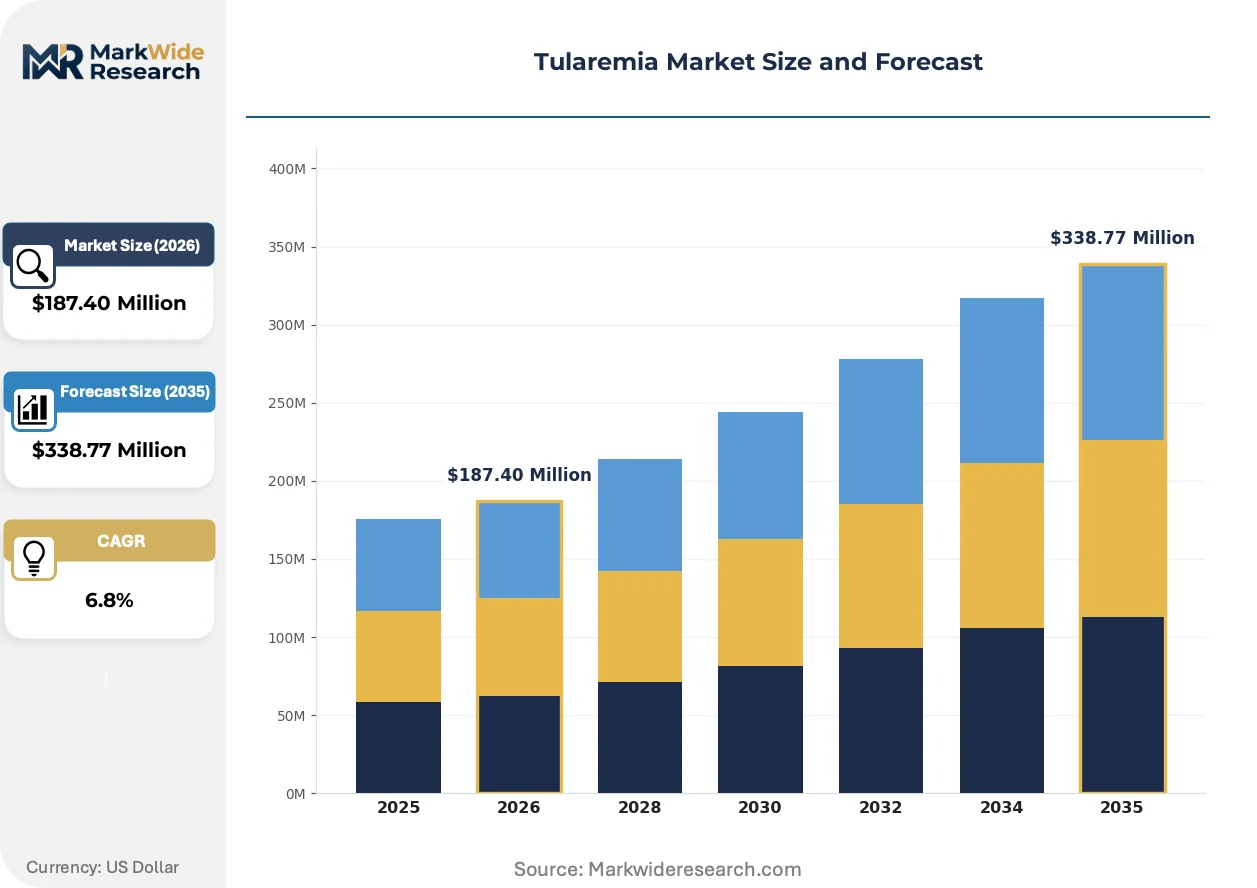
Market Dynamics
Federal biodefense procurement cycles now dominate commercialization pathways, with BARDA stockpiling mandates compressing development timelines and reshaping how diagnostics and therapeutics reach institutional buyers.
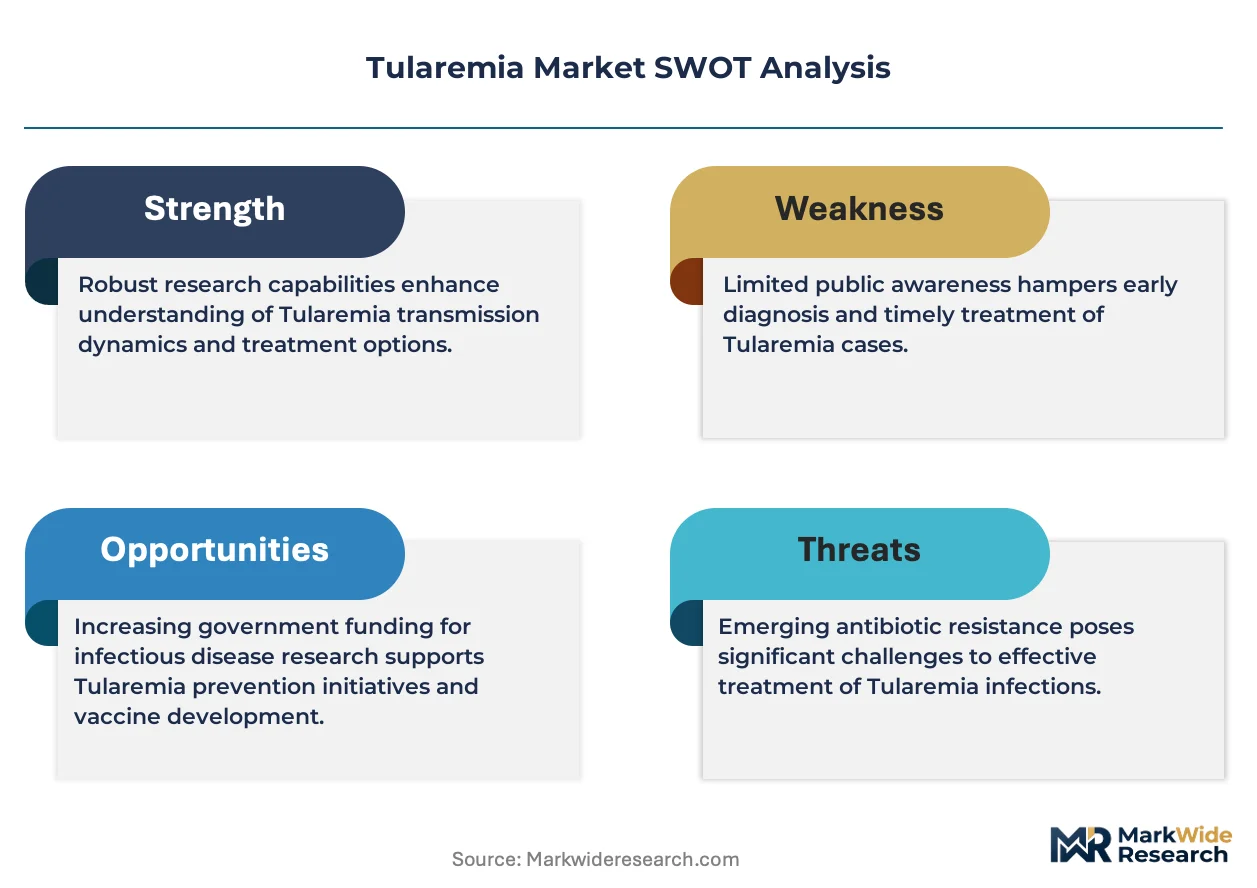
Growth Catalysts
- BARDA Stockpiling Mandates:The US Biomedical Advanced Research and Development Authority's multi-year procurement commitments provide revenue visibility for countermeasure developers, anchoring production capacity investments.
- Veterinary Surveillance Networks:USDA APHIS expansion of sentinel monitoring programs across livestock operations generates recurring diagnostic demand and outbreak response protocols.
- PCR Platform Convergence:Multiplex molecular diagnostics capable of Francisella tularensis detection alongside other Select Agents reduce per-test costs and accelerate laboratory throughput.
Market Restraints
- Biosafety Level 3 Containment:Mandatory BSL-3 infrastructure for F. tularensis culture work restricts manufacturing site expansion and elevates facility construction costs.
- Select Agent Registration Burden:CDC and APHIS security risk assessments, site inspections, and personnel suitability reviews extend product development timelines by 12-18 months.
- Limited Commercial Reimbursement:Human tularemia's rarity in non-endemic regions constrains private insurance coverage for prophylactic diagnostics outside government-funded programs.
Strategic Opportunities
- Point-of-Care Diagnostic Expansion:Lateral flow and isothermal amplification platforms for field-deployable F. tularensis detection address gaps in rural veterinary and first-responder settings.
- Livestock Export Certification:USDA interstate movement controls create demand for validated serological testing supporting commercial breeding stock transactions.
- One Health Integration:Convergence of human public health and veterinary surveillance data streams enables predictive outbreak modeling and preemptive countermeasure positioning.
Industry Challenges
- BSL-3 Technical Talent Scarcity:Specialized microbiologists and containment facility operators command premium compensation, constraining operational scaling.
- Dual-Use Research Scrutiny:Select Agent regulations and export control classifications complicate international collaborative development and knowledge transfer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tularemia Market |
| Market Size in 2026 | $187.40 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
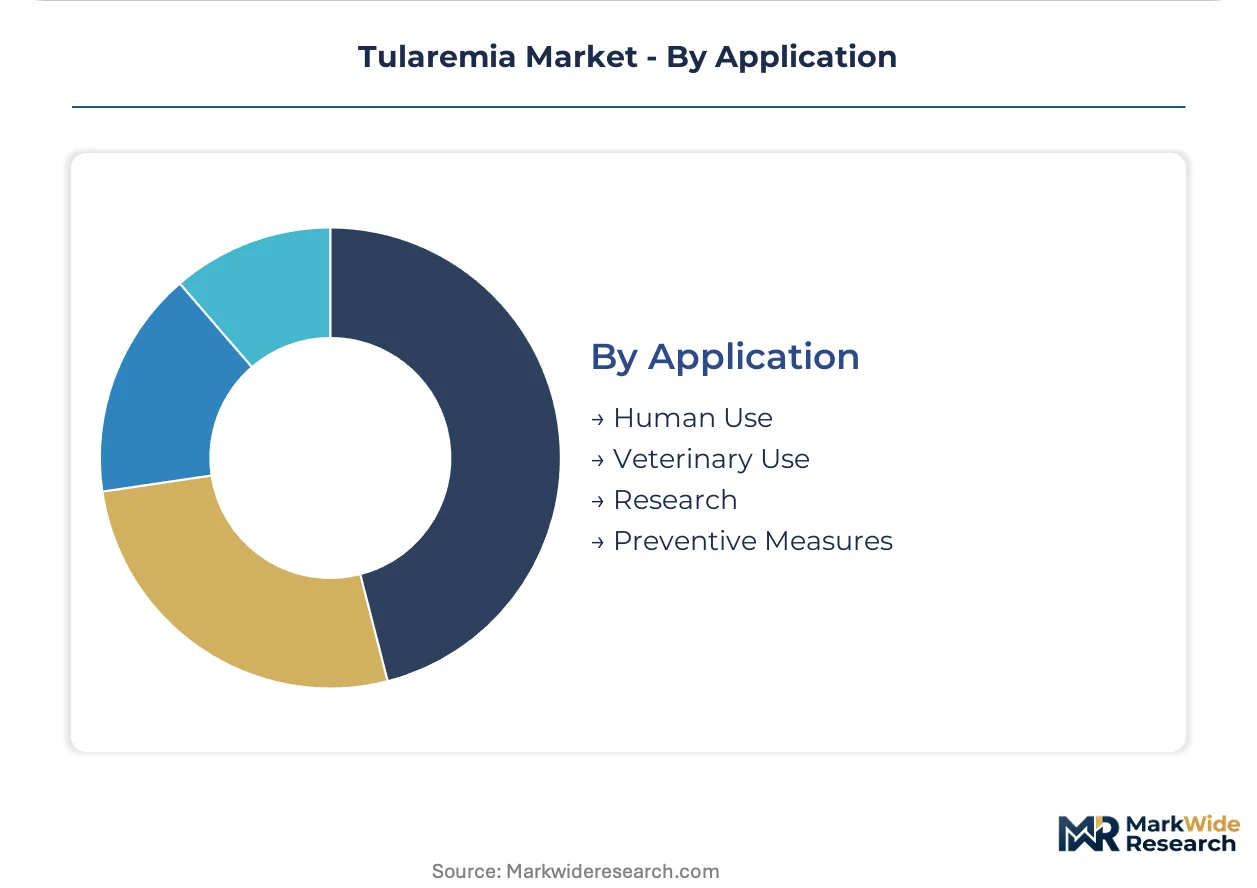
| Segmentation | Product Type: Vaccines, Antibiotics, Diagnostics, Antiseptics End User: Hospitals, Research Labs, Pharmaceuticals, Public Health Agencies Distribution Channel: Direct Sales, Online Pharmacies, Distributors, Retail Outlets Application: Human Use, Veterinary Use, Research, Preventive Measures |
| Companies Covered | Novartis AG, Johnson & Johnson, Pfizer Inc., Emergent BioSolutions, Sanofi, Merck & Co., Bayer AG, Thermo Fisher Scientific, GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tularemia Market Strategic Shifts
Diagnostic platform architecture is fragmenting into interchangeable component systems, enabling rapid assay reconfiguration across emerging pathogen threats without full instrument replacement.
Multiplex PCR panels are modularizing laboratory workflows by consolidating Francisella tularensis detection with other Category A pathogen targets onto single cartridge formats. Public health laboratories and reference hospitals in the United States are adopting these platforms under CDC Laboratory Response Network integration standards. This consolidation is compressing capital equipment footprints while expanding reimbursable test menus per installed base.
FDA's expanding biodefense readiness programs now mandate validated assay performance standards for emergency use authorization eligibility. The agency's 21st Century Cures Act implementation prioritizes rapid diagnostic deployment pathways for Select Agent threats. Diagnostic manufacturers are responding by front-loading analytical validation studies to align with federal procurement qualification requirements.
Institutional buyers are consolidating vendor relationships through sole-source indefinite-delivery contracts rather than transactional purchasing. BARDA's Centers for Innovation in Advanced Development and Manufacturing anchor multi-product agreements that displace spot-market procurement. This concentration is most visible in US federal countermeasure reserves, where long-term supply assurances override unit price optimization.
Tularemia Market Segmentation
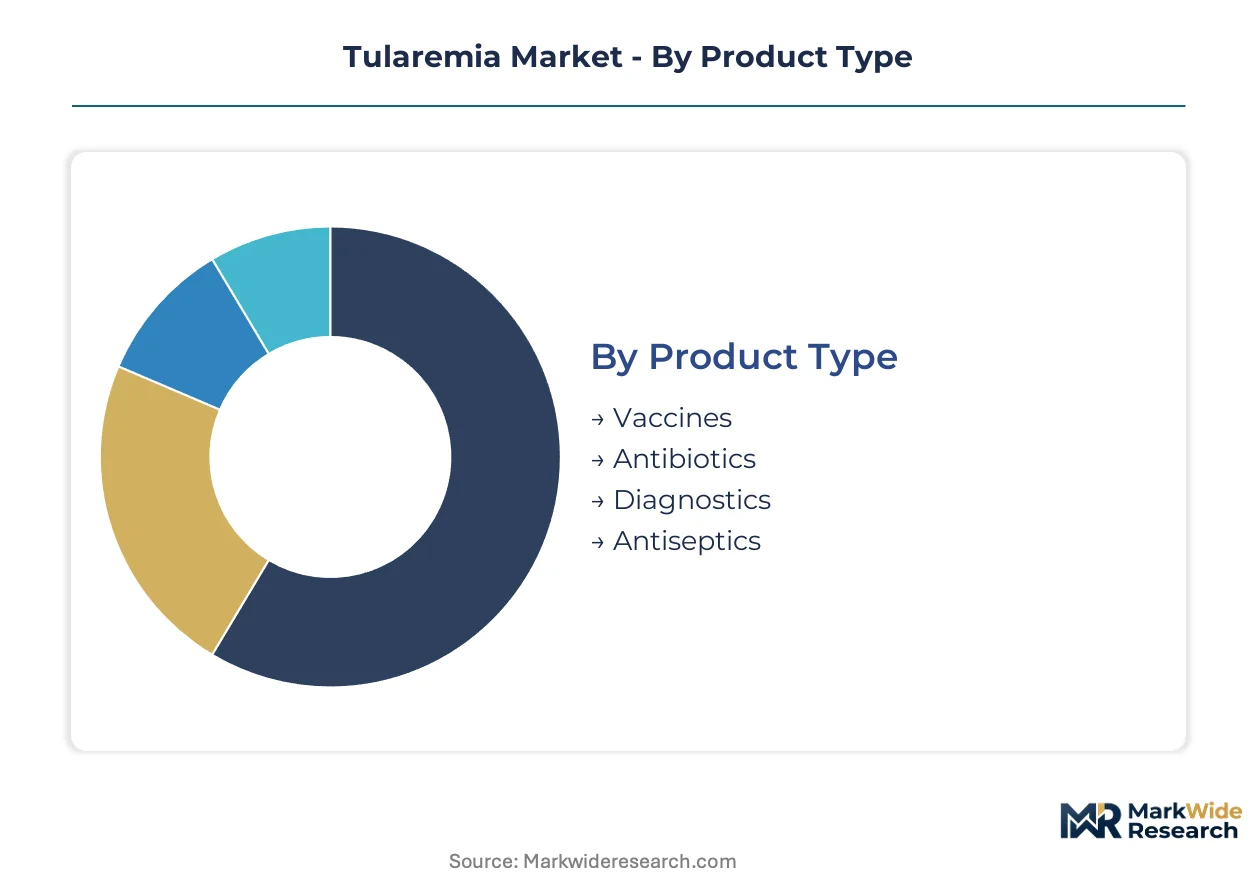
Segmentation in the tularemia market reveals how procurement authority concentrates in institutional channels rather than commercial retail. Federal biodefense programs and veterinary surveillance mandates create distinct demand profiles across product categories.
Product Type:
Diagnostics operate as embedded systems within laboratory workflows, while vaccines and antibiotics function as standalone stockpiled countermeasures.
- Diagnostics:PCR-based and direct fluorescent antibody platforms require Biosafety Level 3 containment for specimen processing. Public health laboratories in the United States anchor procurement volumes through CDC Laboratory Response Network integration and mandatory reporting requirements for Francisella tularensis detection.
- Antibiotics:Broad-spectrum agents including streptomycin and doxycycline serve post-exposure prophylaxis protocols. BARDA stockpiling mandates in the United States secure multi-year supply agreements, constraining spot-market availability for institutional buyers.
- Vaccines:Live attenuated and subunit candidates target Select Agent pathogen categories under FDA biodefense readiness programs.
- Antiseptics:Surface decontamination formulations support laboratory containment protocols and field biosecurity operations.
Diagnostics leads volumes today; vaccines is gaining share fastest through accelerated biodefense procurement timelines.
End User:
Cost tier stratification separates federally funded institutional buyers from commercially constrained healthcare providers.
- Public Health Agencies:CDC, state health departments, and federal countermeasure reserves command sole-source procurement contracts. BARDA multi-year commitments provide revenue visibility that displaces transactional purchasing patterns.
- Hospitals:Reference hospitals in endemic rural regions process confirmatory testing under CDC guidelines. Reimbursement constraints outside government-funded programs limit prophylactic diagnostic adoption.
- Research Labs:Academic and biodefense research facilities operate under Select Agent registration with mandatory security risk assessments.
- Pharmaceuticals:Contract development and manufacturing organizations anchor production capacity investments for countermeasure developers.
Public Health Agencies leads volumes today; Research Labs is expanding most quickly through USDA APHIS sentinel surveillance network scaling.
Distribution Channel:
Supply concentration favors direct relationships with federal procurement offices over intermediated retail pathways.
- Direct Sales:Indefinite-delivery contracts govern biodefense countermeasure acquisition, concentrating margin pools in vendor relationships with BARDA Centers for Innovation in Advanced Development and Manufacturing.
- Distributors:Regional laboratory supply networks serve veterinary diagnostic demand across USDA APHIS-monitored livestock operations.
- Online Pharmacies:Limited penetration due to Select Agent shipping restrictions and cold-chain requirements for biological materials.
- Retail Outlets:Minimal commercial relevance given prescription controls and institutional procurement dominance.
Direct Sales leads volumes today; Distributors is climbing the fastest through veterinary surveillance network expansion.
Application:
Customer type differentiation separates human biodefense preparedness from veterinary outbreak response protocols.
- Human Use:Clinical treatment and post-exposure prophylaxis protocols concentrate in CDC-designated reference hospitals. FDA emergency use authorization pathways prioritize rapid diagnostic deployment for Select Agent threats.
- Veterinary Use:Livestock export certification and interstate movement controls under USDA APHIS generate recurring serological testing demand. Commercial breeding stock transactions require validated diagnostic documentation.
- Research:Basic science and biodefense R&D operate under dual-use research scrutiny with export control classifications complicating international collaboration.
- Preventive Measures:Field-deployable containment and decontamination protocols support first-responder readiness training.
Human Use leads volumes today; Veterinary Use is gaining share fastest through One Health integration of surveillance data streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The tularemia countermeasure industry traces its modern procurement architecture to post-2001 US biodefense expansion, where federal stockpiling mandates first systematized multi-year manufacturing commitments for Select Agent diagnostics and therapeutics.
United States
BARDA's Centers for Innovation in Advanced Development and Manufacturing anchor demand through sole-source indefinite-delivery contracts. FDA emergency use authorization pathways compress validation timelines for Francisella tularensis detection platforms. The Frederick National Laboratory corridor in Maryland concentrates BSL-3 manufacturing infrastructure for countermeasure production.
Germany
EMA's Advanced Therapy Medicinal Products framework accommodates novel vaccine modalities for Select Agent categories. The country's central pharmaceutical regulator maintains stringent containment facility licensing that elevates operational barriers for diagnostic developers. Bavaria's Munich-Planegg biotech cluster hosts specialized microbiology contract research organizations serving European biodefense procurement.
Switzerland
Swissmedic's parallel scientific advice procedures accelerate dialogue between developers and regulators for biodefense-relevant products. The country's pharmaceutical specialization in parenteral formulations supports antibiotic stability research for stockpiled countermeasures. Basel's Novartis heritage cluster retains institutional knowledge in attenuated vaccine development for intracellular pathogens.
United Kingdom
UK Health Security Agency procurement specifications mandate PCR assay interoperability with CDC Laboratory Response Network standards. The Medicines and Healthcare products Regulatory Agency's innovation office facilitates streamlined quality reviews for emergency-relevant diagnostics. Oxfordshire's Harwell science campus accommodates BSL-3 containment expansion for veterinary and human pathogen research.
France
ANSM's early access programs for unmet medical needs channel biodefence-relevant therapeutics toward accelerated assessment pathways. The country's national pharmaceutical regulator coordinates with military health services on aerosolized pathogen countermeasure requirements. The Lyon-Grenoble infectious disease research axis maintains historical expertise in intracellular bacterial pathogenesis and containment laboratory operations.
Tularemia Market Competitive Environment
The competitive structure tilts toward federally contracted specialists rather than broad commercial pharmaceutical portfolios. Vendor relationships concentrate around BARDA-qualified manufacturing sites with validated BSL-3 capacity. Three archetypes dominate: integrated biodefense contractors with dedicated government facilities, broad-spectrum antibiotic manufacturers repurposing existing production lines, and diagnostic platform developers multiplexing Select Agent detection. Capacity expansion and sole-source procurement consolidation represent the primary competitive vectors.
Within the integrated biodefense tier, Emergent BioSolutions exemplifies the government-anchored manufacturing archetype through its dedicated countermeasure infrastructure. Pfizer Inc. occupies a position representing broad-spectrum antibiotic scale production repurposed for post-exposure prophylaxis protocols. Novartis AG sits within the specialized vaccine development segment targeting Select Agent pathogen categories with attenuated and subunit platform expertise.
| Leading Market Players |
|---|
| Novartis AG |
| Johnson & Johnson |
| Pfizer Inc. |
| Emergent BioSolutions |
| Sanofi |
| Merck & Co. |
| Bayer AG |
| Thermo Fisher Scientific |
| GlaxoSmithKline plc |
| Others |
Value Chain & Pricing Dynamics
Specialized BSL-3 microbiologists concentrated in Maryland's Frederick National Laboratory corridor command premium compensation that compresses margins at containment-dependent manufacturing sites and widens pricing spreads between federally contracted premium diagnostics and commercially distributed standard-tier alternatives.
Pricing Analysis
Sole-source indefinite-delivery contracts dominate pricing architecture for biodefense countermeasures, compressing unit price negotiation leverage while securing multi-year revenue visibility. Price differentiation hinges on FDA emergency use authorization tier and BARDA qualification status versus unvalidated commercial platforms. Cost compression in standard-tier veterinary diagnostics intensifies as USDA APHIS expands sentinel surveillance networks. Public health agencies exhibit lowest price sensitivity due to mandated stockpiling appropriations, while rural reference hospitals face reimbursement constraints that elevate cost consciousness.
Supply Chain Analysis
Domestic-content mandates embedded in BARDA Centers for Innovation in Advanced Development and Manufacturing contracts are reshaping sourcing toward US-based BSL-3 containment facilities. Supply concentrates in the United States, Germany, and Switzerland, drawing from specialized fermentation media, PCR reagent kits, and cold-chain logistics infrastructure. Single-source vulnerability pervades validated assay component supply, with FDA-mandated analytical performance standards limiting qualified vendor pools. Distribution runs through direct federal procurement channels rather than intermediated retail pathways, concentrating margin capture in government-contracted manufacturing relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tularemia countermeasure sector represents a late-cycle quality story where procurement consolidation favors BARDA-qualified manufacturers with validated BSL-3 infrastructure, as federal buyers shift demand toward premium-tier multiplex diagnostic platforms with CDC Laboratory Response Network interoperability.
For Market Incumbents: To counter diagnostic platform commoditization, anchor capacity investments in BARDA Center-qualified manufacturing sites with validated BSL-3 containment, and deepen assay multiplexing capabilities to consolidate Laboratory Response Network procurement relationships against emerging point-of-care entrants. For New Entrants and Emerging Players: Begin with lateral flow and isothermal amplification platforms for veterinary point-of-care deployment across USDA APHIS-monitored livestock operations, where regulatory barriers are lower than human biodefense procurement and interstate movement certification creates recurring diagnostic demand. For Investors and Strategic Acquirers: Integrated biodefense contractors with dedicated government facilities are the most active acquirer in this space, targeting specialized BSL-3 manufacturing capabilities over broad pharmaceutical portfolios. Watch BARDA budget appropriation cycles as the inflection signal for countermeasure procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| BSL-3 Manufacturing Scale-Up | BARDA Center qualification expands sole-source contract eligibility for Francisella tularensis countermeasures. |
| Multiplex PCR Platform Development | CDC Laboratory Response Network integration compresses per-test costs while expanding reimbursable assay menus. |
| Select Agent Registration Compliance | CDC and APHIS security risk assessment completion accelerates product development timelines by 12-18 months. |
| One Health Data Integration | Convergence of human public health and veterinary surveillance enables predictive outbreak modeling for preemptive positioning. |
| Point-of-Care Diagnostic Miniaturization | Field-deployable lateral flow platforms address gaps in rural veterinary and first-responder settings outside BSL-3 laboratory networks. |
Study Parameters
Multiple input streams — regulatory filing databases, federal procurement records, and containment facility licensing registries — were reconciled through structured primary interviews with BARDA program officers, CDC Laboratory Response Network laboratory directors, USDA APHIS veterinary diagnostic coordinators, and biodefense manufacturing executives, cross-validated against FDA emergency use authorization pathways, BARDA contract award announcements, and Select Agent registration statistics, with bottom-up product-level build and top-down federal budget appropriation triangulation.
Data-stream reconciliation anchored the analytical framework across the projection horizon, modeling segmentation by product type, end user channel, distribution mechanism, and application domain, with CAGRs derived from federal biodefense budget trajectory analysis and veterinary surveillance network expansion rates, incorporating BARDA stockpiling mandate timelines and USDA sentinel program scaling as pathogen-specific demand drivers.
Several conditions sit outside the modeled scope, including unanticipated Select Agent rulemaking revisions, international export control reclassifications, and BSL-3 containment facility operational disruptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Immortalized Cell Line Market
Medical Biotechnology
Cancer Antigens Market
Medical Biotechnology
Human Placental Protein Market
Medical Biotechnology
Antisense Therapy Market
Medical Biotechnology
Global Microalbumin Test Market
Medical Biotechnology
Hormone Sensitive Prostate Cancer Market
Medical Biotechnology
Ornithine Transcarbamylase (OTC) Deficiency Treatment Market
Medical Biotechnology
Myoglobin Market
Medical Biotechnology
North America Bacteriophages Therapy Market
Medical Biotechnology
Becker Muscular Dystrophy Market
Medical Biotechnology
Global Red Biotechnology Market
Medical Biotechnology
Mycobacterium Tuberculosis Testing Market
Medical Biotechnology
Global Preimplantation Genetic Diagnosis (PGD) Market
Medical Biotechnology
AI in Pharma and Biotech Market
Medical Biotechnology
Insulin Management System Market
Medical Biotechnology
Breast Tissue Markers Market