
 Crown Closures Market | 2026-2036
Crown Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Crown Closures Market Outlook
Lightweighting of aluminum sheet and migration to linerless sealing technologies is tilting capital allocation across the closure supply chain. Crown Holdings Inc. leverages integrated metal packaging operations across North America and Europe to sustain cost-advantaged coil supply. Tecnocap Group anchors its position through specialized R&D on tamper-evident and oxygen-scavenging closure systems for premium beverage clients. Silgan Holdings Inc. dominates the North American food jar closure segment through manufacturing scale and long-standing supply contracts with branded food manufacturers.
Crown closures are stamped metal or molded polymer devices designed to seal container openings, typically incorporating a skirted shell with internal threads, press-fit beads, or crimped edges and a liner or gasket for hermetic sealing against gas, moisture, and microbial ingress. Metal crown caps traditionally use tinplate or aluminum with PVC-free or PE-based liner compounds, while twist-off variants employ rolled-on threads compatible with glass bottle finishes for reusable sealing. The material dimension shows metal retaining volume leadership in carbonated beverages due to pressure retention and recyclability credentials, though composite closures are gaining fastest in wine and spirits where oxygen management and premium aesthetics command margin premiums. Application segmentation reveals beverages as the dominant demand pool, with pharmaceuticals representing a specialized growth corridor driven by child-resistant and senior-friendly closure mandates.
FDA regulations on food contact substances and container closure integrity govern US market access, while EU REACH and MDR frameworks impose chemical migration limits and traceability requirements across metal and polymer closure inputs. BIS certification requirements in India and China's GB standards for packaging materials add compliance layers for suppliers seeking entry into high-volume Asian manufacturing economies. Stakeholders must monitor evolving extended producer responsibility schemes and deposit-return system expansions, as these mechanisms will increasingly determine material preference and regional sourcing decisions.
Market Dynamics
Lightweight aluminum coil supply concentration and EU F-Gas Regulation compliance costs are restructuring competitive economics across metal closure manufacturing, forcing mid-scale producers to consolidate or exit as integrated suppliers capture margin.
Growth Catalysts
- Carbonated Beverage Volume Expansion:Bottlers in India and Brazil are scaling metal crown procurement as domestic soft drink and craft beer production capacity expands. Localized supply agreements reduce landed cost and customs exposure.
- REACH Chemical Migration Limits:EU ECHA enforcement on PVC-based liner compounds is accelerating substitution toward PE and composite sealing materials. Reformulation investments are creating technical barriers for non-compliant imports.
- Deposit-Return System Expansion:Germany's DRS for single-use beverage containers and similar mechanisms across Scandinavia are reinforcing aluminum recyclability premiums. Metal closures command preferential sorting economics versus polymer alternatives.
Market Restraints
- Aluminum Sheet Price Volatility:LME aluminum futures and regional smelter energy cost surges transmit directly into coil input costs. Smaller closure stampers lack hedging infrastructure to buffer margin compression.
- Tinplate Supply Concentration:European and Chinese steel mill capacity controls on electrolytic tinplate create bottleneck risk for traditional crown cap producers. Alternative substrate qualification timelines extend 18-24 months.
- Oxygen Transmission Rate Floors:Metal crown liners face fundamental permeability limits versus screw-cap composites in wine preservation. Premium vineyard clients are substituting toward co-extruded plastic closures for vintage aging applications.
Strategic Opportunities
- India Food Processing Corridor:Domestic packaging capacity investments in Maharashtra and Gujarat are drawing supplier localization. BIS certification requirements favor local manufacturing over import-dependent competitors.
- Pharmaceutical Child-Resistant Mandates:FDA 21 CFR 1700.20 compliance requirements for prescription packaging are expanding addressable demand for tamper-evident metal closures. Specialized tooling investments yield 40-60% gross margin premiums.
- Linerless Sealing Convergence:Rolled-on aluminum thread technology combined with oxygen-scavenging coatings is opening spirits and functional beverage segments. Equipment retrofit costs are declining as Chinese machinery suppliers enter the market.
Industry Challenges
- Tooling Engineer Scarcity:Precision stamping die design and multi-cavity mold flow simulation expertise concentrates among aging workforces in Germany and Japan. Knowledge transfer to Indian and Chinese operations proceeds slower than capacity expansion.
- Legacy Line Integration:Retrofitting 1980s-era glass bottle capping equipment for lightweight aluminum crowns requires mechanical synchronization and torque recalibration. Downtime costs at high-speed bottling facilities exceed $50,000 per hour.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crown Closures Market |
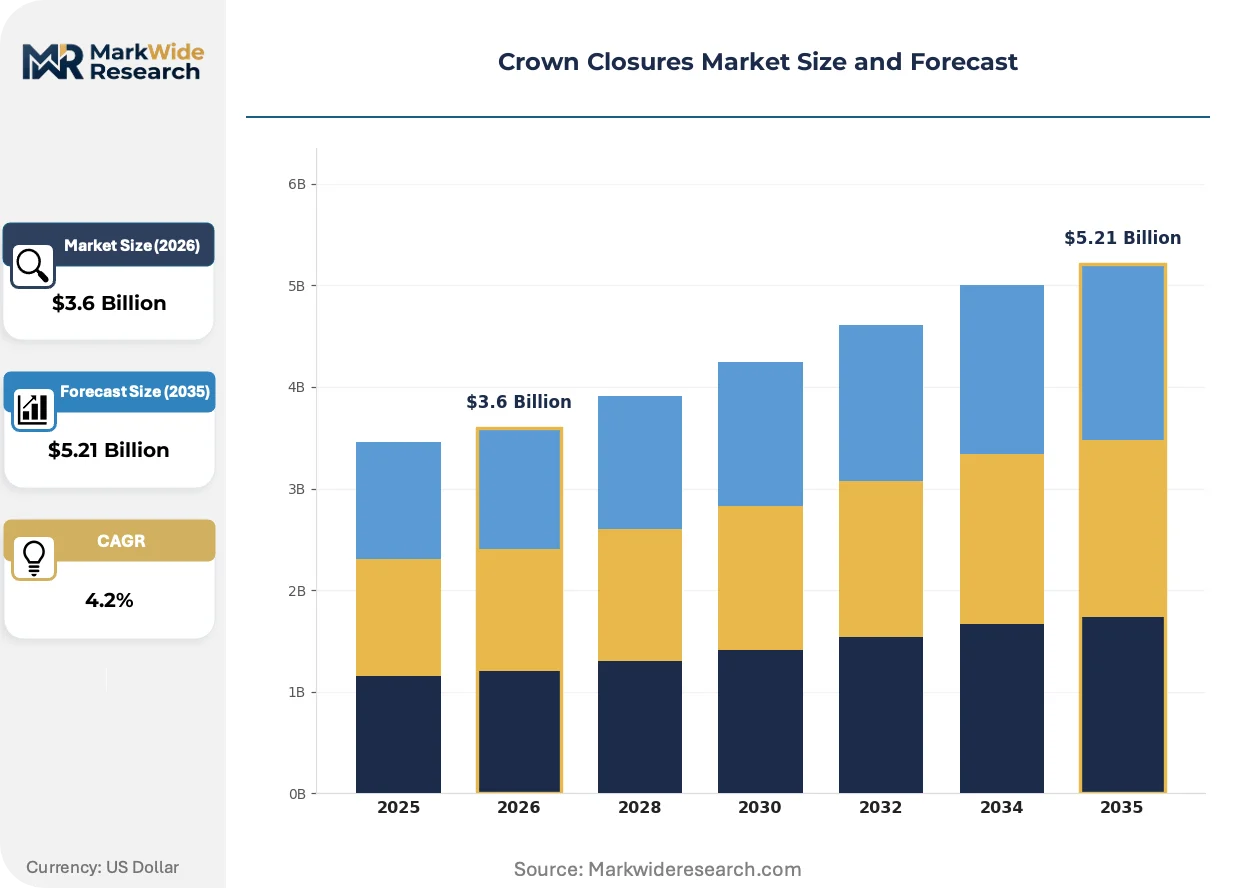
| Market Size in 2026 | $3.6 Billion |
| Market Size in 2035 | $5.21 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Closure Type: Twist-off, Pull-tab, Crown Cap, Snap-on Material: Metal, Plastic, Composite, Glass Application: Beverages, Food, Pharmaceuticals, Cosmetics End User: Manufacturers, Retailers, Distributors, Wholesalers |
| Companies Covered | Silgan Holdings Inc., Tecnocap Group, Crown Holdings Inc., Sonoco Products Company, BERICAP, Pelliconi & C. SpA, Guala Closures Group S.p.A, Ball Corporation, Nippon Closures Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crown Closures Market Strategic Shifts
Material science advances and regulatory chemistry restrictions are compressing traditional closure design cycles, with functional performance and sustainability credentials now determining specification wins ahead of unit cost.
Aluminum sheet gauges are migrating from 0.24mm toward 0.20mm specifications in standard crown applications. Beverage bottlers in Mexico and Southeast Asia are qualifying these lightweight variants to reduce aluminum mass per thousand units. The technology is migrating from carbonated soft drinks into still water and ready-to-drink tea segments where pressure retention demands are less severe.
EU F-Gas Regulation phase-down schedules for hydrofluorocarbon propellants are disrupting liner adhesive formulations. Closure manufacturers are reformulating PVC-free compounds to maintain peel torque consistency under new chemical restrictions. Wine and spirits exporters to European markets face the steepest compliance timelines as existing inventory amortization windows narrow.
Direct procurement relationships between bottlers and coil suppliers are compressing traditional distributor intermediation. Large beverage groups in the United States and Germany are negotiating aluminum tolling arrangements that bypass closure fabricator markups. This channel restructuring is most visible in North American craft brewing, where regional canneries now source decorated shells and liners separately for in-house assembly.
Crown Closures Market Segmentation
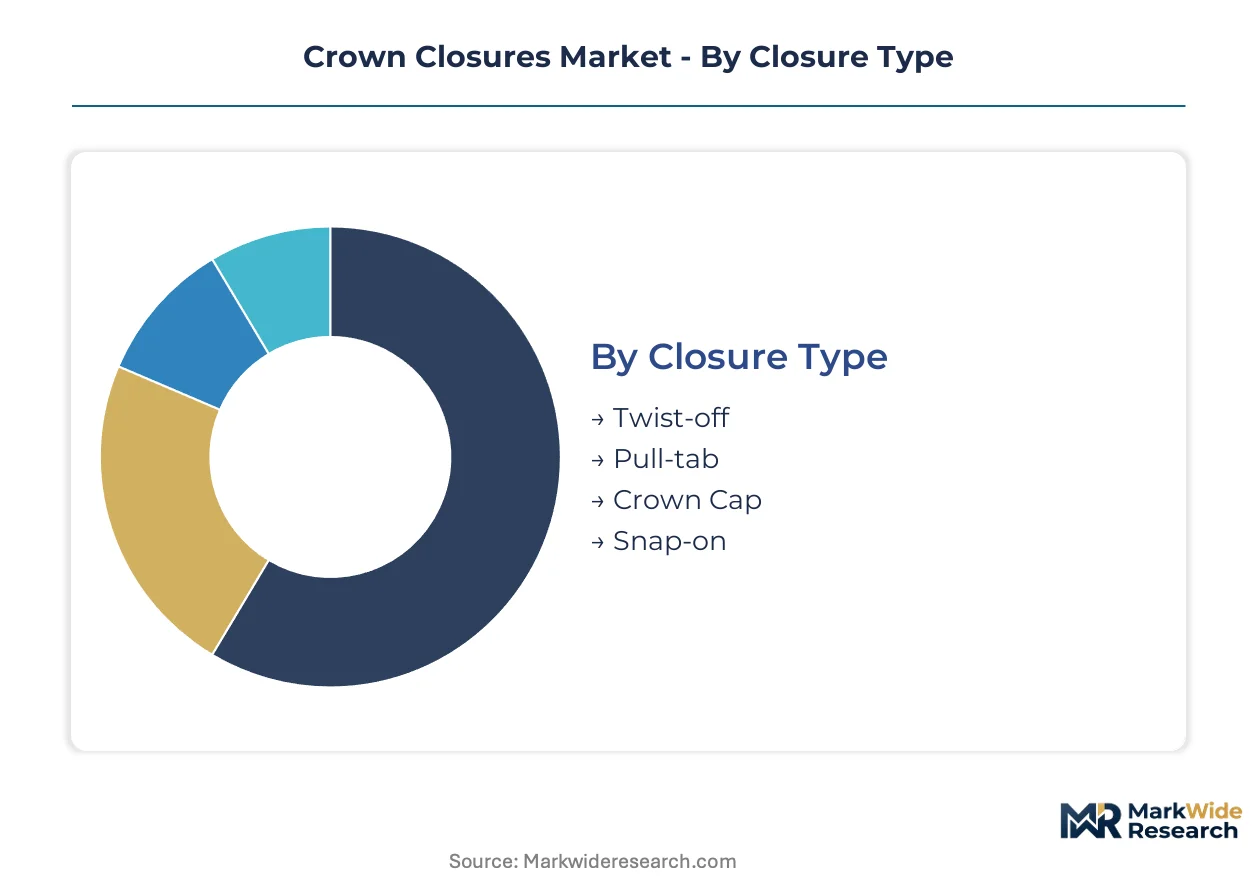
Closure specification diversity across beverage, pharmaceutical, and food packaging channels demands granular segmentation to align material performance with regulatory compliance and line-speed requirements. Technical differentiation in sealing mechanisms and substrate chemistry directly determines procurement economics and supplier qualification timelines.
Closure Type:
After-sales service intensity varies sharply across closure formats, with twist-off and crown cap variants requiring field technical support for line integration and torque calibration while pull-tab and snap-on formats minimize ongoing service engagement.
- Twist-off:Rolled aluminum threads mate with glass bottle finishes to enable resealable containment. Beverage bottlers in Germany and Mexico are standardizing these formats for craft beer and premium water segments where consumer reuse expectations are rising. Thread profile precision demands ongoing technical support for capping equipment synchronization.
- Pull-tab:Integrated aluminum ring mechanisms enable single-handed opening without separate tools. Demand concentrates in Southeast Asian ready-to-drink tea and functional beverage markets where convenience positioning commands shelf price premiums. Equipment retrofit requirements are minimal compared to threaded alternatives.
- Crown Cap:Crimped tinplate or aluminum shells with compressed liners seal carbonated beverages under internal pressure. Traditional format retains dominance in high-volume soft drink and beer bottling operations.
- Snap-on:Polymer or composite beads press-fit onto container neck finishes without rotation. Pharmaceutical and cosmetics packaging applications favor this format for child-resistant and tamper-evident compliance.
By volume, crown cap leads. By growth pace, twist-off is ahead.
Material:
Cost tier stratification separates premium composite formulations from commodity metal substrates, with mid-tier plastic hybrids capturing share in oxygen-sensitive applications.
- Metal:Aluminum coil and electrolytic tinplate deliver pressure retention and infinite recyclability. Carbonated beverage bottlers in India and Brazil are expanding aluminum crown procurement as deposit-return systems strengthen metal's circular economy credentials. ECHA enforcement on chemical migration is accelerating PVC-free liner reformulation investments.
- Composite:Co-extruded plastic and aluminum laminates combine oxygen scavenging with premium aesthetics. Wine producers in France and Italy are substituting toward these closures for vintage aging applications where permeability control justifies unit cost premiums.
- Plastic:Injection-molded polypropylene and polyethylene variants serve still water and non-carbonated segments where pressure retention is unnecessary.
- Glass:Ground glass stoppers with ground neck finishes persist in spirits and perfumery packaging where inertness and heritage positioning outweigh fragility costs.
Metal retains volume leadership. Composite formulations are climbing the fastest.
Application:
Customer type differentiation separates specification-driven pharmaceutical procurement from price-sensitive food commodity purchasing, with beverage applications occupying the intermediate value band.
- Beverages:Carbonated soft drinks, beer, wine, and ready-to-drink formats consume the majority of crown closure output. FDA 21 CFR regulations and EU F-Gas compliance timelines shape material selection across this segment.
- Pharmaceuticals:Prescription packaging mandates child-resistant and senior-friendly closure mechanisms under FDA 1700.20. Specialized tooling yields substantial margin premiums for compliant suppliers.
- Food:Jarred sauces, preserves, and condiments demand hermetic sealing against spoilage organisms. Long-standing supply contracts with branded manufacturers dominate procurement patterns.
- Cosmetics:Fragrance and skincare packaging prioritizes aesthetic differentiation and dispensing functionality over barrier performance.
Beverage applications dominate volume. Pharmaceutical specifications are gaining share fastest.
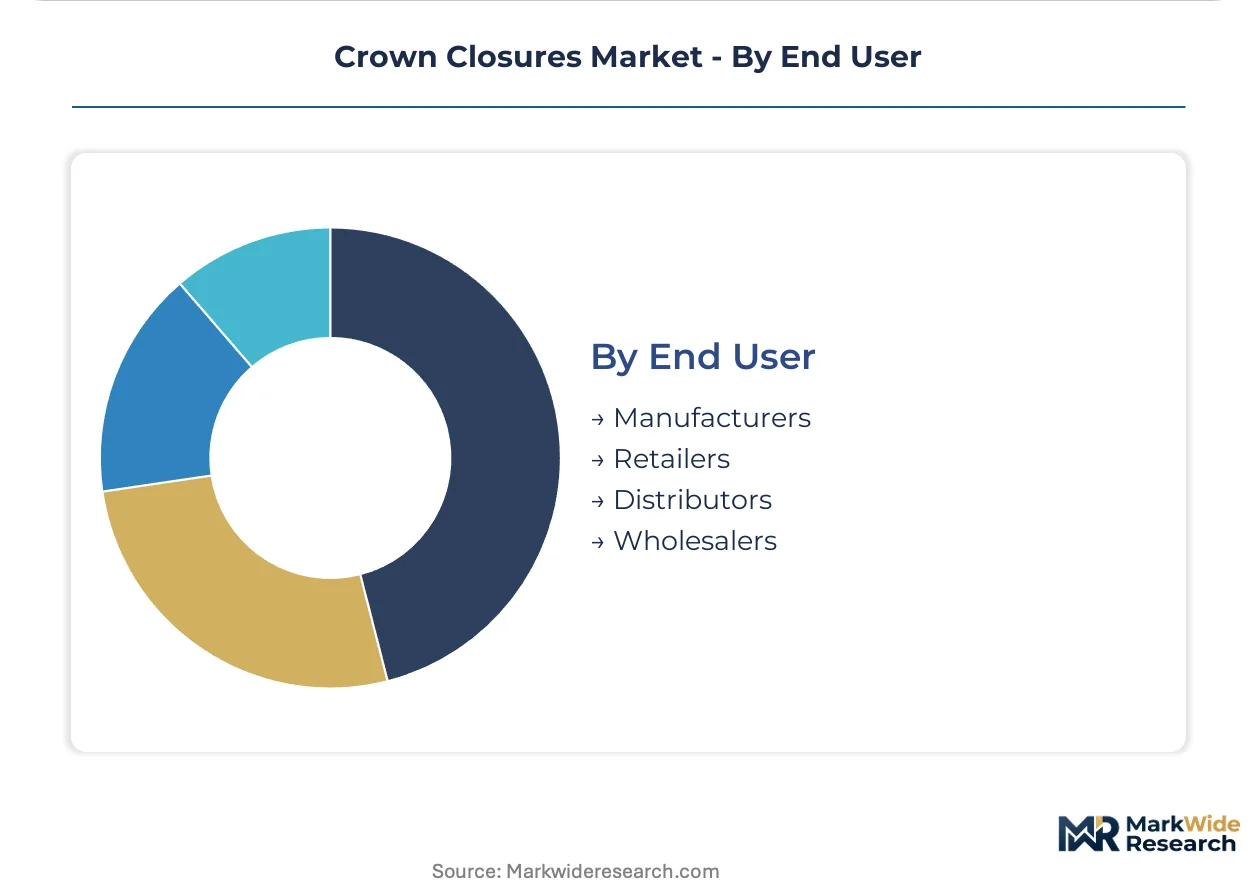
End User:
Supply concentration among integrated beverage manufacturers contrasts with fragmented distributor networks serving regional food processors.
- Manufacturers:Large beverage and pharmaceutical packaging operations source direct from closure fabricators or toll aluminum coil for in-house assembly. Direct procurement relationships are compressing traditional distributor margins.
- Distributors:Regional packaging supply intermediaries aggregate small-batch orders from craft brewers and specialty food producers. Inventory carrying costs and technical support capabilities determine competitive position.
- Retailers:Private-label packaging operations for store-brand beverages and foods specify closures through contracted co-packers rather than direct procurement.
- Wholesalers:Bulk commodity closure trading concentrates in secondary markets for surplus inventory and specification changes.
Manufacturers command volume leadership. Distributor channels are expanding most quickly in craft and specialty segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage bottlers and food processors in emerging economies are expanding metal closure procurement as domestic production capacity scales. Large integrated manufacturers in developed markets negotiate direct aluminum tolling arrangements that bypass traditional fabricator channels. Regulatory chemistry restrictions and deposit-return mechanisms are reshaping material preference geography.
United States
Craft brewers and regional canneries are qualifying lightweight aluminum crown variants to reduce unit mass. FDA 21 CFR food contact substance regulations govern liner compound reformulation timelines. Wisconsin and Colorado brewing clusters are retrofitting legacy capping equipment for 0.20mm gauge shells.
Germany
The national deposit-return system for single-use beverage containers reinforces aluminum recyclability premiums against polymer alternatives. EU F-Gas Regulation phase-down schedules disrupt liner adhesive formulations for exporters. Bavarian bottling equipment manufacturers are synchronizing torque calibration protocols for lightweight crown specifications.
India
Domestic carbonated soft drink and craft beer volumes are drawing supplier localization to Maharashtra and Gujarat food processing corridors. BIS certification requirements for packaging materials favor local manufacturing over import-dependent competitors. Mumbai-Pune industrial belt fabricators are expanding stamping capacity to serve regional beverage brands.
Brazil
Metal crown procurement is scaling alongside expanded soft drink and beer production capacity. ANVISA pharmaceutical packaging regulations create compliance pathways for child-resistant closure exports. São Paulo state bottling clusters are negotiating localized supply agreements to reduce customs exposure and landed cost.
China
GB standards for packaging materials and dual carbon policy goals are accelerating aluminum lightweighting investments. MIIT industrial guidance on circular economy mechanisms favors metal recyclability credentials. Yangtze River Delta closure fabricators are qualifying linerless sealing technologies for spirits and functional beverage segments.
Crown Closures Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered supply positions. Integrated metal packaging groups leverage captive aluminum coil supply to compress fabricator margins, while mid-scale stampers face consolidation pressure from lightweighting capital requirements and compliance cost burdens. Three archetypes dominate: integrated beverage packaging conglomerates, specialized closure R&D houses, and regional tolling intermediaries. Competitive moves concentrate on backward integration into coil supply and geographic expansion through localized stamping joint ventures.
Among North American integrated packaging groups, Crown Holdings Inc. and Silgan Holdings Inc. occupy positions that exemplify channel-control archetypes through metal packaging operation integration. Tecnocap Group represents the specialist tier, anchoring competitive positioning through dedicated closure system development. These three entities collectively illustrate the structural divergence between scale-driven tolling arrangements and technical differentiation strategies.
| Leading Market Players |
|---|
| Silgan Holdings Inc. |
| Tecnocap Group |
| Crown Holdings Inc. |
| Sonoco Products Company |
| BERICAP |
| Pelliconi & C. SpA |
| Guala Closures Group S.p.A |
| Ball Corporation |
| Nippon Closures Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta aluminum coil concentration transmits directly into closure fabricator pricing power, with regional smelter energy cost fluctuations cascading through to bottler procurement negotiations across Asia-Pacific markets.
Pricing Analysis
Cost-plus contracts indexed to LME aluminum futures dominate procurement between beverage bottlers and closure stampers, with premium-mid-economy pricing differentiation separating pharmaceutical-grade child-resistant specifications from commodity crown caps. Pricing pressure stems from lightweighting investments as 0.20mm gauge qualification costs compress margins at mid-scale fabricators. Small-batch craft brewers exhibit highest price sensitivity, while pharmaceutical packaging operations absorb unit cost premiums for FDA 1700.20 compliance.
Supply Chain Analysis
Upstream electrolytic tinplate and aluminum coil feedstock draws from China, India, and Germany, with closure liner compounds resting on PVC-free PE resin and oxygen-scavenging coating chemistry. Single-source vulnerability concentrates in European steel mill tinplate capacity controlled by legacy producers. Distribution runs through direct tolling arrangements between large beverage groups and coil suppliers, compressing traditional fabricator intermediary margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision stamping die design expertise concentrates among aging workforces in Germany and Japan, creating a structural capability gap that outpaces knowledge transfer to Indian and Chinese expansion sites.
For Market Incumbents: Build captive aluminum coil supply moats through backward integration into Yangtze River Delta or Maharashtra smelter partnerships, insulating against LME volatility while capturing margin from direct tolling arrangements. Consolidate tooling engineering talent through acquisition of specialized German or Japanese die design houses before demographic attrition accelerates. For New Entrants and Emerging Players: Pursue pharmaceutical child-resistant closure white space in Brazil and India, where ANVISA and BIS compliance timelines create technical barriers for import-dependent competitors. Target craft brewing clusters in Colorado and Wisconsin with lightweight 0.20mm gauge crown variants plus field technical support for legacy line retrofit. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because mid-scale stampers face exit pressure from lightweighting capital requirements and EU F-Gas compliance burdens. Acquire regional tolling intermediaries with BIS or FDA certification assets. Watch deposit-return system expansion across European markets as the signal for aluminum recyclability premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coil Supply | Crown Holdings and Silgan leverage captive aluminum operations to compress competitor margins across North American beverage bottling contracts. |
| Linerless Sealing Technology Deployment | Tecnocap's oxygen-scavenging coating investments open spirits and functional beverage segments previously closed to metal crown formats. |
| Pharmaceutical Certification Investment | FDA 1700.20 compliance tooling yields 40-60% gross margin premiums for child-resistant closure specialists serving prescription packaging. |
| Localized Stamping Joint Ventures | Maharashtra and Gujarat fabricators expand capacity to serve domestic Indian beverage brands under BIS certification requirements. |
| Lightweight Gauge Qualification | Mexico and Southeast Asia bottlers adopt 0.20mm aluminum specifications to reduce mass per thousand units in carbonated soft drink applications. |
Study Parameters
The analysis maps closure type, material substrate, and application segments, each validated through beverage procurement directors, pharmaceutical packaging engineers, and coil supply managers. Primary interviews with German tooling die designers and Indian stamping plant operators combined with secondary validation against EU ECHA chemical migration databases, LME aluminum futures data, and FDA 21 CFR guidance documents. Bottom-up volume modeling and top-down value triangulation cross-checked against customs records and beverage industry production disclosures.
Assumptions held fixed include EU F-Gas Regulation phase-down schedules and deposit-return system coverage expansion, while aluminum coil gauge migration and pharmaceutical mandate adoption were varied across sensitivity scenarios. Segmentation dimensions modeled span closure mechanism, substrate chemistry, end-use application, and regional regulatory cluster. CAGRs derived from historical volume elasticities applied to projected beverage bottling capacity expansion and food processing corridor investments.
Macroeconomic conditions sit as an overlay; deviation in aluminum energy input costs or emerging market currency volatility would shift the trajectory. Forecasts reflect these assumptions with acknowledged sensitivity to tinplate supply concentration and liner adhesive reformulation timelines. Cross-checking against beverage bottler capital expenditure disclosures and regional packaging machinery order data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Child Resistant Dropper Caps Market
Caps and Closures
Molded Fiber Pulp Cap Market
Caps and Closures
Plunger Stopper Market
Caps and Closures
United Arab Emirates Plastic Caps and Closures Market
Caps and Closures
Bag Closures Market
Caps and Closures
Elastomeric Closures Market
Caps and Closures
North America Plastic Caps and Closures Market
Caps and Closures
APAC Plastic Caps and Closures Market
Caps and Closures
Heat Induction Cap Liner Market
Caps and Closures
Plastic Tamper Evident Closures Market
Caps and Closures
Crimp-On Spouts Market
Caps and Closures
PVC-Free Cap Liners Market
Caps and Closures
Hinged Dual Flap Caps Market
Caps and Closures
Snap Cap Vials Market
Caps and Closures
Sport Caps and Closures Market
Caps and Closures
IBC Caps Market