
 Croscarmellose Sodium Market | 2026-2036
Croscarmellose Sodium Market Size, Share, and Industry Trends Forecast 2026-2036
Croscarmellose Sodium Market Outlook
Continuous manufacturing is rewriting how croscarmellose sodium integrates into pharmaceutical production lines, replacing batch processes with real-time powder feeding and direct compression workflows. DFE Pharma leverages its European manufacturing footprint to supply multinational drug makers with excipient grades tailored for continuous lines. JRS Pharma anchors its position through backward integration into cellulose sourcing, securing consistent raw material quality across production cycles. Roquette Frères differentiates via plant-based excipient portfolios that compete directly with synthetic alternatives in clean-label formulations.
Croscarmellose sodium is a cross-linked sodium carboxymethyl cellulose that functions as a superdisintegrant, typically added at 0.5–5.0% w/w concentration to promote rapid tablet breakup upon contact with aqueous media. Its cross-linked polymeric structure prevents gel formation while enabling rapid water uptake through capillary action, making it indispensable for immediate-release oral solid dosage forms. The tablet segment dominates volume consumption due to the enduring prevalence of oral solids in global drug pipelines, while nutraceutical applications represent the fastest-growing demand pool as supplement brands adopt pharmaceutical-grade disintegration standards. Pharmaceutical manufacturers occupy the deepest margin pools because they specify pharmacopeial-grade material and negotiate multi-year supply agreements.
The US FDA enforces excipient quality standards through IPEC-PQG GMP guidelines, while the European Pharmacopoeia and USP-NF monographs define purity and performance benchmarks that determine market access. India's CDSCO aligns with these frameworks through harmonized BIS standards for imported excipients, creating a multi-jurisdictional compliance burden for suppliers. Stakeholders must monitor evolving pharmacopeial standards for cross-linked cellulose derivatives and assess whether regional manufacturing investments reduce tariff exposure on imported excipient grades.
Market Dynamics
Continuous manufacturing adoption is collapsing traditional batch-based excipient procurement patterns, forcing suppliers to reconfigure powder specifications for real-time feeding systems and inline quality monitoring.
Growth Catalysts
- Generics proliferation in India:Contract manufacturers serving US and EU markets consume rising volumes of superdisintegrants as abbreviated new drug application filings accelerate.
- IPEC-PQG GMP harmonization:Aligned quality standards across FDA and EMA jurisdictions reduce supplier audit burdens and accelerate qualification timelines for multinational excipient vendors.
- Nutraceutical grade migration:Supplement brands adopt pharmacopeial-grade disintegration standards, expanding addressable demand beyond regulated pharmaceuticals.
Market Restraints
- Cellulose feedstock volatility:Wood pulp and cotton linter prices fluctuate with forestry harvest cycles and textile industry competition for raw fiber.
- Indian supply concentration:A disproportionate share of generic tablet production concentrates in Mumbai-Pune and Hyderabad clusters, creating geographic demand risk.
- Cross-linked polymer alternatives:Crospovidone and sodium starch glycolate compete for formulation slots in cost-sensitive generic portfolios.
Strategic Opportunities
- Brazilian ANVISA alignment:Emerging local production of pharmacopeial-grade excipients to serve Latin American generics markets currently dependent on imports.
- Continuous line retrofitting:Equipment suppliers and excipient vendors co-develop powder grades optimized for direct compression without pre-blending steps.
- Clean-label positioning:Plant-derived croscarmellose sodium captures share from synthetic superdisintegrants in consumer-facing supplement applications.
Industry Challenges
- Multi-jurisdictional pharmacopeial compliance:Suppliers must maintain concurrent USP-NF, EP, and JP certification, extending release timelines and documentation overhead.
- Continuous manufacturing integration:Legacy batch-qualified excipient grades require reformulation and revalidation for powder flow properties in real-time production environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Croscarmellose Sodium Market |
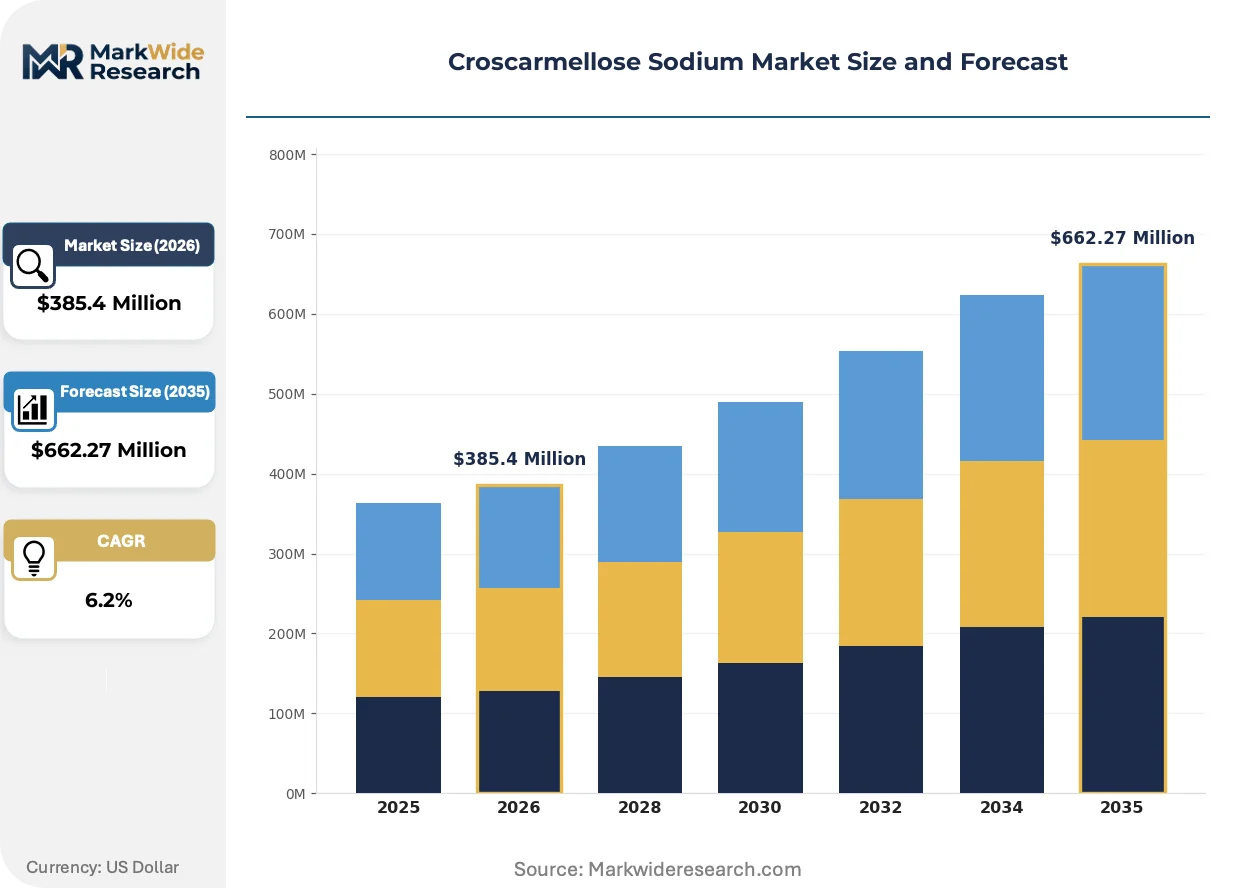
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Powders, Granules Application: Pharmaceuticals, Nutraceuticals, Food Additives, Personal Care End User: Pharmacies, Hospitals, Research Laboratories, Manufacturers Distribution Channel: Online, Distributors, Retail, Wholesalers |
| Companies Covered | Asahi Kasei, Blanver, DFE Pharma, Anhui Sunhere Pharmaceutical Excipients, ALPHA, JRS Pharma, NB Entrepreneurs, Roquette Frères, Mingtai Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Croscarmellose Sodium Market Strategic Shifts
Process analytical technology and real-time release testing are compressing the traditional excipient qualification cycle, while regulatory convergence and buyer consolidation reshape competitive requirements.
Inline near-infrared spectroscopy is collapsing the boundary between excipient production and tablet manufacturing, enabling real-time moisture and particle size verification during continuous compression. Pharmaceutical operators in Germany and Switzerland are deploying these systems for immediate-release oral solids. The technology is compressing batch release timelines from days to hours.
EMA's revised excipient risk assessment guidelines now mandate documented supply chain transparency for cross-linked cellulose derivatives entering European markets. Manufacturers must identify and qualify alternate sources for critical raw materials. Indian exporters to the EU are restructuring supplier agreements to satisfy enhanced documentation requirements.
Buyer concentration among the top ten generic pharmaceutical companies is consolidating procurement decisions into centralized excipient qualification committees. Regional formulation scientists lose autonomy over superdisintegrant selection. This pattern is most visible in North American and Western European headquarters of multinational generics firms.
Croscarmellose Sodium Market Segmentation
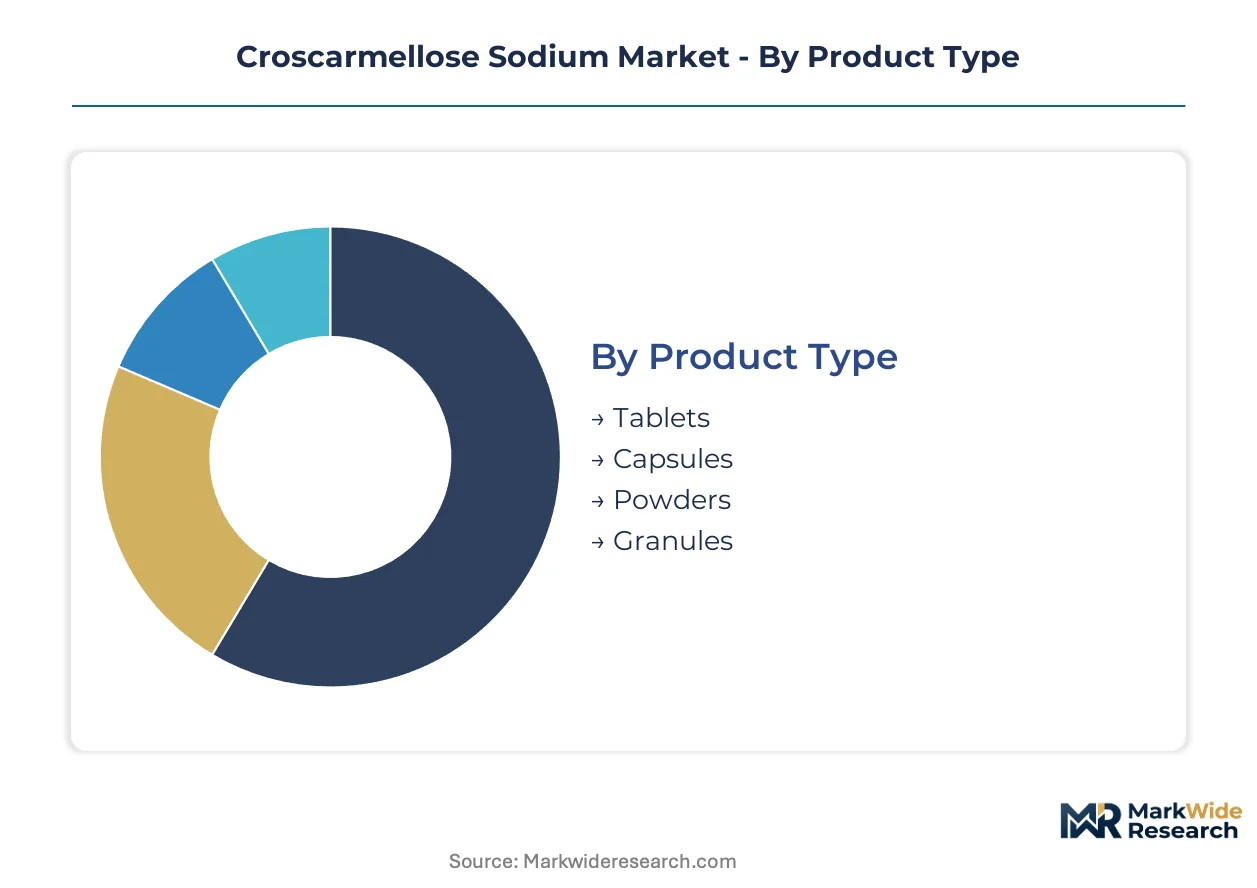
Croscarmellose sodium procurement patterns diverge sharply across dosage forms and customer types, with pharmaceutical-grade specifications commanding premium positioning against nutraceutical and industrial alternatives. Understanding these segment boundaries clarifies where formulation flexibility ends and regulatory compliance begins.
Product Type:
Mature tablet applications coexist with emerging powder formats as continuous manufacturing rewrites material handling requirements.
- Tablets:Immediate-release oral solid dosage forms consume croscarmellose sodium at 0.5–5.0% w/w concentration to achieve rapid disintegration without gel layer formation. Mumbai-Pune and Hyderabad manufacturing clusters in India absorb the dominant share as contract generic producers scale output for US FDA and EMA submissions.
- Capsules:Hard gelatin and HPMC capsule formulations employ lower superdisintegrant loadings than tablets, with croscarmellose sodium functioning primarily as a dissolution aid rather than structural breaker. European nutraceutical brands in Germany and Switzerland are migrating toward pharmacopeial-grade capsule disintegration standards, expanding specification requirements.
- Powders:Direct-to-consumer sachet formulations and dry powder inhaler precursors represent emerging demand channels with specialized particle size distribution requirements.
- Granules:Intermediate processing formats for high-shear wet granulation lines require modified flow properties and moisture tolerance profiles.
Tablets handle the majority of throughput; powders are climbing the fastest on share as continuous line retrofits accelerate.
Application:
Cost tier stratification separates regulated pharmaceutical specifications from food-grade and cosmetic alternatives with divergent certification burdens.
- Pharmaceuticals:USP-NF and EP monograph compliance mandates residual solvent limits, heavy metal specifications, and documented supply chain transparency for cross-linked cellulose derivatives. Manufacturers negotiate multi-year supply agreements with excipient vendors qualified across IPEC-PQG GMP frameworks.
- Nutraceuticals:Supplement brands in North America and Western Europe are adopting pharmaceutical-grade disintegration standards, eroding the traditional quality gap between regulated drugs and dietary supplements. Clean-label positioning favors plant-derived croscarmellose sodium over synthetic superdisintegrant alternatives.
- Food Additives:Bakery and convenience food applications employ technical-grade material with reduced documentation overhead and modified particle morphology for moisture stability.
- Personal Care:Topical and oral care formulations utilize croscarmellose sodium as a rheology modifier and disintegration aid in effervescent tablet formats.
Pharmaceuticals dominate value capture; nutraceuticals are gaining share fastest as quality convergence reshapes buyer expectations.
End User:
Customer type determines procurement autonomy, with centralized excipient qualification committees at multinational manufacturers overriding regional formulation preferences.
- Pharmacies:Compounding operations and hospital outpatient dispensaries purchase small-batch excipient quantities with flexible delivery schedules.
- Hospitals:In-house manufacturing of unit-dose oral solids for clinical trials and personalized medicine drives demand for documented batch-to-batch consistency.
- Research Laboratories:Preclinical and early-phase development work consumes analytical-grade material with extensive characterization data packages for regulatory submission support.
- Manufacturers:Generic pharmaceutical companies and contract development manufacturing organizations anchor volume demand, with top ten global generics firms consolidating procurement decisions into centralized committees.
Manufacturers absorb the dominant volume; research laboratories are expanding most quickly as early-phase pipeline activity intensifies.
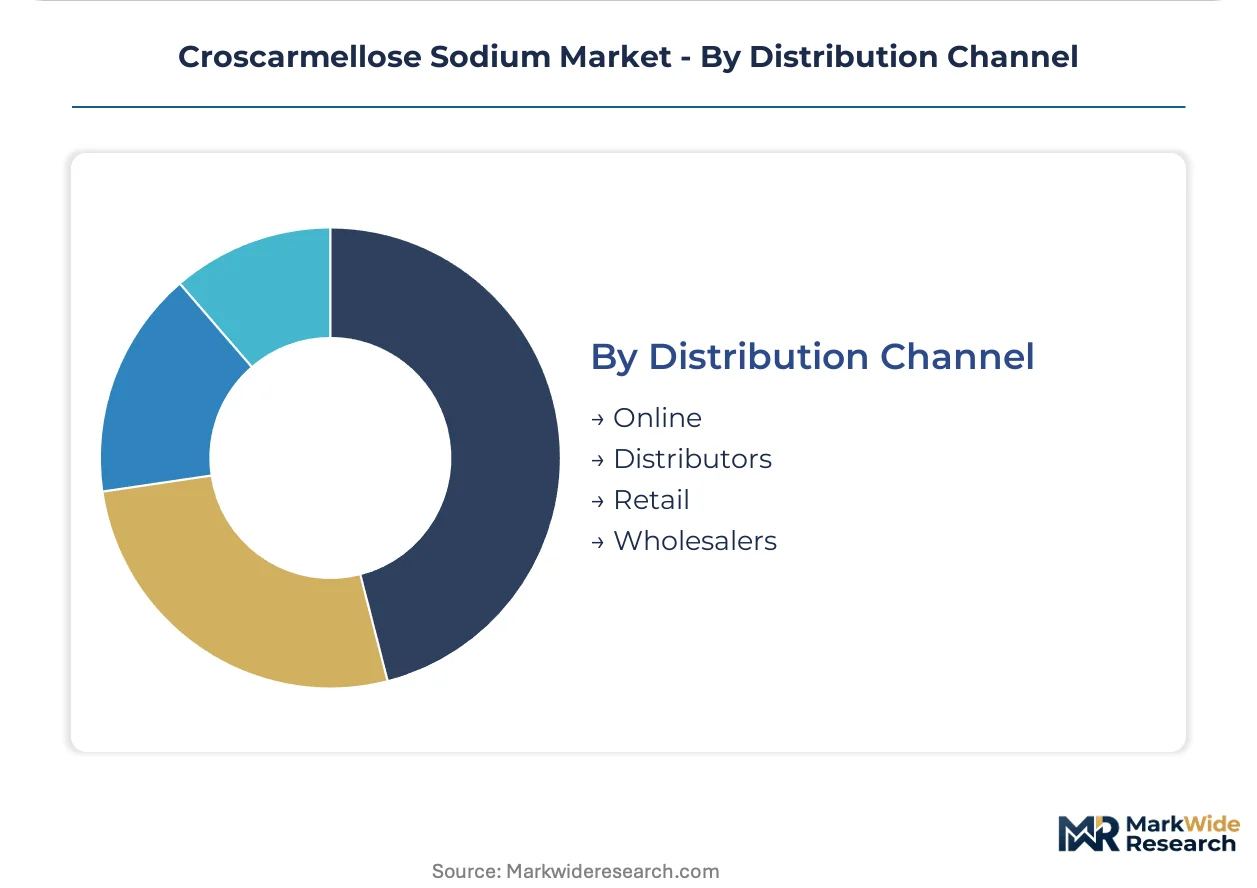
Distribution Channel:
Supply concentration in excipient-specialized distributors shapes availability patterns for qualified pharmaceutical-grade material.
- Online:E-commerce platforms serve nutraceutical and research laboratory segments with rapid fulfillment of catalog-grade specifications.
- Distributors:Excipient-specialized distributors maintain qualified inventory positions, technical support capabilities, and multi-jurisdictional documentation packages for pharmaceutical manufacturers.
- Retail:Direct pharmacy and small-compounder supply represents a fragmented, low-volume channel with limited technical service integration.
- Wholesalers:Bulk material aggregators serve food additive and industrial applications with standardized grades and minimal certification overhead.
Distributors manage the majority of qualified pharmaceutical throughput; online channels are expanding most quickly as digital procurement penetrates mid-tier supplement brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in croscarmellose sodium trace divergent trajectories across major pharmaceutical manufacturing hubs, with India running substantial import dependence for pharmacopeial-grade material while the United States and Germany maintain balanced trade positions in specialized excipient grades.
United States
FDA's IPEC-PQG GMP guidelines drive domestic pharmaceutical manufacturers toward qualified superdisintegrant suppliers with documented supply chain transparency. The New Jersey-Pennsylvania corridor hosts concentrated tablet formulation operations serving both innovator and generic drug pipelines. Continuous manufacturing retrofits at facilities near Princeton accelerate demand for powder grades optimized for real-time feeding systems.
Germany
EMA's revised excipient risk assessment guidelines mandate enhanced documentation for cross-linked cellulose derivatives entering European markets. The Rhine-Main industrial cluster around Frankfurt anchors continental superdisintegrant distribution through excipient-specialized distributors maintaining multi-jurisdictional certification packages. Inline near-infrared spectroscopy deployment at Darmstadt-area facilities compresses batch release timelines from days to hours.
India
CDSCO's harmonized BIS standards for imported excipients create compliance burdens for Mumbai-Pune and Hyderabad contract manufacturers serving US FDA and EMA submissions. The country's generic tablet production concentrates disproportionately in these western and southern clusters, generating geographic demand risk. Domestic excipient vendors are restructuring supplier agreements to satisfy enhanced European documentation requirements.
Switzerland
Swissmedic's alignment with EMA pharmacopeial standards positions Basel-Zurich pharmaceutical operations as quality benchmarks for superdisintegrant specification. The country's precision manufacturing heritage supports early adoption of process analytical technology for immediate-release oral solids. German and Swiss operators co-develop powder grades optimized for direct compression without pre-blending steps.
Brazil
ANVISA's emerging pharmacopeial-grade excipient standards create structural opportunity for local production serving Latin American generics markets currently dependent on imports. São Paulo state's pharmaceutical manufacturing base consumes rising volumes of superdisintegrants as abbreviated new drug application filings accelerate. Regional distributors are consolidating procurement decisions to reduce tariff exposure on imported excipient grades.
Croscarmellose Sodium Market Competitive Environment
On the supply side, the industry is moderately consolidated around cellulose derivative specialists with backward integration into raw fiber sourcing and excipient-focused distributors maintaining qualified inventory positions. Three strategic archetypes dominate: European manufacturers leveraging continuous manufacturing partnerships, Asian suppliers serving cost-sensitive generic portfolios, and plant-based positioning specialists capturing clean-label supplement demand. Capacity expansion and pharmacopeial certification upgrades constitute the dominant competitive moves.
Among European excipient specialists, DFE Pharma and JRS Pharma occupy positions anchored by continental manufacturing footprints and cellulose supply chain control. Roquette Frères exemplifies the plant-derived positioning archetype competing for consumer-facing supplement applications. Asahi Kasei and Mingtai Chemical represent Asian-based manufacturing scale serving pharmaceutical and industrial grade demand pools respectively.
| Leading Market Players |
|---|
| Asahi Kasei |
| Blanver |
| DFE Pharma |
| Anhui Sunhere Pharmaceutical Excipients |
| ALPHA |
| JRS Pharma |
| NB Entrepreneurs |
| Roquette Frères |
| Mingtai Chemical |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Antwerp container corridors absorb 12-15% cost premiums on croscarmellose sodium shipments from Asian manufacturing hubs, compressing margins for European distributors while enabling three-tier pricing stratification across pharmacopeial, technical, and industrial grades. This freight-cost wedge reinforces supply concentration in western India and eastern China, where backward-integrated cellulose processors command pricing power over downstream formulation houses in Germany and the United States.
Pricing Analysis
Batch-process croscarmellose sodium commands 15-20% price premiums over continuous-manufacturing-optimized grades, while next-generation direct-compression powders with inline NIR compatibility trade at further markups. Pricing stratifies across premium, standard, and economy tiers based on USP-NF/EP certification status and particle size distribution precision. Cost compression in standard-grade material is intensifying because Indian contract manufacturers are consolidating procurement volumes under centralized qualification committees. Generic pharmaceutical companies exhibit highest price sensitivity, while innovator drug makers prioritize batch-to-batch consistency over unit cost.
Supply Chain Analysis
EU REACH restrictions on cross-linked cellulose derivative imports have tightened documentation requirements for Mumbai-Pune and Hyderabad exporters, lengthening customs clearance timelines without blocking material flows. Manufacturing gravity centers on India, China, and Germany, with the first two dominating raw cellulose sourcing and the third anchoring high-purity finishing operations. Supply chain stability rests on cotton linter and wood pulp availability from forestry operations in Brazil and Indonesia. Single-source vulnerability concentrates in western India's generic tablet clusters, where CDSCO-mandated BIS compliance creates qualification bottlenecks. Distribution runs through excipient-specialized distributors maintaining qualified inventory positions across IPEC-PQG GMP jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous manufacturing platform standardization is collapsing traditional excipient procurement into interoperable supply ecosystems, with real-time powder feeding systems forcing vendor qualification around performance specifications rather than batch certificates alone.
For Market Incumbents: Entrench market position through captive cellulose sourcing agreements in Brazil and Indonesia, insulating against cotton linter price volatility while securing preferential allocation during harvest cycle disruptions. Accelerate pharmacopeial certification upgrades for USP-NF, EP, and JP concurrent compliance to preempt buyer consolidation among top-ten generic houses. Capacity expansion in continuous-line-compatible powder grades represents the critical defensive lever against crospovidone substitution in cost-sensitive portfolios. For New Entrants and Emerging Players: Brazilian ANVISA-aligned local production of pharmacopeial-grade material represents the most penetrable entry point, serving Latin American generics markets currently dependent on tariff-exposed imports from Asia. Clean-label nutraceutical positioning in North American supplement brands offers secondary white-space capture, leveraging plant-derived croscarmellose sodium against synthetic superdisintegrant alternatives. Go-to-market execution should prioritize co-development partnerships with equipment vendors retrofitting continuous compression lines. For Investors and Strategic Acquirers: Mid-cap European excipient specialists with established IPEC-PQG GMP audit histories and backward-integrated cellulose supply chains offer the most attractive acquisition profile for long-term platform economics exposure. These targets combine defensive moats in qualification-intensive regulated markets with offensive optionality in continuous manufacturing partnerships. Monitor EMA excipient risk assessment guideline enforcement intensity as the primary inflection signal—accelerated documentation requirements would favor acquirers with pre-qualified supply chain transparency systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cellulose Sourcing | Captive supply of cotton linter from Brazilian forestry operations reduces raw material volatility exposure. |
| Continuous Line Powder Grade Development | Co-development with German equipment vendors enables real-time feeding without pre-blending steps. |
| Multi-Jurisdictional Pharmacopeial Certification | Concurrent USP-NF, EP, and JP compliance accelerates qualification with centralized buyer committees. |
| Clean-Label Positioning Investment | Plant-derived croscarmellose sodium captures share from synthetic alternatives in supplement applications. |
| Regional Manufacturing Footprint Expansion | ANVISA-aligned Brazilian production reduces tariff exposure for Latin American generics markets. |
Study Parameters
A spread of perspectives from pharmaceutical formulation scientists, excipient procurement directors, regulatory affairs specialists, and contract manufacturing organization executives converged on the working assumptions driving this analysis. Primary field engagement combined structured interviews with secondary validation against FDA IPEC-PQG GMP guidance documents, EMA excipient risk assessment guidelines, USP-NF and EP monograph specifications, and Indian CDSCO harmonized BIS standards. Customs trade data from major pharmaceutical manufacturing hubs and SEC filings of publicly traded excipient suppliers provided volume and value anchor points. Bottom-up segment sizing triangulated against top-down market reconstruction from identified manufacturer capacities.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation modeling across dosage form, application grade, end-user type, and distribution channel. Treatment line positioning, regional regulatory cluster alignment, and continuous manufacturing adoption intensity provided pharmaceutical-specific forecast dimensions. CAGRs derived from fitted growth curves applied to base-year estimates, with cross-validation against identified capacity expansion announcements and pharmacopeial certification timelines. Raw material cost indices for cotton linter and wood pulp, freight rate fluctuations on Asia-Europe container corridors, and generic drug filing volumes at US FDA and EMA fed industry-specific forecast inputs.
Practitioners should monitor cellulose feedstock harvest cycles, IPEC-PQG GMP audit enforcement intensity, and continuous manufacturing retrofit adoption rates for early signals requiring forecast reassessment. Forecasts reflect assumptions about regulatory convergence trajectories and buyer consolidation patterns among multinational generic houses. Material shifts in EMA excipient documentation requirements or sudden cellulose supply disruptions from major forestry regions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Methyltrimethoxysilane Market
Specialty Chemicals
Dimethicone Market
Specialty Chemicals
4-Benzoylbutyric Acid Market
Specialty Chemicals
Global Spray Polyurethanes Foam Market
Specialty Chemicals
Global Salicylic Acid Market
Specialty Chemicals
Fluoroethylene Carbonate (FEC) Market
Specialty Chemicals
Biocides for Leather Market
Specialty Chemicals
Europe Optical Brighteners Market
Specialty Chemicals
Global Ceramide Market
Specialty Chemicals
Textile Flame Retardants Market
Specialty Chemicals
Photoinitiators Market
Specialty Chemicals
Fluorinated Plasma Surface Treatment Market
Specialty Chemicals
Fluorotelomers Market
Specialty Chemicals
Acesulfame K Market
Specialty Chemicals
Alkoxide Market
Specialty Chemicals
Superoxide Dismutase Market