
 Global Livestock Insurance Market | 2026-2036
Global Livestock Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Global Livestock Insurance Market Outlook
Commercial livestock operations are bifurcating from smallholder cooperatives as the dominant buyer archetype in premium livestock insurance. AXA SA leverages its European agricultural risk infrastructure to dominate specialty cattle coverage in France and Germany. QBE Insurance Group anchors its competitive position through extensive pasture damage assessment networks across Australia and New Zealand. Allianz SE differentiates via integrated climate data platforms that streamline index-based policy pricing for large-scale swine producers.
Livestock insurance constitutes risk-transfer instruments designed to indemnify agricultural producers against mortality, disease, and environmental losses affecting cattle, swine, poultry, and sheep. Underwriters deploy satellite imagery, weather indices, and veterinary epidemiological data to parameterize coverage limits and trigger conditions. Multi-peril policies command the deepest premium pools among commercial farmers, while index-based products represent the fastest-expanding structural category due to reduced claims verification costs. Traditional named-peril coverage retains dominance among smallholder segments where per-unit administrative economics constrain product innovation.
The USDA's Risk Management Agency shapes product standardization through federal crop insurance program guidelines, while EU Green Deal agricultural sustainability mandates drive EFSA-aligned animal welfare compliance into policy terms. India's IRDAI and BIS frameworks increasingly require livestock insurers to maintain localized veterinary verification capacity as a condition for rural market access. Stakeholders must monitor how parametric technology deployment alters capital reserve requirements and distribution economics across divergent farm scale segments.
Market Dynamics
Satellite-based pasture monitoring technology is compressing claims verification cycles and redistributing underwriting economics toward index-based products across commercial cattle operations.
Growth Catalysts
- EU Green Deal agricultural sustainability mandates:EFSA-aligned animal welfare compliance requirements are embedding insurance participation into livestock operation financing across France, Germany, and the Netherlands.
- Commercial dairy operations:Climate volatility in Australia is forcing expansion of mortality and revenue protection coverage among large-scale milk producers.
- Federal agricultural credit programs:Brazil's rural financing frameworks now mandate insurance participation as a condition for accessing subsidized operating capital in cattle ranching regions.
Market Restraints
- Veterinary verification capacity constraints:India's IRDAI and BIS frameworks require localized veterinary infrastructure that insurers must build before rural market entry, raising fixed cost thresholds.
- Smallholder administrative economics:Per-unit policy servicing costs remain prohibitive for traditional named-peril products among fragmented farm holdings in sub-Saharan Africa.
- Parametric basis risk:Index-based triggers using satellite-derived vegetation indices can diverge from actual on-ground livestock losses, creating coverage gaps that undermine producer trust.
Strategic Opportunities
- Underpenetrated poultry segments in Southeast Asia:Industrial broiler and layer operations in Vietnam and Indonesia lack structured mortality coverage despite concentration risk from avian influenza.
- Blockchain-verified livestock provenance:Integration of distributed ledger technology with parametric triggers is creating automated indemnity settlement rails for export-oriented beef producers.
- USDA Risk Management Agency product standardization:Federal guideline alignment is enabling reinsurance capital to flow into previously non-standardized livestock coverage categories.
Industry Challenges
- Climate data science talent scarcity:Underwriters lack sufficient actuarial capacity to parameterize multi-peril policies using satellite imagery and weather index correlations.
- Legacy policy administration system integration:Established insurers face friction embedding parametric trigger engines into core claims processing workflows built for indemnity verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Livestock Insurance Market |
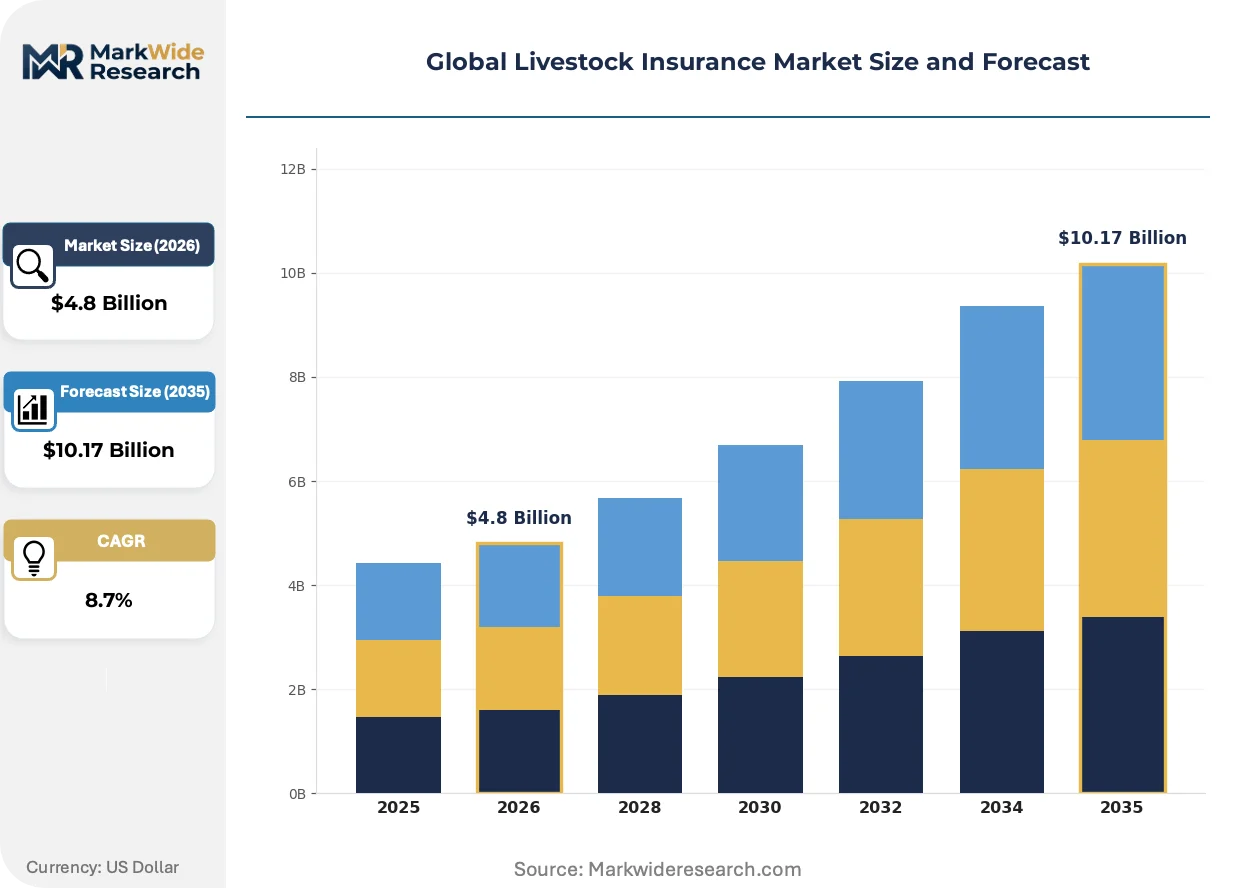
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Full Coverage, Partial Coverage, Livestock Mortality, Pasture Damage Policy Type: Multi-Peril, Named Peril, Index-Based, Traditional Livestock Type: Cattle, Swine, Poultry, Sheep Market Segment: Commercial Farmers, Smallholder Farmers, Cooperatives, Others |
| Companies Covered | Nationwide Mutual Insurance Company, AXA SA, FBL Financial Group, Inc, HDFC ERGO General Insurance Company Limited, ICICI Lombard General Insurance Company Limited, The Hartford, Allianz SE, ProAg (Tokio Marine HCC group of companies), QBE Insurance Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Livestock Insurance Market Strategic Shifts
Technology deployment is compressing the distance between risk occurrence and capital settlement, while regulatory frameworks increasingly embed insurance into agricultural credit access conditions.
Remote sensing hardware is miniaturizing. Nano-satellite constellations now deliver daily pasture biomass measurements at 10-meter resolution. Large-scale cattle ranchers in Australia and Brazil are adopting these feeds for automated forage adequacy monitoring. The technology is miniaturizing the cost structure of index-based underwriting, enabling premium pools that previously required government subsidy to achieve commercial viability.
REACH chemical safety protocols in Europe are extending liability coverage requirements into livestock feed contamination events. Feed additive manufacturers now face mandatory insurance-backed financial assurance for dioxin or mycotoxin outbreak remediation. Specialty cattle coverage in Germany and France is responding with integrated product liability extensions that bundle animal health with supply chain contamination protection.
Buyer concentration among protein processors is reshaping coverage procurement patterns. JBS, Tyson Foods, and Cargill are mandating insurance compliance as a supplier qualification criterion for contracted feedlot operators. This channel consolidation is displacing direct farm-level policy sales in the US cattle feeding corridor and Brazil's Mato Grosso beef production zone, concentrating distribution leverage with underwriting partners holding processor-approved status.
Global Livestock Insurance Market Segmentation
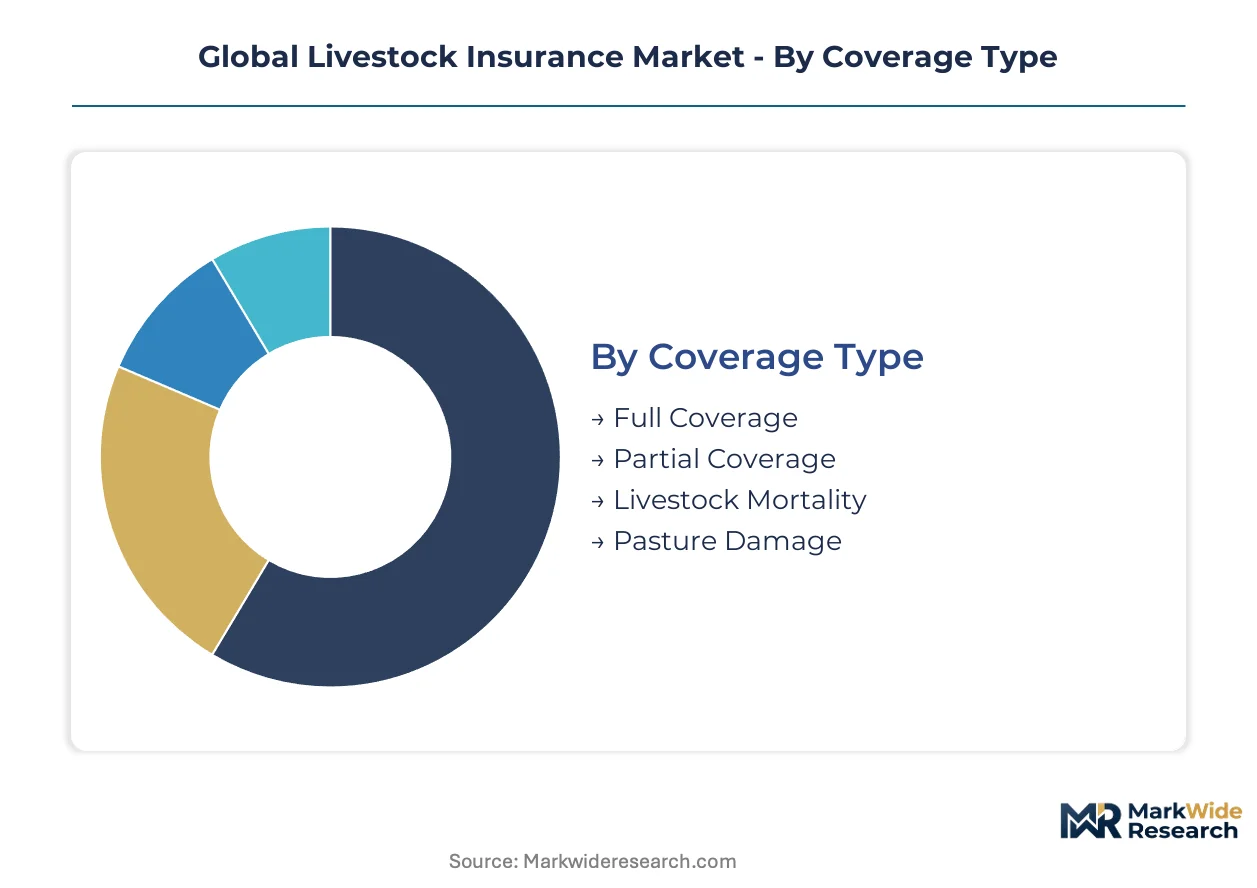
Livestock insurance underwriting economics diverge sharply across coverage structures and buyer scale. Parametric triggers, mortality indemnity limits, and farm operational size collectively determine premium adequacy and claims processing architecture.
Coverage Type:
Regulatory frameworks in Brazil, Australia, and India mandate distinct capital reserve treatments for mortality versus asset-based coverage, reshaping product distribution.
- Full Coverage:Comprehensive indemnity against mortality, disease, and environmental loss with individual animal verification. Australia's commercial dairy operations concentrate demand here as climate volatility forces protection of high-value genetic stock.
- Partial Coverage:Named-peril limitation with proportional payout structures and lower premium thresholds. Smallholder cooperatives in India's Rajasthan and Gujarat states anchor volume as IRDAI veterinary infrastructure requirements constrain full-coverage penetration.
- Livestock Mortality:Specified peril coverage targeting disease and accident losses with veterinary certification triggers. Brazil's cattle ranching regions drive uptake through federal agricultural credit program mandates.
- Pasture Damage:Satellite-indexed forage inadequacy protection with automated trigger settlement. North American and Australian large-scale operators adopt this as nano-satellite biomass measurement costs compress.
Full Coverage handles the majority of throughput; Pasture Damage is gaining share fastest as parametric technology matures.
Policy Type:
Cost tier differentiation separates commercial viability from subsidy dependence across underwriting models.
- Multi-Peril:Bundled coverage combining mortality, revenue, and asset protection with complex actuarial pricing. Germany and France's EFSA-aligned animal welfare compliance requirements embed this structure into livestock operation financing.
- Named Peril:Specified risk enumeration with simplified claims verification and lower administrative overhead. Sub-Saharan Africa's fragmented farm holdings rely on this format where per-unit servicing economics prohibit multi-peril deployment.
- Index-Based:Parametric triggers using satellite imagery and weather indices with automatic payout settlement. Brazil's Mato Grosso beef producers and Australian cattle ranchers expand adoption as verification cost curves flatten.
- Traditional:Conventional indemnity verification with veterinary assessment and documented loss proof. India's BIS framework rural market access requirements preserve this structure where localized verification capacity remains mandatory.
Traditional policies still carry volume weight; Index-Based products are climbing the fastest on technology cost reduction.
Livestock Type:
Species-specific epidemiology and valuation density concentrate underwriting expertise and capital deployment.
- Cattle:High-value beef and dairy genetic stock with individual animal tracking and extended liability horizons. Australia's commercial dairy expansion and Brazil's ranching credit mandates concentrate premium pools.
- Swine:Intensive confinement operations with disease outbreak concentration risk and rapid inventory turnover. Germany and Netherlands EFSA compliance frameworks integrate coverage into operational financing.
- Poultry:Industrial broiler and layer density with avian influenza exposure and short production cycles. Vietnam and Indonesia's underpenetrated segments present structural opportunity despite mortality concentration.
- Sheep:Extensive grazing systems with predator and environmental loss profiles and lower per-unit valuation. Pasture damage index products align naturally with remote monitoring economics.
Cattle underwriting dominates capital deployment; Poultry represents the steepest expansion trajectory on Southeast Asia industrialization.
Market Segment:
Customer scale determines distribution architecture and product innovation feasibility.
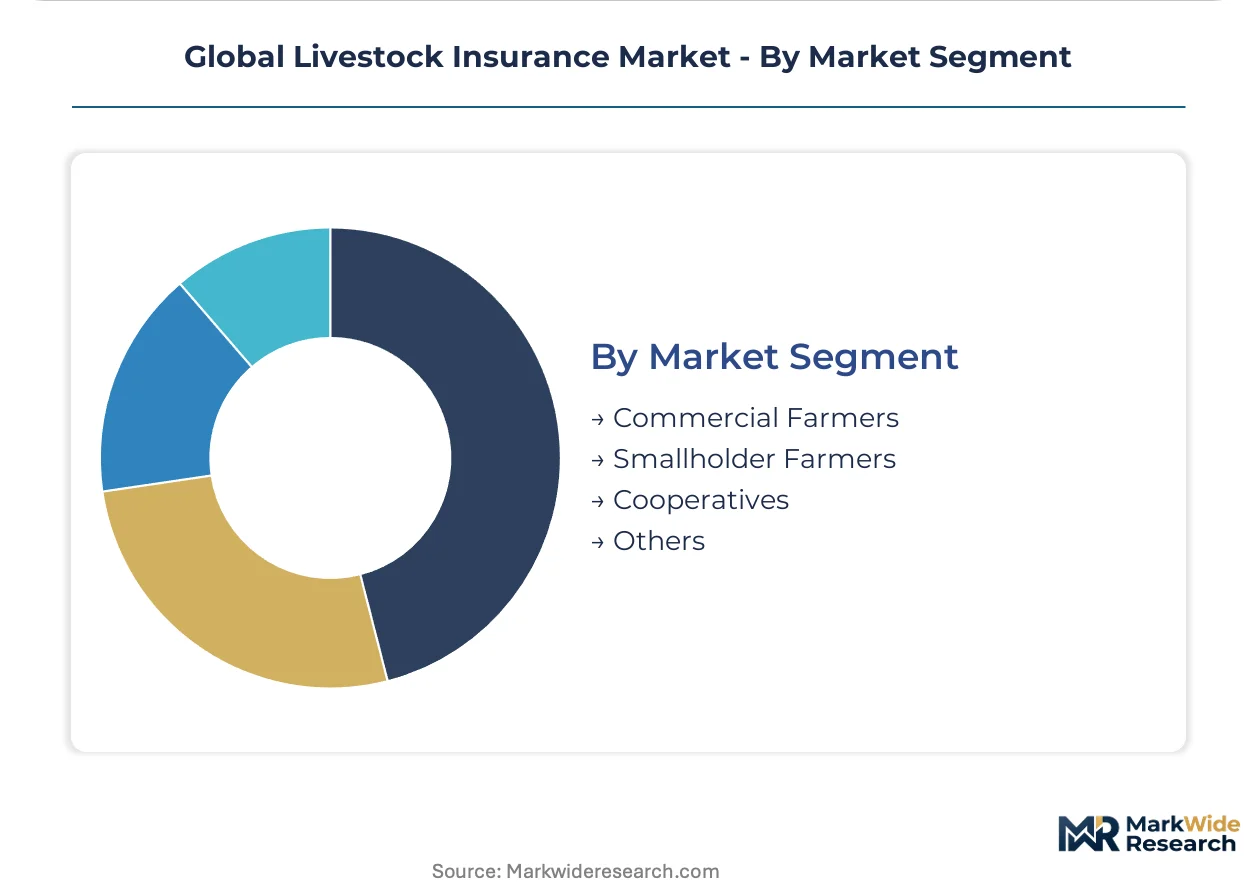
- Commercial Farmers:Large-scale operations with integrated risk management and direct insurer relationships. JBS, Tyson Foods, and Cargill supplier qualification mandates in the US and Brazil concentrate procurement leverage.
- Smallholder Farmers:Fragmented holdings with cooperative aggregation and administrative cost constraints. India's veterinary infrastructure requirements and sub-Saharan Africa's per-unit economics limit product penetration.
- Cooperatives:Collective purchasing and risk pooling with shared verification infrastructure. Australia's dairy cooperative networks and Brazil's rural credit associations anchor this channel.
- Others:Institutional livestock asset managers and integrated protein processors with captive coverage structures. Blockchain-verified provenance integration is emerging here for export-oriented beef supply chains.
Commercial Farmers command premium volume; Cooperatives are expanding most quickly on aggregation efficiency gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial livestock operations in Australia, Brazil, and Germany concentrate premium volume as climate volatility and credit mandates reshape buyer archetypes. Smallholder cooperatives in India and extensive grazing systems in Argentina anchor mid-market penetration where administrative economics permit.
Australia
Commercial dairy operations in Victoria and New South Wales drive mortality and revenue protection expansion as drought frequency intensifies. The country's national agricultural risk agency shapes product standardization through federal program guidelines. Satellite-based pasture monitoring networks across Queensland's cattle corridor compress claims verification cycles for large-scale ranchers.
Brazil
Federal agricultural credit programs in Mato Grosso and Goiás mandate insurance participation for subsidized operating capital access. ANVISA-aligned animal health protocols embed coverage verification into rural financing workflows. JBS and Minerva Foods supplier qualification criteria in São Paulo's processing corridor concentrate procurement leverage with approved underwriters.
Germany
EFSA-aligned animal welfare compliance requirements under EU Green Deal mandates integrate multi-peril coverage into livestock operation financing across Bavaria and Lower Saxony. REACH chemical safety protocols extend liability coverage into feed contamination events for additive manufacturers. Specialty cattle underwriters in Baden-Württemberg bundle supply chain contamination protection with animal health policies.
India
IRDAI and BIS frameworks require localized veterinary verification capacity as a condition for rural market entry in Rajasthan and Gujarat. Smallholder cooperatives anchor named-peril volume where per-unit administrative economics constrain full-coverage penetration. Dairy cooperative networks in Maharashtra aggregate collective purchasing for shared verification infrastructure.
United States
The USDA's Risk Management Agency enables reinsurance capital flow into previously non-standardized livestock coverage categories across Texas and Iowa feedlot corridors. Tyson Foods and Cargill supplier compliance mandates displace direct farm-level policy sales. Index-based parametric products gain traction in Great Plains cattle ranching regions as satellite trigger costs compress.
Global Livestock Insurance Market Competitive Environment
Player mix skews toward diversified multi-line insurers with established agricultural risk infrastructure. Market structure concentrates around three tiers: global carriers with integrated climate data platforms, regional specialists with veterinary verification networks, and government-backed rural development insurers. Dominant competitive moves include parametric technology licensing partnerships and backward integration into satellite imagery analytics capabilities.
Within the global carrier tier, AXA SA and Allianz SE exemplify European agricultural risk infrastructure deployment, while QBE Insurance Group anchors Asia-Pacific pasture assessment network specialization. Nationwide Mutual Insurance Company and The Hartford occupy positions within the North American federal program-aligned segment. HDFC ERGO General Insurance Company Limited and ICICI Lombard General Insurance Company Limited represent the India-focused veterinary verification capacity builders required by IRDAI rural market access rules.
| Leading Market Players |
|---|
| Nationwide Mutual Insurance Company |
| AXA SA |
| FBL Financial Group, Inc |
| HDFC ERGO General Insurance Company Limited |
| ICICI Lombard General Insurance Company Limited |
| The Hartford |
| Allianz SE |
| ProAg (Tokio Marine HCC group of companies) |
| QBE Insurance Group |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at satellite imagery analytics providers shapes premium floors across index-based livestock coverage, concentrating underwriting economics among carriers with captive remote sensing partnerships in Australia and Brazil.
Pricing Analysis
Cost-plus contracts with satellite data indexation dominate parametric policy pricing, tying premiums to vegetation measurement feed costs rather than traditional loss-ratio experience. Price differentiation separates multi-peril bundled coverage for Germany's EFSA-compliant dairy operations from named-peril products serving India's veterinary-constrained cooperatives. Pricing pressure stems from nano-satellite constellation cost compression, which erodes historical data-provider margins. Smallholder cooperatives in sub-Saharan Africa exhibit highest price sensitivity, while JBS-approved feedlot operators in Brazil's Mato Grosso corridor show lowest elasticity due to processor-mandated compliance.
Supply Chain Analysis
Australia and Brazil anchor satellite-based pasture monitoring production, with Germany specializing in EFSA-aligned animal welfare compliance verification systems. Underwriting capacity draws from nano-satellite biomass measurement hardware, localized veterinary certification networks, and blockchain provenance infrastructure. Single-source vulnerability concentrates in satellite imagery feed providers, where constellation operator consolidation threatens data access terms. Distribution runs through processor-mandated supplier qualification channels in the US cattle feeding corridor and Brazil's beef production zones, displacing direct farm-level policy sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Livestock insurance functions as a service-attach opportunity where parametric claims settlement and blockchain-verified provenance layers expand faster than traditional mortality indemnity products.
For Market Incumbents: Fortify satellite imagery analytics partnerships to secure data access pricing advantages against emerging climate-tech entrants. Deepen veterinary verification network density in India's IRDAI-mandated rural corridors before fixed-cost thresholds rise. Backward integration into nano-satellite feed provision reduces third-party data dependency for Australian and Brazilian pasture index products. For New Entrants and Emerging Players: Smallholder cooperative aggregation platforms in sub-Saharan Africa represent the most penetrable white-space, where per-unit administrative economics have blocked incumbent multi-peril deployment. Southeast Asia's industrial poultry mortality coverage gap offers secondary entry, with Vietnamese and Indonesian broiler operations lacking structured avian influenza protection. Partner with protein processors for supplier-qualification channel access rather than competing for direct farm sales. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated carriers combining satellite data partnerships with processor-approved distribution status. Long-term viability hinges on parametric trigger engine differentiation and regulatory compliance automation capabilities. Watch for ANVISA-aligned animal health protocol expansions in Brazil as inflection indicators for mandatory coverage penetration acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Technology Licensing | Enables rapid index-based product deployment without proprietary satellite infrastructure investment. |
| Veterinary Network Expansion | Satisfies IRDAI and BIS rural market access requirements while creating verification cost barriers. |
| Processor Partnership Alignment | Secures JBS, Tyson Foods, and Cargill supplier qualification status for feedlot channel concentration. |
| Blockchain Provenance Integration | Automates indemnity settlement for export-oriented beef supply chains with immutable livestock tracking. |
| Climate Data Science Talent Acquisition | Addresses actuarial capacity scarcity for multi-peril policy parameterization using satellite-weather correlations. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, satellite imagery provider disclosures, and agricultural credit program documentation. Underwriting executives, veterinary verification network managers, and protein processor supply chain officers provided operational perspective. USDA Risk Management Agency guidelines, EU Green Deal implementation texts, and IRDAI rural market access rules supplied regulatory anchors. Bottom-up premium pool estimates triangulated against top-down agricultural output value assessments.
Segmentation dimensions modeled include coverage type, policy structure, livestock species, and farm operational scale across the projection horizon. CAGRs derived from historical penetration rate trajectories adjusted for technology cost curve inflections. Satellite imagery resolution improvements and nano-satellite constellation deployment schedules served as industry-specific forecast inputs alongside federal credit mandate expansion timelines.
Forecasts assume regulatory continuity in USDA federal program guidelines, EU Green Deal agricultural sustainability mandates, and Brazil's rural credit insurance participation requirements; material policy shifts would require re-modeling. Parametric basis risk acceptance rates and veterinary infrastructure buildout pace represent key sensitivity variables. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Europe Travel Insurance Market
Insurance
Green Insurance Market
Insurance
Insurance BPO Services Market
Insurance
Telematics-Based Auto Insurance Market
Insurance
UAE Property and Casualty Insurance Market
Insurance
Digital Innovation in Insurance Market
Insurance
UK Cyber (Liability) Insurance Market
Insurance
Commercial Cyber Insurance Market
Insurance
Logistics Insurance Market
Insurance
Earthquake Insurance Market
Insurance
Insurance Big Data Analytics Market
Insurance
Europe Car Insurance Market
Insurance
Asia-Pacific Livestock Insurance Market
Insurance
Travel Insurance Market
Insurance
Mobile Phone Insurance Market
Insurance
Takaful Market