
 Skin Care Packaging Market | 2026-2036
Skin Care Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Skin Care Packaging Market Analytics
Market Overview
Premium-grade airless and refillable specifications is reorganizing competitive dynamics across skin care packaging. Gerresheimer leverages its glass-molding expertise to dominate pharmaceutical-grade cosmetic vials and ampoules. Quadpack differentiates through wood-based and recycled material innovation in premium secondary packaging. Albéa Group anchors global tube capacity with integrated laminate and decoration capabilities.
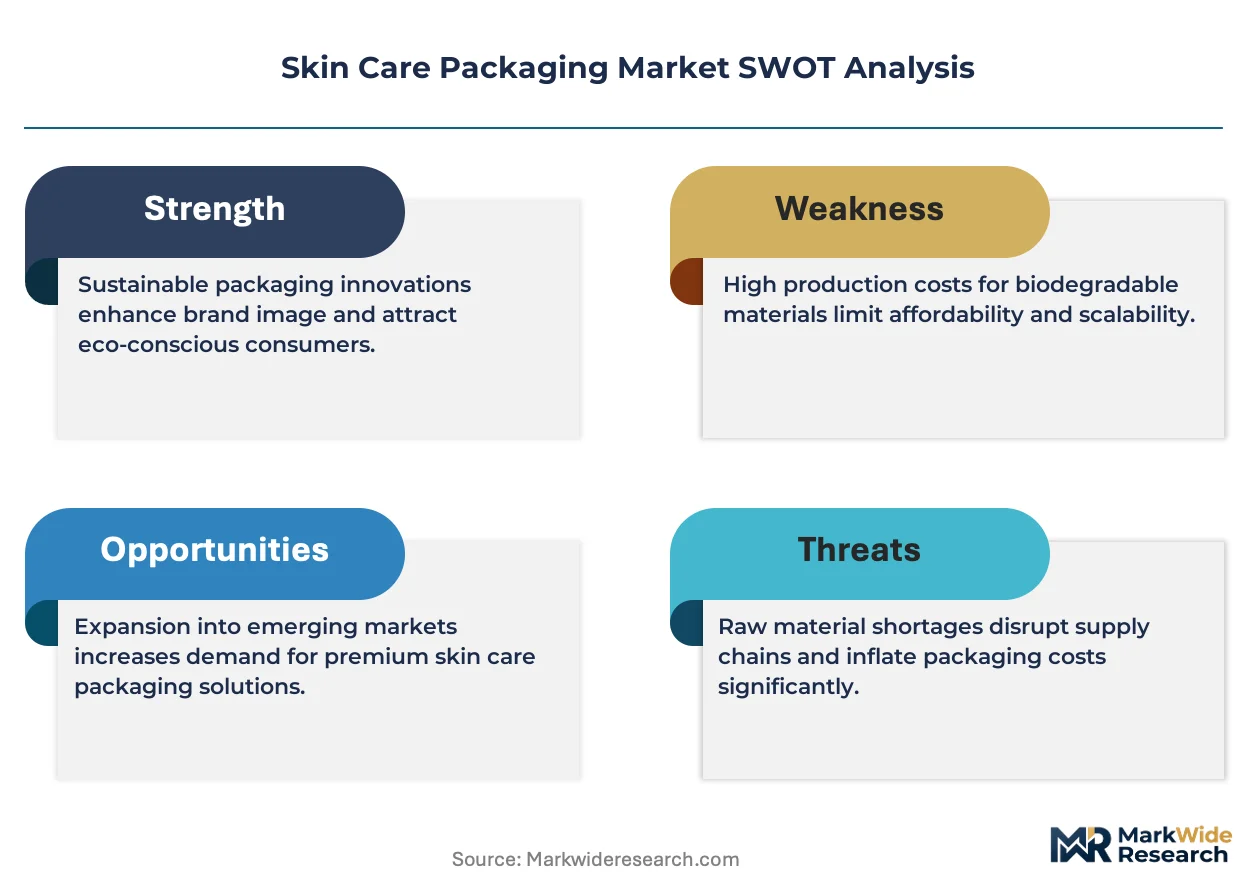
Skin care packaging encompasses primary and secondary containment systems engineered from plastics, glass, metals, and paper substrates with functional specifications including oxygen transmission rates below 0.1 cc/pkg/day for sensitive actives and UV-blocking opacity for retinol formulations. These systems protect formulation stability, enable precise dosing through pump mechanisms, and communicate brand positioning through tactile and visual design elements. Tubes and pump dispensers capture dominant volume share due to hygiene convenience and controlled product evacuation, while glass bottles and jars command premium positioning in anti-aging and luxury segments where perceived purity justifies higher unit economics. Eco-friendly design styles are gaining fastest relative traction as brands respond to Extended Producer Responsibility frameworks and consumer preference shifts.
FDA cosmetic labeling requirements under the Modernization of Cosmetics Regulation Act, EU REACH substance restrictions, and China's GB standards for packaging migration limits collectively elevate compliance costs and reshape material selection across supply chains. South Korea's MFDS enforces rigorous stability testing protocols that indirectly dictate primary packaging performance thresholds for products entering that market. Stakeholders must monitor evolving state-level packaging EPR legislation in the United States and pending EU Packaging and Packaging Waste Regulation revisions to anticipate mandatory recycled content minimums.
Market Dynamics
Extended Producer Responsibility frameworks are forcing material substitutions across skin care packaging supply chains, compressing acceptable feedstock options while elevating compliance costs for converters and brands alike.
Growth Catalysts
- EU Green Deal packaging mandates:Mandatory recycled content minimums and carbon border adjustments are accelerating investment in post-consumer recycled plastic and glass capacity across European converter networks.
- Biotechnology actives proliferation:Peptide and probiotic formulations require oxygen transmission rates below 0.1 cc/pkg/day, driving specification upgrades to multi-layer laminates and airless pump systems.
- Seoul-Incheon cluster concentration:South Korea's K-beauty export engine generates concentrated demand for premium glass ampoules and metallized decorative components with 48-hour sample turnaround capabilities.
Market Restraints
- Post-consumer recycled resin supply scarcity:Cosmetic-grade rPET and rPP availability lags demand by approximately 40 percent, forcing brands to absorb 15-25 percent material cost premiums or downgrade sustainability claims.
- Glass furnace capacity concentration:Pharmaceutical-grade borosilicate and flint glass production concentrates in Germany's Rhine-Ruhr corridor and China's Shandong province, creating single-source vulnerability for premium vial supply.
- Multi-layer laminate recyclability dead-end:Current tube and pouch constructions combining polyethylene, aluminum, and adhesive layers lack viable mechanical recycling pathways under existing EU Packaging and Packaging Waste Regulation sorting infrastructure.
Strategic Opportunities
- Refill station retail expansion:Department stores and specialty beauty retailers in France, Germany, and the United Kingdom are piloting in-store bulk dispensing systems, creating demand for durable primary containers designed for 10+ reuse cycles.
- Digital printing convergence:Direct-to-shape inkjet and laser engraving technologies enable lot-level customization and anti-counterfeiting serialization without plate changeover costs, compressing minimum order quantities for niche and indie brands.
- MFDS stability testing alignment:South Korea's accelerated aging protocols for probiotic and vitamin C formulations create specification premiums for packaging suppliers capable of validated 40°C/75% RH performance documentation.
Industry Challenges
- Decorative metallization chemist scarcity:Vacuum metallization and physical vapor deposition expertise for cosmetic-grade mirror finishes concentrates among aging technician populations in Italy's Lombardy region and Japan's Kansai industrial belt.
- Legacy ERP-to-MES integration friction:Mid-cap converters running 15-20 year-old shop floor systems face 18-24 month implementation timelines to achieve lot traceability required by EU Cosmetics Regulation Article 8 and US FDA MoCRA facility registration mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skin Care Packaging Market |
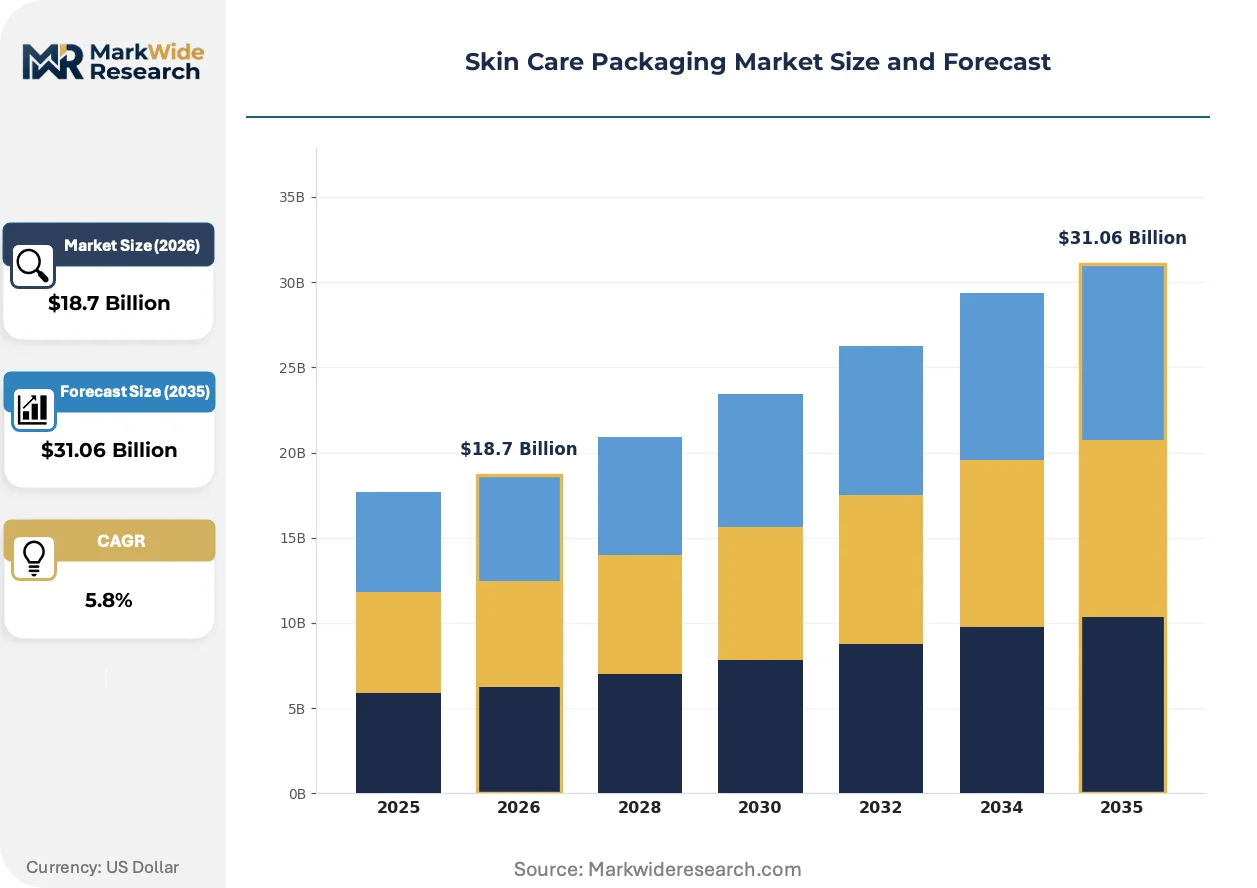
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Tubes, Bottles, Jars, Pumps Material: Plastic, Glass, Metal, Paper Closure Type: Flip Top, Screw Cap, Pump Dispenser, Dropper Design Style: Minimalist, Vintage, Luxurious, Eco-Friendly |
| Companies Covered | Gerresheimer, Quadpack, Albéa Group, PackingCosmetic, Stoelzle Glass Group, Aptar Beauty, Berry Global, Libo Cosmetics, HCP Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skin Care Packaging Market Evolving Landscape
Active and intelligent packaging functionalities are migrating from pharmaceutical applications into prestige skin care, embedding sensors and condition indicators directly into primary containers.
Micro-pump dispensing mechanisms are miniaturizing. These sub-milliliter precision systems enable single-drop serum dosing for high-potency retinol and vitamin C formulations. Premium brands in South Korea and France are specifying these components for 30ml and smaller SKUs. The technology is miniaturizing unit dose formats previously reserved for clinical samples into standard retail presentations.
REACH Annex XVII substance restrictions are tightening migration limits for bisphenols, phthalates, and per- and polyfluoroalkyl substances in cosmetic contact materials. ECHA's 2023-2024 restriction roadmap is forcing laminate converters to reformulate adhesives and heat-seal coatings. Tube and pouch suppliers serving EU markets are accelerating fluorine-free barrier material qualification programs to maintain market access.
Direct-to-consumer subscription models are restructuring order fulfillment requirements. Brands operating on 30-60 day replenishment cycles now specify packaging optimized for individual unit shipping rather than traditional retail case packs. This shift concentrates in North American and Western European markets where Replenishment algorithms and auto-ship programs capture 35-45 percent of prestige skin care volume for participating brands.
Skin Care Packaging Market Segmentation
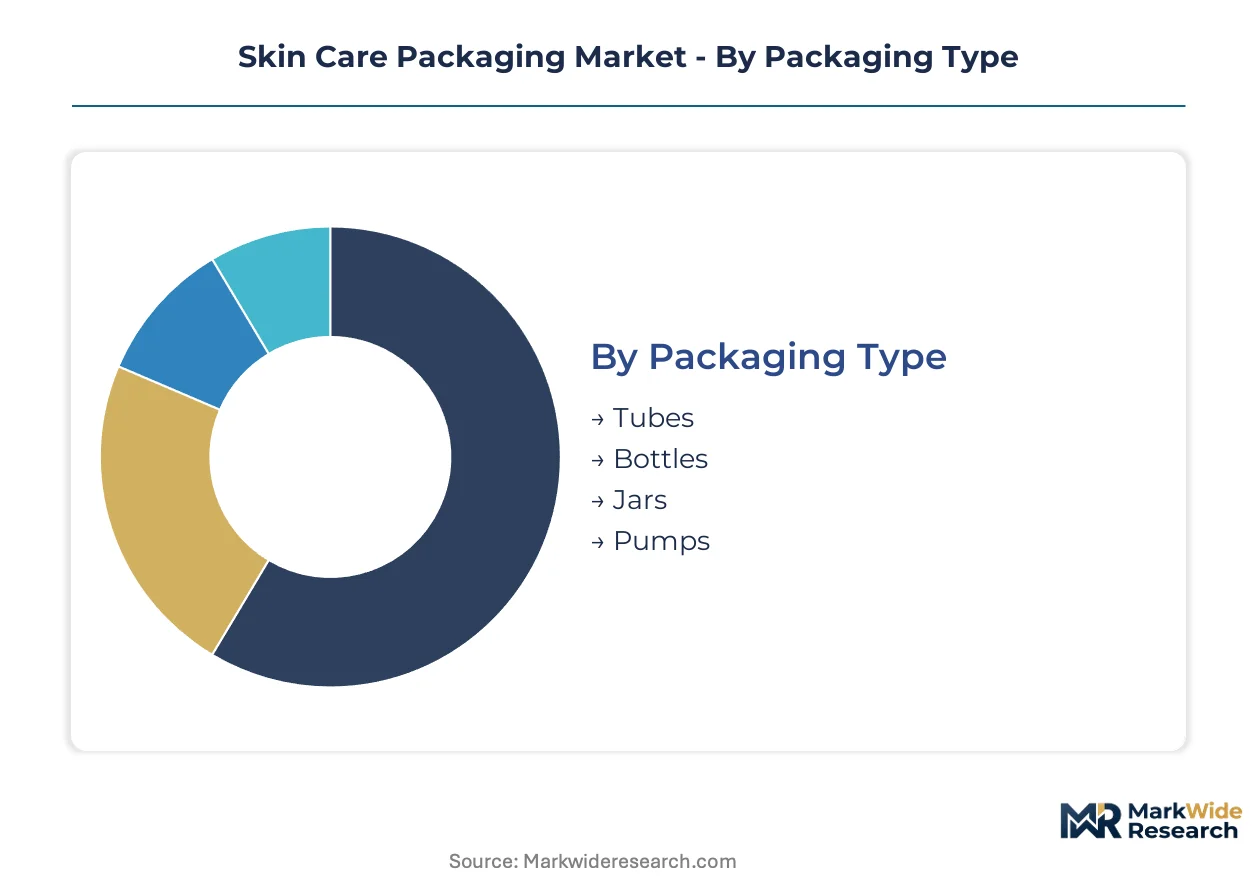
Skin care packaging segmentation reveals divergent supply chain configurations across each dimension. Material selection and closure mechanics dictate regulatory compliance pathways, while design positioning determines geographic market access and margin capture.
Packaging Type:
Tube and bottle formats dominate domestic consumption in North American and European markets, while jar and pump assemblies concentrate in export-oriented manufacturing clusters serving Asian premium brands.
- Tubes:Multi-layer laminate constructions combine polyethylene, aluminum foil, and adhesive barriers to achieve oxygen transmission rates below 0.1 cc/pkg/day for retinol and vitamin C formulations. Demand concentrates in mass-market facial cleanser and sunscreen segments across Germany and the United States, where EU Packaging and Packaging Waste Regulation recyclability mandates are forcing fluorine-free barrier material transitions.
- Bottles:Blow-molded PET and glass formats accommodate liquid serums, toners, and essences with dispensing neck finishes standardized at 18mm, 20mm, and 24mm. South Korea's Seoul-Incheon corridor generates concentrated demand for pharmaceutical-grade borosilicate bottles with metallized decorative treatments, driven by MFDS stability testing requirements for probiotic formulations.
- Jars:Wide-mouth containers in 15ml to 100ml capacities serve thick cream and balm textures.
- Pumps:Airless and standard piston mechanisms enable controlled dosing for sensitive actives.
Tubes hold the largest share; momentum sits with pumps.
Material:
Cost tiers separate commodity feedstocks from performance-grade and certified sustainable alternatives, with recycled content premiums compressing mid-market positioning.
- Plastic:PET, PP, and PE resins dominate volume through injection and blow molding versatility. Post-consumer recycled cosmetic-grade rPET and rPP availability lags demand by approximately 40 percent, forcing brands serving France, Germany, and the United Kingdom to absorb material cost premiums or downgrade sustainability claims under Extended Producer Responsibility frameworks.
- Glass:Flint, amber, and cobalt blue soda-lime and borosilicate compositions provide inert contact surfaces for peptide and acid formulations. Production concentrates in Germany's Rhine-Ruhr corridor and China's Shandong province, creating single-source vulnerability for premium vial supply as pharmaceutical-grade furnace capacity tightens.
- Metal:Aluminum tubes and tinplate components offer collapsible formats and magnetic closure compatibility.
- Paper:Molded pulp and folding carton secondary packaging supports brand sustainability narratives.
Plastic maintains volume leadership; glass is climbing the fastest on biotechnology actives proliferation.
Closure Type:
Application requirements dictate closure selection, with dispensing precision needs escalating across active-ingredient-heavy formulations.
- Flip Top:Hinged polypropylene caps enable one-handed operation for rinse-off products in shower and gym environments.
- Screw Cap:Threaded aluminum and phenolic closures secure jar formats and oil bottles.
- Pump Dispenser:Airless systems with piston or bag-on-valve mechanisms isolate oxygen-sensitive actives from contamination. South Korean and French prestige brands are specifying micro-pump sub-milliliter precision for 30ml serum SKUs, miniaturizing unit dose formats into standard retail presentations.
- Dropper:Glass pipette and bulb assemblies with calibrated tip geometries deliver single-drop dosing for facial oils and concentrated treatments.
Screw caps retain broadest application; pump dispensers are gaining share fastest on oxygen barrier specifications.
Design Style:
Customer type and channel positioning segment design investment, with indie and direct-to-consumer brands driving experimental formats.
- Minimalist:Unadorned surfaces, limited color palettes, and reduced secondary packaging align with clean beauty positioning.
- Vintage:Apothecary-inspired amber glass, serif typography, and cork or wax seal details target heritage brand narratives.
- Luxurious:Heavy-wall glass, magnetic closures, and multi-component secondary boxes command premium shelf presence in department stores.
- Eco-Friendly:Refillable primary containers, mono-material constructions, and molded pulp replacements respond to EU Green Deal mandates and state-level Extended Producer Responsibility legislation in California and New York.
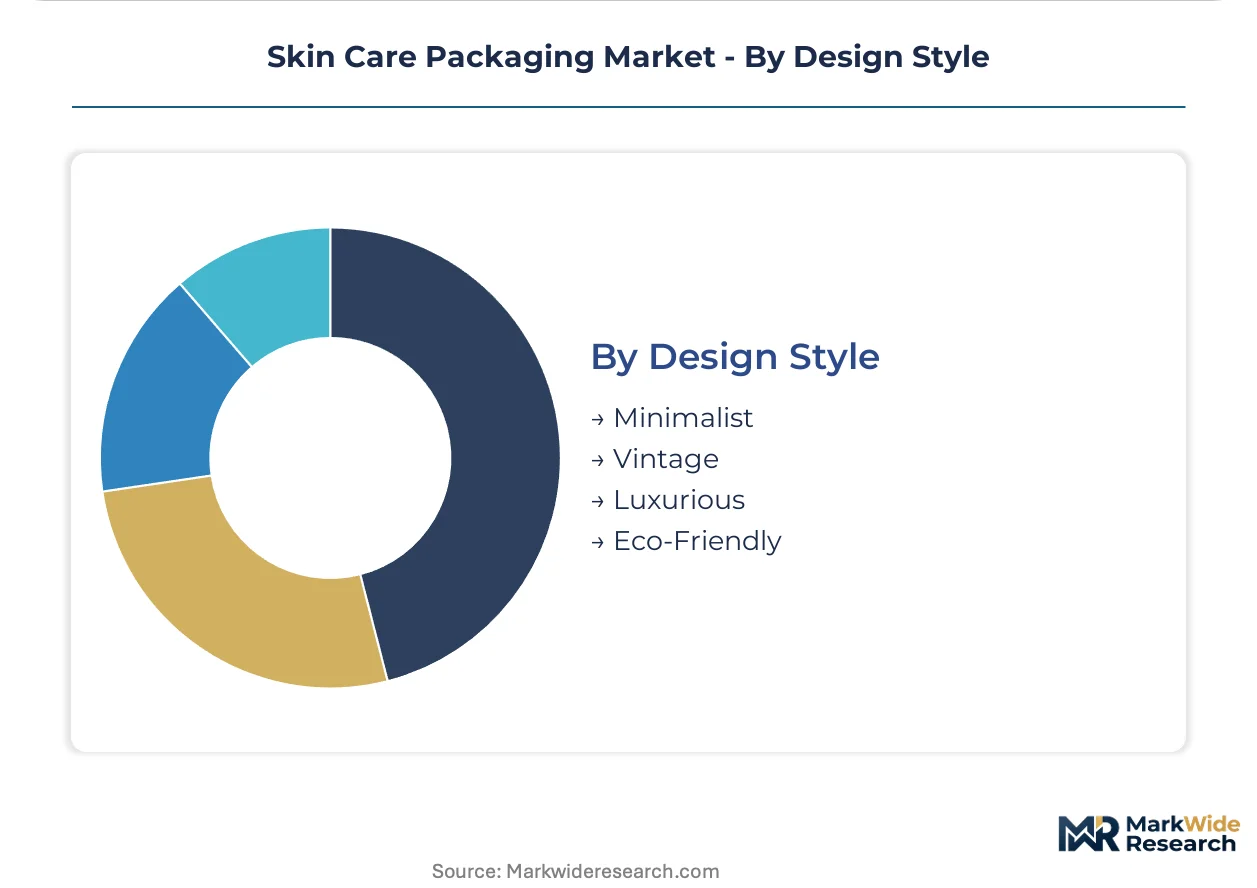
Luxurious designs capture highest per-unit value; eco-friendly formats show steepest expansion trajectory on regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany maintains a structural surplus in pharmaceutical-grade glass exports while importing commodity plastic resins. South Korea and France run deficits in airless pump components, sourcing precision mechanisms from German and Swiss suppliers. China's Shandong province dominates borosilicate furnace capacity, creating asymmetric dependencies for premium vial sourcing.
United States
California and New York state-level Extended Producer Responsibility legislation is forcing rapid material transitions in mass-market facial cleanser tubes. The FDA's Modernization of Cosmetics Regulation Act elevates facility registration and lot traceability requirements for converters serving prestige brands. New Jersey's polymer corridor hosts laminate tube specialists reformulating fluorine-free barrier adhesives to maintain EU market access.
Germany
Rhine-Ruhr packaging corridor converters supply pharmaceutical-grade borosilicate vials to South Korean K-beauty exporters under accelerated stability testing contracts. EU REACH Annex XVII substance restrictions on bisphenols and phthalates are forcing adhesive reformulation across laminate production lines. Bavaria's precision molding clusters are expanding airless pump capacity to capture specification premiums from probiotic formulation brands.
South Korea
Seoul-Incheon beauty cluster demand concentrates on metallized glass ampoules with 48-hour sample turnaround capabilities for export-oriented K-beauty brands. MFDS accelerated aging protocols at 40°C/75% RH create entry barriers for packaging suppliers lacking validated performance documentation. Gyeonggi Province converters are backward integrating into decorative vacuum metallization to reduce Lombardy supplier dependency.
France
Prestige fragrance and skin care houses in Paris drive specification premiums for heavy-wall glass and magnetic closure systems. EU Green Deal packaging mandates and carbon border adjustments are accelerating post-consumer recycled glass qualification programs among Champagne-region furnace operators. Île-de-France retailers are piloting in-store refill stations, creating demand for durable primary containers engineered for 10-plus reuse cycles.
China
Shandong province's borosilicate furnace concentration supplies premium vial demand across Asia-Pacific and European markets. GB standards for packaging migration limits are tightening alignment with EU REACH substance restrictions for export-oriented cosmetic brands. Yangtze River Delta converters are expanding mono-material tube capacity to meet EU Packaging and Packaging Waste Regulation recyclability requirements.
Skin Care Packaging Market Competitive Landscape
Concentration sits with integrated glass and laminate specialists capable of spanning pharmaceutical-grade specifications and mass-market volume. Three tiers structure competitive positioning: multinational converters with furnace and decoration integration, mid-cap regional specialists in precision molding and metallization, and niche players in sustainable material innovation. Capacity expansion and strategic partnerships dominate competitive moves as converters secure captive resin supply and brand co-development relationships.
Among European-integrated specialists, Gerresheimer AG and Stoelzle Glass Group exemplify the furnace-owning archetype with pharmaceutical-grade cosmetic vial capabilities. Quadpack Industries SA occupies a position within the sustainable material innovation tier, representing wood-based and recycled substrate development. These three anchors illustrate the geographic and capability segmentation structuring supplier selection for brands operating across EU Green Deal and MFDS compliance environments.
| Leading Market Players |
|---|
| Gerresheimer |
| Quadpack |
| Albéa Group |
| PackingCosmetic |
| Stoelzle Glass Group |
| Aptar Beauty |
| Berry Global |
| Libo Cosmetics |
| HCP Packaging |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between K-beauty exporters and German furnace operators lock in pharmaceutical-grade borosilicate supply while fixing price visibility for airless pump assemblies across the Seoul-Incheon corridor. These arrangements insulate premium brands from spot resin volatility while embedding compliance premiums for MFDS-validated performance documentation.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in skin care packaging. Pricing stratifies by certification tier—EU REACH-compliant laminates command material premiums over commodity PE constructions—while cost compression in mass-market tubes intensifies because rPET supply scarcity forces brands to absorb feedstock premiums or downgrade sustainability claims. Indie direct-to-consumer brands exhibit highest price sensitivity; prestige houses in France and South Korea demonstrate lowest sensitivity due to specification-locked supplier relationships.
Supply Chain Analysis
Rhine-Ruhr furnace concentration creates single-source vulnerability for pharmaceutical-grade borosilicate vials serving global K-beauty demand. Raw material dependencies center on Shandong province soda-lime feedstock, Lombardy vacuum metallization expertise, and Swiss precision pump mechanisms. Tariff exposure runs through EU carbon border adjustment mechanisms threatening Asian converter cost positions. Distribution feeds from converter direct-to-brand relationships with limited distributor intermediation in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refill infrastructure services and stability-testing documentation layers expand faster than primary container hardware, creating recurring-revenue attach opportunities for packaging suppliers pivoting from transactional unit sales.
For Market Incumbents: Fortify captive resin supply through backward integration into post-consumer recycled flake processing or long-term offtake with European rPET specialists. Expand Bavaria precision molding capacity to capture probiotic formulation specification premiums before mid-cap competitors qualify MFDS protocols. Regulatory tightening on EU Packaging and Packaging Waste Regulation recyclability mandates threatens laminate-heavy product lines without fluorine-free barrier alternatives. For New Entrants and Emerging Players: Rapid 48-hour sample turnaround capabilities for metallized glass ampoules represent a service-layer gap where Lombardy incumbents under-serve Seoul-Incheon cluster demand. Target South Korean export-oriented brands with validated 40°C/75% RH performance documentation as entry wedge. Pursue co-development partnerships with Gyeonggi Province converters seeking decorative vacuum metallization independence from Italian suppliers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors furnace-owning specialists with decoration integration capabilities. Five-to-ten year viability hinges on post-consumer recycled content qualification programs and refill station retail infrastructure buildout. Watch EU Packaging and Packaging Waste Regulation enforcement timelines as inflection signal for mandatory recycled content minimums reshaping converter capital allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Flake Processing | Captive supply secures EU Green Deal compliance without spot market premium exposure. |
| MFDS Stability Testing Qualification | Validated 40°C/75% RH documentation unlocks Seoul-Incheon cluster specification premiums. |
| Fluorine-Free Barrier Material Transition | REACH Annex XVII alignment preserves EU market access for laminate tube portfolios. |
| Refill Station Infrastructure Partnership | Durable primary container engineering for 10-plus reuse cycles captures Paris retailer pilots. |
| Decorative Vacuum Metallization Capacity Addition | Gyeonggi Province backward integration reduces Lombardy supplier dependency for K-beauty exporters. |
Research Methodology
Operator-level perspectives from brand packaging directors, converter plant managers, MFDS regulatory consultants, and refill station retail operators anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through EU REACH restriction roadmaps, FDA MoCRA facility registration filings, and South Korean customs export data for glass ampoule shipments. Bottom-up volume triangulation across material-grade segments intersected with top-down value analysis from converter capacity disclosures.
Sensitivity analysis tested forecast robustness across rPET supply elasticity scenarios and EU carbon border adjustment implementation timelines. The analytical framework modeled segmentation dimensions including packaging type, material grade tier, closure precision level, and design style positioning across the projection horizon. CAGRs derived from converter capacity expansion announcements, brand SKU launch pipelines, and regulatory compliance cost pass-through assumptions. Biotechnology actives proliferation and refill retail infrastructure rollout served as key demand-side inputs.
Forecasts assume regulatory continuity in EU REACH, FDA MoCRA, and South Korea MFDS regimes; material policy shifts would require re-modeling. Supply scarcity in pharmaceutical-grade furnace capacity, EPR framework adoption pace in US states, and Lombardy metallization technician demographics constitute specific revision risks. Practitioners should keep alternative scenarios live as EU Packaging and Packaging Waste Regulation enforcement mechanisms evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
US Personal Care Packaging Market
Cosmetic Packaging
Asia Pacific Cosmetic Packaging Market
Cosmetic Packaging
Nail Polish Packaging Market
Cosmetic Packaging
Glass Cosmetic Bottle Market
Cosmetic Packaging
Metal Cosmetic Packaging Market
Cosmetic Packaging
Fragrance Packaging Market
Cosmetic Packaging
Lotion Tubes Market
Cosmetic Packaging
Cosmetic Spray Bottles Market
Cosmetic Packaging
Europe Cosmetic Packaging Market
Cosmetic Packaging
Global Perfume Packaging Market
Cosmetic Packaging
Beauty Supplements Packaging Market
Cosmetic Packaging
Europe Personal Care Packaging Market
Cosmetic Packaging
Middle East and Africa Cosmetic Packaging Market
Cosmetic Packaging
Make-Up Products Packaging Market
Cosmetic Packaging
India Personal Care Packaging Market
Cosmetic Packaging
Anti-Counterfeit Cosmetic Packaging Market