
 Asia Pacific Cosmetic Packaging Market | 2026-2036
Asia Pacific Cosmetic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Cosmetic Packaging Market Outlook
A capital-intensity divergence between multinational film suppliers and regional molders is bifurcating competitive dynamics in Asia Pacific cosmetic packaging. Amcor Group leverages its multilayer barrier film capabilities to anchor high-volume contracts with global beauty multinationals. Mitsui Chemicals, Inc. sustains polymer innovation pipelines that differentiate its specialty resins for airless pump applications. Albéa Group competes through integrated decoration and dispensing expertise across its Southeast Asian manufacturing footprint.
Asia Pacific cosmetic packaging encompasses primary and secondary containment systems—ranging from mono-material tubes to glass bottles with metallized closures—engineered to preserve product stability, enable precise dosing, and transmit brand identity through haptic and visual design. Mono-material and bio-based polymer formulations are gaining technical priority as recyclability mandates intensify across the region. Tubes and pumps capture expanding share in skincare and personal care end uses where portability and controlled dispensing drive replacement cycles. Glass maintains premium positioning in fragrance and high-end makeup segments where weight and optical clarity signal luxury positioning.
China's SAMR enforces GB standards for cosmetic packaging migration limits, while India's BIS mandates material safety certifications for imported containers. South Korea's MFDS and Japan's METI coordinate divergent labeling and recyclability protocols that fragment compliance costs for pan-Asian suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks and substrate-specific recycling infrastructure buildouts to align capacity investments with regulatory trajectories.
Market Dynamics
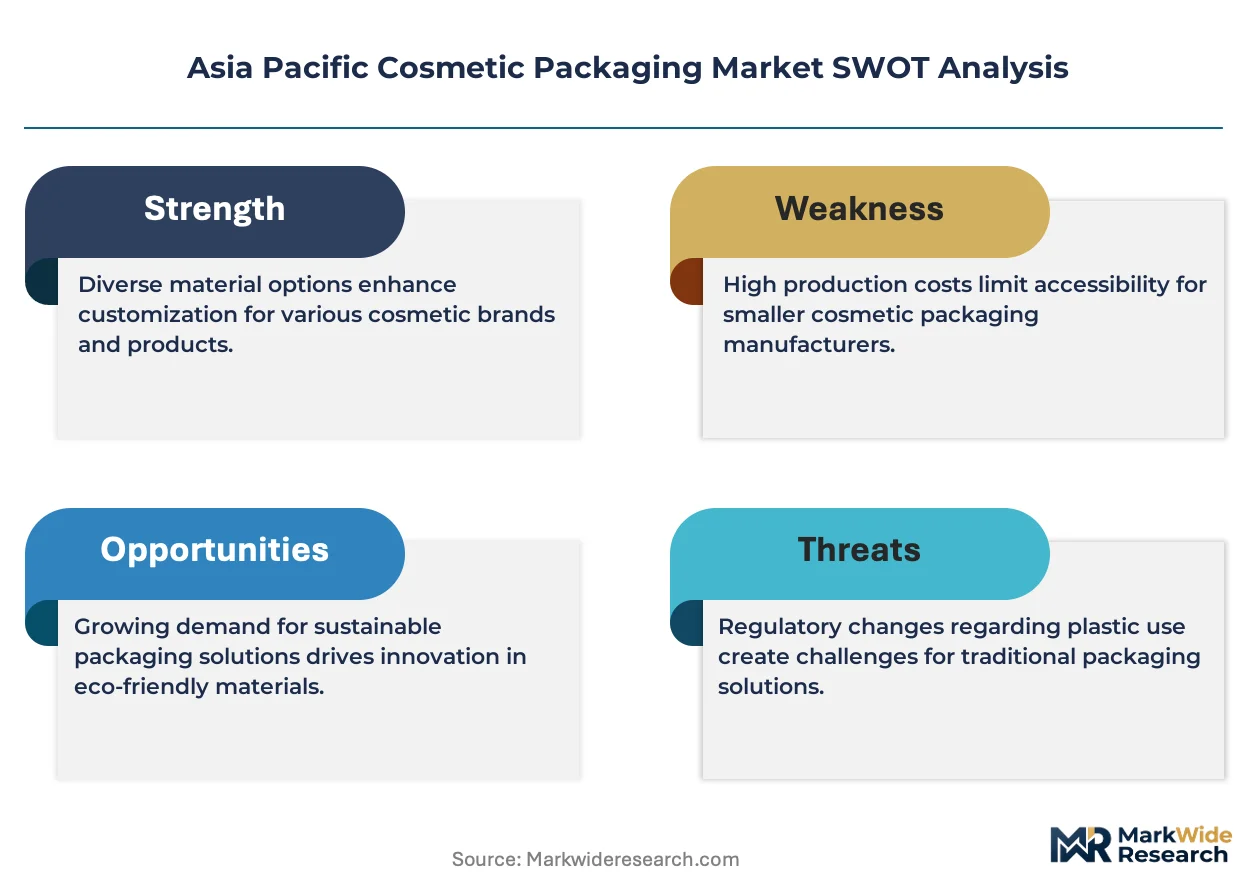
Mono-material packaging specifications are compressing legacy multilayer film architectures across Asia Pacific cosmetic supply chains. South Korea's K-beauty export machine and China's domestic premium skincare expansion are forcing converters to retool extrusion lines for simplified polymer streams that satisfy emerging recyclability mandates without sacrificing barrier performance.
Growth Catalysts
- Airless pump technology:Skincare formulators in South Korea and Japan are specifying precision dosing systems that extend product shelf life and reduce preservative loads. This specification pull is accelerating mold investment in the Seoul-Incheon corridor.
- India's BIS certification expansion:Mandatory material safety testing for imported cosmetic containers is creating captive demand for domestic blow-molding capacity. Local converters are capturing share from Southeast Asian suppliers.
- Bio-based polymer R&D pipelines:Mitsui Chemicals and regional compounders are commercializing sugarcane-derived polyethylene formulations. These materials address brand-owner carbon commitments while maintaining existing filling-line compatibility.
Market Restraints
- Specialty resin import dependence:Asia Pacific cosmetic packaging relies on cyclo-olefin polymer and high-clarity PP shipments from Japan and South Korea. Geopolitical friction and freight rate volatility compress margin predictability for mid-tier molders.
- Glass furnace energy intensity:Natural gas and electricity inputs for borosilicate and soda-lime glass production face carbon pricing pressure under China's dual carbon goals. Premium fragrance bottle costs are rising faster than brand pricing power.
- Recycling infrastructure fragmentation:Multi-resin collection systems in Indonesia, Thailand, and Vietnam lack optical sorting capability. Mono-material claims face downstream verification gaps that expose brands to greenwashing liability.
Strategic Opportunities
- Vietnam's emerging contract manufacturing base:European beauty multinationals are qualifying Vietnamese tube extruders and decorators for EU export production. First-mover converters are securing long-term supply agreements with transfer pricing advantages.
- Refill system integration:Aluminum and glass primary containers paired with polypropylene refill pods are capturing share in Japan's department store channels. This model extends customer lifetime value while reducing per-use material intensity.
- China's GB standard harmonization:SAMR's alignment of cosmetic packaging migration limits with EU REACH annexes is simplifying pan-Asian compliance. Suppliers achieving dual certification are capturing multinational contracts that exclude single-market players.
Industry Challenges
- Decorative metallization chemistry transition:Solvent-based vacuum metallization processes face VOC emission controls under China's MEE enforcement. Water-based and physical vapor deposition alternatives require capital retooling that strains mid-cap decorators.
- Legacy injection mold reconfiguration:Converting existing tool steel for mono-material PP and PE streams demands cavity redesign and cooling channel optimization. Lead times for qualified mold refurbishment are extending project timelines.
- Cross-border EPR registration complexity:Extended producer responsibility frameworks in Japan, South Korea, and emerging ASEAN markets require separate legal entity registrations and financial guarantees. Pan-Asian brand owners face administrative burden multiplication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Cosmetic Packaging Market |
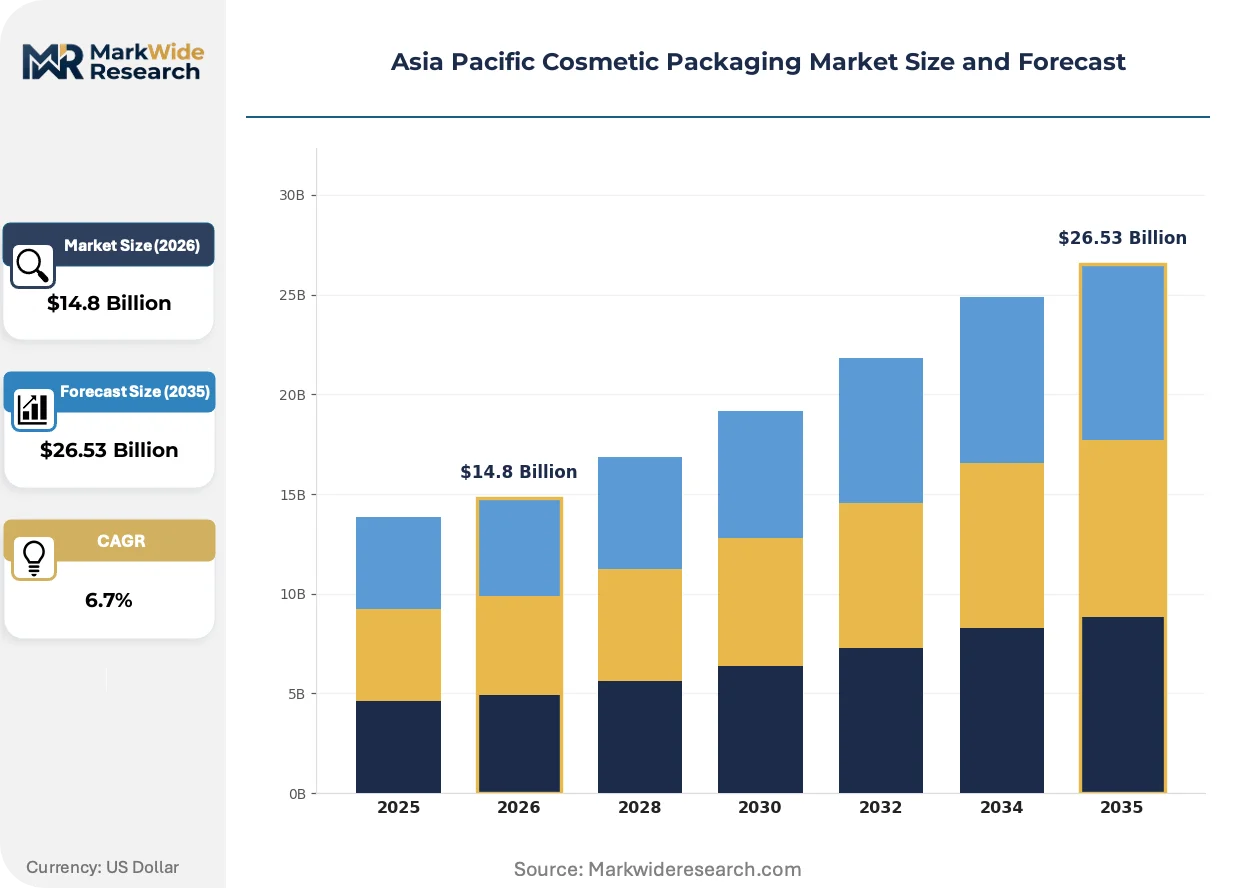
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Tubes, Bottles, Jars, Pumps Material: Plastic, Glass, Metal, Paper Form: Liquid, Solid, Powder, Cream End User: Personal Care, Skincare, Makeup, Fragrance |
| Companies Covered | Amcor Group, Mitsui Chemicals, Inc., Albéa Group, Sumitomo Chemical Co., Ltd., Tosoh Corporation, Berry Global Inc., Zenvista Packagings, Kuraray Co., Ltd., AptarGroup, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Cosmetic Packaging Market Strategic Shifts
Packaging format simplification and substrate transparency are converging to reshape technical specifications across Asia Pacific cosmetic value chains. Regulatory pressure on recyclability claims is accelerating material science investment while digital traceability tools are penetrating quality assurance workflows.
Mono-material polyethylene tubes are displacing laminated aluminum-plastic barrier structures in mass-market skincare applications. Indonesian and Thai brand owners are specifying these formats for body care lines where twelve-month shelf life requirements are less stringent than facial skincare. This displacement is compressing demand for ethylene-vinyl alcohol coextrusion capacity while expanding single-screw extruder utilization.
China's SAMR enforcement of GB standards for cosmetic packaging migration limits is tightening supplier qualification protocols. Testing laboratory backlogs in Shanghai and Guangzhou are extending new product registration timelines by four to six months for imported containers. Premium fragrance houses are responding by pre-qualifying domestic glass suppliers with established GB compliance documentation.
Direct-to-consumer sampling programs are fragmenting order patterns for mini and travel-size formats. K-beauty brands operating through TikTok Shop and domestic e-commerce platforms are specifying 5-15ml tube and jar volumes in batch sizes below traditional MOQ thresholds. Guangdong-based converters with digital printing and agile mold changeover capability are capturing this demand rotation from conventional high-volume suppliers.
Asia Pacific Cosmetic Packaging Market Segmentation
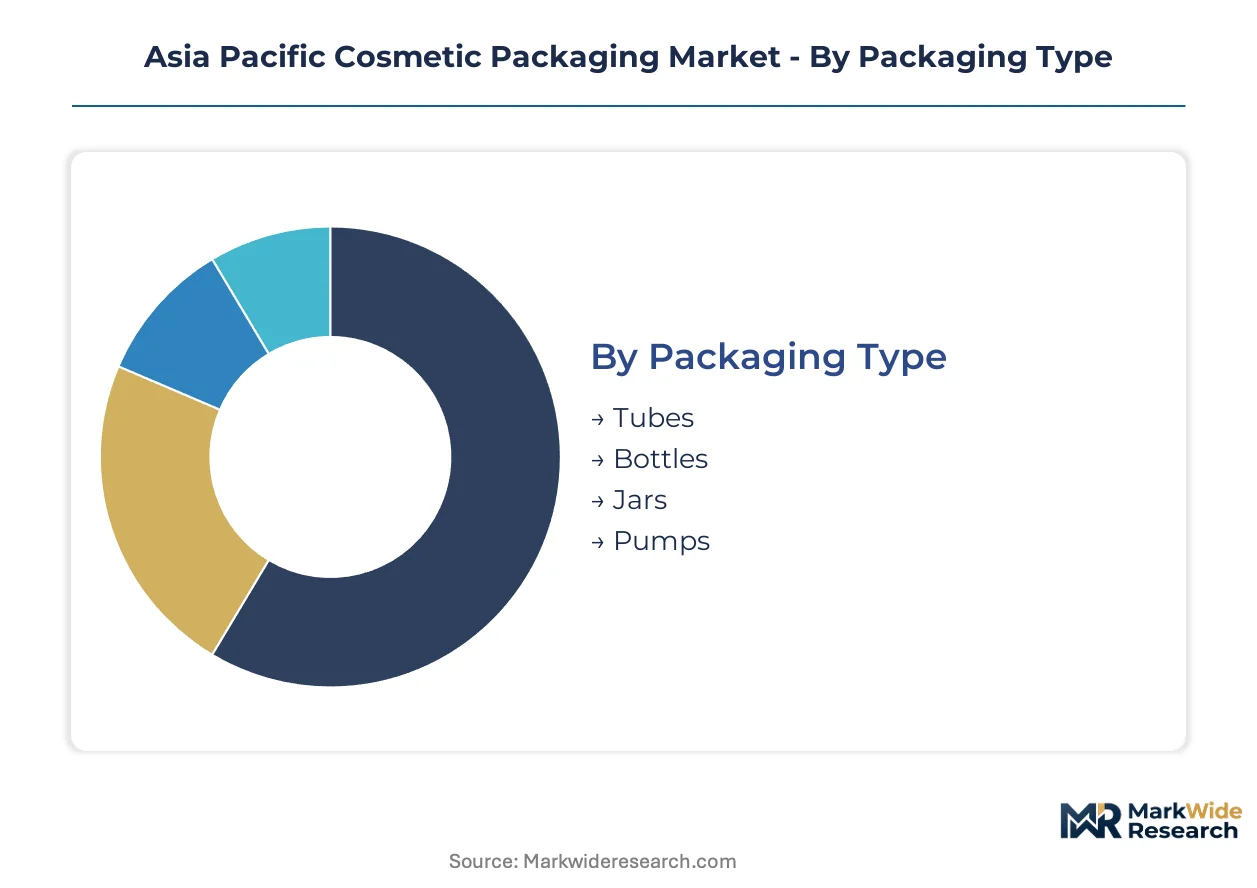
Asia Pacific cosmetic packaging segmentation reveals divergent substitution pressures as mono-material mandates reshape material preferences and airless dispensing technologies displace conventional closures. Understanding these segment dynamics enables suppliers to align capacity investments with regulatory trajectories and brand-owner sustainability commitments.
Packaging Type:
Tubes face intensifying substitution pressure from rigid formats in premium skincare, while pump systems displace traditional caps across facial treatment categories.
- Tubes:Mono-material polyethylene extrusions are displacing laminated aluminum-plastic barriers in mass-market body care. Indonesian and Thai brand owners specify these formats for products with moderate barrier requirements, compressing demand for ethylene-vinyl alcohol coextrusion capacity.
- Pumps:Airless dispensing systems with precision dosing mechanisms anchor premium skincare specifications in South Korea's Seoul-Incheon corridor. K-beauty export momentum accelerates mold investment for these high-value components that extend product shelf life and reduce preservative loads.
- Bottles:Blow-molded PET and HDPE containers dominate hair care and body wash applications across China's coastal manufacturing zones.
- Jars:Wide-mouth configurations in thick-walled PP and glass retain primacy in premium moisturizer and mask segments.
Tubes anchor the volume base while pumps gain share at the steepest rate.
Material:
Plastic formulations concentrate procurement spending, though glass and metal capture disproportionate margin in luxury positioning.
- Plastic:Polyolefin streams—PP, PE, and bio-based polyethylene—dominate technical development pipelines. Mitsui Chemicals and regional compounders commercialize sugarcane-derived formulations that satisfy brand-owner carbon commitments without filling-line reconfiguration.
- Glass:Borosilicate and soda-lime furnace production faces carbon pricing pressure under China's dual carbon goals. Natural gas and electricity inputs are elevating premium fragrance bottle costs faster than brand pricing power permits.
- Metal:Aluminum primary containers paired with polypropylene refill pods capture share in Japan's department store channels, extending customer lifetime value.
- Paper:Molded fiber and laminated board formats penetrate secondary packaging applications where structural protection requirements permit.
Plastic commands the installed capacity base while glass defends the premium tier.
Form:
Liquid formulations drive pump and dispenser attachment rates, whereas solid formats enable simplified barrier specifications.
- Liquid:Serums, essences, and toners require precision dosing systems with migration-tested wetted components. China's SAMR enforces GB standards that extend new product registration timelines for imported containers.
- Cream:Viscous emulsions specify wide-mouth jars and airless pumps with specialized piston designs to maintain evacuation efficiency.
- Solid:Balm and stick formats permit mono-material PP housings with reduced barrier complexity.
- Powder:Pressed and loose formulations demand sifter mechanisms and moisture-resistant closures.
Liquid anchors formulation volume while cream applications expand most quickly in anti-aging segments.
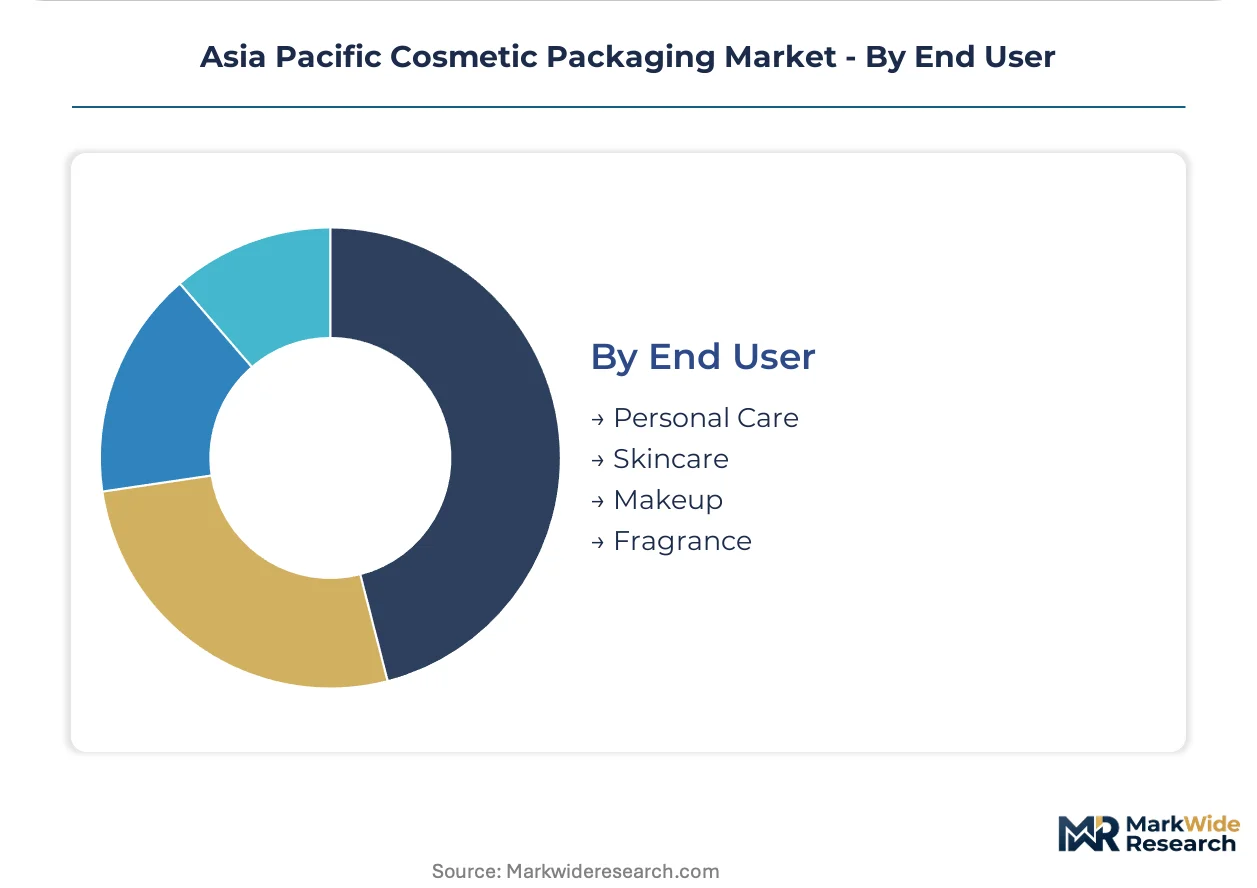
End User:
Skincare commands packaging innovation investment, whereas fragrance maintains glass dependence despite cost pressures.
- Skincare:K-beauty brands operating through TikTok Shop and domestic e-commerce platforms fragment order patterns for 5-15ml mini formats. Guangdong-based converters with digital printing capture this demand rotation from conventional high-volume suppliers.
- Fragrance:Premium houses pre-qualify domestic Chinese glass suppliers with established GB compliance documentation to circumvent testing laboratory backlogs in Shanghai and Guangzhou.
- Personal Care:Body wash, shampoo, and conditioner applications prioritize cost-optimized PET bottles with standard closures.
- Makeup:Color cosmetics specify airless and precision applicator systems for foundation and concealer formats.
Skincare anchors the innovation pipeline while fragrance defends the highest unit-value tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across the Asia Pacific cosmetic packaging landscape. Southeast Asian brand owners prioritize cost-optimized formats, while South Korean and Japanese buyers absorb premiums for precision-engineered dispensing systems.
China
SAMR enforces GB standards for cosmetic packaging migration limits that extend registration timelines for imported containers. Testing laboratory backlogs in Shanghai and Guangzhou compress speed-to-market for multinational beauty brands. Guangdong-based converters with digital printing capability capture fragmented demand for mini formats from TikTok Shop vendors.
South Korea
K-beauty export momentum drives specialized packaging innovation in the Seoul-Incheon corridor. MFDS labeling protocols fragment compliance costs for pan-Asian suppliers serving multiple markets. Airless pump molders concentrate capacity near Incheon port facilities to minimize logistics friction for export-bound production.
Japan
Department store channels specify aluminum primary containers paired with polypropylene refill pods. METI coordinates recyclability protocols that diverge from South Korean and Chinese frameworks. Osaka-based decorators maintain captive relationships with heritage fragrance houses demanding metallized closure expertise.
India
BIS mandates material safety certifications for imported cosmetic containers. Mandatory testing requirements create captive demand for domestic blow-molding capacity. Maharashtra-based converters capture share from Southeast Asian suppliers by offering faster certification turnaround times.
Vietnam
European beauty multinationals qualify Vietnamese tube extruders for EU export production. First-mover converters secure long-term supply agreements with transfer pricing advantages. Ho Chi Minh City industrial zones attract mold investment from regional players seeking labor cost arbitrage.
Asia Pacific Cosmetic Packaging Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in Asia Pacific cosmetic packaging. Multinational film suppliers anchor high-volume contracts through multilayer barrier capabilities, while regional molders compete on agility and localized certification support. Three archetypes dominate: integrated material suppliers with polymer innovation pipelines, full-service converters with decoration integration, and precision dispensing specialists focused on airless technologies. Competitive moves concentrate on capacity expansion in Vietnam and strategic partnerships for bio-based polymer supply.
Among integrated material suppliers, Mitsui Chemicals, Inc. and Sumitomo Chemical Co., Ltd. exemplify the polymer innovation archetype through their captive R&D infrastructure. Albéa Group occupies a position within the full-service converter tier, representing integrated decoration and dispensing expertise across Southeast Asian manufacturing footprints. Amcor Group anchors the multinational film supplier segment, exemplifying scale-driven barrier technology capabilities.
| Leading Market Players |
|---|
| Amcor Group |
| Mitsui Chemicals, Inc. |
| Albéa Group |
| Sumitomo Chemical Co., Ltd. |
| Tosoh Corporation |
| Berry Global Inc. |
| Zenvista Packagings |
| Kuraray Co., Ltd. |
| AptarGroup, Inc. |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Seoul-Incheon airless pump molders and Guangdong digital printing converters creates divergent cost floors that stratify pricing power across the Asia Pacific cosmetic packaging landscape. Scale economies in high-volume mono-material tube extrusion compress unit costs for Indonesian and Thai mass-market suppliers, while precision dosing component specialists capture premium positioning through technical differentiation.
Pricing Analysis
Refill pod and after-market closure revenue streams anchor lifetime value capture for aluminum primary container suppliers serving Japan's department store channels. Three-tier pricing structure across premium, standard, and economy levels separates airless pump assemblies with MFDS certification from basic tube formats and commodity PET bottles. Cost compression in glass fragrance packaging is intensifying because China's dual carbon goals elevate natural gas and electricity inputs faster than brand pricing power permits. Southeast Asian brand owners exhibit highest price sensitivity, while South Korean K-beauty exporters absorb premiums for precision-engineered dispensing systems.
Supply Chain Analysis
Just-in-time resin procurement dominates South Korean and Japanese molders serving export-bound K-beauty production, while Vietnamese tube extruders maintain strategic stockpiles of polyethylene grades to buffer EU qualification timelines. Geographic supply concentration centers on China for blow-molded PET and HDPE containers, South Korea for cyclo-olefin polymer and high-clarity PP, and Japan for specialty barrier resins. Raw material dependencies encompass fossil-based and sugarcane-derived polyethylene streams, borosilicate glass furnace output, and aluminum sheet stock. Single-source vulnerability to Japanese and South Korean specialty resin shipments exposes mid-tier molders to geopolitical friction and freight rate volatility. Distribution runs through Guangdong and Seoul-Incheon manufacturing clusters for domestic Asian consumption, with Ho Chi Minh City industrial zones emerging for EU-bound contract production.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific cosmetic packaging functions as a service-attach opportunity where decoration, certification support, and refill system integration expand faster than primary container hardware sales. Recurring revenue from GB compliance documentation, mold refurbishment, and digital printing setup fees now exceeds unit margin capture in commoditized formats.
For Market Incumbents: Compound defensive positioning by securing captive bio-based polymer supply through Mitsui Chemicals-style R&D partnerships and expanding GB pre-certification services for multinational fragrance houses facing SAMR testing backlogs. Airless pump specialists in the Seoul-Incheon corridor must add mold refurbishment capacity to extend customer lifetime value as mono-material mandates force cavity redesign cycles. Mono-material transition timelines compress margin predictability for converters locked into legacy multilayer film architectures. For New Entrants and Emerging Players: Post-purchase compliance and certification support gaps in India's BIS-mandated testing regime create white-space entry points for Maharashtra-based converters offering faster turnaround than Southeast Asian competitors. Vietnamese tube extruders with EU qualification status represent the most penetrable supply base for European beauty multinationals seeking transfer pricing advantages. First-movers should anchor go-to-market positioning on digital printing agility for TikTok Shop mini-format fragmentation rather than high-volume scale. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision dispensing specialists with airless pump IP and integrated decoration capabilities over commodity blow-molders facing mono-material retooling costs. Long-term viability through the next substrate transition window hinges on polymer innovation pipelines and regulatory certification depth rather than installed extrusion capacity alone. Watch for SAMR-EU REACH harmonization completion as the inflection signal that dual-certified suppliers will capture multinational contract exclusions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Polymer Supply | Mitsui Chemicals' sugarcane-derived PE formulations demonstrate carbon commitment compatibility without filling-line disruption. |
| GB Standard Pre-certification Service Buildout | Domestic Chinese glass suppliers with established SAMR documentation circumvent testing laboratory backlogs in Shanghai and Guangzhou. |
| Digital Printing Capability Expansion | Guangdong-based converters capture TikTok Shop mini-format demand rotation from conventional high-volume suppliers. |
| Vietnam Manufacturing Footprint Establishment | Ho Chi Minh City industrial zones attract mold investment seeking labor cost arbitrage and EU export qualification. |
| Refill System Architecture Development | Aluminum primary containers paired with PP refill pods extend customer lifetime value in Japan's department store channels. |
Study Parameters
Operator-level perspectives from packaging procurement managers at K-beauty brands, blow-molding plant engineers in Maharashtra, and decoration line supervisors in Guangdong anchored the qualitative base for this analysis. Primary interviews with resin compounders, mold refurbishment specialists, and SAMR compliance consultants combined with secondary validation from China customs records, BIS certification databases, and MFDS labeling protocols. Bottom-up capacity assessments at Seoul-Incheon corridor facilities triangulated against top-down demand estimates from skincare brand expansion announcements.
Sensitivity analysis tested forecast robustness across mono-material mandate acceleration scenarios, specialty resin price volatility bands, and carbon pricing implementation timelines. Segmentation dimensions encompassed packaging type, material formulation, product form, and end-use category across the projection horizon. CAGRs derived from installed capacity expansion plans, brand-owner sustainability commitment trajectories, and regulatory enforcement intensity patterns. Forecast inputs incorporated GB standard harmonization progress, extended producer responsibility framework adoption rates, and recycling infrastructure buildout timelines in Indonesia, Thailand, and Vietnam.
Forecasts assume regulatory continuity in China's SAMR enforcement, India's BIS certification expansion, and South Korea's MFDS labeling protocols; material policy shifts would require re-modeling migration limit adjustments or EPR liability reallocations. Specific risks that could revise projections include glass furnace energy cost spikes under accelerated dual carbon goals, geopolitical disruption to Japanese and South Korean specialty resin shipments, and optical sorting infrastructure delays that expose mono-material claims to greenwashing liability. Practitioners should keep alternative scenarios live as ASEAN extended producer responsibility frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
Make-Up Products Packaging Market
Cosmetic Packaging
Cosmetic Spray Bottles Market
Cosmetic Packaging
Beauty Supplements Packaging Market
Cosmetic Packaging
Cream Jars Market
Cosmetic Packaging
Anti-Counterfeit Pharmaceuticals and Cosmetics Packaging Market
Cosmetic Packaging
Crimp Neck Serum Bottles Market
Cosmetic Packaging
Latin America Personal Care Packaging Market
Cosmetic Packaging
Skin Glossing Pencil Packaging Market
Cosmetic Packaging
Single Portion Cosmetic Packaging Market
Cosmetic Packaging
Europe Cosmetic Packaging Market
Cosmetic Packaging
Lip Gloss Tube Market
Cosmetic Packaging
China Personal Care Packaging Market
Cosmetic Packaging
Global Eye Cosmetic Packaging Market
Cosmetic Packaging
North America Cosmetic Packaging Market
Cosmetic Packaging
Anti-Counterfeit Cosmetic Packaging Market
Cosmetic Packaging
Cosmetic Vials Market