
 Marzipan Market | 2026-2036
Marzipan Market Size, Share, and Industry Trends Forecast 2026-2036
Marzipan Market Analysis
Almond paste is rebalancing marzipan economics as confectioners reduce sugar ratios and elevate nut content for premium positioning. Odense Marcipan leverages its Danish heritage to dominate Nordic retail shelves with traditional formulations. Niederegger sustains century-old Lübeck craftsmanship to command price premiums in German-speaking markets. Barry Callebaut AG anchors industrial supply through integrated couverture and nut-paste distribution networks.
Marzipan is a confectionery paste composed primarily of ground almonds, sugar, and glucose syrup, typically containing 25-35% almond content by weight and shaped through cold extrusion or hand-modeling for decorative and edible applications. The confectionery segment leads absolute volume as chocolate-enrobed marzipan bars and figurines sustain year-round manufacturing schedules. Specialty stores capture the highest margin pools in the distribution channel matrix, while ready-to-use paste dominates form-based demand from commercial bakeries seeking operational efficiency.
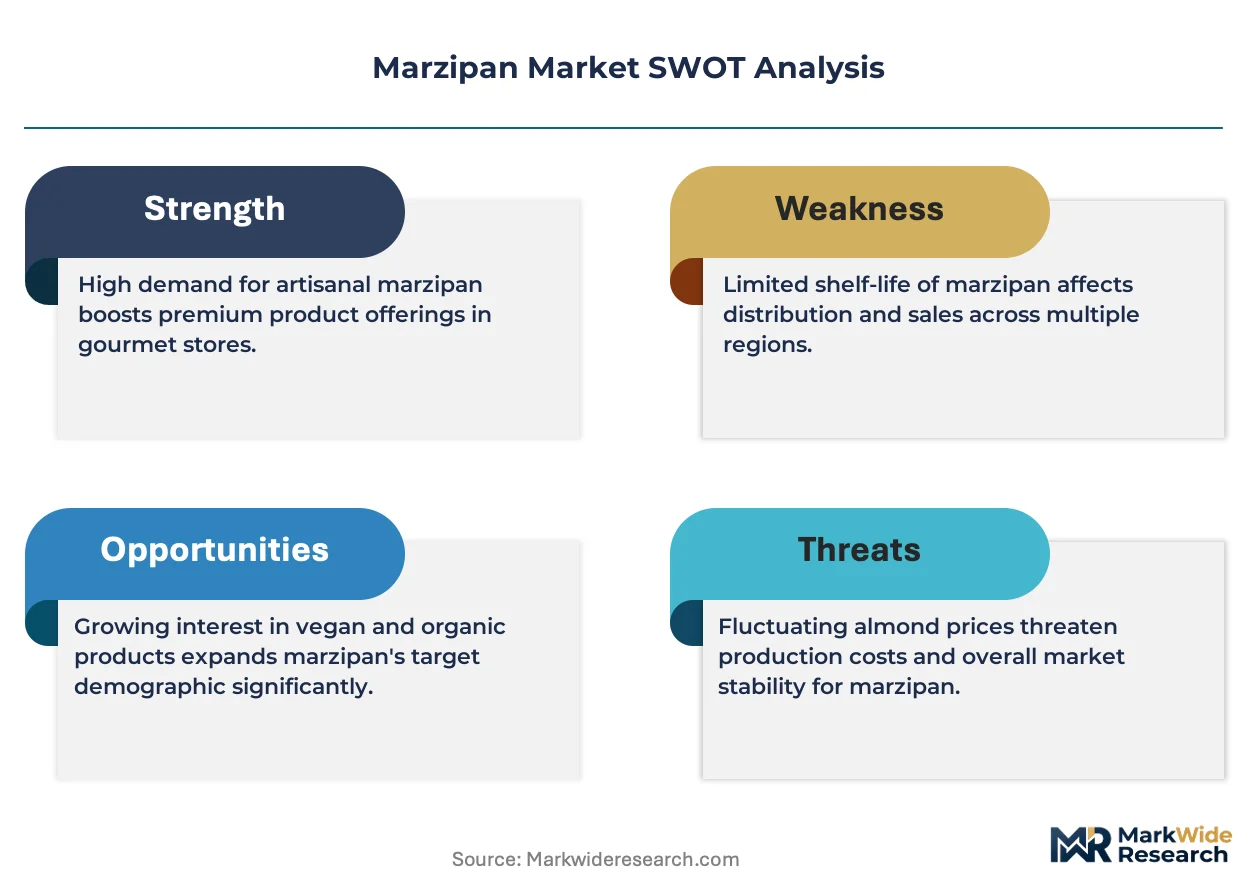
Germany's Lebensmittelrecht, the EU's Food Information to Consumers Regulation, and REACH chemical safety standards collectively govern almond sourcing disclosures, allergen labeling, and processing additive limits across European marzipan production. These frameworks elevate compliance costs for small-batch importers while rewarding established manufacturers with verified supply chains. Stakeholders must monitor almond crop yields in Mediterranean growing regions and assess dual-sourcing strategies before committing to capacity expansion.
Market Dynamics
Germany's tightened Lebensmittelrecht almond-content thresholds are compressing formulation flexibility across European marzipan production, forcing manufacturers to rebalance sugar ratios and elevate nut purity to maintain shelf access.
Growth Catalysts
- Artisan channel expansion:Specialty confectionery retailers in France and Belgium are dedicating expanded seasonal floor space to hand-modeled marzipan figurines, pulling volume from mass-market grocery.
- REACH additive transparency:ECHA-mandated processing chemical disclosures are rewarding established manufacturers with verified supply chains, creating competitive separation from small-batch importers.
- Cold extrusion automation:Precision forming technology is reducing hand-labor dependency in decorative marzipan production, enabling scale without sacrificing dimensional accuracy.
Market Restraints
- Almond price volatility:Mediterranean crop yield fluctuations transmit directly to marzipan input costs, compressing margin stability for producers without multi-year nut supply contracts.
- EU sugar reduction mandates:EFSA-guided reformulation pressures are narrowing the formulation window between compliance and traditional taste profiles.
- Pistachio paste substitution:Premium positioning of alternative nut confections in Middle Eastern and Mediterranean markets is fragmenting traditional marzipan demand pools.
Strategic Opportunities
- Ready-to-use paste channel:Commercial bakeries seeking operational efficiency are driving form-based demand for pre-conditioned almond paste, bypassing in-house grinding.
- EU Green Deal packaging incentives:Biodegradable wrapper mandates are creating first-mover advantage for marzipan producers with compostable film capabilities.
- Chocolate-enrobed premium tier:Couverture integration is electrifying margin expansion in the confectionery segment through year-round manufacturing schedules.
Industry Challenges
- Almond roasting certification timelines:FSSAI-equivalent process validation requirements in target export markets are extending product registration cycles.
- Legacy equipment retrofit costs:Cold extrusion upgrades demand capital deployment that mid-tier producers struggle to finance without strategic partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marzipan Market |
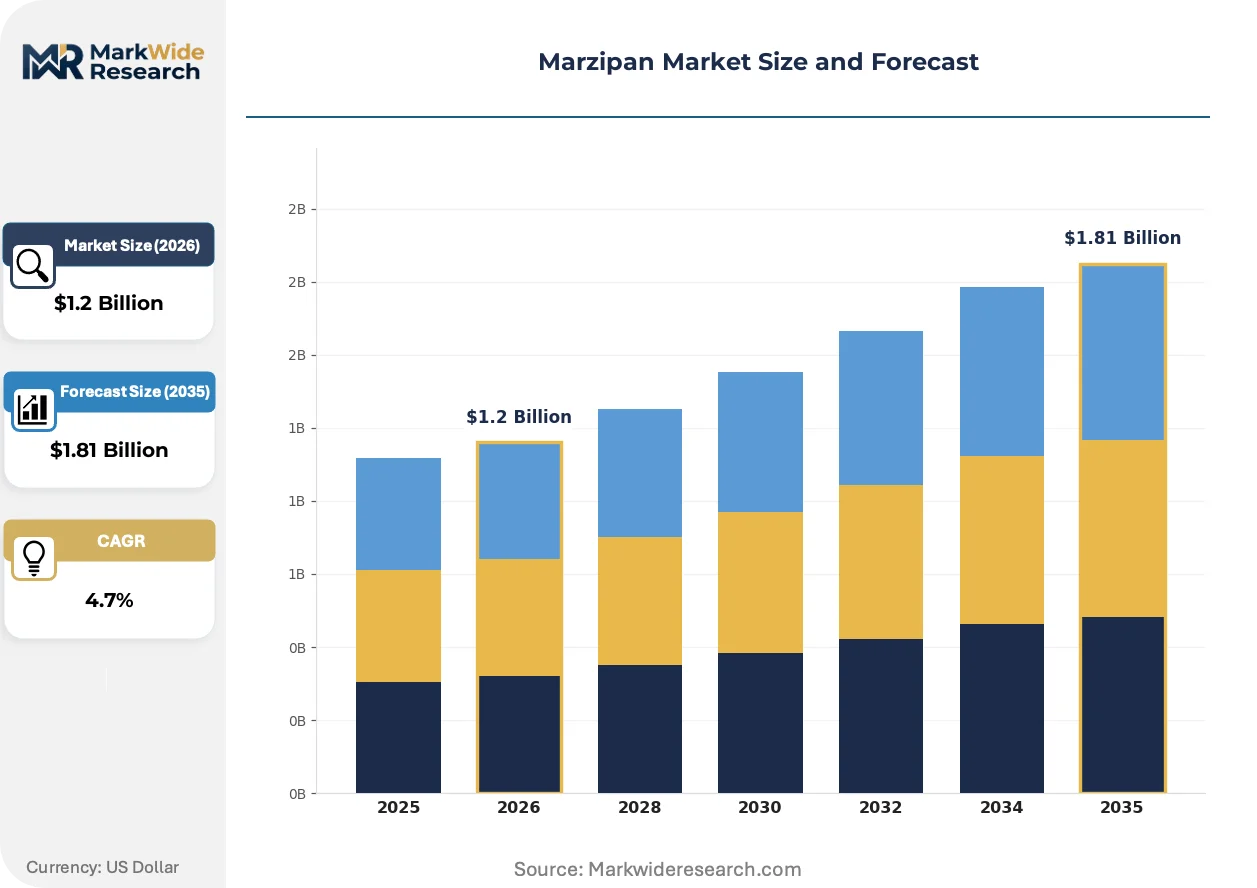
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $1.81 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cakes, Confectionery, Chocolates, Decorations Application: Baking, Artisan Crafting, Festivals, Gifting Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers Form: Ready-to-Use, Powdered, Liquid, Paste |
| Companies Covered | Odense Marcipan, Barry Callebaut AG, Niederegger, Bergen Marzipan, Lubeca, Moll Marzipan, Georg Lemke GmbH & Co. KG, Atlanta Poland SA, Zentis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marzipan Market Emerging Trajectories
Precision forming technology and regulatory transparency mandates are converging to reshape competitive positioning in marzipan manufacturing, with automation and verified supply chains becoming inseparable from market access.
High-pressure cold extrusion systems are electrifying production economics by enabling continuous forming of complex decorative geometries without heat degradation of almond oils. Nordic bakery chains are adopting these systems fastest, replacing batch hand-modeling with throughput-oriented lines that compress unit labor costs while preserving artisan appearance.
REACH chemical safety standards are tightening processing additive limits across European marzipan production, elevating compliance documentation burdens. Small-batch importers face disproportionate cost pressure from ECHA registration requirements, while established manufacturers with in-house laboratory verification capabilities are capturing shelf space in German-speaking markets.
Direct procurement from almond cooperatives is displacing layered distributor relationships in the ingredient channel. Commercial bakeries in Belgium and the Netherlands are negotiating volume contracts with Spanish and Italian growing collectives, bypassing traditional nut brokers and compressing price discovery cycles.
Marzipan Market Segmentation
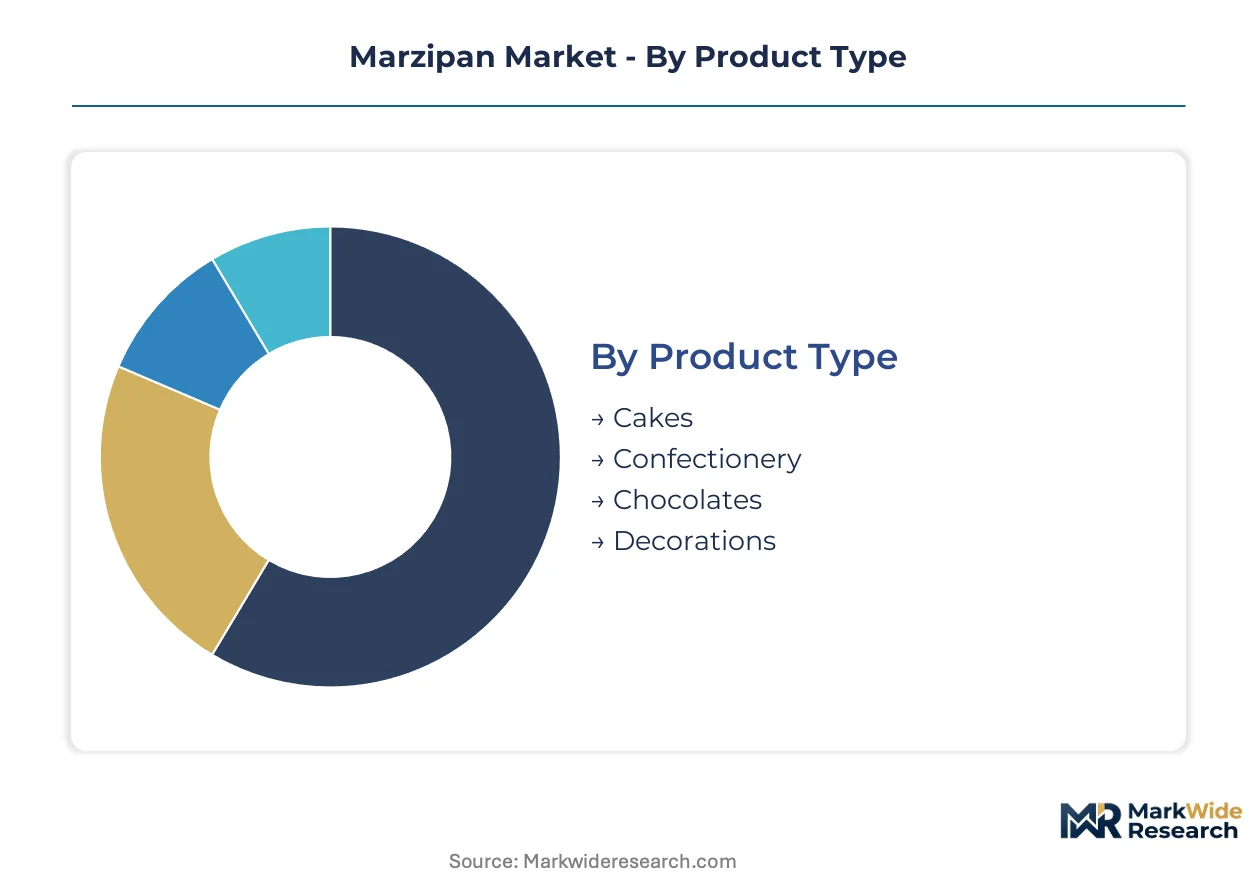
Marzipan segmentation reveals how formulation flexibility and channel economics fragment production strategies across Europe. Manufacturers calibrate almond-sugar ratios and distribution investments differently depending on whether they serve industrial bakeries or artisan confectioners.
Product Type:
Supply concentration in industrial marzipan manufacturing clusters around chocolate-enrobed formats, while decorative specialties remain dispersed across regional ateliers.
- Confectionery:Chocolate-enrobed bars and pralines contain 25-35% almond paste by weight, extruded and enrobed in continuous production lines. German and Belgian industrial producers dominate this segment through integrated couverture supply chains, though tightening Lebensmittelrecht thresholds are forcing almond-content recalibration.
- Decorations:Hand-modeled figurines and seasonal shapes demand higher skill intensity and command price premiums in French and Belgian specialty retail. Cold extrusion automation is now displacing traditional atelier labor in Nordic markets while preserving dimensional precision for complex geometries.
- Cakes:Marzipan layers and coverings for celebration cakes require pliable, rollable consistency with elevated moisture retention. Commercial bakeries in the Netherlands and Denmark source this format in bulk for wedding and birthday portfolios.
- Chocolates:Marzipan-filled chocolate shells and truffles integrate nut paste with cocoa butter matrices. Swiss and German chocolatiers maintain formulation secrecy around roasting profiles and particle size distribution.
Today's leader: Confectionery. Tomorrow's challenger: Decorations.
Application:
Cost tier stratification separates commodity baking inputs from premium positioning in gift and festival contexts.
- Baking:Commercial bakeries in Belgium and the Netherlands drive volume demand for standardized almond paste with predictable rheological properties. Ready-to-use formats eliminate in-house grinding labor and reduce batch-to-batch variation.
- Gifting:Premium boxed assortments command margin premiums in German-speaking markets through heritage branding and limited seasonal releases. Niederegger and Odense Marcipan anchor this tier through authenticated provenance claims.
- Festivals:Easter and Christmas figurines concentrate demand spikes in French specialty stores. Production scheduling challenges favor manufacturers with flexible cold extrusion lines over fixed hand-modeling capacity.
- Artisan Crafting:Independent confectioners in Belgium and France source high-almond-content paste for custom wedding and celebration commissions. Direct procurement from Spanish almond cooperatives is shortening supply chains for this customer type.
Volume concentrates in Baking. Margin concentrates in Gifting.
Distribution Channel:
Customer type fragmentation splits procurement behavior between efficiency-seeking commercial buyers and experience-driven consumers.
- Specialty Stores:Curated assortments and staff expertise sustain price premiums in urban French and Belgian markets. These channels capture the highest margin pools through limited-edition releases and personalized service.
- Supermarkets:Mass-market retail in Germany and Scandinavia demands standardized SKUs with extended shelf stability. Private label penetration pressures branded manufacturers to defend position through heritage marketing.
- Online Retail:Direct-to-consumer platforms enable artisan producers to bypass traditional wholesale markups. Subscription gifting models are gaining traction for seasonal marzipan assortments.
- Wholesalers:Foodservice distributors supply commercial bakeries and restaurant kitchens with industrial-format paste. Consolidated procurement through this channel favors suppliers with verified allergen documentation and REACH compliance.
Margin leadership: Specialty Stores. Volume leadership: Supermarkets.
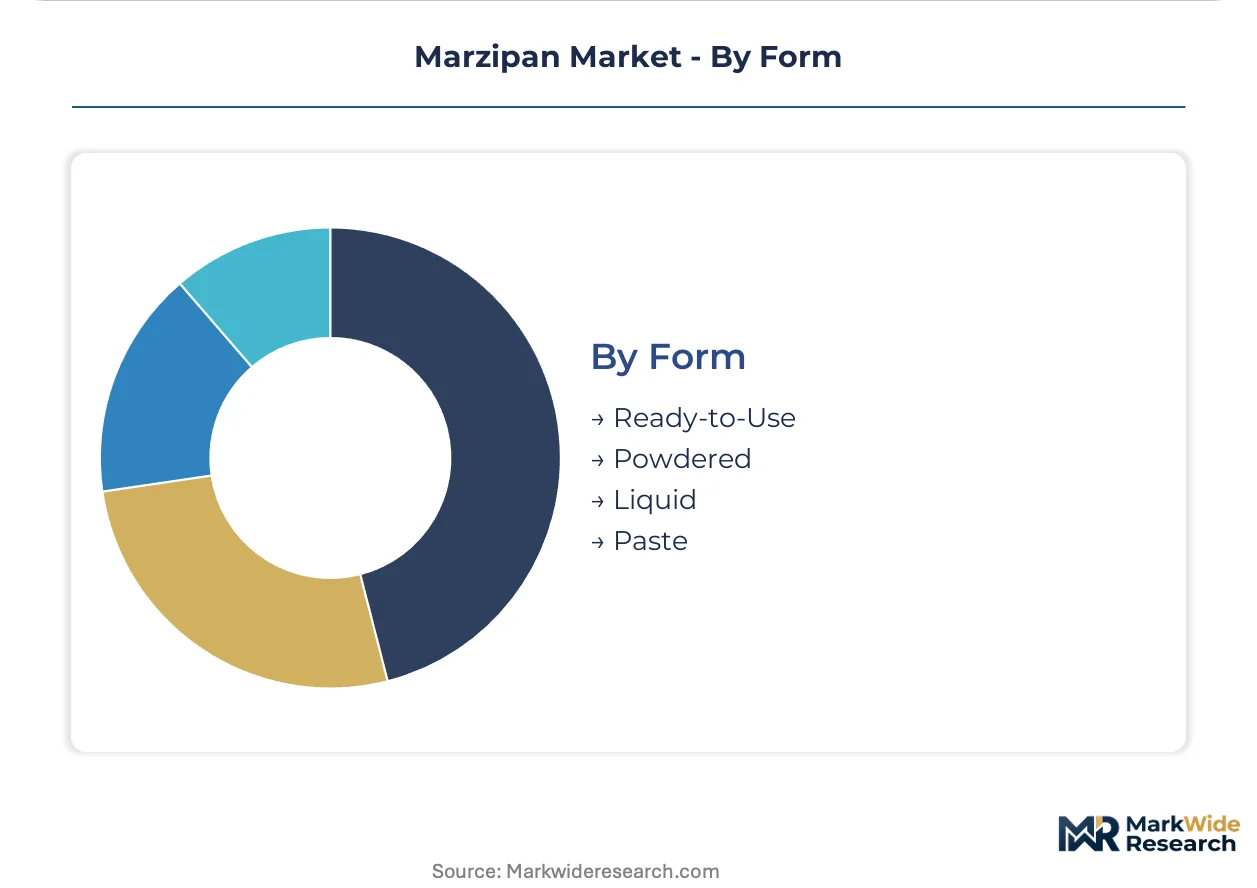
Form:
Maturity gradients separate established paste formats from emerging convenience-oriented alternatives.
- Ready-to-Use:Pre-conditioned almond paste eliminates hydration and tempering steps for commercial bakeries. This format is expanding most quickly in Belgium and the Netherlands as labor costs rise and skill availability tightens.
- Paste:Traditional block format retains dominance in artisan applications requiring manual manipulation. German and Danish manufacturers maintain proprietary grinding and roasting protocols for this specification.
- Powdered:Dehydrated almond flour enables extended shelf life and reduced shipping weights for export markets. Reconstitution quality varies significantly by particle size and oil encapsulation method.
- Liquid:Pumpable marzipan slurries serve industrial enrobing and depositing lines with minimal handling. Adoption remains limited to large-scale confectionery operations with dedicated processing equipment.
Established standard: Paste. Steepest expansion trajectory: Ready-to-Use.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lübeck anchors European marzipan production heritage, with specialized clusters extending through Nordic countries and into Mediterranean almond sourcing zones. Regional differentiation stems from regulatory stringency, craft traditions, and commercial bakery automation adoption rates.
Germany
Lebensmittelrecht amendments tighten almond-content thresholds for confectionery labeling, compressing formulation flexibility for industrial producers. REACH compliance documentation rewards established manufacturers with verified supply chains. Lübeck's centuries-old craft tradition sustains premium positioning through authenticated provenance claims and heritage branding.
France
Specialty retailers in Paris and Lyon dedicate expanded seasonal floor space to hand-modeled figurines, pulling volume from mass-market grocery channels. ANSM food additive oversight aligns with EFSA-guided sugar reduction mandates. Alsace confectioners integrate Germanic craft techniques with French patisserie presentation standards.
Belgium
Commercial bakeries in Brussels and Antwerp drive ready-to-use paste demand for operational efficiency in celebration cake portfolios. EU Food Information to Consumers Regulation governs allergen labeling precision for chocolate-enrobed formats. Flanders maintains concentrated industrial capacity serving both domestic and export confectionery channels.
Netherlands
Wedding and birthday cake marzipan coverings sustain bulk procurement from Rotterdam-area distributors. EU Green Deal packaging incentives accelerate biodegradable wrapper adoption among mid-tier producers. Amsterdam specialty stores capture premium margins through curated assortments and personalized service models.
Denmark
Nordic bakery chains adopt cold extrusion automation fastest, replacing batch hand-modeling with throughput-oriented production lines. Danish heritage positioning dominates retail shelf access across Scandinavian markets. Copenhagen-based procurement teams negotiate direct contracts with Spanish almond cooperatives, shortening supply chains.
Marzipan Market Vendor Landscape
Global majors compete with regional champions across heritage branding and industrial scale dimensions. Market structure tiers between century-old craft houses and integrated couverture distributors, with mid-tier producers facing consolidation pressure from compliance cost escalation. Three archetypes dominate: authenticated heritage specialists, industrial ingredient suppliers, and private-label enablers. Capacity expansion and strategic partnerships represent the primary competitive vectors as automation investments separate scalable players from craft-limited ateliers.
Within the heritage specialist tier, Odense Marcipan and Niederegger exemplify provenance-based positioning, each leveraging geographic origin claims to sustain price premiums in gift-oriented channels. Barry Callebaut AG occupies a distinct position as an integrated industrial supplier, anchoring confectionery segment volume through combined couverture and nut-paste distribution networks. These three entities represent the competitive spectrum from craft authenticity to manufacturing scale.
| Leading Market Players |
|---|
| Odense Marcipan |
| Barry Callebaut AG |
| Niederegger |
| Bergen Marzipan |
| Lubeca |
| Moll Marzipan |
| Georg Lemke GmbH & Co. KG |
| Atlanta Poland SA |
| Zentis |
| Others |
Supply Flow & Price Mechanics
Captive almond sourcing from Spanish and Italian cooperatives anchors supply positioning for European marzipan manufacturers while insulating premium tiers from commodity price swings. This backward integration into Mediterranean growing regions simultaneously secures Lebensmittelrecht-compliant nut purity and sustains price premiums in German-speaking gift channels.
Pricing Analysis
Almond cost pass-through dominates marzipan pricing mechanics, with Mediterranean crop yield fluctuations transmitting directly to input costs and compressing margin stability for producers lacking multi-year supply contracts. Three-tier pricing structure across premium, standard, and economy levels separates heritage-branded Lübeck producers from private-label supermarket tiers and industrial bakery inputs. Pricing pressure stems from EU sugar reduction mandates narrowing formulation flexibility between compliance and traditional taste profiles. Commercial bakeries in Belgium and the Netherlands exhibit highest price sensitivity due to volume procurement and operational cost scrutiny, while French specialty retailers absorb premiums for authenticated provenance claims.
Supply Chain Analysis
Reverse-logistics flows for seasonal marzipan returns concentrate in post-Christmas and post-Easter periods, with unsold figurines and gift assortments feeding discount channels or reprocessing streams for industrial paste applications. Supply concentrates in Spain, Italy, and Germany, with almond cultivation anchoring Mediterranean input zones and Lübeck-area manufacturers commanding finished goods distribution. Raw material dependencies center on sweet almond varieties, glucose syrup, and couverture chocolate for enrobed formats. Single-source vulnerability in Spanish almond cooperatives elevates risk exposure for manufacturers without Italian dual-sourcing arrangements. Distribution runs through specialty retail in France and Belgium, mass-market grocery in Germany and Scandinavia, and foodservice wholesalers supplying commercial bakeries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The marzipan market operates as a regulatory compounder where Germany's tightened Lebensmittelrecht thresholds and REACH additive transparency mandates continuously elevate compliance barriers that favor established manufacturers with verified supply chains and in-house laboratory capabilities.
For Market Incumbents: Deploy cold extrusion automation to compress unit labor costs while preserving artisan dimensional precision for decorative figurines. Defensive priorities center on securing multi-year almond supply contracts with Spanish and Italian cooperatives before crop yield volatility intensifies, and accelerating REACH compliance documentation to widen competitive separation from small-batch importers facing disproportionate ECHA registration burdens. For New Entrants and Emerging Players: Artisan confectioners in Belgium and France seeking direct procurement relationships represent the most penetrable buyer archetype, bypassing traditional nut brokers through cooperative volume contracts. White-space targets include ready-to-use paste formats for Netherlands commercial bakeries prioritizing operational efficiency, and biodegradable wrapper capabilities for EU Green Deal early-mover positioning. Go-to-market execution should anchor in provenance storytelling authenticated by geographic origin claims. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier marzipan manufacturers with cold extrusion automation and verified supply chains because compliance cost escalation is consolidating fragmented craft ateliers unable to finance legacy equipment retrofits. Long-term viability across the analysis window favors targets with REACH-compliant laboratory capabilities and direct almond cooperative relationships. Monitor almond crop yield reports from Mediterranean growing regions as the primary inflection indicator for input cost trajectories and margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Almond Cooperatives | Direct Spanish and Italian sourcing secures Lebensmittelrecht-compliant nut purity while compressing price discovery cycles. |
| Cold Extrusion Automation Deployment | Precision forming technology reduces hand-labor dependency in Nordic bakery chains without sacrificing dimensional accuracy. |
| REACH Compliance Certification Investment | ECHA-mandated additive documentation creates competitive separation from small-batch importers in German-speaking markets. |
| Biodegradable Packaging Transition | EU Green Deal wrapper incentives reward first-mover compostable film capabilities among mid-tier producers. |
| Ready-to-Use Paste Format Expansion | Pre-conditioned almond paste eliminates grinding labor for Belgium and Netherlands commercial bakeries seeking operational efficiency. |
Methodological Framework
Bottom-up commercial bakery and specialty retail modeling reconciled against top-down almond supply and couverture distribution tracking forms the analytical core of this study. Primary interviews with confectionery production managers, procurement leads at bakery chains, specialty store buyers, almond cooperative representatives, and ECHA compliance officers combined with secondary validation from EU Food Information to Consumers Regulation filings, REACH registration databases, Mediterranean agricultural yield reports, and customs trade records. Triangulation across these sources ensures segmentation integrity across product type, application, and distribution channel dimensions.
Input-output matrices mapping almond paste volumes to finished confectionery, decoration, cake, and chocolate applications drive the forecast framework across the projection horizon. Segmentation dimensions modeled include product format, end-use application, channel type, and geographic production cluster. CAGRs derive from trend extrapolation of bakery SKU expansion rates, seasonal demand patterns, and regulatory compliance cost trajectories. Industry-specific forecast inputs incorporate Lebensmittelrecht amendment implementation timelines and cold extrusion automation adoption curves in Nordic markets.
Underlying measurement precision varies by segment; confectionery and baking applications carry tighter precision than artisan crafting due to consolidated reporting from industrial producers. Forecasts reflect assumptions around almond crop yield stability, EU sugar reduction mandate enforcement intensity, and REACH compliance documentation standardization. Practitioners should monitor EFSA guidance updates, Mediterranean climate patterns, and biodegradable packaging cost curves for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Vegan Baking Mix Market
Bakery Products
Ezekiel Bread Market
Bakery Products
United States Bread Market
Bakery Products
Low Calorie Flour Market
Bakery Products
Personalized Bakery Products Market
Bakery Products
Wedding Cakes Market
Bakery Products
Waffle Market
Bakery Products
Global Wafer Biscuits Market
Bakery Products
Low Fat Chocolate Cake Market
Bakery Products
Global Cake Mix Market
Bakery Products
Pancakes Market
Bakery Products
Oman Frozen Bakery Products Market
Bakery Products
Low Fat Oatmeal Cookies Market
Bakery Products
Bread Market
Bakery Products
Pastries Market
Bakery Products
Malted Rye Flour Market