
 Specialty Beer Market | 2026-2036
Specialty Beer Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Beer Market Analytics
Buyer concentration among on-premise hospitality groups is repositioning procurement power toward chain operators that negotiate exclusive tap handles and seasonal rotations. Anheuser-Busch InBev leverages its distributor network to secure shelf space for specialty lagers in mainstream retail. Sierra Nevada Brewing Co. anchors its competitiveness through vertical control over hop sourcing from its North Carolina and California estates. BrewDog competes via direct-to-consumer subscription models that bypass traditional three-tier distribution.
Specialty beer denotes brewed beverages produced in limited quantities with distinctive ingredients, elevated original gravity, or non-standard fermentation protocols such as barrel-aging, wild yeast inoculation, or adjunct infusion beyond traditional malt, hops, water, and yeast. These products serve commercial purposes ranging from premium on-premise margin enhancement to brand differentiation in saturated off-premise retail. Craft Beer commands the largest volume share within product type segmentation, though Sour and Fruity flavor profiles attract the fastest-growing consumer cohort among experimental drinkers. E-commerce as a sales channel has matured beyond pandemic-era peaks into sustained direct-to-consumer infrastructure, while Keg and Cask packaging retains disproportionate margin concentration in draft-focused European markets.
FDA labeling requirements and TTB formula approvals govern ingredient disclosure and market access for U.S. specialty brewers, while EU REACH and F-Gas Regulation constrain refrigerant choices and packaging material chemistry across European production facilities. Germany's BfR and France's DGCCRF enforce additive limits that shape formulation decisions for export-bound producers. Stakeholders must monitor evolving deposit-return schemes and extended producer responsibility frameworks that threaten to raise per-unit packaging costs faster than premium pricing power can absorb.
Market Dynamics
Buyer concentration among on-premise hospitality chains is consolidating procurement leverage, while EU Green Deal mandates on refrigeration and malt sourcing force capital reallocation across production facilities.
Growth Catalysts
- EU F-Gas Regulation:Mandatory phase-down of hydrofluorocarbon refrigerants accelerates brewery investment in CO₂-based cooling systems and heat recovery infrastructure.
- Draft program expansion:North American hospitality chains are extending dedicated specialty tap walls, creating guaranteed volume commitments for limited-batch producers.
- Wild yeast propagation:Advances in controlled Brettanomyces and Lactobacillus cultivation enable consistent sour beer production at commercial scale.
Market Restraints
- Barrel supply concentration:American white oak cooperage capacity concentrates in Kentucky and Missouri, creating allocation bottlenecks for aged beer programs.
- TTB formula approval timelines:Experimental adjunct submissions face extended review periods, delaying seasonal release schedules.
- Hop contract volatility:Forward purchasing agreements for proprietary varieties lock working capital while spot market Citra and Mosaic prices fluctuate.
Strategic Opportunities
- Direct-to-consumer infrastructure:Subscription clubs and brewery-owned e-commerce platforms bypass three-tier distribution markups in permissive jurisdictions.
- India specialty segment:Urban metro markets show nascent demand for imported craft and experimental styles as licensing liberalizes.
- EU Green Deal carbon accounting:Lower-carbon malt sourcing certifications command premium positioning in German and Dutch retail.
Industry Challenges
- Master brewer talent scarcity:Wild fermentation and blending expertise resides in a limited practitioner pool concentrated in Belgium and Northern California.
- Extended aging inventory carrying costs:Barrel-aged programs tie up capital for months or years before revenue realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Beer Market |
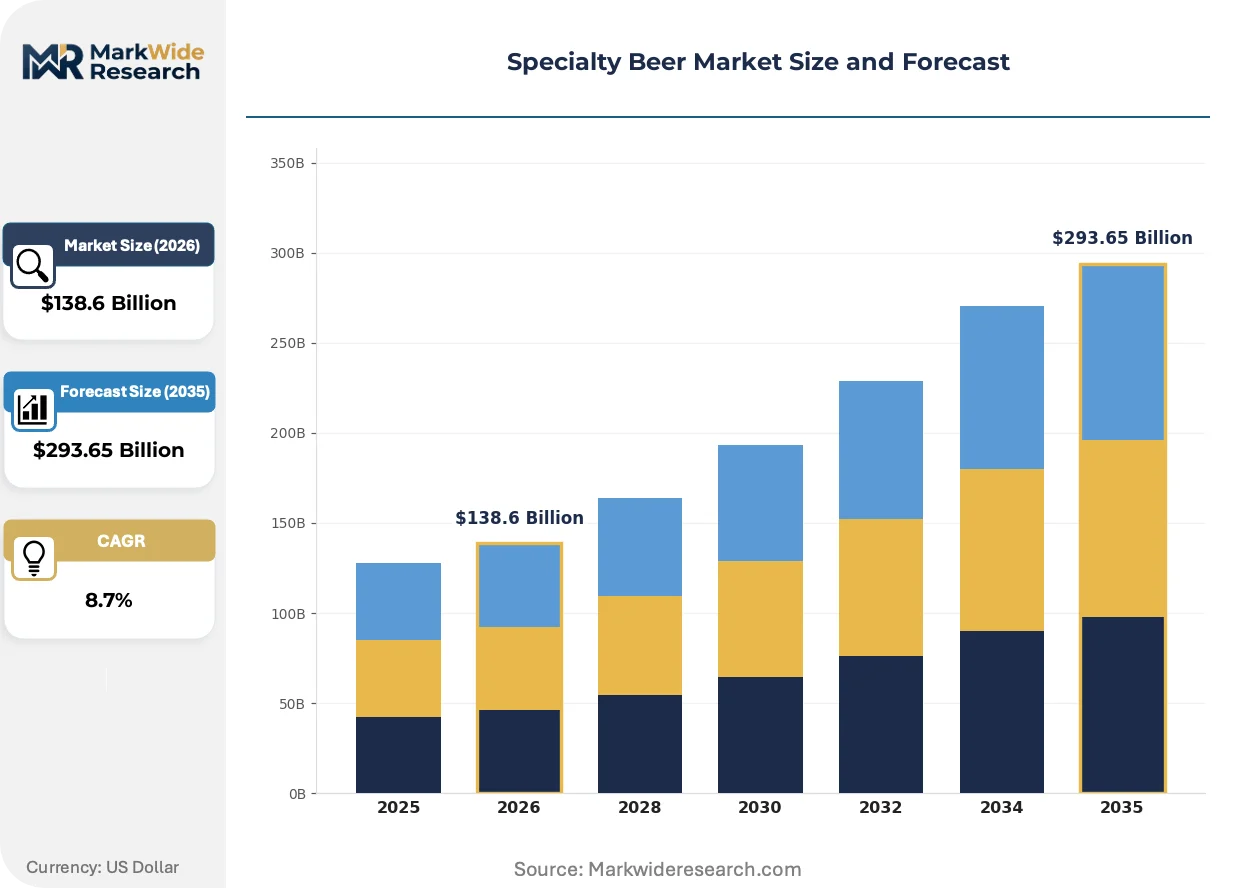
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $293.65 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Craft Beer, Microbrew, Seasonal Beer, Specialty Lager Flavor Profile: Bitter, Fruity, Spicy, Sour Packaging Type: Bottle, Can, Keg, Cask Sales Channel: On-Premise, Off-Premise, E-commerce, Retail |
| Companies Covered | Anheuser-Busch InBev, Heineken N.V., Carlsberg Group, Molson Coors Beverage Company, Boston Beer Company, Sierra Nevada Brewing Co., BrewDog, Constellation Brands, Duvel Moortgat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Beer Market Evolving Landscape
Active fermentation monitoring and alternative grain programs are compressing production cycles while expanding ingredient palettes beyond traditional barley dominance.
Precision fermentation analytics is converging with quality control protocols. Sensor arrays tracking dissolved oxygen, pH, and gravity in real time enable proactive intervention. Mid-size breweries in Denmark and the Netherlands deploy these systems to reduce batch inconsistency. The technology is converging with traditional cellar practices to shorten conditioning periods without sacrificing flavor development.
EU REACH restrictions on packaging material chemistry are forcing adhesive and ink reformulations. Brewers exporting to France and Germany must validate label substrates against BfR and DGCCRF additive limits. Smaller producers without in-house compliance teams face outsourcing costs or market exclusion.
On-premise buyers are consolidating supplier relationships around chain-wide seasonal rotation agreements. Independent draft accounts lose negotiating leverage as hospitality groups centralize procurement. This pattern concentrates most visibly in British pubcos and American casual dining operators seeking menu differentiation through exclusive tap handles.
Specialty Beer Market Segmentation
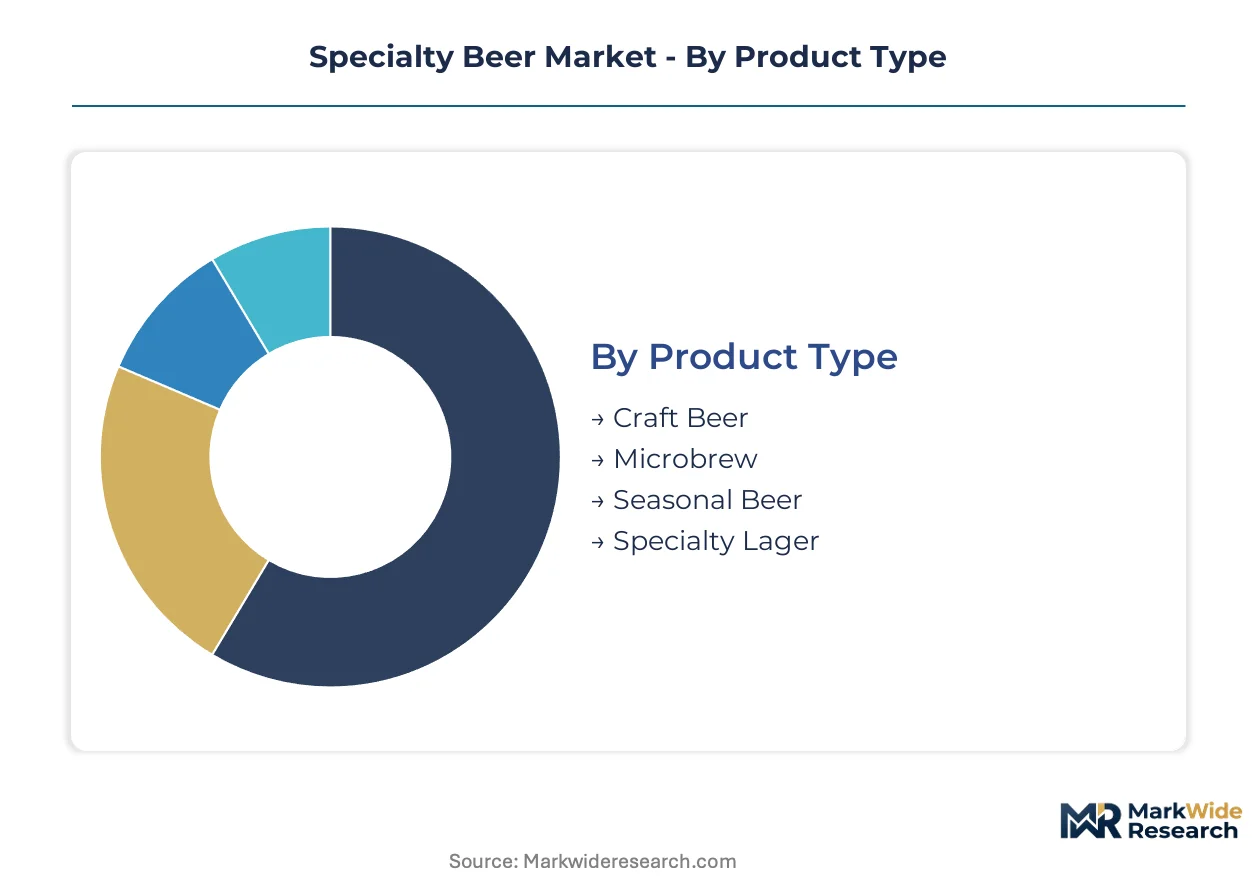
Specialty beer segmentation reveals how regulatory compliance burdens, packaging economics, and channel access requirements vary dramatically across product configurations. Understanding these fault lines enables producers to prioritize capital allocation toward segments with aligned margin structures and permissible distribution pathways.
Product Type:
FDA formula approvals govern adjunct-heavy formulations, while TTB certification timelines stretch longest for experimental yeast strains and non-traditional fermentable substrates.
- Craft Beer:Traditional ale and lager families brewed at scales below six million barrels annually, subject to standard TTB label approval cycles. Demand concentrates in independent draft accounts across Colorado, Oregon, and Vermont where state franchise laws protect tap handle access. Capital intensity rises with in-house canning line investments.
- Microbrew:Ultra-small batch production below fifteen thousand barrels, often distributed exclusively through tasting rooms and local wholesale. German Reinheitsgebot adherence simplifies EU export compliance but constrains formulation flexibility for fruit and spice adjuncts.
- Seasonal Beer:Time-limited releases tied to harvest calendars or holiday consumption windows. Compressed production schedules strain yeast propagation capacity and cold storage availability.
- Specialty Lager:Extended lagering periods and decoction mashing techniques demand dedicated tank farm capacity. Anheuser-Busch InBev's distributor network dominates shelf placement for this category in mainstream retail.
Leading the category by volume: Craft Beer. Growing fastest: Specialty Lager.
Flavor Profile:
Cost tiers stratify sharply across flavor categories, with ingredient sourcing complexity and aging infrastructure requirements driving margin dispersion.
- Bitter:Hop-forward profiles relying on proprietary varieties like Citra and Mosaic. Forward contracting locks working capital eighteen to thirty-six months ahead of harvest. Sierra Nevada Brewing Co. maintains captive supply from its North Carolina and California estates.
- Fruity:Adjunct infusion and hop varieties expressing tropical ester profiles. TTB formula approval timelines extend for non-traditional fruit purees and concentrates.
- Spicy:Phenolic yeast strains and botanical additions including coriander, orange peel, and pepper variants. Belgian brewing traditions supply technical expertise concentrated in Flanders and Wallonia.
- Sour:Controlled Brettanomyces and Lactobacillus fermentation with barrel-aging programs. American white oak cooperage capacity concentrates in Kentucky and Missouri, creating allocation bottlenecks.
Bitter profiles command the highest per-barrel ingredient costs. Sour production is expanding most quickly among experimental drinker cohorts.
Packaging Type:
EU REACH restrictions on adhesive and ink chemistry force reformulation costs that fall disproportionately on smaller producers lacking in-house compliance teams.
- Bottle:Amber and clear glass formats with crown cork or swing-top closures. Deposit-return schemes in Germany and the Netherlands raise per-unit logistics costs but sustain circular economy positioning.
- Can:Aluminum formats with BPA-NI liner requirements under EFSA guidance. Mobile canning services reduce capital barriers for microbrew entrants.
- Keg:Stainless steel returnable vessels for on-premise draft service. Hospitality chain consolidation concentrates procurement leverage around keg pool management and tap handle exclusivity.
- Cask:Unfiltered, unpasteurized real ale served via hand pump. British pubcos retain disproportionate volume concentration despite overall category decline.
Keg packaging dominates on-premise revenue capture. Can formats are climbing the fastest as off-premise retail and direct-to-consumer shipping expand.
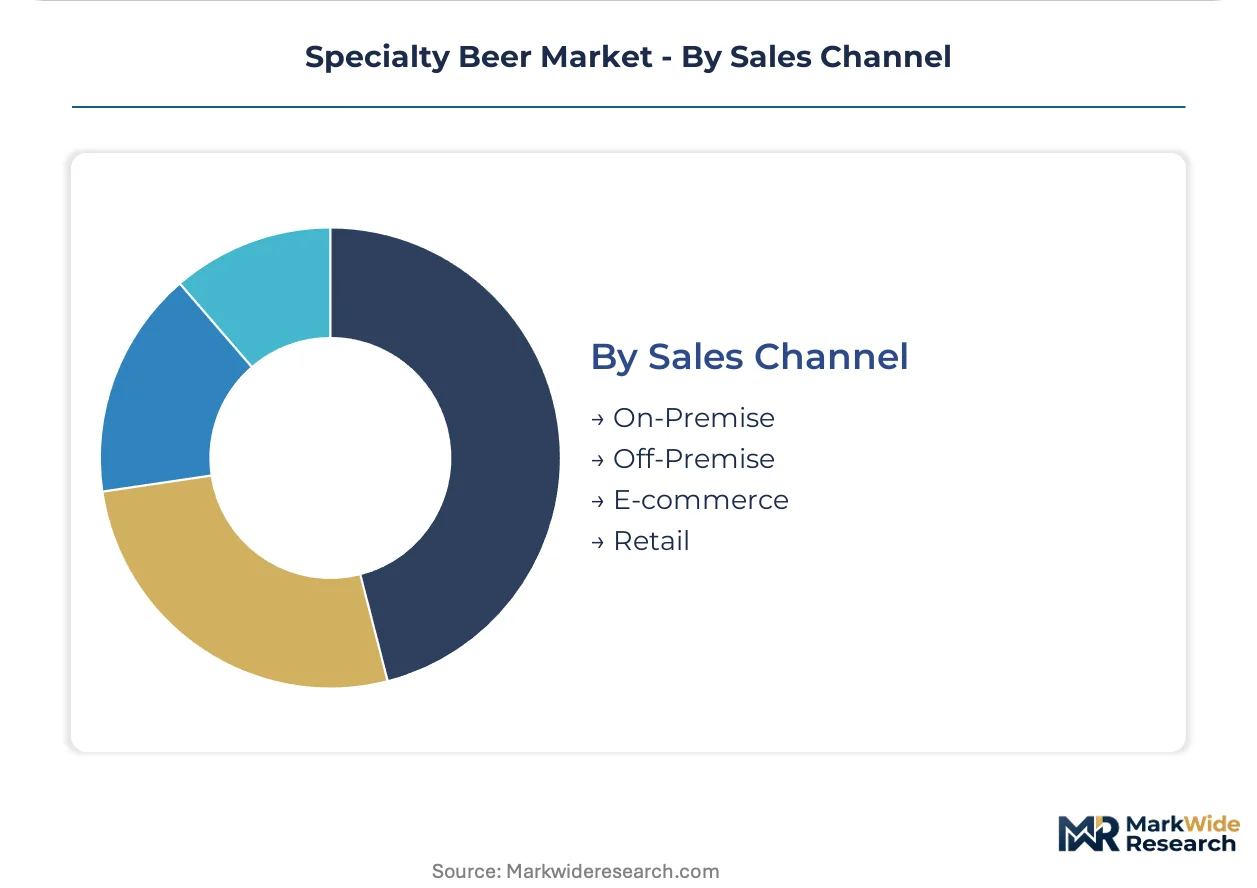
Sales Channel:
Channel access determines margin retention, with three-tier distribution markups consuming thirty to fifty percent of wholesale price in controlled jurisdictions.
- On-Premise:Draft service at bars, restaurants, and tasting rooms. Chain operators centralize procurement around seasonal rotation agreements, squeezing independent draft accounts.
- Off-Premise:Package sales through liquor stores and grocery chains. Shelf placement competition intensifies in states with relaxed franchise laws.
- E-commerce:Direct-to-consumer platforms and third-party delivery aggregators. BrewDog's subscription model bypasses traditional distribution in permissive jurisdictions.
- Retail:Big-box and convenience store formats with limited SKU depth. Specialty lager placement requires distributor leverage or promotional spending.
On-premise channels retain the steepest margin concentration. E-commerce infrastructure is gaining share fastest as fulfillment logistics mature beyond pandemic-era peaks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German malt fields and Czech Saaz hop gardens anchor continental supply chains, while American two-row barley belts in North Dakota and Idaho feed transatlantic specialty lager programs. Demand clusters concentrate where brewing heritage intersects with craft experimentation.
United States
Independent draft accounts in Colorado, Oregon, and Vermont drive volume, protected by state franchise laws that secure tap handle access for regional producers. TTB formula approval timelines constrain experimental adjunct submissions, particularly for seasonal releases. The Pacific Northwest maintains hop breeding concentration, with Yakima Valley estates supplying proprietary varieties to craft breweries.
Germany
Berlin and Munich host the densest craft experimentation clusters within Reinheitsgebot heritage frameworks. The BfR enforces additive limits that shape export-bound formulation decisions, particularly for fruit and spice adjuncts. Bavarian decoction mashing traditions sustain specialty lager infrastructure, while North Rhine-Westphalia develops alternative grain programs.
Belgium
Flanders and Wallonia supply concentrated wild fermentation expertise, with Brettanomyces and Lactobacillus cultivation centers serving European sour beer programs. REACH restrictions on packaging chemistry force adhesive and ink reformulations for export producers. Brussels anchors blending tradition, while rural Flanders maintains farmhouse ale heritage.
United Kingdom
British pubcos centralize procurement around chain-wide seasonal rotation agreements, squeezing independent draft accounts. Cask real ale retains disproportionate volume concentration despite overall category decline, concentrated in Midlands and North England estates. London hosts direct-to-consumer subscription infrastructure that bypasses traditional distribution tiers.
Netherlands
Randstad breweries deploy precision fermentation analytics to reduce batch inconsistency, converging sensor arrays with traditional cellar practices. EU F-Gas Regulation mandates accelerate CO₂-based cooling system adoption across production facilities. Amsterdam and Rotterdam anchor e-commerce fulfillment infrastructure for direct-to-consumer expansion.
Specialty Beer Market Competitive Landscape
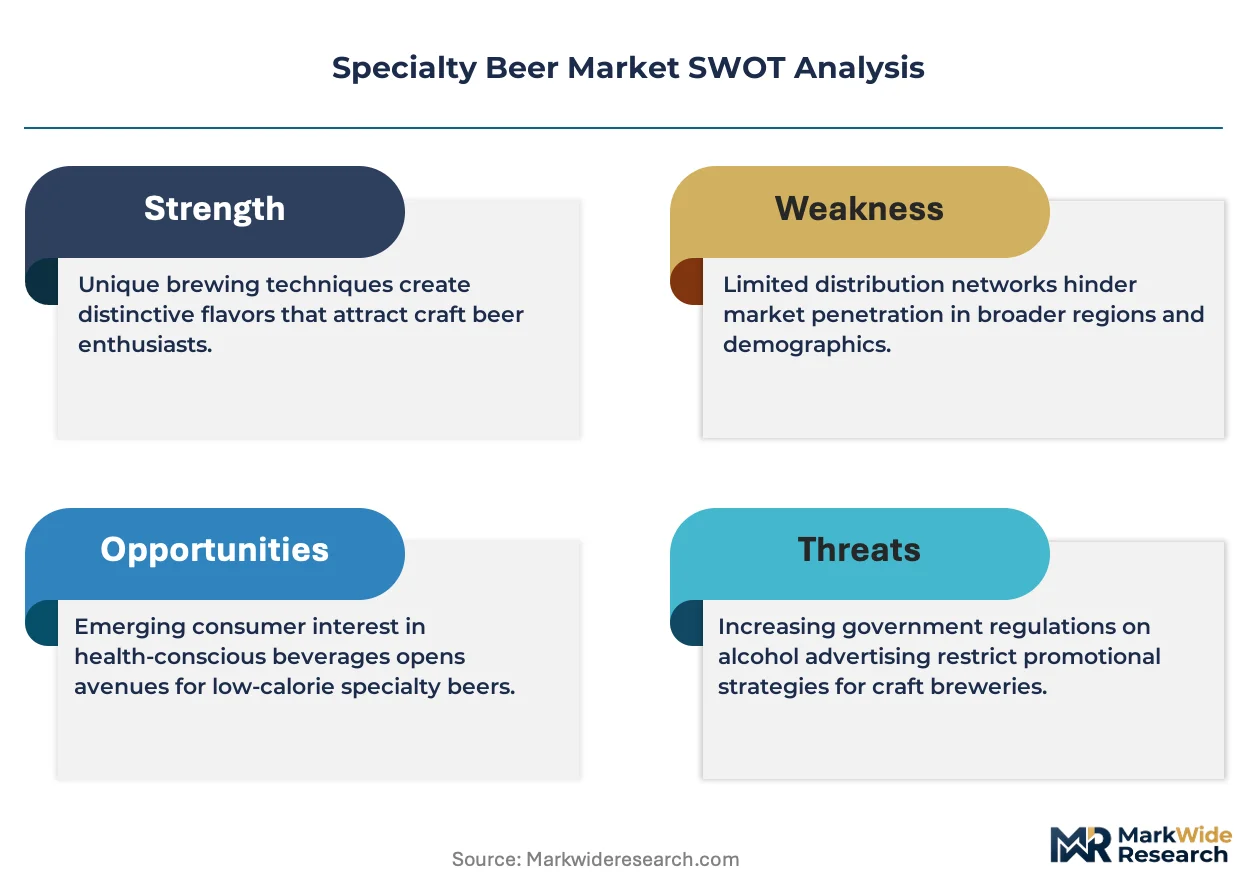
Established producers occupy the standard tier; emerging entrants pursue experimental flavor profiles and alternative distribution pathways. The vendor base stratifies across three tiers: multinational beverage conglomerates with distributor network leverage, mid-size regional craft operators with vertical hop control, and micro-scale specialists with direct-to-consumer subscription models. Consolidation pressure concentrates among hospitality procurement chains, while fragmentation persists in experimental flavor niches. Dominant competitive moves include exclusive tap handle negotiations with on-premise chains and backward integration into hop estate ownership.
Within the multinational tier, Anheuser-Busch InBev and Heineken N.V. represent scale-driven archetypes with distributor network dominance. Sierra Nevada Brewing Co. exemplifies mid-size regional positioning through estate-based supply control. BrewDog occupies the direct-to-consumer disruption vector with subscription infrastructure that bypasses three-tier markups.
| Leading Market Players |
|---|
| Anheuser-Busch InBev |
| Heineken N.V. |
| Carlsberg Group |
| Molson Coors Beverage Company |
| Boston Beer Company |
| Sierra Nevada Brewing Co. |
| BrewDog |
| Constellation Brands |
| Duvel Moortgat |
| Others |
Value Network & Pricing Analysis
EU F-Gas Regulation mandates on hydrofluorocarbon refrigerant phase-downs gate qualified supply access for premium-tier specialty beer producers, as compliance investments in CO₂-based cooling systems and heat recovery infrastructure separate certified sustainable operations from conventional competitors and justify carbon-accounting premiums in German and Dutch retail channels.
Pricing Analysis
Volume concentration in standard craft ale and lager families splits from margin capture in barrel-aged sour programs and direct-to-consumer subscription models. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade—organic malt sourcing and lower-carbon production protocols command shelf price premiums—while cost compression in economy craft tiers intensifies because hospitality chain consolidation centralizes procurement leverage. Independent draft accounts exhibit highest price sensitivity; estate-based hop control insulates mid-size regional operators.
Supply Chain Analysis
Regional distribution centers in Belgium, Germany, and the United States anchor hub-and-spoke patterns for specialty beer logistics, with American white oak cooperage capacity in Kentucky and Missouri creating allocation bottlenecks for aged programs. Raw material dependencies center on Yakima Valley hop estates, Bavarian malt fields, and Czech Saaz cultivation. Single-source vulnerability concentrates in proprietary hop variety contracts. Distribution runs through distributor networks in controlled jurisdictions and direct-to-consumer platforms in permissive markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty beer competition has become a vertical-integration race, with upstream control over hop estate ownership and downstream direct-to-consumer infrastructure emerging as the decisive margin levers separating sustainable operators from margin-squeezed followers.
For Market Incumbents: Anticipate hospitality chain procurement consolidation by securing exclusive tap handle negotiations and backward integration into North Carolina or California hop estates. Investment in CO₂-based cooling systems addresses EU F-Gas compliance before enforcement tightens. Certification in lower-carbon malt sourcing protects premium positioning against private-label encroachment. For New Entrants and Emerging Players: Precision fermentation analytics offers a technology-first wedge into mid-size brewery quality control contracts, particularly in Denmark and the Netherlands where sensor array deployment lags demand. White-space concentration sits in Indian urban metro markets as licensing liberalizes. Direct-to-consumer subscription infrastructure bypasses three-tier markups in UK and US permissive jurisdictions. For Investors and Strategic Acquirers: Extended TTB formula approval timelines for experimental adjunct submissions is the leading indicator that regulatory compliance capabilities will differentiate acquisition targets. Long-term viability across the analysis window favors operators with captive supply chains and diversified channel access beyond distributor dependence. Watch for consolidation signals in mobile canning services and regional keg pool management.| Strategic Initiative | Industry Significance |
|---|---|
| Hop Estate Acquisition | Captive supply of proprietary varieties like Citra and Mosaic insulates against spot market volatility. |
| Direct-to-Consumer Platform Launch | BrewDog's subscription model demonstrates margin retention potential beyond three-tier distribution. |
| CO₂-Based Cooling Retrofit | EU F-Gas Regulation compliance secures German and Dutch retail access against non-certified competitors. |
| Barrel-Aging Program Expansion | American white oak allocation in Kentucky and Missouri creates scarcity-driven premium tier positioning. |
| Precision Fermentation Analytics Deployment | Sensor arrays tracking dissolved oxygen and pH reduce batch inconsistency for mid-size Denmark and Netherlands breweries. |
Research Methodology
Multi-period observation of TTB formula approval timelines, EU F-Gas implementation schedules, and hospitality chain procurement consolidation anchored the trend analysis, supplemented by interviews with master brewers, distributor network managers, on-premise procurement directors, and regulatory compliance officers. Secondary validation drew from FDA labeling guidance documents, EU REACH substance restrictions, BfR additive limit databases, and customs trade data. Bottom-up volume estimates triangulated against top-down category spending assessments.
Segment-weighting across product type, flavor profile, packaging format, and sales channel dimensions calibrated value distribution throughout the forecast period. CAGRs derived from historical trajectory analysis and regulatory inflection point modeling. Industry-specific inputs included hop contract forward pricing patterns, barrel cooperage capacity utilization, and deposit-return scheme adoption curves across European markets.
Several conditions sit outside the modeled scope, including macroeconomic recession impacts on discretionary premium beverage spending, abrupt TTB regulatory reinterpretations, and trade policy disruptions affecting malt or hop imports. Forecasts reflect documented assumptions around licensing liberalization timelines and carbon accounting certification adoption. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Wine Filtering Machine Market
Alcoholic Beverages
Beer Fermenter Market
Alcoholic Beverages
RTD Cocktail Shots Market
Alcoholic Beverages
Malt Beverages Market
Alcoholic Beverages
Ethyl Alcohol (Ethanol) Market
Alcoholic Beverages
Oak Barrel Alternatives Market
Alcoholic Beverages
Global Red Wine Market
Alcoholic Beverages
Alcohol Enzymes Market
Alcoholic Beverages
Global Liquor Confectionery Market
Alcoholic Beverages
Airport Duty-Free Liquor Market
Alcoholic Beverages
UAE Alcohol E-Commerce Market
Alcoholic Beverages
Home Beer Brewing Machine Market
Alcoholic Beverages
Fermented Beverages Market
Alcoholic Beverages
Canada Wine Coolers Market
Alcoholic Beverages
Hard Tea Market
Alcoholic Beverages
Tea Beer Market