
 Vermouth Market | 2026-2036
Vermouth Market Size, Share, and Industry Trends Forecast 2026-2036
Vermouth Market Intelligence
The shift away from bulk-sourced botanicals toward unique, locally grown herbs is consolidating the premium end of the market. This trend allows smaller producers to compete on quality rather than volume. Davide Campari-Milano S.p.A. leverages its extensive brand portfolio to capture diverse consumer preferences. Meanwhile, Distillerie Dolin S.A.S. specializes in its protected French alpine identity, and Bacardi Limited dominates global distribution channels.
Vermouth is an aromatized fortified wine, flavored with a proprietary blend of botanicals, classically including wormwood (Artemisia). Its alcohol content is typically fortified to between 14.5% and 22% ABV, serving primarily as an aperitif or a critical component in cocktails. While sweet vermouth variants command the largest volume share, demand for dry vermouth is accelerating, driven by its use in classic cocktails. The on-premise channels, including bars and restaurants, represent the fastest-growing segment for serving method, outpacing retail store sales.
Market access and product definition are governed by strict geographical and compositional rules. The European Union's PGI for Vermouth di Torino and the U.S. TTB's labeling requirements for formula and alcohol content set key standards for producers. Producers must now decide whether to protect traditional recipes or innovate with novel botanicals and aging processes to attract new consumer demographics.
Market Dynamics
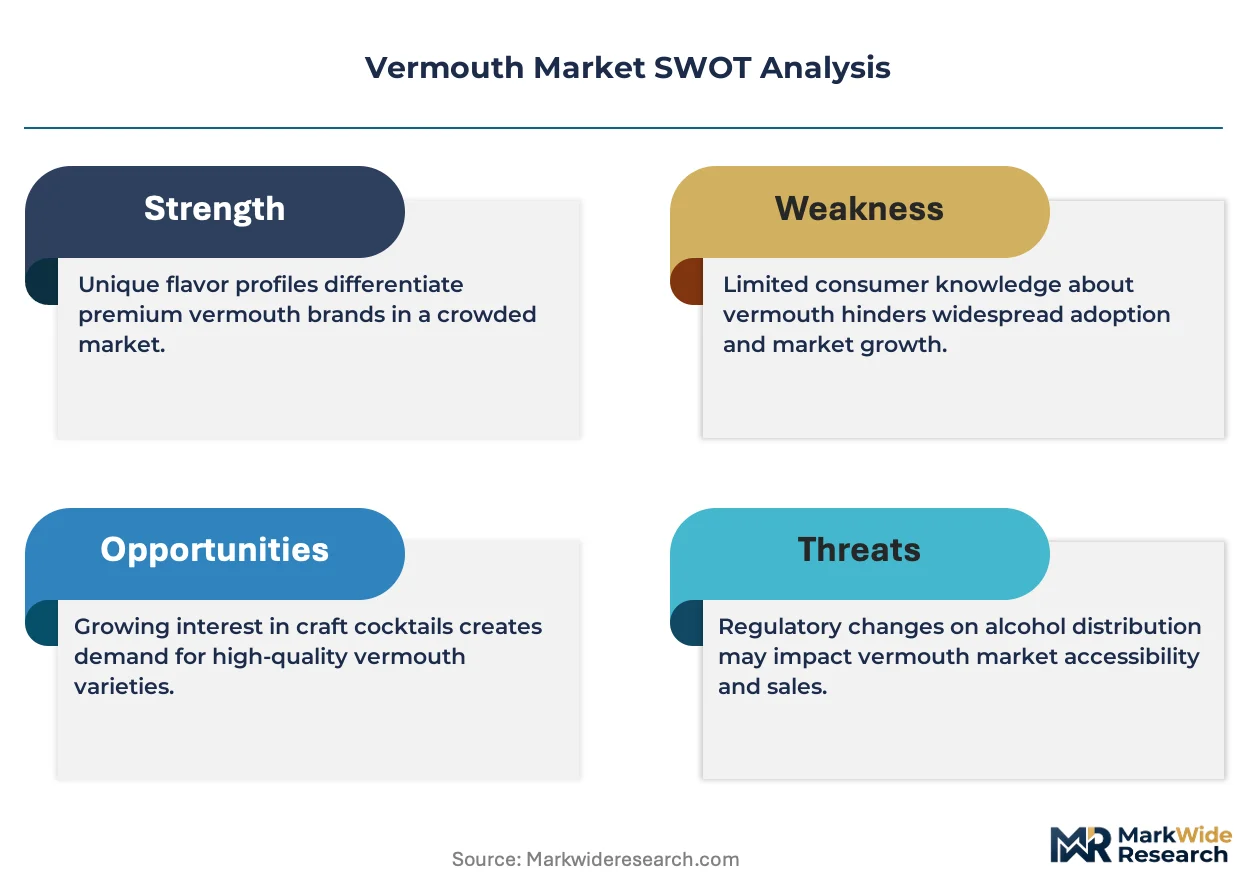
The vermouth market's central tension lies between producers adhering to protected recipes and innovators using novel botanicals. This dynamic shapes strategies for capturing new consumer segments, balancing tradition against the demand for new flavor experiences.
Growth Catalysts
- Premium Cocktail Culture:The expansion of craft cocktail scenes in metropolitan hubs, particularly in the United States and United Kingdom, drives demand for high-quality, artisanal vermouths as essential ingredients.
- Protected Geographical Indications:European Union regulations, such as the PGI for Vermouth di Torino, enforce quality and authenticity standards, building consumer trust and justifying premium price points for certified products.
- Local Botanical Sourcing:A shift toward using unique, locally grown herbs allows smaller, craft producers to differentiate on flavor profile and terroir, competing on quality rather than sheer production volume.
Market Restraints
- Botanical Supply Constraints:Dependence on specific, sometimes scarce, botanicals like wormwood (Artemisia) creates vulnerability to agricultural volatility, impacting cost and production consistency for all producers.
- Strict Regulatory Definitions:Compositional standards set by bodies like the U.S. TTB, which mandate specific alcohol content and formulation disclosures, can stifle experimentation with non-traditional ingredients or production methods.
- Competition from Aperitifs:A broad and expanding category of aperitifs, including other fortified wines and bitter liqueurs, presents a significant substitution threat, competing for the same pre-dinner consumption occasion.
Strategic Opportunities
- Non-Alcoholic Variants:Developing sophisticated, botanically complex non-alcoholic or low-ABV versions of vermouth addresses demand from health-conscious consumers and expands usage occasions beyond traditional cocktails.
- Emerging Market Penetration:Targeting the nascent but growing cocktail cultures in major Asia-Pacific cities offers significant white-space growth, particularly for brands with strong educational marketing programs.
- Direct-to-Consumer Channels:Building direct-to-consumer e-commerce platforms allows producers to bypass traditional distribution, control brand messaging, and capture higher margins on specialty or limited-edition releases.
Industry Challenges
- Navigating Global Regulations:Producers face complexity in aligning a single product with disparate international rules, such as the EU's PGI system versus the U.S. TTB's specific formula and labeling requirements.
- Supply Chain Transparency:Ensuring the authenticity and quality of unique botanicals sourced from numerous small growers presents a significant logistical and verification challenge for brands building a premium identity.
- Consumer Education Gap:A persistent lack of consumer awareness regarding vermouth's diversity and production methods hinders broader adoption and appreciation outside of dedicated cocktail enthusiasts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vermouth Market |
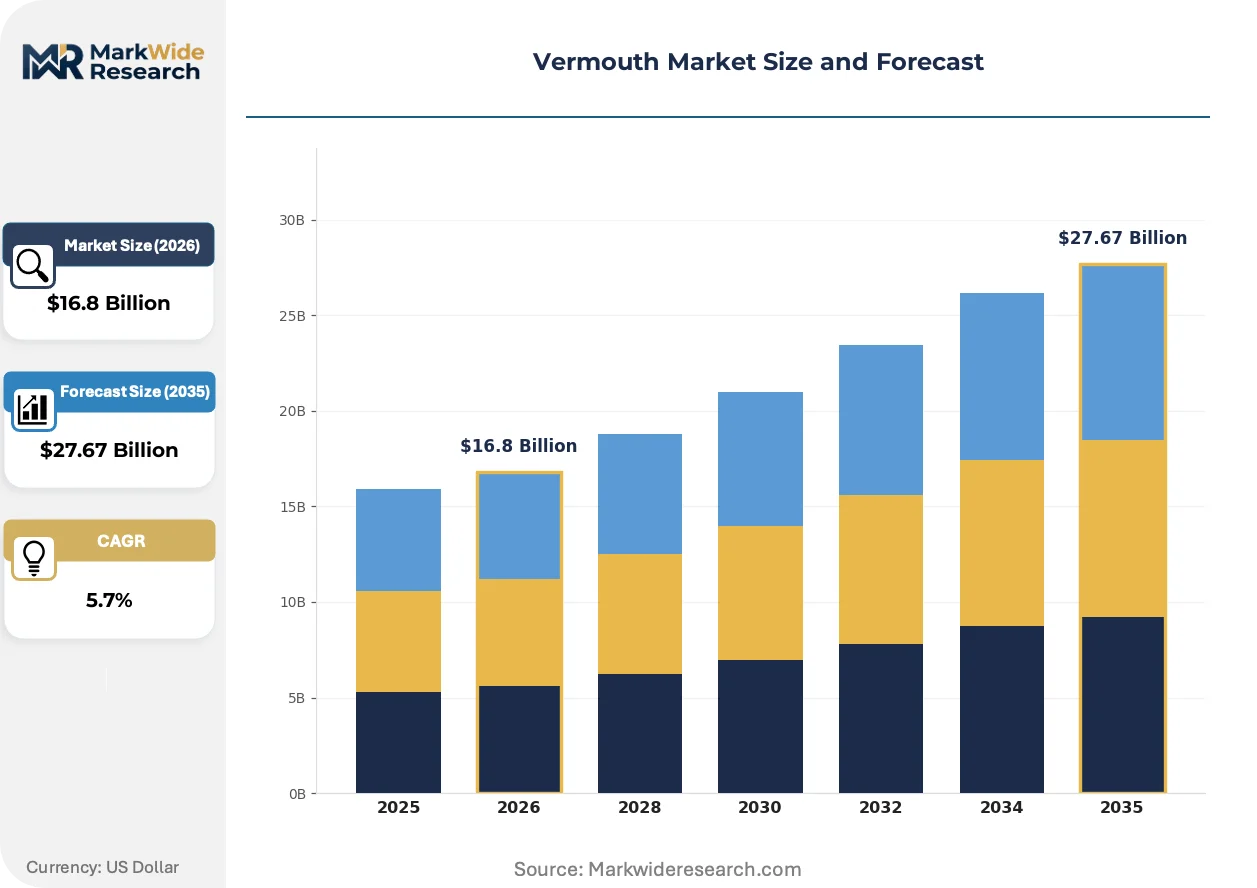
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $27.67 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweet, Dry, White, Red Serving Method: On the Rocks, Neat, Mixed, Cocktail Distribution Channel: Retail Stores, Online, Bars, Restaurants Alcohol Content: Low, Medium, High, Fortified |
| Companies Covered | Gruppo Montenegro S.p.A., Giulio Cocchi S.p.A., Bacardi Limited, Stock Spirits Group plc, Gancia S.p.A., Davide Campari-Milano S.p.A., Distillerie Dolin S.A.S., Lucas Bols N.V., Pernod Ricard S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vermouth Market Strategic Shifts & Innovations
The market is evolving from its role as a classic cocktail modifier into a standalone category driven by botanical exploration and terroir. This transformation is redefining product value, moving it from a commodity ingredient to a craft-centric beverage.
Small-scale production methods that emphasize hyper-local botanicals are gaining traction. Premium on-premise channels and discerning home mixologists are rapidly adopting these terroir-driven products. This focus on unique, regional herb blends is decentralizing flavor profiles away from historically dominant Italian and French styles, creating new expressions of vermouth.
European Union regulations on Protected Geographical Indication (PGI) are formalizing the link between vermouth and its origin. This policy provides a legal framework for products like Vermouth di Torino, mandating specific ingredients and production processes. Producers outside these zones are consequently affected, needing to innovate on brand and formulation to differentiate themselves.
A behavioral shift toward on-premise discovery is altering distribution priorities. Consumers are increasingly selecting vermouths in bars and restaurants, diminishing the influence of traditional retail shelf placement. This trend is most visible in mature cocktail markets like the United States, where bartender recommendations directly shape brand perception.
Vermouth Market Segmentation
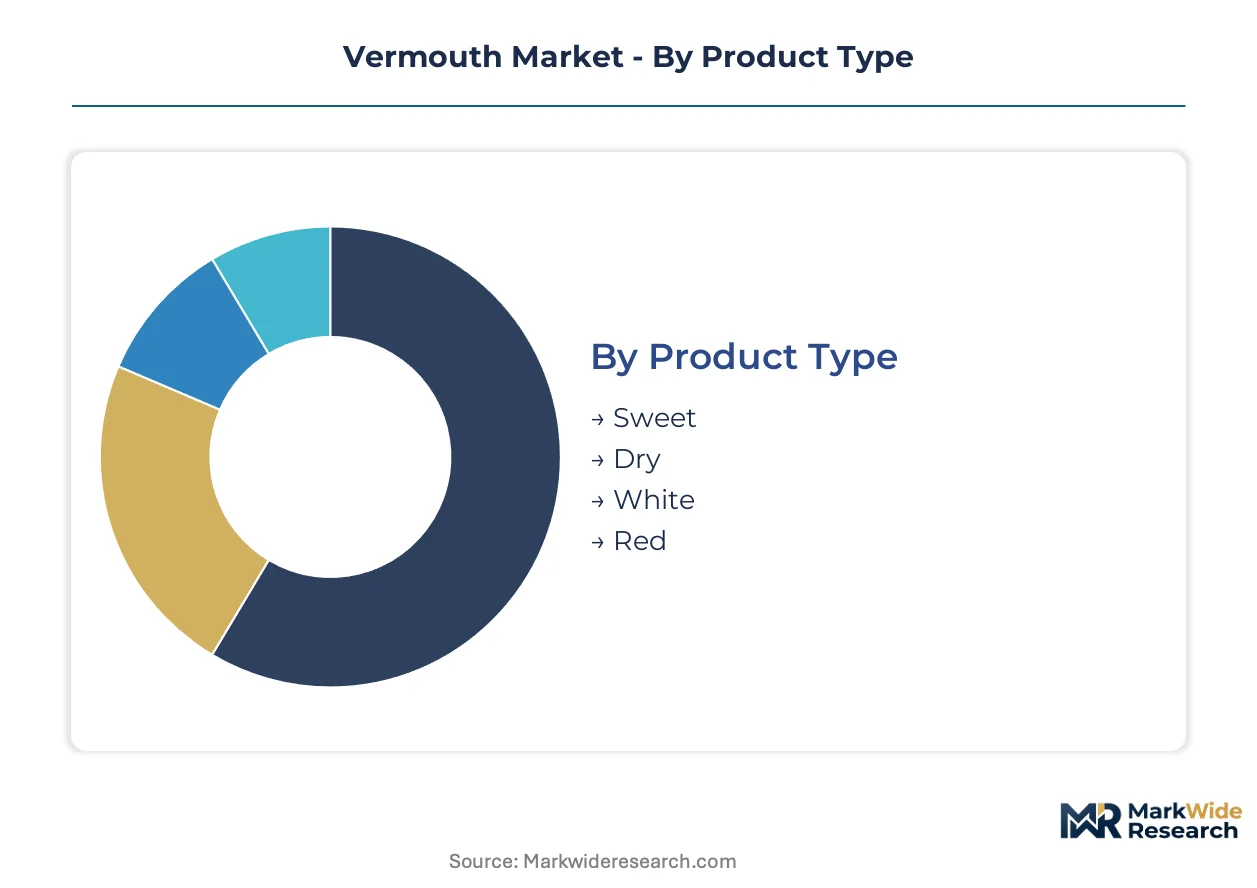
The vermouth market's diverse product offerings and consumption patterns necessitate detailed segmentation. Understanding these distinct market slices allows producers to tailor product development, target specific consumer demographics, and optimize distribution strategies. This analysis illuminates the varied facets of vermouth consumption and production.
Product Type:
Vermouth's fundamental classification hinges on its flavor profile and botanical composition.
- Sweet:This variant, also known as Rosso or Rouge, typically features a higher sugar content and a richer, often caramel-colored base wine. Demand concentrates in classic cocktails like the Manhattan, particularly in established bar scenes across the United States.
- Dry:Characterized by a lower sugar content and a pale, often clear appearance, dry vermouth frequently incorporates a more herbaceous and less sweet botanical blend. Its expanding use in Martini and other sophisticated cocktails drives momentum in metropolitan hubs such as London.
- White:Often a sweeter or semi-dry style, this clear vermouth offers floral or citrus notes, appealing to consumers seeking lighter flavor profiles.
- Red:This category largely overlaps with sweet vermouth, denoting its color and robust flavor, popular in traditional European aperitif culture.
Sweet vermouth leads on volume scale; Dry vermouth leads on momentum.
Serving Method:
Consumption preferences dictate vermouth's presentation, reflecting diverse drinking occasions.
- Cocktail:Vermouth serves as a critical component in numerous classic and contemporary cocktails, balancing spirits and other modifiers. This method represents the fastest-growing segment, driven by the expanding craft cocktail scenes in major cities like New York and Paris.
- Mixed:This method involves combining vermouth with non-alcoholic mixers such as soda water, tonic, or juice, creating lighter, refreshing drinks. Demand for mixed vermouth is gaining traction among consumers seeking lower-alcohol alternatives in casual social settings.
- On the Rocks:Served simply over ice, this method highlights vermouth's inherent botanical complexity, favored by purists seeking an unadulterated experience.
- Neat:Consumed unchilled and without additions, neat vermouth offers an intense appreciation of its aromatic depth, particularly for premium expressions.
Cocktail serving methods demonstrate the steepest expansion trajectory; On the Rocks maintains a niche for connoisseurs.
Distribution Channel:
Vermouth's availability channels cater to distinct purchasing behaviors and consumption environments.
- Bars:On-premise consumption in bars allows for expert recommendations and curated cocktail experiences, significantly influencing brand perception and consumer education. This channel drives discovery for artisanal vermouths, particularly in vibrant cocktail scenes across Berlin and Tokyo.
- Restaurants:Fine dining and casual eateries increasingly feature vermouth in aperitif programs and culinary pairings, enhancing the overall gastronomic experience. Restaurants serve as a crucial platform for introducing premium vermouths to a discerning clientele seeking sophisticated beverage options.
- Retail Stores:Traditional retail outlets, including liquor stores and supermarkets, provide broad consumer access for home consumption and everyday purchases.
- Online:E-commerce platforms offer convenience and access to specialized or limited-edition vermouths, appealing to a digitally-savvy consumer base.
On-premise channels, specifically bars and restaurants, are gaining significant share; retail stores maintain foundational volume.
Alcohol Content:
The alcohol content of vermouth dictates its regulatory classification and influences consumer choice for various occasions.
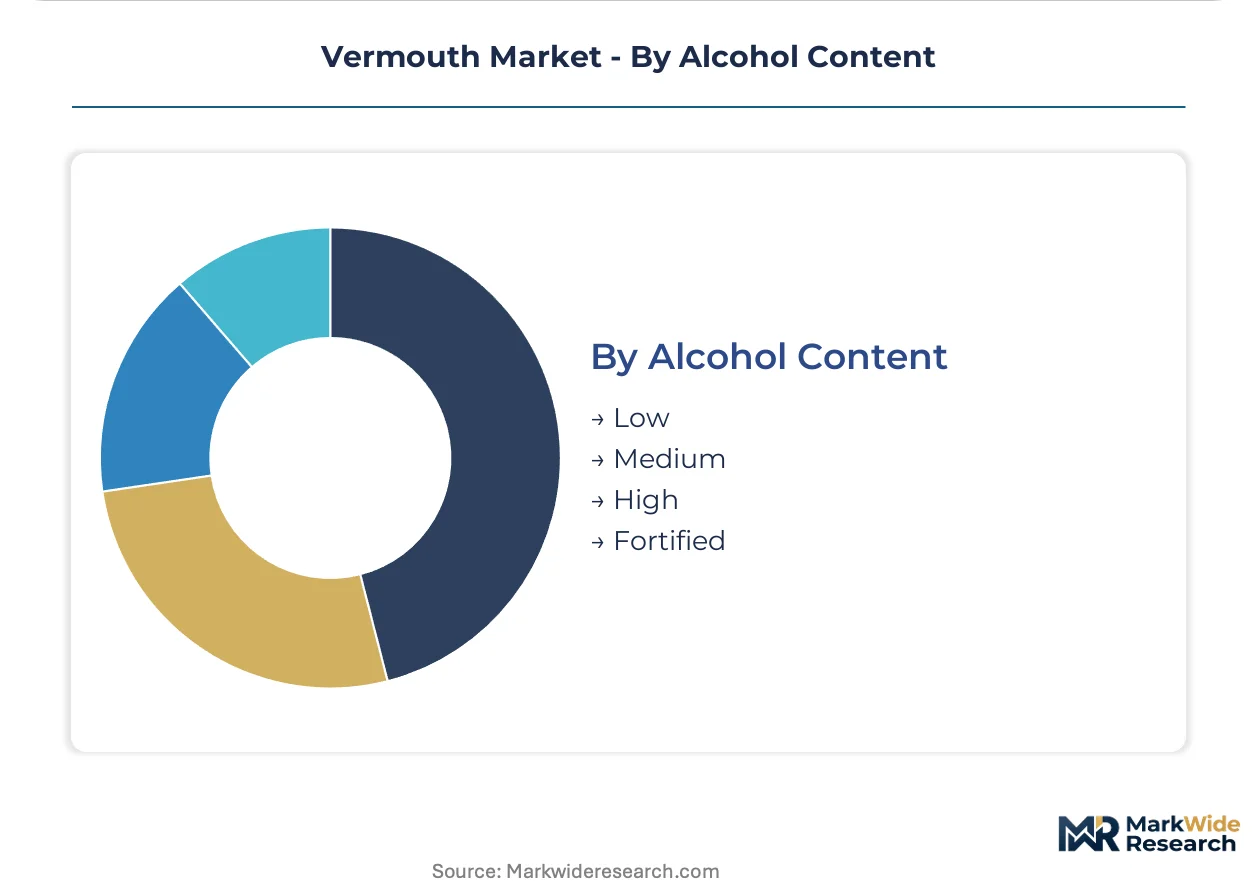
- Fortified:This category encompasses the classic vermouth definition, typically ranging from 14.5% to 22% ABV, achieved through the addition of a neutral spirit during production. Fortified vermouths maintain their dominance in traditional cocktail formulations and aperitif rituals.
- Low:Products with reduced alcohol by volume cater to health-conscious consumers and those seeking lighter beverage options, often below 10% ABV. The demand for low-alcohol vermouth is expanding, particularly in markets with strong wellness trends such as Scandinavia and Australia.
- Medium:These vermouths occupy an intermediate alcohol range, offering a balance between traditional strength and lighter alternatives for broader appeal.
- High:Vermouths at the upper end of the traditional ABV range provide a more robust and intense flavor profile, often favored by connoisseurs.
Fortified variants represent the category's core, while low-alcohol options are attracting new consumer demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turin, Italy, anchors the global vermouth market, driven by its historical significance and Protected Geographical Indication status. This region's influence extends to global consumption patterns and product development. Demand concentrates in major metropolitan areas worldwide.
Italy
Italian consumers prioritize traditional vermouths for aperitif occasions and classic cocktails. The EU's PGI for Vermouth di Torino mandates specific production methods and ingredients, ensuring authenticity. Turin, within the Piedmont region, remains a central hub for artisanal vermouth production and innovation.
United States
The United States drives significant demand for both sweet and dry vermouths, particularly in premium cocktail bars. U.S. TTB regulations govern alcohol content and formulation disclosures for all domestic and imported products. Metropolitan hubs like New York and San Francisco exhibit strong growth in on-premise vermouth consumption.
United Kingdom
United Kingdom's cocktail scene fuels demand for sophisticated vermouths, especially dry variants in classic Martini preparations. Local food and beverage standards ensure product safety and quality for consumers. London's vibrant bar scene is a primary point of discovery for new and established vermouth brands.
France
French consumers maintain a strong preference for vermouth as an aperitif, valuing its botanical complexity. National food and alcohol regulations ensure product integrity and consumer protection. Paris's cocktail establishments are increasingly featuring French vermouths with unique local botanical sourcing.
Germany
German metropolitan areas show a rising appreciation for artisanal vermouths within their expanding cocktail cultures. European Union food and beverage directives govern the production and labeling of vermouth sold nationally. Berlin's dynamic bar scene actively promotes diverse vermouth expressions to a discerning clientele.
Vermouth Market Key Industry Players
Global majors compete with regional champions across brand portfolio depth and distribution reach. The vermouth market exhibits a tiered competitive structure, encompassing large multinational beverage companies and numerous smaller, specialized producers. Key strategic archetypes include global spirits conglomerates, heritage-focused regional brands, and innovative craft distilleries. Companies prioritize portfolio diversification and expanding global distribution networks to capture diverse consumer preferences.
Global conglomerates like Bacardi Limited, a Bermuda-based entity, exemplify expansive distribution capabilities across multiple beverage categories. Italy-headquartered Davide Campari-Milano S.p.A. represents a major player leveraging a broad brand portfolio to address varied consumer tastes. Distillerie Dolin S.A.S., a French company, occupies a niche by specializing in its protected alpine identity, appealing to consumers seeking artisanal and terroir-driven products. These leading enterprises anchor different segments of the market, influencing product innovation and consumer trends through their strategic positioning.
| Leading Market Players |
|---|
| Gruppo Montenegro S.p.A. |
| Giulio Cocchi S.p.A. |
| Bacardi Limited |
| Stock Spirits Group plc |
| Gancia S.p.A. |
| Davide Campari-Milano S.p.A. |
| Distillerie Dolin S.A.S. |
| Lucas Bols N.V. |
| Pernod Ricard S.A. |
| Others |
Cost & Logistics Intelligence
Consumer preference for local botanicals and terroir-driven products is forcing vermouth producers to re-evaluate their sourcing strategies, directly impacting production costs and retail pricing. This demand-side shift necessitates closer relationships with growers and more transparent supply chains.
Pricing Analysis
Rising botanical sourcing costs for unique and locally grown herbs exert upward pressure on vermouth pricing, particularly for premium and craft expressions. The dominant pricing structure is a tiered system, differentiating products across premium, standard, and economy levels. Price differentiation stems from Protected Geographical Indication (PGI) status and the perceived exclusivity of specific botanical blends. Craft cocktail enthusiasts, seeking high-quality ingredients, exhibit the least price sensitivity, while mass-market retail consumers remain highly sensitive to cost.
Supply Chain Analysis
Returns of expired or damaged vermouth stock represent a minor reverse logistics flow for producers managing shelf life and quality standards. Geographic supply concentration for key botanicals centers in regions like Italy (Piedmont) and France (alpine areas), which are critical for authentic flavor profiles. Raw material dependencies include wormwood (Artemisia) and other proprietary botanical blends, often sourced from small-scale growers. Botanical supply constraints, vulnerable to agricultural volatility and climate shifts, pose a structural risk. Distribution runs through a hybrid model, combining on-premise channels for brand discovery with retail stores for volume sales and direct-to-consumer platforms for specialty releases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vermouth market acts as a regulatory compounder, with the EU's Protected Geographical Indication for Vermouth di Torino driving demand for authenticity and premiumization. This regulatory milestone sets a precedent for quality and origin standards, influencing consumer perception and market value.
For Market Incumbents: Cement market leadership by diversifying brand portfolios to include both traditional and innovative vermouth expressions. This strategy defends against the threat from agile craft producers and the rise of non-alcoholic alternatives. Investment in secure, traceable botanical supply chains and expanding global distribution channels through existing networks will reinforce competitive positioning.
For New Entrants and Emerging Players: Launch via direct-to-consumer e-commerce platforms to target niche segments seeking unique, terroir-driven vermouths. The most penetrable segment lies in hyper-local botanical sourcing, offering distinct flavor profiles not tied to traditional Italian or French styles. Partnering with influential craft cocktail bars in metropolitan hubs provides a low-cost, high-impact go-to-market angle for brand discovery.
For Investors and Strategic Acquirers: Asymmetric upside sits with craft producers specializing in unique botanical sourcing and strong regional identities, offering significant potential for long-term portfolio growth within the premium beverage sector. The continued expansion of cocktail culture and consumer demand for artisanal products supports sustained market viability. Watch for new PGI designations or similar geographical protections as a signal of market consolidation and value creation.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand premium botanical sourcing | Secures unique flavor profiles for discerning consumers in metropolitan cocktail scenes. |
| Develop non-alcoholic vermouth lines | Addresses health-conscious consumer demand and expands usage occasions beyond traditional cocktails. |
| Invest in direct-to-consumer e-commerce | Bypasses traditional distribution and captures higher margins on specialty or limited-edition releases. |
| Pursue Protected Geographical Indication status | Formalizes authenticity and quality standards, justifying premium price points for certified products. |
| Establish partnerships with craft cocktail bars | Drives on-premise discovery and shapes brand perception through bartender recommendations. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, forming a robust data approach. Primary research involved discussions with brand managers, master blenders, bar owners, and retail buyers to gather first-hand market insights. Secondary validation drew from EU PGI documentation, U.S. TTB regulations, trade association reports, and broader market trend analyses. This mixed-methods approach enabled comprehensive bottom-up and top-down triangulation of market data.
Segment-weighting approaches define the analytical framework across the analysis window, modeling market dynamics for various dimensions. Segmentation included product type, serving method, distribution channel, alcohol content, and regional market maturity. Compound annual growth rates (CAGRs) were derived through a combination of regression analysis and expert panel consensus. Key industry-specific forecast inputs included consumer spending on premium beverages and the adoption rates of craft cocktail trends.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of significant regulatory shifts or unforeseen botanical supply disruptions. Forecasts reflect assumptions regarding the stability of traditional recipes and the pace of innovation in novel botanicals. Practitioners should monitor new PGI designations and craft botanical sourcing innovations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Pinot Meunier Market
Alcoholic Beverages
Cocktail Market
Alcoholic Beverages
Mushroom Beer Market
Alcoholic Beverages
Cannabis Drinks Market
Alcoholic Beverages
Bottled Craft Beer Market
Alcoholic Beverages
Rotels Market
Alcoholic Beverages
Cider and Perry Market
Alcoholic Beverages
Wine Destemmer Market
Alcoholic Beverages
Hookah Charcoal Market
Alcoholic Beverages
Europe Beer Market
Alcoholic Beverages
Brewers Spent Grain Market
Alcoholic Beverages
Middle East and Africa Alcoholic Beverage Market
Alcoholic Beverages
Barrel Liner Market
Alcoholic Beverages
Beer Adjuncts Market
Alcoholic Beverages
Distilled Spirits Market
Alcoholic Beverages
Germany Wine Coolers Market