
 Yorker Spouts Market | 2026-2036
Yorker Spouts Market Size, Share, and Industry Trends Forecast 2026-2036
Yorker Spouts Market Analytics
REACH compliance is restructuring the cost-of-entry calculus for European suppliers of polymer-based dispensing closures. AptarGroup leverages its captive resin compounding capabilities to sustain margin stability across volatile feedstock cycles. Silgan Holdings anchors North American supply through integrated blow-molding and spout-assembly lines. Amcor Limited differentiates via global footprint scale, operating conversion plants across fifteen countries with unified quality protocols.
Yorker spouts are tapered, threaded dispensing closures typically molded from high-density polyethylene or polypropylene, designed to enable controlled pouring from flexible pouches, bottles, and collapsible containers used in food, agricultural, and chemical packaging. Plastic spouts dominate volume due to cost efficiency and compatibility with standard induction-sealing equipment, though silicone spouts command premium positioning in temperature-variable dispensing applications. The food processing end-user segment leads absolute demand, while the chemical industry channel shows the fastest structural expansion driven by regulatory pressure to replace traditional open-mouth drums with closed dispensing systems.
FDA food-contact notification requirements and EU REACH substance restrictions jointly determine which resin formulations and lubricant additives gain commercial traction in cross-border trade. The EPA's emerging per- and polyfluoroalkyl substance rules threaten incumbent fluoropolymer barrier coatings, forcing reformulation investment across the supplier base. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and qualify alternative barrier technologies before compliance deadlines harden.
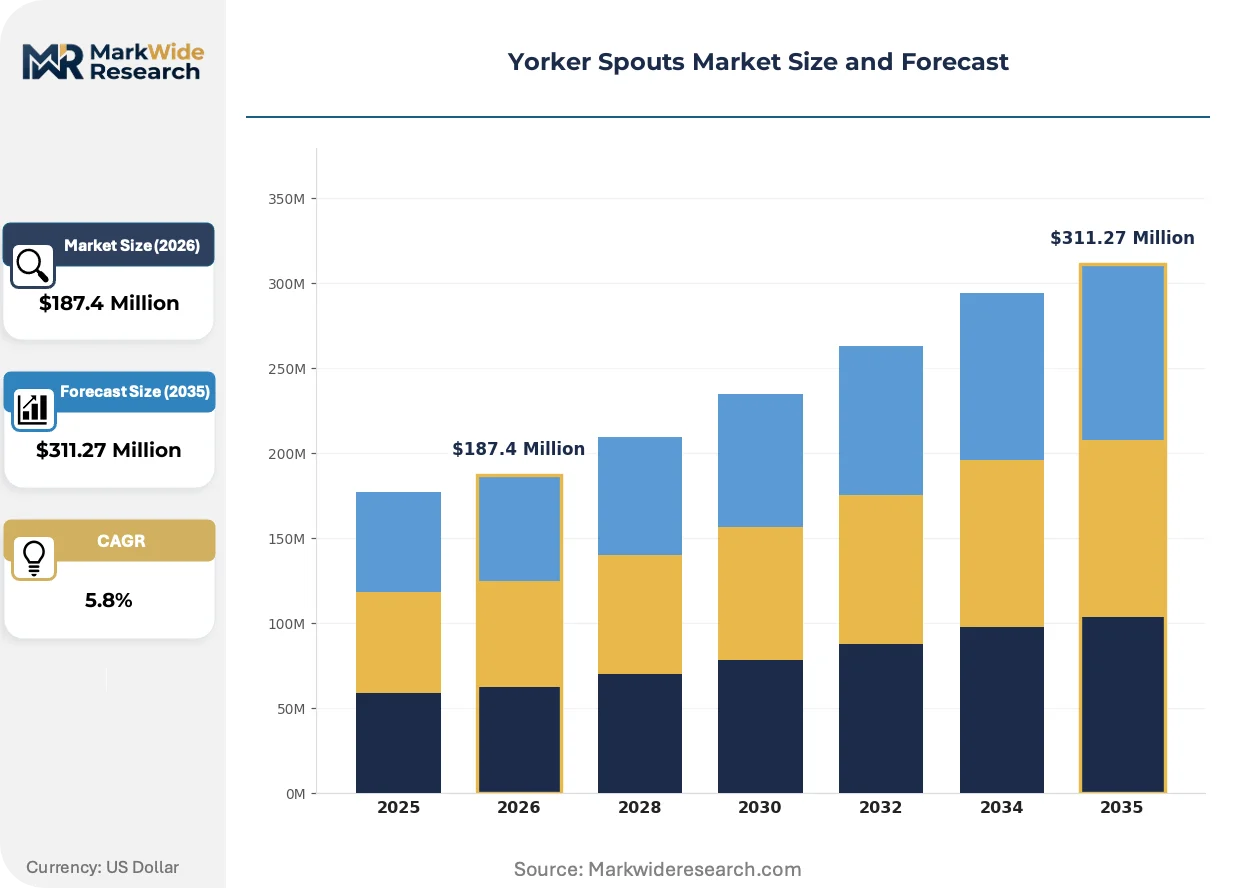
Market Dynamics
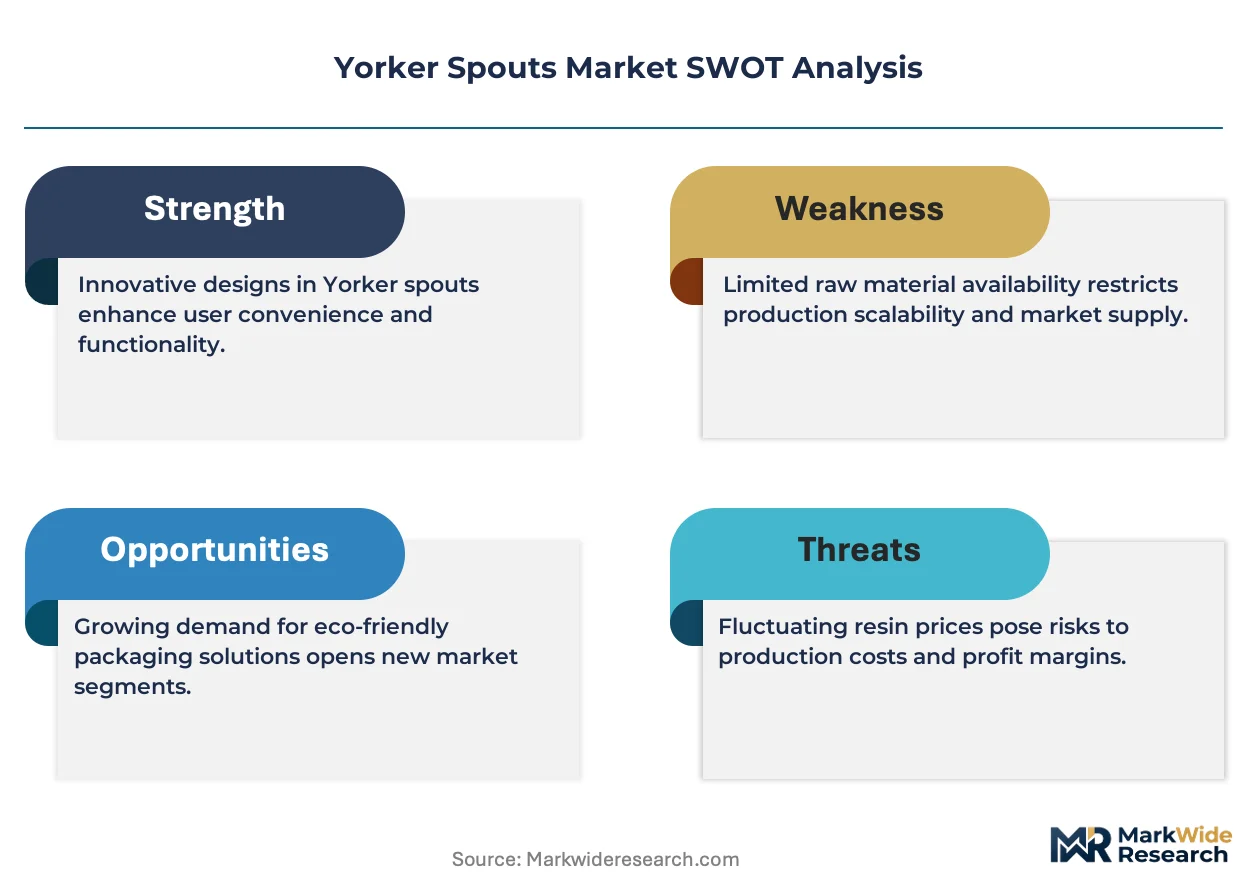
REACH substance restrictions and EPA per- and polyfluoroalkyl substance rules are forcing wholesale reformulation of barrier coatings across the polymer dispensing closure supply base, compressing qualification timelines and elevating technical barriers to market entry.
Growth Catalysts
- EU REACH compliance mandates:Chemical manufacturers across Germany's Rhine-Ruhr corridor are retrofitting drum-to-pouch dispensing systems to meet closed-system handling requirements, accelerating Yorker spout specification in agrochemical packaging.
- Precision dispensing technology:Beverage manufacturers are embedding tapered-thread HDPE spouts into flexible pouch formats to reduce product waste and enable controlled portioning in on-the-go consumption scenarios.
- Food processing automation:Induction-sealing compatibility of polypropylene spouts aligns with high-speed filling line throughput requirements in commercial sauce and condiment operations.
Market Restraints
- Feedstock volatility:High-density polyethylene and polypropylene resin prices fluctuate with naphtha-cracker output cycles, compressing margin stability for non-integrated molders.
- Fluoropolymer coating phase-out:EPA restrictions on per- and polyfluoroalkyl substances threaten incumbent barrier technologies, forcing unplanned R&D expenditure without guaranteed substitute performance parity.
- German supplier concentration:Hamburg's packaging cluster hosts disproportionate conversion capacity, creating geographic vulnerability to regional logistics disruptions or energy cost spikes.
Strategic Opportunities
- Silicone spout premium tier:Temperature-variable dispensing applications in infant nutrition and medical food segments reward silicone's thermal stability with price premiums unattainable in standard polymer formats.
- US chemical packaging conversion:OSHA Process Safety Management pressure and EPA spill prevention mandates are displacing open-mouth drums with closed dispensing systems in specialty chemical distribution.
- Dual-carbon alignment in China:NMPA and MIIT circular economy directives favor lightweight flexible packaging over rigid alternatives, creating regulatory tailwind for pouch-plus-spout configurations in domestic food exports.
Industry Challenges
- Cross-jurisdictional formulation drift:FDA food-contact notification requirements diverge from EU REACH substance restrictions, forcing suppliers to maintain parallel resin grades and lubricant additive portfolios.
- Induction-sealing line retrofit costs:Collapsible container formats with integrated Yorker spouts demand capital expenditure on modified cap-application and seal-verification equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yorker Spouts Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Spouts, Metal Spouts, Silicone Spouts, Composite Spouts End User: Food Processing, Beverage Industry, Agriculture, Chemical Industry Application: Filling, Dispensing, Irrigation, Packaging Distribution Channel: Online Retail, Wholesalers, Direct Sales, Specialty Stores |
| Companies Covered | AptarGroup, Inc., Silgan Holdings Inc., Amcor Limited, Tetra Pak International S.A., Berry Global Inc., WestRock Company, Mondi Group, DS Smith Plc, Berlin Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yorker Spouts Market Evolving Landscape
Active reformulation of barrier coatings and resin systems is compressing product development cycles while elevating technical qualification thresholds across polymer dispensing closure manufacturing.
Biobased polyethylene derived from sugarcane ethanol is electrifying sustainable packaging roadmaps for multinational food brands seeking scope 3 emissions reductions. Nestlé and Unilever procurement teams are mandating renewable content thresholds in flexible pouch specifications by 2027. This material shift is compressing incumbent fossil-based resin volumes in European and North American supply contracts.
EPA per- and polyfluoroalkyl substance rules are prohibiting fluoropolymer barrier coatings in food-contact applications, forcing suppliers to qualify ceramic and silicon oxide alternatives. The regulation's industrial consequence is extended FDA food-contact notification timelines as novel barrier chemistries undergo migration testing. Agrochemical packaging segments are accelerating adoption of uncoated high-barrier multilayer films to preempt compliance exposure.
Consolidated buying by private-label beverage retailers is compressing supplier margins and elevating volume-commitment requirements. Aldi and Lidl central procurement offices are specifying unified spout geometries across multiple product categories to maximize line efficiency. This concentration is most visible in Germany's discount retail channel, where standardized 16mm and 22mm orifice diameters now dominate private-label condiment and sauce introductions.
Yorker Spouts Market Segmentation
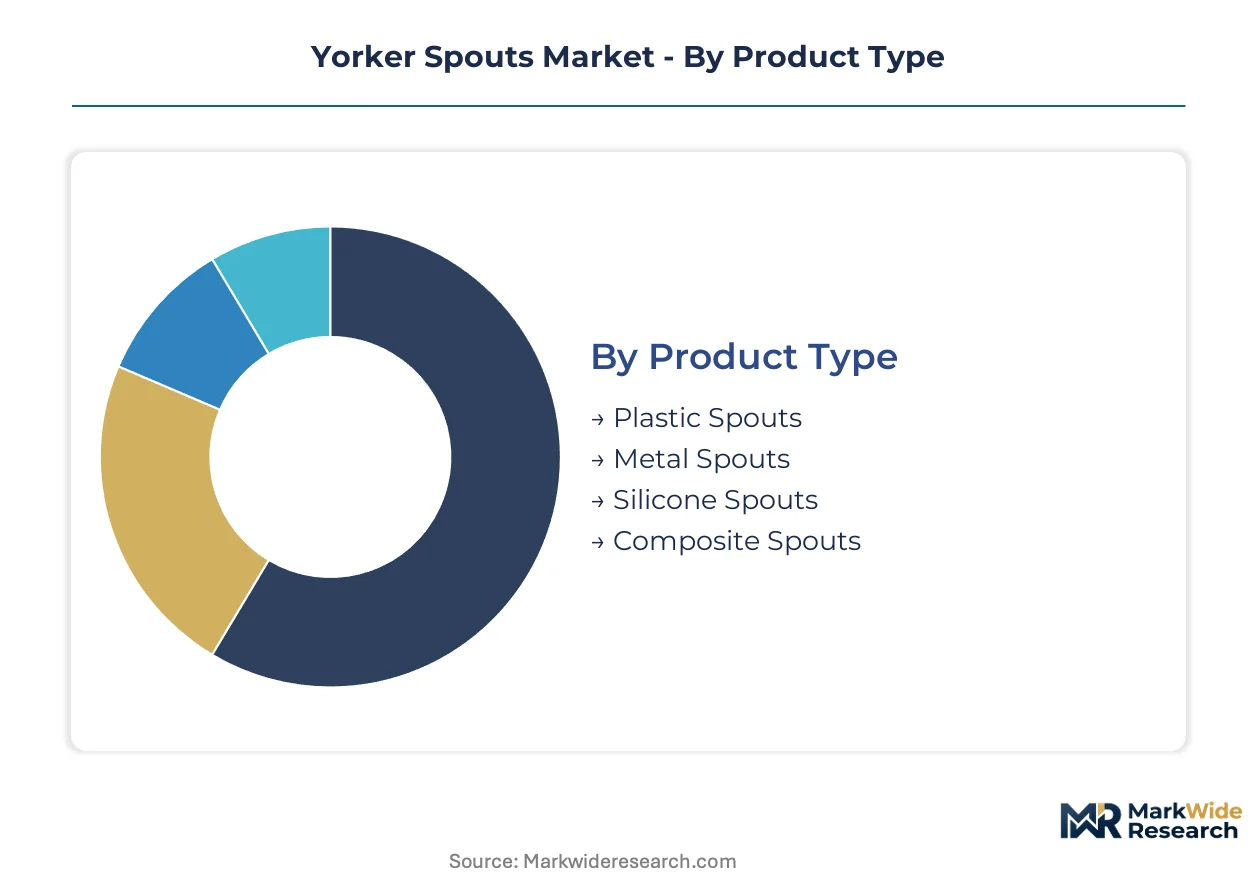
Yorker spouts serve divergent performance requirements across temperature extremes, chemical compatibility demands, and regulatory exposure profiles. Segmentation reveals how material selection and channel strategy determine margin capture and qualification burden.
Product Type:
Plastic spouts dominate unit volume through cost efficiency, while silicone commands premium positioning in performance-critical applications.
- Plastic Spouts:High-density polyethylene and polypropylene formulations enable induction-sealing compatibility with standard filling equipment. Beverage manufacturers in Germany's discount retail channel specify tapered-thread HDPE spouts for flexible pouch formats to minimize product waste during on-the-go consumption.
- Silicone Spouts:Thermally stable elastomer construction withstands temperature-variable dispensing cycles without deformation. Infant nutrition and medical food segments reward silicone's performance with price premiums unattainable in standard polymer formats.
- Metal Spouts:Stainless steel and aluminum variants serve high-barrier chemical packaging where solvent resistance exceeds polymer capabilities.
- Composite Spouts:Hybrid constructions combine polymer bodies with metal or ceramic barrier layers for specialized agrochemical applications.
Mature deployment sits with plastic spouts. Newer deployment is concentrated in silicone formulations.
End User:
Food processing anchors absolute demand volume, though chemical industry conversion to closed dispensing systems drives structural expansion.
- Food Processing:Commercial sauce and condiment operations demand polypropylene spouts compatible with high-speed induction-sealing lines. Aldi and Lidl procurement offices standardize 16mm and 22mm orifice geometries across private-label introductions to maximize line efficiency.
- Chemical Industry:OSHA Process Safety Management pressure and EPA spill prevention mandates displace open-mouth drums with closed dispensing systems. Specialty chemical distributors in the US retrofit drum-to-pouch configurations to preempt regulatory exposure.
- Beverage Industry:Flexible pouch formats with integrated spouts reduce packaging weight versus rigid alternatives.
- Agriculture:Agrochemical packaging segments accelerate adoption of uncoated high-barrier multilayer films to address EPA per- and polyfluoroalkyl substance restrictions.
Volume concentration remains with food processing. Steepest expansion trajectory belongs to chemical industry applications.
Application:
Dispensing functionality commands premium specification, while filling compatibility determines supplier qualification protocols.
- Dispensing:Controlled pouring mechanisms with threaded closure systems enable precise portioning in consumer and industrial contexts. Temperature-variable dispensing applications reward material selection that maintains seal integrity across thermal cycling.
- Filling:Induction-sealing line compatibility requires spout geometries that align with cap-application and seal-verification equipment. Modified filling line capital expenditure creates switching costs for established supplier relationships.
- Packaging:Integrated spout-pouch configurations reduce material usage versus rigid container alternatives.
- Irrigation:Agricultural field deployment demands UV-stabilized polymers resistant to chemical fertilizer exposure.
Established deployment centers on filling operations. Emerging deployment is accelerating in dispensing configurations.
Distribution Channel:
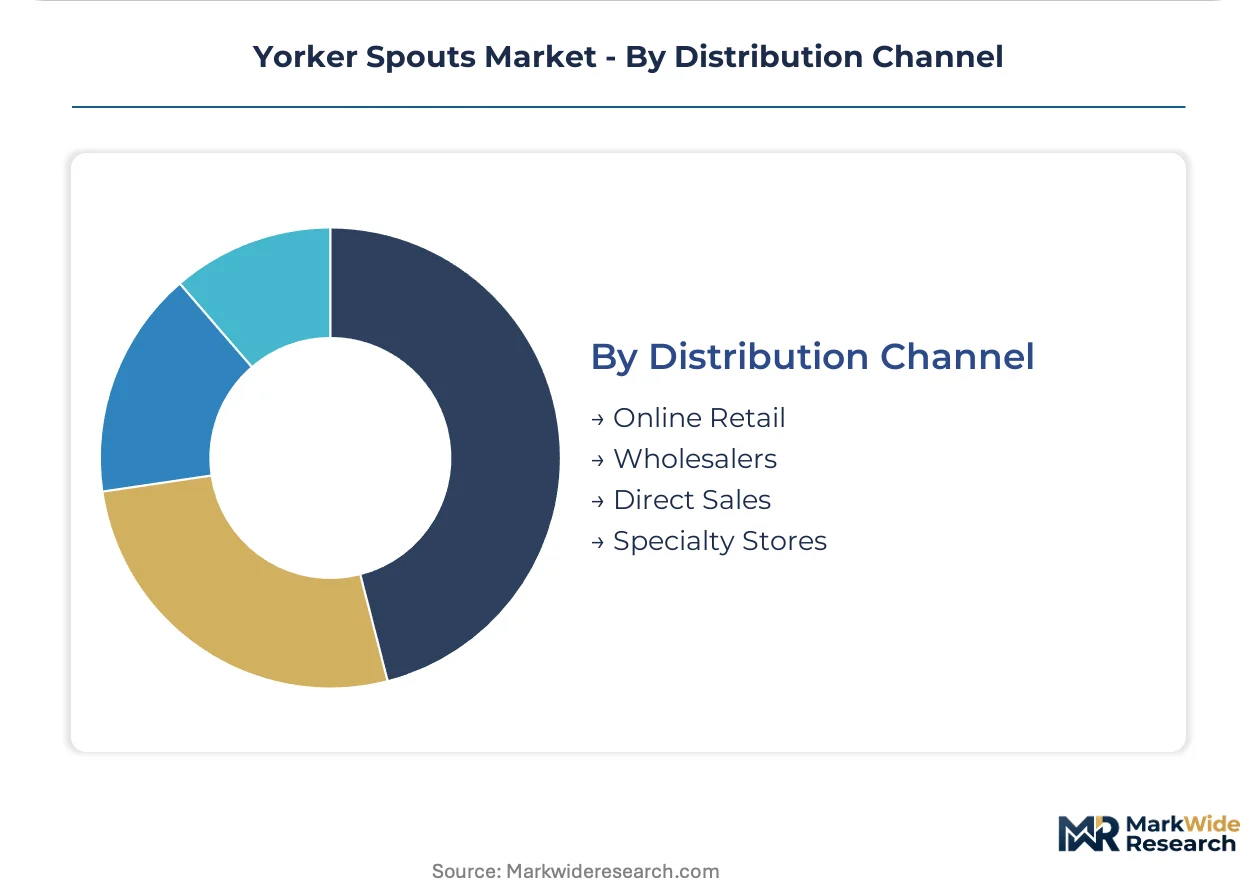
Direct sales capture specification-intensive volume, while online retail serves fragmented maintenance and replacement demand.
- Direct Sales:Beverage and chemical manufacturers negotiate multi-year supply agreements with integrated molders specifying unified quality protocols. Silgan Holdings and Amcor Limited anchor North American and global supply through direct relationships with volume buyers.
- Wholesalers:Regional packaging distributors stock standard spout geometries for mid-tier food processors with intermittent demand patterns.
- Online Retail:E-commerce platforms serve small-batch agricultural and specialty chemical buyers with non-standard specifications.
- Specialty Stores:Local packaging equipment suppliers provide technical consultation for induction-sealing line retrofits.
Contracted volume flows through direct sales. Fragmented demand concentrates in wholesaler and online channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's free-trade zones around Hamburg and the Rhine-Ruhr corridor anchor European conversion capacity for precision dispensing closures. Tax-advantaged warehousing facilities in these zones reduce landed costs for resin imports serving integrated spout-assembly operations.
Germany
Beverage manufacturers in the discount retail channel specify standardized 16mm and 22mm orifice geometries for flexible pouch formats. EU REACH substance restrictions mandate reformulation of barrier coatings in food-contact applications. Hamburg's packaging cluster hosts disproportionate blow-molding and spout-assembly capacity, creating geographic concentration risk.
United States
Specialty chemical distributors retrofit drum-to-pouch dispensing systems to meet OSHA Process Safety Management requirements. EPA per- and polyfluoroalkyl substance rules prohibit fluoropolymer barrier coatings in food-contact packaging. Integrated molders in the Midwest maintain captive resin compounding capabilities to buffer feedstock volatility.
China
NMPA and MIIT circular economy directives favor lightweight flexible packaging over rigid alternatives for domestic food exports. Dual-carbon alignment policies reward scope 3 emissions reductions in packaging supply chains. Yangtze River Delta manufacturing bases concentrate pouch-plus-spout conversion capacity for regional beverage brands.
India
Commercial sauce and condiment operations demand polypropylene spouts compatible with high-speed induction-sealing lines. FSSAI food-contact material regulations determine which resin formulations gain commercial traction in domestic packaging. Maharashtra's industrial corridors host emerging flexible packaging conversion capacity serving FMCG procurement offices.
Brazil
Agricultural chemical packaging segments accelerate adoption of closed dispensing systems to preempt regulatory exposure. ANVISA pharmaceutical packaging standards influence material selection in medical food applications. São Paulo state's packaging belt concentrates blow-molding operations for regional agrochemical distributors.
Yorker Spouts Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across material grades and end-use specifications. The supplier base organizes into three tiers: integrated resin-to-closure manufacturers, independent molders with regional footprints, and specialty compounders serving niche temperature-variable applications. Consolidation pressure intensifies as beverage retailers centralize procurement through unified spout geometry specifications. Two dominant competitive moves define current positioning: backward integration into captive resin compounding and geographic expansion through distribution partnerships in Asia-Pacific growth corridors.
Among diversified packaging conglomerates, AptarGroup, Silgan Holdings, and Amcor Limited exemplify contrasting scale strategies. AptarGroup represents the integrated compounder archetype with in-house resin formulation capabilities. Silgan Holdings anchors North American supply relationships through direct manufacturer engagement. Amcor Limited occupies the global footprint position with unified quality protocols spanning multiple jurisdictions. These three entities collectively illustrate how scale, integration depth, and geographic coverage differentiate competitive positioning in precision dispensing closure supply.
| Leading Market Players |
|---|
| AptarGroup, Inc. |
| Silgan Holdings Inc. |
| Amcor Limited |
| Tetra Pak International S.A. |
| Berry Global Inc. |
| WestRock Company |
| Mondi Group |
| DS Smith Plc |
| Berlin Packaging |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap molders across Germany's Rhine-Ruhr corridor anchor resin-to-closure production, translating captive compounding capabilities into pricing discipline that buffers non-integrated competitors from naphtha-cracker volatility. Their ownership structure supports long-dated supply contracts with Aldi and Lidl procurement offices, locking in volume commitments that stabilize margins against spot resin fluctuations.
Pricing Analysis
Short lead-time premiums attach to silicone spout orders for infant nutrition applications, while spot inventory of standard HDPE geometries trades at modest discounts to contract benchmarks. Three-tier pricing structure across premium silicone, standard polypropylene, and economy HDPE levels reflects certification grade and thermal performance differentiation. Cost compression in the economy tier intensifies because Aldi and Lidl central procurement mandates unified 16mm and 22mm orifice specifications, forcing molders to compete on scale rather than customization. Mid-tier food processors exhibit highest price sensitivity, while medical food buyers accept silicone premiums for temperature stability.
Supply Chain Analysis
Resin supply rests on German petrochemical complexes around Hamburg and the Rhine-Ruhr corridor, with secondary sourcing from Belgian and Dutch polymer producers. High-density polyethylene, polypropylene, and silicone elastomer feedstocks draw from naphtha-cracker output cycles and specialty chemical streams respectively. Single-source vulnerability concentrates in fluoropolymer barrier coatings facing EPA phase-out, forcing qualification of ceramic and silicon oxide substitutes. Distribution runs through direct manufacturer relationships with beverage and chemical volume buyers, supplemented by regional wholesalers serving fragmented agricultural demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Yorker spouts market sits in active barrier-coating transition, with ceramic and silicon oxide formulations displacing fluoropolymer legacy technologies under EPA and REACH pressure. This substitution cycle compresses qualification timelines while elevating technical barriers for suppliers lacking R&D scale.
For Market Incumbents: Deploy captive resin compounding as a defensive lever to sustain margin stability across volatile feedstock cycles. AptarGroup's integrated formulation capabilities exemplify how upstream control buffers margin compression from naphtha-cracker volatility. Invest in FDA food-contact notification capacity for novel barrier chemistries before compliance deadlines harden, preempting stranded inventory exposure from fluoropolymer phase-out.
For New Entrants and Emerging Players: Enter via silicone spout specialization for temperature-variable dispensing in infant nutrition and medical food segments, where price premiums reward thermal stability performance. White-space concentrates in US chemical packaging conversion, where OSHA Process Safety Management pressure displaces open-mouth drums with closed dispensing systems. Pursue toll-compounding partnerships with established resin formulators to bypass capital-intensive compounding infrastructure.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap molders with FDA-compliant barrier coating pipelines in Germany's Hamburg packaging cluster, where energy cost spikes and logistics disruptions create selective pressure. Long-term viability over the next decade hinges on regulatory qualification velocity rather than pure manufacturing scale. Watch EPA enforcement timing on per- and polyfluoroalkyl substance rules as the critical inflection signal for substitute technology adoption rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating Reformulation | EPA and REACH compliance deadlines force ceramic and silicon oxide qualification before fluoropolymer prohibition hardens. |
| Captive Resin Compounding | AptarGroup's in-house formulation capabilities buffer margin stability across naphtha-cracker output cycles. |
| Silicone Spout Capacity Addition | Thermal stability premiums in infant nutrition reward elastomer construction with pricing power unattainable in polymers. |
| Direct Sales Channel Control | Silgan Holdings anchors North American supply through manufacturer relationships bypassing distributor markups. |
| Induction-Sealing Line Retrofit Partnerships | Specialty stores providing technical consultation capture switching costs from modified cap-application equipment. |
Research Methodology
Multi-period observation of FDA food-contact notification timelines, EU REACH substance restriction implementations, and resin price volatility anchored the trend analysis, supplemented by interviews with plant managers at integrated molders, procurement leads at Aldi and Lidl central offices, technical R&D directors at barrier coating suppliers, and distribution channel partners in Germany's packaging cluster. Secondary validation drew from customs and trade data tracking polymer resin flows, SEC 10-K filings of diversified packaging conglomerates, ECHA substance restriction updates, and EPA rulemaking dockets. Bottom-up volume estimates from spout-assembly line capacities were triangulated against top-down demand projections from flexible pouch conversion rates.
Input-output matrices modeled resin feedstock costs, molding cycle efficiencies, and regulatory compliance expenditures across the projection horizon. Segmentation dimensions included material grade tier, end-use industry channel, dispensing versus filling application, and regional production hub concentration. CAGRs were derived from trend extrapolation of historical volume data adjusted for regulatory phase-in schedules and buyer consolidation patterns. Industry-specific forecast inputs incorporated naphtha-cracker operating rates and private-label retailer procurement centralization trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EPA enforcement acceleration or extended FDA migration testing timelines for novel barrier chemistries. Forecasts reflect documented assumptions regarding regulatory implementation pacing and resin price mean-reversion properties. Supply disruption from Hamburg logistics congestion or Rhine-Ruhr energy cost spikes warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Tea Beer Market
Alcoholic Beverages
Commercial Wine Dispenser Market
Alcoholic Beverages
North America Craft Beer Market
Alcoholic Beverages
Global Bars and Nightclubs Market
Alcoholic Beverages
Beer Processing Market
Alcoholic Beverages
Still Wine Market
Alcoholic Beverages
Tanzania Spirits Market
Alcoholic Beverages
Canned Wine Market
Alcoholic Beverages
Wine Destemmer Market
Alcoholic Beverages
Home Brew Boiler Market
Alcoholic Beverages
Germany Wine Coolers Market
Alcoholic Beverages
Global Wine Coolers Market
Alcoholic Beverages
Cordial Drink Market
Alcoholic Beverages
North America Spirits Market
Alcoholic Beverages
Canada Alcohol E-Commerce Market
Alcoholic Beverages
Global Bourbon Market