
 Sparkling Red Wine Market | 2026-2036
Sparkling Red Wine Market Size, Share, and Industry Trends Forecast 2026-2036
Sparkling Red Wine Market Outlook
Market Context
Italy's Emilia-Romagna vineyard expansion is narrowing the supply gap for authentic Lambrusco DOC production. Jackson Family Wines leverages its Sonoma County infrastructure to sustain sparkling red experimentation in California's cooler sub-AVAs. E&J Gallo Winery anchors mass-market accessibility through controlled retail distribution across North American grocery channels. Korbel Champagne Cellars competes on heritage positioning with its traditional methode champenoise red sparkling program.
Technical Profile and Segment Structure
Sparkling red wine denotes effervescent wine produced from red grape varietals through either Charmat tank fermentation or traditional bottle fermentation, retaining anthocyanin pigments that yield ruby to deep purple hues with CO₂ pressure typically at 3-6 atmospheres. The category serves celebratory and gastronomic occasions where tannin structure meets refreshing carbonation. Lambrusco dominates volume through approachable sweetness profiles and competitive price positioning in Italian export markets. Premium price tier offerings concentrate margin pools where extended lees aging and single-vineyard sourcing justify elevated positioning. E-commerce sales channel growth is accelerating as direct-to-consumer platforms bypass traditional three-tier distribution constraints.
Regulatory Environment and Outlook
EU geographical indication protections under EFSA and DG Agriculture frameworks enforce DOC/DOCG labeling standards that shape import eligibility and consumer trust. US TTB labeling requirements and state-level distribution laws fragment market access for foreign producers seeking American retail placement. FDA and Alcohol and Tobacco Tax and Trade Bureau compliance costs favor established importers with dedicated regulatory affairs capacity. Stakeholders must monitor evolving EU Green Deal carbon accounting rules for agricultural inputs and packaging materials.
Market Dynamics
EU Green Deal agricultural standards are compressing vineyard certification timelines for producers exporting into European markets, forcing accelerated adoption of carbon-accounted viticulture practices.
Growth Catalysts
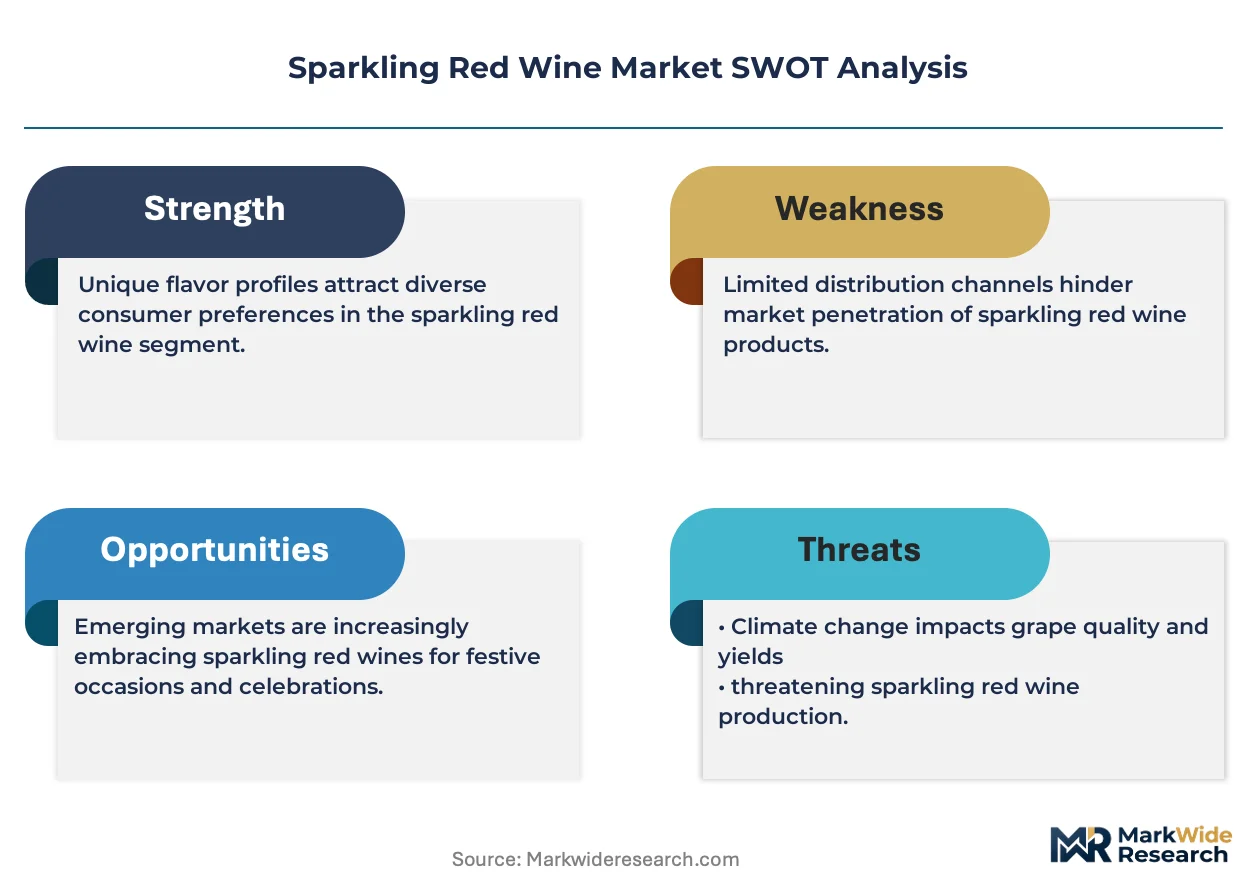
- Boutique Hospitality Expansion:Premium cruise lines and independent hotel chains are expanding sparkling red wine service across beverage programs, creating dedicated list placement for Lambrusco and Brachetto varietals.
- EU Green Deal:Carbon-accounting standards for agricultural inputs and packaging materials are creating competitive differentiation for early-adopting vineyards with certified sustainable practices.
- Modena-Asti Cluster Concentration:Italian regional production hubs maintain heritage positioning through DOC-protected traditional methods, anchoring authenticity premiums in export markets.
Market Restraints
- Three-Tier Distribution Fragmentation:US state-level distribution laws create regulatory friction for foreign producers seeking grocery and retail placement across multiple jurisdictions.
- Input Cost Volatility:Glass packaging and agricultural labor costs in Emilia-Romagna fluctuate with energy price swings, compressing margin pools for mid-tier producers.
- Charmat Method Limitations:Tank fermentation systems constrain extended lees aging programs, capping quality perception for volume-focused producers against methode champenoise competitors.
Strategic Opportunities
- Direct-to-Consumer Platforms:E-commerce channels are bypassing traditional three-tier distribution constraints, enabling producer-margin recovery through subscription and cellar-door models.
- US Market Underpenetration:American grocery channel placement remains sparse for authentic Lambrusco DOC, presenting white-space expansion for certified importers with TTB compliance capacity.
- Single-Vineyard Sourcing:Extended lees aging and estate-bottled programs command premium positioning, concentrating margin pools above mass-market price tiers.
Industry Challenges
- Regulatory Affairs Talent Scarcity:Dedicated FDA and TTB compliance capacity concentrates among established importers, creating barrier-to-entry for new market entrants.
- Certification Timeline Compression:EU Green Deal vineyard recertification deadlines strain producer administrative bandwidth alongside harvest and production cycles.
- Legacy System Integration:Carbon-accounting software must interface with existing estate management platforms, generating implementation friction for smaller vineyard operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sparkling Red Wine Market |
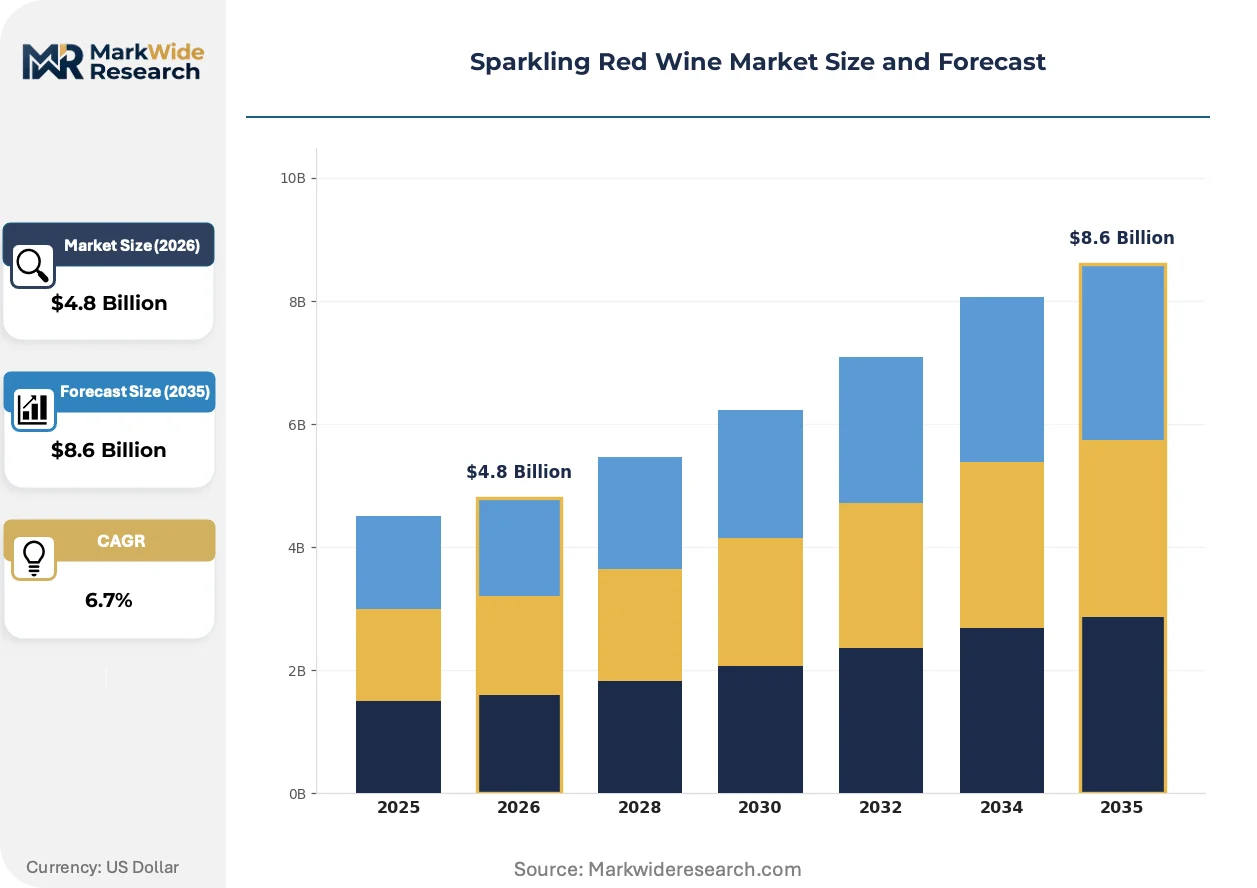
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rosso, Brachetto, Lambrusco, Other Sales Channel: Retail, E-commerce, Wholesale, Direct Packaging Type: Bottle, Can, Box, Carton Price Tier: Premium, Economy, Mid-Range, Luxury |
| Companies Covered | Delicato Family Wines, Jackson Family Wines, E&J Gallo Winery, Korbel Champagne Cellars, Treasury Wine Estates, The Wine Group, Deutsch Family Wine & Spirits, Boisset Collection, Trinchero Family Wine & Spirits, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sparkling Red Wine Market Strategic Shifts
Carbon-accounted viticulture and direct-to-consumer channel expansion are restructuring how sparkling red wine reaches buyers and how producers capture value from heritage positioning.
Precision fermentation monitoring systems are collapsing quality variance between tank-method and traditional bottle-fermentation programs. Boutique producers in Sonoma County's cooler sub-AVAs deploy these sensors to maintain consistent CO₂ pressure and anthocyanin stability. The technology is collapsing the historical quality gap that justified methode champenoise premiums.
EU Green Deal carbon-accounting rules for agricultural inputs are reshaping import eligibility criteria under EFSA and DG Agriculture frameworks. Producers must document vineyard energy use and packaging material footprints to maintain DOC/DOCG labeling rights. Italian export-oriented estates face the steepest compliance ramps as certification deadlines approach.
Subscription-based cellar-door programs are displacing traditional wholesale relationships for premium-tier producers. Direct-to-consumer platforms in California and Oregon enable single-vineyard sparkling reds to bypass three-tier markups. This channel shift concentrates most visibly among millennial buyers in urban coastal markets seeking authentic heritage narratives.
Sparkling Red Wine Market Segmentation
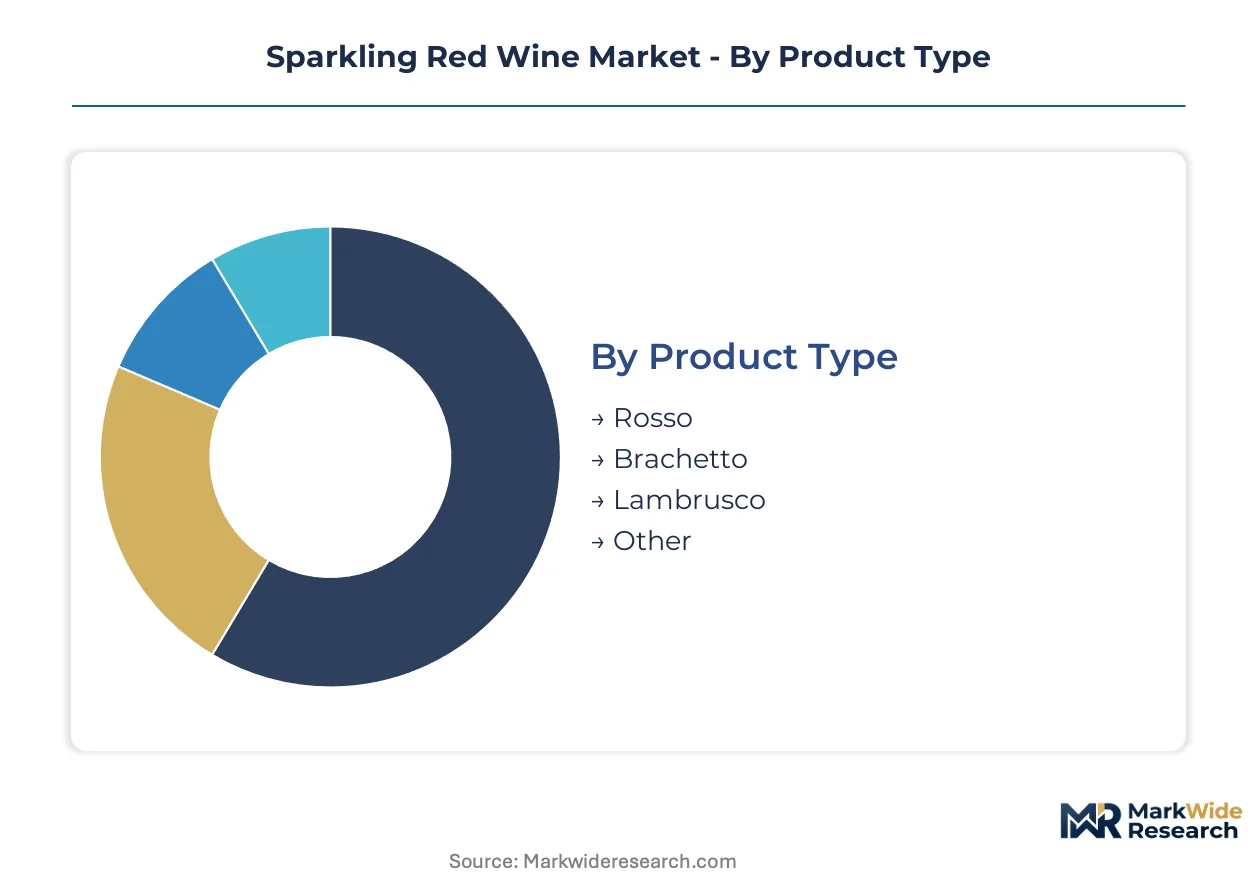
Sparkling red wine segmentation reveals how production methods, distribution pathways, and price positioning fragment buyer access and margin capture. Understanding these divisions exposes where heritage authenticity commands premium positioning versus where volume accessibility drives market penetration.
Product Type:
Consumption occasions span casual aperitivo culture through formal celebratory events, with each varietal anchoring distinct price-occasion combinations.
- Lambrusco:Tank-fermented wines from Emilia-Romagna deliver approachable sweetness profiles with moderate CO₂ pressure. Italian regional clusters around Modena concentrate export-oriented production for North American grocery placement.
- Brachetto:Piedmont's aromatic DOCG varietal exhibits pronounced floral aromatics and lower alcohol content. Boutique hospitality programs in premium cruise lines and independent hotel chains are expanding dedicated list placement for this heritage expression.
- Rosso:Generic sparkling red category captures blended formulations and non-DOC regional productions. Price-competitive positioning serves mass-market accessibility through controlled retail distribution.
- Other:Emerging experimental varietals from California's cooler sub-AVAs and Australian cool-climate regions test market acceptance outside traditional Italian frameworks.
The dominant share belongs to Lambrusco, while Brachetto is closing the gap fastest through heritage positioning in premium on-premise channels.
Sales Channel:
Margin recovery varies sharply across pathways depending on regulatory compliance burdens and three-tier fragmentation exposure.
- E-commerce:Direct-to-consumer platforms bypass traditional wholesale markups through subscription and cellar-door models. Millennial buyers in urban coastal markets drive steepest expansion trajectory through authentic heritage narrative seeking.
- Retail:Grocery and specialty wine shop placement requires TTB-compliant importers with dedicated regulatory affairs capacity. US state-level distribution laws fragment market access for foreign producers seeking multi-jurisdiction presence.
- Wholesale:Three-tier system relationships concentrate volume throughput for established distributors with bonded warehouse infrastructure. Margin compression intensifies as intermediary markups accumulate.
- Direct:Estate tasting room and winery club programs capture highest per-unit margins for single-vineyard producers. California and Oregon operations leverage this channel most aggressively.
E-commerce commands expanding share through margin recovery advantages, while Direct sales climb fastest among premium-tier producers seeking pricing control.
Packaging Type:
Carbon-accounting requirements under EU Green Deal frameworks are reshaping material selection and import eligibility criteria.
- Bottle:Traditional glass packaging dominates premium and heritage-tier positioning with methode champenoise programs. Extended lees aging compatibility cements quality perception advantages.
- Can:Aluminum formats target outdoor and casual consumption occasions with lighter weight logistics. Younger demographic segments in North American markets show strongest acceptance.
- Box:Bag-in-box configurations serve volume-driven hospitality and institutional accounts. Cost efficiency trades against premium positioning limitations.
- Carton:Tetra Pak and similar formats test sustainability messaging alignment with EU agricultural standards compliance.
Bottle retains dominant positioning through quality signaling, though Can formats are expanding most quickly in casual consumption segments.
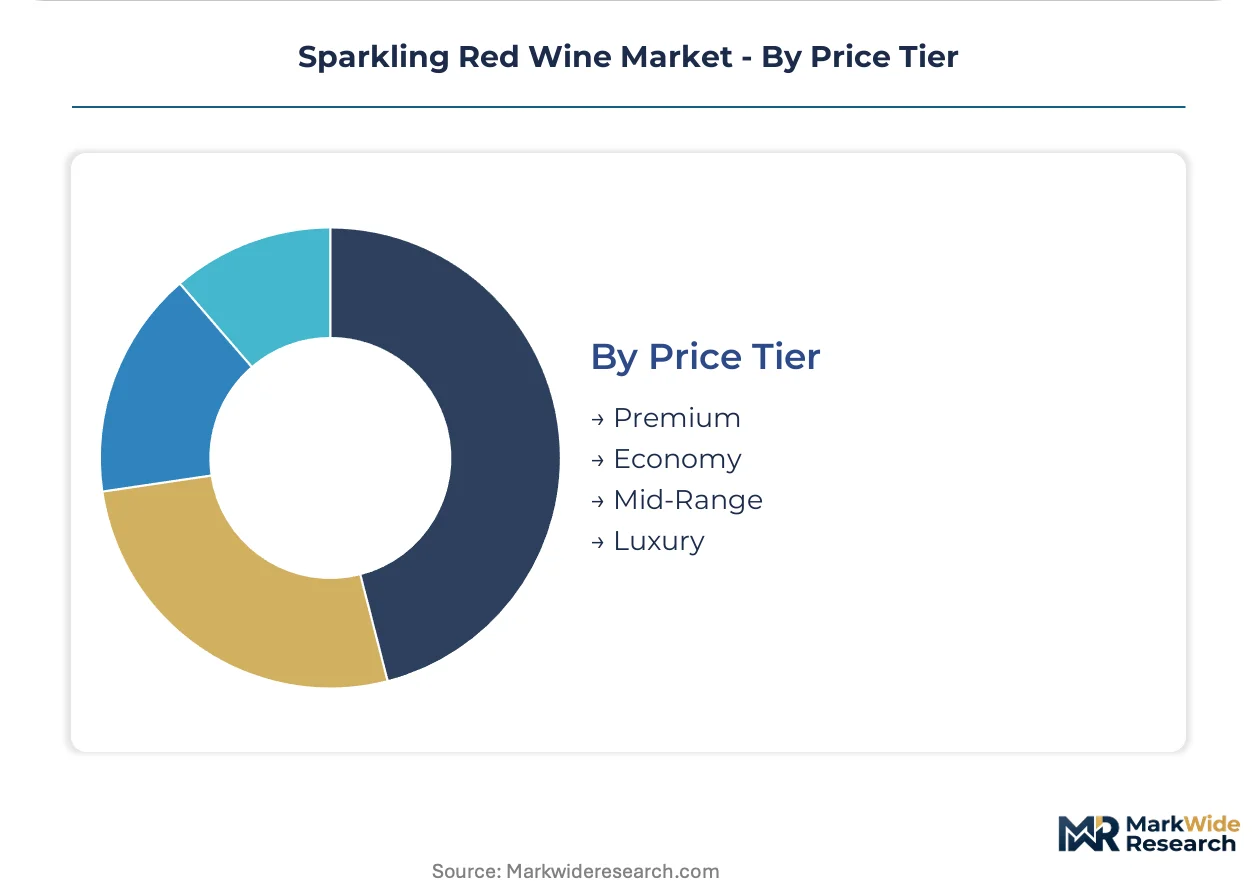
Price Tier:
Margin concentration patterns follow certification complexity and production method investment requirements.
- Premium:Extended lees aging and single-vineyard sourcing justify elevated positioning above mass-market tiers. DOC-protected traditional methods anchor authenticity premiums in export markets.
- Economy:Charmat tank fermentation systems enable competitive price positioning through scaled production. Lambrusco DOC volume exports concentrate in this accessible tier.
- Mid-Range:Bridge positioning captures estate-bottled programs without extended aging investment. Quality perception variance challenges consistent margin defense.
- Luxury:Limited production runs and heritage estate narratives command collector-market pricing. Methode champenoise red sparkling programs from established houses anchor this tier.
Economy tier holds dominant volume share through Lambrusco export concentration, while Premium tier gains share fastest through direct-to-consumer channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA and DG Agriculture frameworks under the EU Green Deal anchor regulatory gravity for sparkling red wine trade, with Italian production clusters facing the steepest compliance ramps as carbon-accounting deadlines approach.
United States
TTB labeling requirements and state-level distribution laws fragment market access for foreign producers seeking grocery placement across multiple jurisdictions. FDA and Alcohol and Tobacco Tax and Trade Bureau compliance costs favor established importers with dedicated regulatory affairs capacity. California's Sonoma County cooler sub-AVAs sustain sparkling red experimentation through precision fermentation infrastructure.
Italy
EU geographical indication protections enforce DOC/DOCG labeling standards that shape import eligibility and consumer trust in export markets. EU Green Deal carbon-accounting rules for agricultural inputs and packaging materials compress vineyard certification timelines for Emilia-Romagna producers. The Modena-Asti regional cluster concentrates authentic Lambrusco and Brachetto production with strong heritage positioning.
Germany
REACH compliance and EU Green Deal agricultural standards reshape import requirements for Italian sparkling red wines entering Central European retail channels. The country's national food safety regulator enforces strict documentation for carbon-accounted viticulture claims. Berlin and Hamburg anchor distribution concentration for premium-tier DOC-protected imports.
France
ANSM and national agricultural standards intersect with EU Green Deal frameworks to regulate sparkling red wine labeling and import protocols. Traditional methode champenoise producers face competitive pressure from Italian tank-fermented alternatives in casual consumption segments. Paris and Lyon metropolitan areas drive on-premise demand through boutique hospitality expansion.
Australia
TGA-equivalent food standards and national wine labeling regulations govern import eligibility for European sparkling red producers. Cool-climate experimental varietals from regional Victoria and Tasmania test market acceptance outside traditional Italian frameworks. Sydney and Melbourne urban coastal markets concentrate millennial buyer demand for direct-to-consumer heritage narratives.
Sparkling Red Wine Market Competitive Environment
Capability concentration sits with heritage estates and regulatory-compliant importers; scale advantage sits with mass-market distributors with bonded warehouse infrastructure. The vendor base organizes around three archetypes: DOC-protected Italian heritage producers, California experimental estates leveraging precision fermentation, and multi-brand portfolio houses with TTB compliance capacity. Dominant competitive moves include direct-to-consumer channel expansion and single-vineyard premium tier development.
Among California-based estates, Jackson Family Wines exemplifies the experimental archetype through cooler sub-AVA infrastructure deployment. E&J Gallo Winery occupies a position representing mass-market accessibility through controlled retail distribution scale. Korbel Champagne Cellars anchors heritage methode champenoise positioning against tank-fermented alternatives. These three entities collectively illustrate the competitive spectrum from premium authenticity to volume accessibility.
| Leading Market Players |
|---|
| Delicato Family Wines |
| Jackson Family Wines |
| E&J Gallo Winery |
| Korbel Champagne Cellars |
| Treasury Wine Estates |
| The Wine Group |
| Deutsch Family Wine & Spirits |
| Boisset Collection |
| Trinchero Family Wine & Spirits |
| Others |
Value Chain & Pricing Dynamics
Emilia-Romagna vineyard concentration anchors margin capture downstream through DOC-protected authenticity premiums that resist Charmat-method commoditization. Glass packaging and agricultural labor cost volatility in this Italian cluster compress mid-tier producer margins while premium single-vineyard programs extract pricing power through extended lees aging narratives.
Pricing Analysis
Geographic price spreads separate Modena-Asti heritage estates from California experimental producers by certification grade and method investment. Three-tier pricing structure across premium, standard, and economy levels stratifies by DOC protection status and lees aging duration. Pricing pressure stems from EU Green Deal compliance cost absorption in Emilia-Romagna. Economy-tier Lambrusco buyers exhibit highest price sensitivity; luxury methode champenoise collectors show least.
Supply Chain Analysis
Extended payment terms from bonded warehouse distributors in North America strain Italian exporter cash conversion cycles. Supply concentrates in Italy, California, and Australia for production; Germany and France for premium import distribution. Glass bottle, crown cap, and vineyard labor inputs face energy-price volatility exposure. Tariff exposure on aluminum packaging materials threatens can-format expansion. Distribution runs through three-tier wholesale relationships with TTB-compliant importers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat. EU geographical indication protections and TTB compliance capacity create switching costs that concentrate margin pools among established participants.
For Market Incumbents: Build certification moats through accelerated EU Green Deal vineyard recertification ahead of deadline compression. Anchor capacity in Sonoma County cooler sub-AVAs to capture precision fermentation quality convergence. Defend against direct-to-consumer disintermediation by acquiring subscription platform capabilities. For New Entrants and Emerging Players: Pursue white-space expansion in American grocery channels where authentic Lambrusco DOC placement remains sparse. Target millennial urban coastal markets through heritage narrative subscription models. Launch through TTB-compliant importer partnerships rather than direct wholesale builds. For Investors and Strategic Acquirers: Capital is best deployed toward DOC-protected Italian estates with carbon-accounted viticulture certification already achieved. Long-term viability favors producers with direct-to-consumer infrastructure and single-vineyard premium tier development. Watch EU Green Deal enforcement stringency as inflection signal for import eligibility disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Launch | Bypasses three-tier markups for Jackson Family Wines-style margin recovery in coastal urban markets. |
| EU Green Deal Certification Acceleration | Secures DOC labeling rights for Emilia-Romagna exporters before DG Agriculture deadline compression. |
| Single-Vineyard Premium Tier Introduction | Commands methode champenoise pricing power through extended lees aging narratives against tank-fermented volume. |
| Precision Fermentation Infrastructure Deployment | Collapses quality variance between Charmat and traditional methods for Sonoma County experimental estates. |
| TTB Compliance Capacity Buildout | Enables multi-jurisdiction retail placement for Italian heritage producers seeking American grocery channel access. |
Study Parameters
The analysis maps Lambrusco DOC, Brachetto DOCG, California experimental, and Australian cool-climate segments, each validated through vineyard operations directors, TTB compliance officers, boutique hospitality beverage directors, and direct-to-consumer platform managers. Primary interviews combined with secondary validation from EFSA regulatory filings, USDA agricultural databases, US TTB label approvals, and EU DG Agriculture carbon-accounting guidance. Bottom-up volume triangulation against top-down value estimation anchored forecast integrity.
Assumptions held EU Green Deal enforcement trajectory and three-tier distribution law stability fixed while varying direct-to-consumer adoption rates and precision fermentation technology diffusion. Segmentation modeled across product type, sales channel, packaging format, and price tier dimensions, with regional regulatory cluster as wine-industry-specific overlay. CAGRs derived from vintage-adjusted production volume trends and channel-shift elasticity coefficients. Forecast inputs incorporated vineyard expansion timelines in Emilia-Romagna and cooler sub-AVA temperature stability indices.
Sensitivities concentrate around EU Green Deal deadline acceleration and TTB labeling requirement amendments. Forecasts reflect assumptions of continued DOC protection enforcement and stable glass packaging supply. Macroeconomic contraction in premium hospitality, regulatory restriction on direct-to-consumer shipping, or breakthrough tank-method quality convergence would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Beer Dispensing Machine Market
Alcoholic Beverages
Middle East and Africa Beer Market
Alcoholic Beverages
Europe Wine Coolers Market
Alcoholic Beverages
Pub Cellar Equipment Market
Alcoholic Beverages
Asia-Pacific Alcohol E-Commerce Market
Alcoholic Beverages
Fermented Beverages Market
Alcoholic Beverages
Japan Tequila Market
Alcoholic Beverages
Kegs Market
Alcoholic Beverages
South Africa Tequila Market
Alcoholic Beverages
Edible Alcohol Market
Alcoholic Beverages
Malaysia Alcohol E-Commerce Market
Alcoholic Beverages
Liqueurs Market
Alcoholic Beverages
CBD Wine Market
Alcoholic Beverages
Wine Enzymes Market
Alcoholic Beverages
Herbal Distillates Market
Alcoholic Beverages
Alcohol Gummies Market