
 Fruit Wine Market | 2026-2036
Fruit Wine Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit Wine Market Analysis
China's Ningxia province is reshaping competitive dynamics through concentrated goji and wolfberry wine production capacity. Ningxia Xueyan anchors regional supply with specialized desert-fruit fermentation infrastructure. Wuliangye leverages its spirits distribution network to extend into fruit wine channels. Beijing Shunxing Halewood Alcoholic Beverages competes through premium positioning in northern China hospitality markets.
Fruit wine denotes fermented alcoholic beverages produced from non-grape pomaceous, drupe, or berry fruits, typically achieving 5-14% ABV through controlled yeast fermentation of fruit sugars without grain-based distillation. Apple wine leads volume production due to raw material abundance and shorter fermentation cycles, while cherry wine commands premium price tiers through limited supply and higher tannin complexity. E-commerce sales channels represent the fastest-expanding distribution vector, though specialty stores retain margin concentration through curated tasting experiences and direct producer relationships.
China's SAMR enforces GB standards for fruit wine labeling and alcohol content disclosure, while NMPA oversight of health-related marketing claims constrains promotional strategies. Japan's METI and JIS standards govern import quality thresholds for foreign fruit wine entry. Stakeholders must monitor evolving low-alcohol taxation frameworks and carbon-footprint disclosure requirements that will determine competitive access across East Asian markets.
Market Dynamics
East Asian regulatory tightening around labeling transparency and alcohol content disclosure is compressing formulation flexibility while simultaneously advantaging producers with established compliance infrastructure and testing capabilities.
Growth Catalysts
- NMPA labeling enforcement:China's SAMR implementation of GB standards for fruit wine alcohol content disclosure is eliminating substandard competitors and consolidating shelf space for compliant producers in tier-one cities.
- Desert-fruit fermentation infrastructure:Ningxia province's concentrated goji and wolfberry processing capacity is creating regionally differentiated supply with unique terroir positioning for hospitality channels.
- E-commerce channel expansion:Direct-to-consumer platforms are bypassing traditional three-tier distribution, enabling smaller producers to access urban clusters previously controlled by established distributors.
Market Restraints
- Raw material seasonality:Cherry and berry harvest windows concentrate input availability into 8-12 week periods, forcing producers to maintain expensive cold-storage inventory or accept quality inconsistency.
- Supply concentration in Ningxia:Over 60% of China's goji wine fermentation capacity sits within 200 kilometers of Yinchuan, creating geographic vulnerability to climate events and water allocation disputes.
- Grain-spirit substitution threat:Baijiu producers leveraging existing distribution networks can undercut fruit wine price positioning in northern China hospitality markets through volume-based rebate structures.
Strategic Opportunities
- Low-alcohol taxation frameworks:Pending revisions to Japan's liquor tax structure for beverages under 10% ABV would compress price gaps with beer and chuhai, opening metropolitan Tokyo and Osaka convenience channels.
- Carbon-footprint disclosure requirements:Early compliance with emerging MEE guidelines for alcoholic beverage environmental labeling would secure preferential access to state-owned enterprise procurement in China's public hospitality sector.
- Hybrid fermentation protocols:Converging precision temperature control with native yeast strain banking enables terroir-specific product differentiation without geographic relocation of production assets.
Industry Challenges
- Certification timeline compression:NMPA health claim review cycles for functional fruit wine positioning now extend 14-18 months, delaying product launches and consuming working capital.
- Legacy distribution integration:Spirits-dominant wholesalers lack temperature-controlled logistics expertise required for fruit wine quality preservation, forcing producers to duplicate infrastructure or accept spoilage risk.
- Enologist specialization scarcity:Formal training programs for non-grape fermentation science remain underdeveloped across East Asian universities, constraining quality consistency at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit Wine Market |
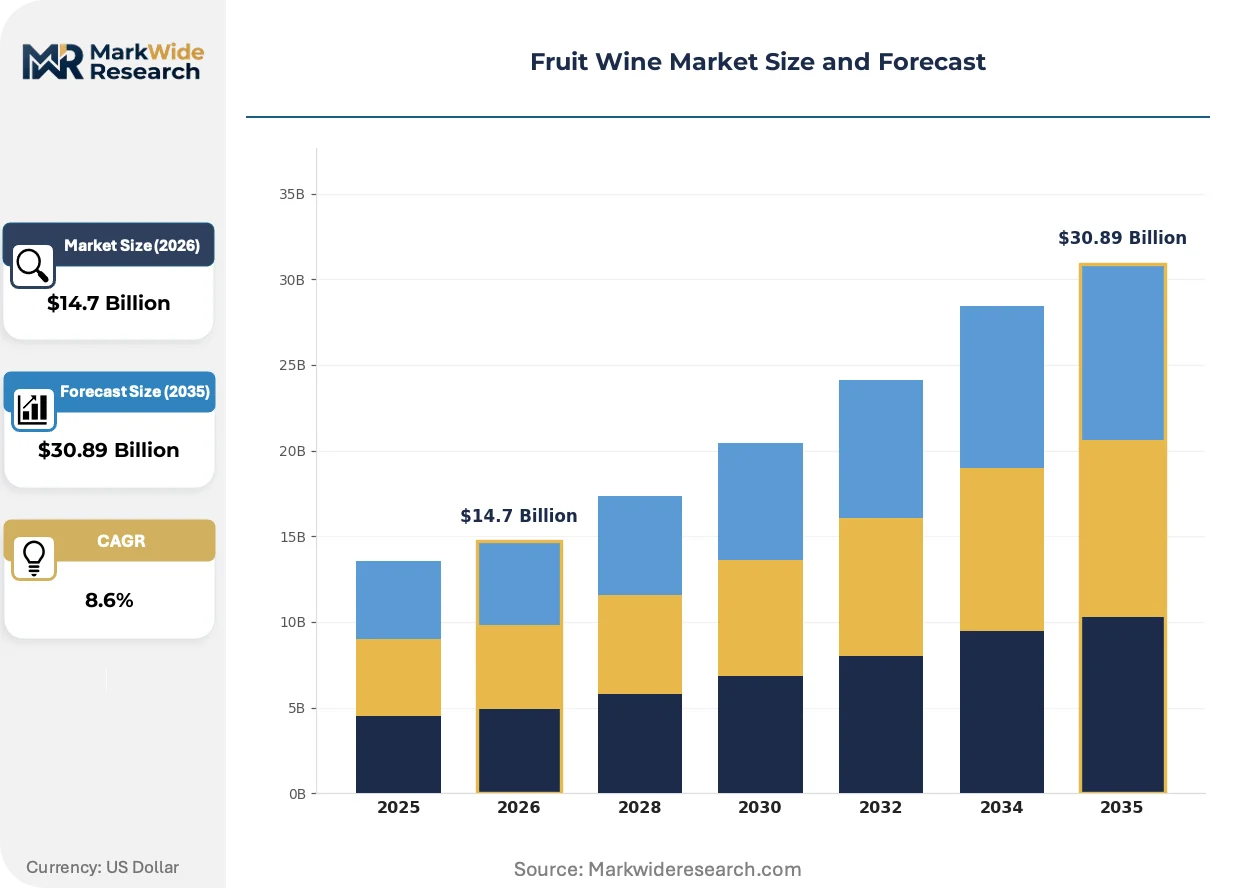
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apple Wine, Pear Wine, Cherry Wine, Peach Wine End User: Restaurants, Retail Outlets, E-commerce, Events Sales Channel: Online, Supermarkets, Specialty Stores, Direct Sales Price Tier: Premium, Mid-Range, Budget, Luxury |
| Companies Covered | 12Ling, Ningxia Xueyan, Bruntys, Wangshi, Beijing Shunxing Halewood Alcoholic Beverages, Jiangzhong Qinong, Zhongbo Green Technology, Wuliangye, Ningxia Hong, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit Wine Market Emerging Trajectories
Controlled-atmosphere fermentation technology is migrating from industrial-scale facilities toward mid-capacity producers, altering the economics of small-batch quality consistency and enabling geographic diversification of supply.
Precision temperature control systems with real-time dissolved oxygen monitoring are migrating from champagne houses and industrial beer facilities into dedicated fruit wine operations. Mid-tier producers in China's Shandong and Japan's Yamanashi prefectures are adopting these systems at 15-20% annual replacement rates for legacy tank infrastructure. This technology migration from capital-intensive to accessible scale is compressing quality variance between premium and standard price tiers.
China's evolving GB standards for alcoholic beverages are tightening permissible additive disclosure and mandating ingredient traceability back to county-level origin. The industrial consequence is forced consolidation among formulators reliant on flavor masking and color stabilization compounds. Fruit wine categories with simpler ingredient decks, particularly apple and pear variants, are responding fastest through supply chain digitization and blockchain-enabled provenance documentation.
Hospitality procurement patterns are fragmenting away from single-source annual contracts toward quarterly rotating portfolios that emphasize regional storytelling and limited releases. Specialty retailers and independent restaurants in Shanghai, Beijing, and Tokyo are displacing volume-commitment purchasing with curated allocation models. This behavioral shift is most visible in China's tier-one cities, where distributor influence over menu placement is weakening relative to sommelier-driven discovery platforms.
Fruit Wine Market Segmentation
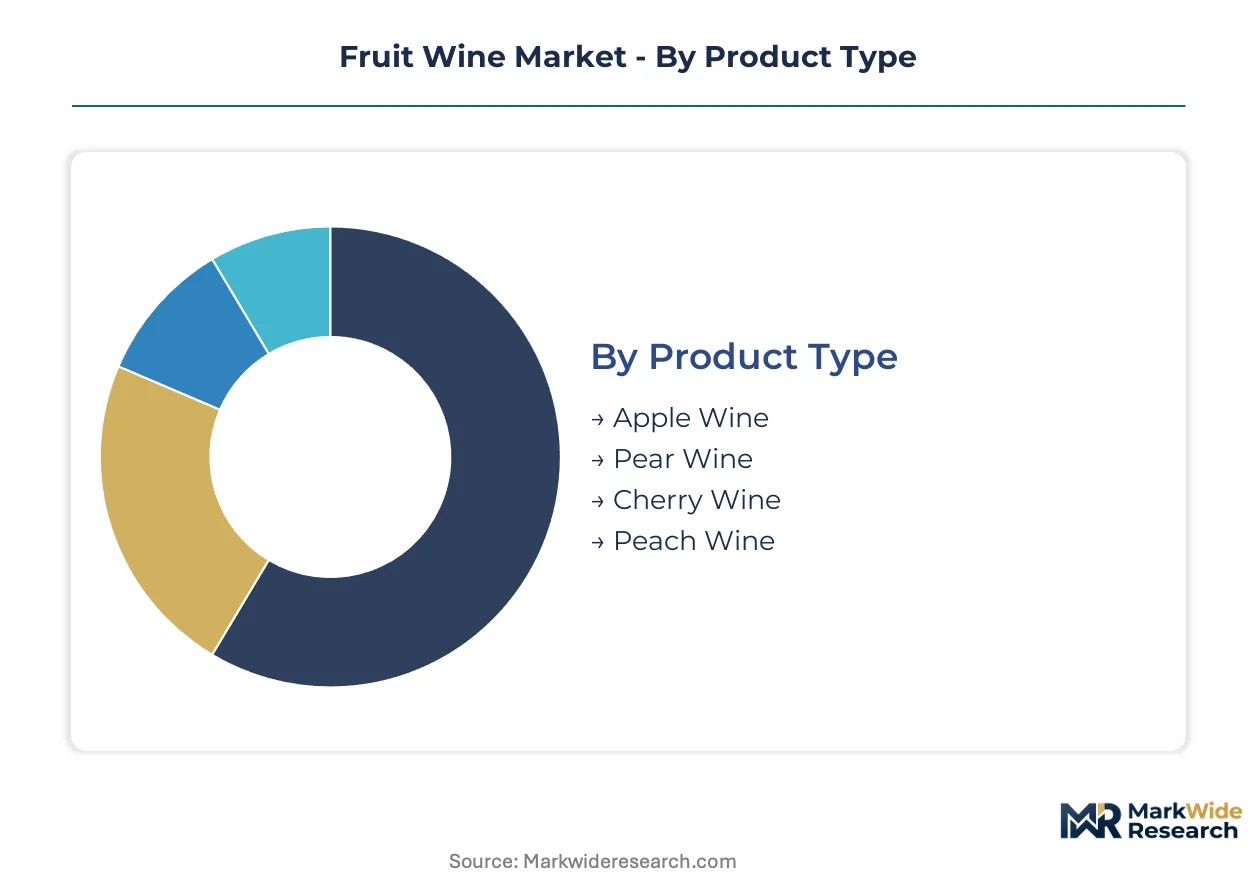
Fruit wine segmentation reveals distinct consumption occasions and channel economics that determine formulation priorities and margin capture. Producers must align product development with specific end-user temperature requirements, shelf-life constraints, and service protocols.
Product Type:
Apple and pear wines dominate volume through raw material abundance, while cherry and peach variants command differentiated positioning in hospitality and gifting channels.
- Apple Wine:Fermented from pomaceous fruit with 5-12% ABV, achieving shorter fermentation cycles than stone-fruit alternatives. China's Shandong province anchors supply through concentrated orchard infrastructure, with demand concentrating in northern China casual dining where price accessibility drives volume.
- Cherry Wine:Produced from tart and sweet cherry varietals with elevated tannin complexity and deeper color extraction. Limited harvest windows in Japan's Yamanashi prefecture and Michigan's Great Lakes region constrain supply, positioning this segment for premium tier-one city hospitality and anniversary gifting occasions.
- Pear Wine:Delicate aromatic profile from European and Asian pear cultivars, requiring precise temperature control during fermentation to preserve volatile compounds.
- Peach Wine:Stone-fruit fermentation yielding higher residual sugar potential, popular in southern China seasonal consumption and summer festival distribution.
Established volume favors apple wine; emerging adoption favors cherry wine in premium hospitality allocation.
End User:
Channel requirements fragment around temperature control sophistication, with restaurants demanding consistent quality at scale while e-commerce prioritizes packaging durability and direct consumer education.
- Restaurants:Full-service and casual dining establishments with dedicated beverage programs and sommelier-driven procurement. Shanghai and Beijing tier-one clusters concentrate demand, where quarterly rotating portfolios displace annual volume contracts and regional storytelling determines menu placement.
- E-commerce:Direct-to-consumer platforms and marketplace aggregators bypassing traditional three-tier distribution. This channel climbs fastest through live-streaming commerce in China's urban clusters, enabling smaller producers to access previously distributor-controlled markets without hospitality intermediary margins.
- Retail Outlets:Supermarkets, hypermarkets, and convenience stores with standardized shelving and promotional slotting fees.
- Events:Festival vending, corporate hospitality, and wedding catering with seasonal demand spikes and temporary permitting requirements.
Margin concentration sits with restaurants; volume expansion favors e-commerce penetration.
Sales Channel:
Channel economics diverge sharply between curated discovery environments and mass-market efficiency plays, with specialty stores retaining margin through direct producer relationships.
- Specialty Stores:Dedicated wine retailers and regional beverage shops with temperature-controlled storage and staff training programs. Tokyo's Shinagawa ward and Shanghai's former French Concession concentrate this channel, where tasting events and producer exclusives justify 25-40% markup over supermarket benchmarks.
- Online:Brand-owned direct sales and third-party marketplace presence with logistics partnerships for last-mile cold chain. China's JD.com and Tmall platforms anchor this channel, where subscription models and limited-release drops build consumer loyalty without retail slotting fees.
- Supermarkets:Mass-market grocery chains with standardized planograms and promotional calendar dependency.
- Direct Sales:Winery tasting rooms, membership clubs, and hospitality-integrated estate experiences with highest margin capture but geographic constraint.
Supermarkets anchor volume throughput; specialty stores defend margin through curation.
Price Tier:
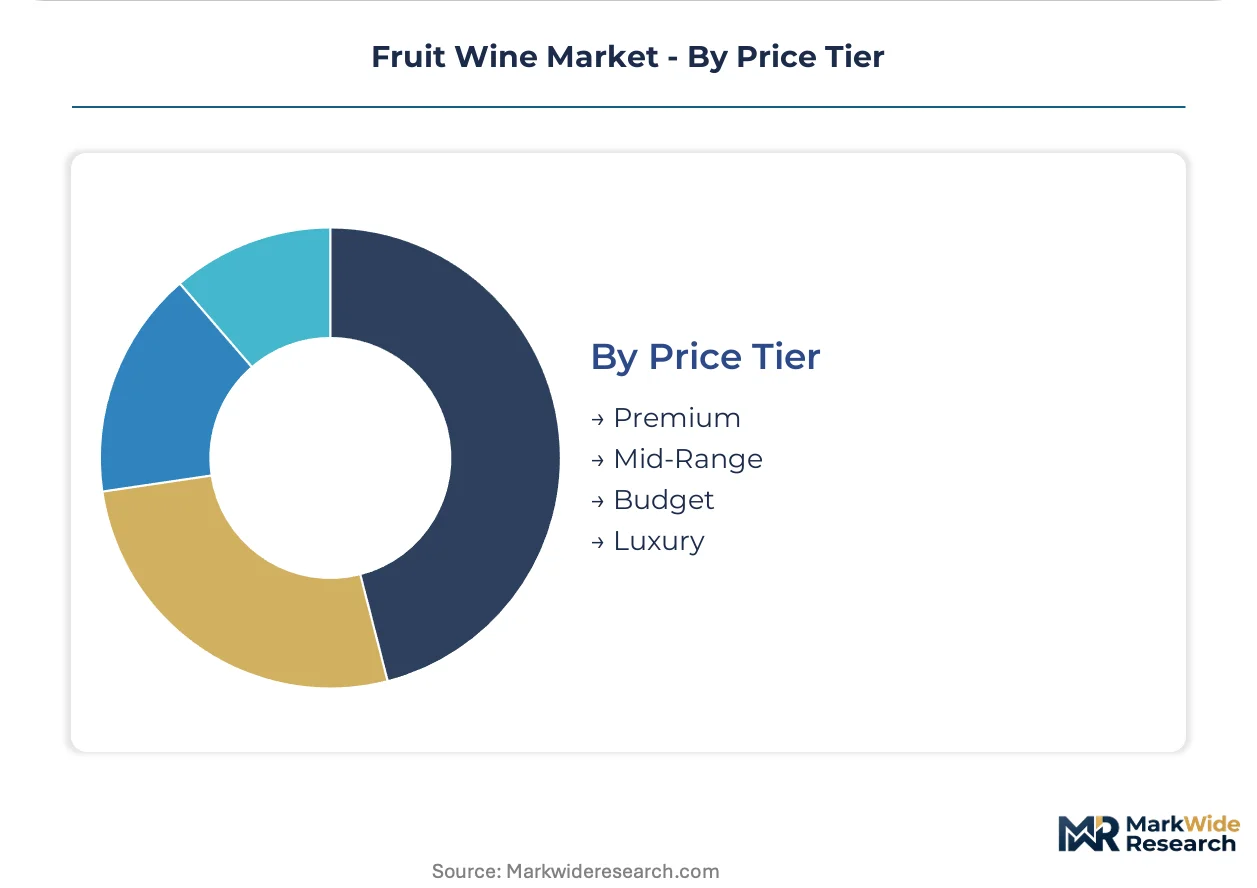
Price stratification reflects input cost structure, aging protocol, and packaging investment, with luxury tiers leveraging terroir documentation and limited production claims.
- Premium:Positioned above mass-market benchmarks through single-fruit sourcing, extended lees contact, or oak adjuncts. Ningxia's goji wine producers and Japanese Yamanashi cherry specialists occupy this tier, with demand concentrating in Beijing and Tokyo business dining where origin documentation influences selection.
- Luxury:Ultra-premium positioning through estate bottling, vintage declaration, and numbered releases with blockchain provenance. China's state-owned enterprise hospitality procurement and Tokyo's Michelin-tier restaurants concentrate demand, where carbon-footprint disclosure and MEE environmental labeling compliance increasingly gate access.
- Mid-Range:Blended fruit sources with standardized production protocols and regional distribution focus.
- Budget:Price-competitive positioning through bulk fermentation, minimal aging, and private-label supermarket supply.
Mid-range captures volume scale; luxury commands expansion in compliance-forward procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR labeling enforcement in China is compressing formulation flexibility while simultaneously advantaging producers with established compliance infrastructure and testing capabilities across East Asian markets.
China
GB standards for fruit wine alcohol content disclosure and NMPA health claim oversight are eliminating substandard competitors in tier-one cities. Ningxia province anchors over 60% of national goji wine fermentation capacity within 200 kilometers of Yinchuan, creating geographic vulnerability to climate events and water allocation disputes.
Japan
METI and JIS standards govern import quality thresholds for foreign fruit wine entry, with pending liquor tax revisions for beverages under 10% ABV threatening to compress price gaps with beer and chuhai. Yamanashi prefecture concentrates cherry wine production through limited harvest windows and elevated tannin complexity positioning.
United States
FDA labeling requirements and state-level alcohol beverage control frameworks shape distribution economics, with Michigan's Great Lakes region supplying tart cherry varietals constrained by seasonal harvest concentration. E-commerce direct-to-consumer platforms bypass traditional three-tier distribution in metropolitan clusters.
Germany
EU Green Deal carbon-footprint disclosure requirements and REACH additive regulations are tightening permissible formulation inputs for imported fruit wine. Precision temperature control systems migrate from champagne houses into mid-capacity producers, altering small-batch quality consistency economics.
South Korea
MFDS alcoholic beverage standards and evolving low-alcohol taxation frameworks determine competitive access, with metropolitan Seoul and Busan convenience channels representing expansion targets for sub-10% ABV products. Subscription models and limited-release drops build consumer loyalty without retail slotting fees.
Fruit Wine Market Vendor Landscape
Capability concentration sits with specialized fermentation infrastructure operators; scale advantage sits with diversified beverage conglomerates leveraging existing distribution networks. The market exhibits tiered structure with desert-fruit specialists, spirits-derived entrants, and hospitality-integrated premium positioners competing through distinct channel access. Strategic archetypes include Ningxia-based terroir specialists, multi-category beverage distributors extending into fruit wine, and northern China hospitality-focused premium marketers. Dominant competitive moves center on e-commerce channel expansion bypassing traditional three-tier distribution and compliance-forward positioning securing state-owned enterprise procurement access.
Within the specialized fermentation tier, Ningxia Xueyan anchors regional supply with desert-fruit infrastructure positioning, while Beijing Shunxing Halewood Alcoholic Beverages occupies premium hospitality allocation in northern China markets. Wuliangye represents the diversified conglomerate archetype extending spirits distribution networks into fruit wine channels through volume-based rebate structures.
| Leading Market Players |
|---|
| 12Ling |
| Ningxia Xueyan |
| Bruntys |
| Wangshi |
| Beijing Shunxing Halewood Alcoholic Beverages |
| Jiangzhong Qinong |
| Zhongbo Green Technology |
| Wuliangye |
| Ningxia Hong |
| Others |
Supply Flow & Price Mechanics
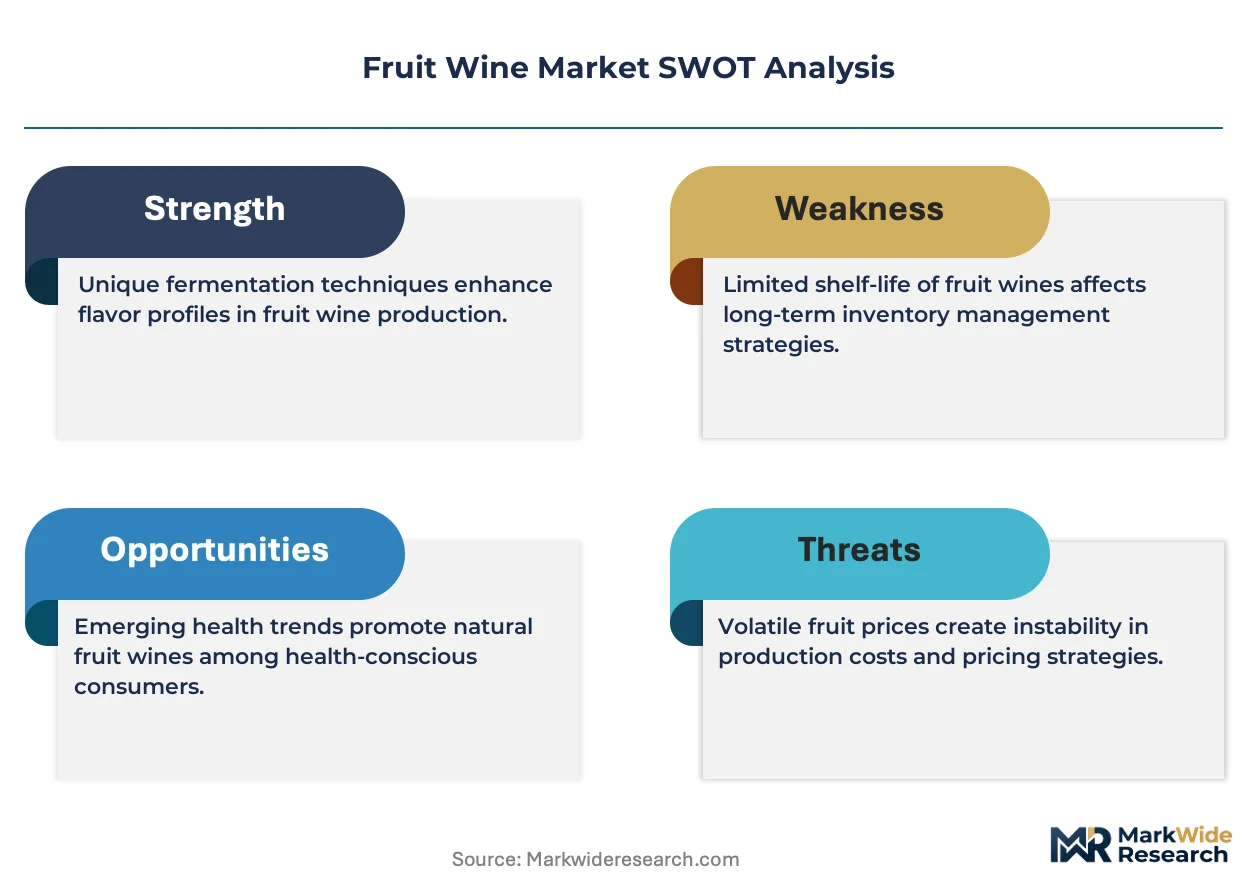
Ningxia province's concentrated goji wine fermentation capacity within 200 kilometers of Yinchuan creates asymmetric pricing power for desert-fruit specialists, while downstream hospitality buyers in Beijing and Tokyo face limited alternative sourcing for terroir-positioned products. This geographic concentration enables producers to command premium positioning through scarcity claims, though climate vulnerability and water allocation disputes introduce cost volatility that compresses margins for non-integrated operators.
Pricing Analysis
Price spreads between Yinchuan-origin goji wines and Shandong apple wines reflect terroir certification premiums and limited harvest windows rather than production cost differentials alone. Three-tier pricing structure across premium, standard, and economy levels separates estate-bottled luxury releases from blended mid-range offerings and private-label supermarket supply. Pricing pressure stems from baijiu producers leveraging volume-based rebate structures to undercut fruit wine positioning in northern China hospitality markets. Budget-tier buyers in casual dining channels exhibit highest price sensitivity, while Michelin-tier procurement in Tokyo shows lowest sensitivity to origin-documentation premiums.
Supply Chain Analysis
Extended payment terms from hospitality distributors force mid-cap producers to rely on supply-chain finance facilities, elevating working capital costs and favoring conglomerates with captive treasury functions. Raw material sourcing draws from China's Shandong apple orchards, Japan's Yamanashi cherry cultivars, and Ningxia's desert-fruit plantations. Distribution runs through e-commerce platforms bypassing traditional three-tier systems, though specialty retailers retain margin concentration through direct producer relationships. Single-source vulnerability concentrates in Ningxia's water-dependent goji processing infrastructure, where climate events threaten input availability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized enologist training for non-grape fermentation science remains underdeveloped across East Asian universities, constraining quality consistency and creating capability scarcity that advantages early movers in precision temperature control infrastructure.
For Market Incumbents: Insulate market position by securing backward integration into cold-storage inventory systems that buffer cherry and berry harvest seasonality, and accelerate NMPA compliance certification to eliminate substandard competitors from tier-one city shelf space. Threats from baijiu substitution through volume rebate structures demand defensive channel control in northern China hospitality markets. For New Entrants and Emerging Players: Establish a beachhead in Japan's sub-10% ABV convenience channel ahead of pending liquor tax revisions, leveraging direct-to-consumer platforms to bypass distributor-controlled urban clusters. White-space targets include carbon-footprint-compliant procurement for China's state-owned enterprise hospitality sector and live-streaming commerce penetration in Shanghai's tier-one consumer base. Go-to-market execution should emphasize blockchain-enabled provenance documentation to satisfy emerging MEE environmental labeling requirements. For Investors and Strategic Acquirers: Carve-out targets emerge from spirits conglomerates seeking to divest non-core fruit wine assets amid grain-spirit substitution pressures. Long-term viability hinges on acquisition of specialized fermentation infrastructure with native yeast strain banking capabilities, rather than distribution-network rollups lacking temperature-controlled logistics expertise. The signal to watch is NMPA certification timeline compression, where 14-18 month health claim review cycles will strain working capital and force distressed exits.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Temperature Control Adoption | Mid-tier producers in Shandong and Yamanashi compress quality variance through champagne-house technology migration. |
| Blockchain Provenance Documentation | GB standards compliance for county-level ingredient traceability gates access to state-owned enterprise procurement. |
| E-commerce Channel Expansion | JD.com and Tmall platforms enable smaller producers to bypass traditional three-tier distribution in urban clusters. |
| Carbon-Footprint Labeling Compliance | Early MEE guideline adherence secures preferential access to public hospitality sector allocation. |
| Native Yeast Strain Banking | Terroir-specific differentiation without geographic relocation of production assets alters competitive economics. |
Methodological Framework
The analysis maps apple, cherry, pear, peach, and goji wine sub-sectors, each validated through fermentation scientists, hospitality procurement directors, e-commerce platform category managers, and NMPA regulatory consultants. Primary interview data triangulates against secondary sources including SAMR GB standard filings, NMPA health claim registration databases, METI liquor tax revision notices, and customs trade records for fruit wine imports. Bottom-up volume modeling from producer capacity and top-down demand estimation from channel consumption patterns converge through iterative reconciliation.
Assumptions around NMPA enforcement intensity, Japan's liquor tax revision timing, and climate stability in Ningxia were held fixed across scenarios, while e-commerce penetration rates and carbon-footprint disclosure adoption were varied. Segmentation dimensions modeled include fruit type, ABV tier, end-user channel, and price positioning across the projection horizon. CAGRs derive from logistic adoption curves fitted to historical channel shift patterns, with inputs from precision fermentation technology cost trajectories and hospitality procurement behavioral surveys.
Stress conditions across water allocation disputes in Ningxia, baijiu rebate escalation, and NMPA certification delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Coffee Beer Market
Alcoholic Beverages
Malt Whiskey Market
Alcoholic Beverages
Draught Beer Market
Alcoholic Beverages
Chocolate Liqueur Market
Alcoholic Beverages
Rice Wine Market
Alcoholic Beverages
Global Brewery Filtration Market
Alcoholic Beverages
Beer Stabilizers Market
Alcoholic Beverages
Europe Craft Beer Market
Alcoholic Beverages
Instant Wine Chillers and Refreshers Market
Alcoholic Beverages
Pinot Noir Market
Alcoholic Beverages
United States Spirits Market
Alcoholic Beverages
Asia-Pacific Spirits Market
Alcoholic Beverages
Tanzania Spirits Market
Alcoholic Beverages
Beer Dispensing Machine Market
Alcoholic Beverages
Liquor Flavored Ice Cream Market
Alcoholic Beverages
Lager Market