
 Smart Meat Thermometer Market | 2026-2036
Smart Meat Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Meat Thermometer Market Outlook
Catering services is repositioning toward precision-driven protein preparation, pulling demand from traditional home-cook segments into commercial kitchens and foodservice operations. ThermoPro leverages its manufacturing scale to dominate North American distribution channels. Meater anchors its competitive stance through smartphone integration and cloud-connected probe architectures. Weber extends its brand strength from grills into adjacent temperature monitoring categories.
A smart meat thermometer is a wireless temperature sensing device that transmits real-time internal and ambient heat data to smartphones or dedicated displays via Bluetooth or Wi-Fi, typically employing stainless steel probes rated for oven, grill, and smoker environments to ensure food safety and optimal doneness. Bluetooth product types currently lead volume shipments due to lower cost thresholds and simpler pairing protocols. Wi-Fi variants represent the fastest-growing product type as cloud connectivity enables remote monitoring across extended ranges. Smartphone integration technology captures the largest margin pool by locking users into proprietary apps with recipe libraries and alert systems.
FDA food code provisions and USDA FSIS guidelines govern commercial thermometer accuracy requirements in the United States, while CE marking and EU food contact material regulations shape product standards across European markets. FCC certification mandates radio frequency compliance for all wireless-enabled devices sold in the United States, adding a gatekeeping layer for new entrants. Stakeholders must monitor evolving cybersecurity standards for IoT kitchen devices as regulators begin scrutinizing data collection practices in connected home appliances.
Market Dynamics
The smart meat thermometer market is experiencing a structural pivot as professional kitchens and catering services displace home cooks as the primary volume buyers, driven by tightening FDA food code traceability mandates and the operational necessity of HACCP-compliant remote monitoring systems.
Growth Catalysts
- Bluetooth Low Energy protocols:Simplified pairing architectures reduce onboarding friction for commercial kitchen staff, accelerating deployment across high-turnover foodservice environments.
- FDA food safety modernization:Enhanced traceability requirements for protein preparation push institutional buyers toward connected temperature logging systems with audit-ready data trails.
- Outdoor cooking culture:Smoker and pellet grill enthusiasts in the United States and Germany are purchasing multi-probe systems for competitive barbecue circuits and weekend entertaining.
Market Restraints
- Stainless steel probe supply concentration:Precision thermistor manufacturing clusters in East Asian foundries, creating single-source vulnerability for North American and European brands.
- Radio frequency certification costs:FCC Part 15 compliance testing for each SKU variant imposes fixed costs that disproportionately burden smaller entrants.
- Smartphone dependency:Reliance on proprietary apps for core functionality exposes users to OS update fragility and manufacturer abandonment risk.
Strategic Opportunities
- Cloud recipe integration:Convergence of temperature telemetry with AI-guided cooking algorithms creates subscription revenue potential for appliance ecosystems.
- Commercial foodservice underpenetration:Independent restaurants and institutional cafeterias in Germany represent untapped deployment potential for multi-node monitoring networks.
- EU cybersecurity labeling:Emerging CE marking extensions for IoT kitchen devices will favor early-compliant vendors in European procurement channels.
Industry Challenges
- Calibration drift management:Foodservice operators lack in-house metrology capabilities to verify probe accuracy against NIST-traceable standards.
- Cross-platform integration complexity:Commercial kitchen management systems require API standardization that thermometer OEMs have not uniformly adopted.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Meat Thermometer Market |
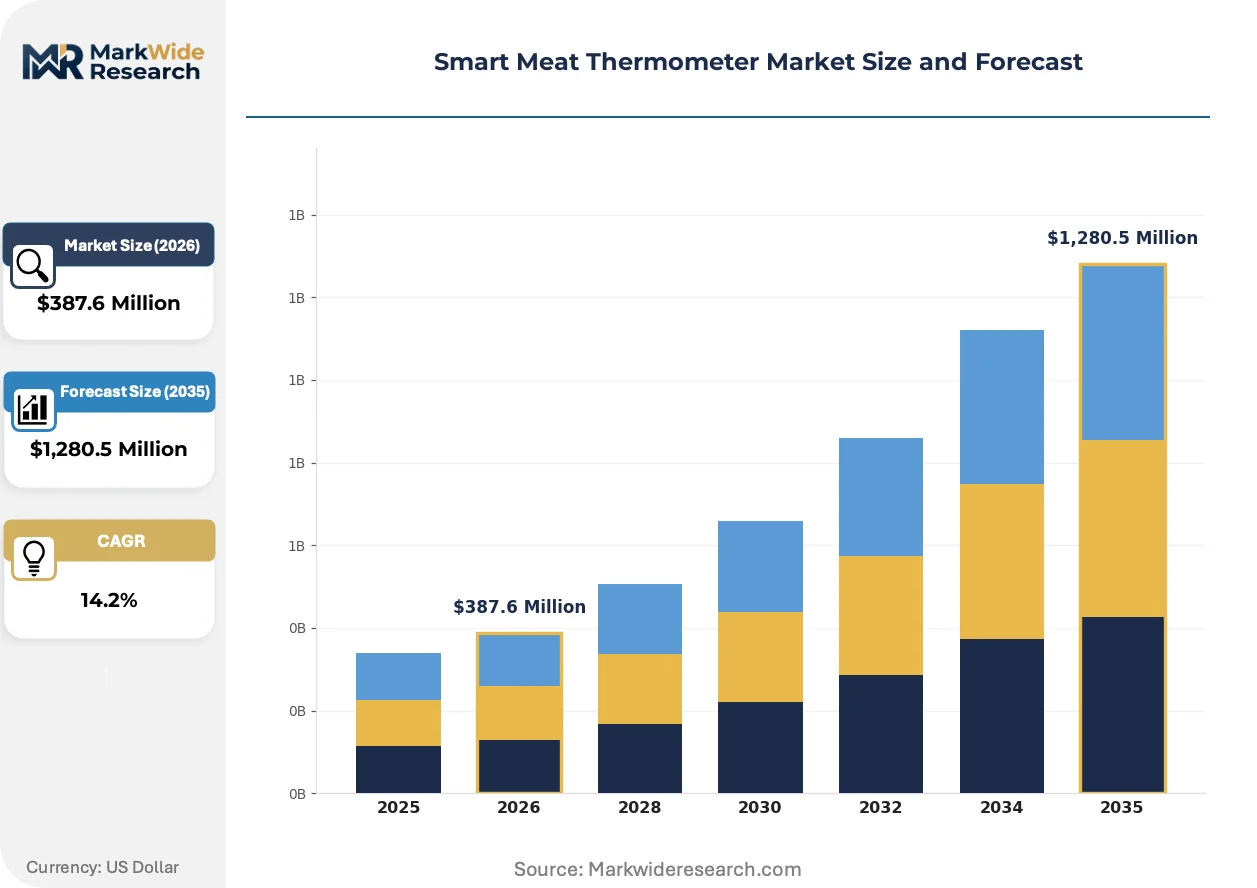
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bluetooth, Wi-Fi, Infrared, Probe Technology: Smartphone Integration, Cloud Connectivity, Voice Control, Sensor Technology End User: Home Cooks, Professional Chefs, Grill Enthusiasts, Catering Services Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | ThermoPro, Meater, MeatStick, ThermoWorks, Inkbird, Yummly, Weber, OXO, Chef iQ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Meat Thermometer Market Strategic Shifts
Wireless connectivity architectures and regulatory compliance frameworks are actively reshaping product development roadmaps, with vendors racing to embed predictive algorithms and hardened cybersecurity before standards crystallize.
Multi-sensor probe arrays is absorbing ambient heat, internal protein temperature, and humidity data simultaneously into unified dashboards. High-volume catering operators in the United States are adopting these systems at accelerated refresh cycles. This convergence is absorbing standalone hygrometer and timer categories into consolidated monitoring platforms.
EU cybersecurity certification schemes for connected kitchen appliances are mandating encrypted data transmission and user consent architectures before CE marking issuance. Manufacturers serving European markets must redesign firmware stacks to satisfy these pre-market requirements. Wi-Fi enabled product lines face the steepest compliance burden due to persistent cloud connectivity.
Direct-to-commercial distribution models are displacing traditional retail intermediaries as institutional buyers seek volume pricing and dedicated support contracts. Foodservice distributors in China are building dedicated smart appliance procurement divisions to capture this shift. Catering conglomerates now specify connected thermometers in centralized equipment tenders rather than leaving decisions to individual kitchen managers.
Smart Meat Thermometer Market Segmentation
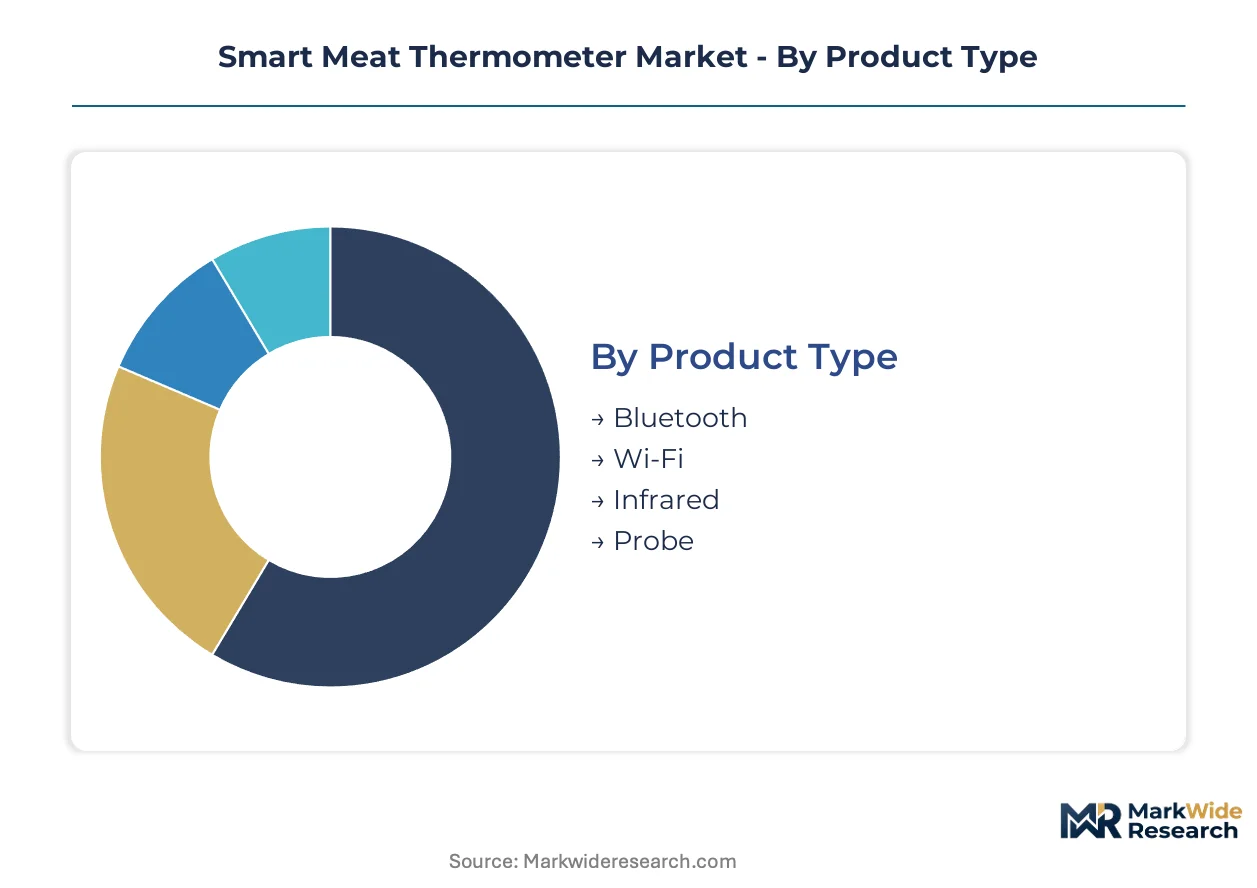
Segmentation in the smart meat thermometer market reveals how connectivity protocols and user environments dictate procurement patterns. Buyers sort themselves by technical sophistication, operational scale, and integration requirements rather than price alone.
Product Type:
Manufacturing scale clusters around radio-enabled architectures, with probe fabrication and wireless module sourcing determining competitive positioning.
- Bluetooth:Low Energy protocols dominate current volume shipments through simplified pairing and reduced hardware costs. Home cooks in the United States and Germany purchase these units for weekend grilling sessions where range limitations pose minimal constraint.
- Wi-Fi:Cloud-enabled architectures extend monitoring range beyond Bluetooth boundaries while enabling persistent data logging. Professional kitchens and catering services in China are adopting these systems fastest, driven by HACCP compliance documentation requirements.
- Infrared:Non-contact surface temperature measurement serves grill enthusiasts verifying grate heat before protein placement.
- Probe:Stainless steel thermistor assemblies constitute the core sensing element across all connected product lines.
Today's leader: Bluetooth. Tomorrow's challenger: Wi-Fi.
Technology:
Margin capture concentrates where vendors lock users into proprietary ecosystems through recurring engagement mechanisms.
- Smartphone Integration:Dedicated applications with recipe libraries and alert systems generate the highest margin pools by creating switching costs. FDA food code traceability mandates push institutional buyers toward platforms with audit-ready data export.
- Cloud Connectivity:Persistent telemetry storage enables predictive algorithm deployment and subscription revenue potential. FCC Part 15 certification requirements impose fixed compliance costs that favor established vendors with certification expertise.
- Voice Control:Hands-free operation appeals to professional chefs managing multiple cooking stations simultaneously.
- Sensor Technology:Multi-sensor arrays combining internal temperature, ambient heat, and humidity data absorb standalone timer and hygrometer categories.
Smartphone Integration commands current margins. Cloud Connectivity opens recurring revenue paths.
End User:
Demand gravity is shifting from residential purchasers toward commercial operators as regulatory compliance tightens.
- Professional Chefs:High-turnover kitchen environments require ruggedized hardware with simplified onboarding protocols. Bluetooth Low Energy pairing architectures reduce training burden for rotating staff.
- Catering Services:Volume protein preparation demands multi-probe systems with centralized dashboard monitoring. Centralized equipment tenders now specify connected thermometers rather than delegating to individual kitchen managers.
- Home Cooks:Weekend barbecue enthusiasts purchase single-probe units through online retail channels.
- Grill Enthusiasts:Competitive barbecue circuits in the United States drive demand for multi-probe smoker monitoring systems.
Catering Services anchor commercial volume. Professional Chefs set technical specifications.
Distribution Channel:
Channel strategy bifurcates between direct institutional procurement and retail intermediaries serving residential segments.
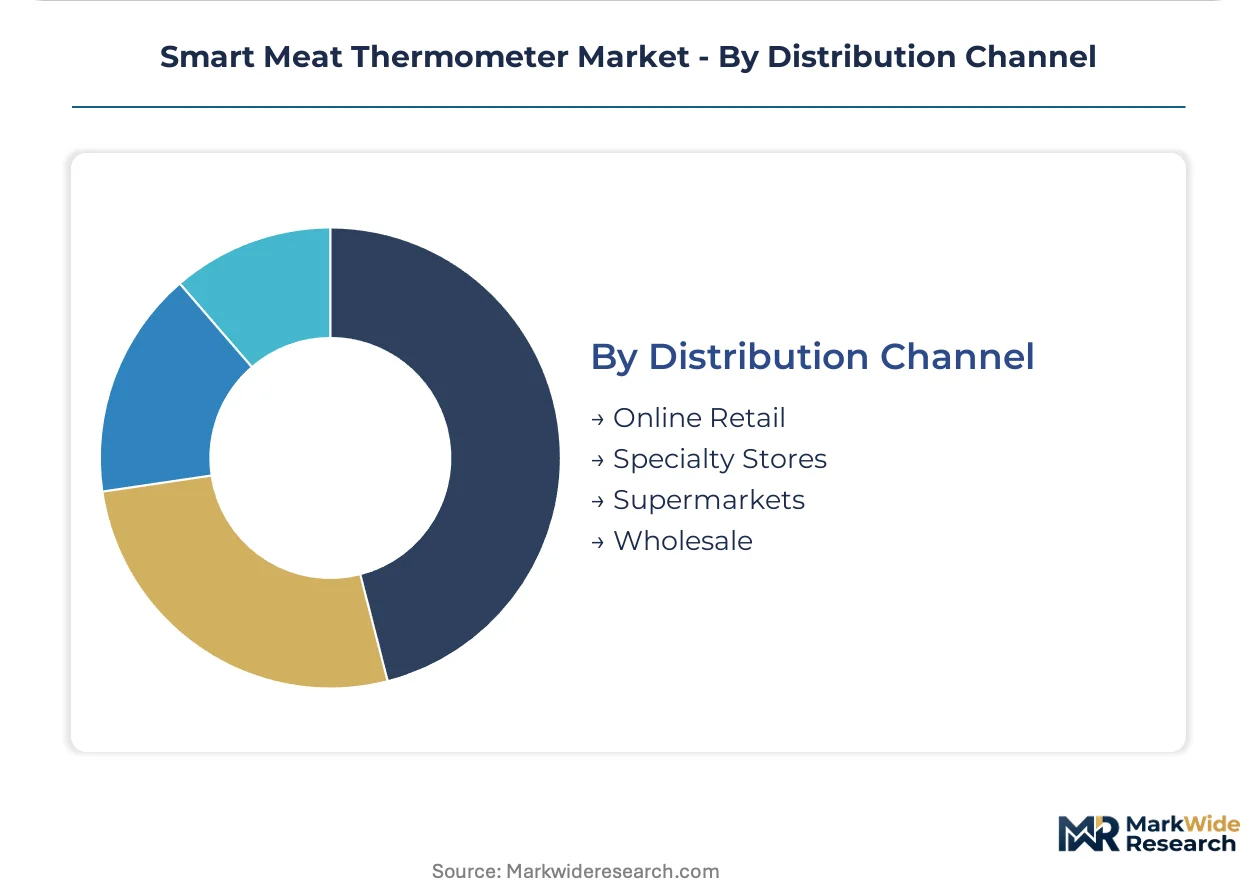
- Online Retail:E-commerce platforms capture residential demand through review-driven discovery and competitive pricing transparency.
- Specialty Stores:Outdoor cooking retailers in Germany and the United States provide hands-on demonstration for grill enthusiasts evaluating probe durability.
- Supermarkets:Mass merchandisers stock entry-level Bluetooth units adjacent to seasonal grilling merchandise.
- Wholesale:Foodservice distributors in China are building dedicated smart appliance procurement divisions to serve institutional buyers seeking volume pricing and support contracts.
Wholesale gains commercial share. Online Retail defends residential volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production footprints as manufacturers seek jurisdictions with streamlined FCC-equivalent certification pathways and lower radio-frequency testing burdens. FDA traceability mandates in the United States create compliance premiums that some producers offset through strategic facility placement.
United States
Professional kitchens and catering services in Texas and the Southeast are driving commercial procurement of Wi-Fi-enabled probe systems. FDA food code provisions and USDA FSIS guidelines enforce strict accuracy standards for protein temperature logging. Austin and Dallas-Fort Worth host expanding foodservice equipment distribution hubs serving institutional buyers.
Germany
Outdoor cooking culture in Bavaria and North Rhine-Westphalia sustains strong residential demand for Bluetooth thermometers with smartphone integration. CE marking and EU food contact material regulations govern probe safety standards across European distribution. The Stuttgart industrial corridor concentrates precision thermistor manufacturing for regional OEM supply.
China
Catering conglomerates in Shanghai and Guangzhou are accelerating adoption of cloud-connected multi-probe systems for HACCP documentation. MIIT radio transmission regulations and GB standards shape wireless device certification requirements. The Pearl River Delta anchors stainless steel probe fabrication clusters serving global brands.
Japan
High-end residential consumers in Tokyo and Osaka prioritize voice-controlled thermometer integration with smart kitchen ecosystems. METI energy efficiency guidelines and PMDA-adjacent quality protocols influence connected appliance standards. The Nagoya manufacturing belt supplies precision sensor components for domestic and export markets.
United Kingdom
Independent restaurants in London and Manchester are specifying connected thermometers in centralized procurement tenders. UK Food Standards Agency hygiene codes and post-Brexit product safety marking requirements create distinct compliance layers. The Midlands logistics corridor facilitates wholesale distribution to foodservice operators.
Smart Meat Thermometer Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with consumer-facing names dominating retail channels while OEM suppliers capture commercial volume. The structure tilts toward fragmentation at the low end and concentration among premium-tier players with proprietary app ecosystems. Three archetypes define positioning: ecosystem-locked specialists with cloud platforms, scale-driven hardware OEMs with manufacturing depth, and grill-brand extenders leveraging adjacent category equity. Competitive moves center on direct-to-commercial distribution bypass and multi-probe system portfolio expansion.
Among North American branded specialists, ThermoPro and Meater exemplify divergent strategic anchors—one representing manufacturing-scale dominance through distribution channel control, the other occupying the smartphone-native position through app-centric user lock-in. Weber sits within the brand-extension archetype, translating grill equipment equity into adjacent temperature monitoring categories without native wireless engineering heritage.
| Leading Market Players |
|---|
| ThermoPro |
| Meater |
| MeatStick |
| ThermoWorks |
| Inkbird |
| Yummly |
| Weber |
| OXO |
| Chef iQ |
| Others |
Value Chain & Pricing Dynamics
Stainless steel thermistor fabrication costs in East Asian foundries cascade through three pricing tiers before reaching end buyers, with FCC Part 15 certification expenses layering fixed overhead onto each SKU variant and compressing margins for smaller entrants competing against manufacturing-scale incumbents.
Pricing Analysis
Distributor margin stacking separates premium Wi-Fi systems from economy Bluetooth units, with certification grade and volume scale driving the primary price differentiation. Three-tier pricing structure across premium, standard, and economy levels reflects probe accuracy tolerances and cloud connectivity depth. Cost compression in the entry tier is intensifying because direct-to-commercial procurement bypasses traditional retail markups. Home cooks exhibit highest price sensitivity, while catering services prioritize audit-ready data trails over unit economics.
Supply Chain Analysis
Precision thermistor supply rests on Japanese and German specialty component producers, with stainless steel probe assembly concentrating in China and South Korea. Raw material dependencies span nickel-chromium alloys, wireless radio modules, and food-grade polymer insulation. Single-source vulnerability in East Asian foundries creates procurement risk for North American brands. Distribution runs through foodservice wholesalers for commercial volume and e-commerce platforms for residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart meat thermometer market represents a late-cycle quality story as HACCP compliance mandates displace home-cook demand with institutional procurement of premium-specification multi-probe systems.
For Market Incumbents: Hedge against smartphone dependency fragility by diversifying into dedicated display hardware and API standardization for commercial kitchen management systems. Invest in NIST-traceable calibration services to capture recurring revenue from foodservice operators lacking in-house metrology capabilities. Channel control through direct-to-commercial distribution contracts defends margin position against emerging OEM competitors.
For New Entrants and Emerging Players: FDA food safety modernization in the United States opens a window for cloud-native temperature logging platforms with audit-ready data export capabilities. Independent restaurants and institutional cafeterias in Germany represent the most penetrable white-space segment. A go-to-market angle anchored in EU cybersecurity labeling compliance captures procurement preference ahead of regulatory crystallization.
For Investors and Strategic Acquirers: Roll-up economics work for app-ecosystem specialists because smartphone integration technology captures the largest margin pool through proprietary platform lock-in. Long-term viability hinges on recurring engagement mechanisms rather than hardware transaction cycles. Acquisition targets should demonstrate cloud recipe integration capabilities and multi-probe system portfolios. The signal to watch is centralized equipment tender specifications from catering conglomerates.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Platform Integration | Convergence of temperature telemetry with AI-guided cooking algorithms creates subscription revenue potential for appliance ecosystems. |
| Direct-to-Commercial Distribution | Foodservice distributors in China are building dedicated smart appliance procurement divisions to capture institutional volume. |
| EU Cybersecurity Certification | CE marking extensions for IoT kitchen devices favor early-compliant vendors in European procurement channels. |
| Multi-Probe System Expansion | High-volume catering operators in the United States adopt multi-sensor arrays at accelerated refresh cycles. |
| NIST-Traceable Calibration Services | Foodservice operators lack in-house metrology capabilities to verify probe accuracy against national standards. |
Study Parameters
Bottom-up end-user modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with foodservice procurement managers, commercial kitchen equipment distributors, connected appliance engineers, and regulatory compliance officers with secondary validation from FCC equipment authorization databases, FDA food code provisions, EU food contact material regulations, and customs trade records.
Historical trendline analysis of Bluetooth and Wi-Fi product shipments across connectivity protocols, end-user segments, and distribution channels anchors the projection framework. Segmentation dimensions span product type, technology integration depth, user environment, and geographic regulatory cluster. CAGR derivation incorporates probe fabrication capacity expansion, cloud infrastructure deployment rates, and HACCP compliance adoption curves across institutional foodservice operations.
Revisions become necessary when cybersecurity standards crystallize, FCC certification pathways shift, or probe supply concentration disrupts manufacturing continuity. Forecasts reflect assumptions about regulatory enforcement intensity and commercial kitchen digitization rates. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Food Extruder Market
Food Processing Equipment
Reach-In Freezers Market
Food Processing Equipment
Food Processing and Handling Equipment Market
Food Processing Equipment
Canning Machine Market
Food Processing Equipment
Food Waste Disposal Equipment Market
Food Processing Equipment
Deep Fryer Oil Filtration Market
Food Processing Equipment
French Fries Cutter Market
Food Processing Equipment
North America Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Potato Processing Market
Food Processing Equipment
Brining Systems Market
Food Processing Equipment
Bottled Water Processing Equipment Market
Food Processing Equipment
Fish Processing Equipment Market
Food Processing Equipment
Mobile Bottling Line Market
Food Processing Equipment
Salmon Fish Scaling Machine Market
Food Processing Equipment
Corn Puff Making Machine Market
Food Processing Equipment
Global Wine Tanks Market