
 Industrial Food and Beverages Filtration System Market | 2026-2036
Industrial Food and Beverages Filtration System Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Food and Beverages Filtration System Market Analysis
OEM-direct and systems-integrator channels are rewriting procurement patterns for industrial filtration equipment. Alfa Laval AB leverages its dairy processing heritage to dominate membrane system configurations in European markets. Parker Hannifin Corp. anchors North American demand through its cartridge and hydraulic filtration crossover expertise. Donaldson Company, Inc. competes on industrial air and liquid filtration scale, extending its agriculture and food manufacturing footprint.
Industrial food and beverages filtration systems separate suspended solids, microorganisms, and dissolved compounds from process streams using porous membranes, depth media, or surface-retentive cartridges rated from 0.1 to 100 microns. These systems serve to clarify raw inputs, stabilize finished products, recover valuable byproducts, and ensure compliance with microbiological safety thresholds. Reverse osmosis and ultrafiltration membrane technologies lead value generation where protein concentration and water recovery command premium pricing. Cartridge and bag filtration segments sustain higher volume throughput in clarification and polishing stages for beverage manufacturers and wineries.
The FDA enforces Hazard Analysis and Critical Control Points validation for filtration systems in commercial food production, while the EPA limits effluent particulate loads from processing facilities. ISO 9001 and 3-A Sanitary Standards certification shape supplier qualification and international market access protocols. Stakeholders must monitor evolving membrane material regulations and water reuse mandates to align capital deployment with compliance trajectories.
Market Dynamics
Membrane filtration technology is compressing replacement cycles for conventional depth media as dairy processors and beverage manufacturers pursue protein recovery economics and water reuse mandates.
Growth Catalysts
- EPA effluent standards:Discharge limits on suspended solids from food processing facilities are compelling wastewater treatment upgrades with advanced filtration stages.
- Protein concentration demand:Whey processing facilities are expanding ultrafiltration capacity to isolate lactoferrin and immunoglobulins for nutraceutical applications.
- German engineering clusters:Bavarian and Baden-Württemberg dairy cooperatives are procuring premium membrane systems with integrated clean-in-place automation.
Market Restraints
- Polymer feedstock volatility:PVDF and PES membrane materials face price instability tied to fluorochemical supply chains concentrated in Chinese manufacturing zones.
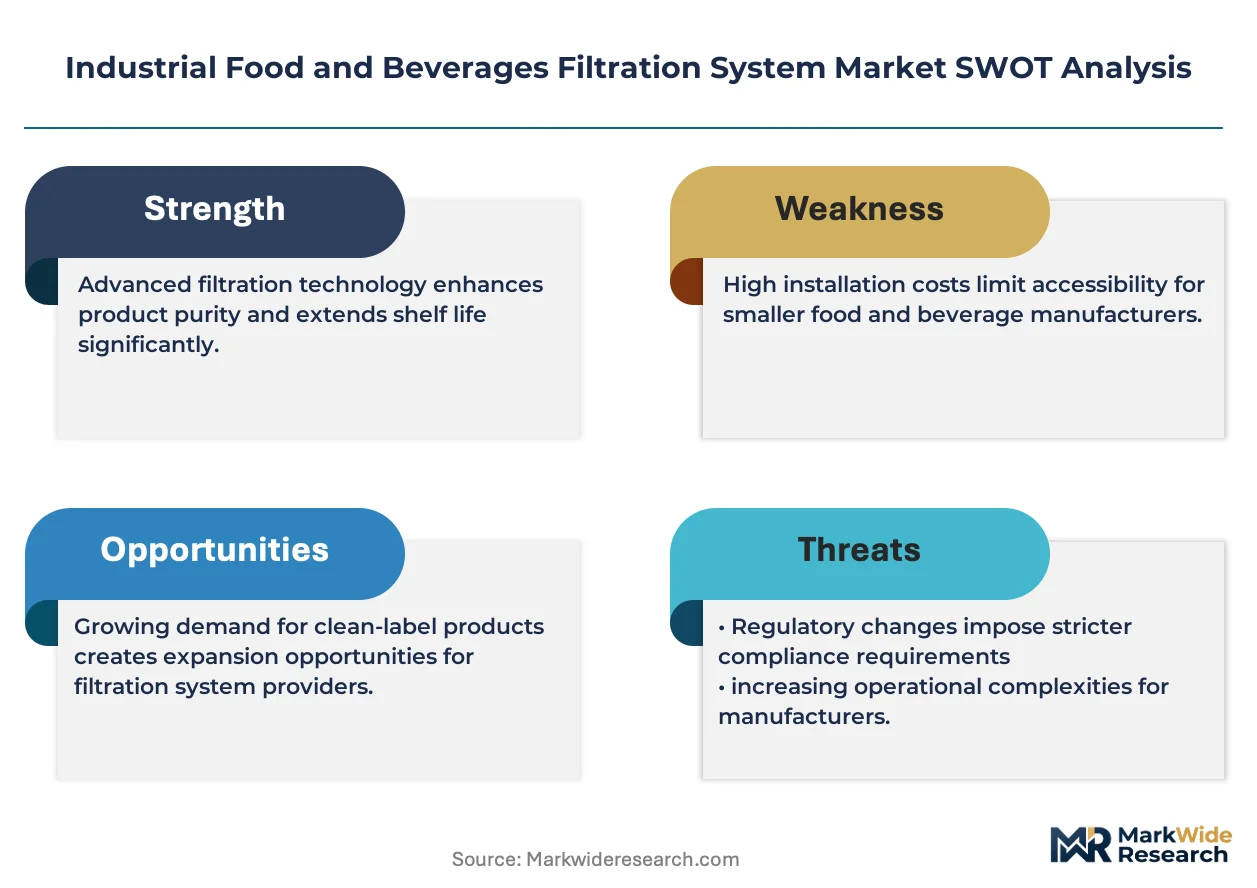
- Sanitary validation bottlenecks:FDA Hazard Analysis and Critical Control Points documentation requirements extend equipment qualification timelines by 8-14 months for novel membrane configurations.
- Cross-flow energy intensity:High-pressure pump requirements for reverse osmosis systems elevate operational expenditures versus dead-end filtration alternatives in low-margin beverage applications.
Strategic Opportunities
- India FSSAI modernization:The Food Safety and Standards Authority of India is mandating HACCP-compliant filtration for packaged dairy, opening membrane system deployment in Uttar Pradesh and Maharashtra processing corridors.
- Cell culture media filtration:Precision bioprocessing requirements for cultivated meat startups are creating demand for 0.1-micron-rated sterilizing-grade cartridges with extractables documentation.
- Water reuse incentives:California's agricultural discharge regulations are driving winery investment in closed-loop filtration systems with reverse osmosis permeate recovery.
Industry Challenges
- Sanitary welding certification:ASME BPE-compliant orbital welding for stainless steel skids requires specialized technician credentials that remain scarce in North American service networks.
- Legacy control integration:Brownfield dairy plants with 1990s-era SCADA architectures face protocol mismatches when retrofitting smart membrane skids with IoT-enabled transmembrane pressure monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Food and Beverages Filtration System Market |
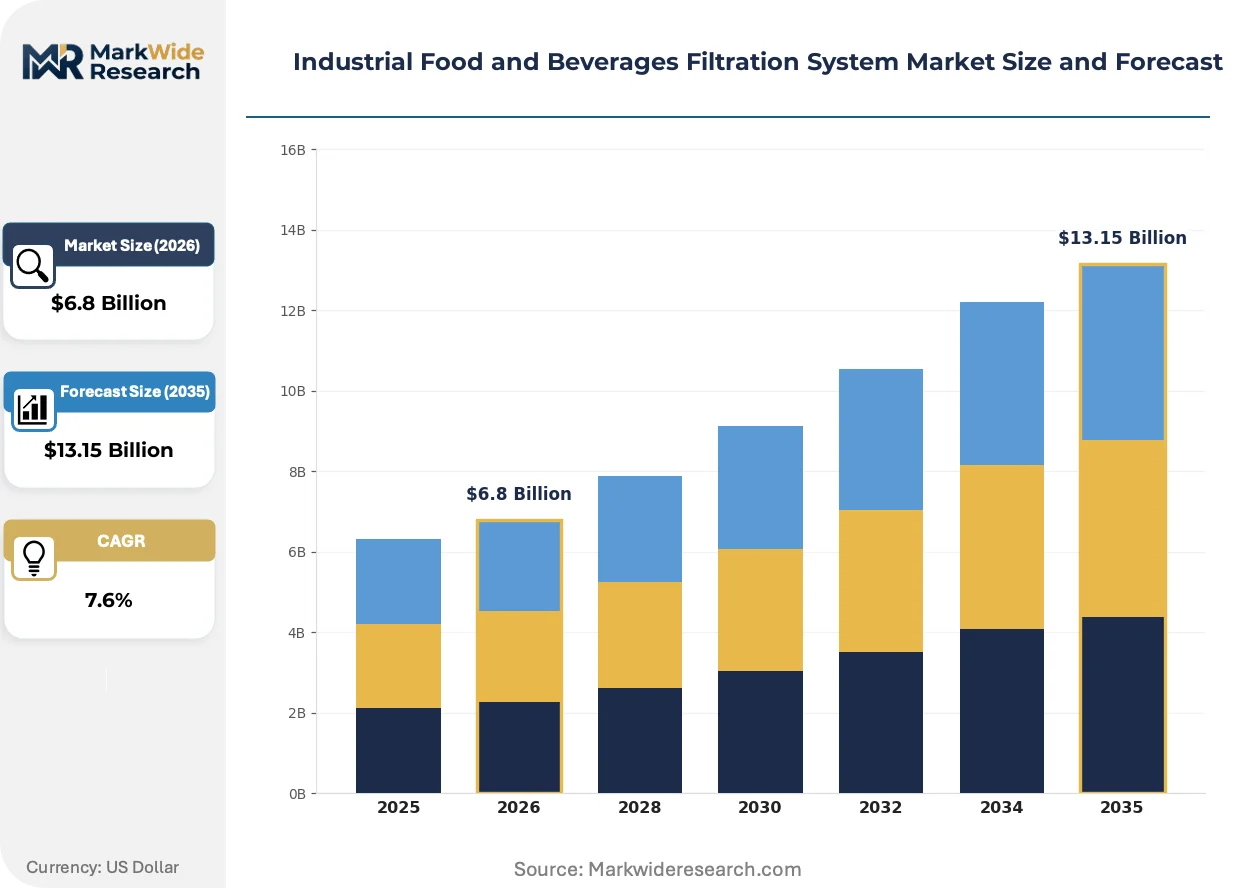
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfiltration, Ultrafiltration, Nanofiltration, Reverse Osmosis End User: Beverage Manufacturers, Dairy Processors, Food Producers, Wineries Technology: Membrane Filtration, Cartridge Filtration, Bag Filtration, Depth Filtration Application: Clarification, Polishing, Sterilization, Separation |
| Companies Covered | 3M Co., Alfa Laval AB, Parker Hannifin Corp., Eaton Corporation plc, Donaldson Company, Inc., GEA Group AG, Pall Corporation, Krones AG, Critical Process Filtration Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Food and Beverages Filtration System Market Emerging Trajectories
Filtration system architecture is pivoting from fixed-configuration skids toward modular, data-integrated platforms that align with variable batch sizes and real-time quality release protocols.
Ceramic membrane technology is rendering obsolete polymeric spiral-wound elements in high-temperature, caustic-cleaning dairy applications. European whey processors operating 24-hour continuous lines are adopting alumina and titania membranes rated for 80°C CIP cycles. The structural consequence is rendering obsolete the three-year replacement schedules typical of polymeric systems, compressing lifecycle cost models toward decade-long amortization horizons.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are phasing out certain refrigerants used in filtration process cooling loops. Industrial consequence includes retrofit pressure on cold-block ultrafiltration systems in French and Dutch dairy clusters. Affected segments are responding by specifying ammonia-based or CO2 transcritical cooling architectures in new membrane plant builds.
Service unbundling is fragmenting traditional equipment-plus-maintenance contracts into separate capital, consumables, and technical service procurement streams. Food manufacturers with centralized engineering procurement functions are disaggregating cartridge supply from OEM technical support. This pattern is most visible in German and Swiss beverage conglomerates with multi-site filtration standardization programs.
Industrial Food and Beverages Filtration System Market Segmentation
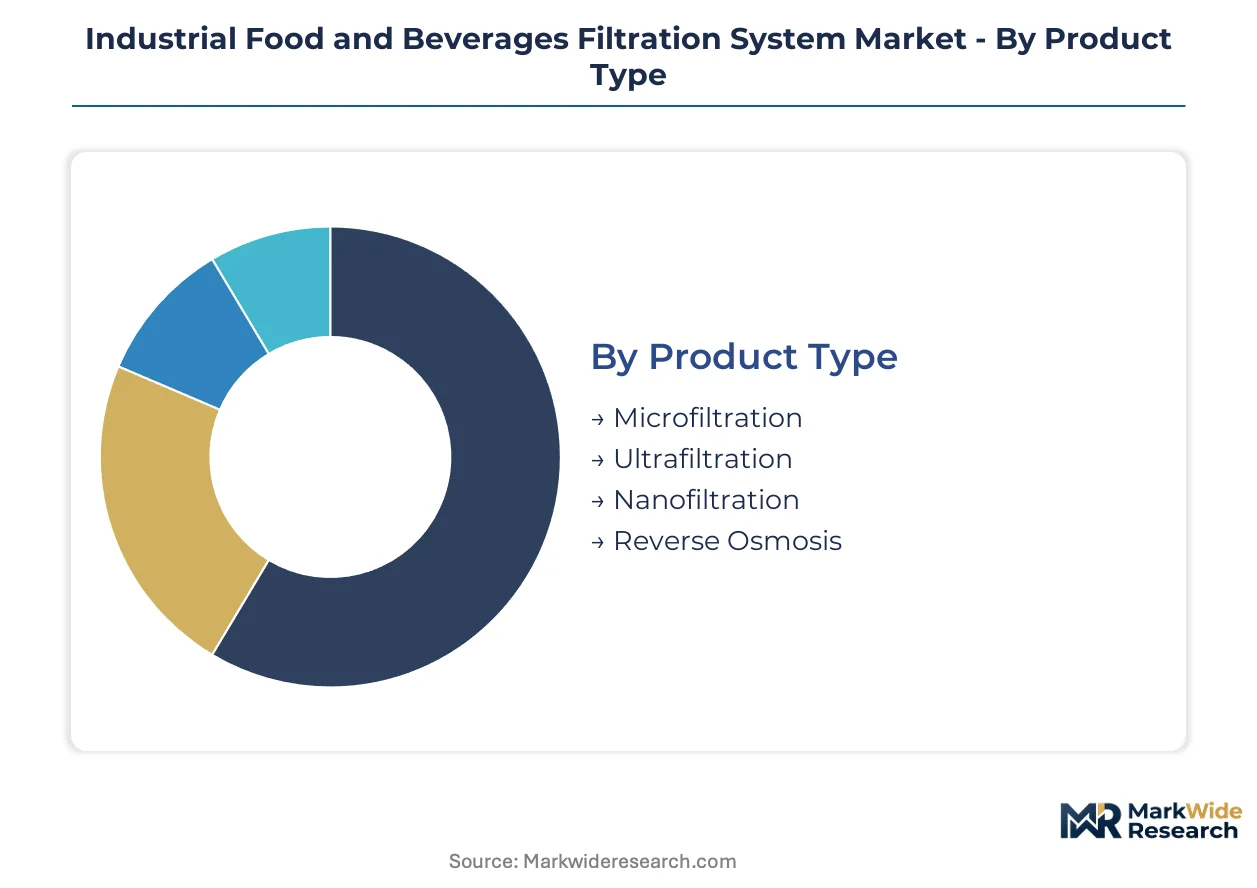
Industrial food and beverages filtration system procurement varies sharply by operational intensity and consumables replacement cadence. Dairy processors running continuous ultrafiltration lines demand membrane replacement contracts every 18-24 months, while beverage clarifying operations prioritize cartridge standardization across multi-site networks.
Product Type:
After-sales-service intensity peaks with membrane systems requiring scheduled element replacement, transmembrane pressure monitoring, and CIP validation protocols.
- Ultrafiltration:Pore structures rated 1-100 nanometers concentrate proteins and fractionate whey streams in continuous dairy operations. Bavarian whey processors are expanding capacity for lactoferrin and immunoglobulin isolation, driving demand for automated clean-in-place skids with integrated permeate flux monitoring.
- Reverse Osmosis:Dense polyamide thin-film composites reject dissolved salts and small organics at operating pressures exceeding 30 bar. California wineries facing agricultural discharge mandates are deploying closed-loop RO systems for permeate recovery and water reuse compliance.
- Microfiltration:0.1-10 micron-rated membranes clarify raw milk and remove spoilage bacteria prior to pasteurization.
- Nanofiltration:Selective divalent ion rejection softens process water and concentrates oligosaccharides in specialized dairy fractions.
Ultrafiltration holds the largest share; momentum sits with reverse osmosis as water reuse mandates tighten across food processing corridors.
End User:
Capital deployment patterns diverge between continuous-process dairy operations and batch-oriented beverage manufacturing.
- Dairy Processors:24-hour production lines demand ceramic membrane durability for high-temperature CIP cycles and decade-long amortization horizons. German dairy cooperatives in Baden-Württemberg specify alumina and titania systems with automated transmembrane pressure control.
- Beverage Manufacturers:Variable batch sizes and frequent product changeovers favor modular cartridge systems with rapid swap-out protocols. Multi-site standardization programs at Swiss beverage conglomerates are disaggregating consumables procurement from OEM technical support contracts.
- Food Producers:Ingredient clarification and cooking oil recovery applications utilize bag and depth filtration for high-solids throughput.
- Wineries:Seasonal harvest pressure and tannin-sensitive polishing stages drive demand for diatomaceous earth alternatives and cross-flow membrane systems.
Dairy processors command the highest installed base; beverage manufacturers are expanding most quickly as SKU proliferation multiplies filtration changeover frequency.
Technology:
Technology selection tracks the tension between separation precision and operational simplicity in sanitary process environments.
- Membrane Filtration:Cross-flow configurations with polymeric spiral-wound or ceramic tubular elements achieve molecular-level separation for protein concentration and water purification. EU F-Gas Regulation restrictions are forcing cooling loop retrofits on cold-block ultrafiltration systems in French and Dutch dairy clusters.
- Cartridge Filtration:Pleated polypropylene or cellulose depth media provide surface-retentive particle removal rated 0.1 to 100 microns. Parker Hannifin anchors North American demand through cartridge standardization programs spanning hydraulic and process filtration crossover expertise.
- Bag Filtration:Felt or mesh housings handle high-solids loading in raw ingredient clarification with minimal operator intervention.
- Depth Filtration:Graded-density media retain particles throughout matrix thickness for pre-filtration and polishing stages in winery and brewing applications.
Membrane filtration dominates value generation; cartridge filtration sustains highest unit volume through beverage clarification standardization.
Application:
Application requirements cascade from coarse solids removal through sterilizing-grade bioburden control.
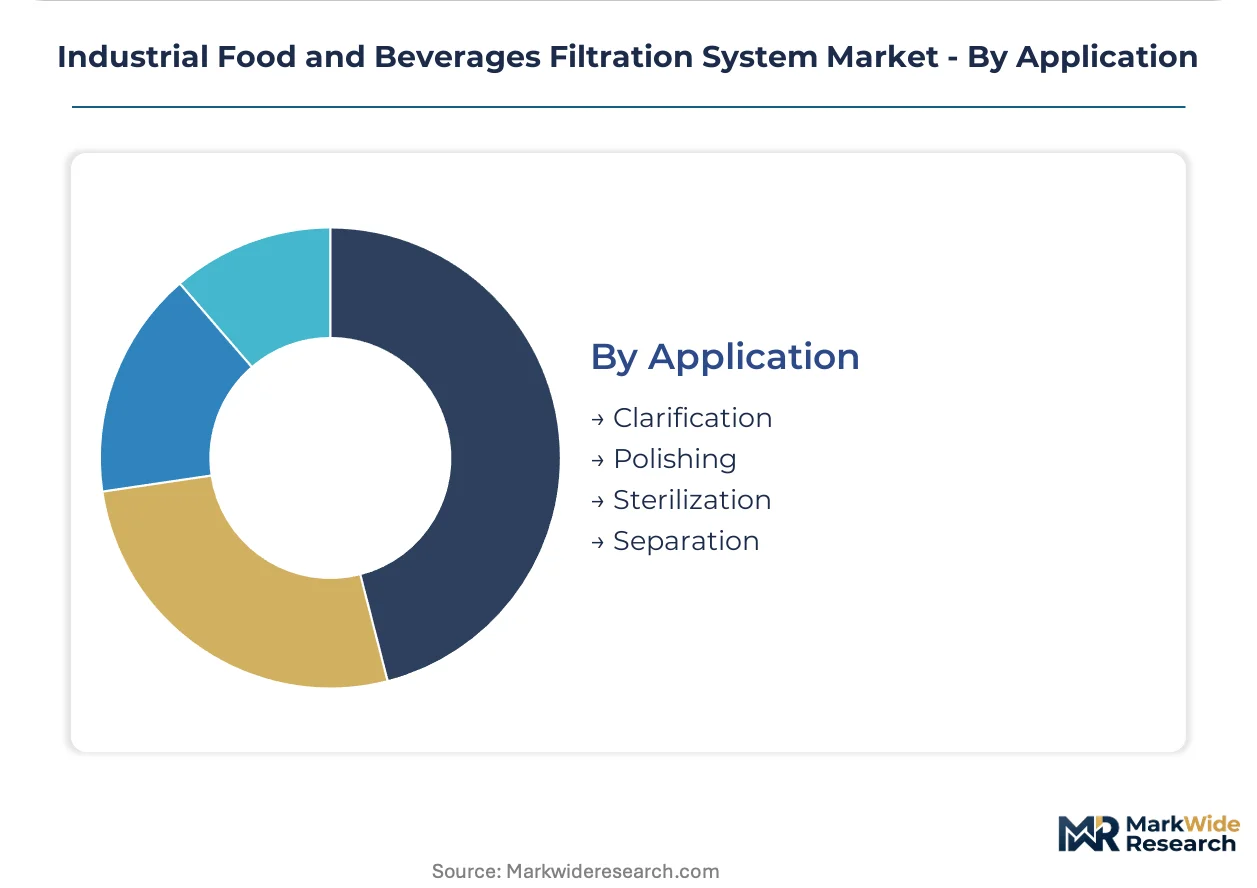
- Clarification:Bulk suspended solids removal using bag, depth, or coarse membrane stages protects downstream equipment and stabilizes raw ingredient quality. FDA Hazard Analysis and Critical Control Points validation requirements extend equipment qualification timelines for novel membrane configurations in commercial food production.
- Sterilization:0.1-micron-rated absolute filters achieve bioburden reduction and spore retention for aseptic packaging lines. Cultivated meat startups are creating demand for sterilizing-grade cartridges with extractables documentation for cell culture media filtration.
- Polishing:Final particulate removal and haze stabilization prior to packaging using pleated cartridge or membrane stages.
- Separation:Molecular fractionation of proteins, sugars, and minerals using pressure-driven membrane selectivity.
Clarification represents the broadest installed base; sterilization is gaining share fastest as aseptic processing expands beyond dairy into plant-based beverages and precision fermentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA discharge mandates and water reuse incentives are redirecting capital toward advanced filtration infrastructure in major dairy and beverage processing corridors. The FDA's Food Safety Modernization Act tightens microbiological thresholds, extending equipment qualification timelines for novel membrane configurations. Germany, the United States, India, France, and Australia concentrate procurement activity.
United States
California wineries facing agricultural discharge regulations are deploying closed-loop reverse osmosis systems for permeate recovery compliance. The EPA enforces effluent limits on suspended solids from food processing facilities, compelling wastewater treatment upgrades. Midwest dairy cooperatives in Wisconsin and Minnesota are expanding ultrafiltration capacity for whey protein concentration.
Germany
Bavarian and Baden-Württemberg dairy cooperatives are procuring premium ceramic membrane systems with integrated clean-in-place automation. The EU F-Gas Regulation phases out certain refrigerants in filtration process cooling loops, forcing retrofits on cold-block ultrafiltration systems. Stuttgart-based engineering clusters specify alumina and titania membranes rated for 80°C CIP cycles.
India
The Food Safety and Standards Authority of India mandates HACCP-compliant filtration for packaged dairy, opening membrane system deployment in Uttar Pradesh and Maharashtra processing corridors. Central pollution control discharge standards tighten effluent particulate thresholds for dairy and beverage plants. Gujarat dairy federations are retrofitting conventional depth media with ultrafiltration skids for protein fractionation.
France
French dairy processors in Brittany and Normandy face EU F-Gas Regulation pressure to specify ammonia-based cooling architectures in new membrane plant builds. The EFSA enforces microbiological safety thresholds for filtration equipment in commercial food production. Lyon-based beverage manufacturers are standardizing cartridge procurement across multi-site networks.
Australia
Victorian dairy exporters are adopting ceramic membrane durability for high-temperature CIP cycles to meet extended amortization horizons. Water reuse mandates in drought-affected regions drive winery investment in closed-loop filtration systems. New South Wales whey processors are expanding capacity for lactoferrin isolation to supply Asian nutraceutical markets.
Industrial Food and Beverages Filtration System Market Vendor Landscape
On the supply side, the industry is consolidating around engineering-intensive membrane system fabricators with dairy processing heritage and diversified industrial filtration conglomerates with cross-sector cartridge expertise. Three strategic archetypes dominate: European membrane specialists with integrated clean-in-place automation capabilities, North American diversified filtration conglomerates leveraging hydraulic and process filtration crossover expertise, and Asian precision component suppliers scaling into sanitary system assembly. Dominant competitive moves include backward integration into membrane material production and geographic expansion through technical service network establishment.
Among European engineering-intensive fabricators, Alfa Laval AB and GEA Group AG represent the integrated-systems archetype, anchoring premium membrane configurations in dairy and beverage clusters. Pall Corporation and Donaldson Company, Inc. exemplify North American diversified filtration expertise spanning industrial air, liquid, and sanitary process applications. Parker Hannifin Corp. occupies a position at the intersection of hydraulic and process filtration, leveraging cartridge standardization programs across multi-site beverage networks.
| Leading Market Players |
|---|
| 3M Co. |
| Alfa Laval AB |
| Parker Hannifin Corp. |
| Eaton Corporation plc |
| Donaldson Company, Inc. |
| GEA Group AG |
| Pall Corporation |
| Krones AG |
| Critical Process Filtration Inc. |
| Others |
Supply Flow & Price Mechanics
PVDF and PES membrane feedstock volatility concentrated in Chinese manufacturing zones compresses margin buffers across equipment tiers while simultaneously forcing procurement officers toward multi-source qualification programs. This raw material instability widens pricing spreads between ISO 9001-certified premium systems and uncertified alternatives as buyers demand supply chain transparency documentation.
Pricing Analysis
Certification level creates the primary spread between equipment tiers, with FDA-validated membrane skids commanding substantial premiums over CE-marked alternatives in North American dairy corridors. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling intensity and clean-in-place automation integration. Cost compression in mid-tier polymeric systems is intensifying because German engineering clusters are standardizing ceramic membrane specifications that obsolete three-year replacement cycles. Beverage manufacturers with centralized procurement functions exhibit highest price sensitivity, while 24-hour dairy operations prioritize lifecycle cost over capital expenditure.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for membrane system procurement, with supply-chain finance facilities increasingly embedded in German and Swiss beverage conglomerate contracts. Manufacturing gravity centers on Germany, the United States, and China, with ceramic membrane sintering concentrated in Baden-Württemberg engineering clusters. Critical inputs draw from fluoropolymer resin suppliers, stainless steel tubing mills, and precision pump manufacturers. Single-source vulnerability sits with Chinese PVDF feedstock concentration. Distribution runs through OEM-direct channels and systems-integrator networks that are rewriting traditional equipment-plus-maintenance contract structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through multi-site standardization programs at German and Swiss beverage conglomerates, fragmenting traditional vendor lock-in and forcing service unbundling across the procurement base.
For Market Incumbents: Pre-empt ceramic membrane commoditization by backward integration into alumina and titania material production, securing captive supply for 80°C CIP-rated systems. Lock in Baden-Württemberg dairy cooperatives through integrated automation partnerships that embed switching costs. The threat of Parker Hannifin's cartridge standardization programs crossing into membrane territory demands channel control investment in technical service network density. For New Entrants and Emerging Players: Establish a beachhead in India's Uttar Pradesh and Maharashtra processing corridors where FSSAI HACCP mandates are opening membrane deployment among first-time adopters. Target winery water reuse retrofit opportunities in California's Central Valley, where agricultural discharge regulations create urgency without incumbent entrenchment. A go-to-market angle emphasizing ammonia-based cooling architectures addresses EU F-Gas Regulation compliance pain points in French dairy clusters. For Investors and Strategic Acquirers: The market sits at a technology-substitution phase that favors ceramic membrane specialists with decade-long amortization value propositions. Long-term viability over the projection horizon rests on regulatory tailwinds for water reuse and protein concentration economics rather than cyclical capital expenditure patterns. Acquisition targets should demonstrate orbital welding certification capacity and IoT-enabled transmembrane pressure monitoring integration. The signal to watch is FSSAI enforcement intensity in Indian dairy corridors as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Membrane Capacity Expansion | Alumina and titania sintering investments capture German dairy cooperative procurement for continuous 24-hour operations. |
| Backward Integration into Fluoropolymer Resins | Captive PVDF supply secures margin stability against Chinese feedstock volatility and extends replacement contract control. |
| Clean-in-Place Automation Partnerships | Integrated CIP validation protocols embed switching costs with Bavarian whey processors expanding lactoferrin isolation capacity. |
| Technical Service Network Establishment | ASME BPE-certified orbital welding capabilities address technician scarcity in North American brownfield dairy retrofit markets. |
| Ammonia-Based Cooling Architecture Specification | EU F-Gas Regulation compliance positioning captures French and Dutch cold-block ultrafiltration retrofit demand. |
Methodological Framework
Operator-level perspectives from dairy processing engineers, beverage plant managers, membrane system procurement officers, and aftermarket service directors anchored the qualitative base for this analysis. Primary field engagement combined structured interviews with secondary validation through FDA 510(k) filings for filtration equipment, EPA effluent discharge enforcement records, and 3-A Sanitary Standards certification databases. Trade data from German engineering exports and Indian dairy processing imports supplemented demand-side calibration. Bottom-up equipment shipment tracking and top-down capital expenditure surveys from food and beverage processing corridors were triangulated against regulatory filing timelines.
Scenario-bracketing around EPA discharge mandate enforcement intensity, EU F-Gas Regulation phase-out pace, and FSSAI HACCP compliance timelines framed the projection range across the analysis window. Segmentation modeling incorporated product type, end user operational intensity, technology architecture, and application stage dimensions alongside regional regulatory cluster differentiation. CAGRs were derived from installed base replacement cycle compression and greenfield capacity expansion patterns. Industry-specific forecast inputs included whey protein concentration economics and water reuse mandate adoption curves in drought-affected processing regions.
Sensitivities concentrate around fluoropolymer feedstock price volatility, FDA validation timeline extensions for novel membrane configurations, and Indian regulatory enforcement intensity variation. Forecasts reflect documented assumptions regarding ceramic membrane substitution rates and service unbundling penetration among multi-site beverage networks. Macroeconomic deviation, regulatory enforcement shifts, or breakthrough membrane material commercialization would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Brewing Equipment Market
Food Processing Equipment
Countertop Food Blenders Market
Food Processing Equipment
Walk-In Coolers and Freezers Market
Food Processing Equipment
Flakes Making Machine Market
Food Processing Equipment
Smart Meat Thermometer Market
Food Processing Equipment
Tea Processing Equipment Market
Food Processing Equipment
Steam Blanching Equipment Market
Food Processing Equipment
Pet Food Processing Market
Food Processing Equipment
Vee Bee Consistometer Market
Food Processing Equipment
China Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Commercial Food Refrigeration Equipment Market
Food Processing Equipment
Tangyuan Machine Market
Food Processing Equipment
Bread Processing Equipment Market
Food Processing Equipment
Ultrasonic Homogenizer Machines Market
Food Processing Equipment
Europe Commercial Sous Vide Machine Market
Food Processing Equipment
Food and Beverages Air Filters Market