
 Ice-Cream Maker Market | 2026-2036
Ice-Cream Maker Market Size, Share, and Industry Trends Forecast 2026-2036
Ice-Cream Maker Market Outlook
Modular accessory bundles paired with base compressor units is broadening buyer choice across price tiers. Cuisinart leverages its manufacturing scale to occupy the mid-market home segment with versatile multi-function machines. Breville competes on technology leadership in precision temperature control for gelato and soft-serve formats. Kitchenaid sustains brand strength through captive compatibility with its stand mixer ecosystem, locking in a loyal consumer base.
An ice-cream maker is a thermomechanical appliance that uses compressor-driven refrigeration or pre-frozen bowl inserts to reduce mixture temperature while churning introduces air and prevents ice crystal formation, typically achieving overrun of 20-50% depending on design. Its primary commercial purpose spans foodservice batch production and retail soft-serve dispensing, while residential units enable customized ingredient control for dietary-restricted consumers. Countertop models lead volume sales in North America and Europe due to compact footprints and sub-$300 price accessibility, yet industrial units command the largest margin pools through durable stainless-steel construction and NSF certification requirements. Soft-serve technology is displacing traditional batch freezing in quick-service restaurants because continuous-output designs reduce labor and waste during peak demand windows.
The EPA regulates refrigerant selection under SNAP program amendments, pushing manufacturers toward R290 propane or R600a isobutane alternatives in US-bound equipment. Europe's ECHA enforces REACH compliance on food-contact materials and RoHS restrictions on electrical components, while CE marking mandates govern electromagnetic compatibility and machinery safety for EU market access. Stakeholders must monitor evolving refrigerant phase-down schedules and efficiency labeling requirements, as regulatory lag between jurisdictions creates asymmetric compliance costs that favor regionally adaptive supply chains over standardized global platforms.
Market Dynamics
Compressor miniaturization and refrigerant chemistry shifts are compressing equipment footprints while expanding placement flexibility across foodservice formats. This thermomechanical convergence is redrawing competitive boundaries between commercial and residential equipment suppliers.
Growth Catalysts
- Foodservice automation mandates:Quick-service chains in the United States are retrofitting kitchens with continuous-output soft-serve units to reduce labor during peak windows. This operational pressure sustains replacement cycles even in mature markets.
- REACH and RoHS compliance evolution:Europe's ECHA enforcement on food-contact materials and electrical component restrictions is accelerating stainless-steel adoption and sealed-bearing designs that outlast legacy models.
- Propane refrigerant transition:EPA SNAP amendments permitting R290 in commercial equipment below specific charge limits are enabling smaller compressor architectures without sacrificing cooling capacity.
Market Restraints
- Copper and aluminum price volatility:Heat exchanger and compressor housing costs fluctuate with London Metal Exchange pricing, compressing margins for mid-tier manufacturers without forward-contract coverage.
- Refrigerant supply concentration:Specialty gas production for hydrofluorocarbon alternatives clusters among German and Chinese chemical processors, creating asymmetric input access.
- NSF certification timelines:Commercial equipment validation for food-zone safety extends 8-14 months, delaying new entrant market entry and freezing design iterations.
Strategic Opportunities
- India foodservice expansion:Organized QSR penetration in tier-two cities remains below saturation, creating first-mover positioning for compact countertop units with 220V compatibility.
- CE marking convergence:Unified EU machinery safety and electromagnetic compatibility standards reduce per-country adaptation costs for manufacturers targeting pan-European distribution.
- IoT-enabled predictive maintenance:Sensor-embedded compressors transmitting vibration and temperature data to cloud platforms are opening subscription revenue streams alongside equipment sales.
Industry Challenges
- Refrigeration technician scarcity:Qualified service personnel for hydrocarbon refrigerant handling remain concentrated in metropolitan areas, extending downtime for rural foodservice operators.
- Legacy electrical infrastructure:Older commercial kitchens in the United States lack dedicated 240V circuits required by high-capacity batch freezers, forcing costly electrical upgrades or capacity compromises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ice-Cream Maker Market |
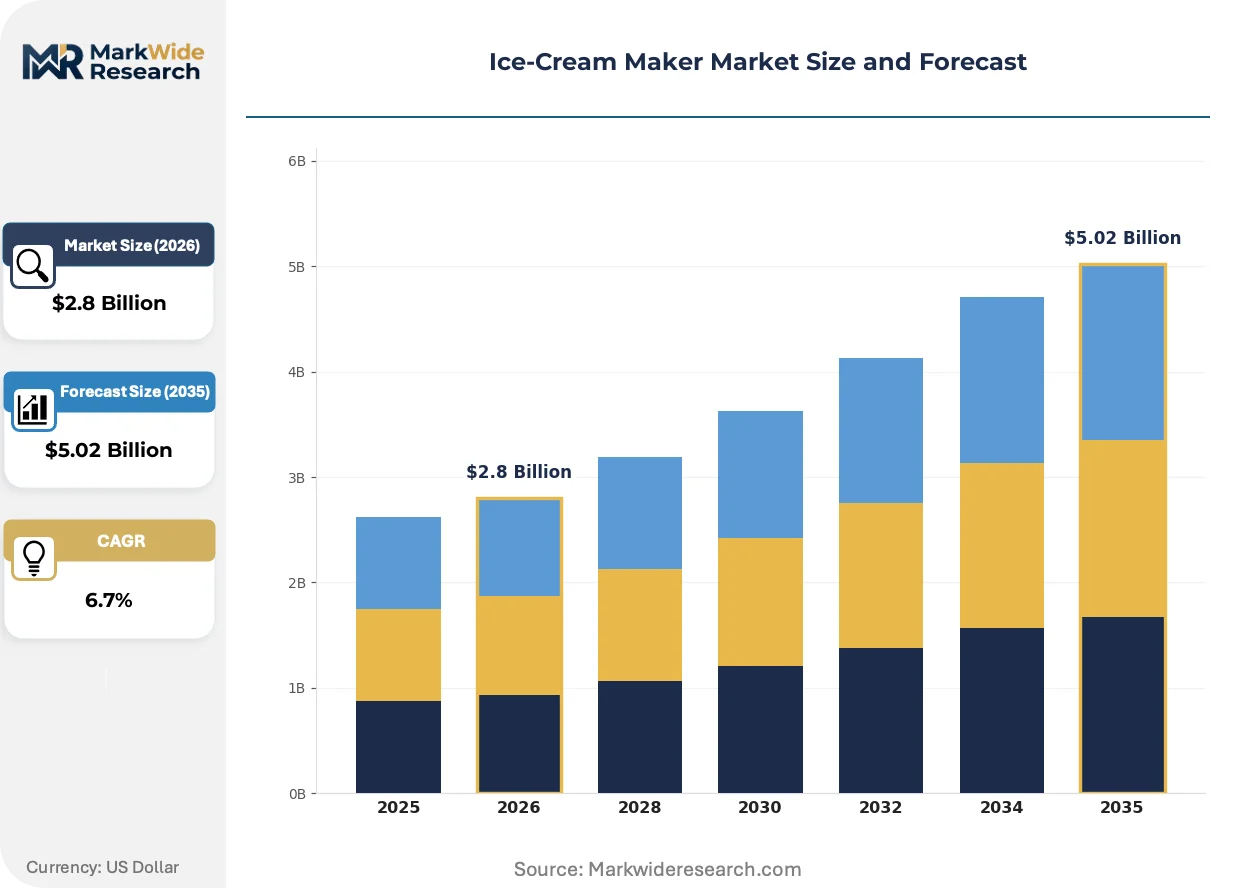
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Industrial, Soft Serve, Gelato Technology: Refrigeration, Mixing, Freezing, Churning End User: Restaurants, Catering Services, Home Use, Retail Outlets Distribution Channel: Online, Retail Stores, Direct Sales, Distributors |
| Companies Covered | Whynter, Lello Musso, Ninja Creami, Hamilton Beach, Dash, Cuisinart, Kitchenaid, GSE Ice, Breville, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ice-Cream Maker Market Strategic Shifts
Equipment intelligence and refrigerant chemistry are converging to redefine ownership economics. These shifts compress maintenance cycles while extending functional lifespans across both commercial and residential segments.
Brushless DC compressor technology is decentralizing cooling system architecture away from centralized HVAC-dependent installations. Smaller foodservice operators in Japan and South Korea are adopting these self-contained units for satellite locations without mechanical room infrastructure. This distributed approach is decentralizing capital deployment patterns and enabling rapid format testing with lower exit costs.
Europe's F-Gas Regulation phase-down schedule is forcing refrigerant portfolio transitions across the manufacturing base. Equipment bound for EU markets now ships with R600a or R290 charges as default configurations, with hydrofluorocarbon options relegated to legacy service parts. Commercial batch freezer lines face the steepest retooling requirements, with production lines in Italy and Germany completing conversions ahead of 2030 reduction milestones.
Direct-to-foodservice procurement through manufacturer-owned digital platforms is compressing traditional distribution layers. Restaurant groups in the United States are negotiating fleet pricing through dedicated portals, bypassing regional equipment dealers. This channel disintermediation concentrates buyer power among multi-unit operators while squeezing margin pools for independent distributors serving single-location accounts.
Ice-Cream Maker Market Segmentation
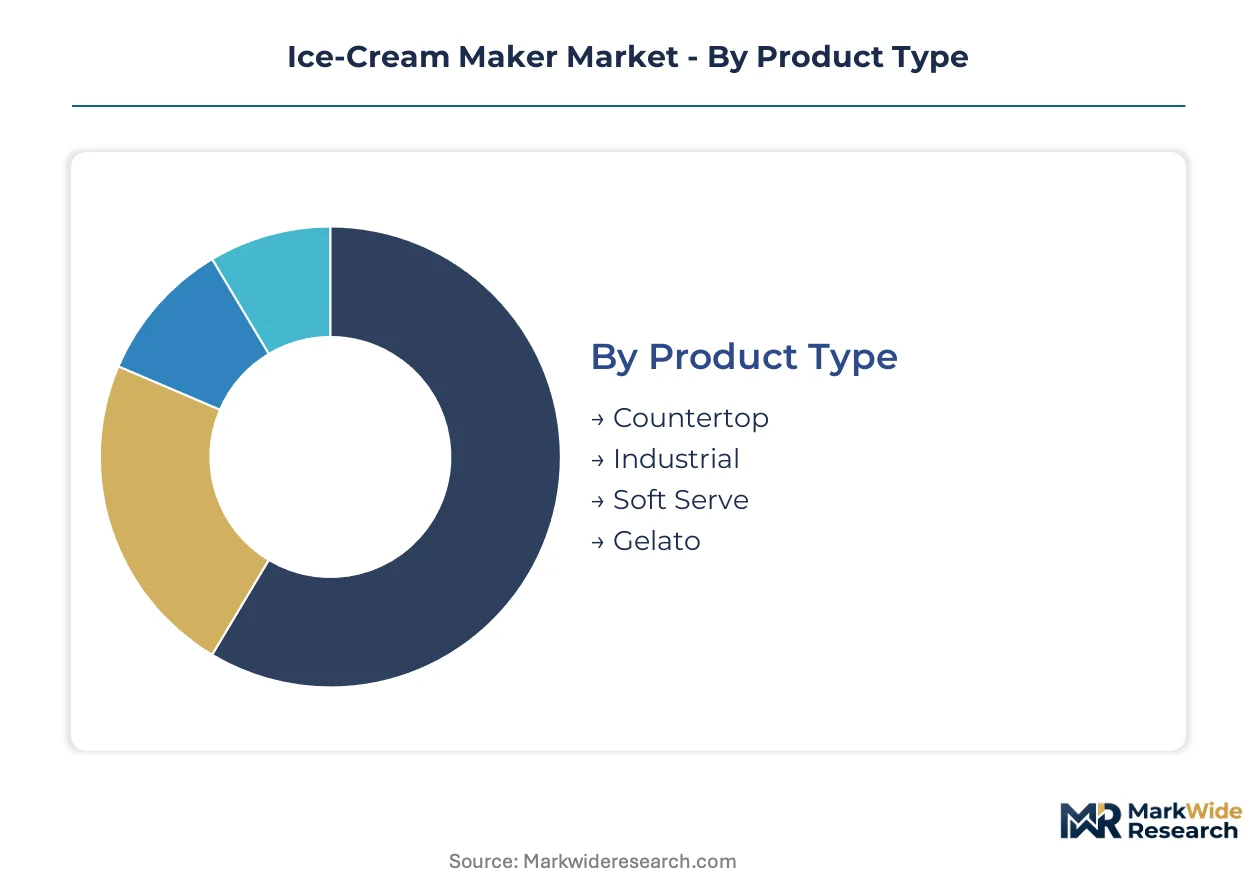
Ice-cream maker segmentation reveals divergent capital requirements and margin structures across product tiers. Equipment buyers face trade-offs between upfront compressor investment and operational flexibility that reshape procurement patterns.
Product Type:
Capital intensity varies dramatically by product type, with industrial batch freezers demanding dedicated electrical infrastructure and NSF-certified stainless-steel construction.
- Industrial:Floor-standing batch freezers with 20-40 quart capacities employ hermetic compressors and glycol cooling systems for continuous production cycles. Demand concentrates in United States foodservice manufacturing facilities where NSF certification and 240V three-phase power are standard. High equipment longevity and service contract attach rates justify premium positioning.
- Soft Serve:Continuous-output machines with gravity or pump-fed dispensing heads maintain product viscosity through precise overrun control. Quick-service restaurants in the United States retrofitting for labor reduction drive replacement cycles, with chains favoring units under 150 lbs for counter placement flexibility.
- Countertop:Compact units with pre-frozen bowl or small compressor designs dominate residential and small commercial settings.
- Gelato:Specialized low-overrun equipment with slower churn speeds targets artisanal producers seeking dense texture profiles.
Most installed capacity flows through Industrial units. Expansion is steepest in Soft Serve.
Technology:
Technology segmentation maps to core thermomechanical functions, with refrigeration systems commanding the largest component cost share.
- Refrigeration:Compressor-driven vapor compression cycles using R290 or R600a refrigerants determine cooling capacity and energy efficiency ratings. Europe's F-Gas Regulation accelerates hydrocarbon adoption, with Italian and German manufacturers completing production line conversions ahead of phase-down deadlines.
- Freezing:Cylinder wall heat exchange design and refrigerant charge optimization control batch consistency. United States commercial operators prioritize rapid pull-down times for peak-demand throughput.
- Mixing:Paddle geometry and motor torque specifications govern air incorporation rates.
- Churning:Speed-variable drive systems enable texture customization across product formats.
Refrigeration technology anchors equipment differentiation. Freezing system innovation is gaining share fastest among premium tier suppliers.
End User:
End-user segmentation reflects divergent duty cycles and purchasing authority structures.
- Restaurants:Full-service and limited-service operators require NSF-certified equipment with rapid recovery times for menu diversification. United States chain accounts negotiate fleet pricing through direct manufacturer portals, consolidating procurement power among multi-unit groups.
- Home Use:Residential buyers prioritize sub-$300 price points and compact storage footprints. Dietary customization for restricted consumers sustains replacement demand in North American and European households.
- Catering Services:Mobile operators demand 220V compatibility and transport durability for off-premise events.
- Retail Outlets:Supermarket and convenience store installations focus on self-serve dispensing with payment integration.
Restaurant channel volume dominates current shipments. Home Use is climbing the fastest as premium appliance positioning expands.
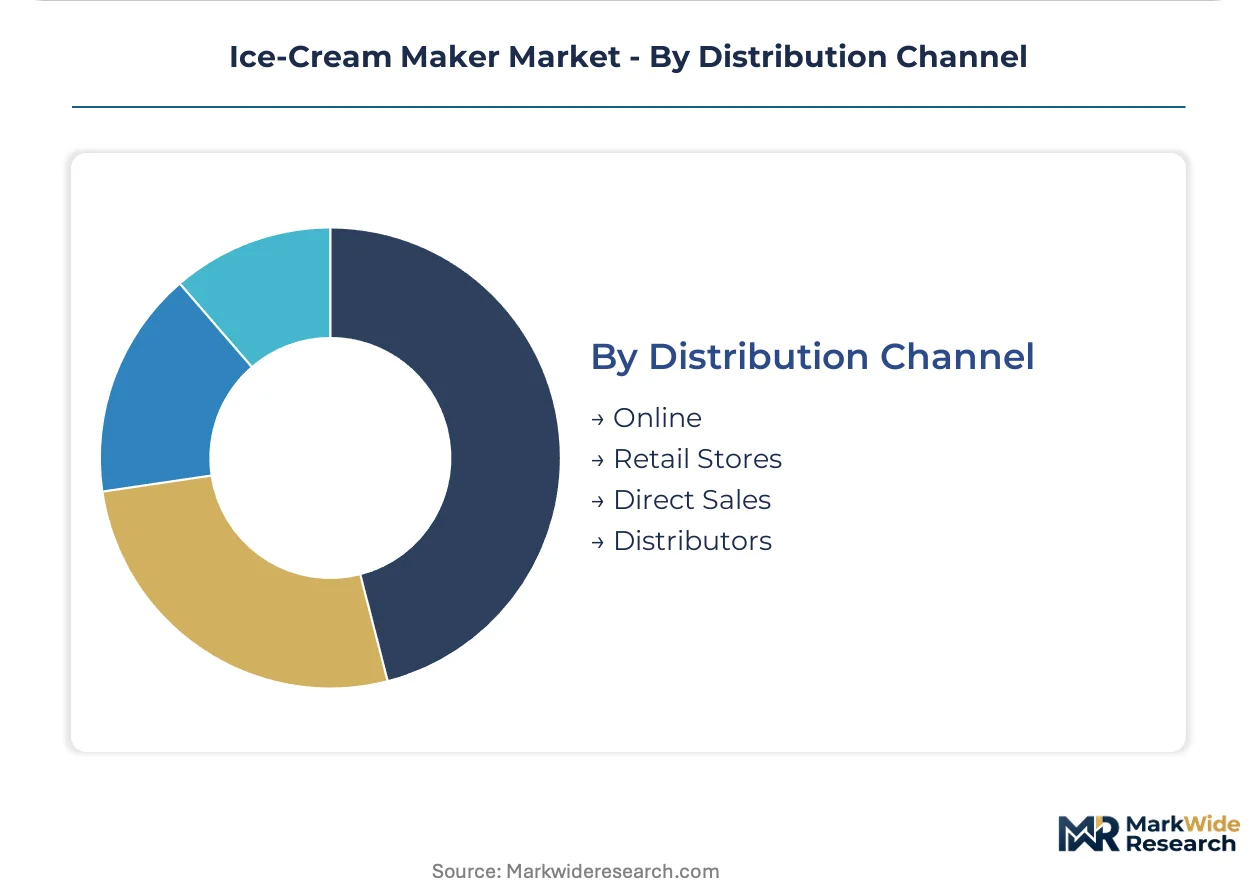
Distribution Channel:
Channel structure determines margin capture and customer relationship depth.
- Direct Sales:Manufacturer-owned digital platforms and field sales teams serve large foodservice accounts with customized fleet configurations. United States restaurant groups leverage dedicated portals for specification standardization across locations, compressing traditional dealer margins.
- Distributors:Regional equipment dealers provide installation and service infrastructure for independent operators. Technician scarcity for hydrocarbon refrigerant handling limits coverage density in rural United States markets.
- Online:E-commerce platforms aggregate residential demand with comparison shopping tools.
- Retail Stores:Big-box and specialty appliance retailers target home-use impulse purchases.
Distributor networks handle most commercial volume. Direct sales is expanding most quickly as chain account consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy pioneered commercial gelato equipment manufacturing in the early twentieth century, establishing design conventions that persist across modern batch freezer engineering. German and Italian producers still supply the majority of NSF-certified stainless-steel units for North American foodservice.
United States
Quick-service restaurant chains drive replacement demand for continuous-output soft-serve machines with labor-reduction features. EPA SNAP amendments permit R290 propane refrigerant in commercial equipment below specific charge thresholds, enabling smaller compressor footprints. Equipment procurement concentrates in Dallas-Fort Worth and Atlanta distribution hubs serving southeastern franchise networks.
Germany
Artisanal gelato producers sustain demand for precision low-overrun batch freezers with extended cylinder wall heat exchange surfaces. ECHA enforces REACH compliance on food-contact stainless steels and RoHS restrictions on electrical bearing assemblies. Manufacturing clusters in Bavaria and Baden-Württemberg complete production line conversions for F-Gas Regulation hydrocarbon transitions ahead of 2030 deadlines.
Italy
Heritage equipment brands anchor premium positioning in artisanal foodservice segments across Europe and export markets. CE marking mandates govern electromagnetic compatibility and machinery safety for EU market access, consolidating certification costs for pan-European distribution. Industrial freezer production concentrates in Emilia-Romagna, where foundry and precision machining suppliers maintain vertical relationships with equipment assemblers.
China
Domestic quick-service expansion in tier-two cities creates first-mover positioning for compact countertop units with 220V electrical compatibility. National refrigerant phase-down schedules align with Kigali Amendment commitments, pressuring manufacturers toward R600a isobutane architectures. Production gravity sits in Guangdong and Zhejiang provinces, where component ecosystems supply both domestic foodservice and export residential markets.
India
Organized QSR penetration in secondary metropolitan areas remains below saturation, opening volume opportunities for price-accessible compressor units. BIS certification requirements and FSSAI food-contact material standards filter import competition while enabling domestic assembly partnerships. Mumbai and Bangalore host emerging distribution infrastructure for commercial kitchen equipment serving western and southern regional markets.
Ice-Cream Maker Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification tier and refrigerant architecture sophistication. The vendor base stratifies between NSF-certified stainless-steel specialists serving chain foodservice accounts and residential-focused brands competing on price-accessible countertop formats. Three archetypes dominate: heritage European equipment houses with artisanal positioning, diversified kitchen-appliance conglomerates leveraging manufacturing scale, and emerging Asian fabricators capturing volume in developing markets. Competitive moves concentrate on direct-to-foodservice digital procurement platforms and hydrocarbon refrigerant production line conversions.
Among diversified appliance manufacturers, Cuisinart and Kitchenaid occupy positions anchored by captive ecosystem compatibility and multi-function machine versatility. Breville exemplifies technology-forward positioning in precision temperature control segments. These three names represent distinct margin-tier strategies rather than exhaustive market coverage, with each archetype commanding different buyer relationships across residential and commercial channels.
| Leading Market Players |
|---|
| Whynter |
| Lello Musso |
| Ninja Creami |
| Hamilton Beach |
| Dash |
| Cuisinart |
| Kitchenaid |
| GSE Ice |
| Breville |
| Others |
Value Chain & Pricing Dynamics
Europe's F-Gas Regulation phase-down schedule gates qualified refrigerant supply and premium-tier pricing access for equipment manufacturers, compressing margin pools for those without hydrocarbon-ready production lines while rewarding early converters with pricing power in NSF-certified stainless-steel segments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates equipment procurement, with NSF certification grade and compressor cooling capacity as primary differentiation drivers. Cost compression in mid-tier countertop units is intensifying because copper and aluminum price volatility erodes forward-contract coverage for smaller manufacturers. Quick-service restaurant chains exhibit lowest price sensitivity due to fleet standardization needs, while independent foodservice operators in rural United States markets face acute budget constraints.
Supply Chain Analysis
NSF certification and CE marking requirements filter component suppliers toward qualified stainless-steel foundries and sealed-bearing manufacturers concentrated in Italy, Germany, and Guangdong province. Compressor housings and heat exchangers draw from copper and aluminum feedstocks vulnerable to London Metal Exchange pricing swings. Single-source vulnerability clusters among German and Chinese specialty gas processors for R290 and R600a refrigerants. Distribution runs through manufacturer-owned digital platforms for chain accounts and regional equipment dealers for independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by quick-service restaurant demand-shift toward continuous-output soft-serve machines with labor-reduction specifications and IoT-enabled predictive maintenance.
For Market Incumbents: Hedge refrigerant transition risk by completing R290 production line conversions ahead of 2030 F-Gas Regulation milestones. Lock in multi-year supply agreements with Bavarian and Baden-Württemberg stainless-steel foundries to defend against copper price volatility eroding NSF-certified equipment margins. For New Entrants and Emerging Players: Launch via direct-to-foodservice digital platforms targeting tier-two Indian cities with 220V-compatible compact countertop units. Exploit underpenetrated organized QSR penetration in Mumbai and Bangalore distribution corridors where BIS certification filters import competition. For Investors and Strategic Acquirers: Roll-up economics work for heritage European equipment houses with artisanal positioning because CE marking consolidation reduces per-country adaptation costs for pan-European distribution. Watch for inflection when EPA SNAP amendments expand R290 charge thresholds, signaling compressor architecture disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Portfolio Transition | R290 and R600a conversions ahead of F-Gas Regulation deadlines secure EU market access for Italian and German manufacturers. |
| Direct-to-Foodservice Platform Launch | Manufacturer-owned portals bypass regional dealers and concentrate buyer power among United States multi-unit restaurant groups. |
| IoT Sensor Integration | Vibration and temperature data transmission opens subscription revenue streams alongside compressor equipment sales. |
| NSF Certification Investment | Food-zone safety validation extends equipment longevity and justifies premium positioning in chain foodservice procurement. |
| India Distribution Infrastructure Buildout | Mumbai and Bangalore hubs capture organized QSR expansion in western and southern regional markets. |
Study Parameters
Direct dialogue with equipment procurement managers at United States quick-service chains, commercial kitchen consultants, refrigerant supply specialists, and aftermarket service technicians grounded qualitative findings. Secondary validation drew from EPA SNAP amendment filings, ECHA REACH compliance bulletins, NSF certification databases, and London Metal Exchange pricing records. Bottom-up equipment shipment tallies and top-down foodservice capital expenditure estimates were triangulated.
Bottom-up modeling tracked unit volumes across industrial batch freezer, soft-serve, countertop, and gelato product types, while top-down analysis calibrated against commercial foodservice equipment spending patterns. Segmentation dimensions included product format, refrigeration technology tier, end-user channel, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating compressor miniaturization adoption rates and hydrocarbon refrigerant penetration assumptions.
Several conditions sit outside the modeled scope, including potential EPA charge threshold revisions for R290 equipment and unscheduled F-Gas Regulation acceleration. Forecasts reflect assumptions about technician training pipeline expansion for hydrocarbon refrigerant handling. A model refresh is warranted upon material change in copper and aluminum price volatility or NSF certification timeline extensions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Global High Pressure Processing (HPP) Market
Food Processing Equipment
Electric Brewing System Market
Food Processing Equipment
Food Slicer and Dicer Market
Food Processing Equipment
Plastic Processing Equipment Market
Food Processing Equipment
US Cold Storage Market
Food Processing Equipment
Food Waste Shredder Market
Food Processing Equipment
Water Pod Soluble Machines Market
Food Processing Equipment
Continuous Fryer Machine Market
Food Processing Equipment
Exhaust Hood Filters and Cleaning Kits Market
Food Processing Equipment
Mobile Bottling Line Market
Food Processing Equipment
Global Food Sterilization Machines Market
Food Processing Equipment
Distillation Analyzer Market
Food Processing Equipment
Residential Food Waste Disposer Market
Food Processing Equipment
Mixing Vessels Market
Food Processing Equipment
Beverage Processing Equipment Market
Food Processing Equipment
UHT Systems Market