
 Global Tortilla Chips Market | 2026-2036
Global Tortilla Chips Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tortilla Chips Market Foresight
Stone-ground masa processing is tilting production economics toward authentic texture profiles and extended shelf stability. PepsiCo leverages its vertically integrated corn procurement network across the US Midwest to lock in supply consistency. Grupo Bimbo anchors its North American position through regional tortilla manufacturing hubs in Texas and California. GRUMA competes on nixtamalization expertise inherited from its Mexican operations, sustaining premium placement in both retail and foodservice channels.
Tortilla chips are thin, crispy snack products fabricated from nixtamalized corn masa that is sheeted, cut, fried or baked, and seasoned, typically achieving moisture content below 3% for shelf stability and structural crunch. The primary commercial purpose centers on ready-to-eat snacking occasions across retail and foodservice environments. Corn tortilla chips dominate volume throughput due to established consumer preference and lower input costs, though organic chips command disproportionate margin pools through certified non-GMO corn sourcing and clean-label positioning. Online retailers represent the fastest-growing distribution channel, driven by subscription snack boxes and direct-to-consumer replenishment cycles that bypass traditional wholesale markups.
FDA enforcement of updated Nutrition Facts labeling and serving-size standards directly shapes sodium and saturated fat reformulation targets across US-manufactured lines. EFSA allergen thresholds and EU Green Deal agricultural sustainability criteria are redirecting European corn sourcing toward regionally certified supply chains. Mexico's COFEPRIS food safety protocols for nixtamalized products maintain export eligibility standards that GRUMA and Arca Continental must navigate for cross-border trade. Stakeholders must monitor how dual carbon goals in China and evolving US bioengineered food disclosure rules will reshape corn input costs and labeling requirements.
Market Dynamics
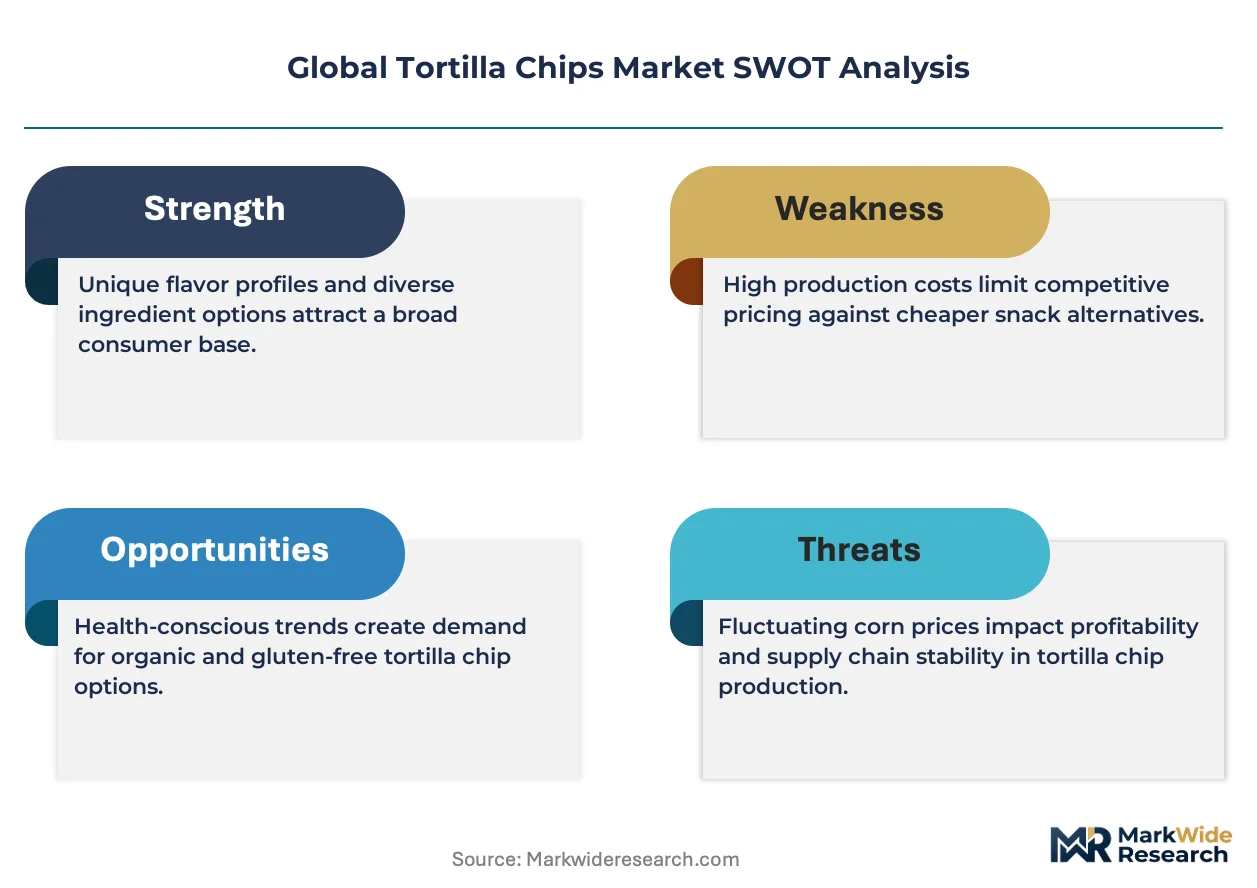
Stone-ground masa processing is compressing production costs for authentic texture profiles while FDA and EFSA disclosure mandates force simultaneous reformulation investments across legacy lines.
Growth Catalysts
- Clean-label corn sourcing mandates:FDA and EFSA tightening of ingredient disclosure norms is pulling reformulated SKUs into premium shelf positions.
- Convenience store channel expansion:North American c-store chains are dedicating incremental linear footage to grab-and-go tortilla chip formats.
- Nixtamalization expertise transfer:Traditional Mexican processing methods are scaling into US and Spanish manufacturing facilities.
Market Restraints
- Yellow corn price volatility:Midwest US drought cycles and biofuel diversion are squeezing input cost predictability for masa processors.
- Supply concentration in Nebraska-Iowa corridor:Three states control over sixty percent of US food-grade corn output, creating geographic risk.
- Sodium reduction technical floors:Taste thresholds below 140mg per serving trigger consumer rejection, capping reformulation flexibility.
Strategic Opportunities
- Subscription snack box penetration:Direct-to-consumer replenishment cycles are bypassing wholesale markups in US and UK markets.
- EU Green Deal agricultural incentives:Certified regional corn sourcing in France and Spain qualifies for sustainability-linked procurement contracts.
- Foodservice portion-control formats:Single-serve bags for workplace and hospitality channels remain underdeveloped relative to retail.
Industry Challenges
- Nixtamalization operator certification:Mexico's COFEPRIS protocols require specialized training pipelines that outpace available talent supply.
- Legacy fryer-to-oven capex conversion:Baked line transitions demand equipment replacement cycles exceeding typical depreciation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tortilla Chips Market |
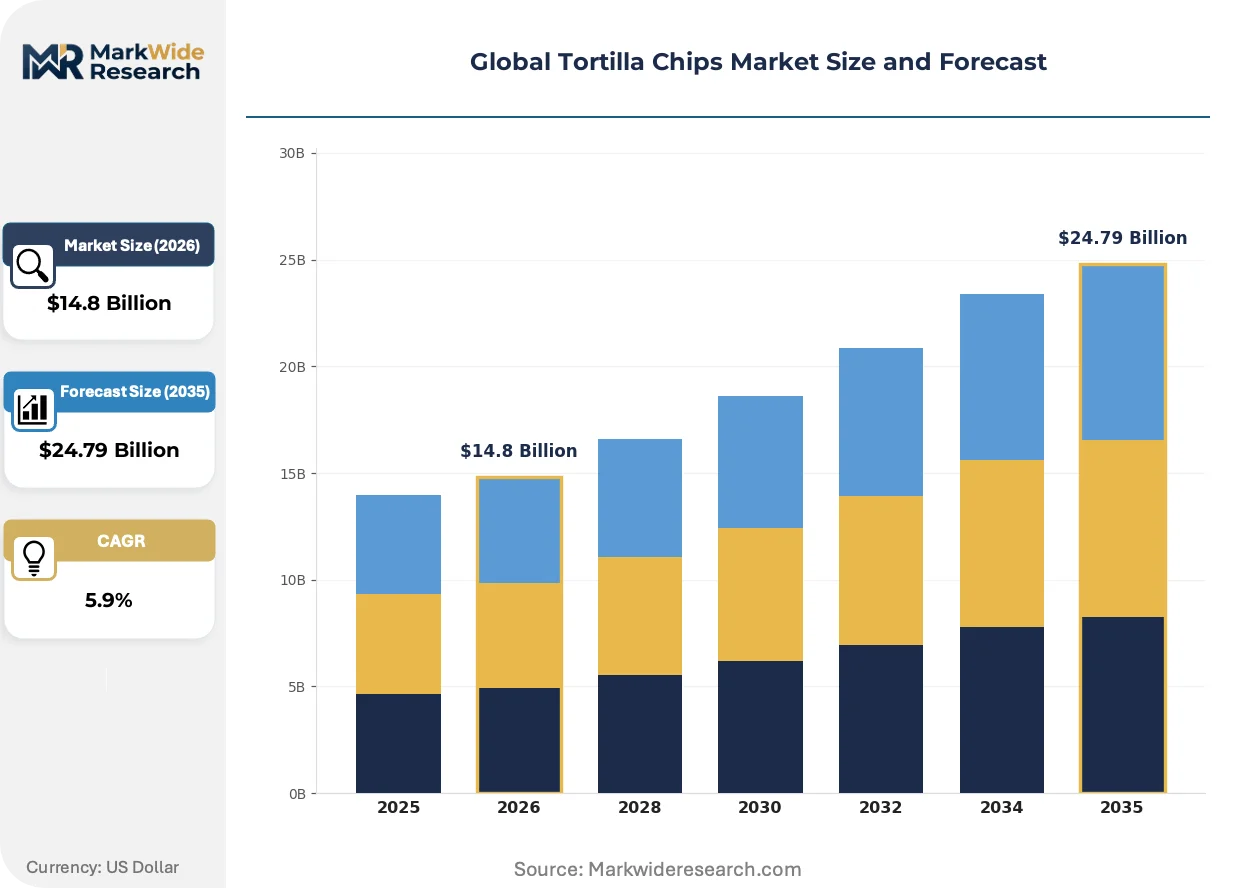
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.79 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corn Tortilla Chips, Multigrain Chips, Flavored Chips, Baked Chips, Organic Chips Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Stores, Wholesale Clubs Consumer Age Group: Children, Teens, Young Adults, Adults, Seniors Flavor Variant: Salted, Spicy Chili, Cheese, Barbecue, Lime |
| Companies Covered | PepsiCo, Grupo Bimbo, GRUMA, Truco Enterprises, Amplify Snack Brands, Arca Continental, Hain Celestial, Intersnack Group, Kellanova, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tortilla Chips Market Shifts & Advancements
Processing automation and regulatory disclosure requirements are simultaneously compressing cost structures and expanding label complexity across manufacturing footprints.
Continuous masa sheeting with real-time moisture sensors is rendering obsolete batch-style forming equipment that required manual thickness calibration. Mid-tier US processors are retrofitting lines at eighteen-month cycles. The technology is rendering obsolete capital-intensive downtime for texture inconsistency remediation.
EFSA's updated allergen threshold enforcement and EU Green Deal sustainability criteria are redirecting European corn sourcing toward regionally certified supply chains. French and Spanish manufacturers face compressed qualification timelines for cross-border retail placement. Organic-certified lines in Germany and Italy are absorbing disproportionate compliance investment.
Young adult snacking frequency in Mexico, the US, and Spain is rotating demand toward impulse-oriented package sizes. Convenience stores and automated retail are capturing volume from traditional grocery weekly stock-up trips. Urban clusters in Madrid, Los Angeles, and Mexico City exhibit the steepest channel-shift gradients.
Global Tortilla Chips Market Segmentation
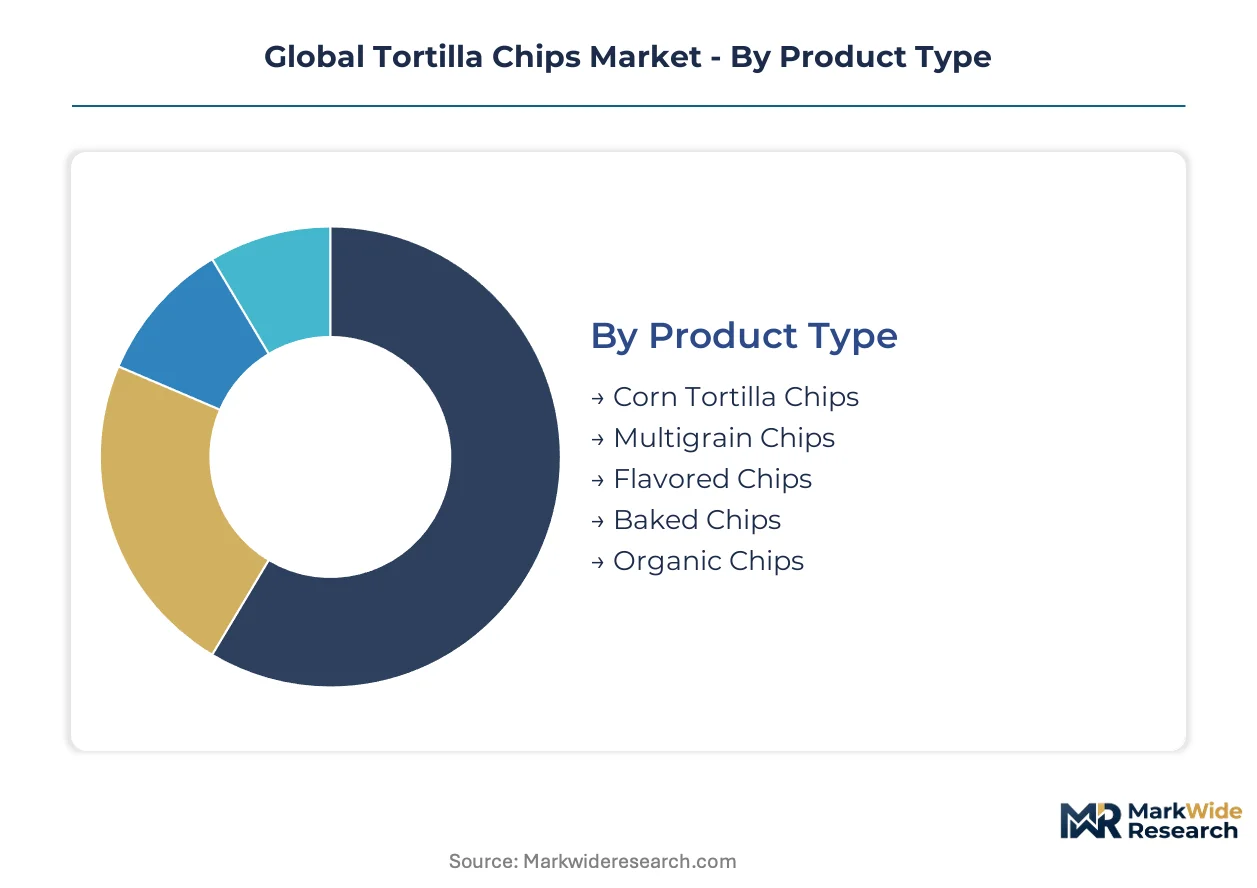
Segmentation in tortilla chips reveals how processing methods, channel economics, and demographic targeting create distinct margin pools. Each dimension carries different regulatory exposure and capital intensity requirements.
Product Type:
After-sales intensity varies sharply across processing formats, with nixtamalized lines demanding specialized maintenance versus extruded alternatives.
- Corn Tortilla Chips:Nixtamalized corn masa forms the base, achieving moisture content below 3% through frying or baking. Volume concentrates in US Midwest production corridors where yellow corn supply chains anchor cost structures.
- Multigrain Chips:Blend corn with quinoa, chia, or amaranth flours for elevated protein positioning. German and Italian retailers are expanding shelf space for these certified variants under EU Green Deal procurement incentives.
- Flavored Chips:Post-frying seasoning application with cheese, chili, or lime coatings.
- Baked Chips:Oven-dried alternative reducing oil absorption by 40-60%.
- Organic Chips:Certified non-GMO corn sourcing with full traceability documentation.
Corn tortilla chips hold the largest share; momentum sits with organic chips climbing the fastest on clean-label premiums.
Distribution Channel:
Channel selection dictates working capital cycles, with direct-to-consumer formats compressing payment terms versus traditional wholesale.
- Supermarkets:Dominant volume channel with weekly promotional cycles and slotting fee structures. Los Angeles, Mexico City, and Madrid retail clusters are reallocating linear footage toward grab-and-go formats.
- Convenience Stores:Impulse-oriented single-serve and sharing bags with higher per-unit margins. North American c-store chains are dedicating incremental shelf space to tortilla chip categories.
- Online Retailers:Subscription snack boxes and direct replenishment bypass wholesale markups. UK and US markets show steepest penetration gains.
- Specialty Stores:Premium positioning through ethnic grocers and health-focused retailers.
- Wholesale Clubs:Bulk-format sales with extended inventory turns and price-driven volume.
Supermarkets hold the largest share; online retailers are expanding most quickly on subscription model adoption.
Consumer Age Group:
Purchase frequency and occasion type rotate dramatically across life stages, from parental gatekeeping to autonomous snacking decisions.
- Young Adults:Highest per-capita consumption with preference for bold flavors and portable formats. Snacking frequency is climbing in Mexico, the US, and Spain among this cohort.
- Adults:Family-size purchasing with sodium-conscious selection criteria. FDA Nutrition Facts label updates directly shape reformulation targets for this segment.
- Children:Mild-flavor preference with parental oversight on ingredient panels.
- Teens:Social and impulse-driven consumption patterns.
- Seniors:Texture-sensitive preferences favoring thinner, lighter chips.
Adults hold the largest share; young adults are gaining share fastest on elevated snacking frequency.
Flavor Variant:
Flavor development pipelines face compressed qualification timelines as regional taste preferences diverge and clean-label seasoning constraints tighten.
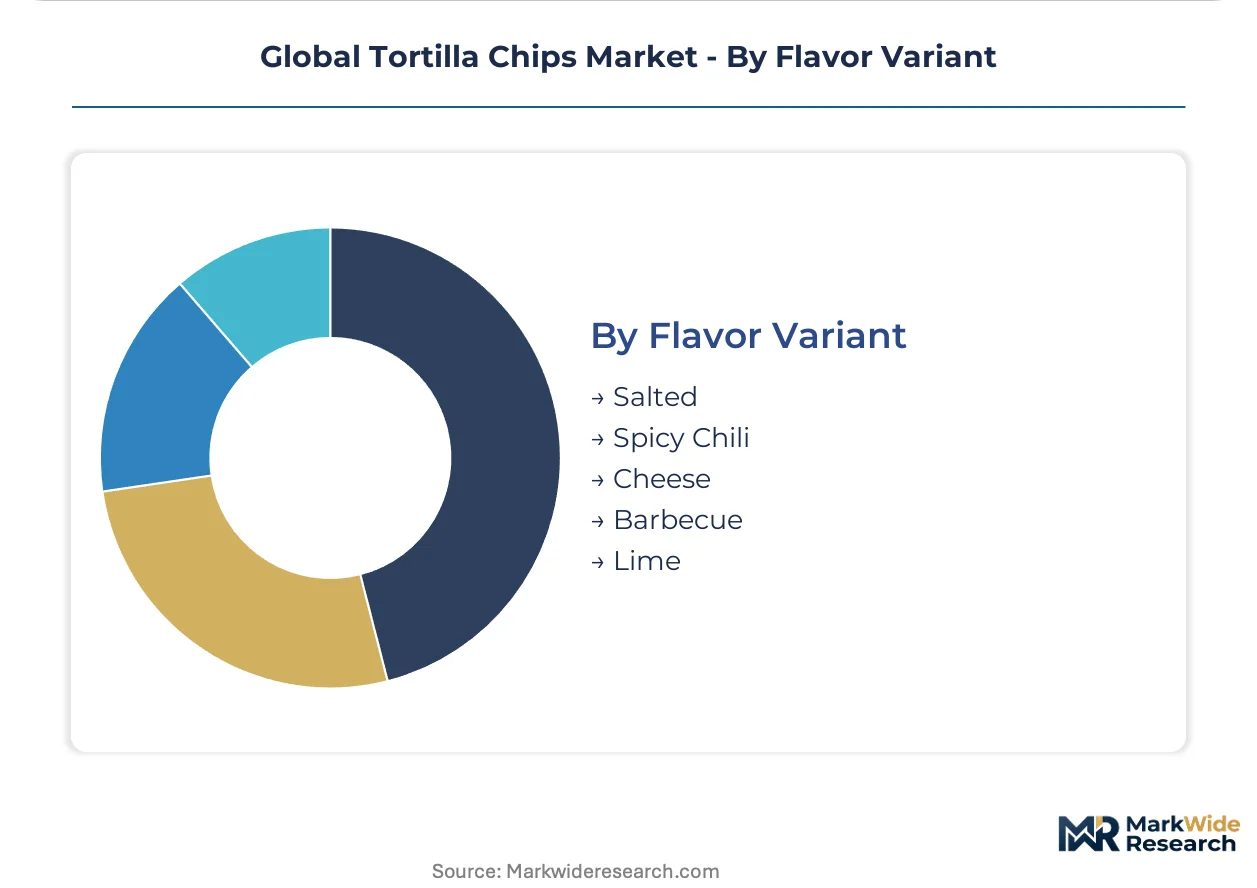
- Spicy Chili:Capsaicin-based heat profiles with regional Scoville calibration for Mexican, Texan, and Spanish palates. COFEPRIS food safety protocols govern chili powder sourcing for cross-border trade.
- Salted:Baseline formulation facing sodium reduction mandates. Taste thresholds below 140mg per serving trigger consumer rejection, capping FDA-driven reformulation flexibility.
- Cheese:Dairy-based or vegan seasoning alternatives with allergen disclosure requirements.
- Barbecue:Smoked-sweet profiles popular in North American markets.
- Lime:Citrus-acid coating requiring moisture barrier packaging.
Salted holds the largest share; spicy chili shows steepest expansion trajectory on authentic Mexican flavor migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico exports nixtamalized corn masa expertise and finished tortilla chips to the United States, Spain, and Latin American markets, establishing the primary trade-flow corridor for authentic processing methods and flavor profiles.
United States
Young adult snacking frequency drives impulse purchases in Los Angeles and Texas convenience store corridors. FDA updated Nutrition Facts labeling mandates sodium reformulation across legacy product lines. The US Midwest yellow corn belt anchors masa processor supply chains through Nebraska and Iowa sourcing networks.
Mexico
Domestic consumption of traditional nixtamalized chips sustains volume leadership alongside export manufacturing for cross-border trade. COFEPRIS food safety protocols govern operator certification requirements for nixtamalization facilities. Mexico City metro clusters concentrate both artisanal production and industrial-scale GRUMA manufacturing campuses.
Spain
Urban snacking rotation in Madrid accelerates grab-and-go format adoption among young adult demographics. EU Green Deal agricultural sustainability criteria redirect corn sourcing toward French and Spanish certified regional supply chains. Barcelona and Valencia manufacturing hubs process imported nixtamalization expertise for European retail placement.
Germany
Organic-certified multigrain chip variants gain shelf space under EU procurement incentives for certified regional sourcing. EFSA allergen threshold enforcement tightens disclosure requirements for flavored seasoning lines. Munich and Frankfurt retail clusters absorb disproportionate compliance investment for cross-border distribution.
United Kingdom
Subscription snack box penetration drives fastest-growing online retail channel expansion for direct-to-consumer replenishment. EFSA-aligned allergen regulations post-Brexit maintain threshold consistency with continental standards. London metro distribution networks bypass traditional wholesale markups through automated fulfillment infrastructure.
Global Tortilla Chips Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Consolidation concentrates around vertically integrated corn procurement networks and regional manufacturing hub strategies. Three archetypes dominate: multinational snack conglomerates with captive supply chains, heritage nixtamalization specialists leveraging Mexican operational expertise, and clean-label insurgents exploiting organic certification premiums. Competitive moves center on capacity expansion in Texas and California corridor manufacturing and strategic partnerships for European organic corn sourcing qualification.
Within the heritage nixtamalization tier, GRUMA exemplifies operational expertise transfer from Mexican facilities into US and Spanish manufacturing. Among multinational snack conglomerates, PepsiCo anchors scale-driven positions through Midwest corn procurement integration. At the clean-label premium vector, Hain Celestial occupies a position representing organic certification and non-GMO traceability positioning. These three companies collectively illustrate how procurement control, processing heritage, and label positioning segment competitive space.
| Leading Market Players |
|---|
| PepsiCo |
| Grupo Bimbo |
| GRUMA |
| Truco Enterprises |
| Amplify Snack Brands |
| Arca Continental |
| Hain Celestial |
| Intersnack Group |
| Kellanova |
| Others |
Supply & Pricing Matrix
Midwest rail corridors connecting Nebraska and Iowa corn terminals to Texas and California masa processing hubs transmit yellow corn price volatility directly into finished goods cost structures, compressing margins for non-integrated processors while amplifying pricing power for operators with captive supply networks.
Pricing Analysis
Batch-style nixtamalization equipment versus continuous sheeting lines with real-time moisture sensors creates a technology-generation pricing gap that stratifies the market. Three-tier pricing structure across organic-certified premium, conventional standard, and private-label economy levels dominates, with organic certification and nixtamalization authenticity as primary price differentiation drivers. Pricing pressure stems from yellow corn commodity swings and biofuel diversion demand, squeezing mid-tier processors most severely. Wholesale club buyers exhibit highest price sensitivity, while specialty ethnic grocers absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Export-control regimes on agricultural biotechnology and germplasm intellectual property constrain proprietary corn hybrid flows into European and Asian markets, fragmenting certified seed access. Supply concentrates in the US Midwest, with secondary sourcing from Mexican yellow corn belts and Argentine export terminals. Masa processors draw from nixtamalized corn, vegetable oils, and clean-label seasoning inputs. Single-source vulnerability pervades the Nebraska-Iowa corn corridor, where drought cycles and biofuel policy shifts cascade unpredictably. Distribution runs through wholesale club and supermarket intermediaries, though direct-to-consumer subscription channels are compressing traditional markup layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment around FDA and EFSA clean-label disclosure standards creates persistent barriers for unqualified entrants.
For Market Incumbents: Pre-empt capacity constraints in Texas and California manufacturing corridors by securing nixtamalization operator certification pipelines ahead of COFEPRIS-mandated talent shortages. Anchor backward integration into Midwest corn procurement networks to neutralize yellow price volatility exposure. Defend shelf position through accelerated baked-line capex conversion before sodium reduction mandates harden into irreversible technical floors. For New Entrants and Emerging Players: Establish a beachhead in organic-certified multigrain variants where EU Green Deal procurement incentives and EFSA allergen thresholds have slowed incumbent qualification timelines. Target German and Italian retail clusters absorbing disproportionate compliance investment for cross-border distribution. Deploy direct-to-consumer subscription models to bypass wholesale slotting fee structures that entrench legacy players. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational snack conglomerates divesting non-core regional tortilla brands lacking nixtamalization heritage. Long-term viability centers on processing authenticity and certified supply chain control rather than flavor innovation alone. Watch for FDA bioengineered food disclosure rule implementation as an inflection signal that would force reformulation capex cycles favoring pre-compliant assets.| Strategic Initiative | Industry Significance |
|---|---|
| Nixtamalization Operator Certification Pipeline | COFEPRIS-mandated training requirements outpace available talent supply in US and Spanish facilities. |
| Continuous Masa Sheeting Retrofit | Real-time moisture sensors render obsolete batch-style equipment requiring manual thickness calibration. |
| EU Green Deal Corn Sourcing Qualification | French and Spanish certified regional supply chains unlock sustainability-linked procurement contracts. |
| Direct-to-Consumer Subscription Launch | UK and US automated fulfillment infrastructure bypasses traditional wholesale markup layers. |
| Baked Line Capacity Conversion | Oven-dried alternatives reduce oil absorption by 40-60%, meeting FDA sodium reduction targets. |
Research Methodology
Cross-validation between executive interviews at GRUMA, PepsiCo, and Grupo Bimbo operations divisions and secondary validation through FDA enforcement actions, EFSA allergen threshold documentation, and COFEPRIS facility inspection records anchors the qualitative findings. Primary fieldwork engaged masa processing plant managers, category buyers at Los Angeles and Madrid retail clusters, corn procurement leads at Nebraska grain elevators, and nixtamalization equipment specialists. Secondary sources encompassed customs trade data for yellow corn and finished tortilla chip flows, SEC 10-K filings for disclosed snack segment performance, and Nielsen retail audit data for channel shift patterns. Bottom-up volume modeling triangulated against top-down macro consumption trends.
Calibration against historical price elasticity responses to corn commodity spikes and sodium reformulation rollout timelines refined the analytical framework. Segmentation dimensions modeled include processing method, distribution channel, consumer age cohort, and flavor variant across the projection horizon. CAGRs derived from trend extrapolation of snacking frequency surveys and channel penetration curves, with nixtamalization expertise transfer rates and clean-label certification adoption as industry-specific forecast inputs.
Stress conditions across Midwest drought severity, FDA disclosure rule enforcement timing, and EU Green Deal subsidy allocation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding young adult snacking trajectory and c-store linear footage expansion. Material shifts in biofuel policy diverting yellow corn from food-grade channels would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Saudi Arabia Snacks Industry Market
Snacks
China Snack Bar Market
Snacks
North America Potato Chips Market
Snacks
Fat Free Meals and Snacks Market
Snacks
Healthy Fat-Free Snacks Market
Snacks
Dairy Snacks Market
Snacks
Legume-Based Snacks Market
Snacks
Veggie Chips Market
Snacks
Asia Pacific Frozen Snacks Market
Snacks
US Potato Chips Market
Snacks
Spain Snack Bar Market
Snacks
Low Fat Sweet Snacks Market
Snacks
On-The-Go Healthy Snacks Market
Snacks
Global Protein Snack Market
Snacks
Super Low Calorie Snacks Market
Snacks
Low Calorie Snacks Market