
 Global Cosmetics OEM/ODM Market | 2026-2036
Global Cosmetics OEM/ODM Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cosmetics OEM/ODM Market Analysis
Indie beauty brands are rotating into the client mix as the fastest-expanding buyer archetype, displacing traditional mass-market dependence on large-volume contracts. Cosmax Inc leverages integrated R&D campuses in South Korea to sustain formulation leadership across K-beauty exports. Intercos S.p.A anchors European luxury supply through specialized color cosmetics manufacturing in Italy. Kolmar Korea competes on manufacturing scale, operating multiple facilities that dominate regional skincare OEM output.
Cosmetics OEM/ODM denotes third-party manufacturing services where contracted facilities formulate, produce, and package beauty products to client specifications, typically involving emulsion processing at precise temperature controls between 70-85°C for cream bases and powder micronization below 20 microns for color consistency. The primary commercial purpose is to enable brand owners to commercialize products without capital-intensive production infrastructure. Skincare leads product type revenue due to higher per-unit formulation complexity and longer development cycles that lock in client relationships. Indie brands within client type represent the fastest-expanding segment, though luxury brands still concentrate margin pools through premium pricing and exclusive contract terms. Eco-friendly packaging is accelerating fastest among packaging types as EU Green Deal requirements reshape procurement specifications.
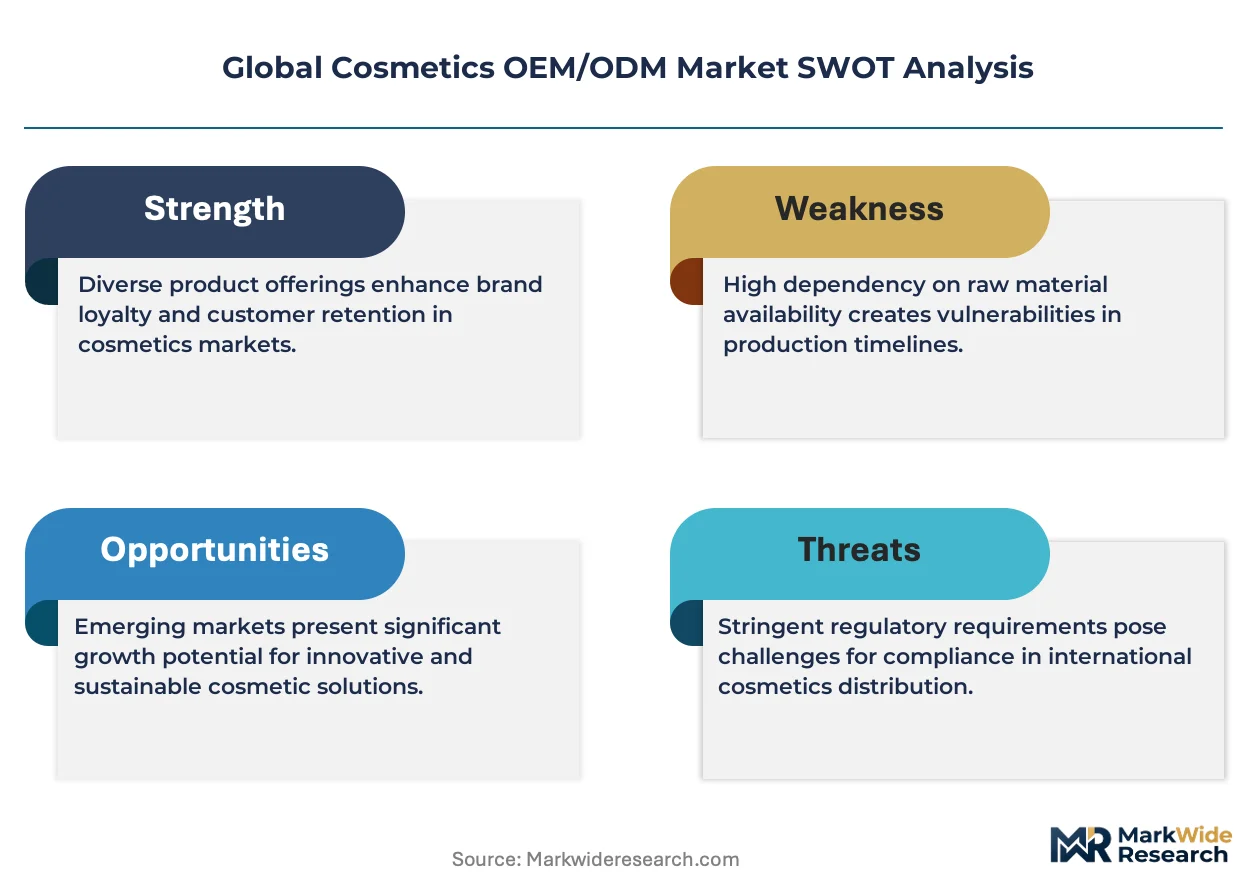
FDA cosmetic registration requirements under the Modernization of Cosmetics Regulation Act reshape U.S. market access timelines and ingredient disclosure standards. REACH compliance in Europe and China's GB standards for cosmetics safety testing create layered regulatory barriers that favor OEM/ODM partners with dedicated regulatory affairs teams. South Korea's MFDS enforces stringent stability testing protocols that Kolmar Korea and Cosmecca Korea have built specialized infrastructure to navigate. Stakeholders must monitor how diverging clean beauty definitions across FDA, REACH, and MFDS frameworks fragment formulation standardization and raise compliance costs for multi-region brand portfolios.
Market Dynamics
Clean beauty mandates under the EU Green Deal and REACH compliance requirements are forcing formulation upgrades across the supply base, while indie brand demand fragments order patterns away from mass-market volume contracts.
Growth Catalysts
- EU Green Deal chemical restrictions:REACH Annex XVII expansions on microplastics and endocrine disruptors compel brands to reformulate through OEM partners with dedicated clean chemistry capabilities.
- Biotechnology-derived actives:Fermentation-based ingredients and lab-grown alternatives to palm-derived emollients reduce supply chain volatility while meeting consumer transparency demands.
- South Korea's Incheon-Free Economic Zone:Concentrated R&D infrastructure and MFDS-aligned stability testing protocols attract global brand outsourcing for K-beauty positioning.
Market Restraints
- Specialty chemical input costs:Volatility in squalane, ceramides, and peptide supply chains squeezes margin buffers for mid-tier contract manufacturers.
- Single-region production concentration:Heavy reliance on South Korean skincare OEM capacity creates geographic risk exposure for brands seeking supply diversification.
- Stability testing bottlenecks:MFDS and FDA divergent shelf-life validation protocols extend product launch timelines by 4-8 months for multi-region portfolios.
Strategic Opportunities
- India's emerging brand ecosystem:Domestic D2C beauty launches under BIS and CDSCO frameworks lack mature local OEM infrastructure, creating first-mover positioning for compliant entrants.
- Refillable and mono-material packaging:EU Packaging and Packaging Waste Regulation mandates are accelerating demand for OEM partners with integrated sustainable packaging engineering.
- AI-driven formulation optimization:Machine learning convergence with high-throughput screening compresses development cycles for personalized skincare lines.
Industry Challenges
- Regulatory affairs talent scarcity:Shortage of professionals fluent in FDA MoCRA, REACH, and MFDS filing requirements drives compensation inflation and delays market entry.
- Legacy ERP integration:Indie brand clients demand real-time batch tracking and co-development portals that strain manufacturer IT infrastructure.
- Clean beauty definition fragmentation:Absence of harmonized standards across EU, US, and South Korean jurisdictions forces redundant certification processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cosmetics OEM/ODM Market |
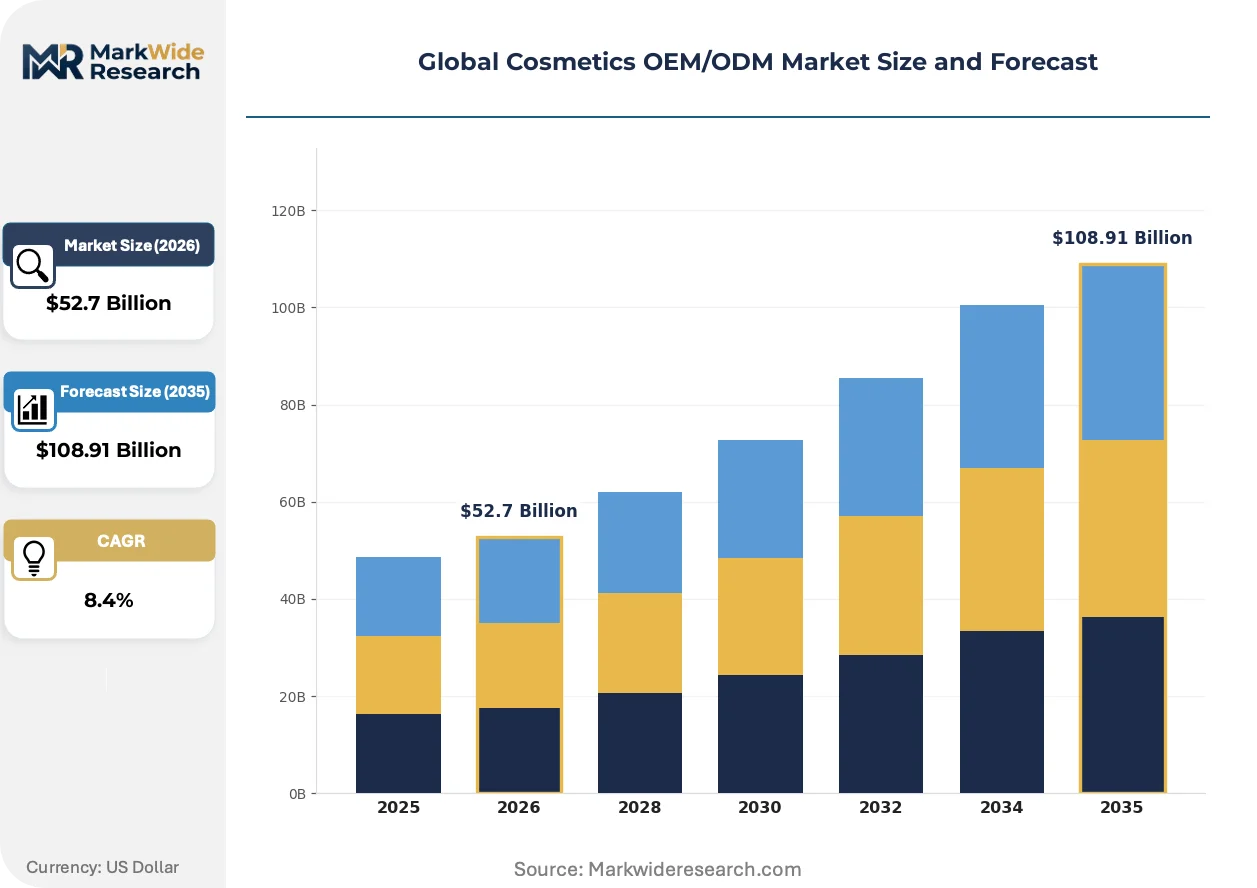
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $108.91 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Makeup, Fragrance, Haircare Client Type: Private Labels, Luxury Brands, Mass Market, Indie Brands Packaging Type: Glass, Plastic, Metal, Eco-friendly Formulation Type: Creams, Powders, Gels, Oils |
| Companies Covered | Cosmax Inc, Intercos S.p.A, Kolmar Korea, Nox Bellcow Cosmetics, Nihon Kolmar, Cosmecca Korea, Toyo Beauty Co. Ltd., Ancorotti Cosmetics S.p.A, Cosmobeauty Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cosmetics OEM/ODM Market Emerging Trajectories
Active ingredient delivery systems and sustainable chemistry platforms are compressing development timelines while regulatory divergence forces parallel compliance investments.
Encapsulation technology using lipid nanoparticles and cyclodextrin complexes is miniaturizing active molecule size for enhanced dermal penetration. Indie skincare brands are adopting these systems at accelerated pace for differentiation in crowded serums and treatments categories. This compression of efficacy claims into smaller molecular architectures is displacing conventional emulsion-based delivery in premium positioning.
REACH microplastic restrictions and the EU Green Deal's chemical sustainability criteria are banning intentionally added microplastics in rinse-off cosmetics by 2026 with leave-on extensions following. Manufacturers must reformulate exfoliants, glitter, and texture modifiers using biodegradable alternatives such as cellulose, rice starch, or mineral substitutes. Color cosmetics and body care segments face the steepest substitution costs, with Italian and French luxury suppliers investing in dedicated clean chemistry campuses.
Direct-to-consumer sampling and subscription models are compressing minimum order quantities and accelerating SKU proliferation. Traditional retail-dependent brands are unbundling from department store exclusivity, forcing OEM partners to accommodate 500-unit production runs with 12-week turnaround. This fragmentation is most visible in North American and Western European indie brand ecosystems where venture-backed launches prioritize speed-to-market over scale economies.
Global Cosmetics OEM/ODM Market Segmentation
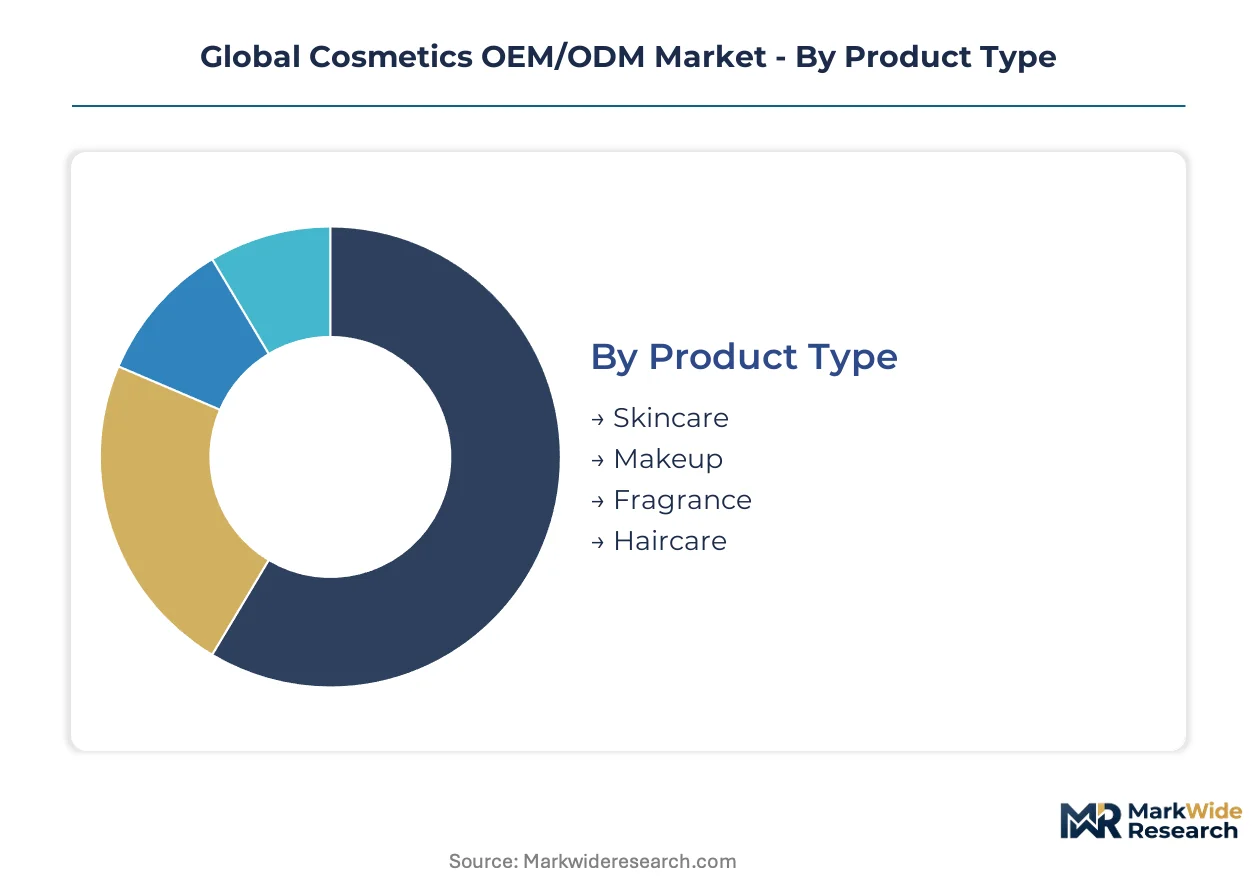
Cosmetics OEM/ODM manufacturers configure production lines around formulation physics and client operational models. Regulatory filing requirements diverge sharply across product chemistry and end-market positioning, fragmenting compliance pathways.
Product Type:
REACH Annex XVII restrictions on microplastics and endocrine disruptors impose tiered compliance burdens depending on rinse-off versus leave-on classification.
- Skincare:Emulsion processing at 70-85°C demands precise temperature-controlled batch reactors. Demand concentrates in South Korea's Incheon-Free Economic Zone, where MFDS stability testing protocols lock in 12-18 month development cycles that deepen client retention.
- Makeup:Powder micronization below 20 microns for color consistency requires dedicated milling infrastructure. Italian and French luxury suppliers anchor European capacity, with REACH microplastic bans forcing reformulation of glitter and texture modifiers into cellulose or mineral substitutes.
- Fragrance:Alcohol-based dilution and maceration processes face volatile ethanol supply costs.
- Haircare:Surfactant chemistry and conditioning polymer selection dominate formulation complexity.
Skincare handles the majority of throughput; indie brand demand within makeup is gaining share fastest.
Client Type:
Order volume patterns and technical service intensity separate margin profiles across buyer archetypes.
- Indie Brands:Venture-backed D2C launches compress minimum order quantities to 500-unit runs with 12-week turnaround demands. North American and Western European ecosystems show the steepest expansion trajectory as brands unbundle from department store exclusivity.
- Luxury Brands:Exclusive contract terms and premium pricing sustain margin pools through dedicated R&D campus access. Italian color cosmetics specialists anchor European supply relationships with multi-year development partnerships.
- Private Labels:Retailer-controlled brands prioritize cost engineering over formulation differentiation.
- Mass Market:Large-volume contracts face displacement as buyer mix rotates toward fragmented order patterns.
Luxury brands retain the dominant margin share; indie brands are expanding most quickly on client count.
Packaging Type:
EU Packaging and Packaging Waste Regulation mandates are reshaping procurement specifications across material categories.
- Eco-friendly:Refillable systems and mono-material designs accelerate fastest under EU Green Deal compliance timelines. Manufacturers with integrated sustainable packaging engineering capture repositioning brand budgets as plastic substitution deadlines approach.
- Glass:Premium skincare and fragrance positioning relies on borosilicate and molded glass supply chains concentrated in France and Germany.
- Plastic:PET and PP formats face recycled content mandates under REACH circular economy provisions.
- Metal:Aluminum aerosols and compacts serve mass-market haircare and color cosmetics with lower per-unit packaging costs.
Plastic still moves the highest unit volumes; eco-friendly formats are climbing the fastest on specification change.
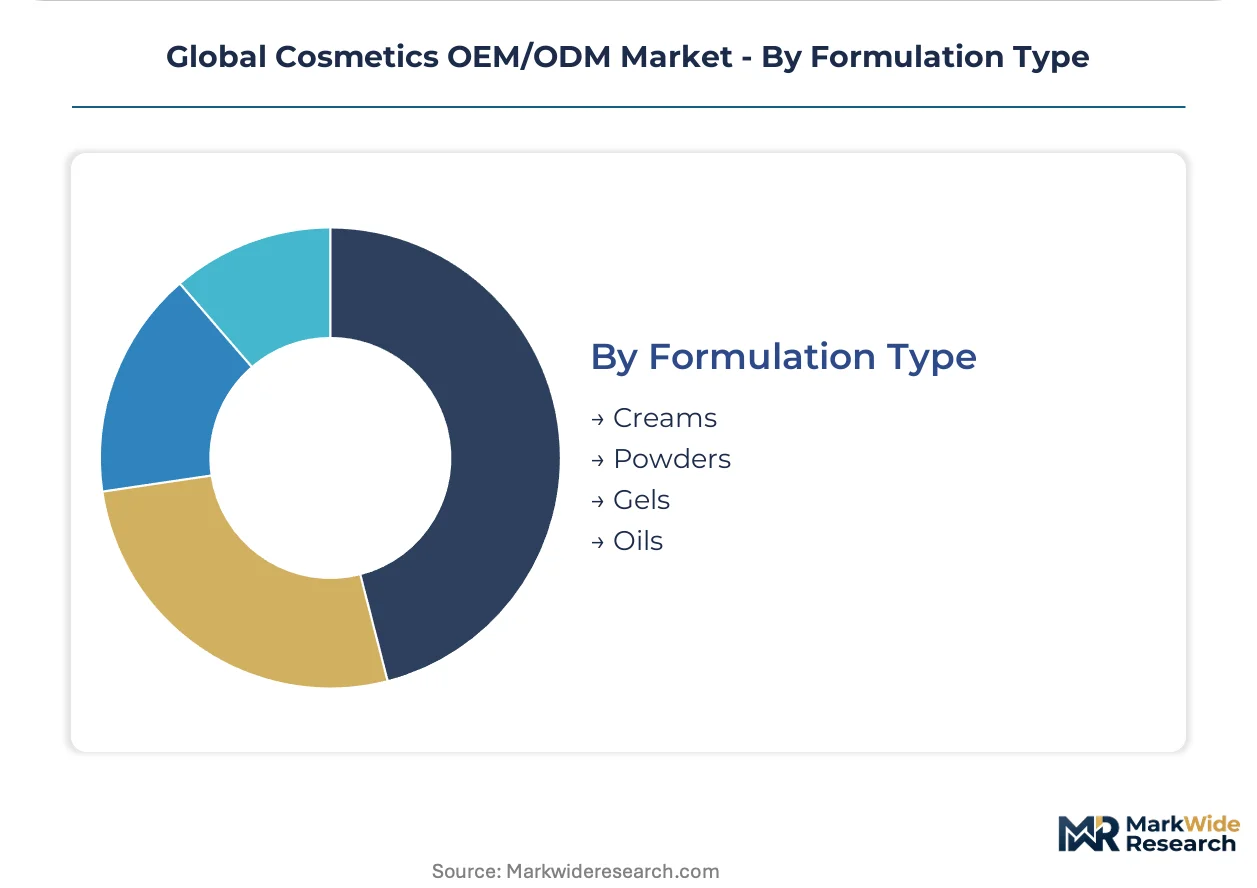
Formulation Type:
Physical state determines equipment capital requirements and batch processing economics.
- Creams:Oil-in-water emulsions dominate skincare manufacturing with the longest development cycles and highest per-unit formulation complexity. South Korean OEMs anchor regional capacity through integrated R&D campuses serving K-beauty export positioning.
- Powders:Pressed and loose formats in color cosmetics require micronization and binding agent expertise. Italian manufacturers lead specialized capacity for luxury brand relationships.
- Gels:Carbomer-thickened aqueous systems serve lower-cost skincare and haircare segments with faster batch turnaround.
- Oils:Anhydrous formulations bypass emulsion stability challenges but face squalane and plant-derived emollient supply volatility.
Creams absorb the greatest R&D investment; powders are expanding fastest on color cosmetics SKU proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cosmetics OEM/ODM capacity clusters most densely in South Korea's Incheon-Free Economic Zone, where MFDS-aligned stability testing infrastructure and K-beauty export positioning attract global brand outsourcing. Secondary concentrations operate in Italy's color cosmetics belt and the United States' contract manufacturing corridors.
South Korea
Seoul Capital Area OEMs process the majority of global K-beauty export volume through integrated R&D campuses. MFDS enforces stringent 12-18 month stability testing protocols that deepen client retention. Incheon-Free Economic Zone hosts Cosmax, Kolmar Korea, and Cosmecca Korea facilities serving venture-backed indie brands with compressed turnaround demands.
United States
FDA MoCRA registration requirements reshape market access timelines for domestic and foreign brands seeking U.S. distribution. Modernization of Cosmetics Regulation Act mandates facility registration and ingredient disclosure standards that favor OEM partners with dedicated regulatory affairs teams. New Jersey and California corridors concentrate contract manufacturing serving D2C indie launches.
Italy
Color cosmetics manufacturing anchors European luxury supply through specialized milling and pressing infrastructure. REACH Annex XVII microplastic bans force reformulation of glitter and texture modifiers into cellulose or mineral substitutes. Lombardy and Piedmont regions host Intercos S.p.A and Ancorotti Cosmetics S.p.A facilities with multi-year development partnerships.
China
NMPA and GB standards for cosmetics safety testing create layered regulatory barriers for foreign brand entry. Yangtze River Delta and Pearl River Delta clusters process domestic volume and export positioning for regional beauty brands. Shanghai and Guangzhou corridors concentrate mid-tier contract manufacturers serving private label and mass-market segments.
Japan
PMDA and METI frameworks enforce quality management system requirements that extend product development cycles. Kanto and Kansai regions host Toyo Beauty Co. Ltd. and Nihon Kolmar facilities with specialized fermentation-based active ingredient capabilities. Tokyo-Osaka manufacturing belt serves domestic luxury positioning and selective export markets.
Global Cosmetics OEM/ODM Market Vendor Landscape
Concentration sits with integrated R&D campus operators and specialized color cosmetics manufacturers. Tiered competition separates scale-driven Korean skincare OEMs from Italian luxury color specialists and mid-tier regional fabricators. Strategic archetypes include integrated R&D campus operators, specialized color cosmetics manufacturers, and fermentation-based active ingredient specialists. Dominant competitive moves encompass geographic capacity expansion into India's emerging brand ecosystem and portfolio diversification into sustainable packaging engineering.
Among Korean integrated manufacturers, Cosmax Inc, Kolmar Korea, and Cosmecca Korea exemplify the R&D campus archetype with MFDS-aligned infrastructure. Italian specialists Intercos S.p.A and Ancorotti Cosmetics S.p.A occupy positions in luxury color cosmetics manufacturing. Japanese fermentation capabilities are represented by Nihon Kolmar and Toyo Beauty Co. Ltd. Chinese contract manufacturers Nox Bellcow Cosmetics and Cosmobeauty Co., Ltd. sit within mid-tier regional supply serving private label demand.
| Leading Market Players |
|---|
| Cosmax Inc |
| Intercos S.p.A |
| Kolmar Korea |
| Nox Bellcow Cosmetics |
| Nihon Kolmar |
| Cosmecca Korea |
| Toyo Beauty Co. Ltd. |
| Ancorotti Cosmetics S.p.A |
| Cosmobeauty Co., Ltd |
| Others |
Supply Flow & Price Mechanics
Cellulose and mineral substitutes replacing microplastic exfoliants and glitter simultaneously redraw raw material sourcing maps from petrochemical hubs toward agricultural processing regions and reshape unit economics for color cosmetics manufacturers facing REACH Annex XVII compliance deadlines. This substitution dynamic compresses margin buffers for mid-tier contract manufacturers while rewarding integrated players with captive biopolymer supply relationships.
Pricing Analysis
REACH Annex XVII dictates the pricing tier structure across the Cosmetics OEM/ODM landscape. Three-tier pricing structure across premium, standard, and economy levels separates luxury brands with exclusive R&D campus access from indie brands purchasing 500-unit minimums and mass-market private labels. Price differentiation hinges on certification grade for MFDS-aligned stability protocols and volume scale for batch processing economics. Pricing pressure stems from specialty chemical input volatility in squalane and ceramide supply chains. Mass-market private labels exhibit highest price sensitivity; luxury brands with multi-year development partnerships demonstrate lowest.
Supply Chain Analysis
South Korea and Italy anchor global Cosmetics OEM/ODM capacity through contrasting specializations. South Korea's Incheon-Free Economic Zone hosts integrated R&D campuses serving K-beauty export demand, while Italy's Lombardy-Piedmont belt concentrates luxury color cosmetics milling infrastructure. Raw material dependencies center on fermentation-derived actives, palm oil alternatives, and borosilicate glass for premium packaging. Single-region production concentration in South Korean skincare OEMs creates geographic risk exposure for brands seeking supply diversification. Distribution runs through direct-to-consumer channels for venture-backed indie launches and long-term exclusive contracts for luxury houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Cosmetics OEM/ODM Market sits in early-cycle recovery as indie brand formation rates rebound from post-2022 venture funding constraints and inventory destocking cycles complete across North American and Western European retail channels.
For Market Incumbents: Compound defensive positioning through backward integration into sustainable packaging engineering and captive fermentation-based active ingredient production. Kolmar Korea and Cosmax Inc should expand MFDS-aligned stability testing infrastructure to deepen client retention against emerging Indian contract manufacturers. Regulatory affairs talent scarcity threatens margin sustainability; incumbents must lock compliance specialists through multi-year retention structures before compensation inflation accelerates further. For New Entrants and Emerging Players: Differentiate on AI-driven formulation optimization and compressed development cycles for personalized skincare lines. India's emerging D2C brand ecosystem under BIS and CDSCO frameworks offers the most penetrable geography, lacking mature local OEM infrastructure. Target first-mover positioning through compliant manufacturing capacity in Mumbai-Delhi corridors before incumbent Korean and Italian players establish regional facilities. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier contract manufacturers in China's Yangtze River Delta struggling with NMPA compliance costs and margin compression. Long-term viability over the next decade favors integrated R&D campus operators with multi-regulatory filing capabilities across FDA MoCRA, REACH, and MFDS frameworks. Watch for inflection signals in India's domestic beauty brand formation rates and venture capital deployment into D2C cosmetics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sustainable Packaging | EU Packaging and Packaging Waste Regulation mandates accelerate demand for refillable mono-material engineering capabilities. |
| AI-Driven Formulation Optimization | Machine learning convergence with high-throughput screening compresses development cycles for personalized skincare launches. |
| Geographic Expansion into India | BIS and CDSCO compliance gaps in domestic OEM infrastructure create first-mover positioning for compliant entrants. |
| Fermentation-Based Active Ingredient Capacity | Lab-grown alternatives to palm-derived emollients reduce supply chain volatility while meeting clean beauty transparency demands. |
| Multi-Regulatory Filing Infrastructure | Divergent FDA, REACH, and MFDS clean beauty definitions favor OEM partners with dedicated regulatory affairs teams. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade flow databases, and industry association disclosures. Interviews with contract manufacturing executives, brand R&D directors, regulatory affairs specialists, and raw material procurement leads informed demand-side and supply-side dynamics. Secondary validation drew from FDA MoCRA registration databases, ECHA REACH Annex XVII updates, MFDS stability testing protocols, and customs records for cosmetics ingredient trade flows. Bottom-up capacity assessments across South Korea's Incheon-Free Economic Zone, Italy's color cosmetics belt, and India's emerging manufacturing corridors triangulated against top-down market sizing.
Segmentation dimensions modeled include product type, client archetype, packaging format, and formulation physics across the projection horizon. Skincare, makeup, fragrance, and haircare categories were disaggregated by emulsion complexity and regulatory filing burden. Client type segmentation captured indie brand, luxury house, private label, and mass-market order patterns. CAGRs were derived from production capacity expansion announcements, client win/loss tracking, and pricing trend analysis. Forecast inputs incorporated EU Green Deal chemical restriction timelines and venture capital deployment into D2C beauty.
The analysis sits within stated boundaries; outcomes outside sustained indie brand formation rates, stable specialty chemical input costs, or harmonized clean beauty regulatory convergence would require recalibration. Forecasts reflect assumptions regarding MFDS stability testing protocol continuity, REACH microplastic ban enforcement schedules, and fermentation technology scale-up economics. Recalibration cycles align with material shifts in regulatory enforcement intensity, venture funding availability for beauty startups, and biopolymer substitution cost parity milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
European Fragrances Microencapsulation Market
Cosmetic Chemicals
Jojoba Oil Derivatives Market
Cosmetic Chemicals
Facial Essence Market
Cosmetic Chemicals
Lanolin Nipple Cream Market
Cosmetic Chemicals
Cosmetic Kaolin Powder Market
Cosmetic Chemicals
Herbal Mascara Market
Cosmetic Chemicals
MENA/G.C.C./China Cosmetics and Personal Care Ingredients Market
Cosmetic Chemicals
Liposome in Cosmetics Market
Cosmetic Chemicals
Fractionated Shea Butter in Cosmetics and Personal Care Market
Cosmetic Chemicals
Shea Butter Market
Cosmetic Chemicals
Methylisothiazolinone Market
Cosmetic Chemicals
China Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Canada Eyeshadow Stick and Blush Stick Market
Cosmetic Chemicals
North America Jojoba Oil Market
Cosmetic Chemicals
PRP and PRF in Cosmetics Market
Cosmetic Chemicals
Minoxidil Market