
 Herbal Mascara Market | 2026-2036
Herbal Mascara Market Size, Share, and Industry Trends Forecast 2026-2036
Herbal Mascara Market Outlook
The gap between premium botanical formulations and mass-market herbal claims is broadening as ingredient transparency becomes a decisive purchase factor. Cheekbone Beauty leverages Indigenous botanical sourcing to anchor its positioning in the North American clean beauty channel. ILIA competes through gel-based technology leadership that extends wear performance without synthetic polymers. 100% PURE sustains its market presence through in-house vertical control over fruit-pigment extraction.
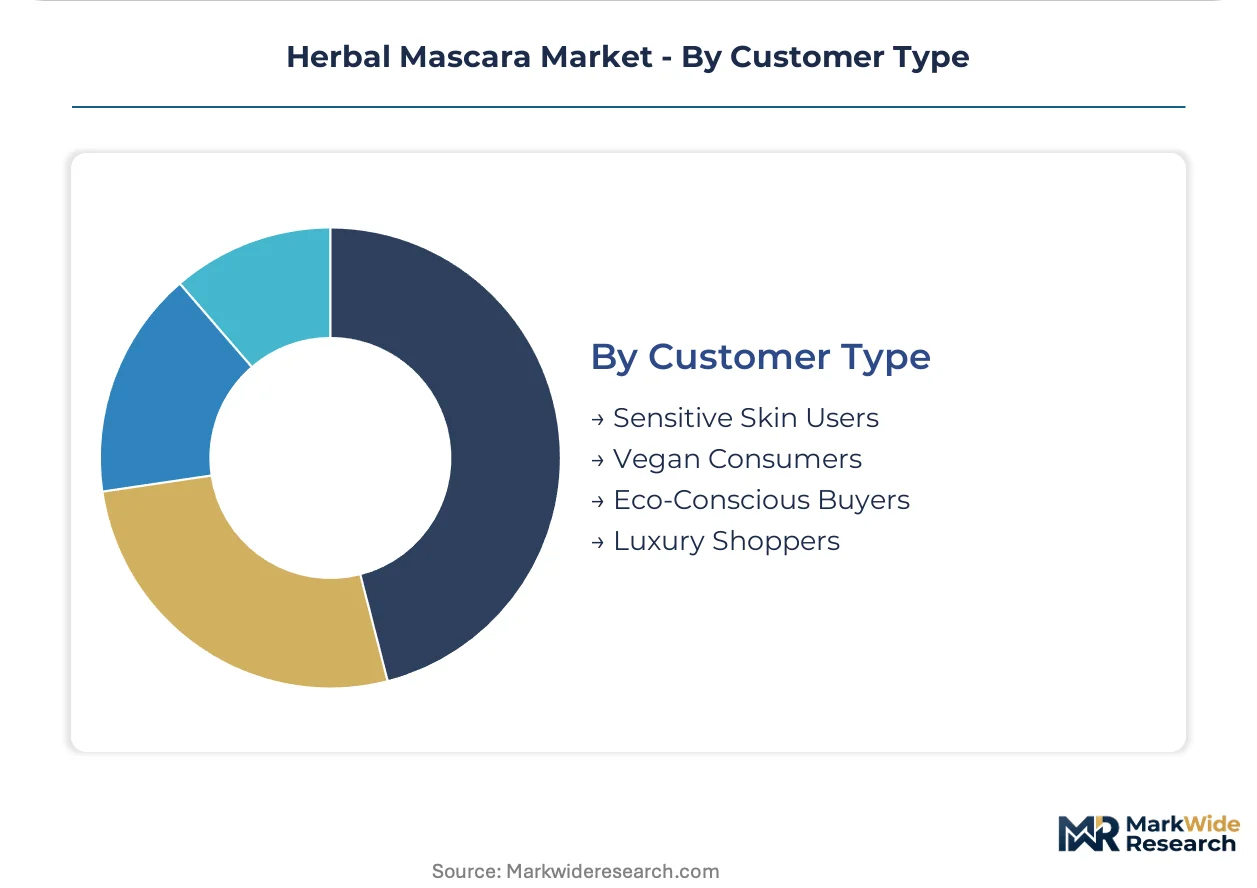
Herbal mascara denotes lash colorants formulated with plant-derived waxes, oils, and mineral pigments rather than petroleum-based synthetics or coal-tar dyes, typically achieving color payoff through iron oxides or carbon black alternatives suspended in beeswax or carnauba bases. The formulation dimension separates mature cream-based offerings from faster-growing gel systems that deliver flexible hold. Volumizing product types dominate current revenue pools, while waterproof variants remain underdeveloped due to formulation complexity with natural binders. Customer type segmentation reveals the steepest growth curve among vegan consumers, though sensitive skin users represent the largest existing wallet share.
FDA cosmetic labeling requirements and EU REACH pigment restrictions jointly determine which botanical inputs qualify for commercial scale in the United States and European markets. ECHA's evolving stance on carbon black alternatives creates compliance-driven R&D allocation across formulators serving both jurisdictions. Stakeholders must monitor how regulatory divergence on natural claim definitions reshapes product development roadmaps and cross-border market access requirements.
Market Dynamics
Formulation chemistry sits at the center of competitive positioning in herbal mascara, as the tension between natural claim authenticity and performance parity with synthetic alternatives determines which brands capture professional makeup artist loyalty and clean beauty consumer wallet share.
Growth Catalysts
- REACH pigment restrictions:ECHA's tightening rules on carbon black alternatives force legacy synthetics out of European formulations, redirecting R&D budgets toward botanical colorant verification and iron oxide suspension systems.
- Vegan consumer segment expansion:Plant-derived wax bases replace beeswax in formulations targeting cruelty-free certification, with carnauba and candelilla wax suppliers scaling extraction capacity to meet formulator procurement volumes.
- Professional channel validation:Makeup artists working red-carpet and editorial shoots now specify herbal mascara in kit requirements, creating downstream pull through retail recommendations and social proof amplification.
Market Restraints
- Carnauba wax supply concentration:Brazilian harvest volatility and processing bottlenecks in Ceará state create input cost instability for formulators dependent on plant-based film-formers.
- Waterproof performance ceiling:Natural binder chemistry cannot yet match synthetic polymer durability in high-humidity or tear-resistant applications, limiting product type expansion.
- FDA-EU claim divergence:Incompatible natural definition standards between American and European regulators force dual-labeling costs and inventory segmentation for cross-border brands.
Strategic Opportunities
- India domestic market penetration:Ayush Ministry recognition of herbal cosmetics creates regulatory tailwind for plant-pigment formulations targeting middle-class consumers in Mumbai and Delhi beauty retail.
- Direct-to-consumer subscription models:Replenishment cycles for mascara consumables align with personalized beauty box economics, bypassing Sephora and Ulta margin compression.
- Biotechnology-pigment convergence:Microbial-derived iron oxides from precision fermentation processes promise batch consistency unavailable in mined mineral alternatives.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulators with dual competence in natural material stability and color cosmetic performance command premium compensation, constraining mid-tier brand R&D staffing.
- Leaping Bunny certification timelines:Cruelty-free verification processes extend product launch windows by eight to fourteen months, compressing first-mover advantage in trend-responsive categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herbal Mascara Market |
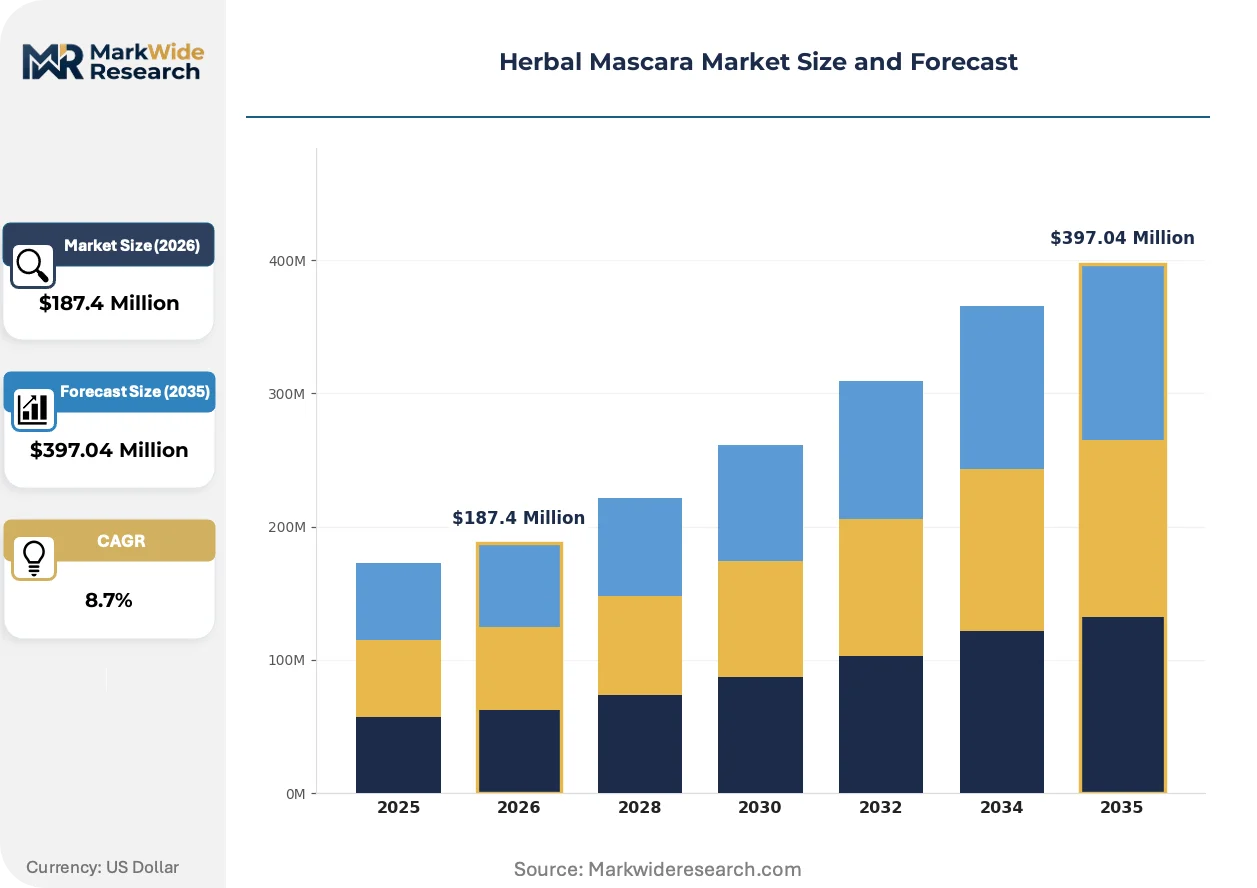
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Volumizing, Lengthening, Curling, Waterproof Formulation: Gel, Cream, Liquid, Powder Application: Everyday Wear, Professional Makeup, Special Occasions, Theater Performance Customer Type: Sensitive Skin Users, Vegan Consumers, Eco-Conscious Buyers, Luxury Shoppers |
| Companies Covered | Cheekbone Beauty, 100% PURE, ILIA, True Botanicals, Alima Pure, Erin's Faces, Juice Beauty, LIV Botanics, Well People, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herbal Mascara Market Strategic Shifts
Active ingredient traceability now functions as a product feature rather than a back-of-package afterthought, with blockchain-verified supply chains and extraction-method disclosure becoming standard competitive table stakes in premium botanical color cosmetics.
Gel-based suspension technology is decentralizing formulation expertise away from legacy cream-mascara specialists. Independent labs in California and South Korea now develop proprietary rheology modifiers from plant polysaccharides, enabling smaller brands to achieve flexible-hold performance without licensing polymer patents from multinational suppliers. This capability diffusion compresses the historical R&D barrier that protected incumbents.
ECHA's evolving stance on carbon black alternatives under REACH Annex XVII is forcing pigment supplier consolidation. German and Dutch specialty chemical firms now dominate compliant iron oxide production, while Italian and French formulators absorb certification costs to maintain EU market access. Waterproof variants remain the most affected category, with natural binder innovation racing against regulatory deadlines.
Ingredient-origin transparency has displaced performance claims as the primary purchase trigger among clean beauty consumers. Sephora's Clean at Sephora program and Credo Beauty's ingredient ban lists now function as de facto gatekeepers, with brands investing in vertical sourcing relationships to satisfy documentation requirements. This verification burden falls heaviest on mass-market entrants lacking captive supply chains.
Herbal Mascara Market Segmentation
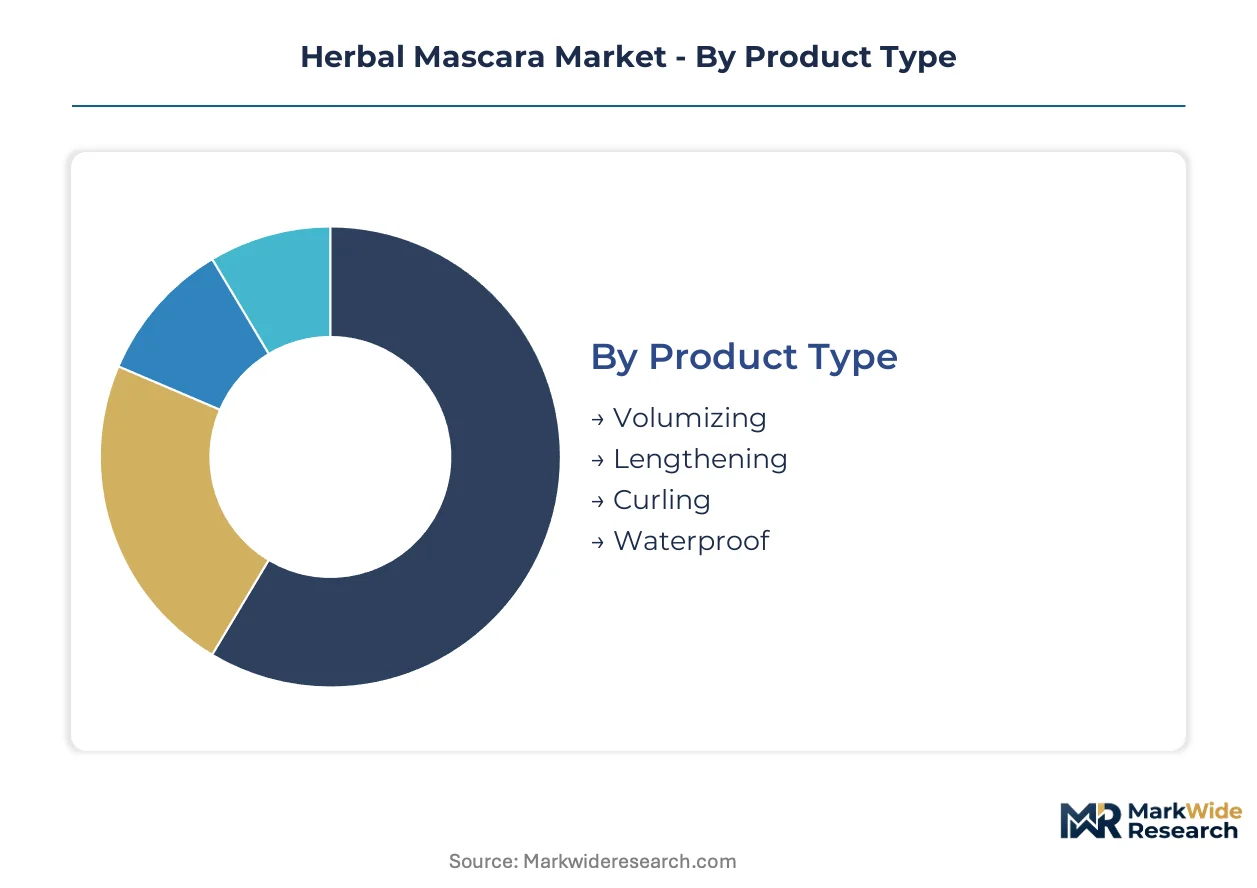
Segmentation in herbal mascara separates volume-driven mass-market formulations from precision-engineered professional kits. Each dimension reveals distinct procurement patterns, formulation complexity thresholds, and certification requirements that determine margin capture and channel access.
Product Type:
Customization intensity runs highest in performance-positioned variants where botanical wax blends must achieve synthetic-comparable lift and separation.
- Volumizing:Dense carnauba and rice bran wax suspensions build lash density through multi-layer film deposition. Demand clusters in United States Sephora and Ulta channels where clean beauty consumers prioritize visible impact over ingredient minimalism.
- Lengthening:Microcrystalline cellulose fibers from bamboo or wood pulp extend lash tips beyond natural terminal length. Professional makeup artists in Los Angeles and New York editorial markets specify these for red-carpet work where camera-ready definition is non-negotiable.
- Curling:Hydrogenated castor oil polymers provide thermoplastic memory for lash shape retention.
- Waterproof:Natural binder chemistry struggles against humidity and sebum; limited commercial penetration reflects formulation cost barriers rather than demand absence.
Most installed capacity flows through Volumizing. Expansion is steepest in Lengthening.
Formulation:
Cost tier stratification places gel systems at premium price points while cream and liquid variants serve accessible market tiers.
- Gel:Rheology-modified plant polysaccharide bases deliver flexible hold without synthetic acrylates. South Korean independent labs and California contract manufacturers now supply proprietary gel technology to mid-tier brands, eroding historical R&D barriers.
- Cream:Traditional beeswax-carnauba emulsions dominate mass-market shelves with straightforward manufacturing and established stability profiles.
- Liquid:Lower viscosity formulations target younger demographics seeking lightweight, buildable coverage.
- Powder:Loose mineral pigment formats appeal to DIY mixing communities and zero-waste retail channels.
Volume concentration sits with Cream. Margin expansion is fastest in Gel.
Application:
Customer type determines performance specification stringency, from casual daily wear to theatrical durability demands.
- Everyday Wear:Moderate pigment load and simplified wax matrices prioritize comfort over longevity. United States direct-to-consumer subscription boxes source these formulations for replenishment economics.
- Professional Makeup:Kit-grade specifications require batch consistency, smudge resistance under hot lights, and rapid layering capability. Demand from Los Angeles and New York production hubs drives formulator qualification programs.
- Special Occasions:Wedding and event segments favor photography-friendly finishes without flashback.
- Theater Performance:Sweat-resistant natural binders remain technically immature; limited herbal penetration here reflects performance ceiling constraints.
Revenue weight centers on Everyday Wear. Professional Makeup is gaining share fastest.
Customer Type:
Certification requirements fragment this category, with vegan and sensitive-skin positioning demanding mutually exclusive formulation choices.
- Sensitive Skin Users:Elimination of fragrance, essential oils, and known irritants drives hypoallergenic claim substantiation. United States dermatologist recommendation channels and Credo Beauty curation prioritize these specifications.
- Vegan Consumers:Carnauba and candelilla wax substitution for beeswax requires supply chain requalification and Leaping Bunny certification timelines. Expansion in this segment reflects cruelty-free positioning rather than performance differentiation.
- Eco-Conscious Buyers:Packaging recyclability and carbon footprint disclosure compete with ingredient sourcing for purchase influence.
- Luxury Shoppers:Vertical sourcing narratives and extraction-method transparency command price premiums in Neiman Marcus and Bergdorf Goodman beauty halls.
Wallet share concentrates with Sensitive Skin Users. Vegan Consumers represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cosmetic chemists with dual competence in natural material stability and color performance concentrate in California, New York, and Seoul, anchoring formulation innovation for plant-derived lash colorants.
United States
Clean beauty consumers in Sephora and Ulta channels drive volumizing variant demand, while professional makeup artists in Los Angeles and New York specify kit-grade formulations for editorial work. FDA cosmetic labeling requirements govern botanical claim substantiation, with particular scrutiny on iron oxide pigment declarations. Brooklyn and Portland host independent contract manufacturers developing proprietary gel-based suspension systems for mid-tier brands.
Germany
ECHA's REACH Annex XVII restrictions on carbon black alternatives redirect formulator procurement toward compliant iron oxide suppliers, concentrating R&D investment in Düsseldorf and Hamburg specialty chemical clusters. The country's national chemical regulator maintains stricter natural definition standards than American counterparts, forcing dual-labeling investments from cross-border brands. Bavarian extraction technology firms scale precision fermentation capacity for microbial-derived mineral pigments.
India
Ayush Ministry recognition of herbal cosmetics creates regulatory tailwind for domestic formulators targeting Mumbai and Delhi middle-class retail channels. The Central Drugs Standard Control Organization oversees cosmetic safety assessments, with state-level licensing variations across Maharashtra and Karnataka. Ahmedabad and Surat processing facilities expand carnauba wax alternative capacity using indigenous plant gums.
South Korea
Independent labs in Seoul and Incheon develop proprietary rheology modifiers from plant polysaccharides, eroding historical R&D barriers that protected multinational incumbents. The Ministry of Food and Drug Safety regulates cosmetic ingredient safety, with faster approval timelines for botanical extracts than novel synthetics. Busan contract manufacturers supply gel-based technology to North American clean beauty brands seeking performance parity.
France
L'Oréal-adjacent formulation talent in Paris and Lyon anchors premium botanical colorant development, with particular strength in fragrance-free sensitive-skin positioning. The National Agency for Food, Environmental and Occupational Health Safety enforces EU REACH compliance with additional national labeling requirements. Grasse extraction houses adapt perfume-grade botanical sourcing protocols for cosmetic pigment applications.
Herbal Mascara Market Competitive Environment
Capital-heavy producers with captive supply chains compete with asset-light designers relying on contract manufacturing partnerships. The vendor base stratifies across three tiers: premium botanical specialists with vertical sourcing control, mid-market brands licensing proprietary gel technology, and mass-market private-label suppliers. Strategic moves concentrate on M&A for extraction capabilities and geographic expansion into India domestic channels.
Within the premium botanical tier, Cheekbone Beauty anchors Indigenous sourcing narratives in North American clean beauty retail, while 100% PURE exemplifies in-house vertical control over fruit-pigment extraction. ILIA occupies a position in gel-based technology leadership, representing the formulation innovation vector that challenges legacy cream-mascara specialists. These three companies collectively illustrate how ingredient transparency and performance parity now determine competitive positioning.
| Leading Market Players |
|---|
| Cheekbone Beauty |
| 100% PURE |
| ILIA |
| True Botanicals |
| Alima Pure |
| Erin's Faces |
| Juice Beauty |
| LIV Botanics |
| Well People |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between Leaping Bunny-verified premium formulations and uncertified mass-market alternatives manifests in both pricing premiums and supply chain reconfiguration toward audited extraction facilities. Carnauba wax procurement from Brazilian Ceará state processing cooperatives commands price multiples over conventional petroleum-based film-formers, with FDA-EU dual-labeling compliance adding further cost layering for cross-border brands.
Pricing Analysis
Subscription bundling versus unbundled per-unit transactions separates direct-to-consumer replenishment economics from Sephora and Ulta shelf pricing. Price differentiation rests on certification tier and vertical sourcing depth, with in-house fruit-pigment extraction commanding premiums over contract-manufactured alternatives. Cost compression in mass-market cream formulations is intensifying as Brazilian harvest volatility feeds raw material inflation. Vegan consumers show lowest price sensitivity, while everyday wear subscribers prioritize replenishment convenience over unit economics.
Supply Chain Analysis
Reverse logistics for mascara tubes remains underdeveloped, with refill programs and aluminum packaging returns piloting in Brooklyn and Portland independent manufacturing clusters. Raw material flows draw from Brazil for carnauba wax, South Korea for plant polysaccharide rheology modifiers, and Germany for REACH-compliant iron oxide pigments. Single-source vulnerability concentrates in Ceará state wax processing bottlenecks. Distribution runs through Sephora and Ulta for premium positioning, with direct-to-consumer subscription boxes capturing replenishment cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as ingredient transparency displaces performance claims as the primary purchase trigger among clean beauty consumers.
For Market Incumbents: Acquire extraction technology capabilities to secure captive supply of fruit-pigments and plant-derived rheology modifiers. ILIA's gel-based technology leadership and 100% PURE's vertical sourcing control illustrate how backward integration into botanical inputs defends margin position against contract-manufactured entrants. ECHA's evolving REACH Annex XVII stance on carbon black alternatives threatens legacy formulation inventories, accelerating R&D allocation toward compliant iron oxide verification. For New Entrants and Emerging Players: The mid-market price-point gap between premium gel systems and mass-market cream formulations offers white-space entry through South Korean or California contract manufacturing partnerships. India domestic channels present the most penetrable geography given Ayush Ministry regulatory tailwinds for herbal cosmetics recognition. Direct-to-consumer subscription positioning bypasses Sephora and Ulta margin compression while capturing replenishment economics. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier brands licensing proprietary gel technology from independent labs rather than building in-house formulation teams. Long-term viability over the projection horizon favors acquisition targets with established Leaping Bunny certification and documented supply chain transparency. Practitioners should monitor ECHA regulatory pronouncements on carbon black alternatives and Brazilian carnauba harvest yields as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Extraction Capabilities | In-house fruit-pigment control eliminates supplier certification bottlenecks and substantiates premium positioning claims. |
| Direct-to-Consumer Subscription Launch | Replenishment cycle alignment with personalized beauty box economics bypasses traditional retail margin structures. |
| Leaping Bunny Certification Investment | Eight-to-fourteen month verification timelines compress first-mover advantage in cruelty-free positioning segments. |
| South Korean Lab Partnership | Proprietary plant polysaccharide rheology modifiers from Seoul and Incheon independent developers erode multinational R&D barriers. |
| India Domestic Market Expansion | Ayush Ministry herbal cosmetics recognition creates regulatory tailwind for Mumbai and Delhi middle-class retail penetration. |
Study Parameters
Multiple input streams — cosmetic chemist interviews, clean beauty retailer procurement discussions, and regulatory filing analysis — were reconciled through bottom-up and top-down triangulation. Primary engagement covered formulation R&D directors at California and New York contract manufacturers, Sephora and Ulta category buyers, Brazilian carnauba wax cooperative managers, and ECHA regulatory affairs specialists. Secondary validation drew from FDA cosmetic labeling guidance documents, ECHA REACH Annex XVII pigment restriction updates, Ayush Ministry herbal cosmetics notifications, and MFDS botanical extract approval databases.
Data-stream reconciliation anchored volume and value projections across the analysis window. Segmentation dimensions modeled include product type, formulation chemistry, application context, and customer certification requirements, with particular weighting on vegan versus sensitive-skin positioning divergence. CAGRs were derived from trend extrapolation of professional makeup artist kit specifications and clean beauty consumer wallet share shifts, cross-referenced against Brazilian wax harvest volatility and REACH compliance cost absorption patterns.
Caveats apply where ECHA regulatory reinterpretation of carbon black alternatives or Brazilian climate disruption to carnauba harvests could materially shift the outlook. Practitioners should monitor REACH Annex XVII amendment timelines and Ceará state processing capacity expansion for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Anti-Aging Serums Market
Cosmetic Chemicals
Fractionated Shea Butter in Cosmetics and Personal Care Market
Cosmetic Chemicals
Arbutin for Cosmetics Market
Cosmetic Chemicals
MENA/G.C.C./China Cosmetics and Personal Care Ingredients Market
Cosmetic Chemicals
Hair Lightening Product Market
Cosmetic Chemicals
Australia Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Cosmetic Grade CI 77491 Market
Cosmetic Chemicals
Minoxidil API Market
Cosmetic Chemicals
Cosmetic UV Absorbers Market
Cosmetic Chemicals
Europe Hyaluronic Acid-Based Dermal Fillers Market
Cosmetic Chemicals
South America Cosmeceuticals Market
Cosmetic Chemicals
European Fragrances Microencapsulation Market
Cosmetic Chemicals
Compound Camphor Ointment Market
Cosmetic Chemicals
UV Nail Gel Polish Market
Cosmetic Chemicals
Cosmetic Isoparaffins Market
Cosmetic Chemicals
Global Hyaluronic Acid Based Dermal Fillers Market