
 North America Jojoba Oil Market | 2026-2036
North America Jojoba Oil Market Size, Share, and Industry Trends Forecast 2026-2036
North America Jojoba Oil Market Intelligence
California's Proposition 65 enforcement is shifting the cost-of-entry calculus for jojoba oil suppliers seeking shelf placement in major retail channels. Nutrix International LLC leverages backward integration into desert cultivation to sustain margin control across volatile harvest cycles. Jojoba Desert anchors supply security through Israeli parent-company germplasm access, while Purcell Jojoba differentiates via cold-press extraction specialization for premium cosmetic accounts.
North America jojoba oil constitutes a liquid wax ester derived from Simmondsia chinensis seeds, with a molecular structure of straight-chain C20-C22 monounsaturated acids and alcohols that resists oxidative rancidity unlike conventional triglyceride oils. Its primary commercial purpose centers on cosmetic emollient applications where oxidative stability and skin-feel properties outperform mineral and petroleum-derived alternatives. Organic jojoba oil commands structural premium positioning as clean-label formulations displace conventional refined grades across prestige personal care lines. Pharmaceutical applications represent the fastest-growing application segment, driven by transdermal drug delivery vehicle adoption and dermatological excipient qualification programs.
The U.S. FDA oversees cosmetic ingredient safety through the Modernization of Cosmetics Regulation Act framework, while USDA organic certification governs cultivation and processing claims for North American-sourced material. Health Canada and PMRA coordinate cross-border agricultural chemical tolerance standards that affect integrated pest management protocols in Mexican and U.S. growing regions. Stakeholders must monitor pending FDA fragrance allergen disclosure rules, as these provisions would force reformulation decisions across mass-market cosmetic portfolios where jojoba oil serves as a carrier base.
Market Dynamics
California's Proposition 65 enforcement is elevating ingredient traceability requirements, forcing jojoba oil suppliers to invest in chain-of-custody documentation systems that separate compliant from non-compliant lots before they reach retail shelves.
Growth Catalysts
- Modernization of Cosmetics Regulation Act:The FDA's expanded safety substantiation mandates are accelerating demand for pre-qualified natural emollients with established toxicological profiles, positioning jojoba oil as a low-risk formulation base.
- Transdermal pharmaceutical delivery:Drug developers are qualifying jojoba esters as penetration enhancers in patch and gel formulations, opening volume channels beyond traditional cosmetic applications.
- Sonora cultivation expansion:Mexican agricultural zones are scaling irrigated desert farming to capture U.S. organic certification premiums, diversifying supply origins beyond California's drought-stressed acreage.
Market Restraints
- Water input volatility:Jojoba cultivation requires sustained irrigation through multi-year maturation cycles, exposing growers to Colorado River allocation cuts and municipal water pricing spikes across Southwestern U.S. production zones.
- Seed oil substitution:Meadowfoam and squalane suppliers are targeting identical cosmetic emollient specifications with shorter supply chains and lower agricultural risk profiles.
- USDA organic transition timelines:Three-year land conversion requirements lock prospective growers out of premium pricing tiers during establishment phases, compressing returns on invested capital.
Strategic Opportunities
- Canadian natural health product registration:Health Canada's expanded cosmetic-drug interface definitions create pathways for jojoba-based therapeutic moisturizers to access pharmacy distribution channels previously reserved for synthetic formulations.
- Supercritical CO2 extraction adoption:Processing technology convergence with pharmaceutical GMP standards enables simultaneous cosmetic and API-grade production from single facilities, capturing equipment utilization premiums.
- Direct-to-formulator e-commerce:Specialty chemical platforms are disintermediating traditional distributor networks, allowing mid-size oil processors to capture margin previously allocated to regional warehousing layers.
Industry Challenges
- Desert agronomy expertise scarcity:Simmondsia chinensis cultivation requires specialized knowledge of arid-land horticulture and integrated pest management that conventional row-crop extension services do not cover.
- Multi-jurisdiction organic equivalency:USDA, Canadian Organic Regime, and Mexican organic standards contain divergent processing aid restrictions that complicate cross-border lot certification for integrated North American supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Jojoba Oil Market |
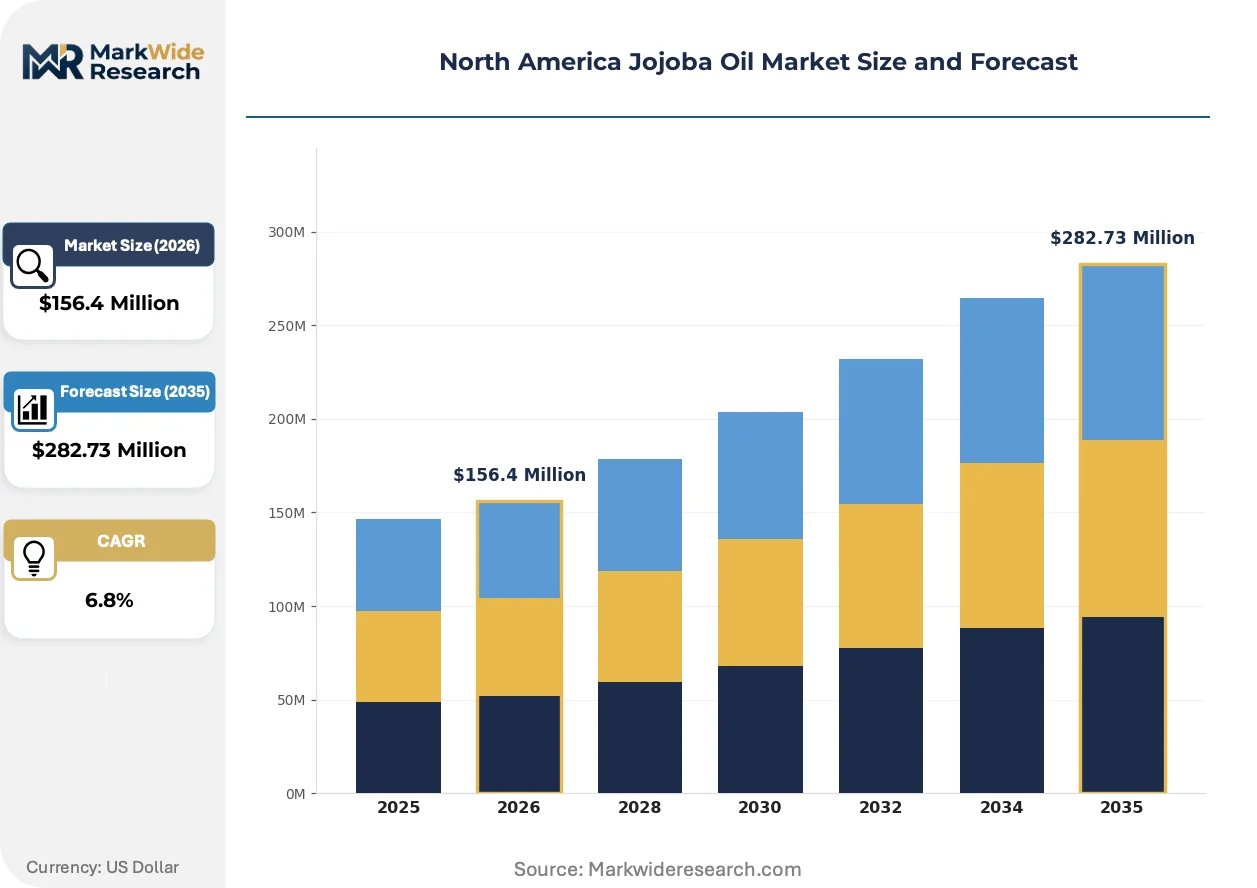
| Market Size in 2026 | $156.4 Million |
| Market Size in 2035 | $282.73 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Jojoba Oil, Organic Jojoba Oil, Virgin Jojoba Oil, Jojoba Oil Blends Application: Cosmetics, Pharmaceuticals, Food Industry, Industrial Uses Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Wholesale End User: Personal Care, Food Manufacturers, Pharmaceutical Companies, Industrial Manufacturers |
| Companies Covered | Nutrix International LLC, Jojoba Desert, Purcell Jojoba, Ecooil, Hallstar, Desert Whale Jojoba Company, US Organic Group Corp, Jojoba Naturals, ConnOils LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Jojoba Oil Market Strategic Shifts & Innovations
Formulation science advances and regulatory disclosure mandates are converging to elevate jojoba oil from commodity emollient to specified functional ingredient with documented performance attributes.
Enzymatic interesterification is absorbing processing capacity investments as cosmetic manufacturers seek tailored wax ester profiles with specific melting points and spreadability coefficients. Premium skincare formulators in California's personal care corridor are specifying enzymatically modified grades for anhydrous balm applications. This technology is absorbing margin compression from conventional cold-press commoditization by creating defensible IP positions around structured lipid architectures.
The FDA's pending fragrance allergen disclosure rules are forcing reformulation audits across mass-market cosmetic portfolios where jojoba oil serves as a carrier base for essential oil blends. Manufacturers must now map complete compositional profiles of natural oil fractions previously treated as single-ingredient line items. Mass-market personal care brands operating in U.S. retail channels are accelerating supplier qualification timelines to secure compliant documentation ahead of enforcement windows.
Certification-driven procurement preferences are fragmenting buyer-seller relationships as formulators separate organic-certified from conventional supply streams at the contract level. Previously consolidated annual supply agreements are splitting into parallel organic and conventional tracks with distinct pricing and volume terms. This bifurcation is most visible among prestige personal care manufacturers headquartered in New York and Los Angeles who face retailer mandates for clean-label shelf positioning.
North America Jojoba Oil Market Segmentation
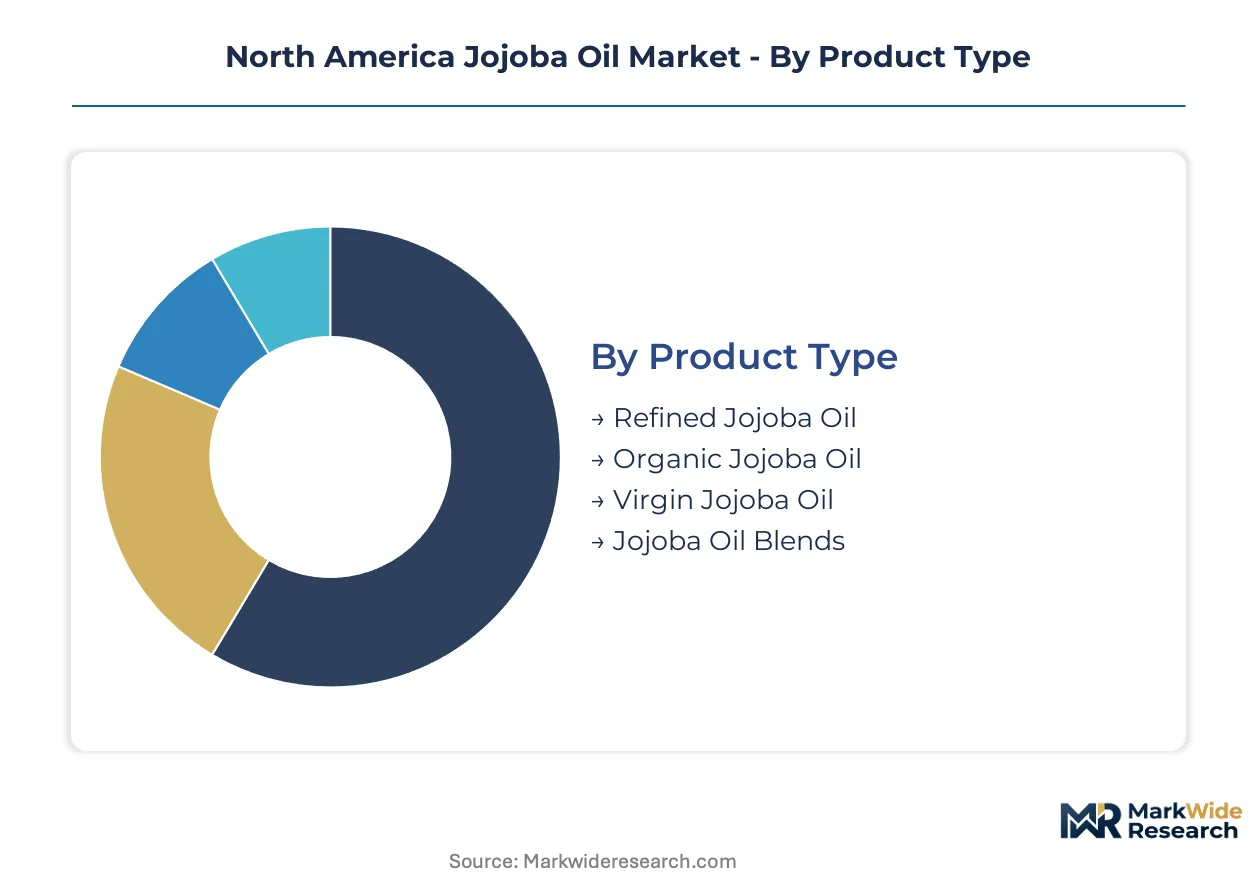
Jojoba oil's liquid wax ester chemistry creates natural fault lines across product tiers, with oxidative stability specifications and certification status determining contract value. Formulators in California's personal care corridor and Sonora's emerging cultivation zones are segmenting procurement to match raw material grades with end-use performance requirements.
Product Type:
Capital intensity varies sharply across extraction and refinement tiers, with organic certification commanding the longest payback periods due to three-year land conversion requirements.
- Refined Jojoba Oil:Molecular distillation and bleaching processes remove color bodies and free fatty acids to achieve cosmetic-grade specifications. Demand concentrates among mass-market personal care manufacturers in California seeking consistent oxidative stability indices for shelf-stable emulsions.
- Organic Jojoba Oil:USDA-certified cultivation with prohibited synthetic pesticide inputs and mechanical cold-press extraction preserves wax ester integrity. Premium positioning in New York and Los Angeles prestige brands drives contract premiums, though supply remains constrained by Southwestern U.S. drought-stressed acreage.
- Virgin Jojoba Oil:Single-pass cold-press extraction retains native tocopherol content and unfiltered particulate matter.
- Jojoba Oil Blends:Pre-formulated mixtures with meadowfoam or squalane target specific spreadability coefficients.
Most installed capacity flows through Refined Jojoba Oil. Expansion is steepest in Organic Jojoba Oil.
Application:
Volume concentration tracks regulatory qualification pathways, with pharmaceutical-grade documentation requiring the most extensive toxicological investment.
- Cosmetics:Emollient formulations leverage jojoba esters' structural similarity to human sebum for skin-feel optimization. California's personal care manufacturing corridor anchors demand, with FDA Modernization of Cosmetics Regulation Act compliance accelerating pre-qualified natural ingredient procurement.
- Pharmaceuticals:Transdermal drug delivery vehicles exploit wax ester penetration enhancement and dermatological excipient compatibility. Health Canada's expanded cosmetic-drug interface definitions are opening pharmacy distribution channels for therapeutic moisturizers.
- Food Industry:Limited GRAS-approved applications in dietary supplements and flavor carriers.
- Industrial Uses:Lubricant formulations and metalworking fluids exploit oxidative stability.
Cosmetics commands the dominant share of current offtake. Pharmaceuticals is gaining share fastest.
Distribution Channel:
Channel economics reflect lot size fragmentation, with direct sales requiring the highest customer acquisition infrastructure.
- Online Retail:Specialty chemical platforms enable mid-size processors to bypass regional distributor margins and capture formulator relationships directly.
- Specialty Stores:Cosmetic ingredient boutiques in Los Angeles and New York serve small-batch formulators with certified organic documentation.
- Direct Sales:Annual supply agreements with prestige personal care manufacturers split into parallel organic and conventional tracks.
- Wholesale:Consolidated procurement for mass-market brands operates through established chemical distributor networks.
Wholesale channels handle the largest aggregate tonnage. Online Retail is climbing the fastest.
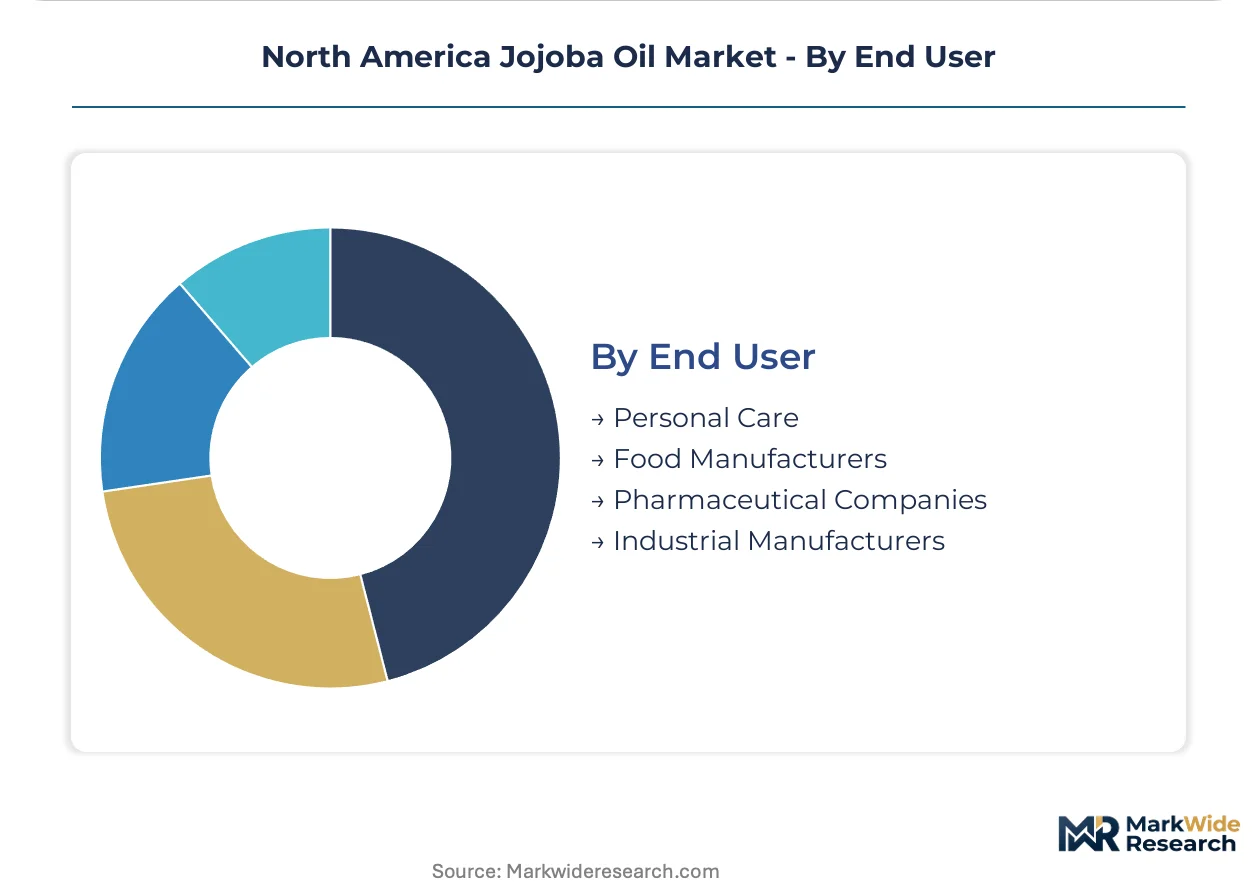
End User:
Customer concentration patterns align with formulation sophistication, with pharmaceutical companies imposing the most stringent supplier qualification protocols.
- Personal Care:Anhydrous balms and therapeutic moisturizers specify enzymatically modified wax ester profiles with tailored melting points.
- Food Manufacturers:Dietary supplement encapsulation requires GRAS notification compliance and lot-level contaminant testing.
- Pharmaceutical Companies:Transdermal patch developers qualify jojoba esters as penetration enhancers through FDA drug master file pathways.
- Industrial Manufacturers:High-temperature lubricant formulators value oxidative stability for extended service intervals.
Personal Care absorbs the majority of current supply. Pharmaceutical Companies show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized desert agronomists and cold-press extraction technicians concentrate in California's Coachella Valley and Sonora's irrigation districts, anchoring North America's jojoba oil technical workforce.
United States
California's personal care manufacturing corridor drives refined jojoba oil procurement for mass-market emulsion formulations. The FDA's Modernization of Cosmetics Regulation Act mandates pre-qualified ingredient documentation, accelerating supplier qualification timelines. Coachella Valley cultivation zones face Colorado River allocation cuts that threaten multi-year orchard maturation cycles.
Mexico
Sonora's emerging irrigated desert farms scale organic-certified acreage to capture USDA premium pricing. Health Canada and PMRA coordinate cross-border agricultural chemical tolerance standards affecting integrated pest management protocols. Hermosillo processing clusters specialize in cold-press extraction for cosmetic-grade export to U.S. formulators.
Canada
Health Canada's expanded cosmetic-drug interface definitions open pharmacy distribution channels for therapeutic moisturizers containing jojoba esters. The Canadian Organic Regime imposes processing aid restrictions that diverge from USDA standards, complicating lot certification for integrated North American supply chains. Toronto-area natural health product distributors qualify jojoba-based formulations for provincial pharmacy procurement.
North America Jojoba Oil Market Key Industry Players
The competitive structure tilts toward backward-integrated desert cultivators with captive germplasm access. Mid-size processors and specialty chemical distributors populate the remaining tiers, creating a bifurcated landscape between volume suppliers and premium-positioned niche players. Two archetypes dominate: cultivation-integrated producers controlling upstream seed supply, and extraction-specialized processors commanding cosmetic-grade certification premiums. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure organic-certified acreage and pharmaceutical GMP processing qualifications.
Among cultivation-integrated operators, Nutrix International LLC anchors the tier through desert farming operations that sustain margin control across volatile harvest cycles. Jojoba Desert exemplifies parent-company germplasm access strategies that secure supply security through Israeli seed stock relationships. Purcell Jojoba occupies a position within the cold-press extraction specialist archetype, differentiating through mechanical processing methods targeting premium cosmetic accounts.
| Leading Market Players |
|---|
| Nutrix International LLC |
| Jojoba Desert |
| Purcell Jojoba |
| Ecooil |
| Hallstar |
| Desert Whale Jojoba Company |
| US Organic Group Corp |
| Jojoba Naturals |
| ConnOils LLC |
| Others |
Cost & Logistics Intelligence
Family-owned desert cultivation operations in California and Sonora anchor upstream supply, translating drought-stressed acreage scarcity into disciplined contract pricing for cosmetic-grade jojoba oil. Their multi-decade orchard maturation timelines create captive financing structures that resist spot-market volatility, forcing mass-market formulators into long-term offtake commitments or premium organic tier migration.
Pricing Analysis
Certification-bundled versus unbundled supply contracts split procurement economics across the North American jojoba oil market. Three-tier pricing structure across premium organic, standard refined, and economy virgin grades tracks USDA certification status and cold-press extraction method. Cost compression in standard refined tiers intensifies as meadowfoam and squalane substitutes erode volume commitments from California personal care manufacturers. Mass-market brands exhibit highest price sensitivity, while prestige New York and Los Angeles formulators absorb organic premiums for clean-label positioning.
Supply Chain Analysis
USDA organic qualification gates upstream participation, locking prospective growers into three-year land conversion timelines before premium pricing access. Supply concentrates in California's Coachella Valley, Sonora's Hermosillo corridor, and Arizona's Yuma district, with each node drawing from Colorado River irrigation allocations. Raw material dependencies center on Simmondsia chinensis germplasm, mechanical cold-press equipment, and synthetic pesticide-free cultivation inputs. Single-source vulnerability runs through Colorado River water rights volatility. Distribution runs through specialty chemical platforms disintermediating traditional regional warehousing layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America jojoba oil market functions as a geographic-arbitrage play between California's drought-constrained cultivation and Sonora's expanding irrigated acreage, with water input cost differentials exceeding organic certification premium capture.
For Market Incumbents: Extend backward integration into Sonora cultivation zones to hedge Colorado River allocation uncertainty. Secure pharmaceutical GMP processing qualifications ahead of FDA Modernization of Cosmetics Regulation Act enforcement windows. Defensive consolidation through captive germplasm banking insulates against Israeli parent-company supply disruptions. For New Entrants and Emerging Players: Specialty chemical e-commerce platforms offer the most penetrable channel for mid-size processors seeking direct formulator relationships. Target Health Canada natural health product registration pathways for therapeutic moisturizer positioning. Pursue enzymatic interesterification capability as differentiated service offering for anhydrous balm specifications. For Investors and Strategic Acquirers: Valuations sit cheapest among extraction-specialized processors lacking cultivation integration. Long-term viability over a five-to-ten-year horizon hinges on water rights security and organic acreage scalability. Watch FDA fragrance allergen disclosure rule enforcement timing as demand inflection signal for pre-qualified ingredient documentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sonora Cultivation | Captures USDA organic premiums while diversifying beyond California drought exposure. |
| Pharmaceutical GMP Processing Qualification | Opens transdermal drug delivery channels through FDA drug master file pathways. |
| Enzymatic Interesterification Capacity Addition | Creates defensible IP positions around tailored wax ester melting point specifications. |
| Direct-to-Formulator E-Commerce Platform Launch | Disintermediates regional distributor margins for mid-size oil processors. |
| Health Canada Natural Health Product Registration | Accesses pharmacy distribution channels for therapeutic moisturizer formulations. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with desert cultivation operators, cold-press extraction technicians, cosmetic formulation chemists, and specialty chemical procurement leads with secondary validation. Trade data from USDA organic certification databases, FDA cosmetic ingredient filings, and Sonora agricultural export records anchored volume estimates. Bottom-up orchard yield modeling and top-down personal care ingredient demand triangulation cross-checked projections.
Comparable historical cultivation cycles and processing capacity utilization rates anchored the forecast window against reference maturation timelines. Segmentation modeling tracked product type tiers, application pathways, distribution channel economics, and end-user qualification requirements across the projection horizon. CAGRs derived from compound growth trajectory analysis of organic acreage expansion and pharmaceutical excipient adoption curves. Colorado River water allocation scenarios and FDA enforcement timing assumptions fed sensitivity testing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to drought severity, regulatory enforcement pace, and substitute ingredient penetration. Projections reflect documented assumptions around orchard maturation timelines and certification conversion rates. A model refresh is warranted upon material change in Colorado River Compact renegotiation outcomes or FDA fragrance allergen disclosure rule finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Cosmetic & Toiletry Chemicals Market
Cosmetic Chemicals
Gemstone Cosmetics Powder Market
Cosmetic Chemicals
Cosmetic Isoparaffins Market
Cosmetic Chemicals
Compound Camphor Ointment Market
Cosmetic Chemicals
Ethylhexylglycerin for Cosmetics Market
Cosmetic Chemicals
Anti-Aging Serums Market
Cosmetic Chemicals
Global Cosmetics OEM/ODM Market
Cosmetic Chemicals
Anti-Aging and Anti-Wrinkle Products Market
Cosmetic Chemicals
Facial Essence Market
Cosmetic Chemicals
Xerosis Market
Cosmetic Chemicals
Makeup Emulsion Market
Cosmetic Chemicals
Australia Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Global Mineral Cosmetics Market
Cosmetic Chemicals
Anti-Acne Serum Market
Cosmetic Chemicals
North America Cosmeceuticals Market
Cosmetic Chemicals
Fractionated Shea Butter in Cosmetics and Personal Care Market