
 Cloud Based Simulation Application Market | 2026-2036
Cloud Based Simulation Application Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Based Simulation Application Market Analysis
High-fidelity multiphysics simulation is bifurcating the competitive landscape into premium certified-grade platforms and accessible mid-tier alternatives. ANSYS leverages its decades-long solver heritage to anchor the top tier with validated aerospace and automotive workflows. Autodesk competes through design-to-simulation integration that extends its CAD-native user base into cloud analysis. SimScale specializes in browser-native accessibility, occupying a distinct position among engineering consultancies and smaller product teams.
Cloud based simulation applications deliver computational modeling, mesh generation, and solver execution through remote server infrastructure rather than local workstations, typically operating across 32 to 1024 core elastic clusters with sub-millisecond latency requirements for interactive pre-processing. Their primary commercial purpose is to compress product development cycles by enabling parallel design exploration without capital-intensive on-premises HPC investment. Public cloud deployment leads in absolute volume due to pay-per-use elasticity that appeals to seasonal project demand, while hybrid cloud configurations capture the fastest expansion as regulated industries reconcile IT governance with burst compute needs. Virtual prototyping within the solution layer commands concentrated margin pools because it replaces physical test iterations with correlated digital twins.
FDA 21 CFR Part 11 electronic records requirements shape healthcare simulation demand by mandating audit trails for computational validation of medical devices. EASA certification memoranda on simulation-based means of compliance steer aerospace procurement toward platforms with formal verification documentation. ISO 27001 and GDPR jointly determine market access for vendors serving European engineering teams with export-controlled or personally identifiable workflow data. Stakeholders must monitor evolving cross-border data sovereignty rulings that threaten to fragment previously unified cloud simulation architectures into jurisdiction-specific instances.
Market Dynamics
Elastic cloud infrastructure is displacing capital-intensive on-premises HPC clusters across engineering workflows, compressing procurement cycles from multi-year capital budgets to operational expenditure models that align compute capacity directly with project phases.
Growth Catalysts
- ISO 27001 certification mandates:European engineering procurement now requires documented cloud security frameworks, accelerating vendor qualification timelines for compliant platforms.
- Automotive supplier network consolidation:German Tier-1 manufacturers are mandating cloud-native simulation standards across their extended supply chains to synchronize design iterations.
- GPU-accelerated solver architectures:NVIDIA H100 clusters are reducing multiphysics computation time from weeks to hours, enabling overnight design exploration cycles previously impossible on workstation hardware.
Market Restraints
- Cross-border data fragmentation:GDPR residency requirements and emerging sovereignty rulings are forcing vendors to maintain jurisdiction-specific infrastructure instances, multiplying operational overhead.
- Specialized talent scarcity:Cloud-native simulation engineering requires hybrid skills spanning HPC architecture, solver physics, and DevOps automation that existing workforce pipelines cannot supply at scale.
- Subscription cost accumulation:Per-core-hour pricing models generate unpredictable spend volatility for seasonal project workflows, creating budget resistance among finance-controlled engineering departments.
Strategic Opportunities
- Medical device computational validation:FDA 21 CFR Part 11 electronic records requirements are opening certified-platform opportunities for cardiovascular implant and surgical instrument simulation workflows.
- AI-augmented mesh generation:Machine learning preprocessing is converging with traditional CAD-to-solver pipelines, enabling novice engineers to execute previously expert-dependent geometry preparation.
- Small-to-mid enterprise accessibility:Browser-native platforms are penetrating product development teams below 50 engineers that previously lacked HPC capital allocation.
Industry Challenges
- Legacy solver migration complexity:Decades of validated on-premises simulation scripts require substantial refactoring for cloud-native parallel architectures, delaying platform transitions.
- EASA certification documentation gaps:Aerospace procurement teams face extended verification timelines as cloud platforms build formal means-of-compliance libraries equivalent to established workstation software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Based Simulation Application Market |
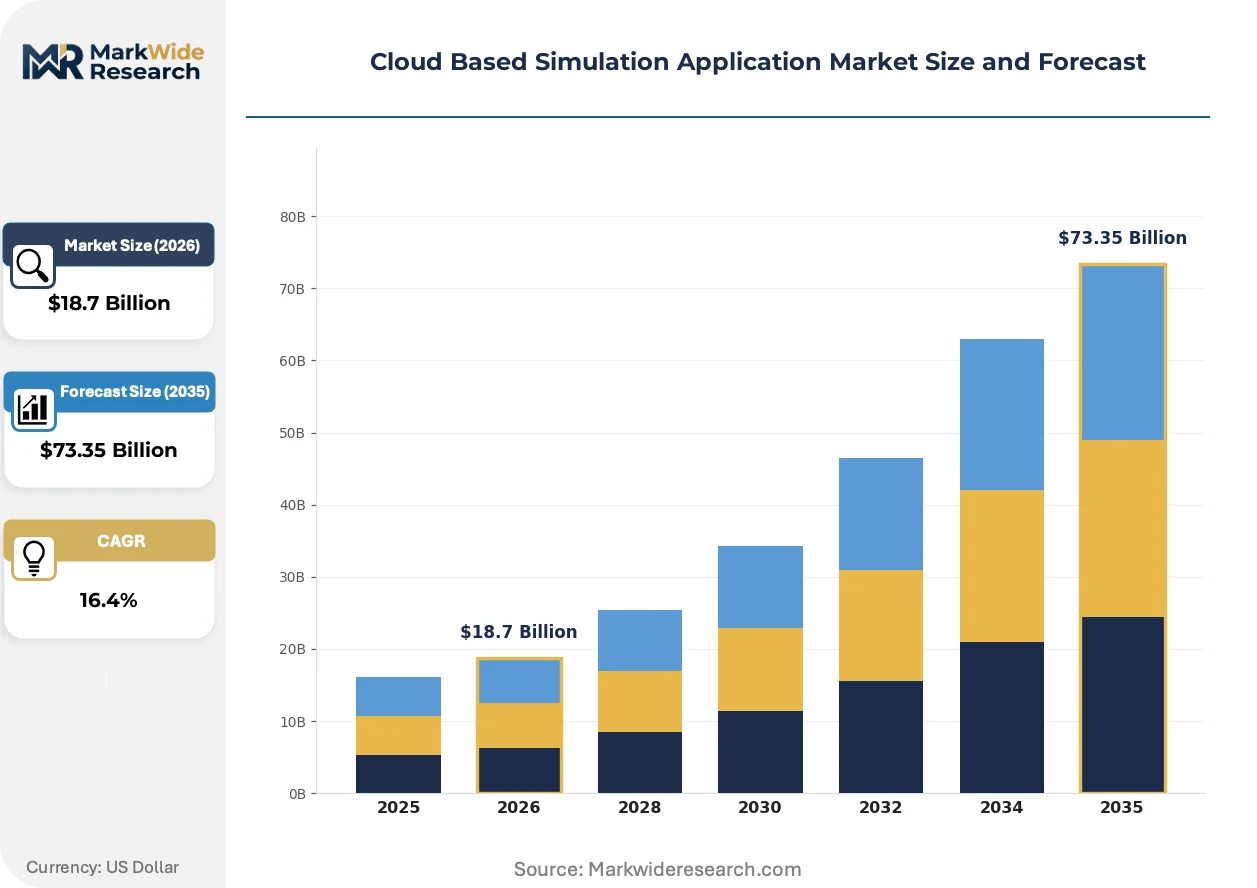
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud End User: Aerospace, Automotive, Education, Healthcare Solution: 3D Modeling, Performance Testing, Virtual Prototyping, Risk Analysis Application: Product Design, Training Simulation, Disaster Management, Process Optimization |
| Companies Covered | ANSYS, Autodesk, Dassault Systèmes, SimScale, Siemens PLM Software, Rescale, MSC Software, Fieldscale, OnScale, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Based Simulation Application Market Emerging Trajectories
Computational modeling workflows are fragmenting into specialized layers where preprocessing, solver execution, and post-processing operate as independently optimizable services rather than unified platform experiences.
Containerized microsolver architectures are displacing monolithic simulation platforms by enabling engineering teams to compose purpose-specific computational pipelines from discrete physics modules. Automotive crash safety teams at BMW and Volkswagen are deploying these architectures for overnight parametric studies. This modularity is compressing vendor lock-in by allowing solver substitution at individual workflow stages.
EASA certification memoranda on simulation-based means of compliance are mandating formal verification documentation for computational results used in airworthiness submissions. European aerospace procurement teams now require platform vendors to supply traceable audit trails equivalent to physical test protocols. This regulatory pressure is bifurcating the vendor landscape between certified-grade documentation capabilities and unsupported academic-tier alternatives.
Consumption-based licensing is replacing perpetual seat models as engineering managers seek cost alignment with project-specific demand spikes. German automotive OEMs are negotiating enterprise agreements that scale core allocations quarterly rather than annually. This behavioral shift is most visible among mid-tier suppliers in Stuttgart and Munich industrial clusters where finance departments now control simulation procurement decisions.
Cloud Based Simulation Application Market Segmentation
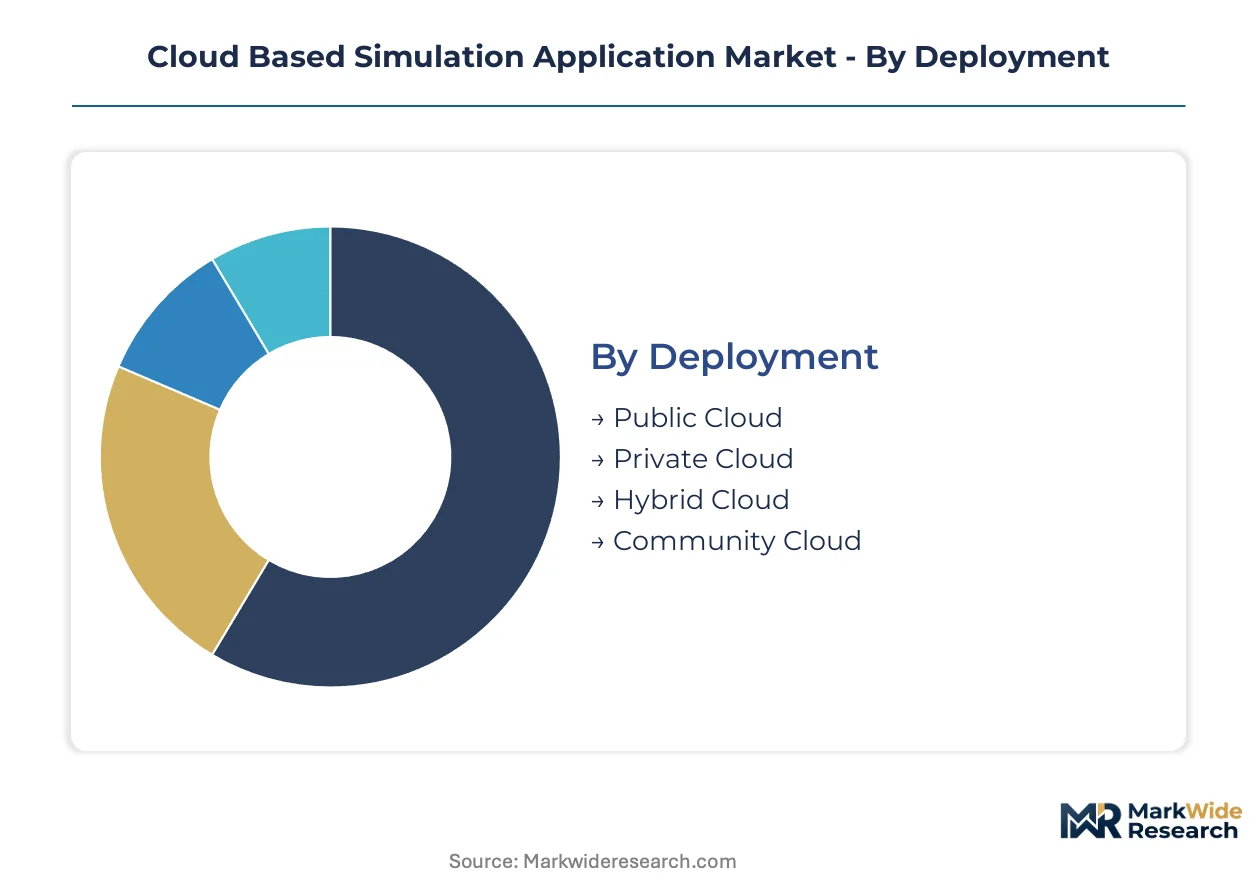
Cloud simulation procurement varies sharply across deployment architectures, end-use industries, and solution layers. Engineering managers select configurations based on data sovereignty exposure, certification requirements, and project-phase compute intensity.
Deployment:
Public cloud deployments face acute substitution pressure from hybrid configurations as regulated industries seek burst elasticity without surrendering governance control.
- Public Cloud:Elastic compute pools provisioned over shared infrastructure deliver pay-per-use scalability for seasonal project workloads. German automotive OEMs in Stuttgart and Munich industrial clusters favor this model for overnight crash simulation batches where data residency requirements permit.
- Hybrid Cloud:Split architectures maintain sensitive preprocessing on controlled infrastructure while bursting solver execution to elastic cloud pools. EASA certification workflows at French and Italian aerospace suppliers increasingly mandate this configuration to reconcile IT governance with computational throughput needs.
- Private Cloud:Dedicated tenant environments serving single organizations with hardware isolation for export-controlled simulation data.
- Community Cloud:Shared infrastructure restricted to specific industry verticals or supplier networks with common compliance frameworks.
Public cloud retains volume leadership; hybrid cloud holds the steepest expansion curve.
End User:
Cost tier stratification separates capital-rich certification-driven buyers from budget-constrained teams prioritizing accessibility over formal verification.
- Aerospace:Airframe manufacturers and Tier-1 suppliers executing EASA means-of-compliance submissions require validated solver documentation and traceable audit trails. Boeing and Airbus procurement teams disqualify platforms lacking formal verification libraries equivalent to established workstation software.
- Automotive:OEMs and supplier networks migrating from on-premises HPC clusters to cloud infrastructure for overnight parametric studies. BMW and Volkswagen crash safety teams deploy containerized microsolver architectures for design exploration cycles.
- Healthcare:Medical device developers navigating FDA 21 CFR Part 11 electronic records mandates for cardiovascular implant and surgical instrument validation workflows.
- Education:University engineering programs and research consortia accessing simulation capacity without capital-intensive infrastructure investment.
Automotive commands the largest procurement volume; healthcare is climbing fastest on regulatory tailwinds.
Solution:
Application maturity divides established CAD-integrated workflows from emerging AI-augmented capabilities reshaping geometry preparation economics.
- Virtual Prototyping:Correlated digital twin environments replacing physical test iterations with computational validation. This layer captures concentrated margin pools due to direct substitution of expensive hardware prototypes in German automotive certification workflows.
- 3D Modeling:Cloud-native geometry preparation and mesh generation services enabling browser-based accessibility for distributed engineering teams.
- Performance Testing:Load, thermal, and structural validation suites for product durability verification.
- Risk Analysis:Probabilistic simulation frameworks for failure mode assessment and safety margin quantification.
Virtual prototyping dominates value capture; 3D modeling is expanding most quickly through AI-augmented accessibility gains.
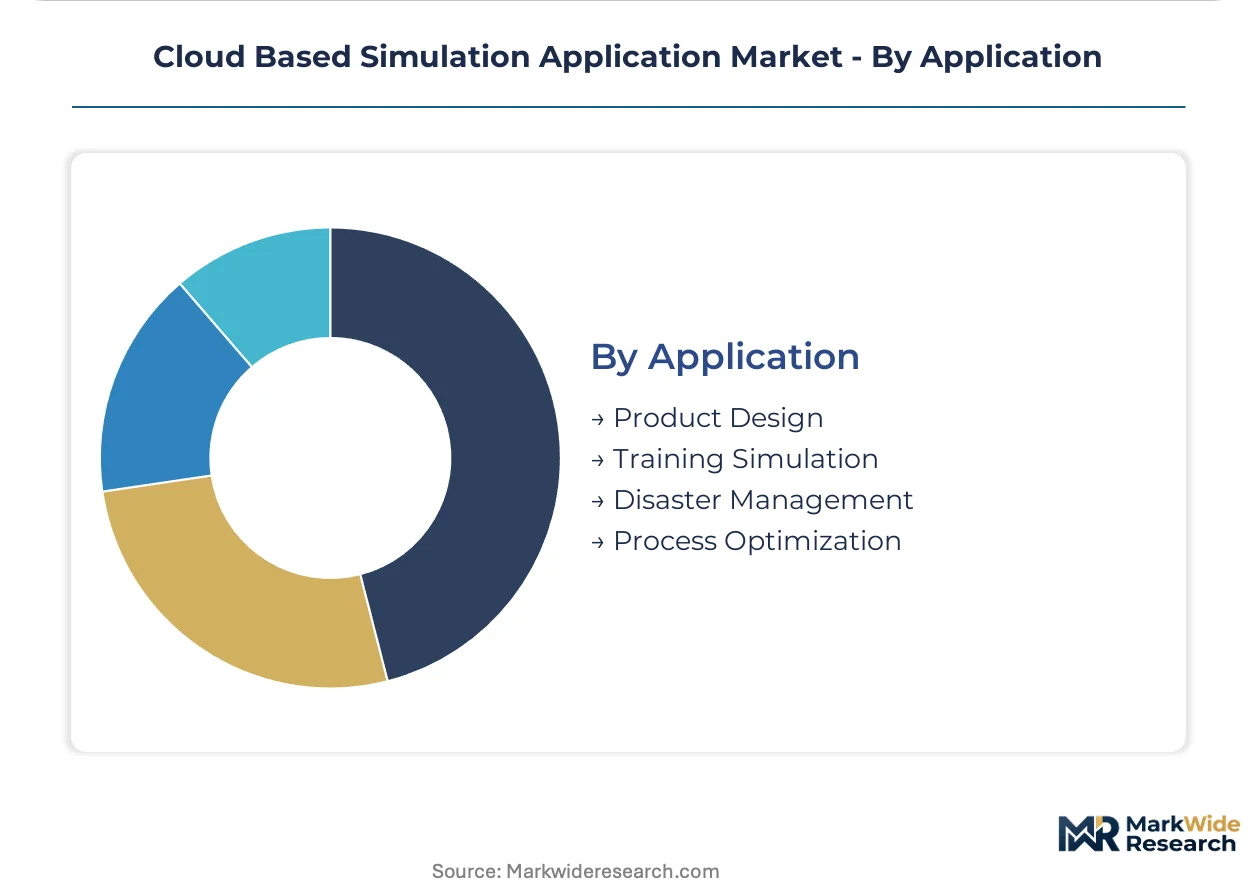
Application:
Customer workflow integration depth separates embedded design-phase simulation from standalone training and planning use cases.
- Product Design:Integrated CAD-to-solver pipelines compressing development cycles through iterative computational exploration. This application concentrates demand among mid-tier suppliers seeking to synchronize design iterations with German OEM release schedules.
- Process Optimization:Manufacturing flow simulation and factory digital twin deployment for throughput and energy efficiency gains.
- Training Simulation:Operator and maintenance crew virtual environments for hazardous procedure rehearsal without physical asset risk.
- Disaster Management:Emergency response and infrastructure resilience modeling for public safety agencies.
Product design anchors procurement volume; process optimization is gaining share fastest on manufacturing digital twin investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud simulation infrastructure concentrates where automotive and aerospace engineering clusters demand elastic compute without capital expenditure. Germany, the United States, Japan, China, and France anchor procurement volume through distinct regulatory and industrial configurations.
Germany
Automotive OEM procurement and Tier-1 supplier network consolidation drive cloud migration across Stuttgart and Munich industrial clusters. KBA vehicle safety standards and GDPR data residency requirements shape vendor qualification for crash simulation workflows. BMW and Volkswagen engineering teams deploy containerized microsolver architectures for overnight parametric studies.
United States
FDA 21 CFR Part 11 mandates for medical device computational validation expand healthcare simulation demand alongside aerospace procurement. FAA certification requirements steer defense and commercial aviation teams toward platforms with formal verification documentation. California and Washington State technology clusters host GPU-accelerated solver deployments for overnight design exploration.
Japan
METI industrial digitalization programs accelerate cloud adoption among precision manufacturing and automotive suppliers. JIS standards frameworks influence simulation platform procurement for quality-critical engineering workflows. Toyota and Honda engineering centers in Nagoya and Tokyo metropolitan areas migrate HPC workloads to elastic infrastructure.
China
MIIT smart manufacturing initiatives and dual carbon goals propel domestic cloud simulation investment for electric vehicle development. GB standards compliance requirements shape platform selection for state-affiliated automotive and aerospace engineering teams. Yangtze River Delta manufacturing clusters in Shanghai and Jiangsu Province concentrate procurement for battery and drivetrain simulation.
France
EASA certification memoranda on simulation-based means of compliance steer aerospace procurement toward documented verification capabilities. ANSM healthcare device regulations intersect with computational validation requirements for cardiovascular implant simulation. Airbus engineering centers in Toulouse and Paris-Saclay anchor demand for certified-grade multiphysics platforms.
Cloud Based Simulation Application Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes within a bifurcated vendor structure. Premium certified-grade platforms command aerospace and medical device procurement through validated solver documentation and traceable audit trails. Accessible browser-native alternatives capture mid-tier engineering teams and consultancies prioritizing operational expenditure flexibility over formal verification. Strategic moves concentrate on M&A for solver technology acquisition and geographic data center expansion to satisfy sovereignty requirements.
Within the heritage solver tier, ANSYS and Dassault Systèmes exemplify decades-long validation libraries that anchor aerospace certification workflows. Autodesk occupies a position bridging CAD-native design integration with cloud analysis accessibility. SimScale represents the browser-native archetype targeting engineering consultancies and sub-50-engineer product teams without HPC capital allocation. Siemens PLM Software anchors the industrial software conglomerate model spanning manufacturing digital twins and simulation infrastructure.
| Leading Market Players |
|---|
| ANSYS |
| Autodesk |
| Dassault Systèmes |
| SimScale |
| Siemens PLM Software |
| Rescale |
| MSC Software |
| Fieldscale |
| OnScale |
| Others |
Supply Flow & Price Mechanics
Capacity reservation agreements with hyperscaler cloud providers lock in compute access and price visibility for German automotive OEMs navigating seasonal crash simulation workloads. These contracts tether core-hour allocations to project-phase demand while insulating procurement teams from spot-market volatility in GPU-accelerated infrastructure.
Pricing Analysis
ISO 27001 certification mandates dictate the pricing tier structure across European procurement, separating certified-grade platforms with documented security frameworks from uncertified alternatives. Pricing stratifies across premium, standard, and economy tiers based on solver validation depth and audit trail completeness. Cost compression in the mid-tier is intensifying because browser-native entrants are undercutting heritage solver licensing. Tier-1 automotive suppliers exhibit highest price sensitivity due to finance-controlled procurement decisions, while aerospace certification teams prioritize traceability over unit cost.
Supply Chain Analysis
Germany and the United States anchor cloud infrastructure provisioning for simulation workloads, with Taiwan and South Korea feeding specialized GPU and high-bandwidth memory components. The supply chain draws from NVIDIA H100 clusters, elastic storage arrays, and low-latency networking gear. Single-source vulnerability concentrates in advanced GPU silicon where foundry capacity constraints create allocation bottlenecks. Distribution runs through direct enterprise sales teams and hyperscaler marketplace integrations serving engineering procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated German automotive OEM procurement functions that mandate cloud-native simulation standards across extended supplier networks. This concentration fragments pricing leverage for mid-tier vendors.
For Market Incumbents: Secure EASA certification documentation libraries equivalent to established workstation software before emerging browser-native platforms achieve formal verification parity. Invest in vertical integration into GPU-reserved capacity pools to defend against hyperscaler pricing power. The threat of containerized microsolver substitution demands solver-level API control. For New Entrants and Emerging Players: FDA 21 CFR Part 11 fast-track certification for cardiovascular implant simulation workflows opens healthcare procurement previously locked by heritage vendor relationships. Target sub-50-engineer product teams in Stuttgart and Munich industrial clusters with consumption-based licensing that bypasses capital budget approval cycles. Lead with AI-augmented mesh generation to reduce expert-dependent onboarding friction. For Investors and Strategic Acquirers: Specialist solver technology boutiques with validated multiphysics modules represent the highest-return acquisition archetype as platform consolidation accelerates. Long-term viability hinges on jurisdiction-specific data center footprints that satisfy emerging sovereignty rulings. Monitor EASA memoranda expansion beyond aerospace into adjacent regulated verticals as the inflection signal for certified-platform premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Geographic Data Center Expansion | Jurisdiction-specific instances satisfy GDPR residency requirements for French and German aerospace procurement. |
| Certification Documentation Investment | Formal verification libraries unlock EASA means-of-compliance submissions at Airbus and Safran engineering centers. |
| GPU-Reserved Capacity Agreements | Hyperscaler partnerships secure compute allocation priority for overnight parametric studies at BMW crash safety teams. |
| AI-Augmented Preprocessing Development | Machine learning mesh generation reduces geometry preparation costs for mid-tier supplier onboarding. |
| Containerized Microsolver Acquisition | Modular physics modules enable workflow-stage substitution that compresses vendor lock-in exposure. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EASA certification memoranda, FDA 21 CFR Part 11 guidance documents, and hyperscaler infrastructure disclosure filings. Primary interviews engaged cloud platform engineering directors, automotive Tier-1 procurement managers, aerospace certification specialists, and healthcare regulatory affairs leads. Secondary validation drew from ISO 27001 audit registries, GDPR enforcement case databases, and GPU supply chain production reports. Bottom-up segment sizing triangulates against top-down infrastructure spend estimates.
Segmentation dimensions modeled span deployment architecture, end-use industry vertical, solution layer maturity, and application workflow integration depth across the analysis window. CAGRs derive from elasticity-adjusted adoption curves that weight seasonal project demand patterns against regulatory compliance deadlines. Industry-specific forecast inputs include German automotive OEM cloud migration timelines and EASA formal verification documentation buildout rates.
Decision-makers should treat outputs as directional under assumptions of continued GDPR enforcement consistency and GPU supply normalization; material deviation would warrant model refresh. Specific risk factors include cross-border data sovereignty rulings that fragment unified architectures and specialized talent scarcity that delays cloud-native migration. Recalibration cycles align with material shifts in EASA certification memoranda coverage and hyperscaler pricing structure revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Conference Room Solutions Market
Digital Solutions
Quality Process Management Application Market
Digital Solutions
Global Smart Offices Market
Digital Solutions
Data Labeling Solution and Services Market
Digital Solutions
Agriculture Software Market
Digital Solutions
Digital Business Support System Market
Digital Solutions
End User Experience Monitoring (EUEM) Market
Digital Solutions
Global Digital Experience Platform Market
Digital Solutions
Digital Onboarding Market
Digital Solutions
Contactless Ticketing Solutions Market
Digital Solutions
UK Route Optimization Software Market
Digital Solutions
Europe Data Virtualization Market
Digital Solutions
Track and Trace Solutions Market
Digital Solutions
Plant Asset Management (PAM) Market
Digital Solutions
Precision Agriculture Software Market
Digital Solutions
Warehouse Digital Twin Simulation and Optimization Market