
 Grna Market | 2026-2036
Grna Market Size, Share, and Industry Trends Forecast 2026-2036
Grna Market Analytics
CRISPR-based therapeutics is restructuring pharmaceutical pipelines as gene editing applications expand from research tools into clinical programs. Thermo Fisher Scientific Inc. leverages its reagent manufacturing scale to supply CRISPR workflows across academic and commercial labs worldwide. Merck KGaA anchors European gRNA production through its Sigma-Aldrich distribution network. Synthego Corporation differentiates through synthetic gRNA chemistry optimized for high-fidelity editing applications.
Guide RNA (gRNA) comprises a customizable 20-nucleotide spacer sequence fused to a conserved scaffold that directs Cas nucleases to specific genomic loci with precision matching determined by Watson-Crick base pairing. The molecule functions as programmable targeting machinery, enabling site-specific DNA cleavage for knockout, insertion, or base-editing applications across mammalian, plant, and microbial systems. Synthetic gRNA products command premium positioning over in vitro transcribed variants due to batch consistency and reduced cellular immunogenicity. Bulk delivery channels serve large pharmaceutical developers running high-throughput screening campaigns, while e-commerce routes capture fragmented academic demand. Packaging in single-use aliquots reduces degradation risks during cold-chain handling.
The US FDA maintains active oversight of gene editing trials through its Office of Cellular, Tissue, and Gene Therapies, while the EMA's CAT committee evaluates advanced therapy medicinal products containing CRISPR components. REACH compliance governs chemical synthesis reagents imported into European manufacturing facilities. ISO 13485 certification pressures suppliers serving diagnostic applications. Stakeholders must monitor evolving patent landscapes around gRNA scaffold designs as freedom-to-operate disputes intensify between platform holders and research supply vendors.
Market Dynamics
CRISPR-based therapeutics is restructuring pharmaceutical pipelines as gene editing applications expand from research tools into clinical programs, creating concentrated demand for high-fidelity synthetic guide RNA across therapeutic development and diagnostic manufacturing.
Growth Catalysts
- FDA Accelerated Approval Pathways:The US FDA's Office of Cellular, Tissue, and Gene Therapies has streamlined IND reviews for nucleic acid therapies, compressing development timelines for CRISPR-based drug candidates.
- Synthetic Chemistry Advances:Optimized phosphoramidite synthesis and purification protocols now deliver batch-to-batch gRNA consistency exceeding in vitro transcribed alternatives, reducing immunogenicity risks in human trials.
- Boston-San Francisco Biotech Clusters:Anchored R&D investment in these metropolitan areas concentrates demand for research-grade and GMP-compliant gRNA, pulling supply chain capacity toward North American manufacturing.
Market Restraints
- Phosphoramidite Raw Material Concentration:Specialty nucleotide monomer supply concentrates among limited European and Asian chemical manufacturers, exposing gRNA producers to input cost volatility and single-source risk.
- Scaffold Patent Thickets:Freedom-to-operate disputes around gRNA structural designs create licensing friction, particularly for research supply vendors seeking to commercialize next-generation editing formats.
- REACH Compliance Burden:Chemical synthesis reagents imported into European manufacturing facilities face extensive registration requirements under ECHA regulations, extending facility qualification timelines.
Strategic Opportunities
- Allogeneic Cell Therapy Manufacturing:Off-the-shelf CAR-T and CAR-NK programs require standardized, scalable gRNA supply chains, opening premium positioning for GMP-certified synthetic producers.
- Japan's Regenerative Medicine Framework:PMDA's conditional approval pathways for gene therapies create a structured route to market for CRISPR developers, pulling gRNA demand toward Asia-Pacific therapeutic partnerships.
- Prime Editing Convergence:Integration of reverse transcriptase with Cas9 nickase architectures demands engineered gRNA variants with extended 3' termini, creating white space for chemistry-optimized product lines.
Industry Challenges
- GMP Facility Qualification Timelines:ISO 13485 certification and FDA facility inspections for diagnostic-grade gRNA production require 18-24 month validation cycles, compressing margin recovery windows.
- Cas9 Protein Co-Manufacturing Complexity:Ribonucleoprotein complex assembly demands synchronized gRNA and recombinant protein production, creating inventory matching and cold-chain coordination hurdles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grna Market |
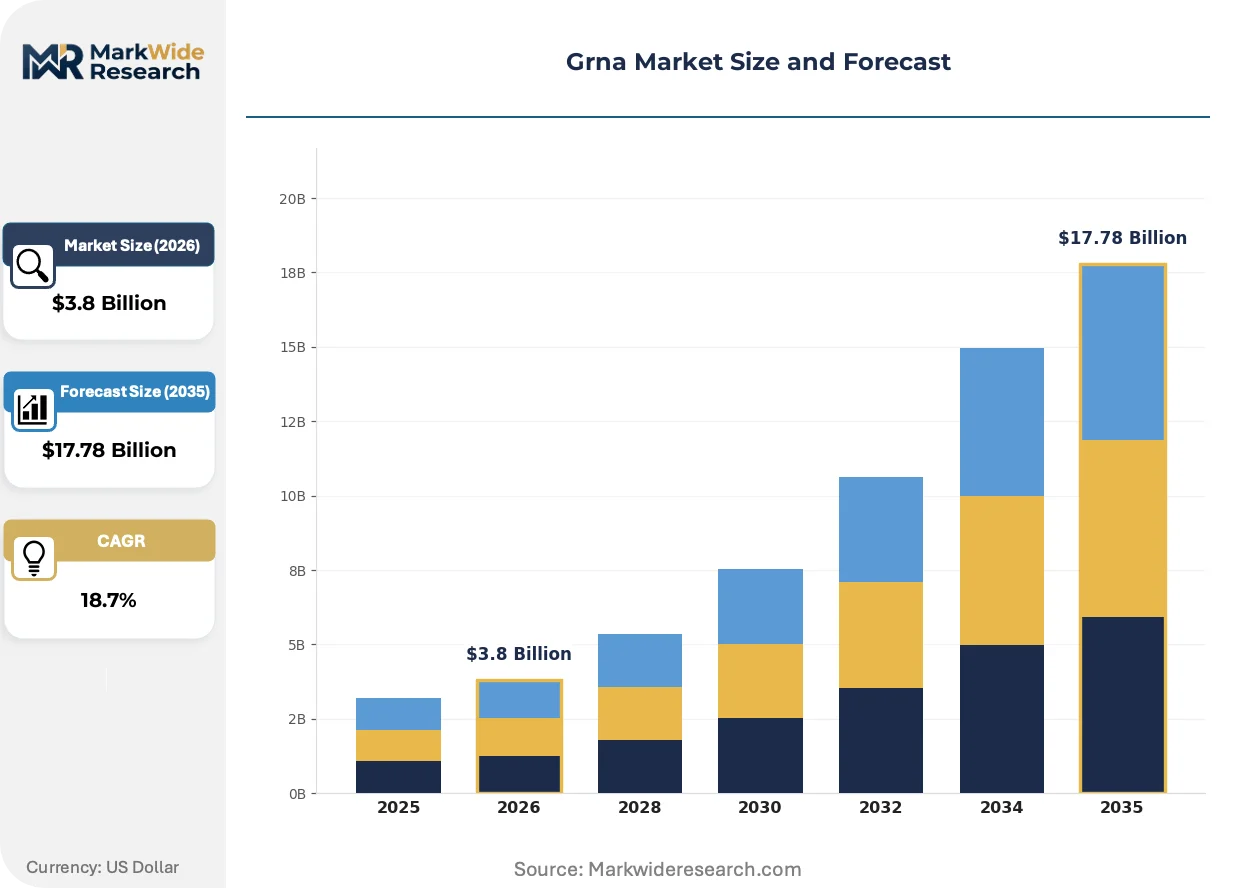
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.78 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seeds, Fertilizers, Insecticides, Herbicides End Use Industry: Agriculture, Horticulture, Landscaping, Gardening Delivery Mode: Bulk Delivery, Retail Distribution, Direct Sales, E-commerce Packaging Type: Packets, Bags, Bulk Containers, Bottles |
| Companies Covered | Thermo Fisher Scientific Inc., Merck KGaA, Agilent Technologies Inc., Jena Bioscience GmbH, Synthego Corporation, Takara Bio Inc., Synbio Technologies, System Biosciences LLC, Azenta Life Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grna Market Evolving Landscape
Guide RNA manufacturing is converging with therapeutic-grade quality systems as clinical applications displace research-scale consumption, while regulatory frameworks mature and procurement patterns consolidate around qualified suppliers.
Engineered gRNA scaffolds with modified 2'-O-methyl and phosphorothioate backbones are unifying previously separate research and therapeutic quality tiers. Large pharmaceutical developers running high-throughput screening campaigns now specify these chemistries for early-stage programs, anticipating clinical transition without reformulation. This unification compresses the supplier base toward manufacturers with validated GMP infrastructure.
EMA's CAT committee has formalized guidance on starting materials for advanced therapy medicinal products containing CRISPR components, requiring documented viral safety and impurity profiles for exogenous nucleic acids. European manufacturers must now maintain dedicated production suites with segregated air handling systems. Diagnostic applications face parallel ISO 13485 certification pressures, forcing dual-track quality investments.
Academic laboratories are consolidating purchasing through institutional procurement agreements with sole-source synthetic gRNA vendors, displacing fragmented e-commerce transactions. Core facilities at research universities in Germany, the United Kingdom, and the Netherlands now negotiate enterprise pricing for standardized aliquot formats. This concentration favors suppliers with established cold-chain distribution networks and batch documentation systems.
Grna Market Segmentation
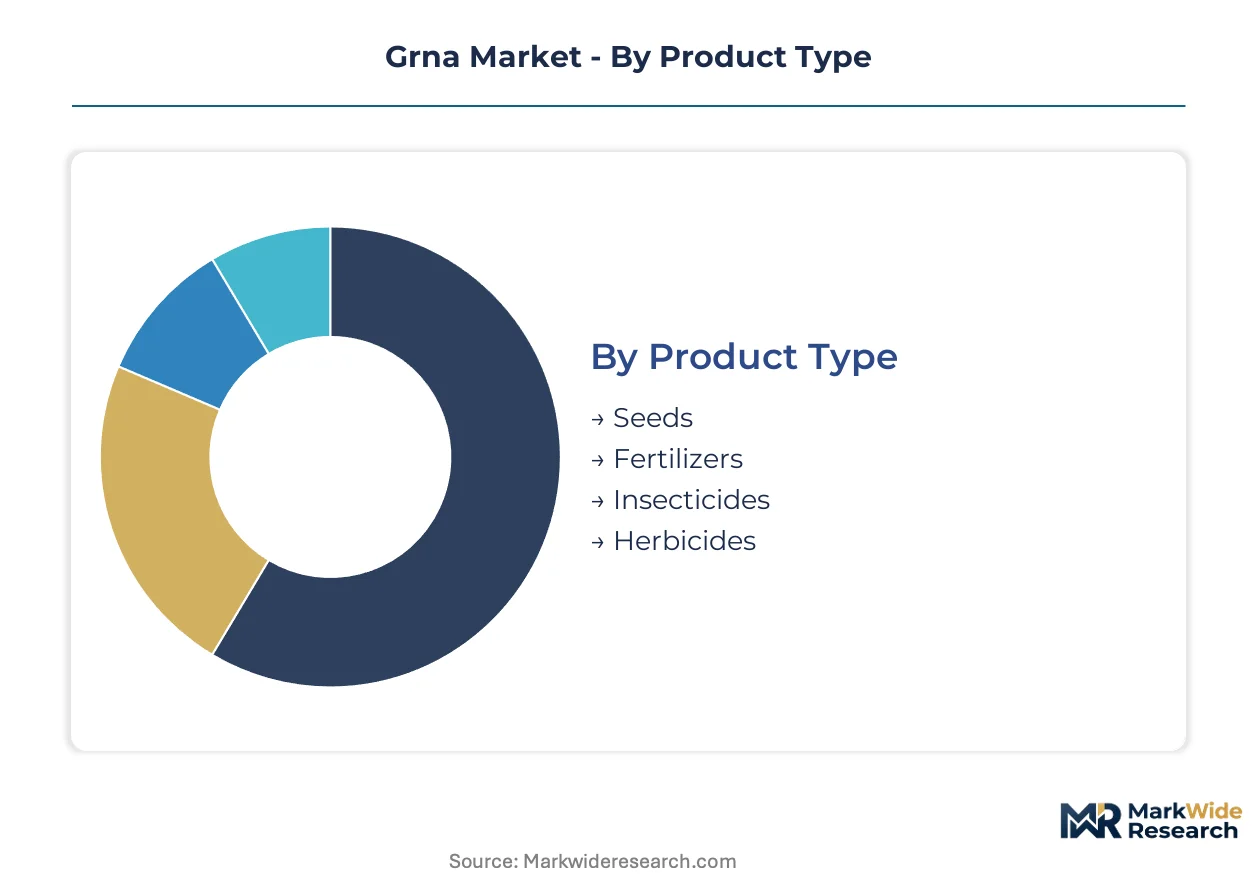
Guide RNA market segmentation reflects the tension between standardized research-grade products and customized therapeutic formulations. Procurement patterns diverge sharply between high-volume screening campaigns requiring bulk consistency and precision editing applications demanding sequence-specific optimization.
Product Type:
The customization-vs-standardization spectrum runs from off-the-shelf catalog products to fully bespoke synthetic constructs engineered for specific genomic targets and delivery modalities.
- Seeds:Genetically modified crop seeds incorporating CRISPR-edited traits require specialized gRNA sequences validated for plant cell transformation protocols. Demand concentrates among agricultural biotechnology developers in the United States and Brazil pursuing drought-resistant and nutrient-optimized varieties, constrained by trait approval timelines at national biosafety regulators.
- Fertilizers:Microbial inoculant formulations enhanced through gene editing rely on gRNA-directed strain improvements for nitrogen fixation efficiency. Research-grade synthetic gRNA supplies academic plant microbiology programs running high-throughput soil bacteria screening.
- Insecticides:RNA interference-based pest control products utilize gRNA-designed dsRNA constructs targeting essential insect genes. Manufacturing scales remain pilot-phase as EPA registration pathways for nucleic acid biocides mature.
- Herbicides:Herbicide-tolerant crop traits engineered via CRISPR base editing specify high-fidelity gRNA with minimized off-target profiles. Bulk procurement channels serve multinational seed developers running stacked trait development programs.
Leading the category by volume: Seeds. Growing fastest: Insecticides.
End Use Industry:
Application maturity determines margin structure, with therapeutic-grade specifications commanding substantial premiums over research and agricultural tiers.
- Agriculture:Large-scale row crop applications drive the highest absolute gRNA consumption volumes. Trait development pipelines at major seed companies specify standardized 20-mer spacer designs for rapid target validation, with procurement consolidating through multi-year supply agreements.
- Horticulture:Specialty fruit and vegetable breeding programs utilize gRNA for accelerated varietal improvement. European greenhouse operators and Mediterranean citrus research stations anchor regional demand for pathogen resistance editing.
- Landscaping:Turfgrass and ornamental plant developers apply CRISPR for reduced-maintenance cultivars. Fragmented demand across municipal and commercial purchasers limits supplier engagement to catalog product offerings.
- Gardening:Consumer-facing gene editing remains pre-commercial, with gRNA supply restricted to research consortiums and regulatory demonstration projects. Direct-to-consumer applications face substantial biosafety and labeling compliance burdens.
By revenue concentration: Agriculture dominates. Steepest expansion trajectory: Horticulture.
Delivery Mode:
Channel configuration directly reflects customer scale and quality documentation requirements, with certified therapeutic supply chains operating in parallel to research distribution networks.
- Bulk Delivery:Pharmaceutical developers running CRISPR therapeutic manufacturing specify GMP-certified gRNA in kilogram quantities. Cold-chain logistics and batch documentation systems anchor supplier relationships.
- Retail Distribution:Research supply distributors serve mid-scale academic and biotechnology customers through regional warehousing networks. Sigma-Aldrich and Thermo Fisher Scientific maintain dominant shelf presence.
- Direct Sales:Large agricultural biotechnology companies negotiate direct manufacturing agreements for proprietary trait development programs. Custom synthesis contracts specify dedicated production capacity and exclusivity provisions.
- E-commerce:Fragmented academic demand consolidates through institutional procurement portals. Core facility managers at research universities optimize cost per edit through volume aggregation.
By transaction value: Bulk Delivery leads. Gaining share fastest: Direct Sales.
Packaging Type:
Format selection balances degradation risk against handling efficiency, with single-use aliquots dominating high-value therapeutic applications and bulk containers serving screening-scale consumption.
- Packets:Pre-measured lyophilized gRNA aliquots eliminate reconstitution variability for standardized editing protocols. Diagnostic manufacturers specify packet formats for kit integration.
- Bags:Flexible packaging accommodates intermediate-scale liquid gRNA shipments with modified atmosphere preservation. Agricultural research stations favor bag formats for field trial logistics.
- Bulk Containers:Stainless steel totes and single-use bioreactor bags serve commercial therapeutic manufacturing with ton-scale nucleic acid requirements. ISO 13485-certified filling operations command substantial facility investment.
- Bottles:Amber glass and fluoropolymer bottles preserve gRNA integrity for long-term storage applications. Research supply catalogs standardize on multiple volume tiers.
By unit volume: Bulk Containers lead. Expanding most quickly: Packets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qualified Opportunity Zones in Massachusetts and California concentrate gene editing R&D through tax-advantaged capital deployment, anchoring North American gRNA demand. Biotech clusters in Greater Boston and San Francisco Bay Area pull supply chain investment toward GMP-certified manufacturing infrastructure.
United States
FDA's Office of Cellular, Tissue, and Gene Therapies maintains active IND review pipelines for CRISPR-based drug candidates, compressing development timelines. The agency's accelerated approval pathways for nucleic acid therapies reduce regulatory friction for therapeutic-grade gRNA procurement. Greater Boston anchors demand through Harvard-MIT-Broad Institute research consortia and Vertex Pharmaceuticals' clinical manufacturing operations.
Germany
REACH compliance governs chemical synthesis reagents imported into European manufacturing facilities, extending facility qualification timelines. EMA's CAT committee evaluates advanced therapy medicinal products containing CRISPR components, requiring documented viral safety profiles. Heidelberg and Munich biotech clusters concentrate demand through EMBL and Max Planck Institute research programs.
China
NMPA's conditional approval pathways for innovative biologics create structured routes to market for gene therapies. Dual carbon goals accelerate agricultural biotechnology investment, pulling gRNA demand toward crop trait development. Shanghai and Shenzhen biotech parks anchor manufacturing through BGI Genomics and domestic CRISPR platform developers.
Japan
PMDA's regenerative medicine framework enables conditional approval for gene therapies, reducing time-to-market for CRISPR developers. METI's strategic innovation programs fund domestic nucleic acid manufacturing capacity. Kobe and Osaka medical device clusters concentrate demand through Riken Institute and Takeda Pharmaceutical partnerships.
Switzerland
Swissmedic's streamlined ATMP authorization procedures attract CRISPR therapeutic developers seeking European market access. Federal technology transfer programs support precision medicine infrastructure investment. Basel and Zurich biotech corridors anchor demand through Roche and Novartis gene editing research divisions.
Grna Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with research supply distributors dominating fragmented academic procurement while GMP-certified producers capture concentrated pharmaceutical demand. The vendor base organizes into three tiers: multinational life science conglomerates with reagent manufacturing scale, mid-cap synthetic chemistry specialists, and regional distribution intermediaries. Capacity expansion and strategic partnerships represent the dominant competitive moves, as players seek backward integration into phosphoramidite raw materials and forward integration into diagnostic applications.
Among US-based life science conglomerates, Thermo Fisher Scientific Inc. exemplifies the scale-driven archetype through its reagent manufacturing infrastructure and global distribution networks. Merck KGaA anchors European supply through its Sigma-Aldrich distribution channel, representing the integrated chemical-synthesis archetype. Synthego Corporation occupies a specialist position within the synthetic gRNA chemistry segment, exemplifying the premium-fidelity archetype optimized for therapeutic applications.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Agilent Technologies Inc. |
| Jena Bioscience GmbH |
| Synthego Corporation |
| Takara Bio Inc. |
| Synbio Technologies |
| System Biosciences LLC |
| Azenta Life Sciences |
| Others |
Value Network & Pricing Analysis
GMP certification tiers bifurcate synthetic gRNA procurement into premium therapeutic-grade and research-grade commodity segments, with pricing power concentrating among ISO 13485-qualified manufacturers serving FDA-regulated clinical programs while spot-market catalog products face cost compression from phosphoramidite input volatility.
Pricing Analysis
Expedited delivery premiums for custom-synthesized gRNA sequences with sub-two-week turnaround anchor pricing power at specialty manufacturers serving Phase I/II therapeutic developers. Three-tier pricing structure across premium, standard, and economy levels reflects batch documentation depth, with GMP-certified lots commanding substantial premiums over research-grade alternatives. Cost compression in catalog 20-mer products is intensifying because Thermo Fisher and Merck KGaA scale automated synthesis platforms. Academic core facilities exhibit highest price sensitivity, while pharmaceutical manufacturing groups prioritize supply security over unit cost.
Supply Chain Analysis
Specialized nucleic acid chemist availability constrains capacity expansion in Switzerland and Germany, where EMA-aligned quality systems demand experienced personnel for CAT-compliant production. Phosphoramidite monomer supply draws from limited European and Asian chemical manufacturers, exposing gRNA producers to single-source vulnerability for specialty modified nucleotides. REACH registration burdens for imported synthesis reagents extend European facility qualification timelines. Distribution runs through qualified cold-chain logistics networks for therapeutic-grade shipments, with research products moving via standard refrigerated freight.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
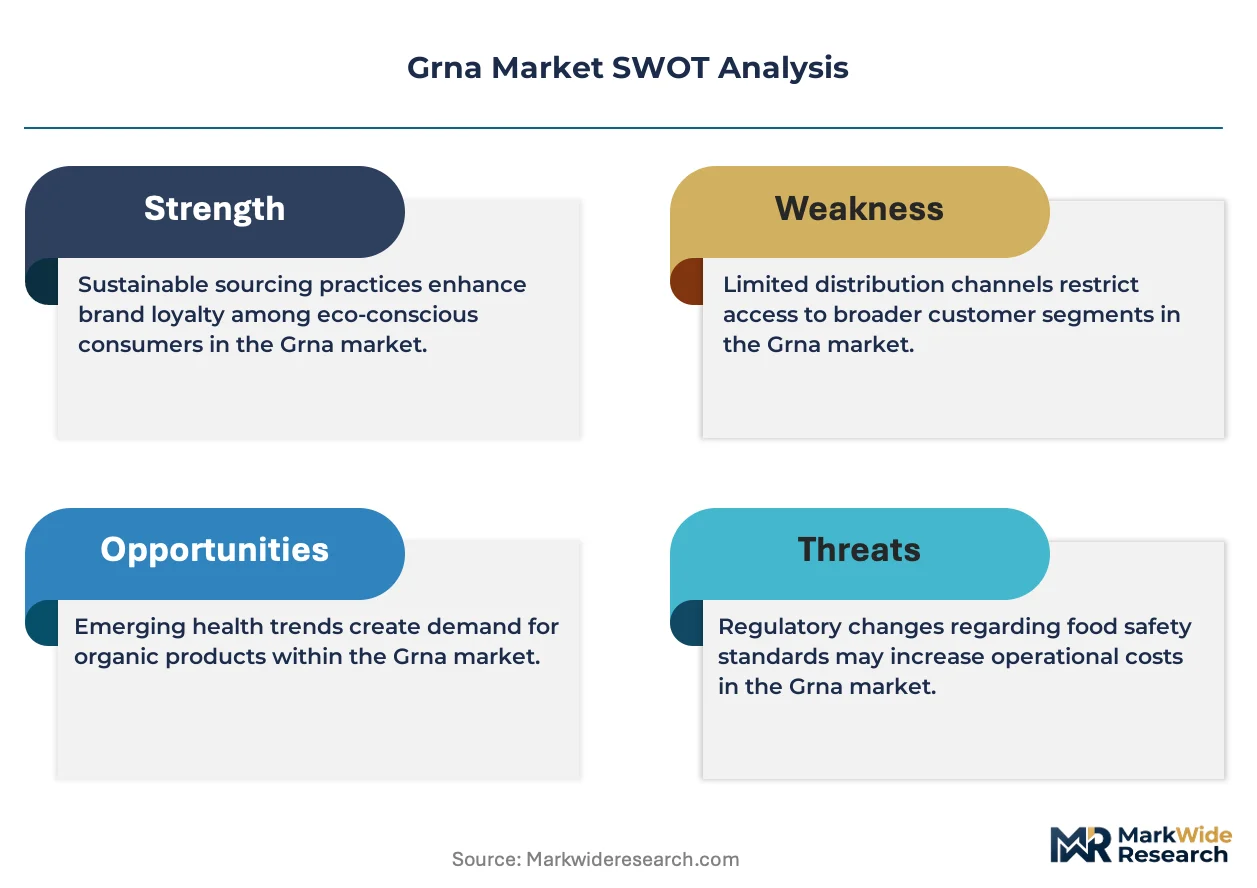
Scaffold patent thickets and GMP qualification barriers are forcing consolidation among undifferentiated research-grade suppliers, rewarding scaled manufacturers with backward integration into phosphoramidite chemistry.
For Market Incumbents: Deploy captive phosphoramidite production to insulate margin structures from specialty nucleotide monomer cost volatility. Secure exclusive distribution agreements with emerging allogeneic cell therapy developers before rival suppliers achieve CAT-compliant certification. Patent litigation risk from platform holders threatens unlicensed scaffold variants, necessitating freedom-to-operate investment or licensing settlements. For New Entrants and Emerging Players: Capture white space in prime editing gRNA variants with extended 3' termini, where engineered backbone chemistries remain underdeveloped relative to standard Cas9 formats. Japan's PMDA conditional approval pathway offers the most penetrable regulatory entry point for therapeutic-grade supply partnerships. Target agricultural biotechnology direct sales channels through custom trait development contracts with Brazilian and Chinese seed developers. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap synthetic chemistry specialists possessing validated GMP infrastructure and established phosphoramidite sourcing relationships, given EMA's formalized starting-materials guidance for advanced therapy medicinal products. Five-to-ten-year viability hinges on CRISPR therapeutic approval velocity and manufacturing scale-up execution. Watch FDA breakthrough therapy designations for gene editing candidates as inflection indicators for gRNA demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Manufacturing Scale-Up | ISO 13485-certified capacity expansion secures supply agreements with Vertex and other clinical-stage CRISPR developers. |
| Phosphoramidite Backward Integration | In-house specialty nucleotide production reduces input cost volatility and single-source exposure for European manufacturers. |
| Prime Editing Chemistry Development | Engineered gRNA variants with modified backbones address reverse transcriptase fusion requirements for next-generation platforms. |
| Japan PMDA Partnership Formation | Conditional approval pathway access pulls gRNA demand toward Asia-Pacific therapeutic manufacturing consortia. |
| Diagnostic Application Certification | IVD-registered gRNA supply opens kit integration opportunities with Roche and Thermo Fisher molecular diagnostics divisions. |
Research Methodology
Independent corroboration across gene therapy manufacturing executives, regulatory affairs specialists at EMA and FDA, CRISPR platform R&D directors, and academic core facility managers underwrites the qualitative findings. Secondary validation draws from ClinicalTrials.gov gene editing trial registrations, EMA CAT committee guidance documents, FDA Office of Cellular, Tissue, and Gene Therapies IND databases, and SEC filings of listed life science reagent suppliers. Bottom-up demand modeling across therapeutic, diagnostic, and agricultural application segments triangulates against top-down market sizing from phosphoramidite consumption trends and CRISPR patent landscape analysis.
Historical reference periods spanning pre-pandemic baseline through recent regulatory guidance issuance anchor the forecast window to observable inflection points in GMP certification timelines and therapeutic candidate advancement rates. Segmentation modeling incorporates product chemistry tier, end-use industry, delivery mode, and regional regulatory cluster dimensions throughout the projection horizon. CAGRs derive from fitted adoption curves for clinical-stage CRISPR programs and elasticity-adjusted agricultural biotechnology investment trajectories. Forecast inputs include EMA advanced therapy medicinal product approval velocity and NMPA innovative biologics pathway utilization rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to scaffold patent litigation resolutions and allogeneic cell therapy manufacturing scale-up success. Forecasts reflect documented assumptions regarding regulatory pathway stability and phosphoramidite supply continuity. CRISPR therapeutic safety events, REACH enforcement intensification, or phosphoramidite manufacturing consolidation could materially revise demand projections. Material deviation in FDA breakthrough therapy designation velocity or EMA CAT committee guidance scope warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Fertility Tracking Apps Market
Others
North America Automotive LED Lighting Market
Others
High Frequency Vibrator Market
Others
Coloring Apps Market
Others
Fibert Market
Others
Enterprise Video Market
Others
Industrial Personal Computer Market
Others
Smart Home Gateways Market
Others
Industrial Computers Market
Others
Cat Food and Snacks Market
Others
North America Micro Market
Others
Digital LUX Meter Market
Others
Smart Home Technologies Market
Others
Asia-Pacific Intercom Devices Market
Others
Rotary Union Market
Others
Europe Video Encoder Market