
 Effervescent Product Market | 2026-2036
Effervescent Product Market Size, Share, and Industry Trends Forecast 2026-2036
Effervescent Product Market Analytics
Germany is reconfiguring its position as a high-volume effervescent manufacturing base, driven by specialized chemical processing infrastructure and stringent pharmaceutical-grade certification standards. Bayer AG leverages its integrated active ingredient sourcing to sustain cost advantages across European distribution networks. Hermes Arzneimittel GmbH anchors regional supply through dedicated effervescent tablet production lines. Reckitt Benckiser Group Plc competes via broad retail channel control spanning supermarkets and pharmacies.
Effervescent products are solid dosage forms that release carbon dioxide when dissolved in water, typically containing sodium bicarbonate and an organic acid such as citric or tartaric acid, with disintegration times under three minutes for optimal bioavailability. They deliver rapid absorption of vitamins, minerals, or active pharmaceutical ingredients through gastric pre-dissolution. Tablets dominate volume production due to established compression tooling and extended shelf stability, while powders capture faster growth in sports nutrition applications where customizable dosing matters. Nutritional supplementation commands the largest application share, though hydration products targeted at fitness enthusiasts and sports teams are expanding fastest through online retail channels.
The EU EMA and EFSA govern pharmaceutical and food-grade effervescent standards, while REACH regulates excipient chemical safety across European formulations. FDA oversight shapes US market access requirements for effervescent drugs and dietary supplements, creating divergent compliance pathways for multinational suppliers. Stakeholders must monitor evolving carbonated dosage form monographs and regional sustainability mandates affecting primary packaging materials.
Market Dynamics
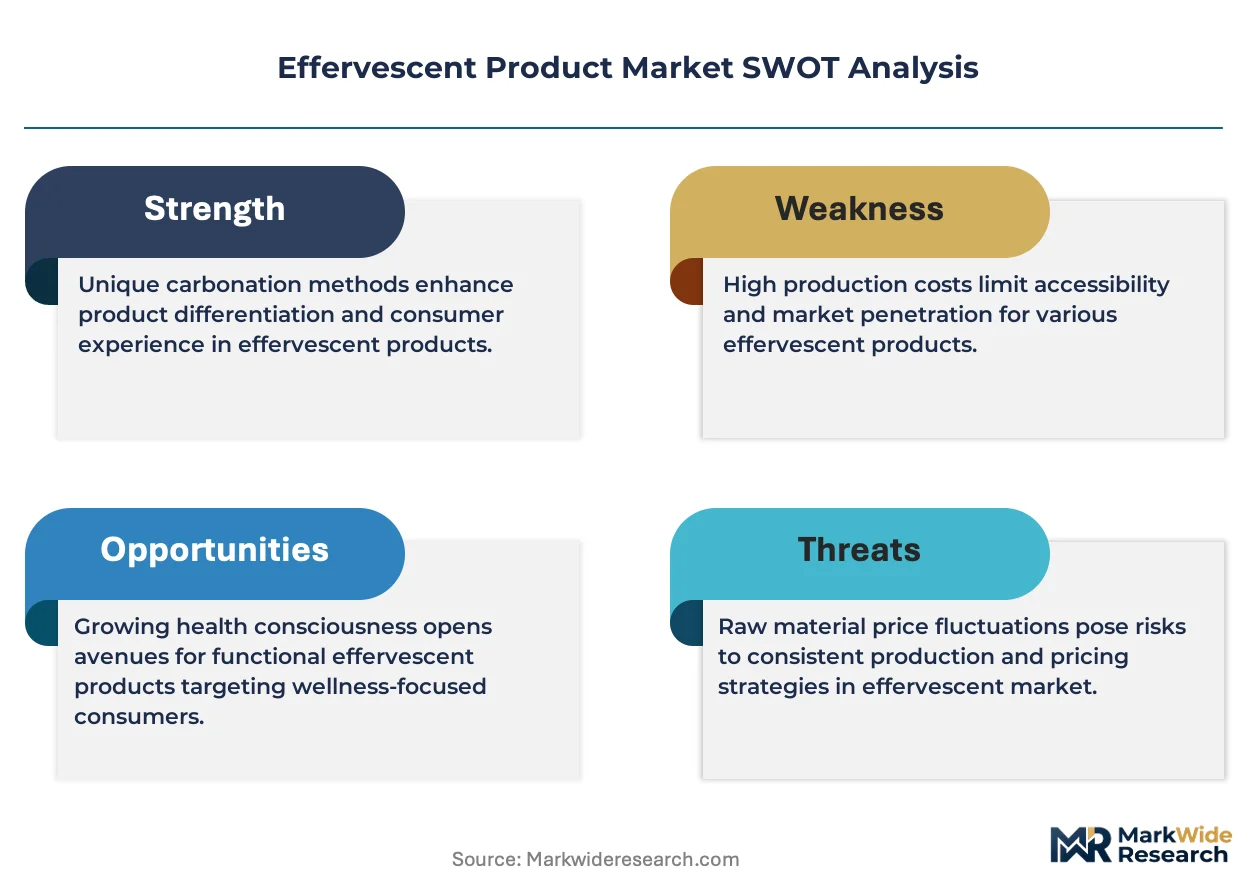
The EU F-Gas Regulation and REACH standards are forcing reformulation of effervescent tablet chemistry, compressing legacy carbonate-acid systems while opening pathways for novel gas-release mechanisms and sustainable excipient sourcing.
Growth Catalysts
- Sports nutrition procurement:Fitness enthusiasts and professional athletic programs are expanding tablet procurement for rapid electrolyte replenishment, driving volume through direct-to-consumer channels.
- REACH chemical safety frameworks:European excipient standardization is creating certified supply pools that reduce regulatory friction for compliant manufacturers.
- German manufacturing concentration:Specialized chemical processing infrastructure around Ludwigshafen and Leverkusen provides integrated active ingredient sourcing for effervescent production.
Market Restraints
- Tartaric acid supply volatility:Brazilian and Spanish grape-derived acid supplies face climate-driven harvest fluctuations, compressing margin stability for carbonate-acid formulations.
- Primary packaging material constraints:Aluminum-PVC blister compliance with EU sustainability mandates requires capital-intensive retooling of moisture-barrier systems.
- Functional beverage substitution:Ready-to-drink carbonated wellness beverages capture convenience-seeking consumers who bypass tablet dissolution steps.
Strategic Opportunities
- Indian pharmaceutical export channels:CDSCO-certified manufacturing for effervescent generics targets underserved African and Southeast Asian markets with price-optimized formulations.
- Personalized dosing platforms:Powder sachet systems with variable-fill technology enable customizable vitamin stacking for nutrition subscription services.
- EU Green Deal packaging incentives:Biodegradable film and paper-based primary packaging innovations qualify for green procurement preferences in German and French hospital systems.
Industry Challenges
- Pharmaceutical-grade certification timelines:EMA carbonated dosage form monograph compliance requires 18-24 month stability documentation, delaying product launches.
- Moisture-control engineering scarcity:Formulation chemists with effervescent-specific hygroscopicity management expertise command premium compensation in tight labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Effervescent Product Market |
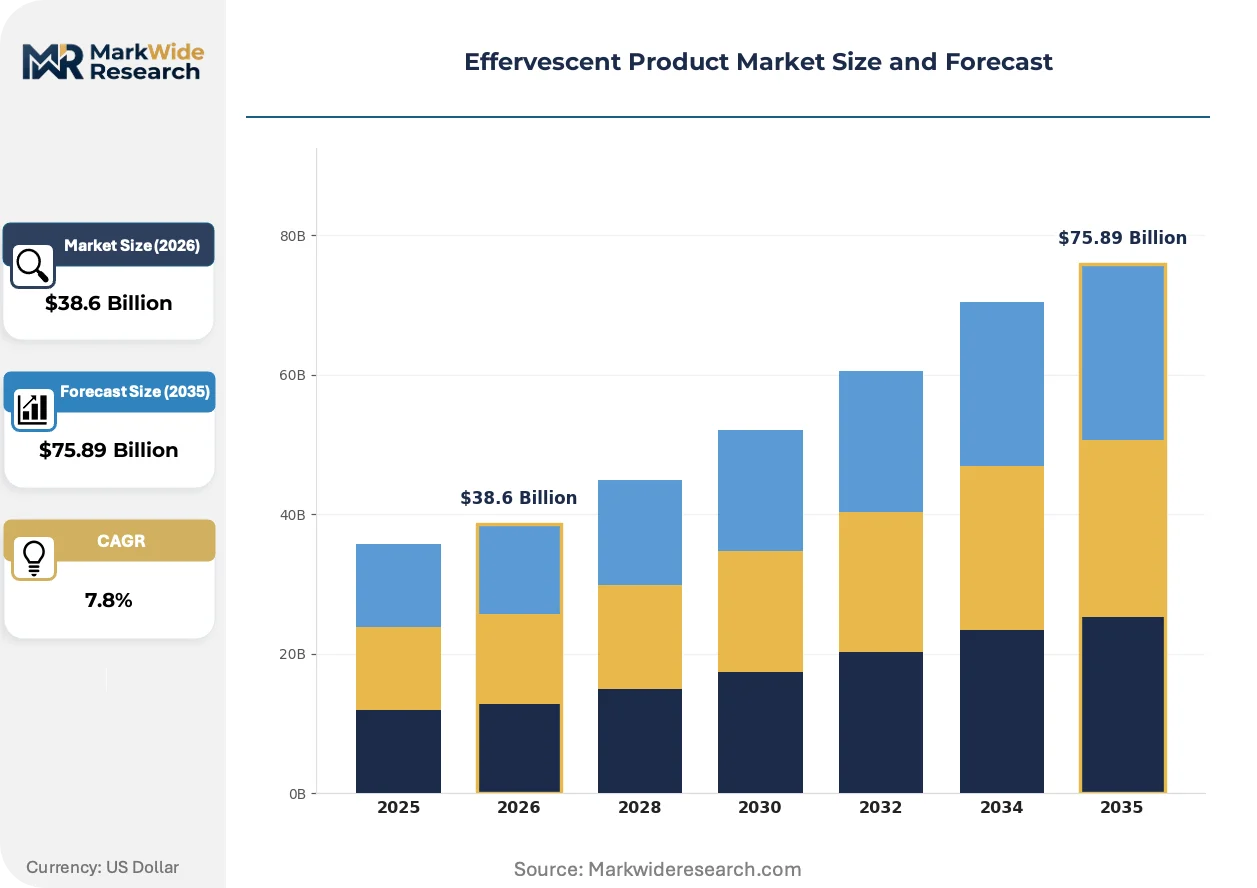
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $75.89 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Powders, Beverages, Capsules End User: Retail Consumers, Fitness Enthusiasts, Healthcare Providers, Sports Teams Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies Application: Nutritional Supplementation, Hydration, Flavoring, Medicinal |
| Companies Covered | Bayer AG, Reckitt Benckiser Group Plc, Nuun and Company Inc., Herbalife International of America, Inc., Perrigo Company plc, Hermes Arzneimittel GmbH, Chiesi Farmaceutici S.p.A., Prestige Brands, Inc., Amerilab Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Effervescent Product Market Evolving Landscape
Formulation science and sustainability mandates are converging to reshape effervescent product architecture, with gas-release mechanisms and packaging systems undergoing simultaneous transformation.
Microencapsulated acid-carbonate systems are hybridizing traditional effervescent chemistry with controlled-release pharmaceutical technology. Pediatric and geriatric medication developers are adopting these systems to mask bitter active ingredients while maintaining rapid disintegration. The technology is hybridizing competitive positioning between instant-dissolve tablets and extended-release capsules, creating intermediate dosage categories.
REACH Annex XIV authorization requirements are restricting legacy perfluorinated moisture-barrier coatings in effervescent packaging. Manufacturers must qualify alternative aliphatic polymer systems that maintain three-year shelf stability. German and French pharmaceutical packagers are most affected, accelerating migration to bio-based barrier films ahead of 2026 sunset dates.
Sports team bulk purchasing is consolidating procurement decisions at the athletic department level, displacing individual athlete retail purchases. Direct-to-club subscription models with seasonal replenishment schedules are capturing volume previously fragmented across pharmacy and supermarket channels. This concentration is most visible in North American collegiate athletic programs and European professional football academies.
Effervescent Product Market Segmentation
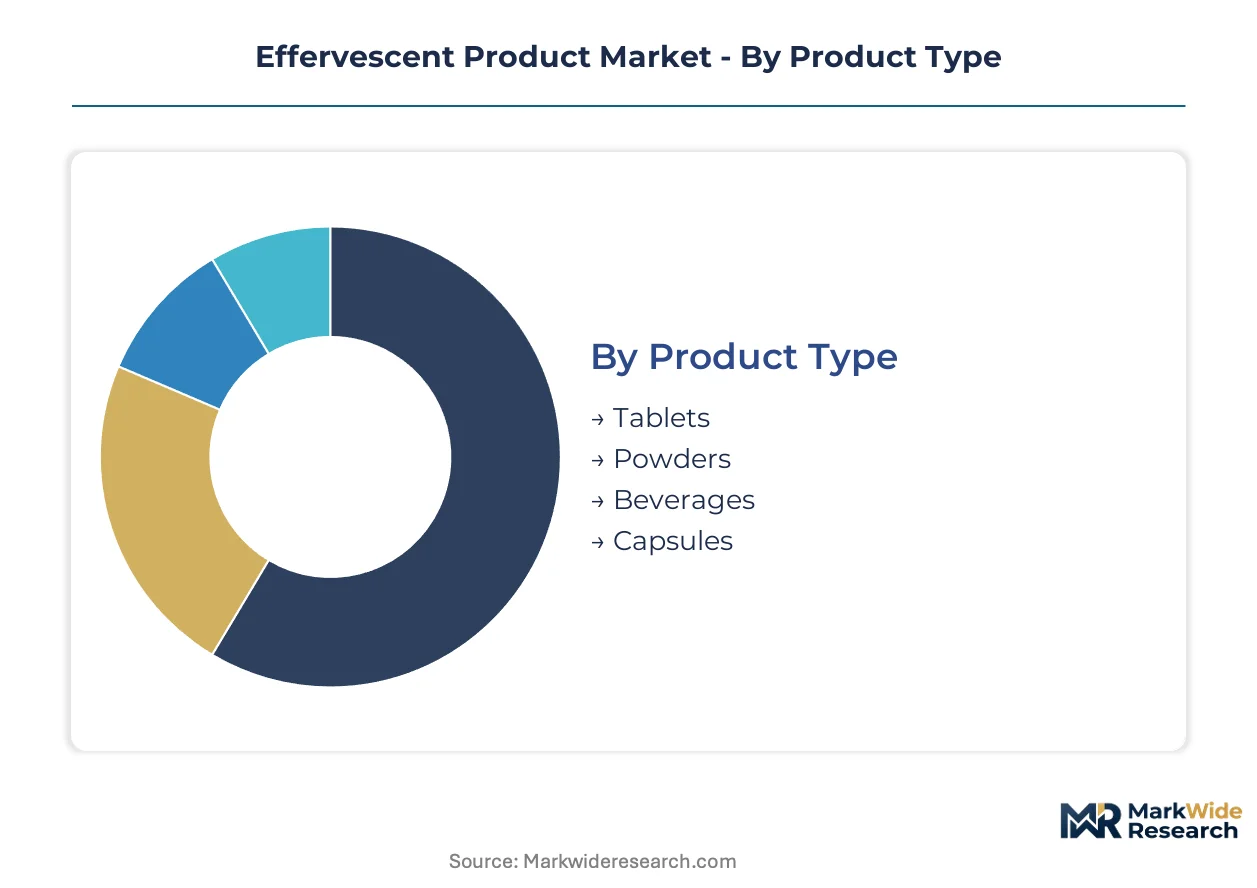
Effervescent product architectures span multiple formulation chemistries, each demanding distinct moisture-control engineering and dissolution kinetics. Segmentation reveals how gas-release mechanisms and packaging requirements fragment manufacturing capabilities across product categories.
Product Type:
Use cases range from portable single-dose convenience to bulk sports nutrition preparation, with each format imposing distinct stability and bioavailability constraints.
- Tablets:Compressed sodium bicarbonate-citrate matrices deliver sub-three-minute disintegration through optimized particle size distribution and lubricant selection. German pharmaceutical packagers dominate volume through automated blister lines serving hospital and retail pharmacy networks, though REACH Annex XIV coating restrictions are forcing qualification of alternative moisture-barrier systems.
- Powders:Granular effervescent systems enable variable dosing for personalized nutrition stacking, with faster hydration kinetics than compressed forms. Sports team procurement concentrates demand through direct-to-club subscription models displacing individual athlete retail purchases, particularly across North American collegiate athletic programs.
- Beverages:Ready-to-drink carbonated wellness formulations bypass dissolution steps entirely, capturing convenience-seeking consumers who reject tablet preparation rituals.
- Capsules:Microencapsulated acid-carbonate hybrids mask bitter actives while maintaining rapid release, serving pediatric and geriatric medication developers seeking intermediate dosage categories between instant-dissolve and extended-release formats.
Established volume favors tablets; emerging adoption favors powders.
End User:
Customer archetypes diverge sharply in procurement scale, price sensitivity, and regulatory sophistication, with institutional buyers consolidating purchasing decisions previously fragmented across individual consumers.
- Retail Consumers:Individual purchasers through pharmacy and supermarket channels prioritize portability and brand recognition over unit economics, driving single-strip blister packaging formats.
- Fitness Enthusiasts:Dedicated amateur athletes generate recurring demand for electrolyte-focused formulations through online subscription services, with customizable dosing preferences favoring powder sachets over fixed-dose tablets.
- Healthcare Providers:Hospital and clinic procurement departments enforce pharmaceutical-grade certification requirements, with German and French hospital systems increasingly applying EU Green Deal packaging incentives to supplier selection criteria.
- Sports Teams:Athletic department-level bulk purchasing consolidates previously fragmented individual decisions, with seasonal replenishment schedules and volume pricing structures capturing procurement previously distributed across retail channels.
Procurement scale concentrates with sports teams; margin capture concentrates with healthcare providers.
Distribution Channel:
Channel economics reflect moisture-sensitivity handling requirements and regulatory compliance burdens, with direct-to-consumer platforms bypassing traditional pharmacy margin structures.
- Online Retail:Direct-to-consumer platforms enable subscription-based replenishment and personalized bundling, with logistics networks requiring climate-controlled warehousing for hygroscopic inventory.
- Supermarkets:Mass-market placement demands price-competitive positioning against functional beverage substitutes, with shelf-stable packaging formats prioritized over pharmaceutical-grade moisture barriers.
- Health Stores:Specialty retailers curate premium-positioned formulations targeting wellness-focused consumers, with staff consultation driving higher conversion rates for complex multi-ingredient products.
- Pharmacies:Professional channel access requires EMA carbonated dosage form monograph compliance and 18-24 month stability documentation, creating regulatory moats against non-pharmaceutical competitors.
Volume flows through supermarkets; value concentrates through pharmacies.
Application:
Functional purpose determines active ingredient selection, dissolution speed requirements, and regulatory pathway, with hydration applications accelerating fastest through fitness-focused channels.
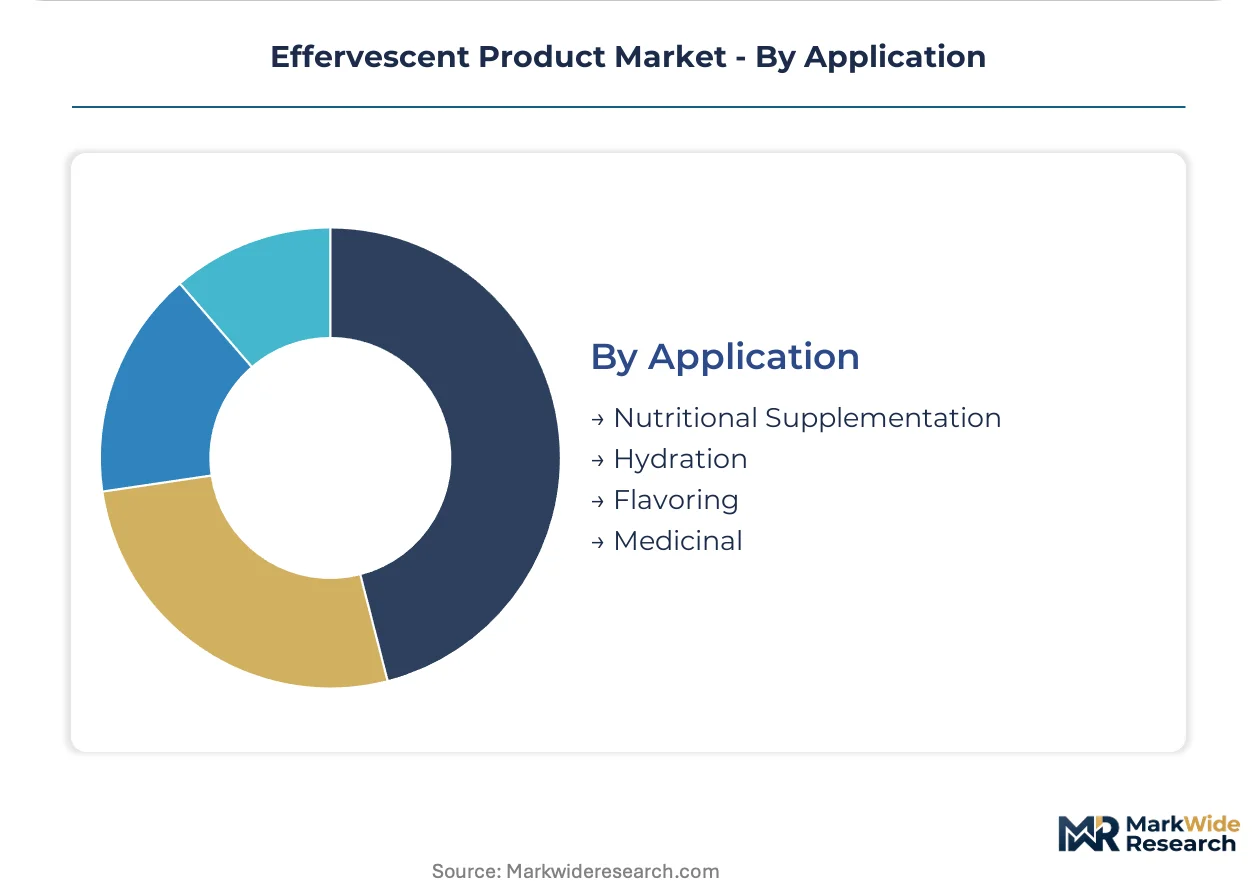
- Nutritional Supplementation:Vitamin and mineral delivery commands the largest application share, with bioavailability advantages over conventional solid dosage forms driving physician recommendations for malabsorption-prone patients.
- Hydration:Electrolyte replenishment formulations are climbing the fastest through sports team and fitness enthusiast procurement, with rapid gastric emptying kinetics supporting intra-workout consumption protocols.
- Flavoring:Carbonated taste enhancement applications leverage effervescent chemistry for beverage preparation, with lower active ingredient loads enabling food-grade rather than pharmaceutical regulatory pathways.
- Medicinal:Prescription and over-the-counter pharmaceutical applications require EMA or FDA oversight depending on market access geography, with analgesic and antacid categories dominating therapeutic use.
Mature scale anchors nutritional supplementation; steepest expansion trajectory sits with hydration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German consumers favor pharmaceutical-grade effervescent tablets through pharmacy channels, while US fitness enthusiasts drive powder sachet adoption via direct-to-consumer platforms. This consumption-mix differential fragments regional manufacturing priorities and regulatory compliance investments.
Germany
Hospital procurement departments enforce EU Green Deal packaging incentives for biodegradable barrier films, with pharmaceutical-grade certification requirements concentrating demand around Ludwigshafen and Leverkusen chemical processing clusters. EMA carbonated dosage form monographs govern production standards, while REACH Annex XIV restrictions accelerate migration from perfluorinated moisture-barrier coatings.
United States
Fitness enthusiasts and collegiate athletic programs consolidate procurement through direct-to-club subscription models, displacing individual retail purchases. FDA oversight shapes dietary supplement and OTC drug pathways, creating divergent compliance requirements for effervescent entrants. Manufacturing concentrates around New Jersey and Pennsylvania pharmaceutical packaging corridors serving East Coast distribution networks.
India
CDSCO-certified generic manufacturers target price-optimized effervescent formulations for underserved African and Southeast Asian export markets. The PLI scheme for pharmaceutical manufacturing incentivizes capacity expansion in Gujarat and Maharashtra. Formulation chemists with hygroscopicity management expertise command premium compensation in tight labor markets around Mumbai and Ahmedabad.
Brazil
Grape-derived tartaric acid harvest fluctuations from São Paulo and Rio Grande do Sul vineyards compress margin stability for carbonate-acid formulations. ANVISA pharmaceutical regulations govern import substitution strategies for effervescent generics. Domestic manufacturing concentrates around São Paulo state pharmaceutical corridors seeking to reduce dependence on Spanish and Argentine acid supplies.
China
NMPA oversight shapes market access for imported effervescent drugs while domestic manufacturers expand vitamin and mineral supplement production for Southeast Asian export channels. Dual carbon goals accelerate packaging sustainability mandates affecting aluminum-PVC blister systems. Manufacturing clusters in Jiangsu and Zhejiang provinces serve both domestic consumption and contract manufacturing for global brands.
Effervescent Product Market Competitive Landscape
Capability concentration sits with specialized pharmaceutical packagers holding EMA certification; scale advantage sits with diversified consumer health conglomerates commanding retail shelf space. The vendor base stratifies across three tiers: integrated chemical-pharmaceutical conglomerates with captive active ingredient sourcing, dedicated effervescent contract manufacturers with formulation expertise, and nutrition-focused direct-to-consumer brands bypassing traditional pharmacy channels. Dominant competitive moves include backward integration into sodium bicarbonate and citric acid supply chains, plus technology licensing for microencapsulated gas-release systems.
Within the pharmaceutical-certified tier, Bayer AG and Hermes Arzneimittel GmbH exemplify integrated European manufacturing archetypes. Among diversified consumer health players, Reckitt Benckiser Group Plc occupies a position representing retail channel control spanning supermarkets and pharmacies. These three entities anchor distinct competitive vectors: chemical integration, specialized effervescent production infrastructure, and mass-market distribution density.
| Leading Market Players |
|---|
| Bayer AG |
| Reckitt Benckiser Group Plc |
| Nuun and Company Inc. |
| Herbalife International of America, Inc. |
| Perrigo Company plc |
| Hermes Arzneimittel GmbH |
| Chiesi Farmaceutici S.p.A. |
| Prestige Brands, Inc. |
| Amerilab Technologies Inc. |
| Others |
Value Network & Pricing Analysis
Ludwigshafen and Leverkusen chemical processing clusters anchor European sodium bicarbonate and citric acid supply, translating captive active ingredient sourcing into downstream pricing power for pharmaceutical-grade effervescent manufacturers. REACH Annex XIV coating restrictions and tartaric acid harvest volatility from Brazilian vineyards are compressing margin stability across carbonate-acid formulation tiers.
Pricing Analysis
Geographic price spreads between German pharmaceutical-grade tablet production and Indian generic export formulations reflect certification-tier differentiation rather than input cost variation alone. Three-tier pricing structure across premium, standard, and economy levels stratifies by EMA carbonated dosage form monograph compliance, with healthcare provider procurement enforcing pharmaceutical-grade premiums. Pricing pressure stems from functional beverage substitution in supermarket channels, where ready-to-drink carbonated wellness products erode tablet convenience premiums. Retail consumers exhibit highest price sensitivity through pharmacy and supermarket channels, while sports team bulk purchasing consolidates volume leverage at athletic department levels.
Supply Chain Analysis
Tariff exposure between Brazil and European Union member states dominates supply chain risk for grape-derived tartaric acid, the organic acid component in traditional effervescent chemistry. Manufacturing concentrates in Germany, India, and China, with sodium bicarbonate sourcing anchored in Ludwigshafen chemical corridors and citric acid production scaling in Chinese Jiangsu and Zhejiang provinces. Raw material dependencies rest on sodium bicarbonate, citric acid, and tartaric acid, with climate-driven harvest fluctuations compressing acid supply stability. Distribution runs through direct-to-club subscription models for sports nutrition powders and automated blister lines serving hospital networks for pharmaceutical tablets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based replenishment services for sports team and fitness enthusiast segments represent a recurring-revenue layer expanding faster than hardware-scale tablet production, transforming effervescent procurement from transactional retail to attached service relationships.
For Market Incumbents: Build regulatory certification moats through EMA carbonated dosage form monograph compliance and 18-24 month stability documentation investments. Bayer AG and Hermes Arzneimittel GmbH exemplify integrated chemical-pharmaceutical positioning that captive active ingredient sourcing from Ludwigshafen clusters reinforces. Defensive moves center on backward integration into sodium bicarbonate supply chains and technology licensing for microencapsulated gas-release systems, countering emerging nutrition-focused direct-to-consumer brands bypassing pharmacy channels. For New Entrants and Emerging Players: Mid-market powder sachet systems for personalized nutrition stacking in North American collegiate athletic programs represent the most penetrable entry point, with variable-fill technology enabling customizable vitamin dosing that fixed-dose tablets cannot match. Indian CDSCO-certified manufacturing for price-optimized effervescent generics targeting underserved African and Southeast Asian markets offers geographic white space. Go-to-market execution favors direct-to-consumer subscription platforms with climate-controlled logistics networks, bypassing traditional pharmacy margin structures. For Investors and Strategic Acquirers: Long-term, this sits as a formulation chemistry consolidation play because specialized effervescent contract manufacturers with hygroscopicity management expertise command premium compensation in tight labor markets. Acquisition targets center on dedicated effervescent production infrastructure holders with EMA certification and established sports team procurement relationships. The signal to watch is sports team bulk purchasing concentration accelerating direct-to-club subscription model adoption, displacing individual athlete retail purchases across European professional football academies and North American collegiate programs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sodium Bicarbonate Supply | Ludwigshafen chemical clusters provide captive active ingredient sourcing for cost-advantaged European distribution. |
| Microencapsulated Gas-Release Technology Licensing | Pediatric and geriatric medication developers adopt hybrid systems masking bitter actives while maintaining rapid disintegration. |
| Direct-to-Club Subscription Platform Launch | Athletic department-level procurement consolidates volume previously fragmented across pharmacy and supermarket channels. |
| Biodegradable Barrier Film Qualification | EU Green Deal packaging incentives in German and French hospital systems accelerate migration from perfluorinated coatings. |
| CDSCO-Certified Export Capacity Expansion | Indian pharmaceutical manufacturing targets price-optimized formulations for underserved African and Southeast Asian markets. |
Research Methodology
Desk research of EMA carbonated dosage form monographs, REACH Annex XIV authorization requirements, and FDA dietary supplement regulations preceded structured interviews with effervescent formulation chemists, pharmaceutical packaging engineers, and sports team procurement coordinators. Secondary validation drew from customs trade data, hospital procurement databases, and GPO contracts. Bottom-up segment sizing triangulated against top-down market value estimates across product type, end user, and distribution channel dimensions.
Assumptions held fixed include sustained EU F-Gas Regulation and REACH standards enforcement, continued sports team procurement consolidation, and functional beverage substitution rates in convenience-seeking consumer segments. Variables modeled encompass tartaric acid supply volatility from Brazilian harvest fluctuations, REACH Annex XIV coating sunset compliance timelines, and CDSCO certification expansion in Indian export manufacturing. CAGRs derived from segment-level volume trajectories and value-per-unit trends across the analysis window, with hydration application growth and powder sachet adoption serving as primary forecast sensitivity inputs.
Practitioners should monitor regulatory restriction timelines for perfluorinated moisture-barrier coatings and climate-driven tartaric acid harvest forecasts for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Milk Powder for Pregnant Women Market
Nutritional Supplements
Forskolin Market
Nutritional Supplements
Global Coq10 Supplement Market
Nutritional Supplements
Insoluble Dietary Fibers Market
Nutritional Supplements
Meal Replacement Products OEM Market
Nutritional Supplements
Calcium Malate Market
Nutritional Supplements
Nutraceutical Supplements Market
Nutritional Supplements
Japan Whey Protein Market
Nutritional Supplements
South Africa Collagen Peptides Market
Nutritional Supplements
Tryptophan Market
Nutritional Supplements
Australia Whey Protein Market
Nutritional Supplements
Bee Pollen Supplements Market
Nutritional Supplements
Fiber Supplements Market
Nutritional Supplements
Hair Growth Supplements Market
Nutritional Supplements
Raspberry Ketones Market
Nutritional Supplements
Whey Protein Market