
 Ready-To-Use Therapeutic Food Market | 2026-2036
Ready-To-Use Therapeutic Food Market Size, Share, and Industry Trends Forecast 2026-2036
Ready-To-Use Therapeutic Food Market Analysis
Humanitarian supply chains is reconfiguring procurement patterns for ready-to-use therapeutic food. Nutriset SAS leverages its patented PlumpyNut formulation to anchor European production capacity. Edesia Inc. sustains dedicated manufacturing lines for UNICEF and USAID orders from its Rhode Island facility. Hilina Enriched Foods PLC competes on regional sourcing from its Ethiopian operations, reducing lead times for East African distribution.
Ready-to-use therapeutic food comprises lipid-based nutrient supplements or fortified pastes engineered to deliver precise caloric density per unit mass, typically formulated with peanut paste, milk powder, vegetable oil, sugar, and micronutrient premixes to treat severe acute malnutrition without requiring water or cooking. High-Calorie Bars dominate institutional procurement due to portion control and shelf stability under tropical storage conditions. Nutrient-Dense Powders represent the fastest-growing format as programs expand into moderate acute malnutrition protocols and community-based management. Ready-to-Drink Shakes concentrate margin pools where premium positioning targets adult therapeutic nutrition and elder care segments.
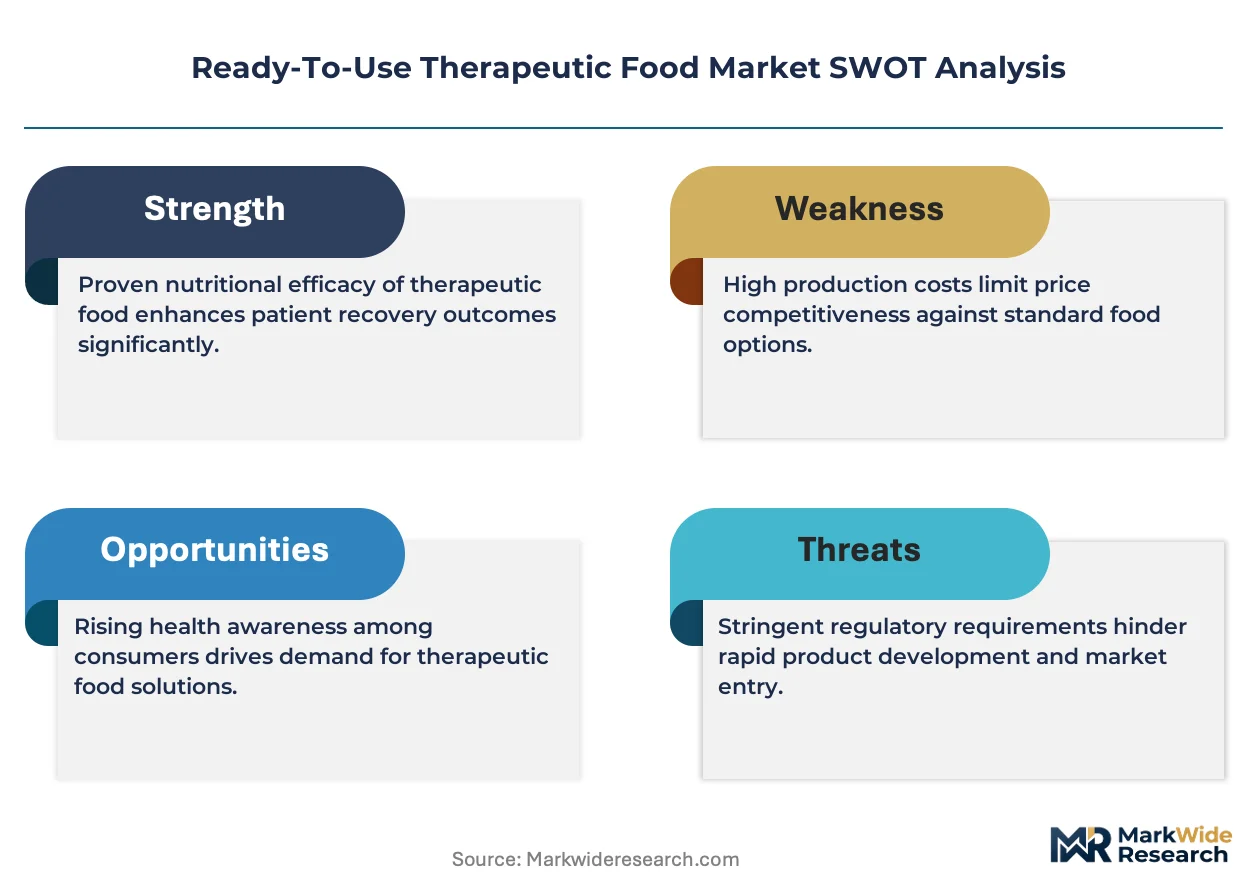
WHO guidelines on ready-to-use therapeutic food composition and Codex Alimentarius standards on food for special medical purposes shape product specifications and prequalification requirements for international tenders. FDA regulations govern U.S. import pathways and donor-funded procurement compliance, while EFSA frameworks influence European manufacturing quality systems and export certification. Stakeholders must monitor evolving procurement consolidation among multilateral agencies and the shift toward localized production mandates in high-burden countries.
Market Dynamics
UNICEF consolidated tendering is compressing supplier margins while mandating localized production footprints, forcing manufacturers to reconfigure supply chains around in-country processing requirements rather than centralized export hubs.
Growth Catalysts
- WHO acute malnutrition treatment protocols:Expanded guidelines now cover moderate acute malnutrition, doubling addressable patient populations and institutional procurement volumes across sub-Saharan African health systems.
- Ethiopia's industrial park incentives:Tax holidays and duty-free import regimes for peanut and milk powder inputs are attracting ready-to-use therapeutic food manufacturers to Addis Ababa and Hawassa production zones.
- Community-based management of acute malnutrition (CMAM):Decentralized distribution networks reduce clinic congestion and extend treatment reach into rural catchment areas previously excluded from facility-based protocols.
Market Restraints
- Peanut paste price volatility:West African groundnut harvest fluctuations and aflatoxin testing rejections create input cost instability that manufacturers cannot fully pass through in fixed-price humanitarian contracts.
- French production concentration:Nutriset's patent-protected formulations and Normandy manufacturing dominance create supply vulnerability if geopolitical or logistics disruptions affect European export capacity.
- FDA import compliance friction:Foreign Supplier Verification Program requirements and facility registration delays extend lead times for non-U.S. manufacturers seeking USAID-funded procurement eligibility.
Strategic Opportunities
- India moderate acute malnutrition protocols:FSSAI regulatory harmonization with Codex standards positions domestic manufacturers to supply India's National Nutrition Mission expansion beyond current pilot districts.
- Ready-to-use supplementary food (RUSF) line extensions:Fortified lipid-based nutrient supplements for pregnant and lactating women represent adjacent therapeutic nutrition segments with similar manufacturing infrastructure.
- Direct-to-government contracting:Bypassing multilateral procurement intermediaries allows manufacturers to negotiate longer-term offtake agreements with national health ministries in Nigeria, Kenya, and Yemen.
Industry Challenges
- ISO 22000 certification timelines:Food safety management system audits and HACCP implementation for new production facilities typically require 18-24 months, delaying market entry for emerging suppliers.
- PlumpyNut formulation licensing complexity:Patent thickets and know-how agreements constrain independent product development, forcing prospective entrants into royalty-bearing arrangements or riskier formulation workarounds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ready-To-Use Therapeutic Food Market |
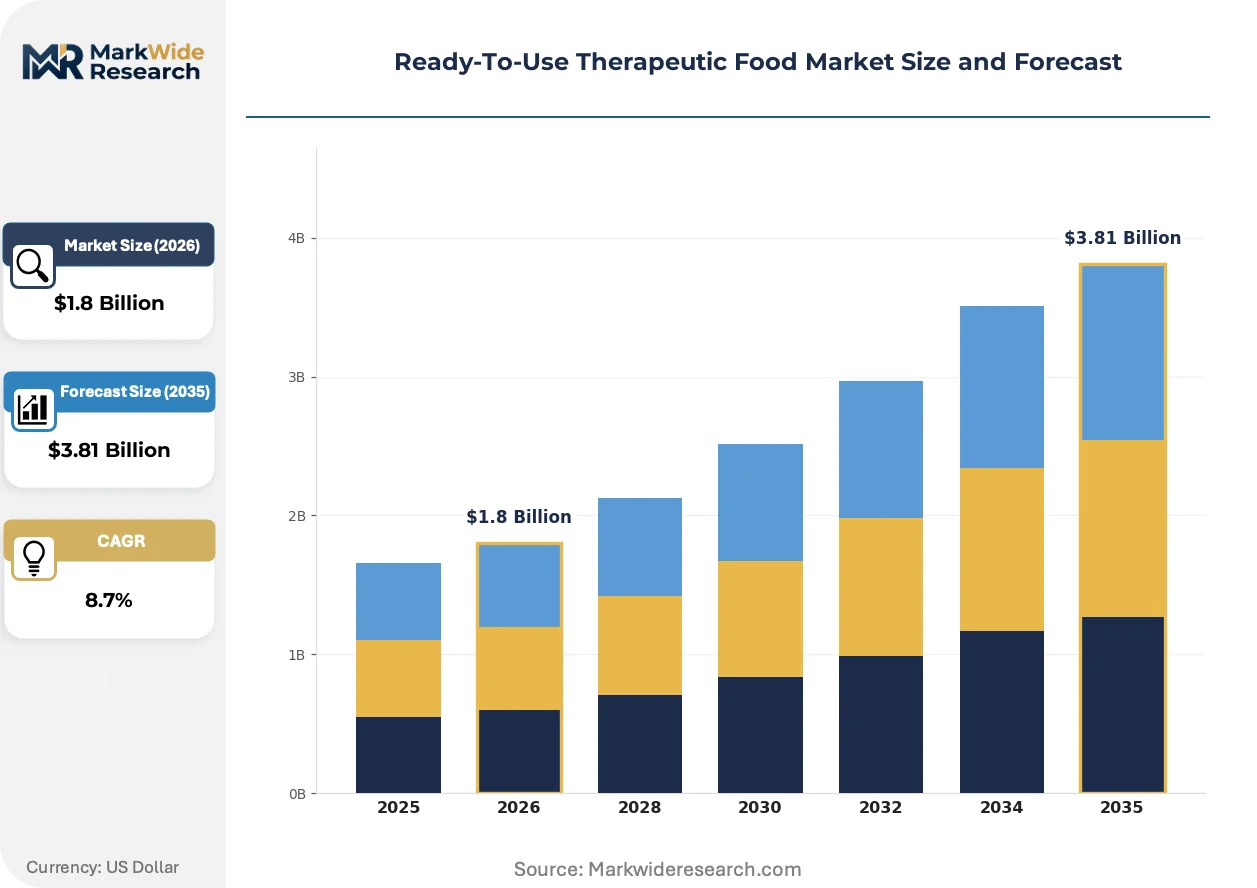
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Calorie Bars, Nutrient-Dense Powders, Ready-to-Drink Shakes, Packaged Meals Target Demographic: Children with Malnutrition, Adults with Chronic Illness, Elderly Population, Active Individuals Distribution Channel: Pharmacies, Online Retail, Supermarkets, Health Food Stores Packaging Type: Flexible Pouches, Tetra Packs, Cans, Rigid Containers |
| Companies Covered | Nutriset SAS, Edesia Inc., Hilina Enriched Foods PLC, GC Rieber Compact AS, Insta Products Ltd., Tabatchnick Fine Foods Inc., Diva Nutritional Products, Société de Transformation Alimentaire, Valid Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ready-To-Use Therapeutic Food Market Emerging Trajectories
Therapeutic food manufacturing is pivoting from standardized peanut-based pastes toward diversified nutrient delivery systems and localized sourcing models that reduce import dependency in high-burden markets.
Sorghum and chickpea base formulations are collapsing the peanut-dominant ingredient paradigm that has defined ready-to-use therapeutic food since PlumpyNut's introduction. UNICEF prequalification pilots for non-peanut recipes are accelerating adoption by procurement officers facing school allergy protocols and religious dietary restrictions. This ingredient diversification is collapsing single-source supply risk and opening formulation licensing to new market entrants previously blocked by patent concentration.
EFSA novel food ingredient approvals for insect protein and algal oil micronutrient carriers are creating regulatory pathways for next-generation lipid-based nutrient supplements. Manufacturers submitting dossiers for house cricket and yellow mealworm protein isolates anticipate 2025-2026 market authorizations that would reduce dairy dependency in therapeutic food formulations. European production facilities are retrofitting allergen-segregated lines in anticipation of these approvals, while African manufacturers monitor EFSA determinations for potential Codex harmonization.
Humanitarian buyers are consolidating annual tenders into multi-year framework agreements with price adjustment clauses indexed to commodity futures. This contractual evolution compresses supplier switching and rewards manufacturers with demonstrated scale and quality consistency. Ethiopian and Kenyan health ministries are piloting these arrangements for national procurement, reducing transaction costs and enabling production planning horizons previously impossible under annual bidding cycles.
Ready-To-Use Therapeutic Food Market Segmentation
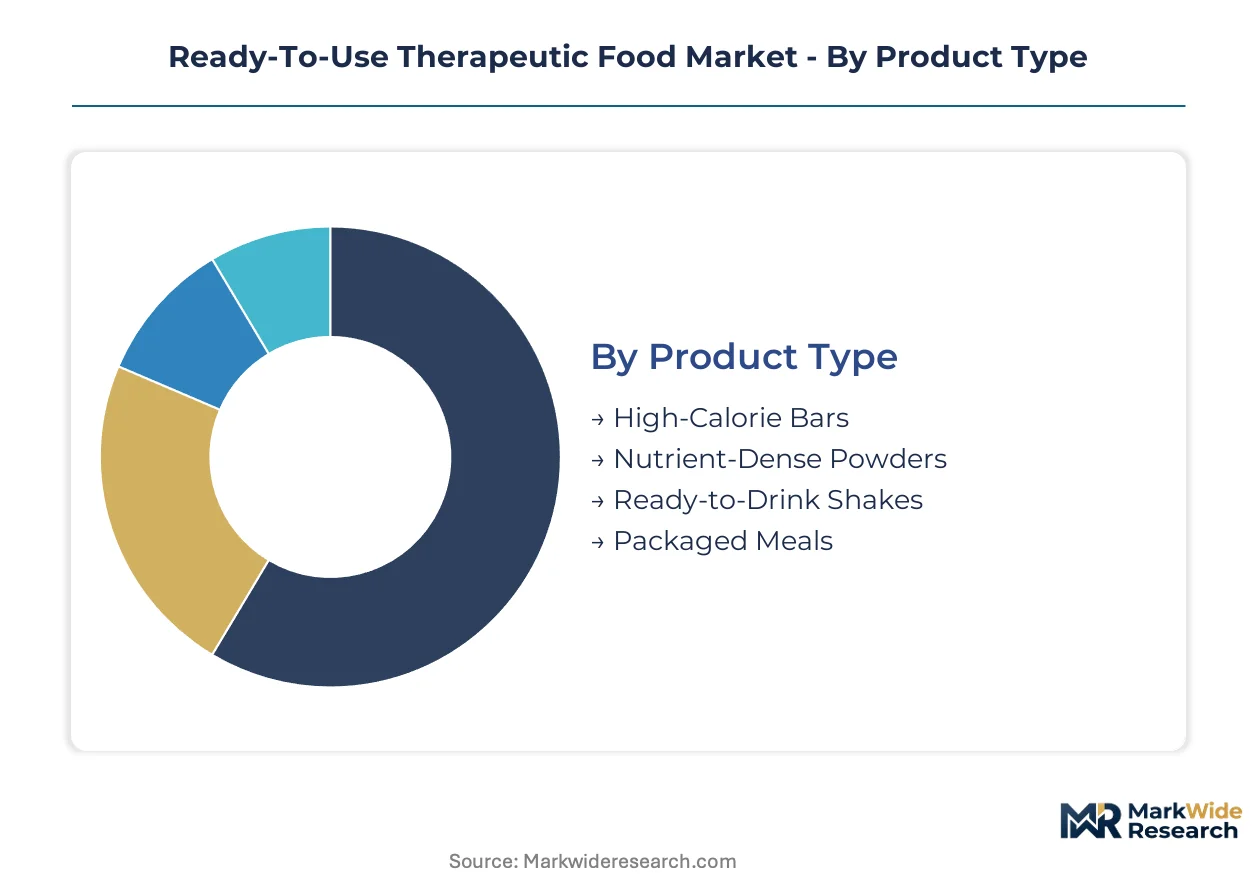
Segmentation in ready-to-use therapeutic food reveals how formulation, delivery format, and procurement channel determine margin structures and regulatory pathways. Manufacturers configure production lines around specific segment requirements rather than pursuing universal product platforms.
Product Type:
Mature formats dominate institutional procurement while emerging delivery systems capture adjacent therapeutic nutrition applications.
- High-Calorie Bars:Lipid-based nutrient supplements formulated as portion-controlled pastes deliver precise caloric density per unit mass, typically combining peanut paste, milk powder, vegetable oil, and micronutrient premixes. UNICEF and World Food Programme tenders concentrate demand in sub-Saharan Africa, where tropical storage conditions favor shelf-stable formats over temperature-sensitive alternatives.
- Nutrient-Dense Powders:Fortified dry blends require reconstitution with clean water but offer lower shipping costs and extended shelf life. Community-based management of acute malnutrition programs in Ethiopia and Kenya are expanding procurement volumes as protocols extend into moderate acute malnutrition treatment and rural distribution networks.
- Ready-to-Drink Shakes:Pre-mixed liquid formulations target adult therapeutic nutrition and elder care segments with premium positioning outside humanitarian procurement channels.
- Packaged Meals:Complete ready-to-eat therapeutic food solutions incorporating multiple macronutrient sources for specialized dietary protocols.
High-Calorie Bars handle the majority of throughput; Nutrient-Dense Powders are gaining share fastest as treatment protocols broaden.
Target Demographic:
Application intensity varies sharply across patient populations, with pediatric protocols anchoring volume and adult segments offering margin expansion.
- Children with Malnutrition:Severe acute malnutrition treatment protocols under WHO guidelines specify exact caloric and micronutrient requirements per kilogram of body weight. Sub-Saharan African health systems drive institutional procurement through CMAM programs and facility-based therapeutic feeding centers.
- Adults with Chronic Illness:HIV/AIDS and tuberculosis co-morbidity treatment creates demand for therapeutic food as adjuvant nutrition support. Procurement concentrates in PEPFAR-funded programs and national health ministries in Nigeria and Yemen negotiating direct-to-government contracts.
- Elderly Population:Sarcopenia and dysphagia-related malnutrition in aged care facilities generates demand for texture-modified therapeutic nutrition in European and North American markets.
- Active Individuals:Sports nutrition and high-metabolic-demand applications represent commercial positioning outside core therapeutic indications.
Children with Malnutrition commands the dominant procurement volume; Adults with Chronic Illness shows the steepest expansion trajectory as HIV/TB integration protocols mature.
Distribution Channel:
Channel configuration reflects the split between institutional procurement systems and retail-accessible therapeutic nutrition.
- Pharmacies:Primary channel for prescription-linked therapeutic food in regulated markets, with FDA and EFSA food-for-special-medical-purposes classifications determining reimbursement eligibility and shelf placement.
- Online Retail:Direct-to-consumer platforms expand access for non-prescription therapeutic nutrition and specialized dietary products, particularly in North American and European markets with established e-commerce infrastructure.
- Supermarkets:Mass-market retail placement for fortified foods positioned at the boundary between therapeutic and general nutrition categories.
- Health Food Stores:Specialty retail channel for premium-positioned therapeutic nutrition targeting wellness-oriented consumers and specific dietary protocols.
Pharmacies process the bulk of regulated therapeutic food volume; Online Retail is expanding most quickly as direct-to-consumer models penetrate chronic disease management.
Packaging Type:
Material selection balances shelf stability requirements against cost constraints and environmental disposal considerations in low-infrastructure settings.
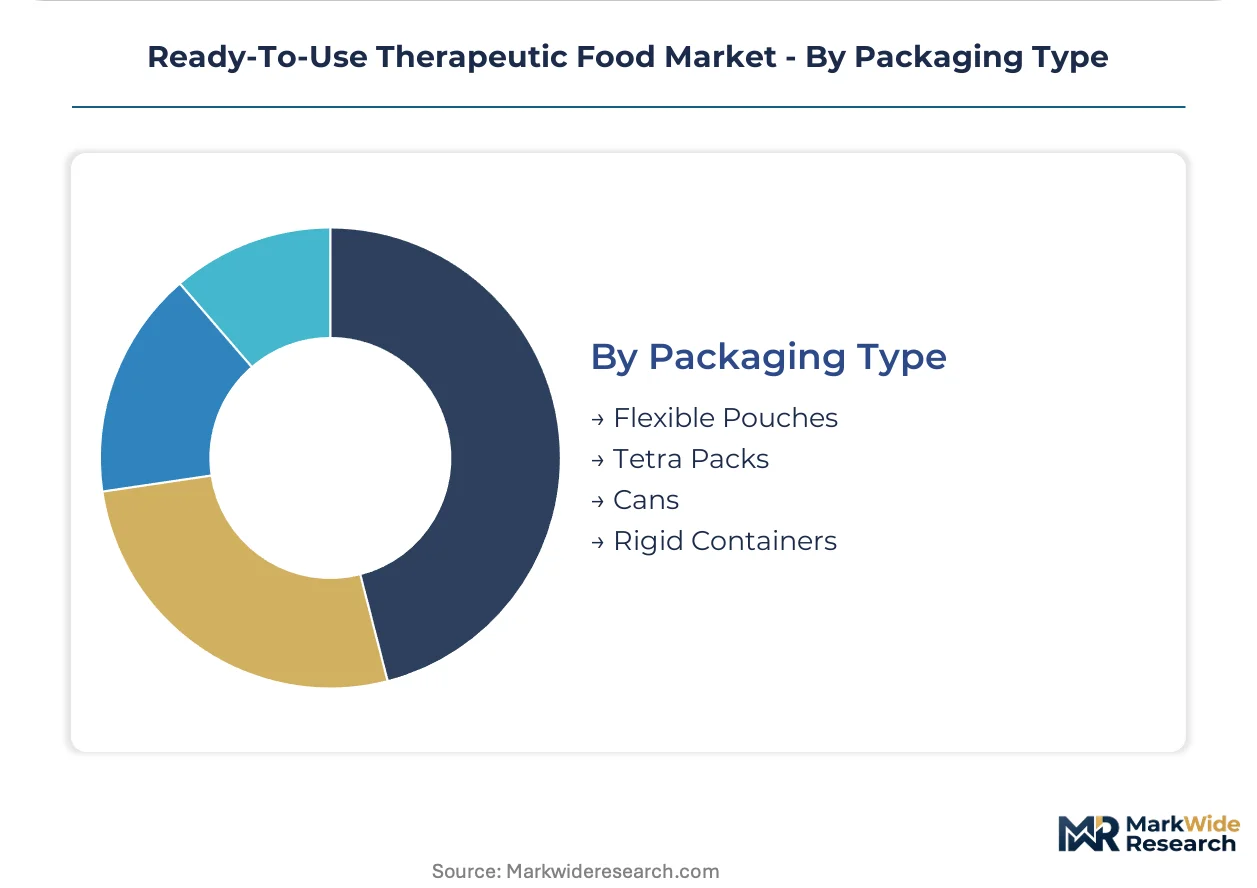
- Flexible Pouches:Multi-layer laminated films provide moisture and oxygen barriers essential for lipid-based nutrient supplement shelf stability. UNICEF prequalification specifications favor this format for field distribution in humanitarian contexts due to light weight and reduced shipping cube.
- Tetra Packs:Aseptic carton systems enable liquid therapeutic food distribution without refrigeration, supporting extended supply chains in regions with unreliable cold chain infrastructure.
- Cans:Metal packaging offers maximum shelf stability and physical protection for ready-to-eat therapeutic meals in long-duration stockpiling scenarios.
- Rigid Containers:Plastic or composite containers support resealable multi-serve formats for institutional feeding programs and household-level distribution.
Flexible Pouches carry the dominant share of humanitarian procurement; Tetra Packs are climbing the fastest as liquid format adoption expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethiopia's industrial park incentives are redirecting manufacturing investment toward East African production clusters. National nutrition programs across high-burden countries are mandating localized procurement footprints that reshape traditional import-dependent supply chains.
Ethiopia
Community-based management of acute malnutrition programs drive institutional procurement volumes through decentralized rural distribution networks. The Ethiopian Industrial Parks Development Corporation offers ten-year tax holidays and duty-free import regimes for peanut and milk powder inputs to ready-to-use therapeutic food manufacturers. Addis Ababa and Hawassa production zones host Hilina Enriched Foods PLC operations that supply UNICEF tenders with reduced lead times for regional distribution.
United States
PEPFAR-funded HIV/AIDS and tuberculosis co-morbidity programs generate demand for therapeutic food as adjuvant nutrition support in adult patient populations. FDA Foreign Supplier Verification Program requirements and facility registration delays extend lead times for non-U.S. manufacturers seeking USAID-funded procurement eligibility. Rhode Island hosts dedicated manufacturing lines configured for UNICEF and USAID order fulfillment from established humanitarian suppliers.
France
Patent-protected PlumpyNut formulation anchors European production capacity for international humanitarian procurement. EFSA frameworks influence manufacturing quality systems and export certification pathways for food-for-special-medical-purposes classifications. Normandy manufacturing clusters concentrate formulation expertise and prequalified supply capacity for multilateral agency tenders.
India
FSSAI regulatory harmonization with Codex standards positions domestic manufacturers to supply National Nutrition Mission expansion beyond current pilot districts. Moderate acute malnutrition protocol adoption doubles addressable patient populations for institutional procurement volumes. Domestic production facilities leverage local dairy and oilseed supply chains to reduce import dependency for therapeutic food manufacturing inputs.
Nigeria
Severe acute malnutrition treatment protocols through national health systems drive direct-to-government contracting opportunities bypassing multilateral procurement intermediaries. Federal Ministry of Health negotiations seek longer-term offtake agreements with manufacturers for predictable supply security. Northern Nigerian states with highest malnutrition burden concentrate demand for localized distribution infrastructure investment.
Ready-To-Use Therapeutic Food Market Vendor Landscape
On the supply side, the industry is consolidating around manufacturers with demonstrated UNICEF prequalification status and established humanitarian procurement relationships. Patent-protected formulations and multi-year framework agreements create barriers for emerging entrants lacking scale or quality certification history. Three archetypes dominate: European formulation patent-holders, North American humanitarian-dedicated producers, and African regional sourcing specialists. Competitive moves center on geographic licensing arrangements and in-country processing facility establishment to satisfy localized production mandates.
Among established European players, Nutriset SAS exemplifies the formulation patent-holder archetype through its PlumpyNut intellectual property position. Edesia Inc. occupies a position among North American humanitarian-dedicated producers with facility configurations optimized for UNICEF and USAID tender fulfillment. Hilina Enriched Foods PLC represents the African regional sourcing specialist model, leveraging proximity to East African distribution networks and reduced logistics lead times for institutional procurement.
| Leading Market Players |
|---|
| Nutriset SAS |
| Edesia Inc. |
| Hilina Enriched Foods PLC |
| GC Rieber Compact AS |
| Insta Products Ltd. |
| Tabatchnick Fine Foods Inc. |
| Diva Nutritional Products |
| Société de Transformation Alimentaire |
| Valid Nutrition |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Ethiopian processing zones is tightening supplier leverage and compressing margins for European exporters while elevating pricing power for regional African manufacturers with localized UNICEF prequalification status.
Pricing Analysis
Volume-discount tiering structures dominate humanitarian procurement, with framework agreements indexing adjustments to peanut paste and milk powder futures. Price differentiation hinges on ISO 22000 certification grade and geographic proximity to distribution hubs. Cost compression in economy-tier formulations is intensifying because UNICEF consolidated tendering mandates fixed-price multi-year commitments. National health ministries in Nigeria and Kenya demonstrate highest price sensitivity, while PEPFAR-funded programs in the United States exhibit lowest sensitivity due to dedicated budget lines.
Supply Chain Analysis
Tariff exposure between France and sub-Saharan African destination markets dominates supply chain risk calculations for PlumpyNut-dependent procurement. Manufacturing concentrates in France, Ethiopia, and the United States. Formulations draw from peanut paste, milk powder, and micronutrient premix inputs. Single-source vulnerability around Nutriset's patent-protected recipes constrains supplier switching. Distribution runs through UNICEF and World Food Programme consolidated tendering channels with direct-to-government contracting emerging as an alternative pathway.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as WHO protocol expansion into moderate acute malnutrition treatment doubles addressable patient populations and restocks institutional procurement pipelines.
For Market Incumbents: Build regulatory moats through accelerated FSSAI and Codex harmonization filings in India ahead of National Nutrition Mission expansion. Patent-protected formulation holders should anchor capacity addition in Ethiopian industrial parks to satisfy localized production mandates. Certification investment in ISO 22000 and HACCP systems for African facilities counters emerging entrant threats from regional sourcing specialists.
For New Entrants and Emerging Players: Moderate acute malnutrition protocols in Indian pilot districts represent the most penetrable entry point for domestic manufacturers with FSSAI-aligned quality systems. Sorghum and chickpea base formulations for UNICEF prequalification pilots bypass PlumpyNut patent thickets. Direct-to-government contracting with Nigerian Federal Ministry of Health offers a go-to-market angle outside consolidated multilateral tendering.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among African regional sourcing specialists with established UNICEF prequalification and in-country processing footprints. Long-term viability over a five-to-ten-year window favors manufacturers with diversified base formulations beyond peanut dependency. Acquisition targets should demonstrate EFSA novel food ingredient dossier progress for insect protein or algal oil carriers. Watch EFSA determination timelines for house cricket and yellow mealworm authorizations as the critical inflection signal for next-generation therapeutic nutrition platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Localized Production Facility Establishment | Ethiopian industrial park incentives reduce lead times for East African UNICEF distribution networks. |
| Non-Peanut Formulation Development | Sorghum and chickpea recipes unlock UNICEF prequalification pilots for allergy-restricted procurement contexts. |
| Multi-Year Framework Agreement Negotiation | Humanitarian buyers consolidate annual tenders into indexed contracts rewarding scale and quality consistency. |
| Novel Food Ingredient Dossier Submission | EFSA approvals for insect protein carriers reduce dairy dependency in next-generation therapeutic formulations. |
| Direct-to-Government Contracting Bypass | Nigerian and Kenyan health ministries seek longer-term offtake agreements outside multilateral procurement intermediaries. |
Methodological Framework
The analysis maps lipid-based nutrient supplements, fortified dry blends, and ready-to-drink therapeutic formats, each validated through procurement officers at UNICEF and World Food Programme, manufacturing executives at European and African production facilities, regulatory affairs leads navigating FDA and EFSA compliance pathways, and national health ministry planners in Ethiopia, Nigeria, and India. Secondary sources include WHO guideline documentation, Codex Alimentarius standards, FSSAI regulatory filings, and humanitarian procurement tender databases. Bottom-up capacity assessments and top-down demand modeling from malnutrition burden statistics provide triangulation.
Assumptions held fixed include WHO protocol adoption timelines and Codex micronutrient composition standards, while variables included commodity input price trajectories and regulatory harmonization progress across jurisdictions. Segmentation dimensions modeled encompass product format, target demographic, distribution channel, and packaging type alongside regional procurement policy evolution. CAGRs were derived from patient population projections, protocol penetration rates, and institutional procurement volume forecasts. Industry-specific inputs included aflatoxin testing rejection rates for West African groundnut harvests and EFSA novel food authorization timelines.
Practitioners should monitor peanut paste price volatility, patent licensing dispute resolutions, and localized production mandate enforcement for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
North America Dietary Supplements Market
Nutritional Supplements
Australia Whey Protein Market
Nutritional Supplements
Fitness Cookies Market
Nutritional Supplements
Multi Nutritional Supplement Market
Nutritional Supplements
Red Ginseng Market
Nutritional Supplements
Nutraceutical Supplements Market
Nutritional Supplements
Functional Carbohydrates Market
Nutritional Supplements
Spirulina Extract Market
Nutritional Supplements
Hydrolyzed Whey Protein Market
Nutritional Supplements
USA Prenatal Vitamin Supplements Market
Nutritional Supplements
Organic Protein Powder Market
Nutritional Supplements
Vitamin K2 Market
Nutritional Supplements
Europe Omega 3 Market
Nutritional Supplements
Fish Protein Isolate Market
Nutritional Supplements
Natural Colostrum Supplements Market
Nutritional Supplements
Food Grade Beta-Alanine Market