
 North America Vegan Supplements Market | 2026-2036
North America Vegan Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
North America Vegan Supplements Market Analytics
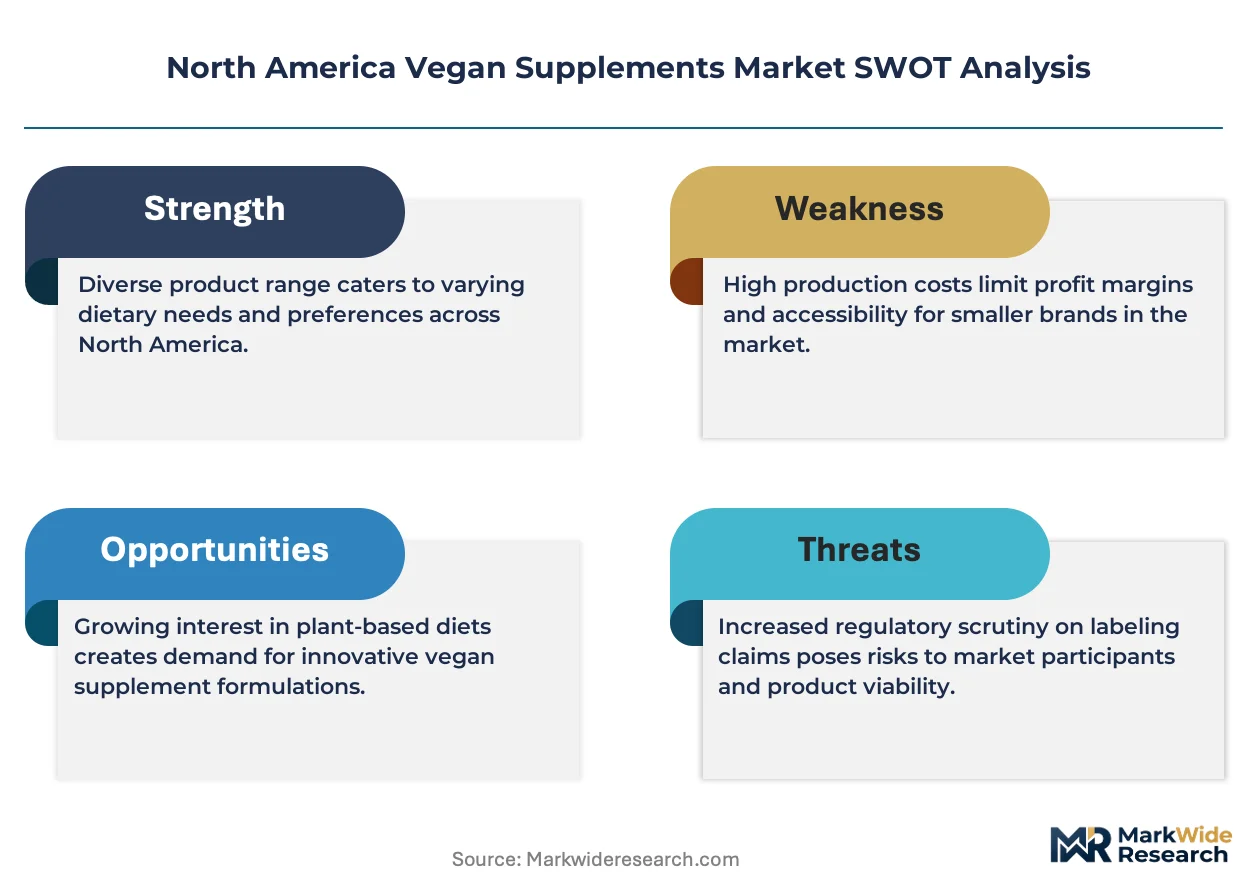
FDA's updated New Dietary Ingredient notification guidelines is shifting the cost-of-entry calculus for novel plant-derived formulations. Garden of Life leverages its in-house fermentation capabilities to sustain supply chain autonomy. NOW Health Group, Inc. competes through pharmacist-trusted distribution across independent health stores. Orgain anchors its position with ready-to-drink protein formats that dominate club-channel velocity.
Vegan supplements comprise plant-derived nutritional products formulated without animal ingredients, typically utilizing pea protein isolates, algal omega-3 oils, and lichen-sourced vitamin D3 to deliver bioavailable micronutrients. Manufacturers employ cold-pressing and spray-drying to preserve thermolabile compounds during production. Protein powders occupy the largest revenue pool given their penetration into mainstream fitness routines. Gummies represent the fastest-expanding formulation as palatability improvements capture hesitant first-time buyers. Online retail channels concentrate margin pools through subscription models that reduce customer acquisition costs.
FDA cGMP enforcement and USDA Organic certification requirements shape product standards and facility auditing protocols across domestic manufacturing. Health Canada's Natural and Non-prescription Health Products Directorate influences cross-border formulation decisions for brands operating in both jurisdictions. Stakeholders must monitor evolving state-level clean-label legislation and third-party testing mandates that will determine which formulations retain shelf access.
Market Dynamics
Precision fermentation capabilities are compressing production timelines for algal omega-3 and vitamin D3 precursors, forcing incumbent manufacturers to reconfigure sourcing strategies or face margin erosion from bio-identical alternatives.
Growth Catalysts
- USDA Organic certification expansion:Retailers in California and the Pacific Northwest now mandate third-party organic verification for shelf placement, accelerating facility upgrades across domestic manufacturing bases.
- Collegiate athletic programs:NCAA Division I nutrition departments are standardizing plant-based protein protocols for recovery regimens, creating institutional procurement pipelines.
- Pea protein isolate processing:Wet-fractionation advances at Canadian Prairie processing hubs are lowering input costs for North American formulators.
Market Restraints
- Algal oil supply concentration:DHA and EPA precursor production clusters in coastal fermentation facilities, exposing brands to weather-related disruption cascades.
- FDA cGMP audit frequency:Elevated inspection tempo for novel dietary ingredients is extending time-to-market for innovative plant extracts.
- Soy protein substitution threat:Established animal-welfare certifications for conventional dairy retain price-competitive positioning in mass-market channels.
Strategic Opportunities
- Canadian Prairie provinces:Underdeveloped retail penetration in Manitoba and Saskatchewan offers first-mover advantages for direct-to-consumer subscription models.
- Sports nutrition crossover:Endurance cycling and trail-running communities present untapped demand for electrolyte-enhanced vegan hydration formats.
- Health Canada NNHPD harmonization:Streamlined cross-border ingredient approvals enable unified North American product portfolios.
Industry Challenges
- Fermentation microbiology talent scarcity:Commercial-scale algal cultivation requires specialized bioprocess engineers, constraining capacity expansion timelines.
- NSF Certified for Sport compliance:Athletic-market entry demands rigorous banned-substance testing protocols that extend certification cycles.
- Legacy ERP integration:Cold-chain traceability requirements for thermolabile compounds clash with outdated inventory management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Vegan Supplements Market |
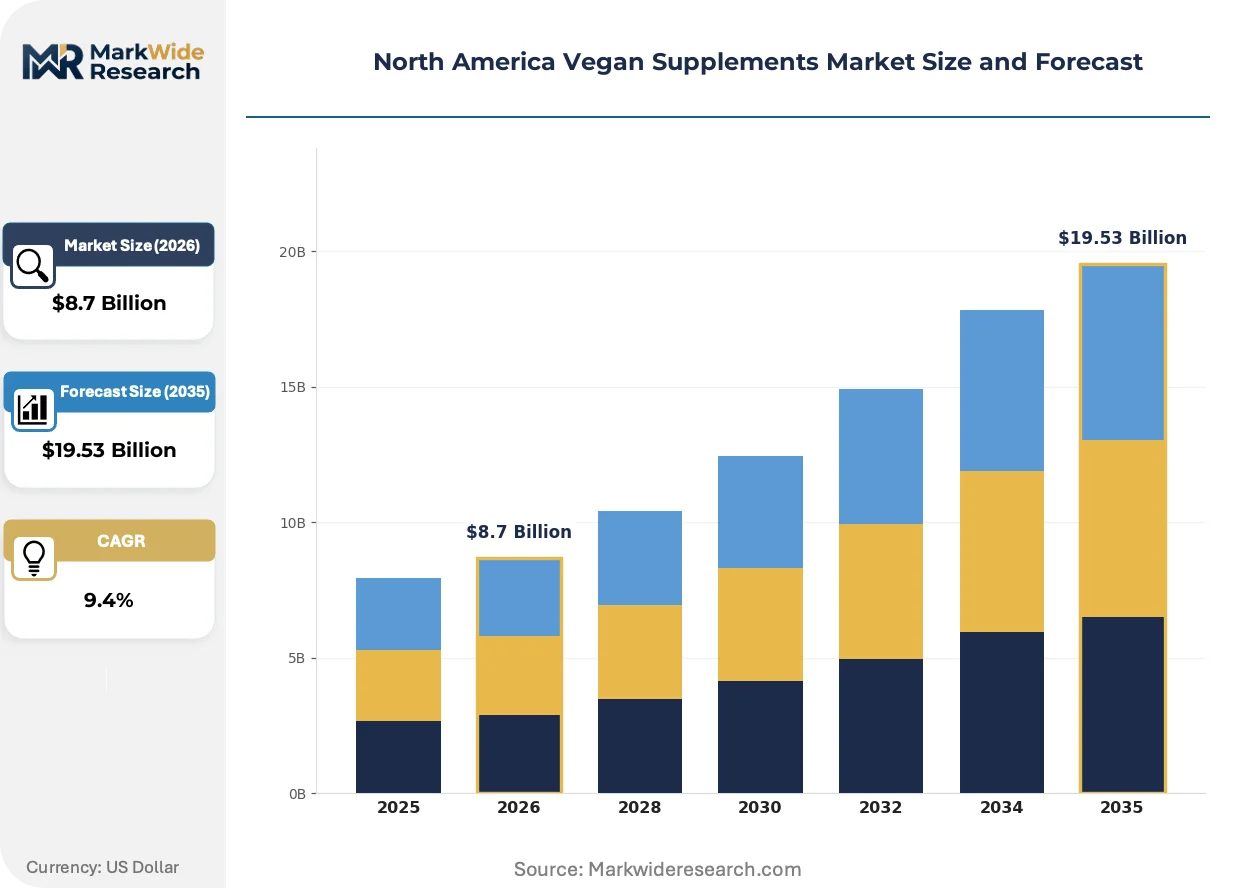
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proteins, Vitamins, Minerals, Omega Fatty Acids Formulation: Pills, Powders, Gummies, Liquids Target Audience: Athletes, Health-Conscious Consumers, Vegetarians, Seniors Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | Nestlé S.A., NOW Health Group, Inc., Country Life, LLC, Ora Organic, Future Kind, Garden of Life, Orgain, Vega, PlantFusion, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Vegan Supplements Market Evolving Landscape
Bioprocess engineering advances are collapsing the cost curve for traditionally expensive plant-derived actives, while regulatory clarity around fermentation-derived ingredients is unlocking formulation flexibility previously reserved for synthetic alternatives.
Precision fermentation of algal omega-3 fatty acids is rewriting the economics of EPA and DHA supplementation. Sports nutrition brands serving collegiate and professional athletes are adopting these bio-identical lipids at accelerated procurement cycles. The technology is compressing the premium pricing umbrella that historically protected fish-oil-derived competitors.
FDA's evolving New Dietary Ingredient notification guidelines are tightening evidentiary standards for novel plant extracts. Manufacturers must now submit comprehensive safety pharmacology data before commercialization, extending development timelines. Brands targeting the California metropolitan corridor are responding by front-loading toxicology investments to secure preemptive market access.
Subscription-based replenishment models are displacing traditional retail replenishment cycles among fitness-adjacent consumers. Club-channel velocity leaders are unbundling bulk purchasing from in-store discovery, shifting margin capture toward direct relationships. This pattern concentrates most visibly in the Pacific Northwest, where urban density supports same-day delivery infrastructure.
North America Vegan Supplements Market Segmentation
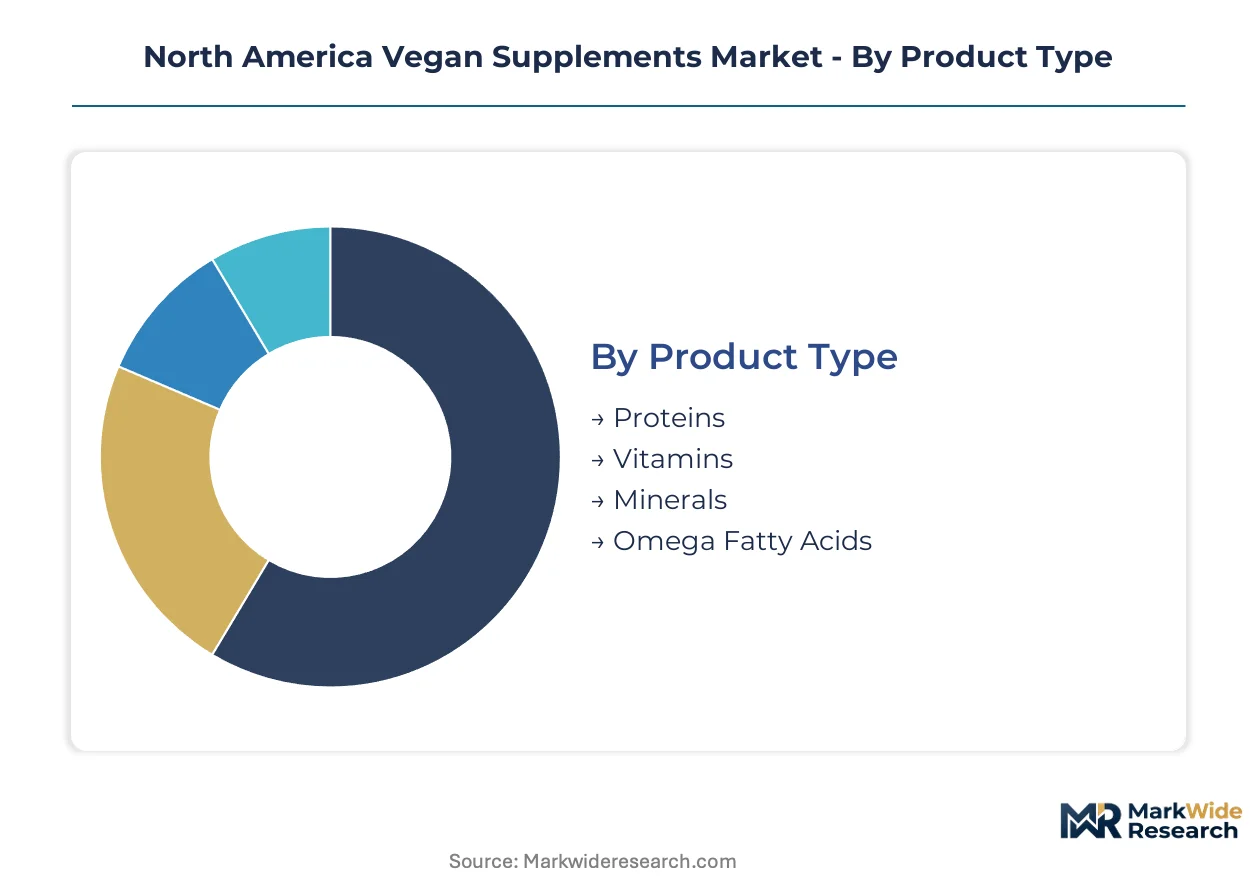
Segmentation in the North America Vegan Supplements Market reveals how regulatory requirements and consumer preferences fragment commercial opportunity. Each dimension carries distinct certification burdens, channel economics, and geographic concentration patterns that determine profitability.
Product Type:
FDA cGMP enforcement intensity varies sharply across product categories, with novel botanical extracts facing elevated New Dietary Ingredient notification requirements while established protein isolates navigate streamlined compliance pathways.
- Proteins:Pea protein isolates and rice protein concentrates dominate formulation portfolios. Wet-fractionation advances at Canadian Prairie processing hubs are compressing input costs for North American manufacturers. Demand concentrates in California metropolitan corridors where collegiate athletic programs drive institutional procurement.
- Vitamins:Lichen-sourced vitamin D3 and fermented B12 complexes require thermolabile handling protocols. USDA Organic certification mandates from Pacific Northwest retailers are accelerating facility audit investments. Precision fermentation capabilities are collapsing production timelines for traditionally expensive actives.
- Minerals:Chelated zinc and algae-derived calcium demand third-party heavy metals testing. Health Canada NNHPD dossier requirements extend cross-border commercialization timelines.
- Omega Fatty Acids:Algal DHA and EPA precursors face supply concentration risks in coastal fermentation facilities. Weather-related disruption cascades expose brands to inventory volatility.
Leading the category by volume: Proteins. Growing fastest: Omega Fatty Acids.
Formulation:
Manufacturing complexity and margin structure diverge significantly across delivery formats, with cold-chain requirements and stability testing protocols determining which SKUs justify facility investment.
- Powders:Spray-dried protein isolates and micronutrient premixes occupy the largest revenue pool given mainstream fitness penetration. Shelf-stable formats minimize distribution complexity across club-channel and direct-to-consumer routes.
- Gummies:Pectin-based matrices with thermolabile vitamin encapsulation are gaining share fastest among hesitant first-time buyers. Palatability improvements are displacing traditional pill formats in Pacific Northwest urban markets.
- Pills:Compressed tablets and hard-shell capsules retain pharmacist trust in independent health stores. NOW Health Group, Inc. competes through this channel with professional-grade positioning.
- Liquids:Liposomal delivery systems and ready-to-drink formats demand refrigerated logistics. Orgain anchors club-channel velocity with this format despite margin compression.
Dominating shelf space: Powders. Climbing the fastest: Gummies.
Target Audience:
Customer lifetime value and acquisition cost profiles vary dramatically, with institutional procurement pipelines offering predictable volume versus direct-to-consumer subscriptions capturing superior margins.
- Athletes:Collegiate and professional programs require NSF Certified for Sport compliance and banned-substance testing protocols. NCAA Division I nutrition departments are standardizing plant-based recovery regimens.
- Health-Conscious Consumers:Subscription-based replenishment models concentrate in the Pacific Northwest where urban density supports same-day delivery infrastructure. Margin capture shifts toward direct relationships.
- Vegetarians:Ethical positioning drives premium pricing tolerance for third-party verified formulations. California metropolitan corridors show highest per-capita penetration.
- Seniors:Bioavailability-focused marketing emphasizes fermented and chelated nutrient forms. Pharmacist consultation dependency sustains independent health store relevance.
Highest volume concentration: Athletes. Steepest expansion trajectory: Health-Conscious Consumers.
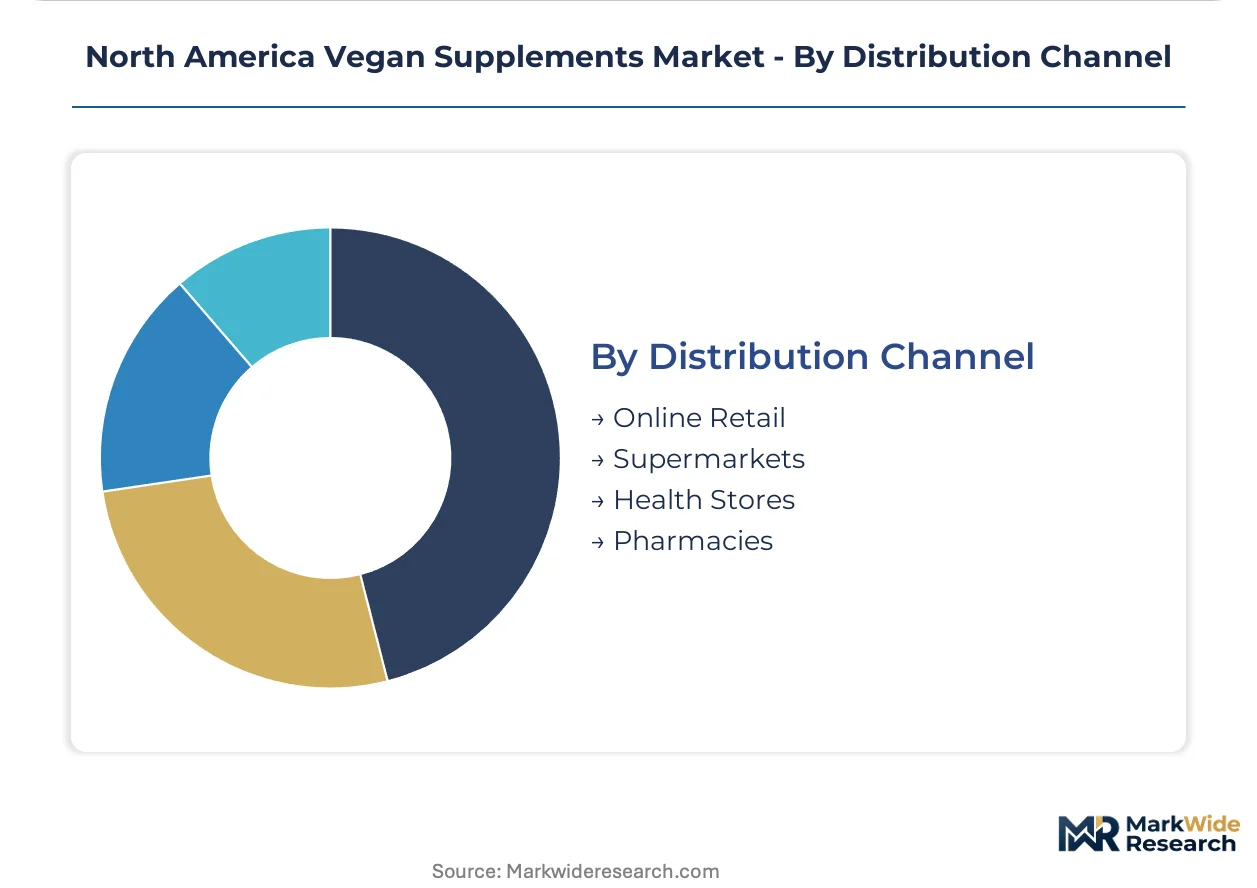
Distribution Channel:
Channel selection determines regulatory exposure, with online retail concentrating margin pools through subscription models while brick-and-mortar mandates third-party certification for shelf placement.
- Online Retail:Direct-to-consumer subscriptions reduce customer acquisition costs and enable personalized regimen bundling. Garden of Life leverages in-house fermentation capabilities to sustain supply chain autonomy for this channel.
- Health Stores:Independent retailers demand third-party organic verification and cGMP documentation. Pharmacist-trusted distribution requires professional education investments.
- Supermarkets:Mass-market placement competes on price with conventional dairy alternatives. Club-channel velocity leaders unbundle bulk purchasing from in-store discovery.
- Pharmacies:White-label and practitioner-exclusive lines require Health Canada NNHPD harmonization for cross-border portfolios. Regulatory clarity unlocks formulation flexibility.
Margin concentration: Online Retail. Fastest channel expansion: Health Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Opportunity Zones and Canadian Prairie provincial tax credits for agricultural processing have concentrated fermentation capacity and pea protein fractionation investments in these corridors.
United States
Collegiate athletic procurement pipelines and Pacific Northwest subscription density drive volume concentration. FDA cGMP enforcement and evolving New Dietary Ingredient notification guidelines shape facility investment decisions. California metropolitan corridors host the densest cluster of precision fermentation operations serving algal omega-3 production.
Canada
Wet-fractionation advances at Prairie processing hubs lower input costs for North American formulators. Health Canada's Natural and Non-prescription Health Products Directorate influences cross-border formulation standardization. Manitoba and Saskatchewan present underdeveloped retail penetration opportunities for direct-to-consumer subscription models.
Mexico
Cross-border manufacturing partnerships leverage USMCA provisions for duty-free botanical extract processing. COFEPRIS regulatory alignment initiatives with FDA standards streamline ingredient approval pathways. Baja California and Mexico City metro areas concentrate contract manufacturing capacity serving US brand owners.
North America Vegan Supplements Market Competitive Landscape
US producers anchor the premium tier with fermentation capabilities and third-party certification infrastructure; Canadian specialists hold supply-side positioning through Prairie protein processing. The market structures around three strategic archetypes: vertically integrated fermentation operators, pharmacist-trusted distribution players, and club-channel velocity leaders. Competitive moves concentrate on capacity expansion in Canadian Prairie processing hubs and strategic partnerships for cross-border Health Canada harmonization.
Among US-based operators, Garden of Life, Orgain, and NOW Health Group, Inc. exemplify distinct competitive positioning. Garden of Life occupies the in-house fermentation tier with supply chain autonomy capabilities. Orgain anchors club-channel velocity through ready-to-drink format dominance. NOW Health Group, Inc. sits within the pharmacist-trusted distribution archetype across independent health store networks.
| Leading Market Players |
|---|
| Nestlé S.A. |
| NOW Health Group, Inc. |
| Country Life, LLC |
| Ora Organic |
| Future Kind |
| Garden of Life |
| Orgain |
| Vega |
| PlantFusion |
| Others |
Value Network & Pricing Analysis
Precision fermentation scale-up is collapsing production timelines for algal omega-3 and vitamin D3 precursors while simultaneously redrawing supply concentration maps toward coastal bioprocessing clusters. This dual transformation compresses cost curves for bio-identical actives and intensifies margin pressure on legacy extraction-dependent suppliers across the North American vegan supplements landscape.
Pricing Analysis
Short-lead-time premiums now command substantial markups for NSF Certified for Sport formulations serving collegiate athletic procurement cycles, while spot inventory of conventional pea protein isolates trades at discounted clearing rates. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and organic verification status. Cost compression in mass-market protein powders is intensifying because wet-fractionation advances at Canadian Prairie processing hubs are expanding supply availability. Institutional buyers within NCAA Division I nutrition departments demonstrate lowest price sensitivity due to performance-guarantee requirements, whereas hesitant first-time buyers in Pacific Northwest urban markets exhibit highest elasticity to palatability-driven gummy premiums.
Supply Chain Analysis
Dual-sourcing requirements now mandate multi-supplier qualification for algal DHA and EPA precursors after weather-related disruption cascades exposed single-source vulnerabilities in coastal fermentation facilities. Supply concentration clusters in the United States, Canada, and Mexico with cross-border manufacturing partnerships leveraging USMCA provisions for duty-free botanical extract processing. Raw material dependencies center on pea protein isolates, lichen-sourced vitamin D3, and algae-derived calcium with third-party heavy metals testing protocols. Tariff exposure on imported organic certification inputs represents the dominant structural risk. Distribution runs through direct-to-consumer subscription models that reduce customer acquisition costs alongside club-channel velocity for ready-to-drink formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Vegan Supplements Market is becoming a vertical-integration race as players pursue captive supply of precision fermentation capacity to secure margin control over algal omega-3 and vitamin D3 actives.
For Market Incumbents: Extend fermentation microbiology talent acquisition programs to constrain competitor capacity expansion timelines while accelerating in-house bioprocess engineering capabilities. Secure long-term offtake agreements with Canadian Prairie pea protein fractionators before wet-fractionation advances fully commoditize input costs. Garden of Life's supply chain autonomy model demonstrates how backward integration into algal cultivation insulates against coastal weather disruption cascades. For New Entrants and Emerging Players: Capture underdeveloped direct-to-consumer subscription penetration in Manitoba and Saskatchewan where urban density still supports same-day delivery infrastructure buildout. Target endurance cycling and trail-running communities with electrolyte-enhanced vegan hydration formats that incumbent protein-heavy portfolios underserve. Lead with Health Canada NNHPD harmonization positioning to unlock unified North American product portfolios without dual dossier investments. For Investors and Strategic Acquirers: Exit pathways concentrate in vertically integrated fermentation operators with demonstrated commercial-scale algal cultivation capabilities and existing USDA Organic certification infrastructure. Long-term viability over the coming decade hinges on securing bioprocess engineering talent pipelines and cold-chain traceability systems that legacy ERP platforms cannot support. Watch NSF Certified for Sport compliance velocity as the inflection indicator—brands achieving accelerated certification cycles will capture institutional procurement pipelines before competitors clear audit backlogs.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Captive algal omega-3 production collapses reliance on coastal weather-exposed suppliers. |
| Canadian Prairie Processing Hub Investment | Wet-fractionation proximity secures lowest-cost pea protein isolate feedstock access. |
| NSF Certified for Sport Acceleration | Expedited banned-substance testing unlocks NCAA Division I institutional procurement pipelines. |
| Health Canada NNHPD Harmonization | Streamlined cross-border approvals enable unified product portfolios without dual regulatory investments. |
| Direct-to-Consumer Subscription Infrastructure | Same-day delivery density in Pacific Northwest urban corridors concentrates margin capture away from retail. |
Research Methodology
Independent corroboration across primary interviews with fermentation bioprocess engineers, NCAA Division I nutrition directors, independent health store pharmacists, and club-channel category buyers underwrites the qualitative findings. Secondary validation draws from FDA cGMP inspection databases, Health Canada NNHPD submission records, USDA Organic certification registries, and provincial agricultural processing tax credit disclosures. Bottom-up SKU-level demand modeling triangulates against top-down category expenditure estimates from regional retail audit data.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. Segmentation dimensions include product type, formulation format, target audience archetype, and distribution channel with geographic regulatory cluster overlays. CAGRs derive from fitted growth curves incorporating precision fermentation cost-collapse trajectories, collegiate athletic procurement standardization timelines, and subscription-model penetration saturation patterns. Industry-specific forecast inputs capture wet-fractionation capacity buildout schedules and evolving New Dietary Ingredient notification backlogs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA cGMP enforcement tempo shifts, algal cultivation weather disruption frequency, and Health Canada NNHPD harmonization progress. Deviation in precision fermentation commercialization timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Direct Fed Microbials Market
Nutritional Supplements
Whey Protein Concentrate Market
Nutritional Supplements
Pulse Protein Market
Nutritional Supplements
Algae Omega 3 Market
Nutritional Supplements
Fish Oil Supplements Market
Nutritional Supplements
South America Collagen Supplements Market
Nutritional Supplements
Asia Pacific Nutritional Supplements Market
Nutritional Supplements
Middle East Protein Market
Nutritional Supplements
Japan Whey Protein Market
Nutritional Supplements
Pet Dietary Supplements Market
Nutritional Supplements
Selenium Yeast Market
Nutritional Supplements
Vitamin B12 Market
Nutritional Supplements
Canada Nutraceuticals Market
Nutritional Supplements
DHA Oil Supplement Market
Nutritional Supplements
US and Canada Beta Glucan Market
Nutritional Supplements
Global Nutraceutical Market