
 Nutraceutical Oral Thin Films Market | 2026-2036
Nutraceutical Oral Thin Films Market Size, Share, and Industry Trends Forecast 2026-2036
Nutraceutical Oral Thin Films Market Analytics
Multi-source API procurement is broadening across the nutraceutical oral thin films supply base as manufacturers reduce concentration risk. Cure Pharmaceutical leverages captive polymer formulation capabilities to control strip dissolution profiles. LTS Lohmann Therapie-Systeme AG anchors European production capacity with validated transdermal and oral film lines. Aquestive Therapeutics Inc. specializes in PharmFilm technology platforms that extend beyond pharmaceuticals into wellness applications.
Nutraceutical oral thin films are single-layer or multi-layer polymeric matrices, typically 50-150 microns thick, that disintegrate on the tongue or buccal mucosa within seconds to minutes to deliver active ingredients without water. These strips employ hydrophilic polymers such as pullulan, hydroxypropyl methylcellulose, or polyvinyl alcohol as film-forming agents, with plasticizers and active compounds distributed uniformly via solvent casting or hot-melt extrusion. Vitamins and herbal extracts dominate current volume, while probiotics represent the fastest-growing product type due to formulation stability challenges that command premium pricing. Sublingual delivery mode captures the highest bioavailability-driven margin pools, whereas buccal films compete on convenience in mass-market channels.
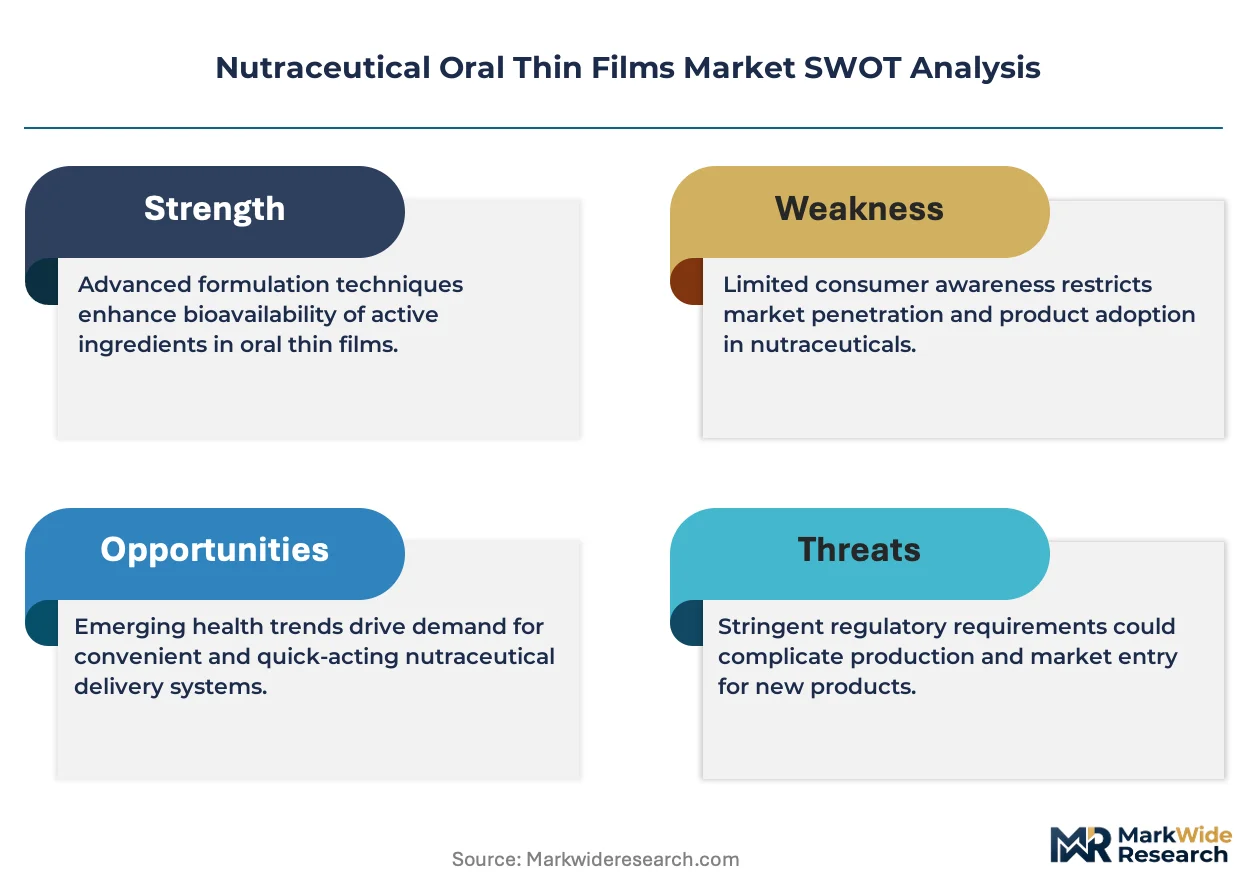
FDA cGMP regulations for dietary supplements and EFSA novel food evaluations shape product development timelines and market access pathways in North America and Europe. India's FSSAI and CDSCO impose parallel requirements on contract manufacturers serving export markets, raising compliance costs for smaller participants. Stakeholders must monitor evolving pharmacopeial monographs for dissolution testing and polymer purity standards that will determine which formulations qualify for pharmacy shelf placement versus relegation to unregulated online channels.
Market Dynamics
Polymer formulation chemistry and dissolution profile engineering now determine competitive positioning in nutraceutical oral thin films, as pharmacy buyers demand validated batch-to-batch performance that separates qualified suppliers from commodity strip producers.
Growth Catalysts
- Pediatric formulation demand:Parents actively seek alternatives to conventional pills and syrups for children, expanding the addressable patient population for vitamin and probiotic strips.
- FDA cGMP dietary supplement enforcement:Tightening quality benchmarks for current good manufacturing practice elevate compliant manufacturers above unregulated online competitors.
- Sublingual bioavailability advantage:First-pass metabolism avoidance drives premium positioning for rapid-dissolve strips in wellness and clinical nutrition segments.
Market Restraints
- API stability limitations:Heat-sensitive probiotics and certain herbal extracts degrade during solvent casting or hot-melt extrusion, constraining active ingredient selection.
- Pullulan supply concentration:Film-forming polymer production clusters in East Asian fermentation facilities, exposing formulators to input cost volatility and logistics disruption.
- EFSA novel food assessment timelines:European market entry for innovative botanical actives faces 12-18 month safety evaluation periods that delay revenue recognition.
Strategic Opportunities
- Pharmacy channel expansion in Germany:Apotheken distribution networks remain underpenetrated for wellness-oriented strips relative to pharmaceutical oral films.
- Probiotic strain stabilization breakthroughs:Microencapsulation advances combined with moisture-barrier packaging unlock shelf-stable live culture delivery formats.
- Buccal convenience positioning:Mass-market retailers in Japan favor slower-dissolve buccal films for on-the-go consumption without water requirements.
Industry Challenges
- Dissolution testing standardization:Pharmacopeial method harmonization across USP, EP, and JP monographs remains incomplete, complicating multi-territory registration strategies.
- Polymer purity certification delays:Supplier qualification for pharmaceutical-grade pullulan and HPMC requires extended analytical validation timelines that stretch working capital cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nutraceutical Oral Thin Films Market |
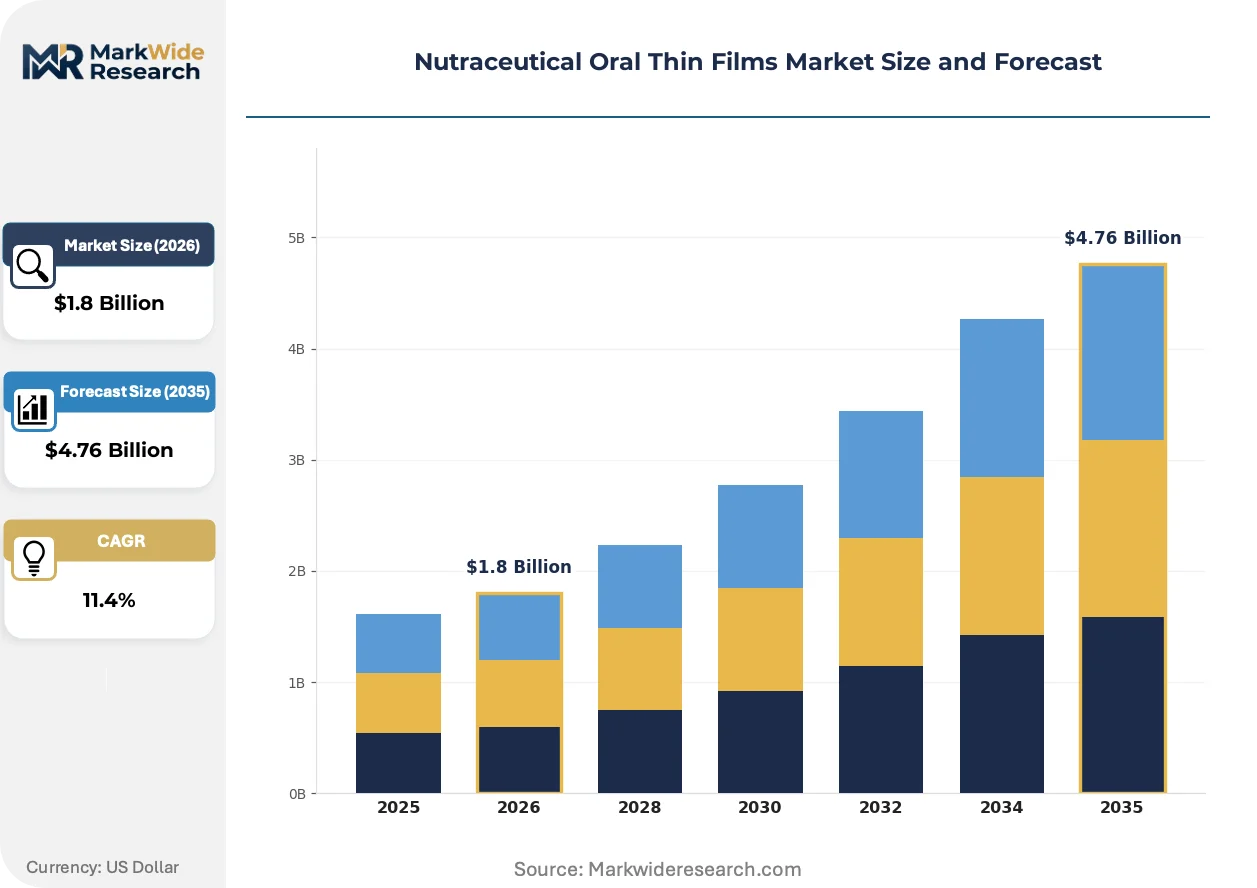
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Herbal Extracts, Probiotics Delivery Mode: Buccal, Sublingual, Orally Disintegrating, Chewable End User: Adults, Seniors, Pediatric, Athletes Distribution Channel: Pharmacies, Online Retail, Supermarkets, Health Stores |
| Companies Covered | Cure Pharmaceutical, LTS Lohmann Therapie-Systeme AG, Aquestive Therapeutics Inc., Corium Innovations Inc., C.L. Pharm, ZIM Laboratories Limited, Viatris Inc., Nova Thin Film Pharmaceuticals LLC, IntelGenx Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nutraceutical Oral Thin Films Market Evolving Landscape
Hot-melt extrusion is overtaking solvent casting as the dominant manufacturing platform, driven by sustainability mandates and residual solvent concerns that reshape equipment investment priorities across contract manufacturing networks.
Extrusion technology eliminates organic solvent handling and recovery infrastructure, reducing environmental compliance burdens and facility capital requirements. European toll manufacturers and North American specialty producers are retrofitting casting lines or installing twin-screw systems at replacement cycle points. This shift is overtaking incumbent solvent-dependent capacity in high-wage jurisdictions where volatile organic compound emissions face tightening scrutiny.
REACH registration requirements for polymer additives and plasticizers are forcing reformulation of legacy strip compositions ahead of 2026 registration deadlines. Manufacturers serving EU distribution channels must document substance volumes and hazard profiles for film-forming agents previously treated as non-reactive processing aids. Smaller nutraceutical brands lacking regulatory affairs capacity are outsourcing compliance to full-service contract development organizations with established ECHA submission track records.
Direct-to-consumer subscription models are compressing traditional pharmacy and mass retail distribution for personalized vitamin strip portfolios. Wellness startups in the United States bypass wholesale intermediaries to capture recurring revenue and consumption data, while established players defend shelf placement through exclusivity arrangements with drugstore chains. Japan's aging demographic drives comparable channel experimentation for senior-focused mineral supplementation delivered through postal pharmacy networks.
Nutraceutical Oral Thin Films Market Segmentation
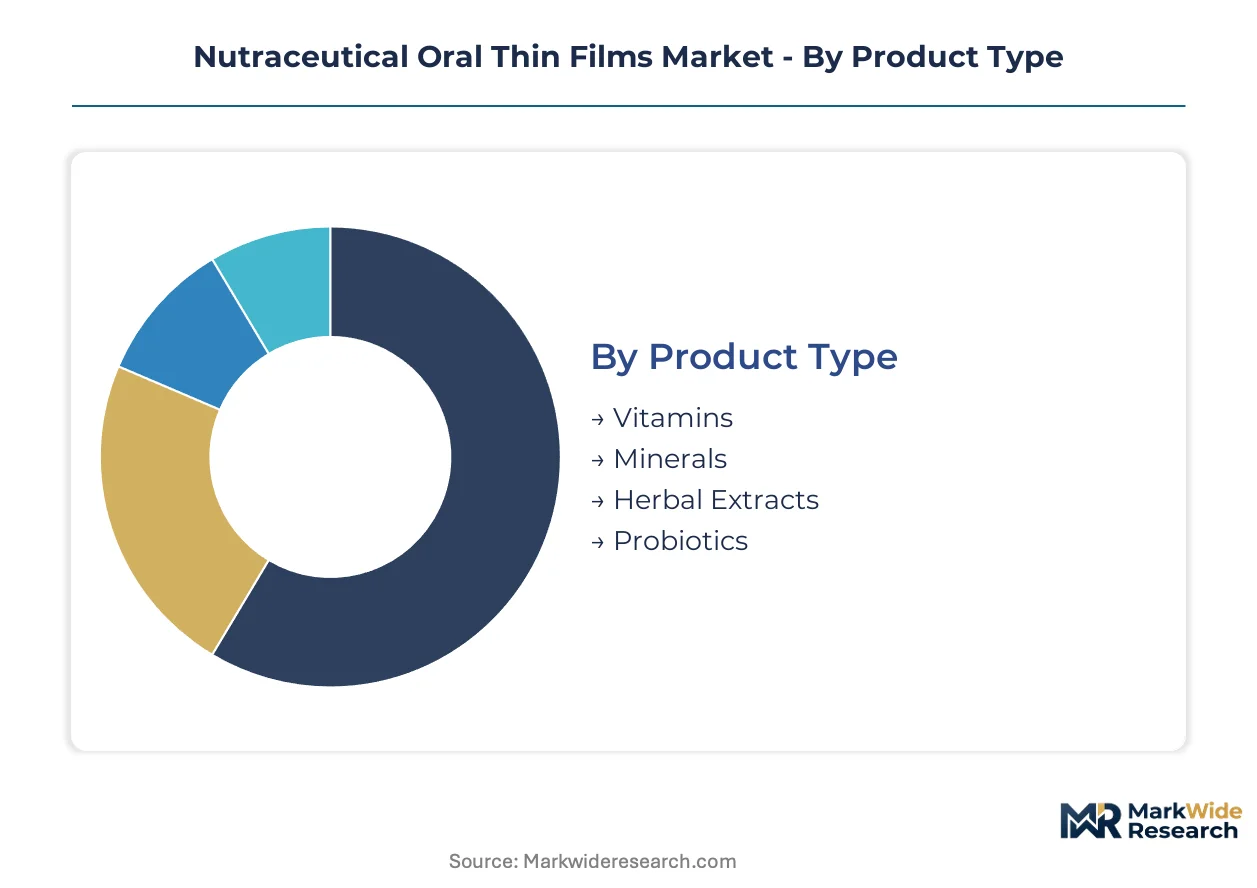
Segmentation in nutraceutical oral thin films reveals how formulation technology, consumer physiology, and channel economics create distinct margin pools. Buyers prioritize dissolution speed, bioavailability claims, and regulatory compliance differently across these dimensions.
Product Type:
Purchase criteria vary sharply by whether buyers seek daily wellness maintenance or targeted therapeutic outcomes.
- Vitamins:Water-soluble B-complex and fat-soluble D3 strips dominate current production volumes, with pullulan matrices stabilizing photosensitive actives against oxidation. Demand concentrates in United States pharmacy chains where insurance-adjacent wellness programs drive subscription adherence. FDA cGMP certification separates pharmacy-grade suppliers from unregulated direct-to-consumer competitors.
- Probiotics:Live culture delivery demands moisture-barrier packaging and microencapsulation advances to survive hot-melt extrusion temperatures. Japan's aging population and Germany's pharmacy networks show strongest uptake for shelf-stable Lactobacillus and Bifidobacterium strains. Premium pricing reflects formulation stability challenges that constrain supplier qualification.
- Minerals:Ionic magnesium and zinc citrate strips address bioavailability limitations of traditional tablet forms.
- Herbal Extracts:Standardized polyphenol and alkaloid delivery from ashwagandha and ginseng sources faces EFSA novel food assessment timelines.
Vitamins lead volumes today; probiotics is gaining share fastest.
Delivery Mode:
Speed of mucosal absorption and first-pass metabolism avoidance determine price tier placement across these formats.
- Sublingual:Rapid venous uptake through the floor of the mouth delivers peak plasma concentrations within minutes, commanding premium positioning in clinical nutrition and wellness segments. United States specialty pharmacy channels favor sublingual strips for CoQ10 and melatonin where bioavailability claims support reimbursement discussions.
- Buccal:Slower dissolution against the cheek mucosa extends release profiles for 15-30 minute consumption windows without water. Japanese mass-market retailers and German Apotheken networks favor buccal convenience for on-the-go mineral supplementation.
- Orally Disintegrating:Tongue-disintegrating matrices compete on swallowing ease for geriatric and dysphagia populations.
- Chewable:Gelatin-based chewable films target pediatric palatability with flavor-masked actives.
Sublingual formats capture the highest margin pools; buccal films show steepest expansion trajectory in mass-market channels.
End User:
Physiological differences in saliva production, mucosal permeability, and swallowing function shape formulation requirements.
- Pediatric:Flavor engineering and rapid disintegration address pill-aversion and dosing accuracy concerns for children aged 2-12. United States parents actively seek alternatives to syrups with preservative concerns, expanding pharmacy demand for vitamin D and probiotic strips with child-safe packaging.
- Seniors:Reduced saliva flow and dysphagia prevalence drive demand for moisture-independent delivery among adults over 65. Japan's postal pharmacy networks and Germany's long-term care facilities show concentrated uptake for B12 and magnesium formulations.
- Adults:Working-age consumers prioritize convenience and discretion in workplace consumption settings.
- Athletes:Electrolyte and amino acid strips target pre-workout and recovery use cases with rapid absorption claims.
Adult segments dominate current revenue; pediatric applications are expanding most quickly as parental preferences shift.
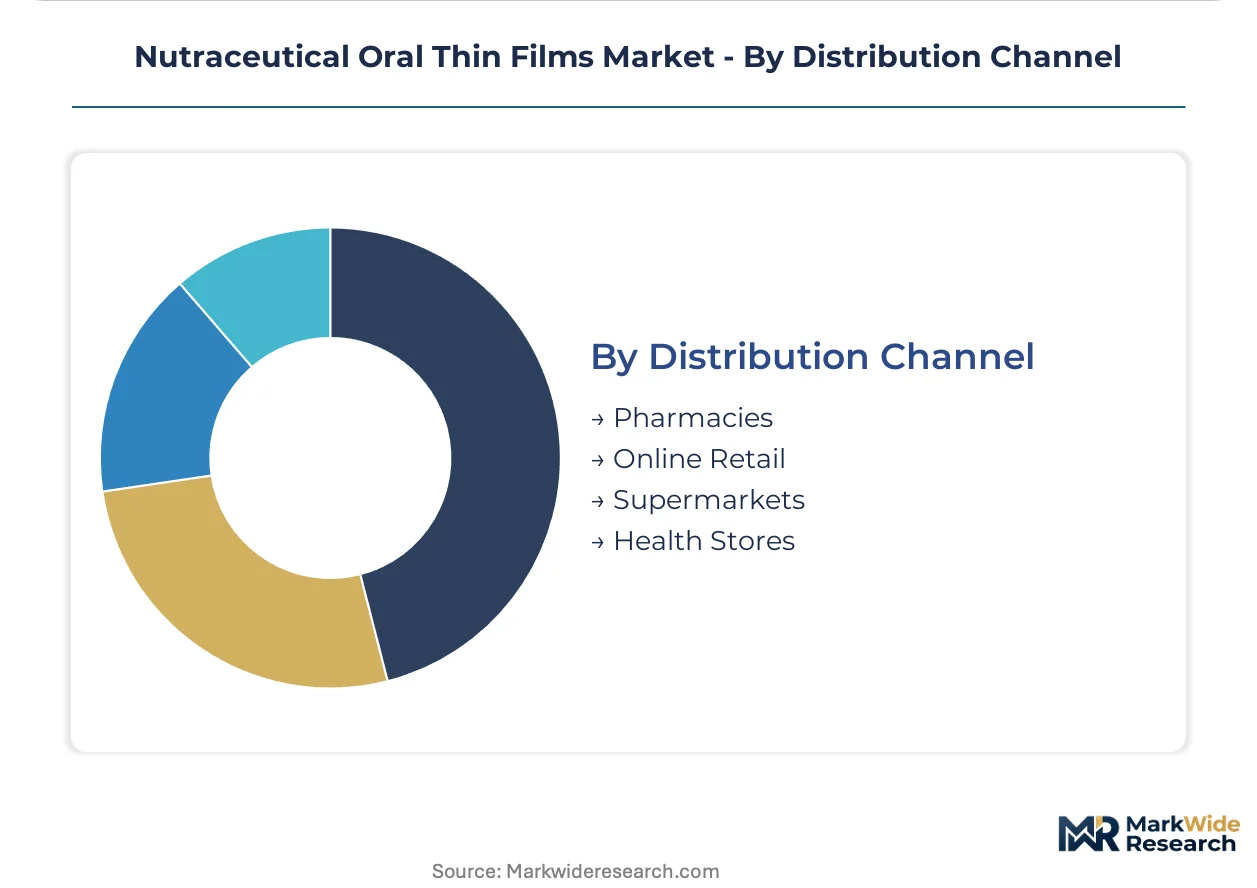
Distribution Channel:
Channel selection determines regulatory scrutiny depth, margin structure, and brand positioning latitude.
- Pharmacies:Brick-and-mortar Apotheken in Germany and drugstore chains in the United States demand validated dissolution profiles and polymer purity certifications. Pharmacy placement requires compliance with USP monographs and EMA pharmacopeial standards that commodity strip producers cannot satisfy.
- Online Retail:Direct-to-consumer subscription models bypass wholesale intermediaries to capture recurring revenue and consumption data. Wellness startups in the United States leverage this channel for personalized vitamin portfolios, though FDA cGMP enforcement is tightening quality benchmarks for online-only brands.
- Supermarkets:Mass-market shelf placement competes on unit economics and impulse purchase visibility.
- Health Stores:Specialty retailers emphasize organic certification and clean-label positioning for premium herbal extracts.
Pharmacies anchor value capture today; online retail is climbing the fastest as subscription models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production capacity toward jurisdictions where polymer formulation expertise and quality certification costs align favorably. Manufacturers balance FDA cGMP compliance burdens against EFSA novel food assessment timelines when siting oral thin film operations.
United States
Pediatric vitamin strips and sublingual wellness formats drive pharmacy channel expansion as parents reject pill-based dosing for children. FDA cGMP dietary supplement enforcement tightens quality benchmarks for contract manufacturers serving drugstore chains. California-based polymer formulators and New Jersey toll manufacturers anchor domestic capacity for rapid-dissolve strip production.
Germany
Apotheken distribution networks underpenetrate wellness-oriented strips relative to pharmaceutical oral films, creating whitespace for compliant entrants. EFSA novel food assessments govern botanical active approvals, stretching European market access timelines for herbal extract formats. North Rhine-Westphalia hosts validated transdermal and oral film production lines serving EU pharmacy channels.
Japan
Aging demographics and postal pharmacy networks concentrate demand for senior-focused mineral and B12 buccal strips. METI standards and PMDA consultations shape polymer purity requirements for moisture-independent delivery formats. Osaka-area contract manufacturers specialize in slower-dissolve films targeting on-the-go consumption without water requirements.
India
FSSAI and CDSCO compliance requirements raise export qualification barriers for contract manufacturers serving regulated markets. Domestic demand for affordable vitamin strips expands through pharmacy and general trade channels. Hyderabad and Mumbai clusters house solvent casting and hot-melt extrusion capacity for regional supply and contract export production.
Nutraceutical Oral Thin Films Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent wellness and clinical nutrition applications where bioavailability claims command premium positioning. The vendor base stratifies across validated pharmacy-grade suppliers and commodity strip producers lacking dissolution profile documentation. Three archetypes dominate: polymer formulators with captive excipient capabilities, toll manufacturers with validated multi-format lines, and technology licensors extending pharmaceutical platforms into nutraceuticals. Capacity expansion and strategic partnerships represent the dominant competitive moves as participants secure polymer supply and pharmacy channel placement.
Among North American technology specialists, Aquestive Therapeutics Inc. occupies a position exemplifying platform extension from pharmaceuticals into wellness applications. European production capacity anchors around LTS Lohmann Therapie-Systeme AG, representing validated transdermal and oral film manufacturing at scale. Cure Pharmaceutical sits within the polymer formulation archetype, illustrating captive control over strip dissolution engineering.
| Leading Market Players |
|---|
| Cure Pharmaceutical |
| LTS Lohmann Therapie-Systeme AG |
| Aquestive Therapeutics Inc. |
| Corium Innovations Inc. |
| C.L. Pharm |
| ZIM Laboratories Limited |
| Viatris Inc. |
| Nova Thin Film Pharmaceuticals LLC |
| IntelGenx Corp. |
| Others |
Value Network & Pricing Analysis
Pullulan price volatility cascades through nutraceutical oral thin film manufacturing, compressing margins for solvent-casting operators while rewarding hot-melt extrusion adopters with polymer input cost stability. This raw-material benchmark differential splits the market into pharmacy-grade certified tiers commanding premium positioning versus commodity strip producers exposed to spot-market polymer sourcing.
Pricing Analysis
Input-cost pass-through from East Asian fermentation facilities drives a three-tier pricing structure across premium, standard, and economy levels. Pharmacy-grade strips with USP-certified dissolution profiles and FDA cGMP documentation capture the highest tier, while unregulated direct-to-consumer brands compete on unit economics. Cost compression in the standard tier is intensifying because REACH registration deadlines for polymer additives force reformulation expenses onto mid-market manufacturers. Mass-market retailers show greatest price sensitivity, whereas specialty pharmacy buyers prioritize validated batch-to-batch performance over per-unit cost.
Supply Chain Analysis
Single-source vulnerability sits with pullulan production concentrated in East Asian fermentation facilities, exposing formulators to logistics disruption and input cost volatility. Active pharmaceutical ingredient sourcing draws from India, China, and domestic United States manufacturers for vitamin and probiotic actives. Film-forming polymer supply hinges on hydroxypropyl methylcellulose from European chemical producers and polyvinyl alcohol from Japanese petrochemical operations. Tariff exposure on imported excipients represents the dominant structural risk for North American toll manufacturers. Distribution runs through pharmacy wholesale networks in Germany and drugstore chain distribution centers in the United States, with direct-to-consumer subscription models bypassing traditional intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where manufacturers balance FDA cGMP compliance costs in the United States against EFSA novel food assessment timelines in Europe to optimize working capital deployment.
For Market Incumbents: Lock in polymer supply agreements with validated East Asian fermentation facilities before REACH registration deadlines constrain supplier qualification pools. Defend pharmacy channel placement through exclusivity arrangements with United States drugstore chains and German Apotheken networks, as emerging toll manufacturers threaten shelf access with lower-cost hot-melt extrusion capacity.
For New Entrants and Emerging Players: Parents of children aged 2-12 represent an underserved buyer archetype seeking alternatives to preservative-laden syrups, creating white-space opportunity for flavor-engineered vitamin D and probiotic strips with child-safe packaging. German Apotheken networks show underpenetration for wellness-oriented strips relative to pharmaceutical oral films. Direct-to-consumer subscription models offer the most penetrable go-to-market angle, capturing recurring revenue and consumption data while bypassing wholesale margin compression.
For Investors and Strategic Acquirers: Asymmetric upside sits with contract development organizations possessing established ECHA submission track records and validated multi-format production lines. Long-term viability over a multi-year horizon favors participants with captive polymer formulation capabilities that control strip dissolution engineering. Acquisition targets should demonstrate pharmacy-grade certification and hot-melt extrusion capacity. Monitor probiotic strain stabilization breakthroughs as the inflection indicator for premium pricing sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Hot-Melt Extrusion Capacity Expansion | Eliminates organic solvent handling while satisfying EPA emissions scrutiny in high-wage jurisdictions. |
| Pharmacy Channel Exclusivity Arrangement | Secures shelf placement against direct-to-consumer subscription models in United States drugstore chains. |
| Probiotic Microencapsulation R&D Partnership | Unlocks shelf-stable live culture delivery formats commanding premium positioning in Japan's postal pharmacy networks. |
| REACH Registration Compliance Outsourcing | Transfers ECHA submission burdens to full-service contract development organizations with established track records. |
| Direct-to-Consumer Subscription Platform Launch | Captures recurring revenue and consumption data while bypassing wholesale intermediaries in wellness segments. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with polymer formulation chemists, pharmacy procurement managers, contract manufacturing executives, and regulatory affairs specialists informed supply chain and pricing dynamics. Secondary sources included FDA cGMP guidance documents, EFSA novel food assessment databases, USP dissolution monographs, and REACH registration filings. Bottom-up volume estimates triangulated against top-down market sizing across product type, delivery mode, and distribution channel dimensions.
Rate-of-change decomposition anchored the analytical framework, disaggregating volume growth into pediatric expansion, senior demographic shifts, and channel migration components. Segmentation dimensions modeled encompassed product type, delivery mode, end user physiology, and distribution channel regulatory scrutiny level. CAGRs derived from fitted growth curves incorporating polymer supply constraints, EFSA assessment timeline delays, and pharmacy certification penetration rates. Industry-specific inputs included pullulan price indices, hot-melt extrusion equipment installation data, and dissolution testing standardization progress across USP, EP, and JP pharmacopeial methods.
Underlying measurement precision varies by segment; pharmacy-grade certified strips with validated dissolution profiles carry tighter precision than unregulated direct-to-consumer commodity products. Forecasts reflect assumptions regarding REACH registration compliance rates, probiotic stabilization technology adoption curves, and pharmacy channel expansion trajectories in Germany. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
US Hangover Cure Products Market
Nutritional Supplements
North America Digestive Health Supplements Market
Nutritional Supplements
Global Hangover Rehydration Supplements Market
Nutritional Supplements
Europe Vegan Supplements Market
Nutritional Supplements
Custom Supplement Formulation Service Market
Nutritional Supplements
Europe Collagen Peptides Market
Nutritional Supplements
Global Natural Health Supplements Market
Nutritional Supplements
Omega-3 Fish Oils Market
Nutritional Supplements
Vitamin B3 Market
Nutritional Supplements
Global Nutraceuticals Product Market
Nutritional Supplements
Omega-3 Concentrates Market
Nutritional Supplements
Plant Sterol Supplements Market
Nutritional Supplements
DHA Oil Supplement Market
Nutritional Supplements
Longevity and Anti-Aging Brain Health Supplements Market
Nutritional Supplements
Coq10 Gummies Market
Nutritional Supplements
Fatty Acid Supplements Market