
 Bio-Based Sealant Films Market | 2026-2036
Bio-Based Sealant Films Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Based Sealant Films Market Outlook
Food packaging converters are bifurcating from industrial buyers as the dominant demand archetype for bio-based sealant films. NatureWorks LLC leverages its Ingeo polylactic acid platform to anchor supply relationships with major flexible packaging houses across North America. BASF SE competes through its certified compostable polyurethane chemistry, sustaining technical service teams dedicated to sealant film converters. DuPont de Nemours, Inc. differentiates via controlled crystallization technology that extends heat-seal performance in high-speed form-fill-seal lines.
Bio-based sealant films are multilayer polymer structures engineered to provide hermetic closure in packaging applications, typically comprising polylactic acid, bio-polyurethane, or thermoplastic starch matrices with seal initiation temperatures between 80°C and 120°C. These films bond to rigid or flexible substrates through controlled melt flow during thermal activation, replacing fossil-derived polyethylene and ionomer sealants in food, medical, and consumer goods packaging. Polymer-based formulations currently dominate installed capacity due to processing familiarity on conventional extrusion lines, though starch-based variants are registering the fastest formulation patent activity as moisture barrier improvements advance. Extrusion technology leads commercial deployment, while coating processes capture concentrated margin pools in medical device packaging where precision thickness control commands specification premiums.
The EPA regulates volatile organic compound emissions from adhesive and coating operations under NESHAP standards, compelling solvent-free sealant film adoption in U.S. manufacturing facilities. REACH restrictions on isocyanate monomers and the EU Green Deal packaging waste directives are reshaping product registration requirements and import compliance across European supply chains. ISO 17088 and ASTM D6400 certification protocols govern compostability claims, creating market access barriers for uncertified film producers. Stakeholders must monitor evolving state-level extended producer responsibility laws and bio-preferred procurement mandates to anticipate which certification regimes will determine competitive viability in downstream segments.
Market Dynamics
Retailer sustainability mandates are compressing procurement cycles for compostable sealant layers, forcing converters to pre-qualify bio-based alternatives ahead of contract renewals. This demand-side pressure is restructuring supplier relationships and accelerating reformulation investments across flexible packaging supply chains.
Growth Catalysts
- EU Green Deal packaging waste directives:The EU Green Deal mandates renewable content thresholds in food-contact flexible packaging, compelling German brand owners to specify certified compostable sealant films in supplier contracts.
- High-speed form-fill-seal line compatibility:Controlled crystallization advances in polylactic acid matrices now enable heat-seal performance matching fossil-derived ionomers, accelerating adoption in automated food packaging operations.
- REACH isocyanate restrictions:REACH limitations on petroleum-derived adhesive chemistries are redirecting converter procurement toward bio-polyurethane sealant formulations with compliant monomer profiles.
Market Restraints
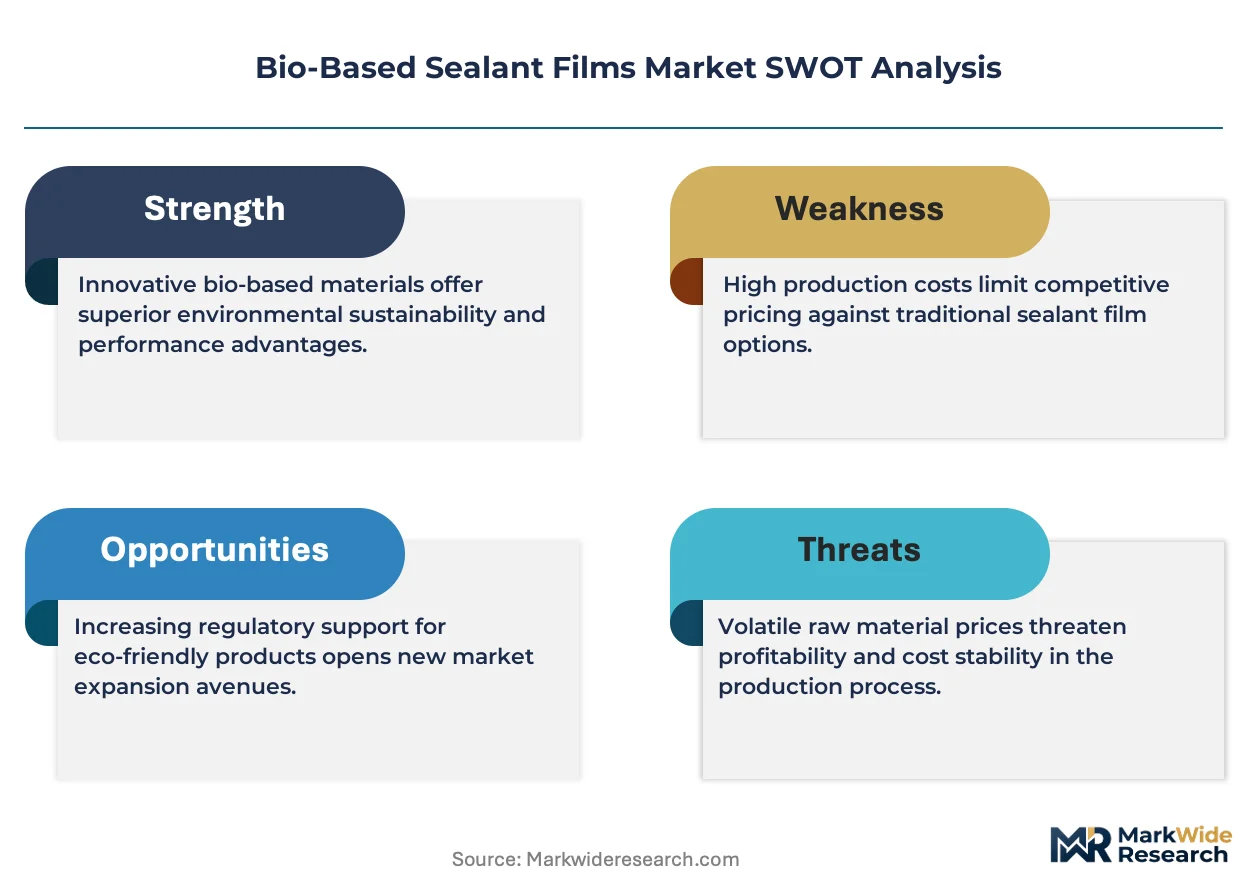
- Lactic acid feedstock cost volatility:Corn and sugarcane price fluctuations transmit directly to polylactic acid resin costs, compressing margin stability for film extruders without backward integration into fermentation capacity.
- Moisture barrier technical limitation:Thermoplastic starch matrices exhibit oxygen transmission rates 3-5x higher than polyethylene equivalents, restricting deployment in shelf-stable meat and dairy applications.
- ISO 17088 certification timeline friction:Multi-month compostability validation protocols delay product launches and lock working capital in pre-commercial inventory.
Strategic Opportunities
- Medical device packaging precision coating:Bio-based sealant films with sub-10 micron thickness control command specification premiums in sterile barrier applications, creating margin pools unavailable in commodity food packaging.
- Extended producer responsibility tailwinds:State-level EPR laws in California and New York are mandating post-consumer recycled and renewable content minimums, opening procurement channels for certified bio-based alternatives.
- Starch-polyester blend technology convergence:Hybrid formulations combining thermoplastic starch with bio-polyesters are narrowing moisture barrier gaps while maintaining home compostability certification.
Industry Challenges
- Extrusion technician skill scarcity:Bio-based resins require modified temperature profiles and die configurations compared to polyethylene, creating workforce retraining burdens for converters.
- Multi-layer coextrusion capex intensity:Barrier-enhanced sealant films demand 7-9 layer line investments exceeding conventional 3-5 layer equipment, concentrating capacity expansion among capitalized players.
- ASTM D6400 batch certification complexity:Lot-specific compostability testing requirements create documentation overhead and disqualification risk for production-scale film rolls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Based Sealant Films Market |
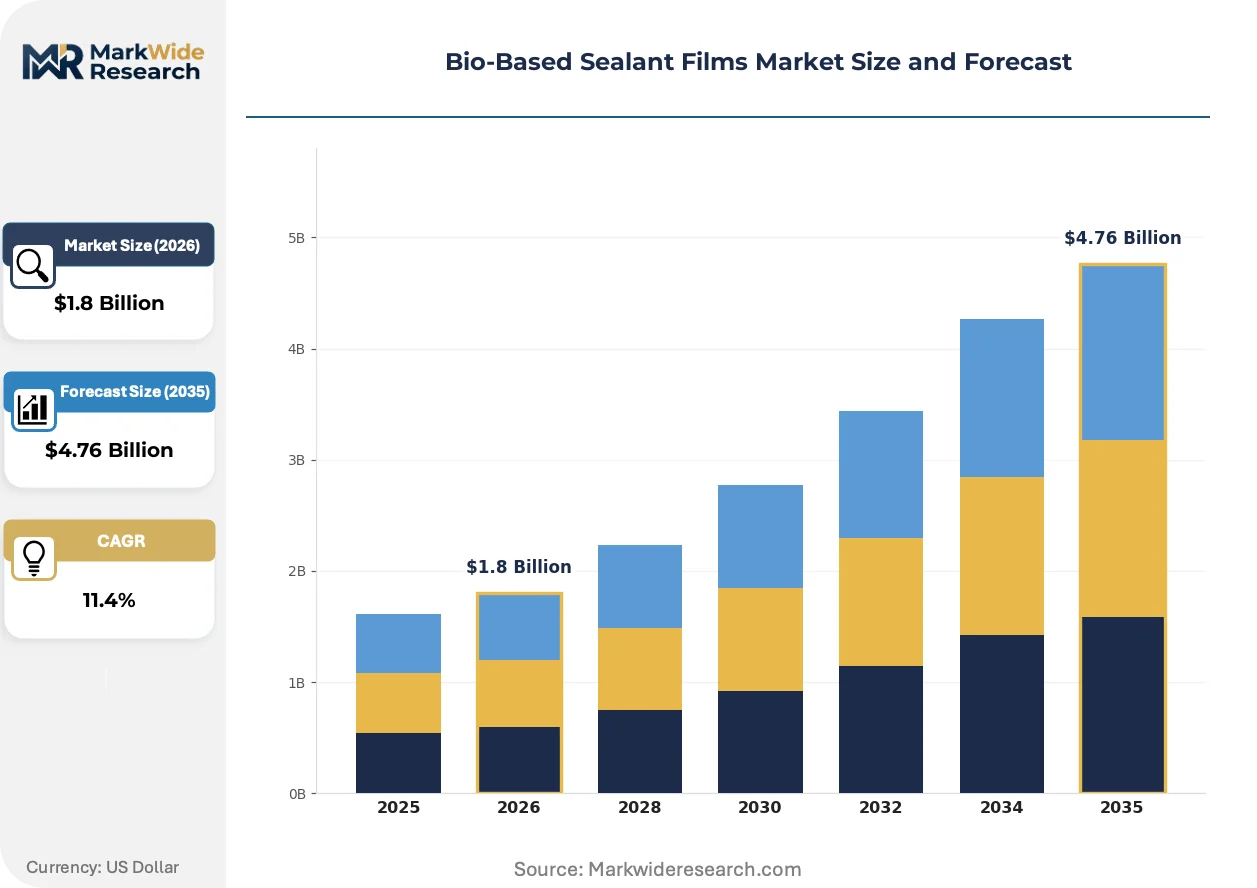
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer-Based, Bio-Polyurethane, Starch-Based, Cellulose-Based End User: Food Packaging, Medical Devices, Construction, Automotive Technology: Extrusion, Coating, Lamination, Molding Application: Flexible Packaging, Surface Protection, Adhesives, Insulation |
| Companies Covered | NatureWorks LLC, BASF SE, DuPont de Nemours, Inc., DSM, Amcor plc, Toray Industries Inc., Mitsubishi Chemical, Braskem S.A., Danimer Scientific, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Based Sealant Films Market Strategic Shifts
Reformulation activity is accelerating around moisture barrier enhancement and heat-seal latitude extension. Three interconnected developments are reshaping technical specifications and procurement criteria across end-use verticals.
Controlled crystallization technology in polylactic acid sealant layers is fragmenting the historical performance gap between bio-based and fossil-derived alternatives. High-speed form-fill-seal operators in snack food packaging are adopting these grades at contract renewal cycles. The technology is fragmenting incumbent ionomer positions in applications previously deemed technically inaccessible to renewable materials.
REACH restrictions on isocyanate monomers are compelling polyurethane sealant film producers to validate bio-based polyol feedstocks. Industrial consequence includes reformulation of adhesive layers in medical device pouches and retort food packaging. German packaging converters are responding fastest, driven by domestic retailer renewable content mandates and ECHA compliance deadlines.
Food packaging buyers are consolidating supplier panels around certified compostable film sources with validated heat-seal performance data. Direct converter-brand owner relationships are displacing distributor-mediated procurement in private-label grocery segments. This concentration is most visible in Germany, where Aldi and Lidl sustainability scorecards now weight sealant film certification status in vendor qualification.
Bio-Based Sealant Films Market Segmentation
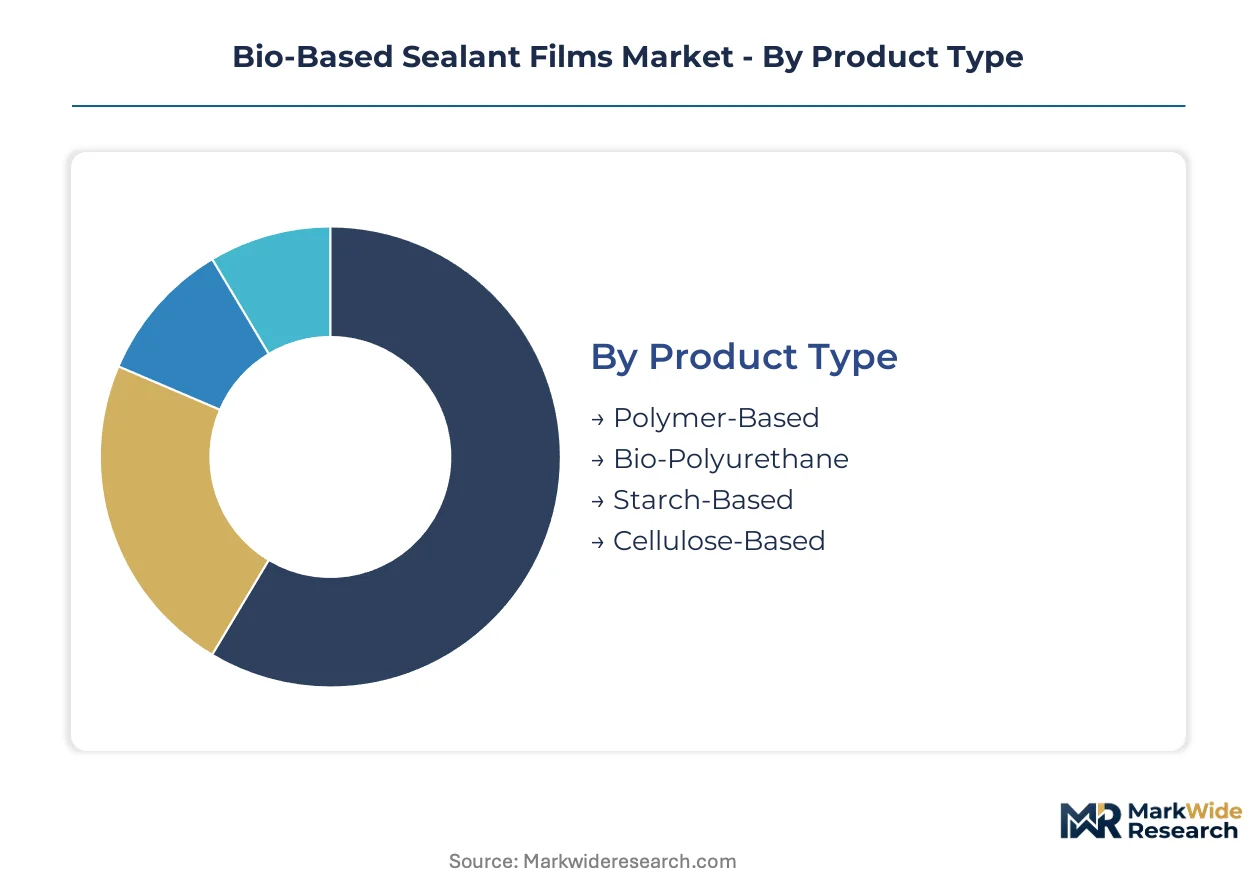
Bio-based sealant films compete across multiple formulation platforms and processing technologies, each facing distinct substitution pressures from fossil-derived alternatives. Segmentation clarity enables converters to match material selection with performance requirements and certification obligations.
Product Type:
Polymer-based formulations face the most intense substitution pressure from conventional polyethylene sealants, while starch-based variants confront technical barriers in moisture-sensitive applications.
- Polymer-Based:Polylactic acid and bio-polyester matrices dominate installed extrusion capacity due to processing familiarity on conventional lines. German food packaging converters specify these grades for Aldi and Lidl supplier scorecards demanding renewable content verification.
- Bio-Polyurethane:Certified compostable polyurethane chemistry from BASF SE competes through REACH-compliant monomer profiles, sustaining dedicated technical service teams for sealant film converters in medical device and retort food packaging.
- Starch-Based:Thermoplastic starch matrices exhibit oxygen transmission rates 3-5x higher than polyethylene equivalents, restricting deployment in shelf-stable meat and dairy despite accelerating patent activity in moisture barrier improvements.
- Cellulose-Based:Regenerated cellulose and cellulose ester formulations serve niche applications in premium cosmetic and pharmaceutical blister packaging where optical clarity and dead-fold properties command specification premiums.
Polymer-based formulations retain volume leadership; starch-based alternatives hold the steepest expansion curve as hybrid technologies narrow performance gaps.
End User:
Cost tier stratification separates commodity food packaging from precision medical applications, with construction and automotive segments occupying intermediate value positions.
- Food Packaging:High-speed form-fill-seal operators in snack food packaging adopt controlled crystallization polylactic acid grades at contract renewal cycles, fragmenting historical ionomer positions in applications previously inaccessible to renewable materials.
- Medical Devices:Sterile barrier applications command sub-10 micron thickness control premiums, with bio-based sealant films capturing concentrated margin pools unavailable in commodity food packaging through precision coating processes.
- Construction:Surface protection and temporary adhesion films for building envelope applications prioritize cost parity over compostability certification, limiting penetration where polyethylene scrap value recovery dominates procurement.
- Automotive:Interior trim lamination and acoustic insulation films face qualification timelines exceeding 24 months, slowing adoption despite OEM sustainability commitments and extended producer responsibility tailwinds.
Food packaging concentrates procurement volume; medical devices deliver the highest margin realization per square meter.
Technology:
Volume concentration in extrusion creates supply-side constraints for coating and lamination specialists serving specification-driven segments.
- Extrusion:Multilayer coextrusion dominates commercial deployment, though barrier-enhanced sealant films demand 7-9 layer line investments exceeding conventional 3-5 layer equipment and concentrating capacity among capitalized players.
- Coating:Precision thickness control in medical device packaging commands specification premiums, with coating processes capturing margin pools through validated sterile barrier performance and ISO 17088 certification.
- Lamination:Adhesive and thermal lamination processes integrate bio-based sealant layers into composite structures for high-barrier food and pharmaceutical applications, requiring modified temperature profiles and die configurations.
- Molding:Injection and compression molding of sealant preforms serves specialized medical device closure systems and custom automotive gaskets, representing a niche deployment route with limited scale economies.
Extrusion commands installed capacity; coating expands most quickly in medical precision segments.
Application:
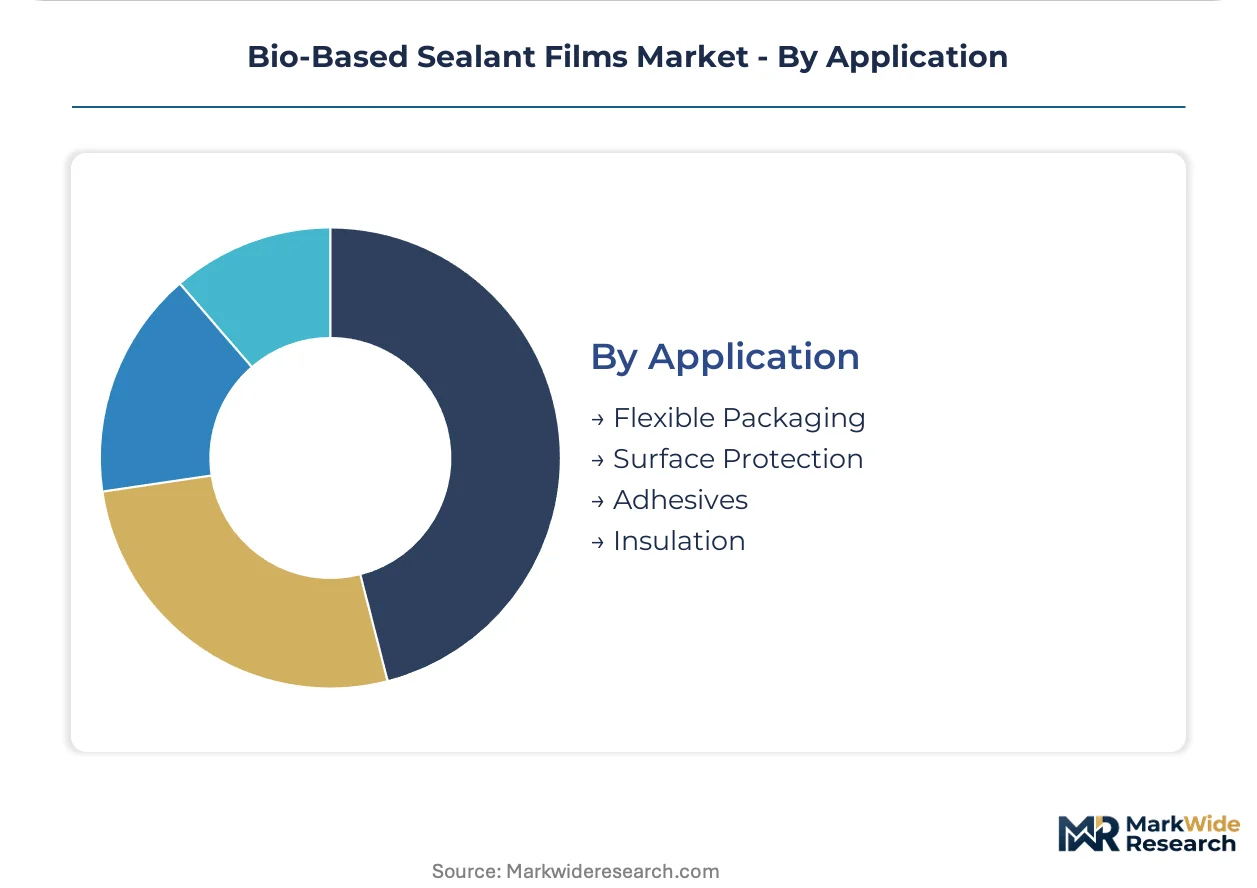
Customer type differentiation separates private-label grocery procurement from industrial specification buyers, with adhesive and insulation applications occupying emerging volume positions.
- Flexible Packaging:Hermetic closure in form-fill-seal lines represents the core demand archetype, with compostable sealant layer procurement accelerating ahead of retailer sustainability mandate deadlines across European supply chains.
- Surface Protection:Temporary adhesion films for electronics, appliances, and building materials prioritize clean removal and residue-free performance, where bio-based formulations compete on regulatory compliance rather than technical superiority.
- Adhesives:Pressure-sensitive and heat-activated adhesive layers in tape and label applications face REACH isocyanate restrictions, redirecting converter procurement toward bio-polyurethane formulations with compliant monomer profiles.
- Insulation:Thermal and acoustic insulation films in construction and automotive applications remain underpenetrated due to fire safety certification requirements and established mineral wool supply chains.
Flexible packaging anchors revenue concentration; adhesives gain share fastest through regulatory displacement of petroleum-derived alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food packaging converters concentrate procurement decisions in Germany, the United States, and Japan, where retailer sustainability mandates and regulatory compliance timelines compress supplier qualification cycles. Brand owners in these markets impose renewable content thresholds that restructure flexible packaging supply chains.
Germany
Aldi and Lidl sustainability scorecards weight sealant film certification status in vendor qualification, accelerating converter procurement of compostable alternatives. ECHA REACH restrictions on isocyanate monomers redirect formulation toward bio-polyurethane chemistries with compliant profiles. The Rhine-Ruhr industrial corridor hosts BASF SE technical service teams dedicated to sealant film converter support.
United States
EPA NESHAP standards on volatile organic compound emissions compel solvent-free sealant film adoption in manufacturing facilities. California and New York state-level extended producer responsibility laws mandate post-consumer recycled and renewable content minimums. The Midwest corn belt anchors lactic acid fermentation capacity that feeds polylactic acid resin supply to domestic extruders.
Japan
METI carbon neutrality roadmaps pressure packaging converters to demonstrate bio-based content in food-contact applications. JIS standards on compostable plastics create certification pathways that parallel ISO 17088 protocols. The Chubu region around Nagoya concentrates precision coating specialists serving medical device packaging with sub-10 micron thickness control.
China
MIIT dual carbon goals and GB standards on biodegradable plastics reshape domestic procurement criteria for flexible packaging. SAMR food-contact material regulations tighten compliance requirements for imported sealant film technologies. The Yangtze River Delta clusters multilayer coextrusion capacity serving both export and domestic brand owner specifications.
France
ANSM pharmaceutical packaging regulations intersect with EU Green Deal waste directives to mandate renewable content in medical barrier films. The country's national pharmaceutical regulator enforces sterile barrier performance standards that bio-based alternatives must validate through precision coating processes. The Île-de-France region hosts formulation R&D centers targeting hybrid starch-polyester blends for home compostability certification.
Bio-Based Sealant Films Market Competitive Environment
Player mix skews toward diversified chemical conglomerates with fermentation or polymer science heritage, creating a tiered structure where captive resin supply confers cost position advantages. Mid-scale specialists compete through ISO 17088 certification speed and converter technical service density. The dominant competitive moves involve backward integration into lactic acid fermentation capacity and strategic partnerships with high-speed form-fill-seal equipment OEMs to validate heat-seal performance data.
Within the diversified chemical conglomerate tier, NatureWorks LLC and BASF SE exemplify archetypes that anchor supply relationships through platform technologies and REACH-compliant chemistry portfolios respectively. DuPont de Nemours, Inc. occupies a position representing controlled crystallization specialization. These three entities collectively illustrate how technical service investment and certification infrastructure separate viable competitors from commodity resin traders in converter procurement decisions.
| Leading Market Players |
|---|
| NatureWorks LLC |
| BASF SE |
| DuPont de Nemours, Inc. |
| DSM |
| Amcor plc |
| Toray Industries Inc. |
| Mitsubishi Chemical |
| Braskem S.A. |
| Danimer Scientific, Inc. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts with corn and sugarcane price indexation lock in lactic acid resin supply for German and US extruders while exposing film converters to agricultural commodity volatility. These arrangements simultaneously guarantee capacity allocation from NatureWorks LLC and BASF SE fermentation assets and create margin compression risk when feedstock costs spike.
Pricing Analysis
Cost-plus contracts with agricultural commodity indexation dominate procurement between lactic acid fermenters and film extruders. Pricing stratifies across medical-grade ISO 17088 certified films, standard food-contact compostable grades, and uncertified industrial tiers. Pricing pressure stems from corn price volatility transmitting directly to polylactic acid resin costs. Food packaging converters exhibit highest price sensitivity due to thin margins in private-label grocery segments, while medical device buyers accept premiums for sub-10 micron thickness precision.
Supply Chain Analysis
Inventory cycles stretch 8-12 weeks for multilayer coextrusion equipment due to specialized die configurations for bio-based resins. Supply concentrates in the United States, Germany, and Japan, with the Midwest corn belt anchoring lactic acid fermentation and the Rhine-Ruhr corridor hosting BASF SE technical service infrastructure. Raw material dependencies center on corn and sugarcane feedstocks, bio-polyol chemistries, and thermoplastic starch modifiers. Single-source vulnerability in lactic acid fermentation capacity creates supply chain risk. Distribution runs through direct converter relationships displacing distributor channels in Aldi and Lidl supplier scorecard segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Aldi, Lidl, and private-label grocery chains consolidate supplier panels around certified compostable film sources, fragmenting incumbent positions and compressing procurement cycles.
For Market Incumbents: Shield market position through backward integration into lactic acid fermentation capacity and ISO 17088 certification infrastructure investment. NatureWorks LLC demonstrates this archetype through captive Ingeo polylactic acid supply. The priority defensive move involves technical service team expansion in Germany to defend against REACH-compliant bio-polyurethane substitutes. Capacity addition in the US Midwest corn belt reinforces cost position against sugarcane-dependent Brazilian resin imports. For New Entrants and Emerging Players: Anchor in medical device packaging precision coating segments where sub-10 micron thickness control commands specification premiums unavailable in commodity food packaging. The most penetrable white-space target involves sterile barrier applications in France and Japan where ANSM and METI regulations mandate renewable content validation. A direct converter technical service model bypasses distributor channels and accelerates heat-seal performance data qualification with high-speed form-fill-seal OEMs. For Investors and Strategic Acquirers: Specialist coating technology firms with validated sterile barrier performance represent the highest-conviction acquisition target archetype. Long-term viability hinges on certification speed and converter relationship density rather than raw resin scale. The signal to watch is state-level extended producer responsibility law passage in California and New York, which would inflect procurement channel openings for certified bio-based alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lactic Acid Fermentation | Captive corn-belt supply shields NatureWorks LLC from sugarcane price volatility. |
| ISO 17088 Certification Infrastructure Investment | Accelerated compostability validation compresses product launch timelines for German converters. |
| Precision Coating Capacity Expansion | Sub-10 micron thickness control captures medical device packaging margin pools in Japan. |
| Technical Service Team Density in Rhine-Ruhr | BASF SE converter support sustains REACH-compliant bio-polyurethane adoption. |
| High-Speed Form-Fill-Seal OEM Partnerships | Heat-seal performance data validation fragments historical ionomer positions in snack food packaging. |
Study Parameters
The analysis maps polylactic acid, bio-polyurethane, thermoplastic starch, and cellulose-based formulation sub-sectors, each validated through flexible packaging converter procurement directors, medical device sterile barrier engineers, and chemical plant operations managers. Primary interview intelligence triangulates against customs trade data, EPA NESHAP enforcement records, ECHA REACH registration databases, and SEC 10-K filings from diversified chemical conglomerates. Bottom-up resin capacity modeling and top-down end-use demand estimation converge through iterative stakeholder validation.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. Segmentation dimensions include formulation chemistry, end-use vertical, processing technology, and regional regulatory cluster. CAGRs derive from annualized growth rate interpolation across modeled periods. Forecast inputs incorporate lactic acid fermentation capacity expansion timelines and retailer sustainability mandate compliance deadlines.
Decision-makers should treat outputs as directional under sustained EU Green Deal enforcement and corn price stability assumptions; material deviation in agricultural commodity markets or REACH regulatory scope would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Frisket Masking Film Market
Packaging Barrier Films
Pan Liners Market
Packaging Barrier Films
Global Medical Packaging Films Market
Packaging Barrier Films
Global Metalized Barrier Films Market
Packaging Barrier Films
Global Shrink Films Market
Packaging Barrier Films
Oxygen Barrier Films and Coatings for Dry Food Market
Packaging Barrier Films
Heat Insulating Films Market
Packaging Barrier Films
Volatile Corrosion Inhibitors (VCI) Packaging Market
Packaging Barrier Films
Anti-Fog Lidding Films Market
Packaging Barrier Films
Sealant Films Market
Packaging Barrier Films
Barrier Foil Market
Packaging Barrier Films
Electron High Barrier Packaging Film Market
Packaging Barrier Films
Metalized Barrier Film Packaging Market
Packaging Barrier Films
Liquid Masking Film Market
Packaging Barrier Films
Holographic Transfer Film Market
Packaging Barrier Films
Antimicrobial Packaging Market